
 Food Grade Carrageenan Market | 2026-2036
Food Grade Carrageenan Market Size, Share, and Industry Trends Forecast 2026-2036
Food Grade Carrageenan Market Foresight
Multi-source seaweed procurement is expanding as extractors hedge against Philippine and Indonesian supply volatility. Cargill, Incorporated leverages its integrated agricultural supply chain to secure consistent red seaweed volumes across multiple origins. CP Kelco sustains technology leadership in refined kappa carrageenan production for dairy applications. Gelymar anchors its competitive position through specialized iota extraction capabilities serving European meat processors.
Food grade carrageenan comprises sulfated galactan polysaccharides extracted from Rhodophyceae seaweed species, primarily differentiated by kappa, iota, and lambda structural variants with gel-forming and viscosity-modifying properties. Extracted powder dominates current volume flows due to its stability in extended shelf-life dairy systems and cost-efficient bulk handling. Dairy alternatives represent the fastest-expanding application segment as oat and pea milk processors adopt kappa carrageenan for suspension and mouthfeel replication. Refined flakes command premium positioning among nutraceutical companies requiring precise dissolution control in capsule and tablet formulations.
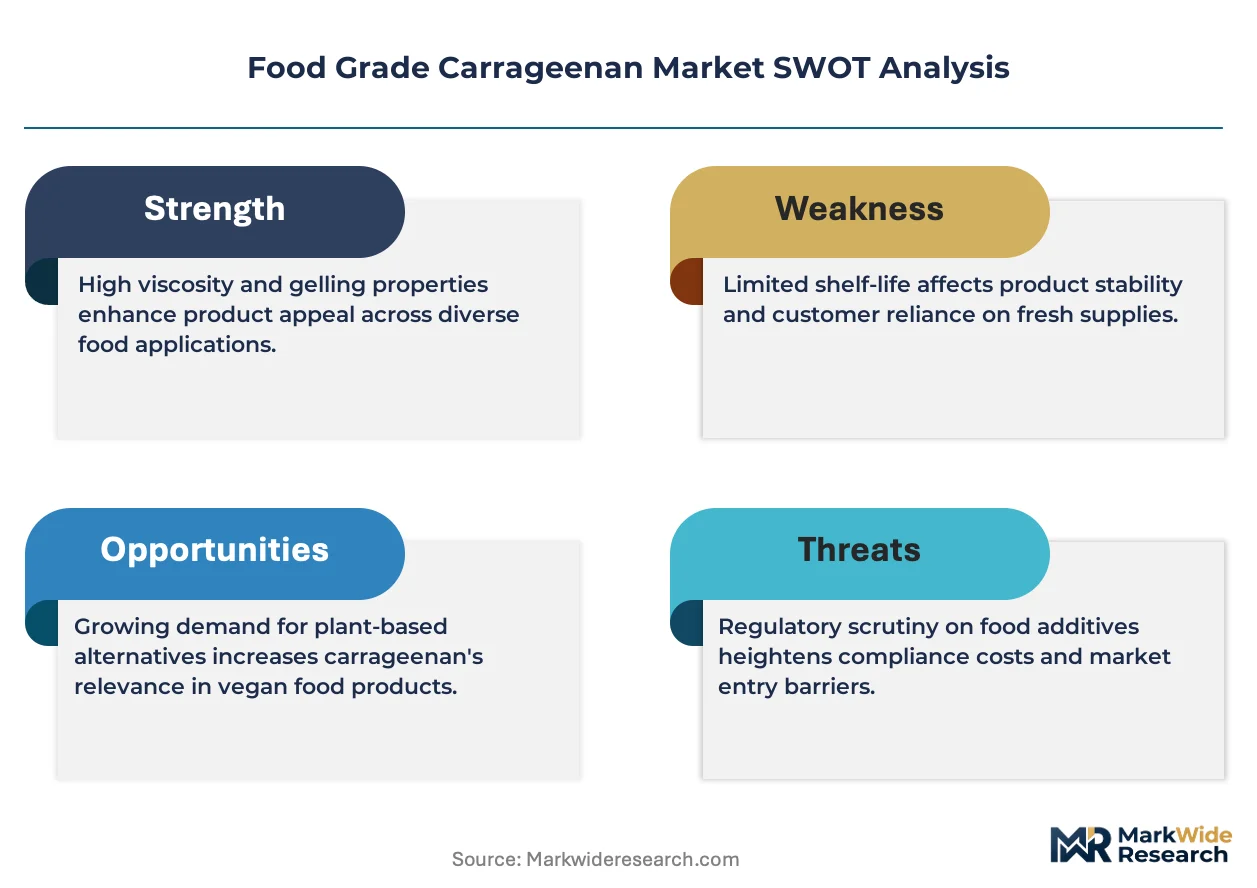
FDA food additive regulations under 21 CFR 172.620 govern carrageenan safety thresholds in U.S. processed foods, while EFSA periodic re-evaluations drive reformulation documentation burdens across European Union member states. The FSSAI in India enforces BIS purity standards for imported hydrocolloids entering domestic dairy and confectionery channels. Stakeholders must monitor evolving seaweed sustainability certification requirements and regional clean-label sentiment to anticipate substitution risks from rival hydrocolloids.
Market Dynamics
Clean-label reformulation mandates from EFSA additive reviews are compressing carrageenan adoption timelines as dairy processors validate functional equivalence against rival hydrocolloids before label claims expire.
Growth Catalysts
- Plant-based dairy expansion:Oat and almond milk processors pull significant kappa carrageenan volumes for suspension stability and mouthfeel replication in shelf-stable formulations.
- EFSA re-evaluation protocols:European additive safety reviews force documented hydrocolloid benchmarking, locking in carrageenan where suppliers provide compliant toxicological dossiers.
- Seaweed supply clustering:Indonesian and Philippine coastal farming concentrates raw material access, reducing extraction facility feedstock procurement cycles.
Market Restraints
- Red seaweed price volatility:Kappaphycus alvarezii harvest fluctuations in the Sulu Sea and Sulawesi Strait transmit directly to extractor margin compression.
- Clean-label substitution pressure:Gellan gum and locust bean gum displace carrageenan in premium European dairy where E numbers trigger consumer rejection.
- Refined-grade capacity concentration:Multi-stage filtration and alcohol precipitation infrastructure clusters with three specialized processors, creating supply bottleneck risk.
Strategic Opportunities
- Indian nutraceutical penetration:FSSAI BIS purity standard enforcement creates entry barriers for unqualified imports, favoring certified suppliers in tablet and capsule dissolution applications.
- Precision fermentation convergence:Cell-cultured dairy alternatives require texturizing systems combining carrageenan with microbial exopolysaccharides for fat-mimetic structures.
- Direct-to-processor digital channels:Seaweed extractors bypass traditional ingredient distributors through proprietary portals serving mid-size plant-based beverage startups.
Industry Challenges
- Halal certification complexity:Alcohol-based precipitation in refined carrageenan production triggers religious compliance audits across Indonesian and Malaysian supply chains.
- Extraction wastewater treatment capex:Potassium chloride recovery and seaweed residue processing require membrane filtration investments exceeding small-facility balance sheet capacity.
- Lambda variant standardization gaps:Inconsistent cold-soluble viscosity specifications between Philippine and Indonesian origin batches disrupt confectionery processor formulation lock.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Grade Carrageenan Market |
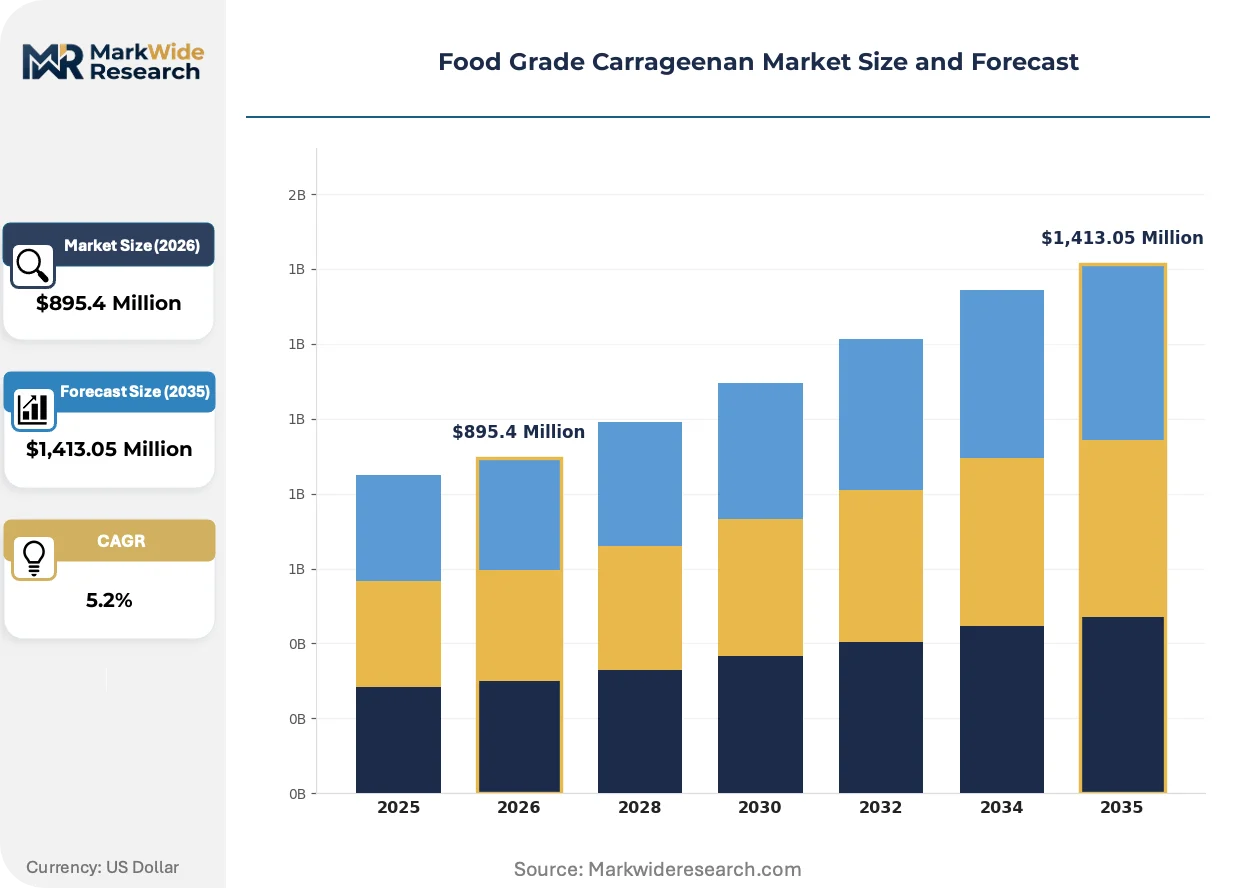
| Market Size in 2026 | $895.4 Million |
| Market Size in 2035 | $1,413.05 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extracted Powder, Gel Form, Liquid Suspension, Refined Flakes Application: Dairy Alternatives, Meat Extenders, Bakery Ingredients, Beverages, Personal Care End User: Food Manufacturers, Nutraceutical Companies, Cosmetic Producers, Pharmaceutical Firms Packaging Type: Bulk Bags, Retail Packs, Sachets, Drums |
| Companies Covered | Cargill, Incorporated, MCPI Corporation, CP Kelco, Ashland, CEAMSA, DuPont, Gelymar, W Hydrocolloids, Inc., Ingredion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Grade Carrageenan Market Shifts & Advancements
Seaweed biorefinery integration and regulatory-driven hydrocolloid substitution are compressing traditional extraction economics while opening adjacent revenue streams from previously discarded biomass fractions.
Semi-refined carrageenan (SRC) processing is overtaking traditional refined routes in cost-sensitive dairy applications. SRC retains higher cellulose content while delivering equivalent gel strength for cheese analogs and chocolate milk. Latin American and Southeast Asian processors adopt SRC to bypass alcohol precipitation costs without sacrificing label functionality.
EFSA's systematic re-evaluation of food additives under Regulation (EU) No 257/2010 imposes new toxicological data requirements on sulfated polysaccharides. Carrageenan suppliers must submit extended metabolic studies to maintain authorized status through 2026 review cycles. European dairy and meat processors accelerate dual-formulation development to ensure continuity if E407 faces usage restrictions.
Long-term supply agreements with named seaweed farming cooperatives are displacing spot-market raw material purchasing. Extraction facilities in Cebu and Makassar lock three-to-five-year offtake contracts with village-level cultivators to secure volume predictability. This contractualization trend reduces price arbitrage opportunities but stabilizes kappa variant availability for multinational dairy formulators.
Food Grade Carrageenan Market Segmentation
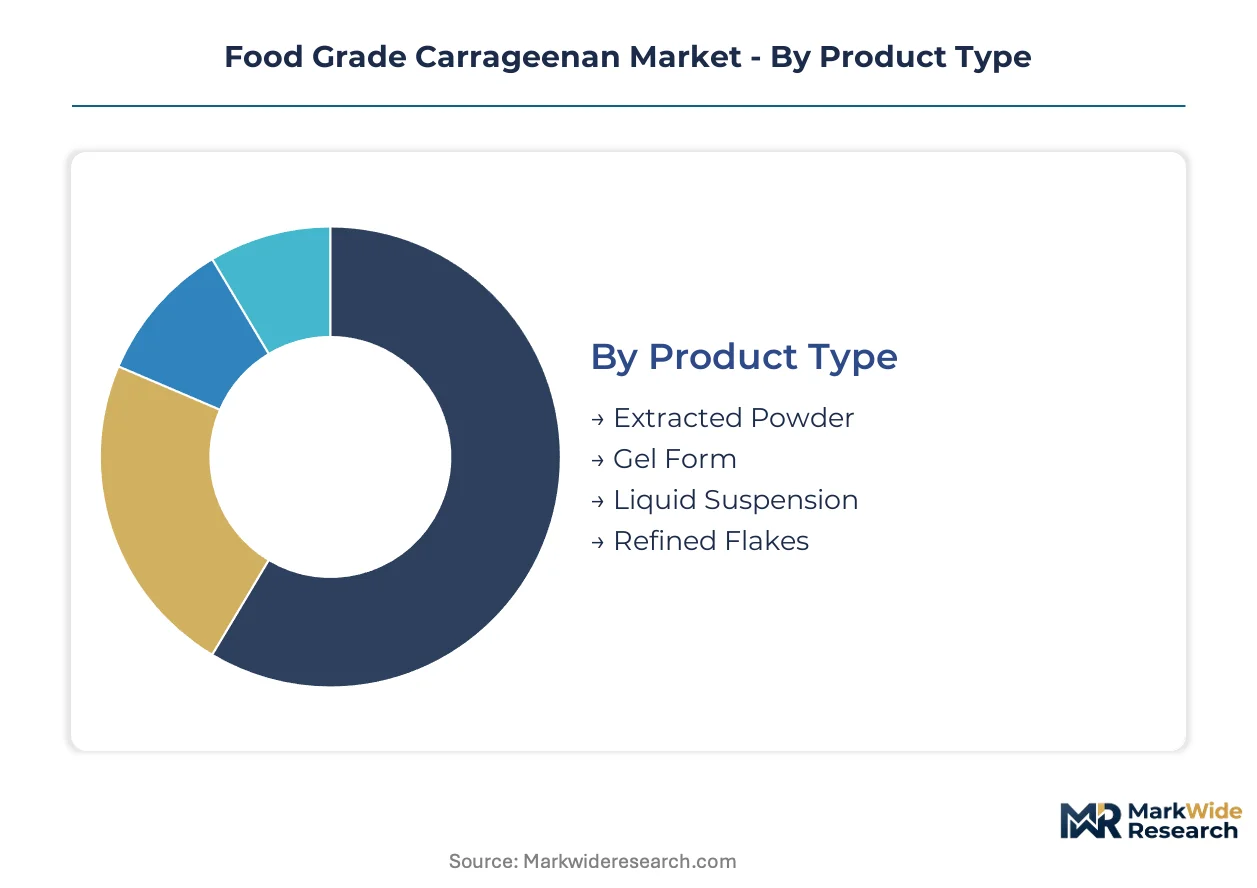
Carrageenan procurement patterns diverge sharply across product formats and end-use specifications. Indonesian and Philippine extraction facilities configure output grades to match distinct customer handling requirements and dissolution protocols.
Product Type:
Supply concentration in kappa-variant extraction determines which physical formats dominate volume flows.
- Extracted Powder:Spray-dried kappa and iota variants deliver standardized gel strength for extended shelf-life dairy systems. Powdered form dominates bulk procurement by Indonesian and Philippine processors serving multinational dairy formulators requiring pneumatic conveying compatibility.
- Refined Flakes:Alcohol-precipitated flakes enable precise dissolution control in high-value applications. Nutraceutical compounders in India and Europe specify flake geometry for tablet binding and capsule suspension where batch-to-batch viscosity consistency outweighs cost premiums.
- Gel Form:Pre-hydrated kappa blocks reduce processing steps for small-scale meat processors.
- Liquid Suspension:Cold-stable lambda dispersions serve beverage applications requiring pumpable dosing systems.
Today's leader: Extracted Powder. Tomorrow's challenger: Refined Flakes.
Application:
Cost tier differentiation separates commodity dairy thickeners from premium meat and bakery texturizers.
- Dairy Alternatives:Oat and almond milk processors deploy kappa carrageenan for fat-mimetic mouthfeel and protein suspension. This segment climbs the fastest as plant-based beverage startups in North America and Europe lock multi-year supply agreements with Cebu and Makassar extractors.
- Meat Extenders:Iota-variant gels bind water and fat in restructured poultry and surimi products. European meat processors validate carrageenan against EFSA additive review requirements while Asian processors prioritize cost-optimized semi-refined grades.
- Bakery Ingredients:Lambda variants stabilize whipped toppings and glazes in ambient distribution.
- Beverages:Cold-soluble grades suspend cocoa and calcium fortificants in chocolate milk.
- Personal Care:Low-ash refined grades thicken toothpaste and shampoo formulations.
Volume concentrates in Dairy Alternatives. Margin migrates toward Meat Extenders.
End User:
Customer type dictates certification burden and technical service intensity.
- Food Manufacturers:Dairy and meat processors drive standardized kappa volumes with halal and kosher documentation requirements.
- Nutraceutical Companies:Precise dissolution specifications and heavy metal testing protocols command premium flake grades.
- Cosmetic Producers:Low-odor, low-color refined grades serve skin-care and oral-care formulators.
- Pharmaceutical Firms:USP-grade documentation and excipient compatibility studies support tablet and suspension applications.
Procurement scale favors Food Manufacturers. Specification complexity elevates Nutraceutical Companies.
Packaging Type:
Handling infrastructure at customer facilities determines packaging selection.
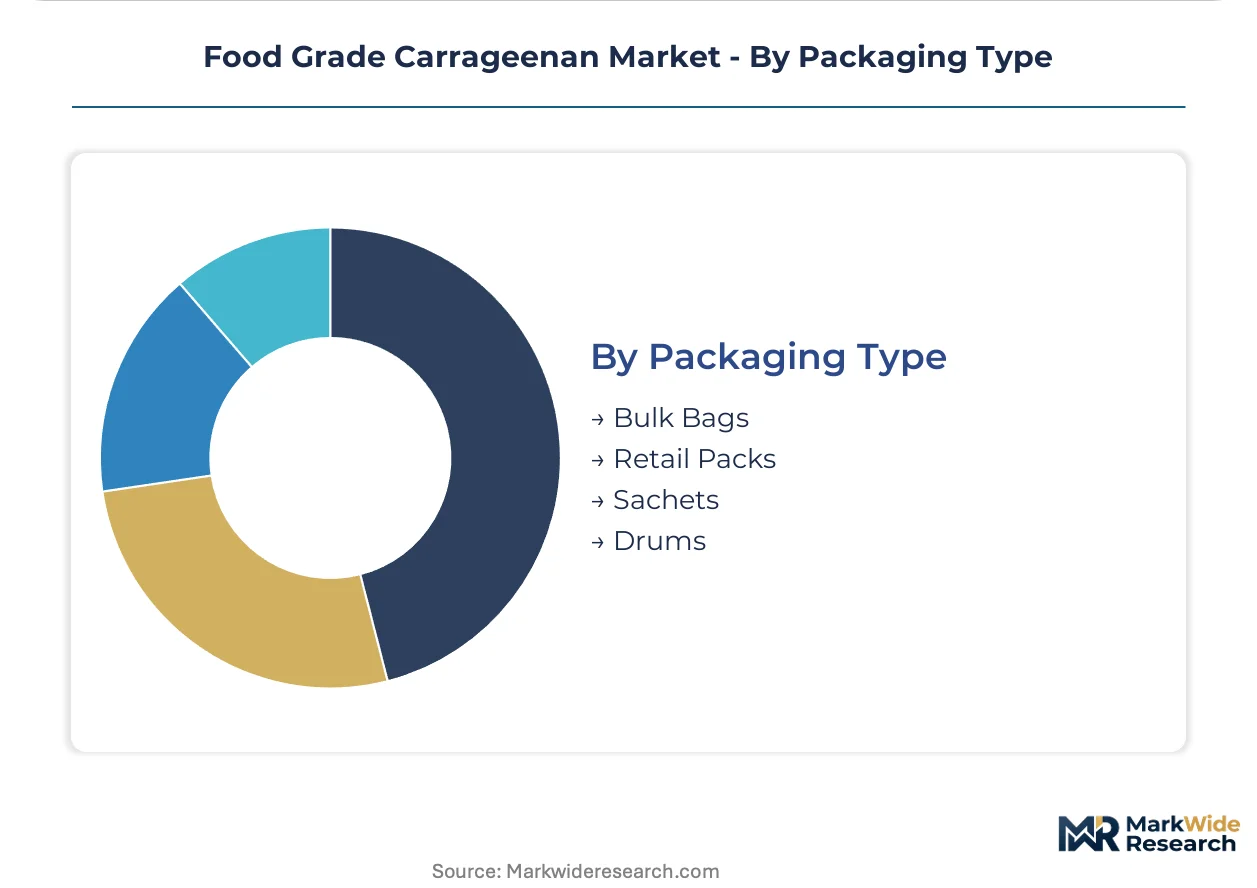
- Bulk Bags:One-ton FIBC units with liner systems serve high-volume dairy processors with pneumatic unloading systems.
- Drums:Fiber or steel drums protect hygroscopic powders in humid Southeast Asian distribution.
- Retail Packs:Five-kilogram poly-lined cartons serve artisanal food producers and small-batch cosmetic compounders.
- Sachets:Pre-weighed unit doses support R&D laboratories and pilot-scale production trials.
Logistics efficiency anchors Bulk Bags. Flexibility advantage belongs to Sachets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting carrageenan extraction investments toward jurisdictions where EFSA-mandated documentation costs remain lower than European manufacturing. Philippine and Indonesian coastal facilities capture this migration, while Indian and Brazilian processors exploit domestic purity standard gaps to serve price-sensitive dairy formulators.
Philippines
Cebu and Mindanao seaweed farming cooperatives supply kappa-variant raw material to Makassar-bound extraction vessels. The Bureau of Fisheries and Aquatic Resources enforces coastal zoning permits that concentrate cultivation in the Sulu Sea archipelago. Davao del Sur processors now operate semi-refined lines that bypass alcohol precipitation entirely.
Indonesia
Sulawesi Strait Kappaphycus alvarezii harvests anchor Southeast Asian supply volumes for multinational dairy contracts. The Ministry of Marine Affairs and Fisheries coordinates village-level farming permits through its aquaculture directorate. Makassar extraction clusters are expanding membrane filtration capacity to meet FSSAI import specifications for Indian nutraceutical channels.
India
Maharashtra and Gujarat dairy processors drive domestic carrageenan consumption for traditional sweets and processed cheese analogs. FSSAI BIS purity standards for hydrocolloids create entry barriers against unqualified Southeast Asian imports. Mumbai pharmaceutical compounders specify refined flake grades for tablet binding applications with heavy metal testing protocols.
Germany
EFSA additive re-evaluations under Regulation (EU) No 257/2010 force documented hydrocolloid benchmarking across Bavarian and North Rhine-Westphalia dairy operations. The Federal Office of Consumer Protection and Food Safety coordinates member-state enforcement of clean-label reformulation timelines. Hamburg ingredient distributors now stock dual-formulation portfolios to ensure continuity if E407 faces usage restrictions.
Brazil
São Paulo and Minas Gerais meat processors deploy iota-variant carrageenan for restructured poultry and surimi water-binding. ANVISA food additive regulations maintain carrageenan authorization without the toxicological dossier burdens imposed by EFSA protocols. Campinas extraction facilities import semi-refined Philippine grades for cost-optimized local finishing.
Food Grade Carrageenan Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue semi-refined processing shortcuts and direct-to-processor digital channels. The vendor base stratifies across three operational tiers: multinational agricultural conglomerates with integrated seaweed supply chains, specialized extraction houses with regional coastal access, and contract manufacturers serving private-label nutraceutical brands. Dominant competitive moves include multi-year offtake contracting with village-level farming cooperatives and backward integration into captive seaweed cultivation.
Among Philippine and Indonesian extraction specialists, MCPI Corporation and W Hydrocolloids, Inc. exemplify coastal-integrated operations with direct farming cooperative relationships. Within the diversified agricultural tier, Cargill, Incorporated anchors multinational supply security through multi-origin procurement networks. CP Kelco occupies a position representing technology-intensive refined processing capabilities for premium dairy applications. These three entities collectively illustrate the competitive spectrum from raw material capture through high-purity finishing.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| MCPI Corporation |
| CP Kelco |
| Ashland |
| CEAMSA |
| DuPont |
| Gelymar |
| W Hydrocolloids, Inc. |
| Ingredion |
| Others |
Supply & Pricing Matrix
Multinational dairy formulators command pricing leverage through multi-year offtake contracts that compress spot-market premiums for refined kappa grades. Three-tier pricing structure across premium, standard, and economy levels stratifies around certification burden, with FSSAI-compliant flakes commanding substantial premiums over semi-refined powders.
Pricing Analysis
Distributor markups of 15-25% separate Philippine extraction facilities from European compounders, though direct-to-processor digital portals are eroding this margin layer. Price differentiation rests on halal certification status and EFSA toxicological dossier completeness, with documented suppliers capturing premium positioning. Pricing pressure stems from gellan gum substitution in clean-label European dairy, forcing carrageenan extractors to absorb alcohol precipitation cost increases. Small-scale plant-based beverage startups exhibit highest price sensitivity, while Indian nutraceutical compounders accept substantial premiums for heavy metal-tested flake grades.
Supply Chain Analysis
Direct-to-processor channels handle hyperscale demand from oat and almond milk processors, bypassing traditional ingredient distributors. Raw material supply concentrates in Indonesia and the Philippines, with Kappaphycus alvarezii harvests from the Sulawesi Strait and Sulu Sea anchoring global kappa variant flows. Extraction infrastructure draws from potassium chloride, membrane filtration systems, and alcohol precipitation capacity. Single-source vulnerability in Philippine seaweed farming cooperatives threatens volume predictability. Distribution runs through Makassar and Cebu extraction clusters serving multinational dairy contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EFSA's systematic re-evaluation of food additives under Regulation (EU) No 257/2010 functions as a regulatory compounder, accelerating dual-formulation development and locking in carrageenan suppliers with compliant toxicological dossiers.
For Market Incumbents: Deepen captive seaweed cultivation through three-to-five-year offtake contracts with village-level farming cooperatives in the Sulu Sea archipelago. Expand membrane filtration capacity to meet FSSAI BIS purity specifications for Indian nutraceutical channels. Lock in kappa variant supply security against red seaweed price volatility from Kappaphycus alvarezii harvest fluctuations. For New Entrants and Emerging Players: Capture semi-refined carrageenan processing opportunities in Latin American markets where alcohol precipitation costs deter refined-grade investment. Target Brazilian meat processors through Campinas finishing facilities importing Philippine SRC grades. Deploy direct-to-processor digital portals serving mid-size plant-based beverage startups with pumpable dosing systems. For Investors and Strategic Acquirers: Diversified agricultural conglomerates with integrated seaweed supply chains represent the most active acquirer category in this space. Five-to-ten year viability hinges on extraction facilities achieving backward integration into captive cultivation. Monitor EFSA review cycle outcomes as the critical inflection signal for substitution risk acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seaweed Cultivation | Cargill's multi-origin procurement networks secure volume predictability against Philippine supply volatility. |
| Membrane Filtration Capacity Expansion | Makassar extractors meet FSSAI import specifications for Indian pharmaceutical tablet binding applications. |
| Direct-to-Processor Digital Channel Launch | Proprietary portals bypass distributor markups for oat milk startups requiring pneumatic conveying compatibility. |
| Dual-Formulation Development Investment | Bavarian dairy processors ensure continuity if E407 faces usage restrictions under EFSA protocols. |
| Halal Certification Infrastructure Buildout | Indonesian facilities resolve alcohol precipitation compliance audits across Malaysian supply chains. |
Research Methodology
Direct dialogue with extraction facility plant managers, dairy processor procurement leads, nutraceutical compounder technical directors, and FSSAI regulatory affairs specialists grounded the qualitative foundation. Secondary validation drew from EFSA additive re-evaluation documentation, FDA 21 CFR 172.620 filings, BIS purity standards, Bureau of Fisheries and Aquatic Resources coastal zoning permits, and Indonesian Ministry of Marine Affairs aquaculture directorate records. Bottom-up volume triangulation across product format, application segment, and end-user category reconciled with top-down macroeconomic drivers.
Bottom-up modeling aggregated segment-level volume and value outputs across the projection horizon. Segmentation dimensions included product type hierarchy, application tier differentiation, end-user certification burden, and regional regulatory cluster. CAGRs derived from historical trajectory analysis and forward-looking demand elasticity assessment. Forecast inputs incorporated Kappaphycus alvarezii harvest yield variability and EFSA review cycle timing assumptions.
Underlying measurement precision varies by segment; extracted powder volumes carry tighter precision than emerging lambda variant applications. Forecasts reflect documented assumptions regarding seaweed sustainability certification adoption rates and clean-label substitution velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Food Grade Phosphates Market
Food Additives and Ingredients
Food Protein Ingredient Market
Food Additives and Ingredients
Africa Food Stabilizers Market
Food Additives and Ingredients
Meat Tenderizing Agents Market
Food Additives and Ingredients
Firming Agents Market
Food Additives and Ingredients
Clean Labelled Food Additives Market
Food Additives and Ingredients
Food Humectants Market
Food Additives and Ingredients
Food Grade Calcium Phosphate Market
Food Additives and Ingredients
Spain Food Colorants Market
Food Additives and Ingredients
Japan Food Preservatives Market
Food Additives and Ingredients
Liquid Caramel Color Market
Food Additives and Ingredients
Food Stabilizer Systems Market
Food Additives and Ingredients
China Monosodium Glutamate (MSG) Market
Food Additives and Ingredients
Africa Microbial Food Culture Market
Food Additives and Ingredients
Food Clarifiers Market
Food Additives and Ingredients
Russia Food Emulsifiers Market