
 Brazil Food Acidulants Market | 2026-2036
Brazil Food Acidulants Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Food Acidulants Market Outlook
Technical service contracts for acidulant dosing calibration and pH monitoring systems is consolidating supplier relationships across Brazil's food manufacturing base. Cargill Incorporated leverages its integrated fermentation and distribution network to anchor supply security for citric acid buyers in the Southeast. Tate & Lyle competes through specialized buffering solutions tailored to dairy and beverage applications. Archer Daniels Midland Company dominates import channels for phosphoric acid, controlling port-to-plant logistics from Santos to interior processing hubs.
Food acidulants comprise organic and inorganic compounds—primarily citric, lactic, phosphoric, and tartaric acids—added to food matrices to lower pH, enhance microbial stability, modify flavor profiles, and control gelation in processed products; citric acid dominates production volumes due to its GRAS status and compatibility with clean-label positioning. Citric acid leads the product type landscape as the workhorse acidulant across beverages and confectionery, while lactic acid represents the fastest-growing category driven by fermented dairy expansion and natural preservation trends. Powdered and granular forms command the largest share of acidulant shipments, though liquid formulations gain traction in automated beverage production lines where precision dosing reduces waste.
ANVISA governs acidulant purity specifications and maximum usage levels under Brazilian food additive regulations, while the Ministry of Agriculture enforces Good Manufacturing Practices at processing facilities; these frameworks elevate compliance costs for importers but create barriers that favor established domestic distributors with certified warehousing. The PLI scheme for food processing inputs indirectly supports local acidulant blending investments. Stakeholders must monitor ANVISA's alignment with Codex Alimentarius revisions, as harmonized standards would reshape import qualification pathways for European and Asian acidulant suppliers.
Market Dynamics
ANVISA's tightened purity documentation for imported citric and phosphoric acid is redrawing procurement relationships across Brazil's food manufacturing base, favoring domestic distributors with certified warehousing over direct importers.
Growth Catalysts
- Fermented dairy expansion:Lactic acid demand accelerates as yogurt and cheese processors in Minas Gerais scale natural preservation systems to replace synthetic additives.
- PLI scheme for food processing inputs:The government's production-linked incentive program indirectly subsidizes local acidulant blending investments, reducing import dependency for beverage manufacturers.
- Automated beverage lines:Precision dosing systems in São Paulo processing plants are converting powder users to liquid acidulant formulations, expanding addressable volume per installation.
Market Restraints
- Molasses price volatility:Citric acid fermentation costs swing with sugarcane harvest cycles, compressing margins for domestic producers in the Southeast.
- Port concentration risk:Phosphoric acid imports funnel through Santos, creating single-point vulnerability for interior processors dependent on just-in-time delivery.
- Technical substitution ceiling:Phosphoric acid retains irreplaceable functionality in cola formulations, blocking complete clean-label migration despite consumer pressure.
Strategic Opportunities
- Clean-label positioning:Tartaric acid from grape processing waste offers premium differentiation for organic wine coolers and natural confectionery in Rio Grande do Sul.
- Technical service bundling:Acidulant suppliers can capture recurring revenue by embedding pH monitoring calibration contracts into initial chemical sales.
- Northeast underpenetration:Bahia and Pernambuco food processors remain underserved for bulk acidulant distribution, presenting first-mover warehouse investment potential.
Industry Challenges
- ANVISA documentation backlog:Import qualification timelines for new acidulant suppliers stretch 8-14 months, freezing competitive entry and locking incumbents.
- Fermentation technician scarcity:Citric acid production facilities in Campinas compete with pharmaceutical biotech for skilled microbial process engineers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Food Acidulants Market |
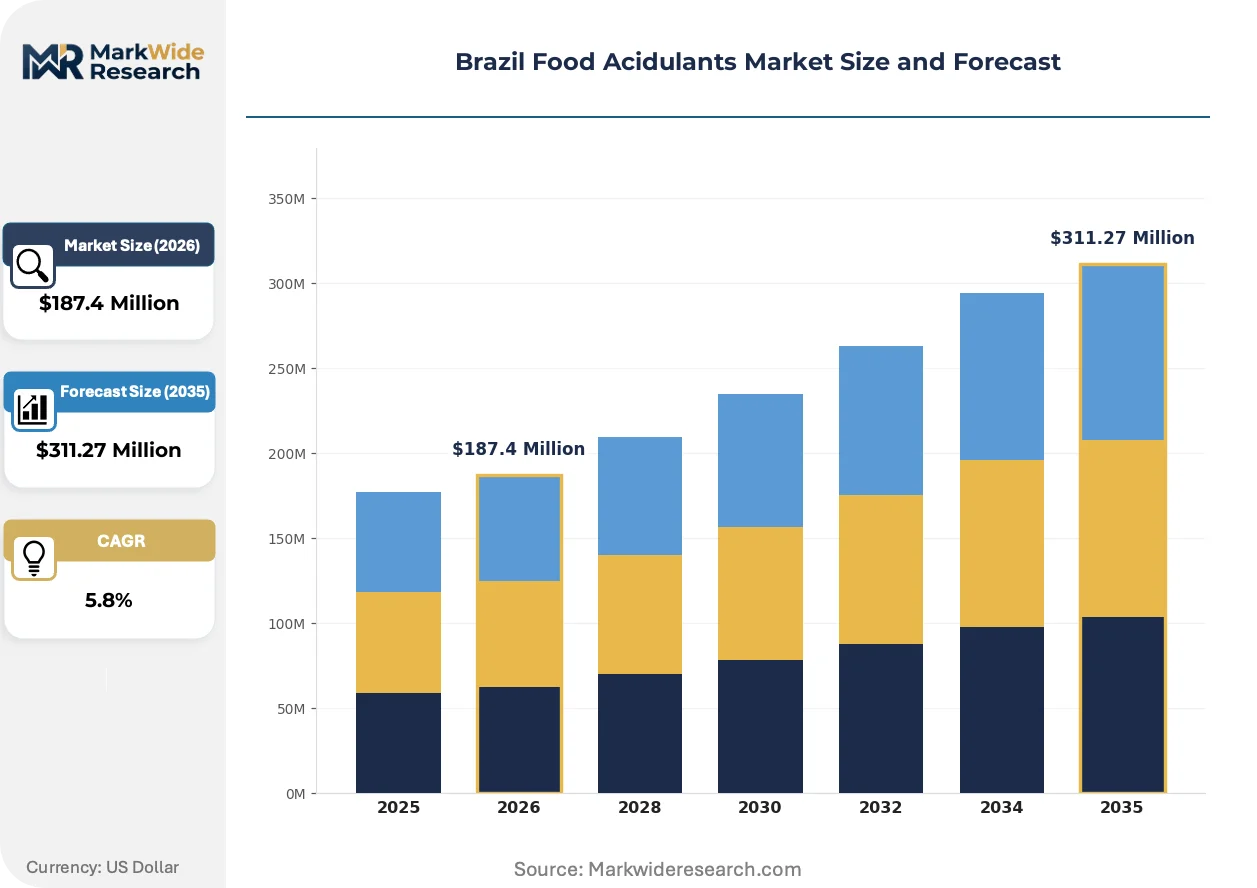
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citric Acid, Lactic Acid, Phosphoric Acid, Tartaric Acid Application: Beverages, Dairy Products, Bakery, Confectionery Form: Liquid, Granular, Powdered, Crystalline End User: Food & Beverage Manufacturers, Food Service Industry, Retail, Household |
| Companies Covered | Cargill Incorporated, Tate & Lyle, Archer Daniels Midland Company, Kemin Industries Inc, Brenntag, Maxsoy Foods, Elekeiroz, CHEMCAR, DuPont de Nemours Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Food Acidulants Market Strategic Shifts
Digital pH control systems and fermentation process analytics are compressing quality variance in acidulant production, while regulatory data harmonization pressures reshape supplier qualification workflows across Brazilian food manufacturing.
Encapsulated citric acid with delayed-release coatings is absorbing demand from sports beverage manufacturers seeking flavor stability through extended shelf life without premature acid degradation. Gatorade and isotonic drink producers in São Paulo are piloting these microencapsulated formats at 15-20% formulation premiums. The technology is absorbing volume share from conventional granular acidulants in segments where taste consistency overrides raw material cost sensitivity.
ANVISA's alignment review with Codex Alimentarius standards is forcing importers to revalidate European and Asian supplier certificates ahead of anticipated mutual recognition protocols. The regulatory friction elevates compliance costs for new market entrants while streamlining documentation for established distributors with pre-positioned certified inventory. Brazilian dairy processors face the steepest recertification burden given their reliance on tartaric acid imports from limited qualified sources.
Direct-to-plant liquid acidulant delivery is displacing bagged powder procurement among high-volume beverage manufacturers seeking to eliminate handling waste and dosing inconsistency. Automated production lines in Ribeirão Preto now specify tanker-fed phosphoric acid systems with integrated flow monitoring. The Northeast region lags this conversion, where smaller processors maintain manual powder handling due to capital constraints and lower throughput volumes.
Brazil Food Acidulants Market Segmentation
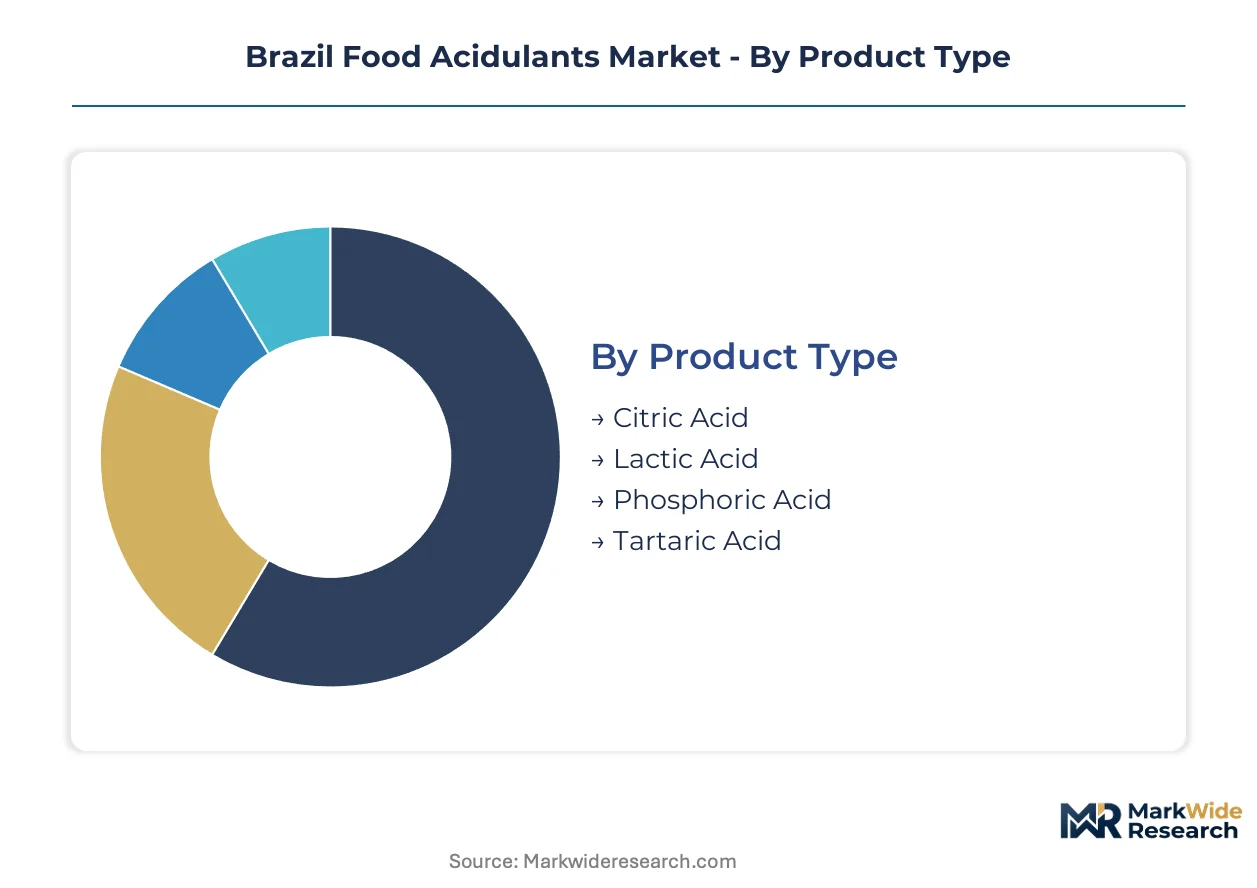
Acidulant procurement patterns in Brazil diverge sharply between commodity-scale beverage processors seeking bulk citric acid and specialized dairy operators demanding precision-formulated lactic acid blends. Segmentation reveals how form factor preferences and end-user scale reshape supplier relationships across São Paulo's industrial corridors and Minas Gerais dairy clusters.
Product Type:
Standalone commodity acidulants dominate procurement volumes, while functional blends embedding pH control systems command premium positioning in automated production environments.
- Citric Acid:Derived from Aspergillus niger fermentation of molasses or sucrose, this GRAS-status acidulant delivers sharp tartness and chelating functionality. Beverage manufacturers in Campinas and Ribeirão Preto anchor procurement volumes for shelf-stable soft drinks, though sugarcane price volatility compresses domestic fermentation margins.
- Lactic Acid:Produced through bacterial fermentation of carbohydrates, this milder acidulant enables clean-label positioning and natural preservation. Yogurt and cheese processors in Minas Gerais drive accelerating demand as synthetic additive replacement intensifies across fermented dairy lines.
- Phosphoric Acid:Inorganic acid supplying intense sourness and rust-inhibiting properties in cola formulations. ANVISA documentation requirements constrain import channels, locking Santos-dependent supply chains for interior processors.
- Tartaric Acid:Naturally occurring dicarboxylic acid from grape processing byproducts. Rio Grande do Sul wine cooler producers leverage this organic positioning for premium differentiation in natural confectionery segments.
Volume placements concentrate in citric acid; the faster expansion belongs to lactic acid.
Application:
Cost tier stratification separates high-throughput commodity applications from formulation-intensive premium segments requiring technical service bundling.
- Beverages:Carbonated soft drinks, sports isotonics, and juice formulations absorb the majority of acidulant tonnage. Automated dosing systems in São Paulo plants are converting powder users to liquid acidulant tanker delivery, eliminating handling waste.
- Dairy Products:Yogurt, cheese, and fermented milk applications prioritize lactic acid for natural preservation alignment. Minas Gerais processors face steepest ANVISA recertification burdens given tartaric acid import dependency.
- Bakery:Dough conditioning and preservative functions utilize acidulants for pH control and mold inhibition. Smaller Northeast bakers maintain manual powder handling due to capital constraints on automated lines.
- Confectionery:Gummy candies and hard sweets require precise acidulant coating for sour flavor delivery. Encapsulated citric acid formats absorb demand at formulation premiums where taste stability overrides raw material cost sensitivity.
Revenue margins peak in confectionery; operational tonnage flows through beverages.
Form:
Supply concentration in powder and granular formats is yielding to liquid system penetration where precision dosing infrastructure exists.
- Liquid:Pre-dissolved acidulant solutions enabling automated flow monitoring and reduced handling labor. High-volume beverage lines in Ribeirão Preto now specify tanker-fed phosphoric acid systems with integrated pH calibration.
- Granular:Free-flowing crystalline particles balancing dissolution speed with storage stability. Campinas confectionery plants favor this format for controlled-release sour coating applications.
- Powdered:Fine-milled acidulant for dry-blend incorporation and extended shelf stability. Remains dominant in Northeast processing where smaller throughput volumes resist capital conversion to liquid systems.
- Crystalline:Large-particle acidulant for slow-dissolution applications and visual texture differentiation. Limited penetration outside premium organic product positioning.
Shipments concentrate in granular and powdered forms; liquid formats are climbing the fastest.
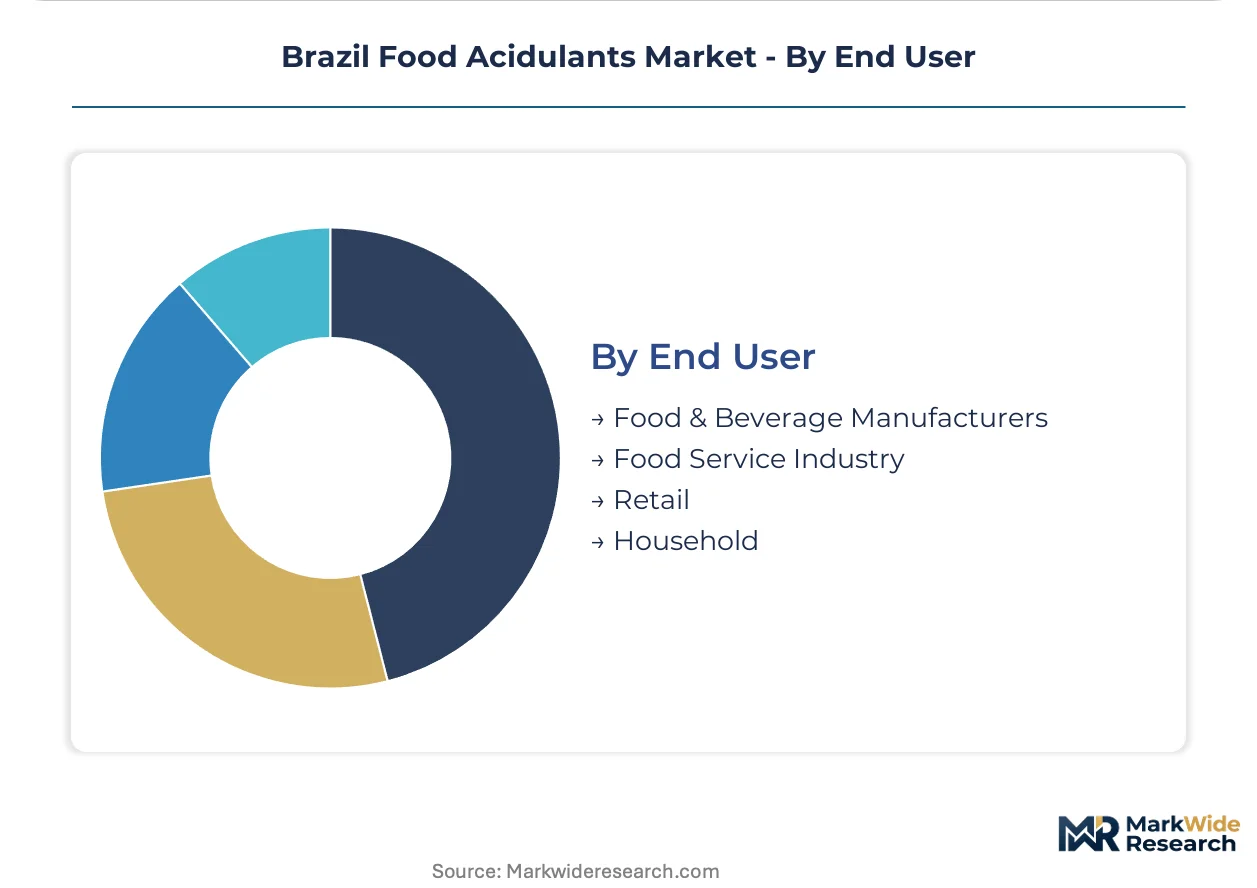
End User:
Customer scale determines procurement modality, with industrial manufacturers demanding technical service contracts and retail channels prioritizing packaged unit convenience.
- Food & Beverage Manufacturers:Industrial-scale processors purchasing bulk acidulant with embedded pH monitoring calibration and dosing system maintenance. Southeast cluster concentration around Campinas drives supplier warehouse proximity requirements.
- Food Service Industry:Restaurant chains and institutional caterers sourcing pre-formulated acidulant blends for sauce and beverage preparation. Bahia and Pernambuco segments remain underserved for bulk distribution infrastructure.
- Retail:Packaged acidulant for consumer home preservation and cooking applications. Limited penetration given Brazilian household preference for fresh ingredient consumption.
- Household:Small-unit sales through supermarkets and convenience channels for occasional domestic use. Marginal volume contribution relative to industrial procurement scales.
Procurement volume concentrates in food and beverage manufacturers; food service channels show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's acidulant production clusters in São Paulo and Minas Gerais, yet consumption spreads across five macro-regions with divergent processing scales and import dependencies. The Southeast dominates procurement volumes while regulatory friction shapes supplier access elsewhere.
São Paulo
Campinas and Ribeirão Preto anchor beverage manufacturing corridors where automated dosing systems convert powder users to liquid acidulant tanker delivery. ANVISA's warehousing certification requirements favor established distributors with pre-positioned inventory. Santos port concentration creates single-point vulnerability for phosphoric acid supply chains serving interior processors.
Minas Gerais
Yogurt and cheese processors in Belo Horizonte and surrounding dairy belts drive accelerating lactic acid demand for synthetic additive replacement. The state's fermentation facilities compete with pharmaceutical biotech for skilled microbial process engineers. PLI scheme subsidies indirectly support local acidulant blending investments reducing import dependency.
Rio Grande do Sul
Wine cooler producers in Serra Gaúcha leverage tartaric acid from grape processing waste for premium organic positioning. ANVISA's alignment review with Codex Alimentarius standards forces tartaric acid importers to revalidate European supplier certificates. Porto Alegre food manufacturers face steepest recertification burdens given limited qualified import sources.
Bahia
Food processors in Salvador and Feira de Santana remain underserved for bulk acidulant distribution infrastructure. Smaller bakeries maintain manual powder handling due to capital constraints on automated liquid dosing systems. First-mover warehouse investment potential exists for suppliers establishing certified storage capacity.
Paraná
Curitiba's processed meat and condiment manufacturers absorb citric acid for pH control and preservative functions. The state's interior cities lag Southeast automation levels, preserving granular format dominance. Regional distributors without ANVISA-certified warehousing struggle to compete against São Paulo-based incumbents.
Brazil Food Acidulants Market Competitive Environment
Top-tier vendors anchor supply security through integrated fermentation and port-to-plant logistics, while mid-tier distributors compete on technical service bundling and regional warehouse proximity. The market exhibits tiered concentration with three to four dominant import-channel controllers and a fragmented base of local blenders. Strategic archetypes include integrated fermentation specialists, import-logistics orchestrators, and application-focused technical service providers. Capacity expansion and pH monitoring calibration contract embedding represent the dominant competitive moves reshaping supplier relationships.
Within the integrated supply tier, Cargill Incorporated leverages its fermentation network and distribution infrastructure to anchor citric acid security for Southeast buyers. Tate & Lyle occupies a position exemplifying application-focused specialization through buffering solutions. Archer Daniels Midland Company represents import-logistics dominance controlling phosphoric acid channels from Santos to interior hubs.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Tate & Lyle |
| Archer Daniels Midland Company |
| Kemin Industries Inc |
| Brenntag |
| Maxsoy Foods |
| Elekeiroz |
| CHEMCAR |
| DuPont de Nemours Inc |
| Others |
Value Chain & Pricing Dynamics
Sugarcane molasses price indices cascade through Brazilian acidulant supply chains, compressing fermentation margins in the Southeast while elevating procurement premiums for Northeast processors dependent on trucked-in inventory. ANVISA-certified warehousing scarcity concentrates pricing power among São Paulo distributors capable of pre-positioning buffer stock against harvest volatility.
Pricing Analysis
Margin tightening in standard-grade citric acid reflects sugarcane harvest cyclicality and energy cost pass-through from fermentation facilities. Three-tier pricing structure across pharmaceutical-grade, food-grade, and technical-grade certifications separates premium positioning from commodity tonnage. Cost-down pressure on powdered formats accelerates as automated beverage lines convert to liquid tanker delivery systems. Small-scale Northeast bakeries exhibit highest price sensitivity due to capital constraints blocking liquid system adoption.
Supply Chain Analysis
Direct-to-plant tanker channels handle high-volume beverage demand in Campinas and Ribeirão Preto, while bagged powder distribution serves smaller processors through regional distributors. Manufacturing concentrates in Brazil's Southeast fermentation corridor with phosphoric acid sourcing tethered to Chinese and Moroccan import flows. Raw material dependencies span sugarcane molasses, sulfuric acid for pH adjustment, and phosphate rock derivatives. Single-port concentration at Santos creates vulnerability for interior phosphoric acid consumers. Distribution runs through certified warehouse networks with ANVISA documentation gates filtering supplier access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's food acidulant sector sits at a formulation transition phase, with liquid precision-dosing infrastructure displacing legacy powder handling systems across high-volume beverage manufacturing.
For Market Incumbents: Acquire certified warehousing capacity in Bahia and Pernambuco to preempt first-mover positioning in underpenetrated Northeast markets. Backward integration into sugarcane fermentation feedstock secures margin defense against molasses price volatility. ANVISA documentation expertise constitutes a defensible moat against import-channel entrants facing 8-14 month qualification timelines.
For New Entrants and Emerging Players: Encapsulated citric acid with delayed-release coatings offers technology-first positioning into sports beverage premium segments where formulation premiums absorb higher input costs. Tartaric acid recovery from Rio Grande do Sul wine waste streams presents white-space entry with organic certification differentiation. Technical service bundling embedding pH monitoring calibration contracts enables recurring revenue capture against commodity-only competitors.
For Investors and Strategic Acquirers: Distressed-cycle entries favor regional distributors with pre-qualified ANVISA warehousing in interior states lacking incumbent density. Long-term viability across the analysis window hinges on automation-conversion exposure in beverage processing clusters. Monitor PLI scheme subsidy renewals as policy inflection signals for local blending investment economics.
| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA-Certified Warehouse Expansion | Pre-positioned inventory in Salvador and Recife captures Northeast acidulant demand before incumbent response. |
| Liquid Acidulant Tanker Infrastructure | Tanker-fed phosphoric acid systems in Ribeirão Preto eliminate powder handling waste and dosing variance. |
| Encapsulated Citric Acid R&D Partnership | Microencapsulation technology from sports beverage pilots at 15-20% formulation premiums expands addressable margin pools. |
| Fermentation Technician Training Programs | Campinas facilities compete with pharmaceutical biotech for microbial process engineers, elevating human capital scarcity. |
| PLI-Aligned Local Blending Investment | Government production-linked incentives reduce import dependency for Minas Gerais dairy processors seeking synthetic additive replacement. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving acidulant procurement managers at São Paulo beverage manufacturers, ANVISA compliance officers, fermentation facility technical directors, and Northeast regional distribution heads. Secondary sources included ANVISA additive purity standards, Ministry of Agriculture GMP enforcement records, Brazilian customs import documentation, and Codex Alimentarius alignment review proceedings. Bottom-up volume modeling from individual facility throughput reconciled against top-down sector aggregates from industry association membership data.
Reconciliation of production volume data, import flow records, and end-use consumption surveys informed the analytical framework across the projection horizon. Segmentation dimensions encompassed acidulant type, application category, physical form, and end-user scale tier. CAGRs derived from trend extrapolation of historical volume trajectories adjusted for PLI scheme impact, automation conversion rates, and regulatory documentation timeline effects. Forecast inputs incorporated sugarcane harvest cycle patterns, phosphoric acid import channel concentration, and encapsulated format adoption curves from sports beverage pilot programs.
Several conditions sit outside the modeled scope, including extreme weather disruption to Center-South sugarcane harvests, abrupt ANVISA regulatory reversals on Codex harmonization, and phosphoric acid supply interruptions at Santos port. Forecasts reflect base-case assumptions regarding continued PLI scheme operation and gradual automation penetration across beverage processing lines. Periodic stress-testing of base assumptions is recommended given commodity price volatility and single-point logistics vulnerabilities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
United Kingdom Food Preservatives Market
Food Additives and Ingredients
Neohesperidine DC Market
Food Additives and Ingredients
Egypt Food Enzymes Market
Food Additives and Ingredients
PVPP Beer Stabilizer Market
Food Additives and Ingredients
Fat Replacers Salt Reducers and Replacers Market
Food Additives and Ingredients
Food Grade Ammonium Carbonate Market
Food Additives and Ingredients
Microencapsulated Phytosterols Market
Food Additives and Ingredients
Spain Food Additives Market
Food Additives and Ingredients
Russia Food Enzymes Market
Food Additives and Ingredients
Lycopene Food Colors Market
Food Additives and Ingredients
Asia-Pacific Food Emulsifier Market
Food Additives and Ingredients
Ellagic Acid Market
Food Additives and Ingredients
Microencapsulation Market
Food Additives and Ingredients
South America Food Colorants Market
Food Additives and Ingredients
Acetylated Monoglycerides (AMG) Market
Food Additives and Ingredients
Egypt Food Emulsifiers Market