
 Europe Food Acidulants Market | 2026-2036
Europe Food Acidulants Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Food Acidulants Market Foresight
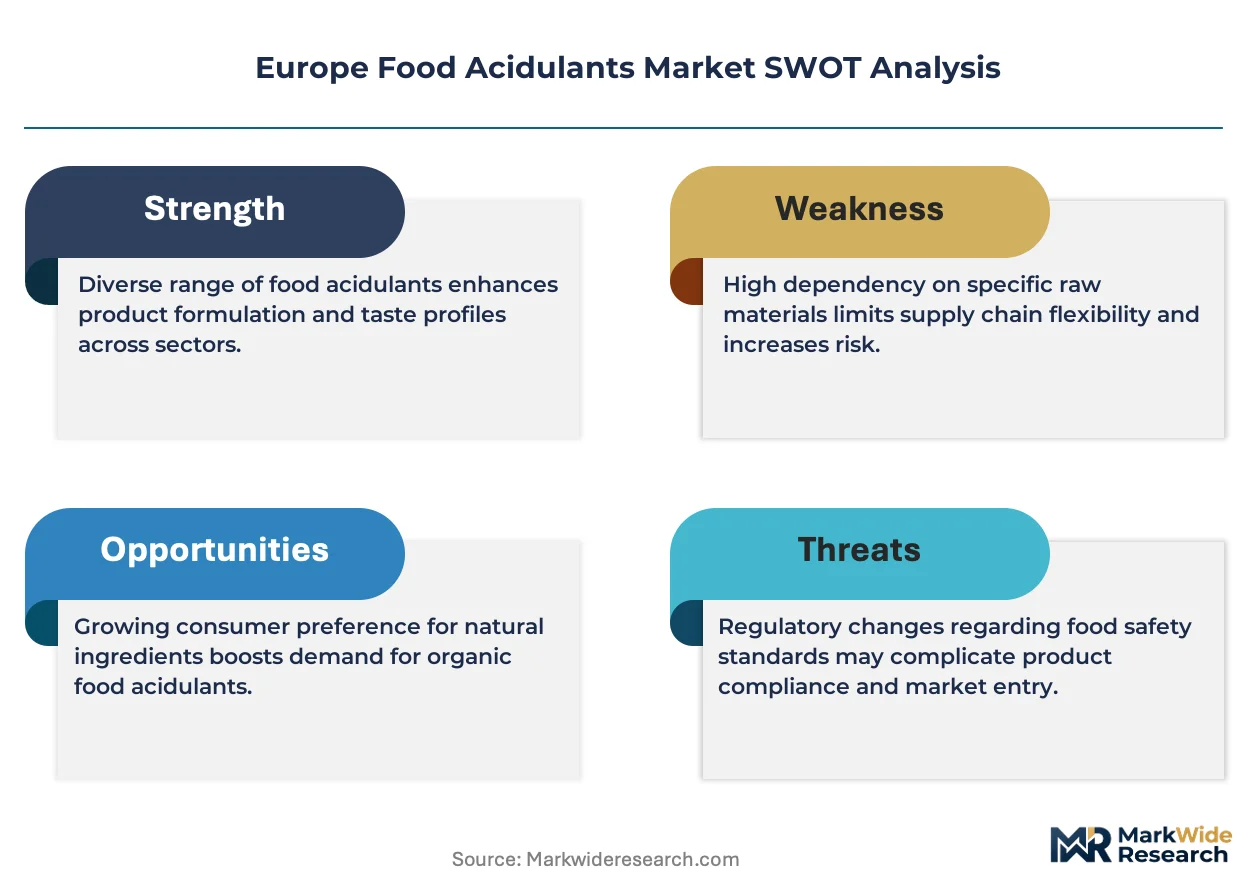
REACH compliance is consolidating the supplier landscape for food-grade acidulants across Europe. Cargill Incorporated leverages its integrated fermentation capacity to secure citric acid supply chains from Central European facilities. Jungbunzlauer Suisse anchors the premium organic acid segment through Swiss manufacturing precision and sustained EFSA-compliant certification programs. Corbion NV differentiates via biobased lactic acid platforms that align with EU Green Deal carbon intensity benchmarks.
Food acidulants comprise organic and inorganic compounds—primarily citric, phosphoric, lactic, and acetic acids—used to regulate pH, enhance flavor profiles, and extend shelf stability in processed foods. Industrial production relies on submerged fermentation of carbohydrate feedstocks followed by crystallization or liquid concentration to achieve food-grade purity specifications typically exceeding 99.5% active content. Citric acid dominates volume flows due to its versatility across beverage acidification and preservative applications, while lactic acid captures expanding margin pools in dairy processing and plant-based alternatives. Powder and granular forms command logistical premiums in bakery and confectionery channels where moisture control dictates handling protocols.
EMA food-contact guidelines, EFSA additive safety assessments, and EU Green Deal sustainability disclosures collectively determine formulation eligibility and import access for acidulant suppliers. ECHA substance registration requirements now extend to fermentation-derived intermediates, forcing reformulation investments among non-integrated compounders. Stakeholders must monitor impending CSRD supply-chain transparency mandates that will expose Scope 3 emissions from Southeast Asian citric acid feedstock origins.
Market Dynamics
REACH registration deadlines and ECHA substance evaluation protocols are compressing supplier timelines while consolidating procurement toward integrated fermentation operators with captive EFSA-compliant certification pathways.
Growth Catalysts
- Clean-label beverage reformulation:German and French bottlers are replacing synthetic preservatives with citric and lactic acid blends to meet retailer E-number reduction mandates.
- F-Gas Regulation phase-down:The EU's hydrofluorocarbon restrictions are accelerating investment in fermentation-derived acidulants with lower process refrigeration footprints.
- Plant-based dairy expansion:Dutch and Belgian processing clusters are scaling lactic acid procurement for oat and soy protein stabilization in yogurt analogues.
Market Restraints
- Molasses feedstock volatility:Sugar beet supply fluctuations in Eastern European growing regions create citric acid input cost instability for non-integrated compounders.
- Southeast Asian citric acid concentration:Chinese and Thai fermentation capacity dominates global powder flows, exposing European buyers to shipping disruption and carbon border adjustment exposure.
- Phosphoric acid substitution ceiling:Cola manufacturers face technical barriers replacing phosphoric acid in classic formulations without sensory profile degradation.
Strategic Opportunities
- Polish and Romanian bakery penetration:Eastern European confectionery channels remain underdeveloped for encapsulated acidulant systems that extend shelf life in humid climates.
- CSRD supply-chain disclosure readiness:Early compliance with EU corporate sustainability reporting mandates creates differentiation for acidulant suppliers with verified Scope 3 traceability.
- Biobased lactic acid-platform convergence:Integration of fermentation-derived lactides with biodegradable packaging films opens adjacent material science revenue pools.
Industry Challenges
- Fermentation process engineering talent scarcity:European universities produce insufficient metabolic engineering graduates to staff expanded citric acid and lactic acid production facilities.
- Multi-jurisdiction certification lag:Simultaneous EFSA novel food evaluation and national food-contact approvals create 18-24 month commercialization timelines for new acidulant salts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Food Acidulants Market |
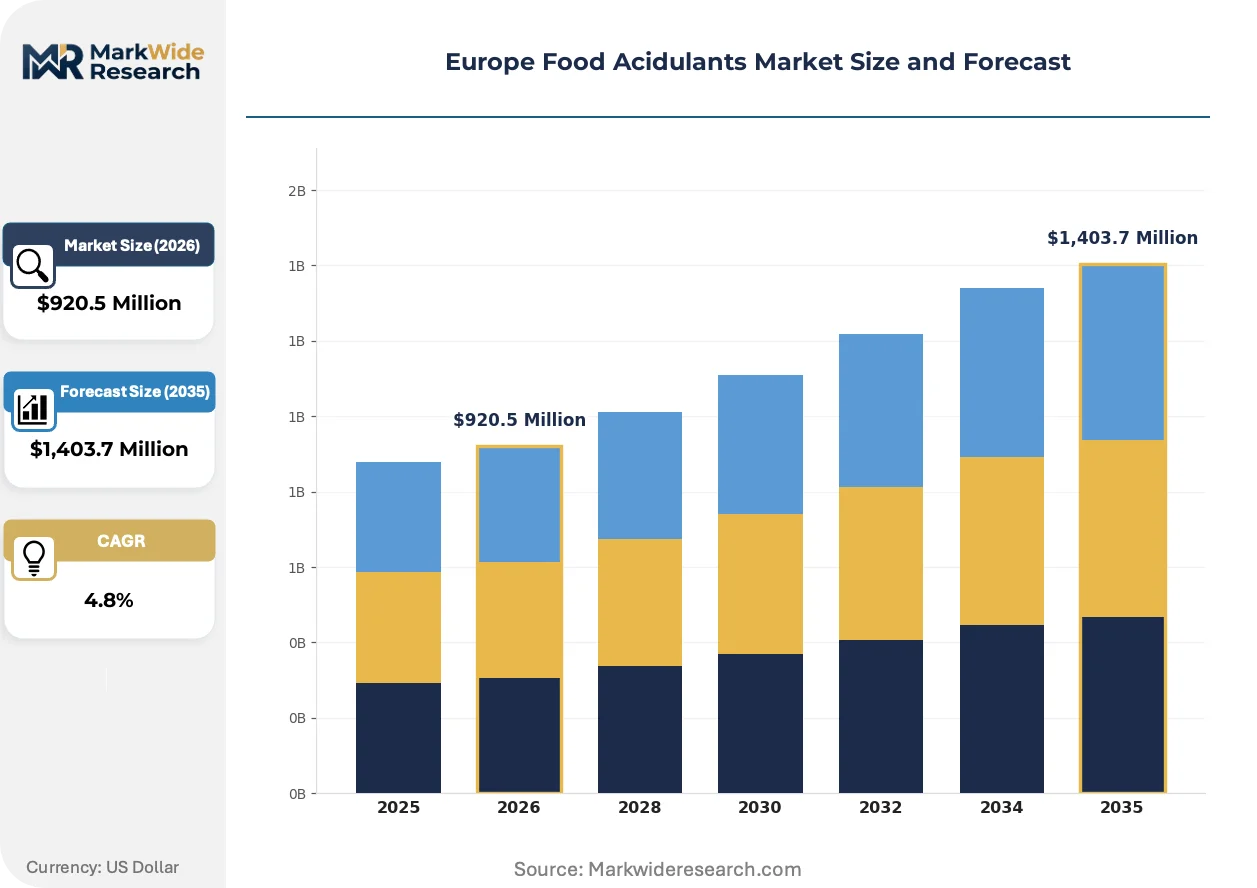
| Market Size in 2026 | $920.5 Million |
| Market Size in 2035 | $1,403.7 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citric Acid, Phosphoric Acid, Lactic Acid, Acetic Acid Application: Beverages, Bakery Products, Dairy, Confectionery Form: Liquid, Powder, Granular, Crystal End User: Food Manufacturers, Beverage Producers, Catering Services, Retailers |
| Companies Covered | Brenntag SE, Cargill Incorporated, Jungbunzlauer Suisse, Hawkins Watts, ADM, Corbion NV, Archer Daniels Midland Company, FBC Industries, Tate & Lyle PLC, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Food Acidulants Market Shifts & Advancements
Continuous fermentation monitoring and downstream crystallization automation are compressing batch-to-batch variability while enabling real-time purity adjustments that meet tightening EFSA specification bands.
Precision fermentation using CRISPR-edited Aspergillus strains is rewriting citric acid yield economics. Dutch biotechnology operators are deploying these platforms at 50,000-liter scale to serve Benelux beverage contracts. The technology is rewriting competitive entry barriers by reducing capital intensity for mid-volume acidulant production.
EU Green Deal carbon intensity benchmarking now mandates Scope 1 and Scope 2 disclosure for fermentation facilities above 500-tonne annual capacity. German and French acidulant processors are retrofitting combined heat and power systems to maintain EFSA-compliant site certification. The regulation most affects citric acid granulation operations near Rotterdam and Antwerp port clusters.
Ingredient buyers in Nordic retail channels are consolidating acidulant procurement through cooperative sourcing platforms that bypass traditional distribution tiers. Swedish and Danish food manufacturers now contract directly with Jungbunzlauer Suisse and Corbion NV for annual volume commitments. This pattern is most visible in plant-based dairy processing where formulation stability requirements demand technical service integration unavailable through commodity traders.
Europe Food Acidulants Market Segmentation
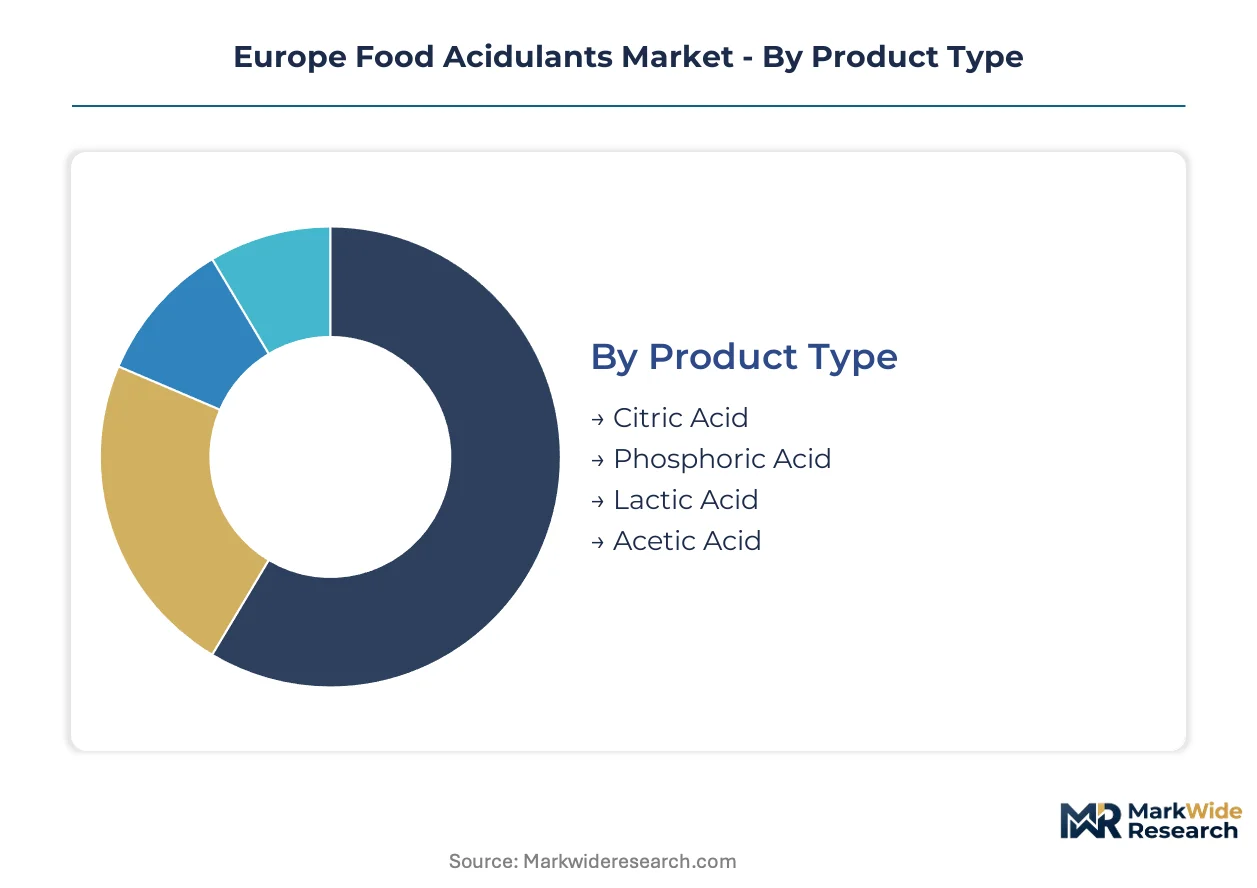
Food acidulant procurement patterns across Europe diverge sharply by product chemistry, application intensity, and handling requirements. Supply chain configuration and REACH compliance burdens create distinct margin structures within each segment category.
Product Type:
Production gravity concentrates around fermentation-derived organic acids with captive EFSA certification pathways.
- Citric Acid:Derived via submerged fermentation of carbohydrate feedstocks, typically achieving purity above 99.5% active content. German and French beverage bottlers dominate procurement for clean-label reformulations replacing synthetic preservatives. REACH registration complexity favors integrated operators with Central European fermentation capacity.
- Lactic Acid:Biobased platforms utilizing bacterial fermentation of sugars yield polymer-grade and food-grade specifications. Dutch and Belgian plant-based dairy processors drive demand for oat and soy protein stabilization in yogurt analogues. Corbion NV's biobased production aligns with EU Green Deal carbon intensity benchmarks.
- Phosphoric Acid:Inorganic mineral acid produced through wet-process phosphate rock treatment. Cola manufacturers retain this acid for classic formulations despite clean-label substitution pressure elsewhere in beverage portfolios.
- Acetic Acid:Bacterial oxidation of ethanol yields food-grade vinegar concentrates and pure acid specifications. Eastern European pickling and sauce manufacturers represent concentrated demand pockets.
Today's leader: Citric Acid. Tomorrow's challenger: Lactic Acid.
Application:
Cost tier differentiation separates high-volume commodity acidification from premium formulation stability services.
- Beverages:Carbonated soft drinks, juices, and functional waters require precise pH regulation between 2.5 and 4.0 for microbial stability and sensory balance. German retail chains mandate E-number reductions, accelerating citric-lactic acid blend adoption.
- Dairy:Fermented milk products and fresh cheese applications demand lactic acid for pH control and protein coagulation. Benelux processing clusters scale procurement for plant-based dairy expansion.
- Bakery Products:Encapsulated acidulant systems extend shelf life in humid climates through controlled release. Polish and Romanian confectionery channels remain underdeveloped for moisture-sensitive formulations.
- Confectionery:Hard candies and gelled sweets utilize acidulants for flavor enhancement and sugar inversion control. Swiss and Austrian premium chocolate manufacturers specify crystalline forms for precise dosing.
Beverages command volume dominance; dairy applications are climbing the fastest on plant-based substitution trends.
Form:
Handling protocols and moisture sensitivity dictate logistics premiums across physical specifications.
- Powder:Free-flowing crystalline material with standardized particle size distribution. Bakery and confectionery channels pay logistics premiums for moisture control in humid supply chains.
- Liquid:Aqueous solutions at 50-80% concentration reduce handling costs for high-volume beverage processors. Rotterdam and Antwerp port clusters concentrate liquid acidulant storage and blending operations.
- Granular:Agglomerated particles with enhanced flow properties for automated dosing systems. German meat processing applications favor this form for brine injection consistency.
- Crystal:High-purity monoclinic or anhydrous crystals for premium applications requiring visual clarity. Pharmaceutical-adjacent food specifications command margin premiums.
Powder leads current procurement volumes; liquid forms gain share fastest on beverage industry automation investments.
End User:
Customer type determines technical service intensity and contract structure complexity.
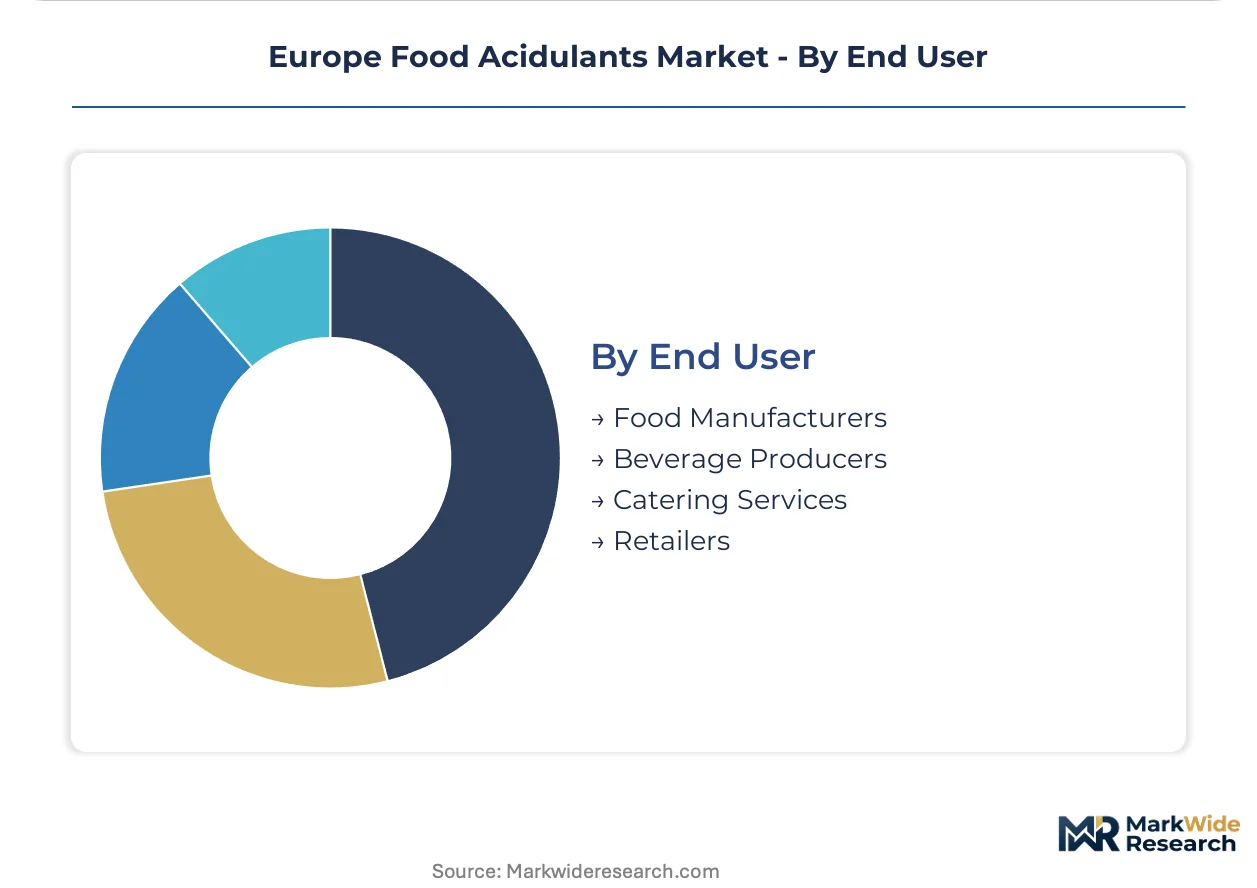
- Food Manufacturers:Integrated processing operations with captive formulation laboratories. Nordic retail cooperatives bypass distribution tiers to contract directly with Jungbunzlauer Suisse for annual volume commitments.
- Beverage Producers:Bottling operations with just-in-time acidification requirements. French mineral water producers specify dual-sourcing strategies to mitigate supply disruption risks.
- Catering Services:Institutional foodservice operations with standardized menu acidification needs. Airport and railway catering hubs around Frankfurt and Paris concentrate demand.
- Retailers:Private-label brand owners specifying acidulant blends for shelf-stable prepared foods. Discounter chains in Germany and Poland drive cost-optimized procurement through centralized buying.
Food Manufacturers anchor procurement value; Beverage Producers show steepest expansion trajectory on clean-label reformulation timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metabolic engineering talent concentrates in Dutch and German university corridors, anchoring fermentation-based acidulant production clusters. Benelux processing hubs leverage this workforce density to scale biobased lactic acid platforms. REACH compliance costs are consolidating procurement toward integrated operators with captive certification pathways.
Germany
Beverage bottlers in Bavaria and North Rhine-Westphalia are expanding citric acid procurement for clean-label reformulations replacing synthetic preservatives. The country's F-Gas Regulation enforcement is accelerating investment in fermentation-derived acidulants with lower refrigeration footprints. Frankfurt airport catering hubs concentrate institutional acidulant demand for standardized menu applications.
Netherlands
Plant-based dairy processors around Rotterdam and Utrecht are scaling lactic acid volumes for oat and soy protein stabilization in yogurt analogues. Dutch REACH registration deadlines are compressing supplier timelines toward integrated fermentation operators. The Rotterdam-Antwerp port cluster anchors liquid acidulant storage and blending operations serving Benelux beverage contracts.
France
Mineral water producers in the Auvergne-Rhône-Alpes region specify dual-sourcing strategies to mitigate supply disruption risks. EFSA additive safety assessments determine formulation eligibility for acidulant suppliers accessing French retail channels. Paris-based discounter chains drive cost-optimized procurement through centralized buying for private-label prepared foods.
Belgium
Confectionery manufacturers in Flanders utilize encapsulated acidulant systems for moisture-sensitive formulations in humid supply chains. The country's ECHA substance evaluation protocols extend to fermentation-derived intermediates, forcing reformulation investments. Antwerp's granulation operations serve German meat processing applications favoring automated dosing consistency.
Poland
Bakery and confectionery channels in Warsaw and Krakow remain underdeveloped for encapsulated acidulant systems extending shelf life. The country's sugar beet supply fluctuations create citric acid input cost instability for non-integrated compounders. Polish retail cooperatives are consolidating acidulant procurement through centralized platforms bypassing traditional distribution tiers.
Europe Food Acidulants Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the European food acidulants landscape. The supplier base compresses toward integrated fermentation operators with captive EFSA-compliant certification pathways. Three archetypes dominate: multinational ingredient conglomerates with backward integration into carbohydrate feedstocks, Swiss precision manufacturers anchoring premium organic acid segments, and biobased platform specialists aligning with EU Green Deal carbon benchmarks. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with fermentation process engineering talent scarcity forcing collaborative R&D arrangements.
Within the integrated conglomerate tier, Cargill Incorporated and Archer Daniels Midland Company exemplify backward integration into Central European fermentation capacity. Jungbunzlauer Suisse occupies a position representing Swiss manufacturing precision and sustained EFSA-compliant certification programs. Corbion NV anchors the biobased specialist archetype through fermentation-derived platforms that align with EU Green Deal carbon intensity disclosure requirements. These three companies collectively illustrate the competitive tension between scale-driven feedstock security and premium-tier certification differentiation.
| Leading Market Players |
|---|
| Brenntag SE |
| Cargill Incorporated |
| Jungbunzlauer Suisse |
| Hawkins Watts |
| ADM |
| Corbion NV |
| Archer Daniels Midland Company |
| FBC Industries |
| Tate & Lyle PLC |
| Others |
Supply & Pricing Matrix
EFSA certification tiers split European acidulant procurement into parallel tracks, with REACH-registered integrated operators capturing 15-20% logistics premiums over non-integrated compounders while commodity citric acid flows through Rotterdam-Antwerp spot markets. This bifurcation concentrates margin capture among fermentation operators with captive certification pathways and fragments pricing power across Southeast Asian import-dependent distributors.
Pricing Analysis
The bundled-versus-unbundled service split separates Nordic retail cooperatives contracting directly with Jungbunzlauer Suisse for technical service integration from spot-market buyers in Eastern Europe. Three-tier pricing structure across premium, standard, and economy levels tracks EFSA compliance grade, molasses feedstock origin, and volume commitment scale. Pricing pressure stems from Chinese citric acid oversupply flooding Rotterdam spot markets. Discounter chains in Germany and Poland exhibit highest price sensitivity; Swiss confectionery manufacturers show lowest.
Supply Chain Analysis
Direct-to-beverage-producer channels handle German and French bottler demand for clean-label reformulations, while distributor networks serve Polish and Romanian bakery channels. Supply concentrates in Chinese and Thai fermentation capacity for citric acid, Dutch and Belgian biobased platforms for lactic acid, and Central European sugar beet zones for molasses feedstock. Raw material dependencies include carbohydrate feedstocks, phosphate rock, and fermentation nutrients. Carbon border adjustment exposure creates structural risk for Southeast Asian import flows. Distribution runs through Rotterdam-Antwerp liquid storage clusters and Central European powder granulation facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between REACH-compliant integrated operators in Central Europe and carbon-intensive Southeast Asian import sources, with the EU Green Deal's Scope 3 disclosure mandates widening cost differentials.
For Market Incumbents: Anticipate CRSD supply-chain transparency mandates compressing margins for non-integrated compounders by securing captive fermentation capacity in Poland or Romania. Defend position through backward integration into sugar beet feedstock zones and precision fermentation R&D partnerships with Dutch biotechnology operators. Certification investment represents the critical lever for maintaining Nordic retail cooperative contracts.
For New Entrants and Emerging Players: Begin with Polish and Romanian bakery channels where encapsulated acidulant systems remain underpenetrated for humidity-stable shelf-life extension. Target plant-based dairy processing clusters around Rotterdam and Utrecht for lactic acid technical service integration. Position through direct contracting with retail cooperatives bypassing traditional distribution markups.
For Investors and Strategic Acquirers: Consolidation pressure builds where REACH registration deadlines eliminate non-integrated compounders without EFSA-compliant certification pathways. Long-term viability favors biobased platform specialists with verified Scope 3 traceability and fermentation process engineering talent retention. Watch for CSRD disclosure mandates triggering distressed asset availability among import-dependent distributors.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | CRISPR-edited Aspergillus strains at 50,000-liter capacity serve Benelux beverage contracts. |
| Backward Integration into Feedstocks | Captive sugar beet supply in Eastern Europe insulates citric acid production from molasses volatility. |
| EFSA-Compliant Certification Investment | Sustained additive safety assessment programs unlock Nordic retail cooperative procurement channels. |
| CSRD Supply-Chain Disclosure Readiness | Verified Scope 3 traceability creates differentiation ahead of corporate sustainability reporting mandates. |
| Combined Heat and Power Retrofit | Rotterdam-Antwerp granulation facilities maintain site certification under EU Green Deal carbon benchmarks. |
Research Methodology
Coverage spans Western European processing clusters and Eastern European growth corridors, with primary inputs from each. The research combines interviews with fermentation plant managers, beverage procurement leads at German and French bottlers, Dutch plant-based dairy R&D directors, and Polish bakery channel distributors with secondary validation. Sources include EFSA additive safety assessments, ECHA substance registration databases, EU customs trade flows, and SEC filings from listed ingredient conglomerates. Bottom-up volume triangulation across product chemistry segments and top-down macroeconomic calibration ensure cross-verified outputs.
Rate-of-change decomposition separates volume growth drivers from price-mix effects across the analysis window. The analytical framework models product type, application intensity, physical form, and end-user contract structure dimensions. CAGRs derive from segment-level production capacity expansion schedules, clean-label reformulation adoption curves, and regulatory compliance cost pass-through assumptions. Forecast inputs incorporate REACH registration deadline impacts and F-Gas Regulation phase-down timelines for fermentation refrigeration footprints.
Several conditions sit outside the modeled scope, including abrupt Southeast Asian supply disruptions, sugar beet crop failures beyond historical variance, and unanticipated EFSA novel food evaluation delays. Forecasts reflect assumptions about regulatory implementation pacing and buyer substitution elasticity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Global Integrated Food Ingredient Market
Food Additives and Ingredients
Food Grade Ammonium Carbonate Market
Food Additives and Ingredients
AKD Emulsifier Market
Food Additives and Ingredients
Calcium Inosinate Market
Food Additives and Ingredients
Gellan Gum Market
Food Additives and Ingredients
France Food Acidulants Market
Food Additives and Ingredients
Argentina Food Emulsifiers Market
Food Additives and Ingredients
Japan Food Preservatives Market
Food Additives and Ingredients
Japan Food Emulsifiers Market
Food Additives and Ingredients
Ascorbyl Palmitate Market
Food Additives and Ingredients
Acetylated Distarch Phosphate Market
Food Additives and Ingredients
China Anti-Caking Market
Food Additives and Ingredients
US Food Emulsifiers Market
Food Additives and Ingredients
United States Food Enzymes Market
Food Additives and Ingredients
Mexico Food Emulsifiers Market
Food Additives and Ingredients
Argentina Food Colorants Market