
 Global Bitterness Suppressors and Flavor Carriers Market | 2026-2036
Global Bitterness Suppressors and Flavor Carriers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bitterness Suppressors and Flavor Carriers Market Intelligence
Food Safety System Certification (FSSC) 22000 compliance is redrawing the competitive landscape, setting a high barrier for new entrants in food-grade applications. Givaudan leverages its extensive R&D in taste modulation technologies to serve multinational clients. Kerry Group sustains its market position through a broad portfolio covering both suppressors and complex flavor systems. Symrise specializes in solutions for the pharmaceutical and nutraceutical sectors, addressing complex taste-masking challenges.
Bitterness suppressors and flavor carriers are functional ingredients designed to modify sensory perception and improve product palatability. Suppressors work by blocking or interfering with the tongue's bitter taste receptors (T2Rs), while carriers encapsulate or solubilize flavor compounds for uniform distribution and stability. Within applications, the beverage segment leads in volume, driven by functional drinks and low-sugar formulations. Natural suppressors represent the fastest-growing product type, aligning with consumer demand for clean-label ingredients.
Ingredient safety and labeling are governed by stringent frameworks from the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA). These regulations, particularly the Generally Recognized as Safe (GRAS) process in the US, dictate market access and formulation choices. In China, National Medical Products Administration (NMPA) standards for pharmaceutical excipients influence the use of these agents in medications. Success for ingredient manufacturers now depends on navigating this complex, multi-jurisdictional regulatory environment while innovating in natural-origin solutions.
Market Dynamics
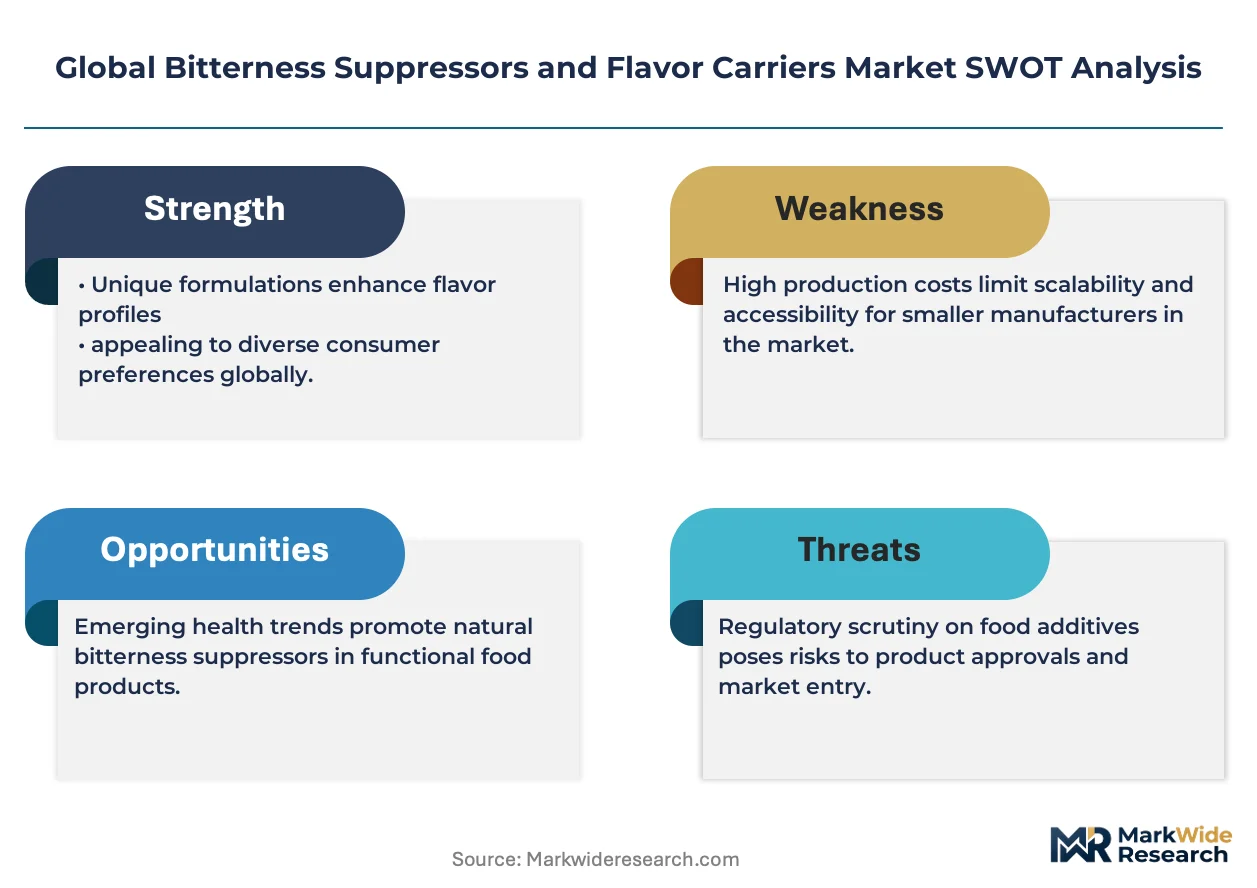
The central force shaping this market is the concurrent demand from two distinct sectors: the food and beverage industry's aggressive move toward sugar reduction and the pharmaceutical industry's need for more palatable oral medications for patient compliance.
Growth Catalysts
- Clean-Label Demand:Consumer preference for natural and non-GMO ingredients is accelerating the development and adoption of plant-derived bitterness suppressors, particularly in the functional food and beverage segments.
- Pharmaceutical Palatability:The expansion of pediatric and geriatric medicine, where taste is a primary factor in adherence, creates sustained demand for effective taste-masking solutions for active pharmaceutical ingredients (APIs).
- Sugar Reduction Mandates:Government policies, including sugar taxes and front-of-pack labeling requirements in Europe and Latin America, compel manufacturers to reformulate products using high-intensity sweeteners, which necessitates the use of bitterness blockers.
Market Restraints
- Higher Cost of Naturals:Natural bitterness suppressors derived from specialized plant extracts often have a significantly higher cost-in-use compared to their synthetic counterparts, limiting their adoption in price-sensitive product categories.
- Regulatory Hurdles:The lengthy and costly Generally Recognized as Safe (GRAS) notification process in the United States and equivalent European Food Safety Authority (EFSA) approvals slow the commercialization of novel ingredients.
- Formulation Complexity:The efficacy of a suppressor can vary significantly based on the product's pH, temperature, and interaction with other ingredients, creating technical challenges in achieving consistent taste modulation across diverse applications.
Strategic Opportunities
- Plant-Based Protein Boom:The inherent bitter and beany off-notes in many plant-based proteins, such as pea and soy, present a major opportunity for specialized masking solutions to improve consumer acceptance.
- Emerging Markets:Rapidly growing functional beverage and nutraceutical markets in Southeast Asian countries offer significant untapped potential for suppliers able to navigate local tastes and regulatory requirements.
- AI-Powered Discovery:Leveraging artificial intelligence and machine learning to screen molecules and predict their interaction with bitter taste receptors (T2Rs) can dramatically accelerate the discovery of new, highly effective suppressors.
Industry Challenges
- Navigating Dual Regulations:Manufacturers face operational complexity in managing separate compliance pathways and documentation for ingredients sold as food additives versus those classified as pharmaceutical excipients under bodies like the NMPA.
- Raw Material Volatility:Securing a stable, high-quality supply chain for natural suppressors is a persistent challenge, as raw material availability and pricing are subject to agricultural seasonality, climate events, and geopolitical factors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bitterness Suppressors and Flavor Carriers Market |
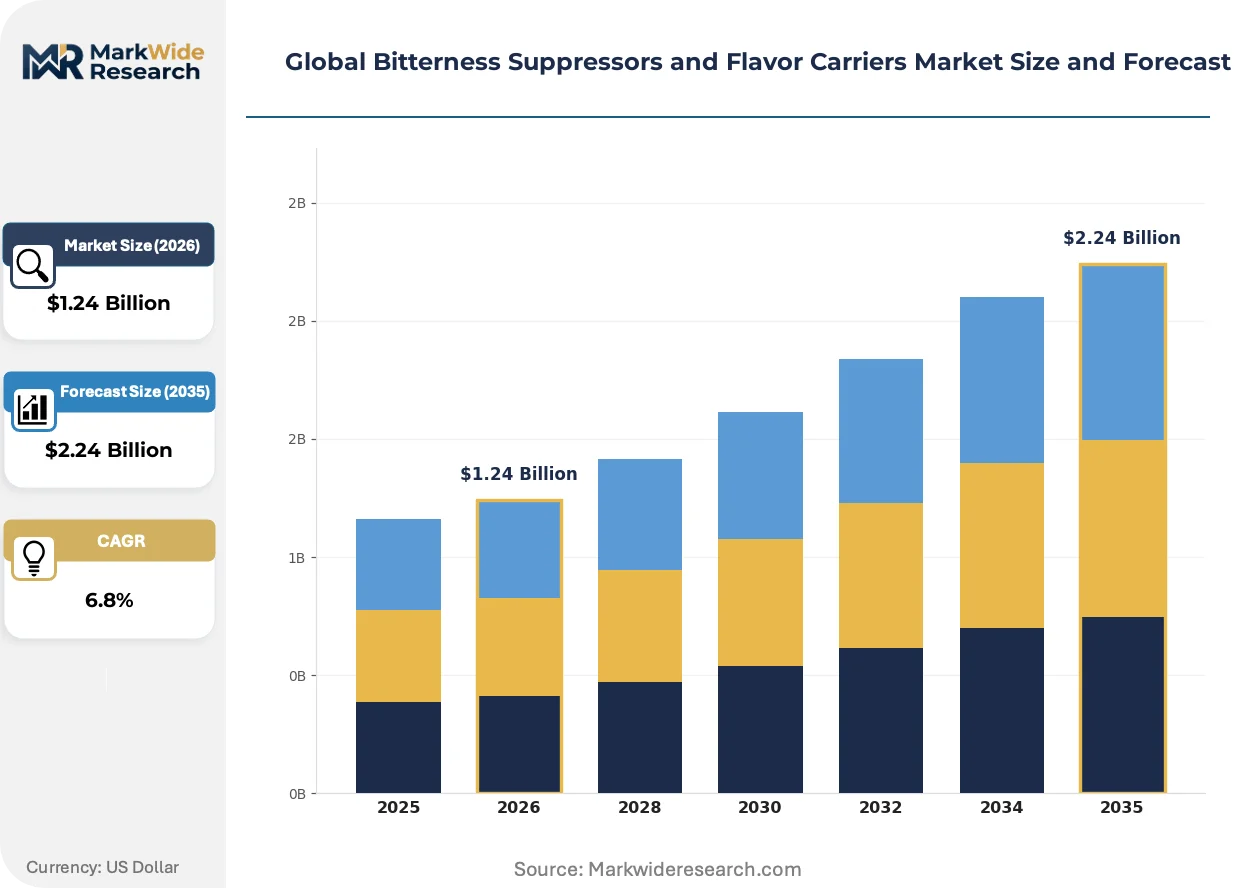
| Market Size in 2026 | $1.24 Billion |
| Market Size in 2035 | $2.24 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Suppressors, Synthetic Suppressors, Carrier Agents, Masking Agents, Flavor Enhancers Application: Beverages, Confectionery, Pharmaceuticals, Personal Care, Animal Nutrition Form: Liquid, Powder, Gel, Granules, Emulsions End User: Food Processing Units, Oral Care Manufacturers, Nutraceutical Companies, Cosmetic Producers, Veterinary Firms |
| Companies Covered | Symrise, Cargill, Givaudan, Sensient Technologies, Tate & Lyle, International Flavors and Fragrances, Kerry Group, Dohler, Firmenich, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bitterness Suppressors and Flavor Carriers Market Strategic Shifts & Innovations
Formulation science is advancing toward multifunctional ingredients that not only suppress bitterness but also improve stability and mouthfeel. This push for holistic sensory improvement is driven by consumer demand for healthier products that do not compromise on taste, forcing innovation in both ingredient chemistry and delivery systems.
Encapsulation technologies, including spray-drying and coacervation, serve as advanced flavor carriers. Nutraceutical and beverage producers are adopting these methods to protect volatile flavor compounds and active ingredients from degradation. This advanced delivery mechanism is displacing simpler solubilizing agents that offer inferior protection against oxidation and interaction with other components, thereby extending product shelf life.
The European Food Safety Authority (EFSA) is applying greater scrutiny to the safety data for novel food ingredients, including natural extracts used for taste modulation. This regulatory pressure compels suppliers to generate extensive toxicological and characterization data to secure or maintain market access within the European Union. The natural suppressors category is particularly affected, as firms must now scientifically validate the safety of complex botanical-derived substances.
Food and pharmaceutical brand owners are moving from transactional component sourcing toward integrated co-development partnerships with flavor specialists. This collaborative model replaces the standard procurement of off-the-shelf ingredients with a system where suppliers contribute expertise early in the product design phase. This shift is most visible in the competitive North American functional foods market, where rapid and effective formulation is key to capturing consumer interest.
Global Bitterness Suppressors and Flavor Carriers Market Segmentation
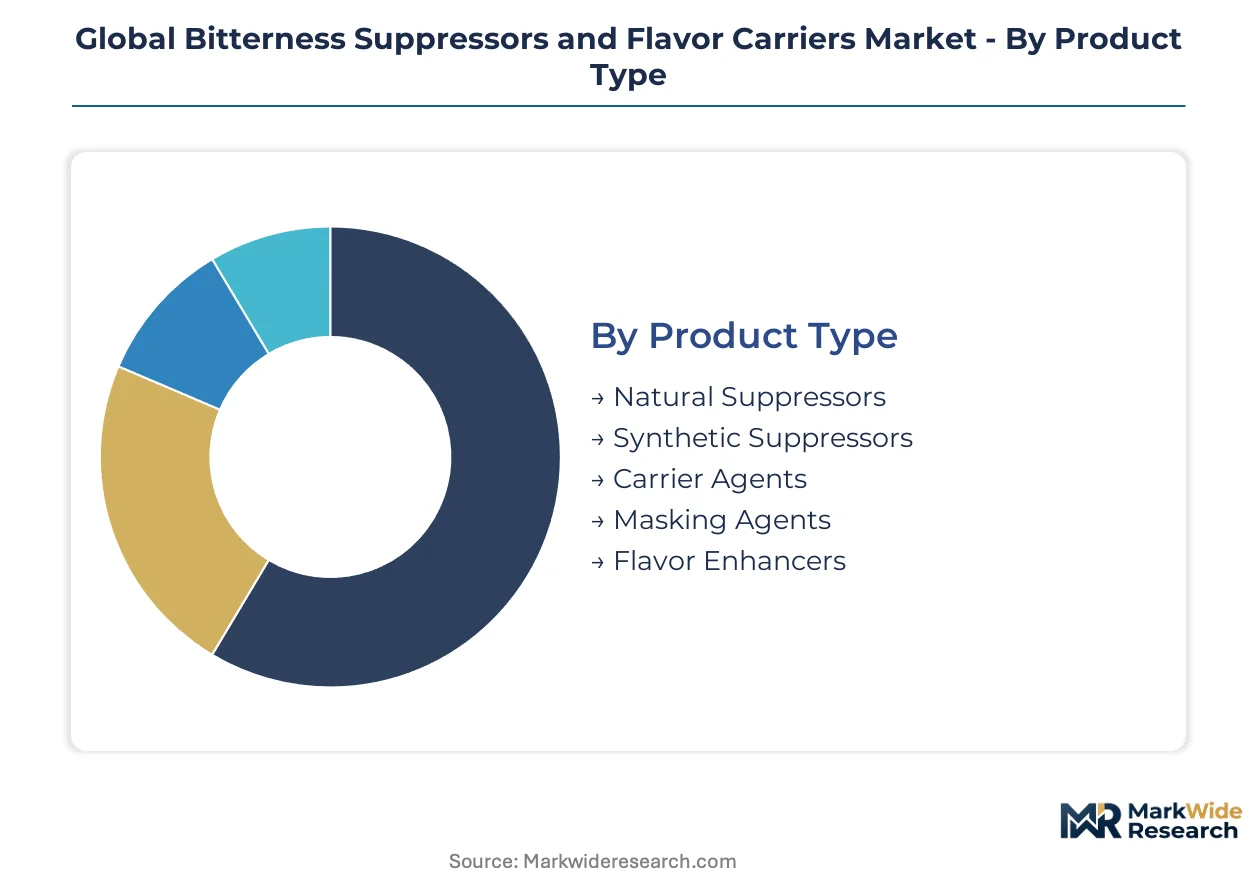
Market segmentation provides a granular view of the bitterness suppressors and flavor carriers landscape, revealing distinct demand drivers and regulatory influences across various product types, applications, forms, and end-user categories. Understanding these segments is crucial for manufacturers to tailor innovation and market strategies effectively.
Product Type:
Regulatory frameworks significantly differentiate product types, influencing market access and formulation choices across various geographies.
- Natural Suppressors:Natural Suppressors originate from plant extracts, offering clean-label appeal for consumers seeking healthier options. Demand is concentrating in the United States functional beverage market, driven by consumer preference for plant-derived ingredients.
- Synthetic Suppressors:Synthetic Suppressors are chemically synthesized compounds designed to block bitter taste receptors. Their lower cost-in-use makes them prevalent in price-sensitive food categories, particularly in emerging markets where cost efficiency is paramount.
- Carrier Agents:Carrier Agents encapsulate or solubilize flavor compounds for uniform distribution and stability within a product matrix.
- Masking Agents:Masking Agents work by overwhelming undesirable tastes with more pleasant, often stronger, flavors to improve palatability.
- Flavor Enhancers:Flavor Enhancers boost inherent flavors without adding their own distinct taste, improving the overall sensory profile.
Carrier Agents handle the majority of throughput; Natural Suppressors are the fastest mover on share.
Application:
Application segments reflect distinct end-use cases, each with specific volume requirements and formulation challenges.
- Beverages:The Beverages segment leads in volume due to the widespread use of taste modifiers in functional drinks. Low-sugar formulations in Europe drive significant demand for bitterness suppressors.
- Pharmaceuticals:Pharmaceuticals require precise taste-masking solutions for active ingredients to enhance patient compliance. Pediatric and geriatric medicine expansion in China creates sustained demand for palatable oral medications.
- Confectionery:Confectionery products utilize these ingredients to balance sweetness and manage off-notes from alternative sweeteners.
- Personal Care:Personal Care applications include oral hygiene products, where taste modulation improves user experience and product acceptance.
- Animal Nutrition:Animal Nutrition uses flavor carriers to improve palatability of feed and supplements, ensuring consistent consumption by livestock.
Beverages generate the largest demand, while Pharmaceuticals demonstrate consistent expansion.
Form:
The form of the ingredient dictates its delivery mechanism and ease of integration into various product matrices, impacting processing and stability.
- Liquid:Liquid formulations offer easy dispersion and are often preferred for their immediate solubility in aqueous systems. They see widespread use in beverage manufacturing across North America.
- Powder:Powder forms provide excellent stability and ease of transport, making them suitable for dry mixes and encapsulated applications. Their versatility drives adoption in nutraceutical and food processing units globally.
- Gel:Gel forms are used for sustained release or specific textural applications, especially in confectionery and some pharmaceutical dosage forms.
- Granules:Granules offer controlled release and improved handling properties, often used in pharmaceutical excipients and solid food applications.
- Emulsions:Emulsions facilitate the uniform distribution of oil-soluble flavors in water-based products, enhancing stability and sensory perception.
Powder formulations offer broad utility; Emulsions provide advanced delivery capabilities.
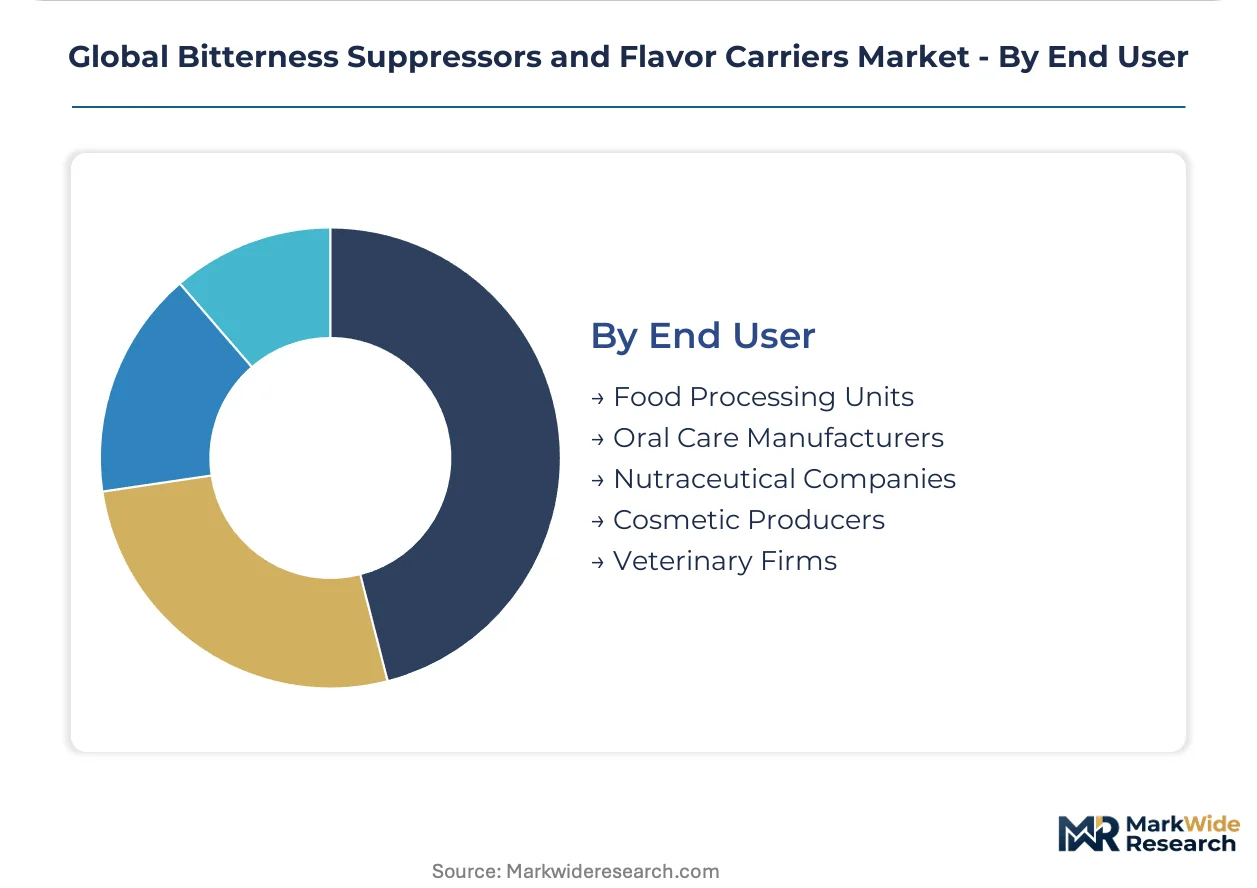
End User:
End-user segments represent distinct customer types, each with unique product development cycles and regulatory compliance needs.
- Food Processing Units:Food Processing Units represent a broad customer base, requiring solutions for diverse product lines including dairy, bakery, and snacks. Demand for sugar reduction drives their adoption of bitterness suppressors in Europe.
- Nutraceutical Companies:Nutraceutical Companies integrate taste modifiers into supplements and functional foods to improve consumer acceptance. Their focus on clean-label ingredients fuels demand for natural suppressors in the United States.
- Oral Care Manufacturers:Oral Care Manufacturers use these ingredients to mask unpleasant tastes in toothpaste and mouthwash products, improving consumer compliance.
- Cosmetic Producers:Cosmetic Producers employ flavor carriers in lip balms and other topical applications for sensory appeal and product differentiation.
- Veterinary Firms:Veterinary Firms utilize taste modifiers to improve palatability of animal medications and supplements, ensuring pets and livestock consume necessary treatments.
Food Processing Units represent the largest customer base; Nutraceutical Companies are driving innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration significantly influences regional market dynamics for bitterness suppressors and flavor carriers. The United States leads demand, driven by its advanced nutraceutical and functional beverage markets. Europe's stringent sugar reduction mandates also compel manufacturers to adopt these ingredients.
United States
Consumer preference for clean-label and plant-derived ingredients drives strong demand for natural suppressors in the United States. The US Food and Drug Administration (FDA) regulations, particularly the GRAS process, dictate market access for novel ingredients. Major food and beverage innovation hubs in California and New York concentrate product development efforts.
China
The expansion of pediatric and geriatric medicine in China creates sustained demand for palatable oral medications. National Medical Products Administration (NMPA) standards for pharmaceutical excipients significantly influence ingredient choices. Major pharmaceutical manufacturing centers in the Yangtze River Delta actively integrate taste-masking solutions.
Germany
Low-sugar formulations in Europe, driven by evolving consumer health trends, necessitate increased use of bitterness suppressors. The European Food Safety Authority (EFSA) applies greater scrutiny to novel food ingredients, requiring extensive safety data. Food ingredient innovation clusters in Bavaria and North Rhine-Westphalia develop advanced taste modulation technologies.
India
Emerging markets like India present a significant opportunity, particularly in price-sensitive food categories where cost-efficient synthetic suppressors find broad application. The Food Safety and Standards Authority of India (FSSAI) governs food additive approvals and labeling. Pharmaceutical manufacturing hubs in Gujarat and Maharashtra require effective taste-masking for generic drugs.
Brazil
Government policies, including sugar taxes, compel Brazilian manufacturers to reformulate products using high-intensity sweeteners. ANVISA, Brazil's health surveillance agency, regulates food additives and pharmaceutical excipients. The functional beverage market in São Paulo drives innovation in taste modulation for healthier drink options.
Global Bitterness Suppressors and Flavor Carriers Market Key Industry Players
Player mix skews toward established global flavor houses and specialized ingredient suppliers. The market exhibits a tiered structure, with a few large entities dominating the advanced taste modulation segment. Strategic archetypes include diversified portfolio providers and niche solution specialists. Dominant competitive moves involve extensive R&D in taste modulation technologies and strategic co-development partnerships with brand owners.
Global flavor and fragrance leaders such as Givaudan and International Flavors and Fragrances exemplify the diversified portfolio archetype, leveraging broad R&D capabilities. Kerry Group sustains its market position through a comprehensive ingredient portfolio covering both suppressors and complex flavor systems. Symrise occupies a specialist position, focusing on complex taste-masking challenges for the pharmaceutical and nutraceutical sectors.
| Leading Market Players |
|---|
| Symrise |
| Cargill |
| Givaudan |
| Sensient Technologies |
| Tate & Lyle |
| International Flavors and Fragrances |
| Kerry Group |
| Dohler |
| Firmenich |
| Others |
Cost & Logistics Intelligence
Scale economies in ingredient manufacturing drive supply concentration and influence price floors for bitterness suppressors. Efficient production processes for synthetic compounds allow for competitive pricing in high-volume applications.
Pricing Analysis
Cost-plus contracts often include indexation to raw material costs for long-term supply agreements. Price differentiation stems from certification level, such as FSSC 22000 compliance, and the volume scale of the order. Pricing pressure stems from the adoption of cost-efficient synthetic options in price-sensitive food categories. Pharmaceutical and nutraceutical buyers prioritize efficacy and regulatory compliance over lowest cost.
Supply Chain Analysis
Inventory management for natural extracts faces challenges due to agricultural seasonality and climate events. Supply concentrates in China for synthetic compounds and some botanical extracts, while Europe leads in advanced natural extract processing. Raw material dependencies include specialized plant extracts and synthetic chemical precursors. Regulatory restrictions, particularly import/export controls, present a structural risk. Distribution runs through direct sales channels to large manufacturers and specialized ingredient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market's growth hinges on specialized taste modulation capabilities, creating a scarcity story. Navigating complex multi-jurisdictional regulatory frameworks represents a critical asset gap for many participants.
For Market Incumbents:
Consolidate expertise in taste modulation technologies through targeted acquisitions of R&D-focused firms. Defend market share against novel AI-driven ingredient discovery by investing in internal machine learning platforms. Expand global regulatory teams to proactively address stricter clean-label mandates from EFSA and FDA. Enhance certification investment, particularly FSSC 22000, to maintain competitive differentiation.
For New Entrants and Emerging Players:
Lead with innovative solutions for plant-based protein masking to address inherent off-notes. Target specialized pediatric pharmaceutical solutions, where palatability is paramount for patient adherence. The functional beverage market in Southeast Asia offers a penetrable segment for novel natural suppressors. Co-development partnerships with agile food tech startups provide a compelling go-to-market angle.
For Investors and Strategic Acquirers:
Recurring-revenue conversion is highest among specialized ingredient suppliers with strong intellectual property in taste modulation. Long-term viability remains strong, driven by sustained consumer demand for healthier products and pharmaceutical compliance needs. Niche players possessing proprietary natural extracts or AI-driven discovery platforms represent attractive acquisition targets. Acceleration in EFSA and FDA approvals for novel natural suppressors serves as a critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Enhance AI-Powered Discovery | Givaudan can accelerate new suppressor identification by leveraging machine learning. |
| Expand Clean-Label Portfolio | Kerry Group can meet consumer demand for natural ingredients in functional food formulations. |
| Strengthen Regulatory Compliance | Symrise ensures market access for pharmaceutical excipients under NMPA standards. |
| Form Co-development Partnerships | Ingredient manufacturers can integrate expertise earlier in brand owner product design phases. |
| Target Emerging Markets | Suppliers can capture untapped potential in Southeast Asian functional beverage markets. |
Research Approach
The analysis maps bitterness suppressors and flavor carriers across product types and applications, each validated through primary interviews. Conversations with R&D directors at flavor houses, procurement leads at food manufacturers, and regulatory affairs specialists informed market dynamics. Secondary validation drew from FDA GRAS notices, EFSA scientific opinions, and NMPA excipient guidelines. Bottom-up market sizing was triangulated with top-down industry reports.
Forecast outputs underwent consistency checks against external benchmarks across the analysis window. The analytical framework modeled market segmentation by product type, application, form, end-user category, and regional regulatory environment. Compound Annual Growth Rates were derived from historical trends and projected market dynamics. Sugar reduction policy impacts and new active pharmaceutical ingredient approvals served as key forecast inputs.
The analysis sits within stated boundaries; outcomes outside unforeseen regulatory shifts or major raw material supply disruptions would require recalibration. Forecasts reflect assumptions documented through stakeholder consultations and secondary research. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
North America Vanilla and Vanillin Market
Flavorings and Food Additives
Chicory Products Market
Flavorings and Food Additives
Natural Extracts Market
Flavorings and Food Additives
Salts and Flavored Salts Market
Flavorings and Food Additives
Russia Food Colorants Market
Flavorings and Food Additives
Botanical Flavors Market
Flavorings and Food Additives
Tangerine Extract Market
Flavorings and Food Additives
Clean Label Flavors Market
Flavorings and Food Additives
Global Vanilla (B2B) Market
Flavorings and Food Additives
Lemon Oil Market
Flavorings and Food Additives
Flavor and Flavor Enhancers Market
Flavorings and Food Additives
Cocoa Extract Market
Flavorings and Food Additives
Ylang Ylang Extract Market
Flavorings and Food Additives
Synthetic Food Colors Market
Flavorings and Food Additives
Flavoring Agents Market
Flavorings and Food Additives
Jujube Extracts Market