
 Food Botanicals Market | 2026-2036
Food Botanicals Market Size, Share, and Industry Trends Forecast 2026-2036
Food Botanicals Market Analysis
Market Context
The gap between certified organic botanical extracts and conventional commodity herb supplies is broadening as buyers enforce stricter provenance documentation. International Flavors & Fragrances leverages captive farming partnerships across three continents to secure traceable raw material flows. Givaudan anchors its position through integrated extraction facilities that convert whole herbs into standardized oleoresins. Martin Bauer Group specializes in sustainable wild-collection networks for European medicinal herbs.
Technical Definition and Segment Structure
Food botanicals comprise dried, fresh, or extracted plant materials including herbs, spices, flowers, and roots, standardized to active compound concentrations for flavor, color, or bioactive functionality in finished goods. Steam distillation, solvent extraction, and cold-pressing yield essential oils, oleoresins, and powdered extracts with defined volatile oil or polyphenol content. The extracts segment captures expanding margin pools as beverage manufacturers seek concentrated, shelf-stable formats with batch-to-batch consistency. Nutraceutical applications outpace conventional food and beverage use as consumers prioritize immunity and digestive health positioning. Dried herbs retain volume leadership in food service and retail seasoning channels where visual identity and aroma intensity drive selection.
Regulatory Framework and Outlook
EFSA novel food assessments, FDA GRAS self-affirmation pathways, and EU REACH compliance for extraction solvents collectively determine market access timelines and formulation costs for botanical suppliers. Organic certification under USDA NOP and EU Regulation 2018/848 adds premium eligibility but requires multi-year field conversion and residue testing protocols. Stakeholders must monitor evolving maximum residue limits for pesticides in botanical raw materials as importing jurisdictions tighten enforcement against adulterated shipments.
Market Dynamics
Clean-label mandates from EFSA and FDA are compressing formulation timelines while forcing suppliers to rebuild extraction protocols around solvent-free and supercritical CO2 methods that satisfy residue thresholds.
Growth Catalysts
- EFSA Novel Food Pathway:Streamlined safety assessments for traditional botanicals from third countries accelerate European market entry for South American and African herb suppliers.
- Functional Beverage Formulation:Beverage manufacturers in Germany and the United States are expanding SKU counts featuring adaptogenic and nootropic botanical positioning.
- Supercritical CO2 Extraction:This solvent-free technology enables premium oleoresin production that meets organic certification requirements under USDA NOP and EU 2018/848.
Market Restraints
- Wild Collection Supply Concentration:European medicinal herb supply depends on fragmented Balkan and Carpathian wild-collection networks vulnerable to climate volatility and overharvesting.
- Multi-Jurisdiction Compliance Costs:REACH solvent registration, FDA GRAS self-affirmation, and organic certification create cumulative fixed-cost barriers for mid-scale extractors.
- Synthetic Flavor Substitution:High-purity natural identical compounds from fermentation biotechnology threaten commodity-grade botanical extracts in cost-sensitive beverage applications.
Strategic Opportunities
- Indian Ayurvedic Export Expansion:India's FSSAI-export corridor and Geographical Indication protections for turmeric, ashwagandha, and holy basil create defensible origin positioning.
- Cellular Agriculture Convergence:Precision fermentation of rare botanical actives combines with traditional extraction to secure supply of climate-threatened species.
- Direct-to-Brand Procurement Platforms:Blockchain-traceable ingredient marketplaces disintermediate traditional spice traders and shorten provenance documentation chains.
Industry Challenges
- Phytochemistry Analytical Talent Scarcity:Standardization of complex botanical matrices requires rare expertise in HPLC-MS metabolite profiling that outpaces university training pipelines.
- Multi-Year Organic Conversion Timelines:Field transition to EU 2018/848 or USDA NOP certification locks working capital for 24-36 months before premium pricing eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Botanicals Market |
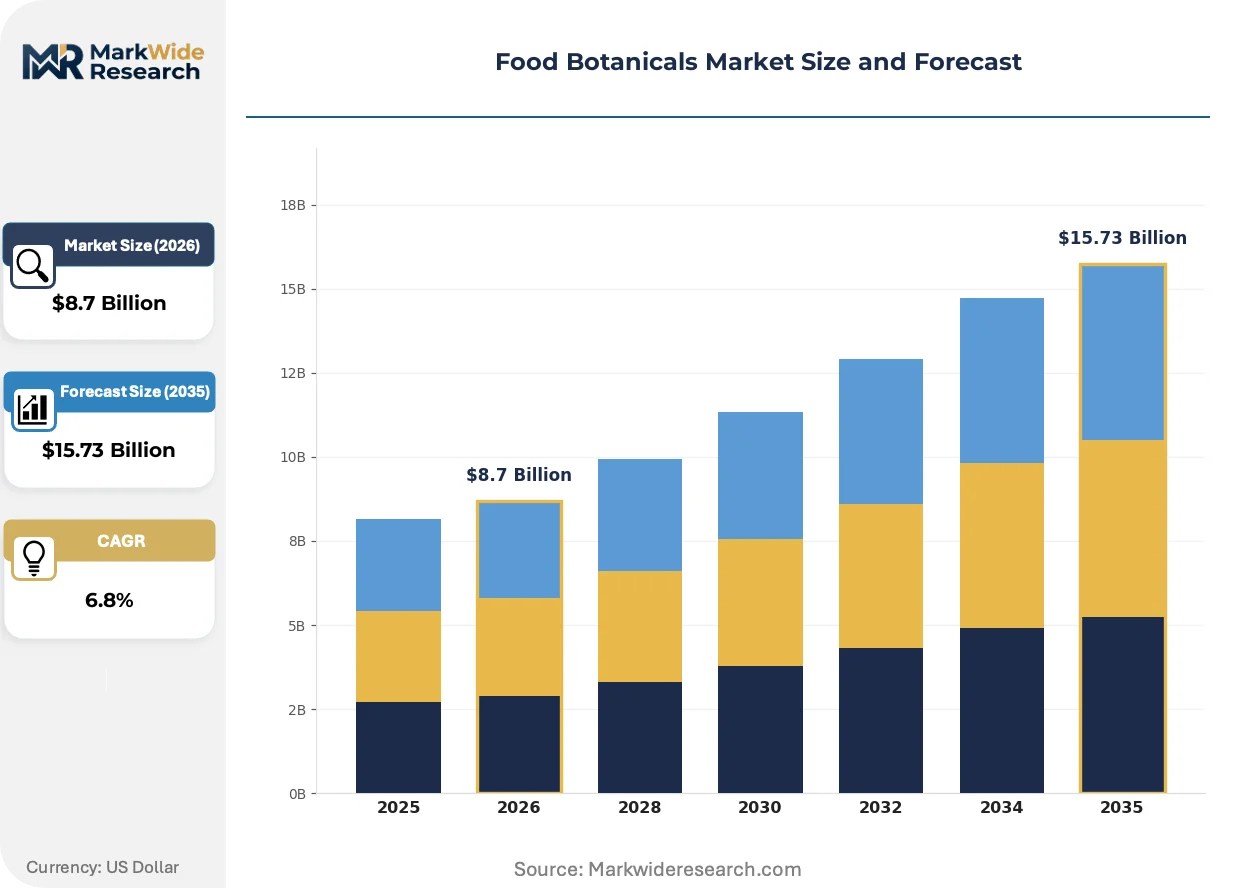
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbs, Spices, Flowers, Roots Form: Dried, Fresh, Extracts, Powders Application: Food & Beverage, Nutraceuticals, Cosmetics, Pharmaceuticals End User: Food Manufacturers, Health Stores, Restaurants, Home Consumers |
| Companies Covered | International Flavors & Fragrances, Givaudan, Martin Bauer Group, Indena, Symrise AG, Indesso, Sensient Technologies Corporation, Kerry Group, ADM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Botanicals Market Emerging Trajectories
Extraction technology and regulatory data requirements are converging to reshape how botanical suppliers prove composition consistency and bioactive equivalence across harvest seasons.
Supercritical CO2 extraction systems with integrated in-line analytics are rewriting quality assurance economics for high-value oleoresin production. Premium beverage manufacturers in Germany and Switzerland are adopting these systems to eliminate solvent residue testing costs. The technology is compressing batch release timelines from weeks to days while enabling real-time standardization.
EU REACH enforcement against undocumented extraction solvents is tightening residue documentation requirements for imports into Rotterdam and Hamburg processing hubs. Suppliers must now submit full analytical datasets with every shipment or face port detention. Small-scale African and South American collectors are consolidating around export cooperatives that can afford compliance infrastructure.
Brand procurement teams are consolidating supplier rosters from dozens to handfuls of vertically integrated partners capable of single-origin documentation. This consolidation is displacing spot-market trading at traditional spice houses in Rotterdam and New York. German and Dutch botanical buyers now prioritize multi-year contracts with farm-level traceability over price optimization.
Food Botanicals Market Segmentation
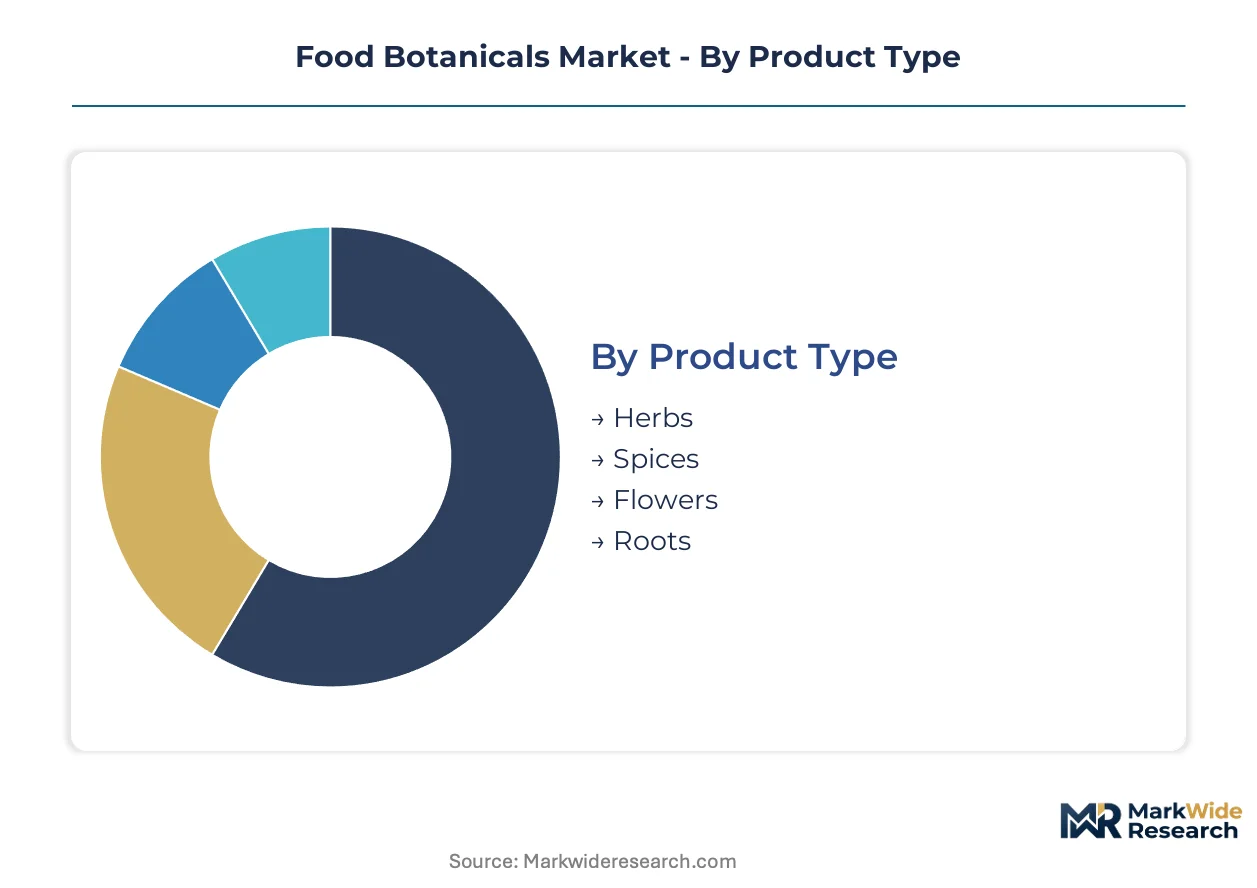
Food botanicals suppliers must align product formats with distinct margin profiles and regulatory pathways. Each segmentation dimension reveals divergent growth trajectories between commodity volume plays and premium certified positioning.
Product Type:
Volume concentrates in culinary staples while premium extraction feedstocks command specialized cultivation contracts.
- Herbs:Leafy aromatic plants such as basil, oregano, and mint standardized to essential oil content. German beverage formulators in Hamburg source contract-grown holy basil for adaptogenic SKUs under EFSA novel food guidance.
- Spices:Seed, bark, and rhizome products including pepper, cinnamon, and cardamom traded on volatile commodity markets. Indian Geographical Indication protections for turmeric create origin-defensible supply for nutraceutical extractors.
- Flowers:Dried or extracted floral materials including chamomile, lavender, and hibiscus. Cosmetic manufacturers in France leverage ANSM cosmetic ingredient listings for skincare applications.
- Roots:Underground plant structures such as ginger, ginseng, and licorice requiring multi-year cultivation cycles. Korean red ginseng commands captive farming arrangements due to MFDS health functional food registration requirements.
Today's leader: Spices. Tomorrow's challenger: Roots.
Form:
Margin pools shift toward concentrated formats that reduce logistics burden and extend shelf stability.
- Dried:Dehydrated whole or cut botanicals retaining visual identity for food service and retail seasoning channels. European wild-collection networks in the Balkans supply dried medicinal herbs to Martin Bauer Group processing facilities.
- Fresh:Unprocessed plant materials with limited shelf life demanding cold-chain logistics. Restaurant chains in urban Germany prioritize fresh herb delivery through specialized produce distributors.
- Extracts:Concentrated oleoresins and tinctures standardized to active compound levels. Supercritical CO2 extraction systems in Switzerland enable solvent-free premium production for organic-certified beverage lines.
- Powders:Micronized botanical materials for instant dissolution in functional beverages. Nutraceutical manufacturers in the United States specify particle size distribution for capsule-filling equipment compatibility.
Extracts capture the steepest expansion trajectory as beverage manufacturers seek batch-to-batch consistency.
Application:
Regulatory complexity stratifies across end-use categories with divergent safety assessment burdens.
- Food & Beverage:Flavoring and coloring applications governed by FDA GRAS self-affirmation or EFSA flavoring substance evaluations. Clean-label mandates compress formulation timelines toward recognizable botanical ingredients.
- Nutraceuticals:Dietary supplement and functional food positioning requiring substantiated health claims. Immunity and digestive health positioning drives ashwagandha and turmeric extract demand in German and US markets.
- Cosmetics:Botanical actives for skincare and fragrance applications under REACH cosmetic ingredient requirements. Lavender and chamomile extracts feature in natural positioning for premium European personal care brands.
- Pharmaceuticals:Botanical drug substances requiring full marketing authorization through FDA botanical drug pathway or EMA herbal medicinal product procedures. Standardized St. John's wort and ginkgo extracts dominate evidence-based phytomedicine.
Food & Beverage anchors current volume. Nutraceuticals are climbing the fastest on functional positioning.
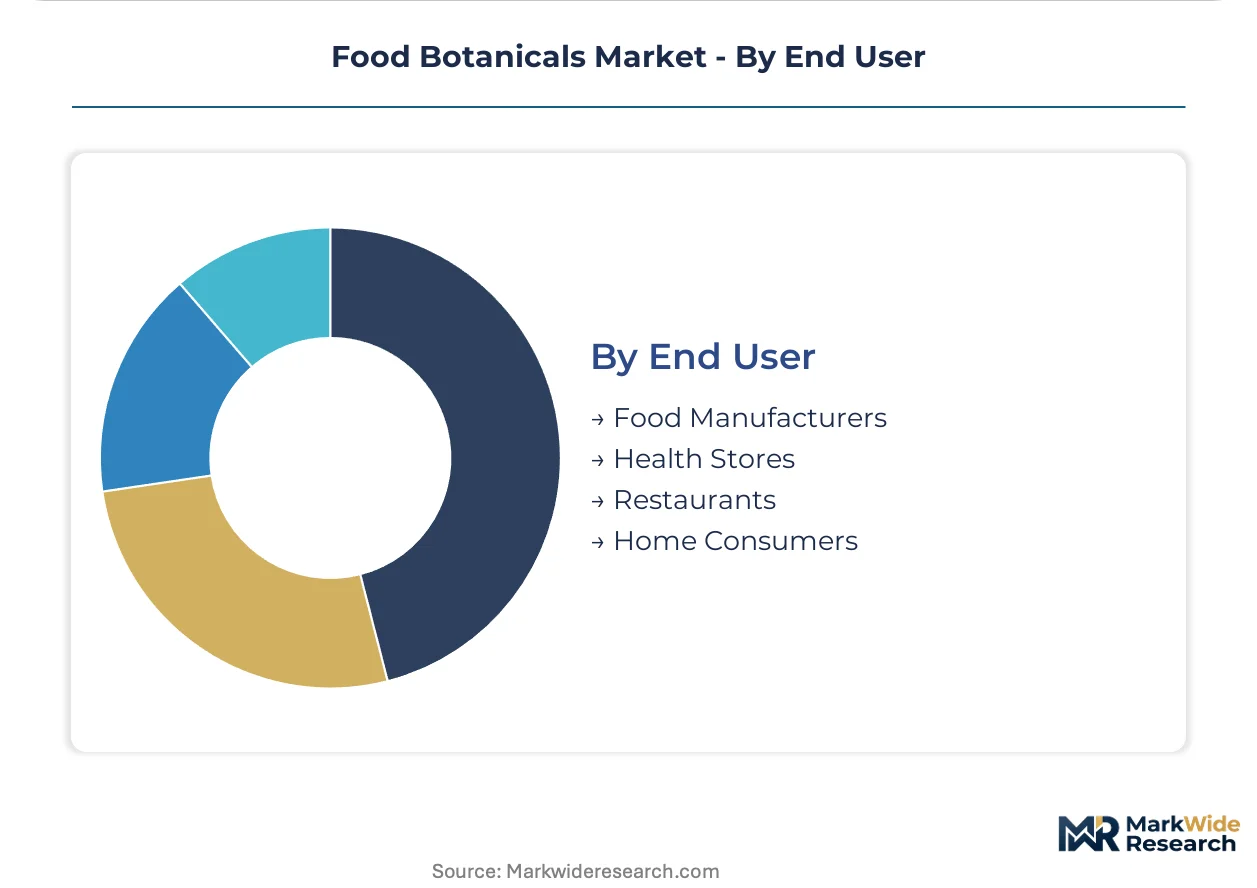
End User:
Procurement sophistication varies dramatically across buyer types from spot-market commodity purchasing to multi-year traceability contracts.
- Food Manufacturers:Industrial-scale processors of sauces, seasonings, and beverages. German herbal processing clusters around Hamburg consolidate supplier rosters toward vertically integrated partners with single-origin documentation.
- Health Stores:Specialty retail channels emphasizing organic certification and traditional herbal knowledge. EU 2018/848 organic labeling requirements shape product assortment decisions.
- Restaurants:Food service operators prioritizing aroma intensity and visual presentation. Fresh herb demand concentrates in metropolitan culinary hubs.
- Home Consumers:Individual purchasers through retail and e-commerce channels. Direct-to-brand procurement platforms with blockchain traceability disintermediate traditional spice trading for this segment.
Food Manufacturers dominate procurement scale. Health Stores are gaining share fastest on premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany processes more botanical extracts than France and Italy combined, yet India's export corridor now supplies the raw material backbone for European formulation. This geographic interdependence shapes procurement strategies across three continents.
United States
Functional beverage manufacturers in California and New York drive demand for adaptogenic botanicals with clean-label positioning. FDA GRAS self-affirmation pathways allow faster market entry for novel extracts compared to EFSA procedures. Chicago and New Jersey host concentrated extraction facilities serving national nutraceutical distribution networks.
Germany
Hamburg anchors Europe's largest herbal processing cluster, where Martin Bauer Group and Symrise AG operate integrated extraction facilities. EFSA novel food assessments create regulatory bottlenecks for non-traditional botanicals entering the EU market. Bavaria's contract farming networks supply holy basil and ashwagandha for German beverage formulators seeking EFSA-compliant adaptogenic SKUs.
India
FSSAI-export corridor regulations and Geographical Indication protections for turmeric, ashwagandha, and holy basil create defensible origin positioning for Ayurvedic suppliers. India's botanical extract exports concentrate around Mumbai and Ahmedabad processing hubs. Karnataka and Madhya Pradesh farming cooperatives now consolidate around export-compliant infrastructure to meet EU residue documentation requirements.
Switzerland
Swissmedic regulations for botanical drug substances attract premium pharmaceutical extraction investment around Basel and Zurich. Supercritical CO2 extraction systems enable solvent-free oleoresin production that satisfies organic certification under USDA NOP and EU 2018/848. Geneva-based procurement teams source single-origin botanicals through multi-year traceability contracts rather than spot markets.
Brazil
ANVISA's evolving botanical ingredient framework creates compliance complexity for Amazonian wild-collection networks supplying açaí and camu camu extracts. São Paulo formulators serve Latin American functional beverage markets with regional adaptogenic positioning. Pará and Amazonas states consolidate wild-collection cooperatives around export infrastructure to meet Rotterdam and Hamburg documentation standards.
Food Botanicals Market Vendor Landscape
Top-tier vendors anchor integrated extraction and captive farming operations, while mid-scale specialists compete on single-origin documentation and organic certification. The vendor base stratifies between flavor houses with beverage formulation partnerships and standalone extractors serving nutraceutical channels. Three archetypes dominate: integrated flavor houses with captive supply chains, specialist extractors with wild-collection networks, and agricultural processors with geographic indication leverage. Competitive moves concentrate on backward integration into farming partnerships and multi-year procurement contracts that displace spot-market trading.
Within the integrated flavor house tier, International Flavors & Fragrances and Givaudan exemplify archetypes built on captive farming partnerships across multiple continents. Martin Bauer Group occupies a distinct position as a European specialist with sustainable wild-collection networks for medicinal herbs. These three companies represent the dominant competitive configurations: global scale with agricultural control, and regional expertise with biodiversity access.
| Leading Market Players |
|---|
| International Flavors & Fragrances |
| Givaudan |
| Martin Bauer Group |
| Indena |
| Symrise AG |
| Indesso |
| Sensient Technologies Corporation |
| Kerry Group |
| ADM |
| Others |
Supply Flow & Price Mechanics
Captive farming partnerships across three continents anchor supply positions and pricing power for integrated flavor houses, compressing margin pools for spot-market dependent traders. International Flavors & Fragrances and Givaudan leverage these agricultural controls to enforce multi-year offtake terms that stabilize input costs against commodity volatility.
Pricing Analysis
Capacity additions in India and Brazil are reshaping price floors for commodity-grade botanical extracts. Three-tier pricing structure across organic-certified, conventional-standard, and wild-collection economy levels stratifies the market. Cost compression in the economy tier stems from synthetic flavor substitution via fermentation biotechnology. Food manufacturers exhibit highest price sensitivity, while pharmaceutical extractors absorb premiums for documented provenance.
Supply Chain Analysis
Direct-to-brand procurement channels handle traceability-demanding buyer segments, displacing traditional spice house intermediaries. Raw material flows concentrate in India, Germany, and Brazil, drawing from wild-collection networks in the Balkans and captive farms in Karnataka. Supply chain risk centers on EU REACH documentation requirements that detain shipments at Rotterdam and Hamburg without full analytical datasets. Distribution runs through vertically integrated partners with single-origin blockchain traceability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The food botanicals market functions as a stable compounder, with clean-label regulatory mandates driving steady reformulation demand across beverage and nutraceutical channels.
For Market Incumbents: Hedge wild-collection exposure by deepening captive farming arrangements in India and Brazil against climate volatility in Balkan supply zones. Accelerate supercritical CO2 extraction capacity to capture organic certification premiums and eliminate solvent residue testing costs. Consolidate supplier rosters toward farm-level traceability contracts that displace spot-market trading. For New Entrants and Emerging Players: The mid-tier price gap between premium organic extracts and economy conventional grades offers white-space positioning for FSSAI-certified Indian suppliers with Geographical Indication leverage. Target German beverage formulators seeking EFSA-compliant adaptogenic inputs with shorter documentation chains than established traders. Pursue direct-to-brand procurement platform partnerships to bypass Rotterdam spice house intermediaries. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale European extractors with wild-collection licenses because regulatory compliance costs are consolidating the vendor base faster than organic growth. Five-to-ten year viability hinges on backward integration into farming partnerships rather than trading margins. Monitor EU 2018/848 organic conversion timelines as inflection signals for premium supply availability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Farming | International Flavors & Fragrances secures traceable turmeric and holy basil flows across Indian contract farms. |
| Supercritical CO2 Extraction Scale-Up | Givaudan eliminates solvent residue testing costs for Swiss organic-certified beverage lines. |
| Blockchain Traceability Platform Launch | Direct-to-brand procurement shortens provenance documentation chains for German health store channels. |
| Geographical Indication Certification | Indian cooperatives leverage FSSAI-export corridor protections for defensible ashwagandha positioning. |
| Multi-Year Procurement Contracting | Martin Bauer Group locks Balkan wild-collection supply against spot-market volatility. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with extraction facility managers, beverage formulation chemists, organic certification auditors, and spice trading executives. Secondary validation draws from FDA GRAS filings, EFSA novel food assessments, EU REACH registration databases, and FSSAI export corridor documentation. Bottom-up volume triangulation against top-down value estimates ensures segment consistency.
Rate-of-change decomposition separates volume growth from price mix effects across the projection horizon. Segmentation dimensions modeled include product type, form, application, and end-user procurement sophistication. CAGRs derive from weighted regional growth rates applied to segment baselines. Industry-specific forecast inputs incorporate organic conversion timelines and supercritical CO2 extraction adoption curves.
Caveats apply where EU REACH enforcement intensity or FDA GRAS pathway modifications could materially shift the outlook for import-dependent suppliers. Forecasts reflect documented assumptions about regulatory stability and climate patterns in wild-collection zones. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Ahiflower Oil Market
Ingredients
L-Arabinose Market
Ingredients
Modified Soya Flour Market
Ingredients
Konjac Flour Market
Ingredients
Bouillon Cubes Market
Ingredients
India Soy Protein Market
Ingredients
Global Natural Gum Market
Ingredients
Organic Edible Oil Market
Ingredients
Dried Beet Pulp Market
Ingredients
South America Fermented Ingredients Market
Ingredients
US Vegetable Oil Market
Ingredients
Siraitia Grosvenorii Extract Market
Ingredients
Almond Flour Market
Ingredients
Hydrolyzed Egg Market
Ingredients
North America Brewing Enzymes Market
Ingredients
Asia-Pacific Food Coating Ingredients Market