
 Menthol Market | 2026-2036
Menthol Market Size, Share, and Industry Trends Forecast 2026-2036
Menthol Market Outlook
Pharmaceutical-grade purity specifications are reorganizing procurement priorities across the menthol value chain. BASF SE leverages its synthetic menthol platform to serve European pharmaceutical formulators with consistent USP-grade output. Arora Aromatics Pvt. Ltd. anchors South Asian supply through integrated distillation and crystallization operations in northern India. Symrise AG differentiates via biotechnology-derived menthol routes that reduce agricultural dependency.
Menthol is a cyclic terpene alcohol (C₁₀H₂₀O) typically isolated from Mentha arvensis oil via freezing and centrifugation, yielding crystals with melting points near 42°C; it functions primarily as a cooling agent, topical counterirritant, and flavor enhancer across consumer and medical products. The pharmaceuticals application commands premium pricing due to compendial-grade certification requirements, while personal care represents the volume anchor through toothpaste and cosmetic formulations. Flavors segment growth in confectionery and beverages is accelerating as clean-label natural positioning displaces synthetic alternatives.
The US FDA enforces identity and purity standards under 21 CFR for menthol used in drug products, while India's CDSCO mandates API-grade documentation for pharmaceutical applications, and REACH in Europe requires full toxicological dossiers for high-volume chemical registration. These frameworks elevate compliance costs for smaller distillers while creating protected market access for certified producers. Stakeholders must monitor evolving restrictions on tobacco-related applications as regulatory bodies reassess menthol's role in flavored nicotine products.
Market Dynamics
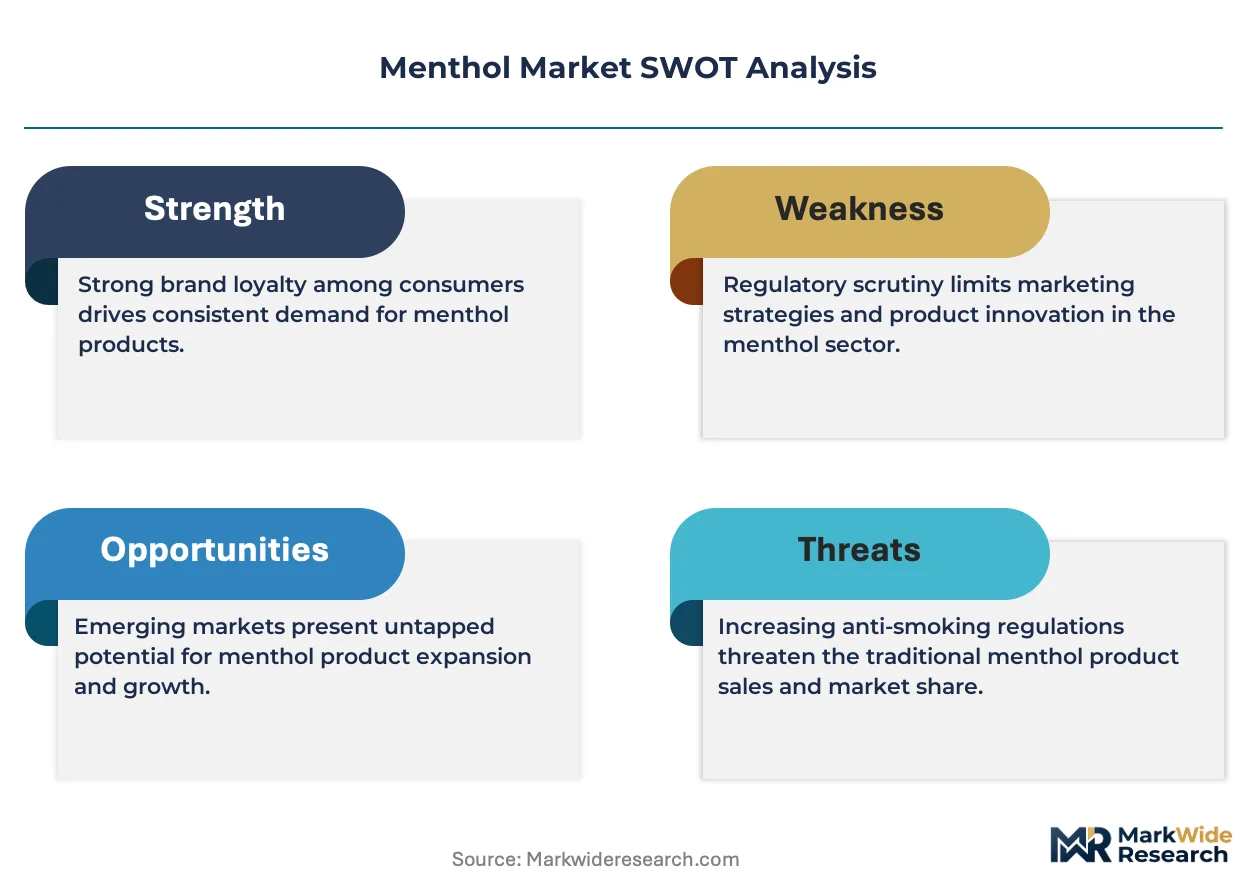
Pharmaceutical-grade certification requirements are concentrating procurement power among integrated producers capable of sustaining USP-grade documentation and multi-jurisdiction compliance dossiers.
Growth Catalysts
- Clean-label confectionery reformulation:Natural menthol derived from Mentha arvensis oil is displacing synthetic alternatives in premium candy and beverage applications across North American and European retail channels.
- REACH registration completion:Full toxicological dossier acceptance under European chemical law has opened sustained bulk chemical access for certified Indian and European producers serving pharmaceutical formulators.
- Topical analgesic pipeline expansion:Transdermal patch and gel formulations incorporating menthol as a counterirritant are multiplying across pain management portfolios in Japan, Germany, and the United States.
Market Restraints
- Mentha arvensis crop volatility:Monsoon dependency and pest pressure in Uttar Pradesh and Bihar create recurring raw material shortages that compress margins for non-integrated crystal processors.
- CDSCO API-grade documentation burden:India's pharmaceutical regulator mandates extensive stability and impurity profiling that smaller distillers cannot sustain without dedicated quality infrastructure.
- Synthetic biology substitution threat:Engineered yeast and bacterial fermentation routes for terpenoid production are advancing toward commercial viability in European and North American biotechnology hubs.
Strategic Opportunities
- Brazilian pharmaceutical market penetration:ANVISA's expanding GMP certification reciprocity with Indian regulators creates pathway for Uttar Pradesh-based producers to supply South American generic drug manufacturers.
- Biotechnology-derived menthol scale-up:Convergence of metabolic engineering and continuous fermentation technology enables production decoupled from agricultural growing seasons.
- Direct-to-formulator digital platforms:B2B marketplace channels are compressing traditional multi-layer distribution in European personal care ingredient sourcing.
Industry Challenges
- USP-NF monograph compliance timeline:Batch release testing for identity, melting range, and optical rotation extends lead times for pharmaceutical-grade crystal shipments.
- Specialized extraction technician scarcity:Freezing-centrifugation operations and fractional distillation expertise concentrate in aging workforce pools around Lucknow and Moradabad.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Menthol Market |
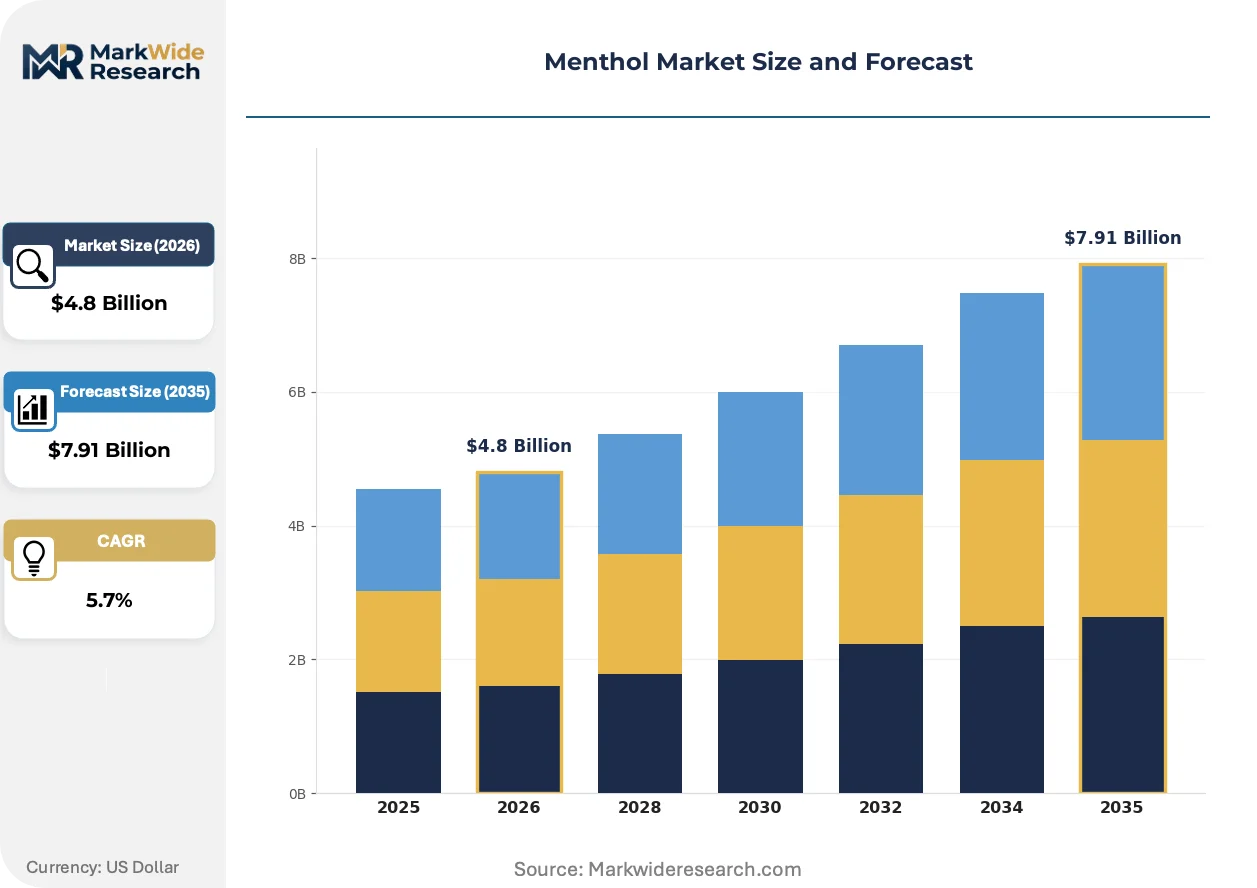
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cigarettes, Cigars, Smokeless Tobacco, Vape Products Application: Personal Care, Pharmaceuticals, Food & Beverages, Flavors End User: Retail Consumers, Wholesale Distributors, Manufacturers, Food Service Distribution Channel: Online Retail, Convenience Stores, Specialty Shops, Supermarkets |
| Companies Covered | Agson Global, Arora Aromatics Pvt. Ltd., Symrise AG, Tienyuan Chem, Fengle Perfume, BASF SE, Nantong Menthol Factory, Silverline Chemicals, Takasago International Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Menthol Market Strategic Shifts
Biotechnology platforms and regulatory documentation automation are compressing traditional agricultural dependency while elevating purity verification standards across the value chain.
Continuous fermentation systems using engineered Saccharomyces cerevisiae strains are miniaturizing production footprints for terpenoid biosynthesis. European flavor houses and pharmaceutical ingredient suppliers are piloting these platforms to reduce acreage requirements and harvest risk. The technology is compressing capital intensity for new market entrants while enabling geographic relocation of production away from traditional growing belts.
EMA's updated excipient guidelines and FDA's enhanced drug master file requirements for flavor and fragrance materials are elevating documentation burdens for menthol suppliers. Pharmaceutical formulators now demand complete supply chain transparency and contaminant risk assessments. European and North American drug manufacturers are consolidating supplier lists to those with pre-submitted regulatory packages.
Ingredient buyers in cosmetics and oral care are consolidating purchase volumes with fewer certified producers rather than maintaining fragmented supplier rosters. Long-term supply agreements with fixed purity specifications are displacing spot market transactions for USP-grade material. This concentration is most visible in German and French personal care manufacturing clusters where procurement functions have merged quality and sourcing responsibilities.
Menthol Market Segmentation
Menthol's functional versatility creates distinct demand profiles across product categories. Channel strategies diverge sharply between regulated pharmaceutical applications and consumer-facing tobacco and flavor segments.
Product Type:
Channel-mix patterns split between regulated tobacco channels and emerging vape distribution networks.
- Cigarettes:Menthol concentration in combustible tobacco products faces tightening regulatory scrutiny. Demand concentrates in the United States and Southeast Asian markets where flavor preferences persist despite FDA and national health authority restrictions.
- Vape Products:E-liquid formulations represent the fastest-expanding menthol application category. Formulators in the United Kingdom and Germany prioritize cooling-agent consistency for pod-based systems.
- Cigars:Premium hand-rolled varieties incorporate mentholated tipping papers and flavor-infused wrappers. Caribbean and Central American manufacturers supply boutique retailers in Miami and Madrid.
- Smokeless Tobacco:Snus and moist snuff products utilize menthol for sensory masking and throat comfort. Scandinavian regulatory frameworks permit broader flavor latitude than combustible alternatives.
By volume, Cigarettes leads. By growth pace, Vape Products is climbing the fastest.
Application:
Cost-tier stratification separates premium pharmaceutical grades from commodity flavor inputs.
- Pharmaceuticals:USP-grade crystals command substantial price premiums for topical analgesics and cough-cold formulations. CDSCO and FDA documentation requirements filter out uncertified Indian distillers from formulation supply chains.
- Personal Care:Toothpaste and cosmetic cooling agents drive volume throughput. German and French personal care clusters consolidate procurement with pre-qualified Uttar Pradesh producers holding REACH dossiers.
- Food & Beverages:Clean-label confectionery reformulation accelerates natural menthol displacement of synthetic alternatives. North American premium candy manufacturers specify Mentha arvensis-derived crystals.
- Flavors:Beverage and oral care flavor houses demand consistent optical rotation specifications. Swiss and Dutch flavor compounders maintain dedicated quality agreements with crystallization specialists.
Pharmaceuticals captures the highest margin tier. Food & Beverages shows the steepest expansion trajectory.
End User:
Customer-type concentration shapes contract structures and technical service intensity.
- Manufacturers:Pharmaceutical formulators and flavor houses require batch-specific certificates of analysis. Long-term supply agreements with fixed purity specifications displace spot transactions.
- Wholesale Distributors:Regional chemical traders bridge fragmented Indian crystal production and European personal care clusters. Inventory risk concentrates with distributors lacking direct distillery relationships.
- Retail Consumers:Over-the-counter topical analgesic purchases drive pharmacy channel throughput. Japanese and German consumers demonstrate highest per-capita spending on mentholated pain relief patches.
- Food Service:Limited direct uptake concentrates in specialty beverage preparation. Craft cocktail establishments in London and New York specify natural mint extracts.
Manufacturers dominate procurement value. Retail Consumers generate the highest transaction frequency.
Distribution Channel:
Geographic reach and regulatory exposure determine channel viability for menthol-containing products.
- Convenience Stores:Tobacco product accessibility drives menthol cigarette availability. United States point-of-sale restrictions in certain municipalities compress shelf space.
- Specialty Shops:Vape boutiques and premium cigar retailers provide technical guidance on cooling-agent selection. German vape shops emphasize TPD-compliant nicotine concentrations.
- Supermarkets:Mass-market personal care and oral care products reach household penetration. French hypermarkets consolidate toothpaste and cosmetic cooling-agent demand.
- Online Retail:Direct-to-consumer pharmaceutical and vape product sales face evolving age-verification requirements. United Kingdom MHRA guidance shapes e-pharmacy menthol product listings.
Supermarkets move the largest unit volumes. Online Retail faces the most complex compliance evolution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian buyers absorb price volatility from monsoon-dependent Mentha arvensis harvests, while German pharmaceutical formulators prioritize purity certification over cost minimization.
United States
Topical analgesic manufacturers in New Jersey and North Carolina drive USP-grade crystal procurement. FDA enforces 21 CFR identity standards that filter out uncertified distillers. Menthol cigarette restrictions in California and Massachusetts redirect demand toward vape-compatible cooling agents.
Germany
Pain relief patch formulators in Bavaria and Baden-Württemberg specify optical rotation tolerances tighter than Asian commodity grades. EMA's updated excipient guidelines mandate complete contaminant risk assessments. REACH dossier holders in the Frankfurt-Rhine-Main cluster consolidate supply agreements with pre-qualified Indian exporters.
India
CDSCO API-grade documentation requirements concentrate pharmaceutical crystal output among integrated Uttar Pradesh distillers. Monsoon variability in Bihar and Uttar Pradesh compresses margins for non-integrated processors. Lucknow and Moradabad host the specialized freezing-centrifugation technician workforce.
Japan
PMDA-regulated transdermal patch manufacturers in Kansai and Kanto regions specify menthol for counterirritant formulations. METI's chemical substance reporting framework elevates documentation burdens for foreign suppliers. Osaka-based formulators maintain dedicated quality agreements with crystallization specialists.
Brazil
ANVISA's expanding GMP certification reciprocity with Indian regulators opens pathways for Uttar Pradesh producers to supply generic drug manufacturers. São Paulo pharmaceutical clusters seek alternatives to European-priced USP-grade material. Domestic confectionery reformulation accelerates natural menthol displacement of synthetic cooling agents.
Menthol Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with biotechnology platforms competing against agricultural extraction scale. The vendor base spans integrated Indian distillers, European synthetic producers, and Asian contract manufacturers. Three archetypes dominate: purity-certified pharmaceutical suppliers, volume-driven flavor houses, and fermentation-based technology developers. Capacity expansion and regulatory dossier pre-submission represent the dominant competitive moves.
Among German chemical conglomerates, BASF SE exemplifies synthetic platform scale, while Arora Aromatics Pvt. Ltd. anchors South Asian supply through integrated Uttar Pradesh operations. Symrise AG occupies a position within biotechnology-derived routes that reduce agricultural dependency.
| Leading Market Players |
|---|
| Agson Global |
| Arora Aromatics Pvt. Ltd. |
| Symrise AG |
| Tienyuan Chem |
| Fengle Perfume |
| BASF SE |
| Nantong Menthol Factory |
| Silverline Chemicals |
| Takasago International Corporation |
| Others |
Value Chain & Pricing Dynamics
Freezing-centrifugation capacity utilization in Uttar Pradesh and Gujarat shapes both supply concentration and price floors for menthol crystals. Integrated distillers with captive Mentha arvensis acreage command margin protection that non-integrated processors cannot match when monsoon failures compress raw material availability.
Pricing Analysis
USP-NF monograph compliance dictates the pricing tier structure across pharmaceutical, personal care, and flavor segments. Three-tier pricing structure across USP-grade, technical-grade, and natural-extraction economy levels separates certified crystal from commodity alternatives. Price differentiation rests on optical rotation tolerances and impurity profiling depth rather than volume scale alone. Cost compression in technical-grade material is intensifying because Brazilian and Southeast Asian buyers are consolidating procurement with REACH-registered Indian exporters.
Supply Chain Analysis
Strategic stockpile preferences dominate menthol procurement, with German and Japanese pharmaceutical formulators maintaining six-month safety inventories against Uttar Pradesh harvest volatility. Supply concentrates in India, China, and Germany, with raw material dependencies on Mentha arvensis oil, synthetic precursors, and fermentation feedstocks. Single-source vulnerability runs through the freezing-centrifugation technician pool concentrated in Lucknow and Moradabad. Distribution runs through regional chemical traders bridging Indian crystal production and European personal care clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must navigate synthetic biology substitution as engineered yeast routes advance toward commercial viability in European biotechnology hubs.
For Market Incumbents: Consolidate backward integration into Mentha arvensis cultivation to secure raw material access against monsoon volatility. Lock in long-term supply agreements with Brazilian and Japanese pharmaceutical formulators before biotechnology-derived alternatives achieve cost parity. Certification investment in CDSCO API-grade documentation and REACH dossier maintenance remains essential for market access retention. For New Entrants and Emerging Players: Anchor in biotechnology-derived production platforms to bypass agricultural growing season constraints and geographic concentration risk. Target Brazilian pharmaceutical manufacturers seeking alternatives to European-priced USP-grade material through ANVISA GMP reciprocity pathways. Direct-to-formulator digital platforms offer channel compression opportunities in European personal care ingredient sourcing. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated Uttar Pradesh distillers with captive cultivation and pre-submitted regulatory packages. Long-term viability across the projection horizon favors producers with fermentation-based technology pipelines or established REACH dossier positions. Watch synthetic biology cost curves as the inflection indicator for agricultural extraction margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Captive Mentha arvensis acreage in Uttar Pradesh insulates margin from monsoon-driven price spikes. |
| Biotechnology Scale-Up | Engineered Saccharomyces cerevisiae strains enable production decoupled from agricultural harvest cycles. |
| Regulatory Dossier Pre-Submission | CDSCO API-grade documentation and REACH registration open protected access to pharmaceutical formulators. |
| Direct-to-Formulator Digital Platforms | B2B marketplace channels compress multi-layer distribution in European personal care ingredient sourcing. |
| Long-Term Supply Agreements | Fixed-purity contracts with Brazilian and Japanese manufacturers displace spot market volatility. |
Study Parameters
Operator-level perspectives from distillery operations managers, pharmaceutical procurement leads, flavor house technical directors, and regulatory affairs specialists anchored the qualitative base. Primary interviews combined with secondary validation from CDSCO filings, EMA excipient guidelines, REACH registration databases, and Indian customs trade data. Bottom-up crystal production estimates and top-down pharmaceutical formulation demand triangulated volume figures across the analysis window.
Sensitivity analysis tested forecast robustness against Mentha arvensis yield variance, synthetic biology cost reduction trajectories, and regulatory restriction scenarios on tobacco-related applications. Segmentation dimensions modeled include product grade tier, end-use application, geographic production hub, and customer type. CAGRs derived from weighted average of historical volume trends and forward-looking substitution elasticity assumptions. Industry-specific inputs incorporated monsoon pattern correlations and biotechnology pilot scale timelines.
Decision-makers should treat outputs as directional under stable regulatory frameworks for pharmaceutical-grade certification; material deviation would warrant model refresh. Forecasts reflect assumptions on synthetic biology commercialization pace and REACH enforcement continuity. Revision becomes warranted when engineered fermentation yields cross cost-competitive thresholds against agricultural extraction.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
1-Decanol Market
Flavorings and Food Additives
Asia-Pacific Food Flavor Market
Flavorings and Food Additives
Mexico Food Colorants Market
Flavorings and Food Additives
Global Eucalyptus Essential Oil Market
Flavorings and Food Additives
Tangerine Extract Market
Flavorings and Food Additives
US Essential Oil Market
Flavorings and Food Additives
Natural Flavors Market
Flavorings and Food Additives
Clean Label Flavors Market
Flavorings and Food Additives
Water-Soluble Flavors Market
Flavorings and Food Additives
Basil Oil Market
Flavorings and Food Additives
Flavor Drops Market
Flavorings and Food Additives
South America Flavors and Fragrances Market
Flavorings and Food Additives
Browning Solutions Market
Flavorings and Food Additives
Anthocyanin Food Colors Market
Flavorings and Food Additives
Flavor Masking Agents Market
Flavorings and Food Additives
Natural Food Colors and Flavors Market