
 Canola Lecithin Market | 2026-2036
Canola Lecithin Market Size, Share, and Industry Trends Forecast 2026-2036
Canola Lecithin Market Outlook
Soy lecithin is recalibrating procurement economics across the emulsifier sector as food manufacturers confront non-GMO and allergen-labeling pressures. Cargill leverages its North American crush footprint to secure non-GMO canola streams at scale. Archer-Daniels-Midland Company anchors its lecithin portfolio with integrated oilseed processing that sustains cost discipline. Bunge Limited competes through South American origination networks that extend supply security for European compounders.
Canola lecithin comprises phospholipid mixtures extracted from Brassica napus oil through degumming, typically containing 60-70% phosphatidylcholine, phosphatidylethanolamine, and inositol phosphatides, functioning as natural emulsifiers, wetting agents, and dispersants across food and industrial systems. Liquid lecithin dominates volume throughput due to its direct incorporation into chocolate confections and bakery formulations, though powder lecithin captures margin concentration from infant nutrition and dietary supplement applications where low-fat, free-flowing specifications command premium positioning. The nutraceuticals application segment exhibits the steepest trajectory as dietary supplement companies reformulate softgel encapsulation around plant-derived phospholipid sources.
FDA allergen-labeling requirements under FALCPA and EFSA non-GMO verification protocols shape product standards and market access for canola-derived alternatives. Health Canada and CFIA oversight of novel food ingredients further conditions import pathways for modified phospholipid fractions. Stakeholders must monitor evolving regulatory divergence between North American and European jurisdictions on processing aid classifications to anticipate reformulation mandates and certification investments.
Market Dynamics
Non-GMO verification protocols and allergen-labeling mandates are restructuring procurement economics across the emulsifier sector, compelling food manufacturers to source Brassica napus-derived phospholipids in place of genetically modified soy alternatives.
Growth Catalysts
- FALCPA allergen-labeling requirements:US food manufacturers face mandatory disclosure obligations for soy-derived ingredients, accelerating reformulation toward canola-sourced emulsifiers in confectionery and bakery applications.
- Clean-label confectionery demand:Chocolate compounders in Germany and Switzerland specify de-oiled canola lecithin to meet retailer non-GMO certification standards and consumer transparency expectations.
- Enzymatic degumming advances:Novel phospholipase processing methods improve phosphatidylcholine recovery rates from crude canola oil, reducing input waste and expanding viable supply streams.
Market Restraints
- Canola seed price volatility:Crush margin compression and weather-driven yield fluctuations in Canadian prairie provinces transmit directly to lecithin feedstock costs.
- European supply concentration:Premium de-oiled grade production clusters around German and Dutch processing facilities, creating single-source vulnerability for compounders elsewhere.
- Sunflower lecithin substitution:Non-allergen, non-GMO sunflower-derived alternatives capture share in infant nutrition and pharmaceutical encapsulation segments.
Strategic Opportunities
- Indian nutraceutical penetration:FSSAI novel food ingredient approvals for modified phospholipid fractions remain underutilized, opening softgel and dietary supplement formulation channels.
- EU Green Deal bio-based manufacturing incentives:Sustainable process certification for solvent-free extraction methods qualifies producers for preferential procurement programs.
- E-commerce ingredient platforms:Direct procurement portals for mid-scale bakeries and craft chocolate makers bypass traditional distributor markups.
Industry Challenges
- Phospholipid fractionation expertise scarcity:Specialized chemical engineering talent for high-purity phosphatidylcholine isolation remains concentrated at established European processors.
- EFSA novel food dossier timelines:Extended safety assessment procedures for enzymatically modified lecithin grades delay market entry by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canola Lecithin Market |
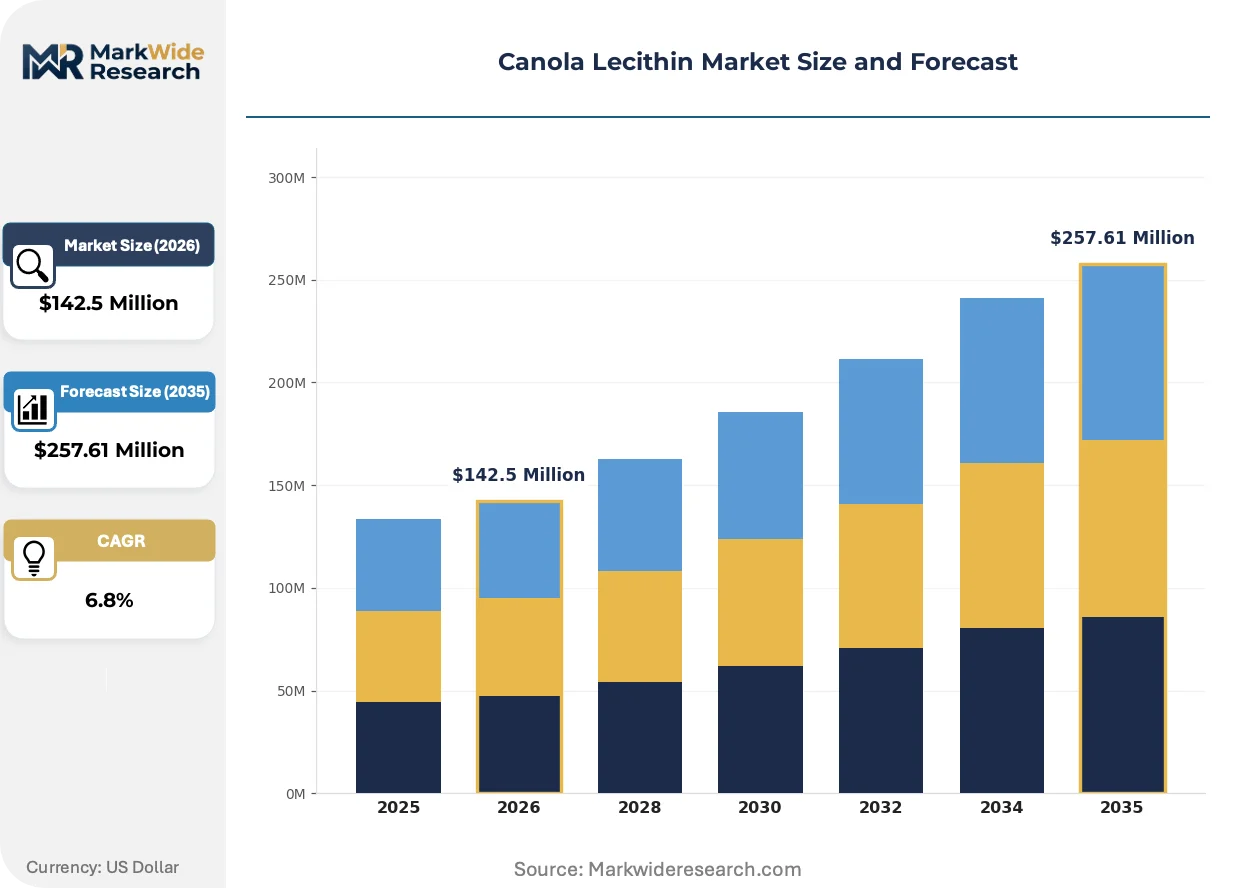
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $257.61 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Lecithin, Powder Lecithin, Granulated Lecithin, Emulsifiers Application: Food Industry, Nutraceuticals, Animal Feed, Industrial Applications End User: Food Manufacturers, Dietary Supplement Companies, Animal Nutrition Providers, Cosmetics Producers Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | American Lecithin Company, Austrade Inc., Cargill, Bunge Limited, American Chemie, Archer-Daniels-Midland Company, Ciranda, Wilmar International Limited, Lecico GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canola Lecithin Market Strategic Shifts
Processing technology convergence and regulatory divergence are accelerating product differentiation strategies across the phospholipid supply base. Manufacturers now compete on certification depth and extraction method transparency rather than commodity volume.
Membrane filtration systems are integrating into degumming operations to replace traditional solvent-based phospholipid recovery. Specialty oilseed processors in Canada and France deploy ceramic microfiltration units that yield higher-purity phosphatidylcholine fractions without hexane residue. This technology is integrating food-grade and pharmaceutical-grade production lines, collapsing the historical separation between these supply tiers and enabling batch-traceable output.
REACH registration requirements for imported lecithin derivatives are tightening substance documentation obligations for non-EU suppliers. Compounders must now verify full supply chain phospholipid composition data to maintain formulation approvals. Nutraceutical and infant formula segments face the steepest compliance burden, driving consolidation toward vertically integrated crush-to-lecithin operators with captive analytical capabilities.
Direct contracting between chocolate manufacturers and oilseed processors is displacing traditional ingredient distributor relationships. Mid-scale confectioners in Belgium and Switzerland now negotiate annual volume agreements with specific crush facilities, specifying fatty acid profiles and pesticide residue thresholds. This pattern concentrates most visibly in premium single-origin chocolate verticals where provenance claims extend to emulsifier sourcing.
Canola Lecithin Market Segmentation
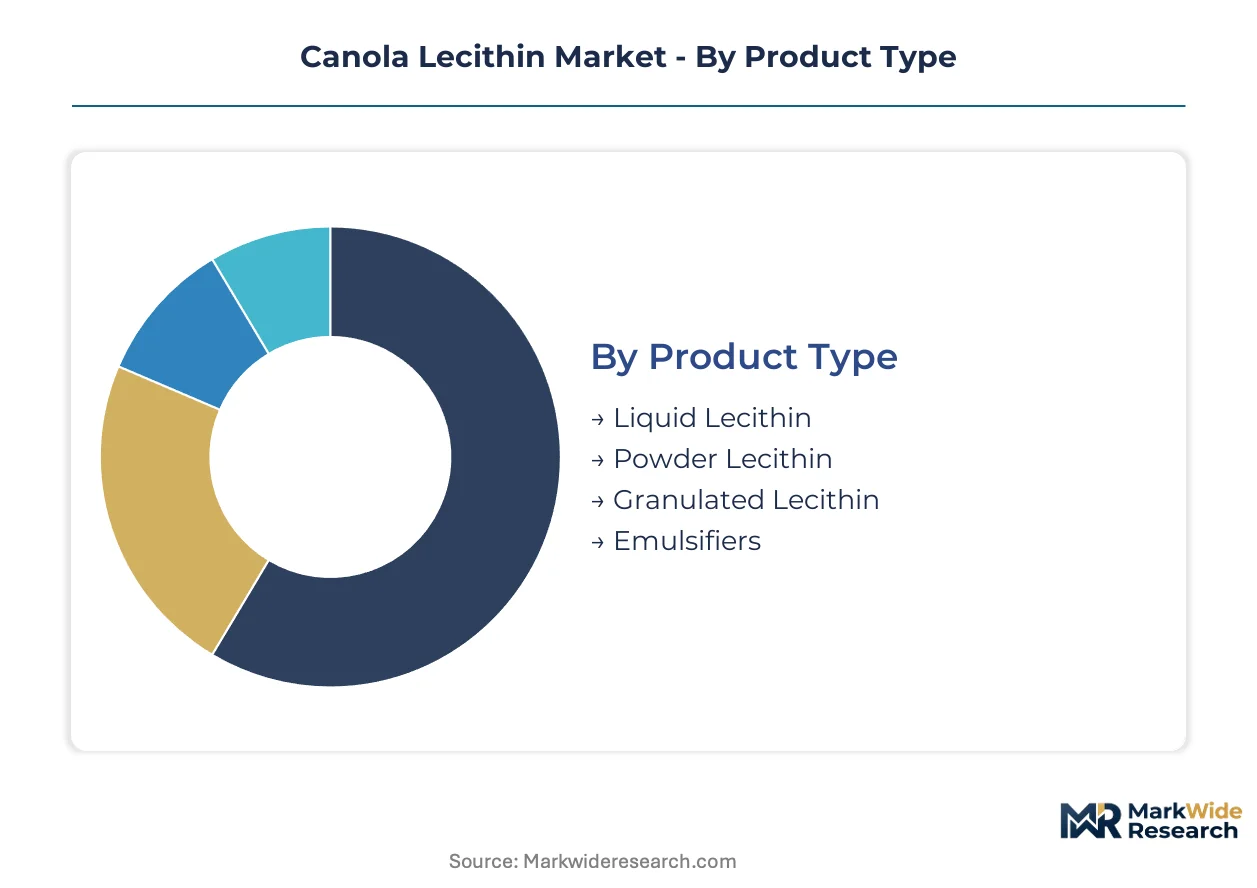
Canola lecithin procurement decisions pivot on functional specifications, regulatory compliance burdens, and supply chain traceability requirements. Buyers weigh phospholipid concentration against handling properties and certification depth when selecting across product formats and application segments.
Product Type:
Formulation compatibility and handling economics drive product type selection, with viscosity requirements and shelf-stability needs conditioning buyer preferences across liquid, powder, and granulated formats.
- Liquid Lecithin:Standard degummed canola oil extract containing 60-70% phospholipids in fluid form, directly pumpable into chocolate conching and bakery mixing operations. German and Swiss confectioners specify liquid grades for cost-efficient volume throughput in compound chocolate manufacturing.
- Powder Lecithin:De-oiled phospholipid fractions processed into free-flowing particulate form through acetone precipitation or spray-drying, delivering enhanced oxidative stability and reduced fat content. Dietary supplement compounders in North America specify powder grades for softgel encapsulation and instant beverage premixes where low-fat certification commands premium positioning.
- Granulated Lecithin:Agglomerated powder particles engineered for reduced dusting and improved flowability in automated handling systems, serving industrial compounders with pneumatic conveying infrastructure.
- Emulsifiers:Fractionated and modified phospholipid derivatives with tailored hydrophilic-lipophilic balance values, produced through enzymatic or chemical modification for specialized stabilizing functions.
Liquid lecithin leads on scale; powder lecithin leads on momentum.
Application:
End-use performance standards and regulatory scrutiny intensity segment demand patterns, with food safety protocols and novel food ingredient classifications creating divergent compliance pathways.
- Food Industry:Emulsification and anti-spattering functions in chocolate, margarine, bakery, and processed foods, where FALCPA allergen-labeling compliance and non-GMO verification shape supplier qualification. Belgian chocolate manufacturers specify canola-derived alternatives to meet retailer clean-label procurement mandates.
- Nutraceuticals:Phosphatidylcholine and phosphatidylserine extraction for cognitive health and liver support supplements, with EFSA novel food dossier requirements and Health Canada natural health product licensing conditioning market entry. Softgel encapsulation demand concentrates in dietary supplement contract manufacturers seeking plant-derived phospholipid sources.
- Animal Feed:Feed-grade emulsification and energy density enhancement in poultry and aquaculture rations, competing with soy lecithin on cost per unit phospholipid.
- Industrial Applications:Lubricant additives, paint dispersants, and leather tanning auxiliaries where technical-grade specifications prioritize functional performance over food safety certification.
Food industry applications anchor volume; nutraceuticals demonstrate the steepest expansion trajectory.
End User:
Procurement sophistication and specification stringency differentiate end user segments, with quality management system maturity and supply chain audit capabilities determining supplier access tiers.
- Food Manufacturers:Integrated bakery, confectionery, and processed food operations with established supplier qualification programs and annual volume contracting frameworks. Mid-scale craft chocolate makers in Belgium and Switzerland increasingly specify provenance-traceable canola lecithin for premium positioning.
- Dietary Supplement Companies:Contract manufacturers and branded marketers with cGMP compliance requirements and finished product testing protocols for phospholipid identity and purity verification.
- Animal Nutrition Providers:Premix compounders and integrated livestock operations prioritizing feed cost optimization and ration energy density over emulsifier sourcing transparency.
- Cosmetics Producers:Formulators of skin care emulsions and hair conditioning products leveraging canola-derived phospholipids for natural positioning and skin barrier function claims.
Food manufacturers dominate procurement scale; dietary supplement companies are gaining share fastest.
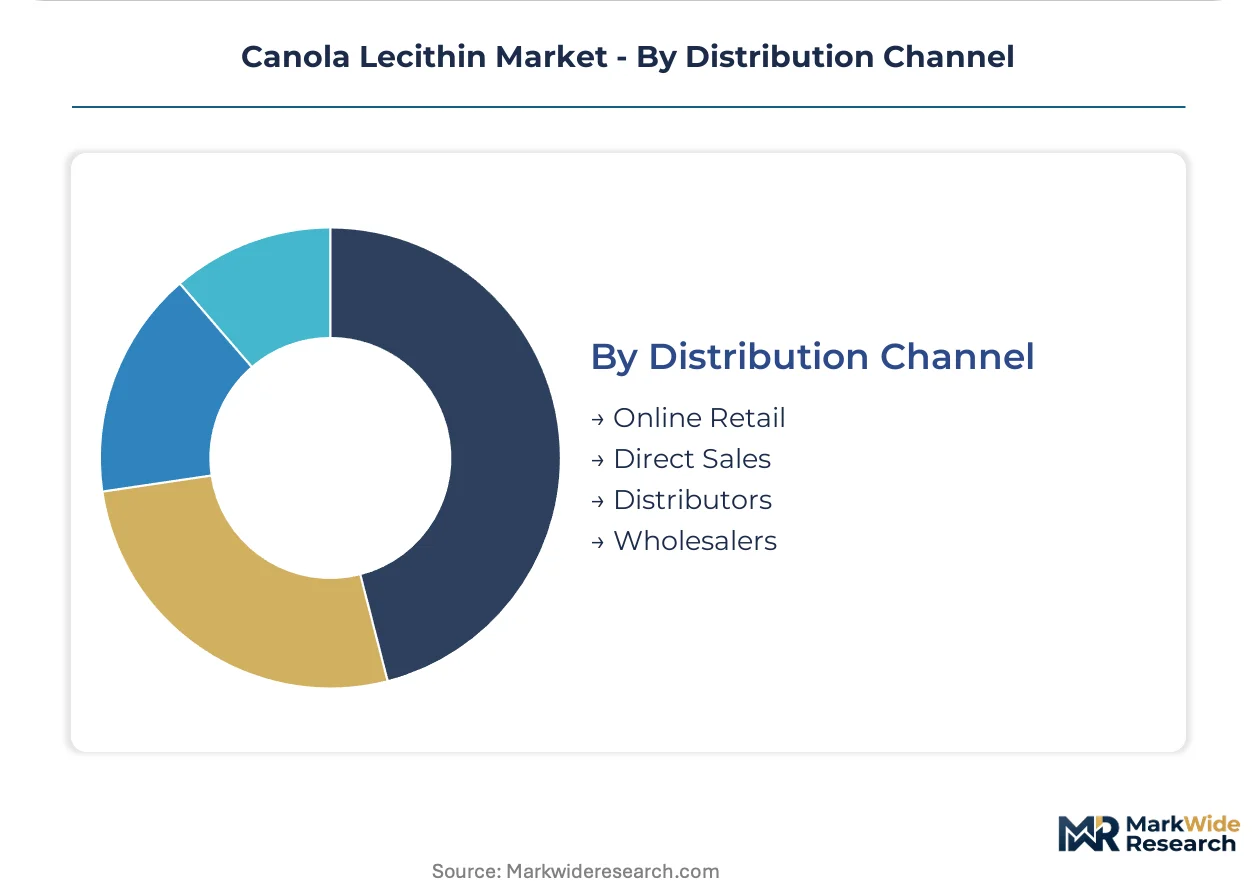
Distribution Channel:
Order fragmentation and technical service requirements shape channel selection, with specification complexity and volume scale determining whether direct processor relationships or intermediary networks prove optimal.
- Direct Sales:Annual volume agreements between oilseed processors and large-scale food manufacturers, specifying fatty acid profiles, pesticide residue thresholds, and delivery scheduling. Ciranda and Lecico GmbH anchor direct supply relationships with German compounders for premium de-oiled grades.
- Distributors:Regional ingredient specialists maintaining inventory positions and technical application support for mid-scale manufacturers lacking direct procurement infrastructure.
- Online Retail:E-commerce platforms serving craft bakeries, small-batch chocolate makers, and dietary supplement startups with fractional packaging and rapid fulfillment.
- Wholesalers:Bulk commodity handlers aggregating standard-grade liquid lecithin for price-sensitive industrial applications and animal feed compounders.
Direct sales command the largest transaction values; online retail channels are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German processing clusters anchor demand concentration for premium de-oiled grades, while North American crush capacity and Asian nutraceutical formulation drive supply diversification across distinct regulatory environments.
United States
FDA FALCPA allergen-labeling mandates accelerate soy-to-canola reformulation in confectionery and bakery operations. Cargill leverages its North American oilseed crush footprint to secure non-GMO canola streams at commercial scale. Chicago-area food manufacturers specify liquid grades for chocolate compound production.
Germany
EFSA non-GMO verification protocols and retailer clean-label procurement standards concentrate premium de-oiled demand. Ciranda and Lecico GmbH anchor direct supply relationships with compounders in Hamburg and Cologne processing corridors. Belgian chocolate manufacturers source across the border to meet certification requirements.
Canada
Health Canada and CFIA oversight of novel food ingredients conditions import pathways for modified phospholipid fractions. Prairie province crush facilities transmit seed price volatility directly to lecithin feedstock economics. Alberta and Saskatchewan oilseed processors supply North American and Asian export channels.
India
FSSAI novel food ingredient approvals for modified phospholipid fractions remain underutilized, opening formulation channels for dietary supplement contract manufacturers. Mumbai and Hyderabad nutraceutical clusters demonstrate reformulation interest around plant-derived phospholipid sources. Domestic oilseed processing capacity expansion lags demand growth.
Switzerland
Swissmedic pharmaceutical-grade certification requirements and premium chocolate provenance claims extend to emulsifier sourcing specifications. Zurich and Geneva-based confectioners negotiate direct annual volume agreements with specific crush facilities. Single-origin chocolate verticals specify fatty acid profiles and pesticide residue thresholds.
Canola Lecithin Market Competitive Environment
Global majors compete with regional champions across integrated crush-to-lecithin supply chains and specialized fractionation capabilities. The vendor base separates into three tiers: multinational oilseed processors with captive supply networks, European specialists commanding premium de-oiled grades, and Asian traders aggregating standard liquid volumes. Dominant competitive moves include backward integration into oilseed crush assets and enzymatic degumming technology licensing for phosphatidylcholine recovery optimization.
Among North American integrated processors, Archer-Daniels-Midland Company and Cargill exemplify the multinational oilseed archetype with crush footprint leverage. Lecico GmbH occupies a specialist position within the European premium tier. These three anchors represent distinct competitive vectors: scale-driven supply security, certification-depth positioning, and regional market access respectively.
| Leading Market Players |
|---|
| American Lecithin Company |
| Austrade Inc. |
| Cargill |
| Bunge Limited |
| American Chemie |
| Archer-Daniels-Midland Company |
| Ciranda |
| Wilmar International Limited |
| Lecico GmbH |
| Others |
Value Chain & Pricing Dynamics
Membrane filtration adoption in Canadian and French processing facilities is collapsing the historical separation between food-grade and pharmaceutical-grade production tiers, simultaneously reducing hexane-related compliance costs and concentrating margin capture among operators with ceramic microfiltration capabilities. This technological transition feeds directly into pricing power dynamics for premium de-oiled grades.
Pricing Analysis
Canadian canola seed futures transmit volatility directly into lecithin feedstock economics, with crush margin compression in Alberta and Saskatchewan forcing contract renegotiations. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-certified de-oiled grades from standard liquid formats and feed-grade alternatives. Price differentiation hinges on phosphatidylcholine concentration and organic certification depth. Pricing pressure stems from sunflower lecithin substitution in infant nutrition segments. Animal feed compounders exhibit highest price sensitivity; Swiss chocolate manufacturers demonstrate lowest sensitivity due to provenance-traceability requirements.
Supply Chain Analysis
Container freight rates from Hamburg to Mumbai and trans-Pacific routes from Vancouver to Shanghai condition landed cost competitiveness for Asian nutraceutical formulators. Supply concentrates in Germany, Canada, and the Netherlands, with German processors commanding premium de-oiled grade production. Raw material dependencies include Brassica napus seed stocks, hexane for traditional extraction, and phospholipase enzymes for novel degumming methods. Single-source vulnerability characterizes European premium grade access, as Dutch and German facilities serve compounders across Belgium and Switzerland. Distribution runs through direct annual volume agreements for large-scale manufacturers, with regional distributors serving mid-scale bakeries and craft chocolate operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canola lecithin procurement functions as a geographic-arbitrage play between North American crush economics and European certification premiums, with the spread between Canadian feedstock costs and German processing margins creating repositioning incentives for integrated operators.
For Market Incumbents: To counter sunflower lecithin incursion in infant nutrition and pharmaceutical encapsulation segments, Cargill and ADM should deepen backward integration into prairie province crush assets while accelerating enzymatic degumming licensing to recover phosphatidylcholine yields competitive with sunflower alternatives. Certification investment in EFSA novel food dossiers for modified fractions extends defensive moats against substitution threats. For New Entrants and Emerging Players: E-commerce ingredient platforms targeting craft chocolate makers and mid-scale bakeries in Belgium and Switzerland offer the most penetrable route, bypassing established distributor markups through fractional packaging and rapid fulfillment. White-space concentration sits in Indian nutraceutical softgel formulation, where FSSAI approvals for modified phospholipid fractions remain underutilized. Direct procurement portals with technical application support capture share from traditional channel structures. For Investors and Strategic Acquirers: Valuations sit cheapest among Canadian oilseed processors with underutilized lecithin fractionation capabilities and captive canola supply. Long-term viability over a five-to-ten year horizon rests on enzymatic processing adoption curves and regulatory divergence between FDA and EFSA novel food pathways. The signal to watch is EFSA novel food dossier approval velocity for enzymatically modified grades, which would unlock premium positioning for early movers.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Degumming Licensing | Phospholipase processing methods improve phosphatidylcholine recovery from Canadian canola oil. |
| Backward Integration into Crush Assets | Captive supply of non-GMO canola streams secures cost discipline against seed price volatility. |
| EFSA Novel Food Dossier Investment | Regulatory approval for modified fractions unlocks premium positioning in European nutraceutical channels. |
| E-Commerce Platform Development | Direct procurement portals bypass distributor markups for Belgian and Swiss craft chocolate segments. |
| Membrane Filtration Capacity Expansion | Ceramic microfiltration units collapse food-grade and pharmaceutical-grade production separation. |
Study Parameters
Multiple input streams — primary interviews with oilseed procurement directors, lecithin fractionation engineers, and dietary supplement contract manufacturers; secondary validation through customs/trade data, EFSA novel food registers, and SEC filings from integrated processors; and proprietary crush margin databases — were reconciled through bottom-up and top-down triangulation. Stakeholder consultations spanned German compounders, Canadian prairie province processors, and Mumbai nutraceutical formulators to capture geographic variance in specification requirements and regulatory compliance burdens.
Historical volume trajectories were cross-referenced against panel input from procurement leads to establish baseline assumptions across the projection horizon. The analytical framework modeled segmentation dimensions including product format (liquid, powder, granulated, modified), application vertical (food, nutraceuticals, feed, industrial), and end-user sophistication tier. CAGRs were derived from demand elasticity estimates tied to soy-to-canola reformulation rates and enzymatic processing adoption curves, with specific weighting applied to FALCPA compliance timelines and EFSA novel food assessment durations.
Canadian prairie weather patterns, EFSA dossier approval delays, and sunflower lecithin price competitiveness are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented assumptions about regulatory divergence and processing technology diffusion rates. Stakeholders should weight assumptions against their own operating context and supply chain exposure to single-source European premium grade dependencies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Argentina Food Flavor and Enhancer Market
Flavorings and Food Additives
Citrus Extract Market
Flavorings and Food Additives
Cheese Flavor Market
Flavorings and Food Additives
Citrus Flavonoid Complexes from Mediterranean Peels Market
Flavorings and Food Additives
Japan Food Colorants Market
Flavorings and Food Additives
France Food Colorants Market
Flavorings and Food Additives
Asia-Pacific Flavor and Fragrance Market
Flavorings and Food Additives
Russia Food Colorants Market
Flavorings and Food Additives
US Flavors Market
Flavorings and Food Additives
United States Food Colorants Market
Flavorings and Food Additives
All-Natural Flavors System Market
Flavorings and Food Additives
Mexico Food Colorants Market
Flavorings and Food Additives
Citrus Concentrate Market
Flavorings and Food Additives
American Spikenard Extract Market
Flavorings and Food Additives
Clean Label Flavors Market
Flavorings and Food Additives
North America Flavors and Fragrances Market