
 Flavoring Oil Market | 2026-2036
Flavoring Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Flavoring Oil Market Analysis
The EU Green Deal and its Farm to Fork strategy is consolidating procurement priorities across European food manufacturers toward botanical-derived inputs. Kerry Group leverages its integrated taste and nutrition platform to secure long-term supply contracts with clean-label brands. Givaudan anchors its competitive position through deep backward integration into natural raw material sourcing across tropical growing regions. Firmenich differentiates via biotechnology-led fermentation processes that replicate rare botanical profiles without agricultural extraction constraints.
Flavoring oils comprise concentrated aromatic lipophilic preparations, typically extracted through cold-pressing, steam distillation, or solvent recovery, designed to impart specific taste and olfactory signatures to finished goods. Essential oils and natural extracts command premium positioning as food manufacturers reformulate away from synthetic additives under tightening EFSA and FDA scrutiny. Within applications, food and beverage dominates volume while nutraceuticals represents the fastest-growing margin pool as functional positioning commands higher per-unit pricing. Direct sales channels to food manufacturers concentrate the highest-value transactions, though specialty stores sustain artisan producer access for small-batch premium lines.
FDA food additive regulations and GRAS self-affirmation requirements shape product development timelines and market access thresholds for U.S.-bound suppliers. REACH registration obligations and EFSA flavoring substance evaluations impose compositional transparency demands that favor vertically integrated producers with in-house analytical capabilities. Stakeholders must monitor evolving botanical novel food classifications under EFSA and emerging state-level fragrance disclosure laws in California that could cascade into broader flavor oil labeling mandates.
Market Dynamics
Clean-label procurement mandates from food and beverage manufacturers are compressing synthetic flavoring oil demand while accelerating backward integration into natural raw material sourcing across tropical growing regions.
Growth Catalysts
- EU Green Deal Farm to Fork Strategy:European food manufacturers face binding sustainability targets that favor botanical-derived inputs over petroleum-based synthetic alternatives.
- India PLI Scheme:Domestic food processing capacity expansion and production-linked incentives attract flavor compound manufacturing investments from multinational suppliers.
- Biotechnology-led Fermentation:Precision fermentation processes replicate rare botanical profiles without agricultural extraction constraints, unlocking supply of scarce natural flavor molecules.
Market Restraints
- Raw Material Volatility:Weather-dependent yields of vanilla, citrus, and spice crops in Madagascar, Indonesia, and India create input cost instability for natural extract producers.
- REACH Registration Burden:ECHA compliance obligations impose compositional transparency demands that favor large vertically integrated producers with captive analytical laboratories.
- Synthetic Substitution Ceiling:Cost-competitive artificial flavor alternatives retain share in price-sensitive mass-market applications where clean-label premiums cannot be passed to consumers.
Strategic Opportunities
- Nutraceutical Functional Positioning:Flavoring oils with adaptogenic or wellness claims command premium pricing in dietary supplement and functional beverage applications.
- Direct-to-Manufacturer Channels:Bypassing traditional distributor networks allows specialty producers to capture margin and secure long-term formulation partnerships with clean-label brands.
- EFSA Novel Food Pathways:Emerging botanical classifications create first-mover advantages for suppliers that successfully navigate pre-market authorization for unconventional plant extracts.
Industry Challenges
- GRAS Self-Affirmation Complexity:FDA food additive timelines for U.S. market access extend product development cycles and strain smaller producers lacking dedicated regulatory affairs capacity.
- Analytical Capability Gaps:Authenticity testing and adulteration detection require capital-intensive chromatography and spectroscopy infrastructure that fragments competitive positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flavoring Oil Market |
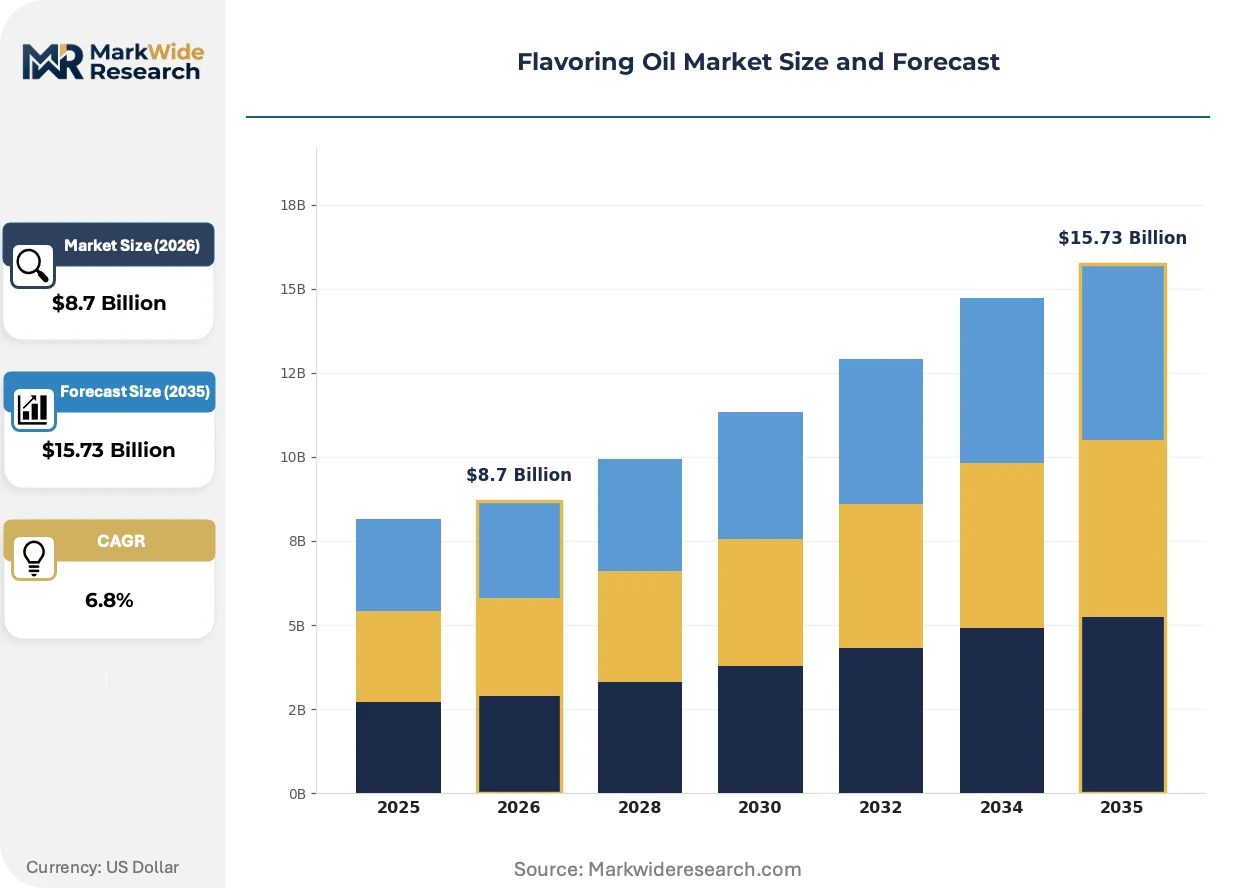
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oils, Natural Extracts, Flavor Compounds, Synthetic Flavorings Application: Food & Beverage, Cosmetics, Pharmaceuticals, Nutraceuticals Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales End User: Food Manufacturers, Beverage Producers, Cosmetic Brands, Others |
| Companies Covered | Kerry Group, Sensient Technologies, Givaudan, Robertet, Land O’Lakes, International Flavors & Fragrances, T. Hasegawa, Firmenich, Symrise, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flavoring Oil Market Emerging Trajectories
Digital quality control systems and biotechnology platforms are compressing traditional extraction economics while regulatory transparency mandates reshape supplier qualification protocols across food manufacturing value chains.
Supercritical CO2 extraction technology is automating separation of heat-sensitive aromatic compounds that degrade under conventional steam distillation. Mid-tier flavor houses in Germany and Switzerland are retrofitting production lines with these systems to capture premium natural positioning. The technology is automating quality consistency while reducing solvent residue compliance risks that previously required extensive third-party testing.
REACH registration obligations and EFSA flavoring substance evaluations are tightening compositional disclosure requirements for all suppliers targeting European food manufacturers. Registration dossiers now demand full supply chain traceability back to agricultural source. Small-batch artisan producers without captive laboratory infrastructure face exclusion from procurement shortlists of multinational food manufacturers consolidating supplier bases.
Buyer concentration among contract food manufacturers is compressing traditional distributor intermediation in high-volume transactions. Direct technical partnerships between flavor oil suppliers and co-manufacturing facilities in India and Mexico are replacing arm's-length commodity purchasing. This channel consolidation is most visible in private-label snack and beverage production where formulation stability and batch consistency override price minimization.
Flavoring Oil Market Segmentation
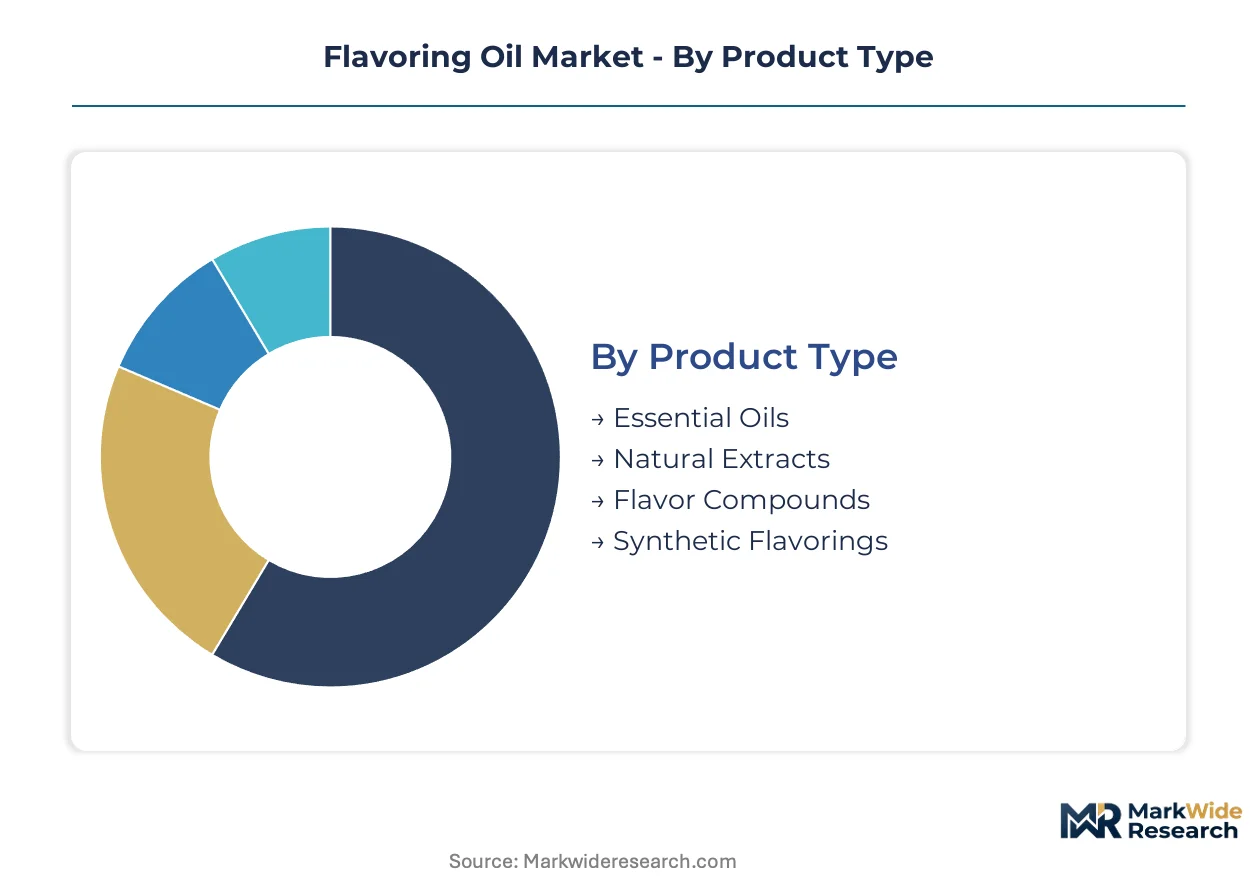
Flavoring oil procurement patterns diverge sharply between mass-market food manufacturing and premium-positioned wellness applications. Segmentation reveals how extraction method, regulatory classification, and channel structure determine margin capture across supplier tiers.
Product Type:
Volume concentration favors solvent-extracted and synthetically derived inputs, while cold-pressed and steam-distilled variants command price premiums in clean-label formulations.
- Essential Oils:Concentrated lipophilic aromatic preparations extracted through cold-pressing or steam distillation retain volatile terpene profiles sensitive to thermal degradation. Food manufacturers in Germany and Switzerland prioritize these for organic confectionery lines where EFSA organic labeling requirements restrict synthetic additive use.
- Natural Extracts:Solvent-recovered or supercritical CO2-extracted preparations capture broader molecular spectra including non-volatile taste compounds. Demand concentrates in Indian food processing clusters where FSSAI clean-label enforcement and PLI scheme incentives accelerate domestic extraction capacity installation.
- Flavor Compounds:Semi-synthetic or nature-identical molecules manufactured through chemical synthesis or bioconversion bridge cost and performance gaps.
- Synthetic Flavorings:Petroleum-derived aromatic molecules engineered for stability and standardization retain share in price-sensitive mass-market applications.
Mature deployment sits with Synthetic Flavorings. Newer deployment is concentrated in Essential Oils.
Application:
Food and beverage manufacturing absorbs the highest absolute volumes, yet nutraceutical positioning unlocks the steepest per-unit margin expansion.
- Food & Beverage:Bakery, confectionery, and savory applications require heat-stable oil matrices that resist oxidation during processing. European manufacturers under EU Green Deal Farm to Fork mandates are reformulating toward botanical-derived inputs, compressing synthetic share in premium product lines.
- Nutraceuticals:Functional positioning with adaptogenic or wellness claims commands premium pricing in dietary supplements and functional beverages. U.S. suppliers navigate FDA GRAS self-affirmation complexity to access this margin pool, with development timelines favoring larger producers with dedicated regulatory affairs capacity.
- Cosmetics:Fragrance and skincare applications demand low-irritancy profiles and INCI-compliant labeling transparency.
- Pharmaceuticals:Excipient-grade oils meet USP-NF or Ph.Eur. monograph specifications for oral and topical dosage forms.
Volume leadership belongs to Food & Beverage. Margin expansion is climbing the fastest in Nutraceuticals.
Distribution Channel:
Channel selection tracks transaction scale and technical service intensity, with direct relationships displacing traditional intermediation in high-volume supply.
- Direct Sales:Technical partnerships between flavor houses and contract manufacturers consolidate procurement for private-label snack and beverage production. Formulation stability requirements and batch consistency specifications override price minimization in these relationships.
- Specialty Stores:Artisan producers and small-batch premium lines access curated buyer bases through dedicated retail channels in urban centers.
- Online Retail:E-commerce platforms serve hobbyist bakers and small foodservice operators with standardized pack sizes.
- Supermarkets:Mass-market retail channels distribute consumer-packaged flavoring oils for home cooking applications.
Established procurement flows through Supermarkets. Emerging channel concentration is visible in Direct Sales.
End User:
End-user structure reflects the divergence between industrial-scale manufacturing and brand-owner formulation control.
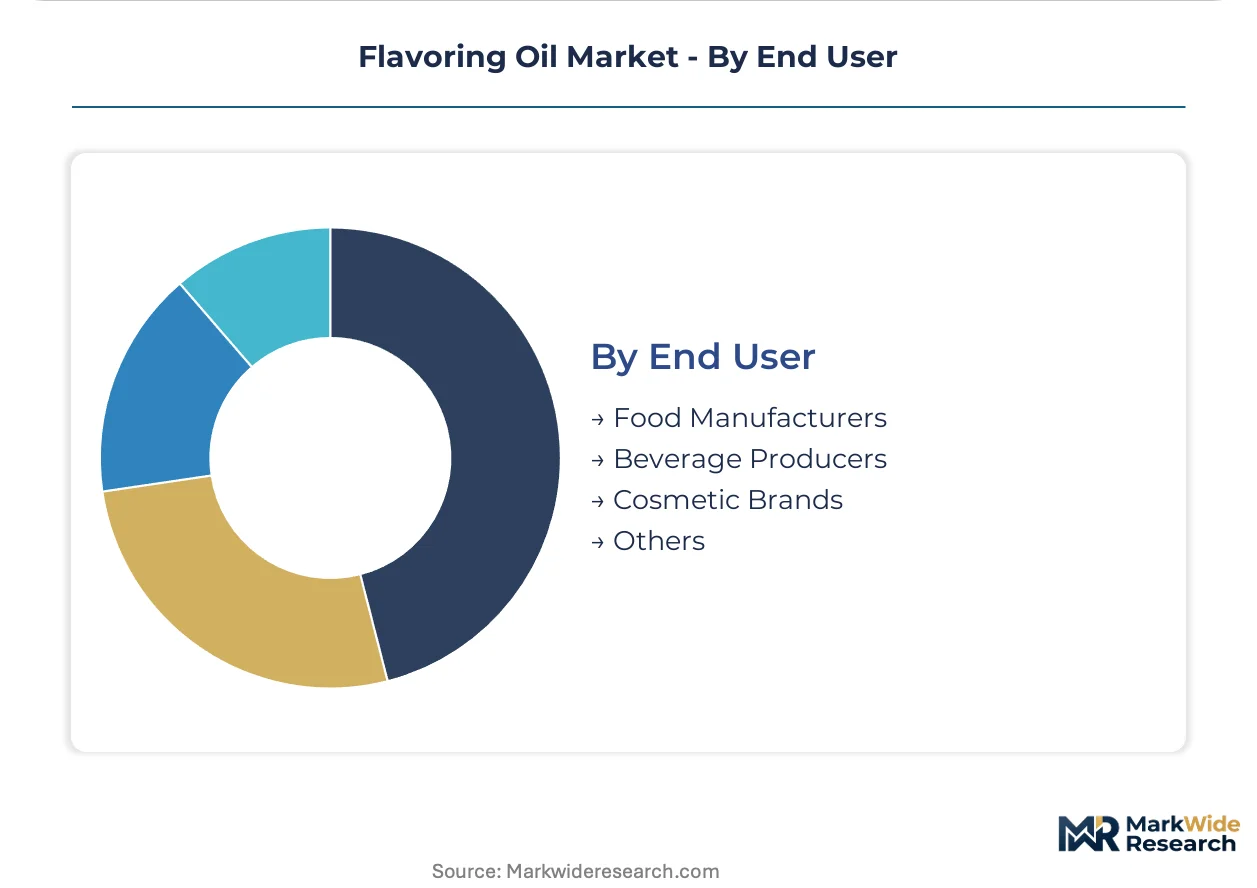
- Food Manufacturers:Industrial bakeries, confectioners, and savory processors specify oil matrices for finished goods production. REACH registration obligations and EFSA compositional transparency demands favor vertically integrated suppliers with captive analytical laboratories in procurement shortlists.
- Beverage Producers:Soft drink, functional beverage, and alcoholic drink manufacturers require water-dispersible or emulsion-stable flavor systems.
- Cosmetic Brands:Skincare and fragrance houses source IFRA-compliant aromatic inputs with documented allergen profiles.
- Others:Pharmaceutical excipient manufacturers and household product formulators represent niche demand pockets.
Procurement maturity centers on Food Manufacturers. Emerging specification intensity is concentrated in Beverage Producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of flavoring oils concentrates in tropical growing regions while formulation and value-added processing clusters in industrialized markets. Consumption patterns diverge between clean-label reformulation in Europe and cost-optimized mass-market applications in emerging economies.
United States
Reformulation mandates from major food manufacturers are compressing synthetic flavoring oil demand while expanding procurement of natural extracts. FDA GRAS self-affirmation requirements shape product development timelines for domestic suppliers. Chicago and New Jersey host concentrated flavor house operations serving contract food manufacturers.
Germany
EU Green Deal Farm to Fork targets are binding procurement priorities toward botanical-derived inputs across confectionery and savory processing. REACH registration obligations imposed by ECHA favor vertically integrated suppliers with captive analytical laboratories. Bavaria and North Rhine-Westphalia anchor extraction technology clusters retrofitting supercritical CO2 systems.
India
Domestic food processing capacity expansion under the PLI scheme is attracting multinational flavor compound manufacturing investments. FSSAI clean-label enforcement is accelerating domestic extraction capacity installation in spice-growing regions. Maharashtra and Gujarat concentrate new production facilities serving both export and domestic markets.
Switzerland
Precision biotechnology platforms are replicating rare botanical profiles without agricultural extraction constraints. Swissmedic and FOPH transparency requirements align with EFSA compositional disclosure standards for European market access. Basel and Geneva host fermentation-based flavor molecule development operations.
Indonesia
Vanilla and spice crop cultivation supplies raw material inputs to global extraction networks. Weather-dependent yields create input cost instability that propagates through natural flavor oil value chains. Sumatra and Sulawesi concentrate clove and nutmeg processing infrastructure serving international buyers.
Flavoring Oil Market Vendor Landscape
The competitive structure tilts toward integrated multinational flavor houses with captive raw material sourcing and biotechnology capabilities. Tiered positioning separates premium botanical extract specialists from mass-market synthetic compound suppliers. Dominant competitive moves include backward integration into tropical growing regions and fermentation-based capacity expansion to bypass agricultural supply constraints.
Among Ireland-based and Swiss-anchored integrated platforms, Kerry Group, Givaudan, and Firmenich occupy positions exemplifying the convergence of taste technology with nutrition science. These entities represent archetypes of deep upstream control over natural raw material sourcing combined with biotechnology-led manufacturing processes. Sensient Technologies and International Flavors & Fragrances sit within the specialty ingredient tier, while Robertet exemplifies family-structured botanical extraction heritage. T. Hasegawa anchors Japanese fermentation expertise, and Symrise represents German precision in flavor and fragrance integration.
| Leading Market Players |
|---|
| Kerry Group |
| Sensient Technologies |
| Givaudan |
| Robertet |
| Land O'Lakes |
| International Flavors & Fragrances |
| T. Hasegawa |
| Firmenich |
| Symrise |
| Others |
Supply Flow & Price Mechanics
Chromatography technicians in Basel and Geneva command wage premiums that widen spreads between fermentation-derived specialty molecules and commodity-extracted alternatives. Labor-cost differentials between Swiss biotechnology clusters and Indian solvent-extraction facilities stratify pricing tiers across natural flavor oil procurement.
Pricing Analysis
Margin tightening in cold-pressed essential oils reflects Madagascar vanilla crop failures and Indonesian clove yield instability. Three-tier pricing structure across premium organic-certified, standard natural-extract, and economy synthetic-identical levels separates buyers by formulation positioning. Price differentiation hinges on EFSA organic labeling compliance and REACH registration dossier completeness. Beverage manufacturers exhibit lowest price sensitivity for heat-stable emulsion systems, while private-label snack producers prioritize cost minimization over botanical provenance.
Supply Chain Analysis
Single-source vulnerability sits with Madagascar vanilla and Indonesian clove suppliers subject to cyclone disruption and El Niño rainfall patterns. Raw material procurement draws from India for spice oleoresins, Indonesia for tropical aromatics, and Switzerland for fermentation-derived molecules. Supply chain risk centers on weather-dependent agricultural yields propagating cost volatility through natural extract value chains. Distribution runs through direct technical partnerships between flavor houses and contract manufacturers, displacing traditional distributor intermediation in high-volume transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive control over tropical growing regions and biotechnology platforms determines margin capture. Players are pursuing backward integration into agricultural sourcing and precision fermentation capacity to bypass raw material volatility.
For Market Incumbents: Anchor competitive position through supercritical CO2 extraction retrofitting in Germany and Switzerland to capture EFSA-compliant organic positioning. Defend against biotechnology-led fermentation entrants by securing long-term offtake agreements with Madagascar and Indonesian agricultural cooperatives. Prioritize REACH registration dossier completeness to maintain procurement shortlist eligibility among consolidating multinational food manufacturers. For New Entrants and Emerging Players: Capture white-space opportunity in Indian domestic food processing clusters where PLI scheme incentives and FSSAI clean-label enforcement accelerate extraction capacity demand. Target nutraceutical functional positioning with adaptogenic claims, the fastest-expanding margin pool where FDA GRAS complexity disadvantages smaller competitors. Pursue direct-to-manufacturer channel partnerships bypassing traditional distributor networks to secure formulation collaboration contracts. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier European flavor houses possessing captive analytical laboratories and incomplete REACH registration portfolios given ECHA compliance consolidation pressure. Long-term viability favors suppliers with dual capabilities in agricultural extraction and biotechnology fermentation platforms. Monitor EFSA novel food authorization timelines as inflection indicators for first-mover botanical extract positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tropical Growing Regions | Madagascar vanilla and Indonesian clove sourcing agreements reduce weather-driven input cost volatility. |
| Precision Fermentation Capacity Expansion | Swiss biotechnology platforms replicate rare botanical molecules without agricultural yield constraints. |
| Supercritical CO2 Extraction Retrofitting | German and Swiss facilities automate heat-sensitive compound separation for EFSA organic compliance. |
| Direct-to-Manufacturer Channel Development | Technical partnerships with Indian and Mexican co-manufacturers displace distributor intermediation. |
| EFSA Novel Food Authorization Pursuit | First-mover botanical extract suppliers secure pre-market authorization for unconventional plant inputs. |
Methodological Framework
Document review covered FSSAI enforcement circulars, EFSA flavoring substance evaluations, and Indian PLI scheme implementation guidelines, complemented by interviews with extraction technology specialists, regulatory affairs directors at flavor houses, procurement leads at contract food manufacturers, and chromatography equipment suppliers. Secondary validation drew from customs trade data, REACH registration dossiers, and agricultural yield statistics from tropical growing regions. Bottom-up capacity assessments and top-down consumption estimates were triangulated to establish market sizing.
Historical volume trajectories were cross-referenced against panel input from industry stakeholders to construct projection models across the analysis window. Segmentation dimensions modeled include extraction method, regulatory classification tier, application end-use, and distribution channel structure. CAGRs were derived from slope analysis of normalized growth curves adjusted for PLI scheme incentive timing and EFSA novel food pathway progression rates. Forecast inputs incorporated biotechnology fermentation yield improvement assumptions and climate volatility indices for vanilla and citrus crops.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to El Niño frequency intensification and EU Green Deal Farm to Fork target acceleration. Forecasts reflect documented assumptions regarding REACH registration compliance timelines and FSSAI clean-label enforcement consistency. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Caralluma Extract Market
Flavorings and Food Additives
Original and Flavored Syrup Market
Flavorings and Food Additives
Asia-Pacific Vanilla Beans and Extract Market
Flavorings and Food Additives
Sour Cream Powder Market
Flavorings and Food Additives
Italy Food Colorants Market
Flavorings and Food Additives
North America Licorice Extract Market
Flavorings and Food Additives
South America Food Flavor Market
Flavorings and Food Additives
South America Flavors and Fragrances Market
Flavorings and Food Additives
Africa Food Colorants Market
Flavorings and Food Additives
Natural Flavors Market
Flavorings and Food Additives
Citrus Flavors Market
Flavorings and Food Additives
Fenchol Market
Flavorings and Food Additives
United States Food Colorants Market
Flavorings and Food Additives
Africa Food Flavor Market
Flavorings and Food Additives
Keto Friendly Flavors Market
Flavorings and Food Additives
Lemon Essential Oil Market