
 Global Artichoke Extract Market | 2026-2036
Global Artichoke Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Global Artichoke Extract Market Foresight
Buyer concentration among dietary supplement producers is shifting as mid-sized nutraceutical firms fragment procurement across specialized botanical suppliers. Jiaherb, Inc. leverages its vertical integration from raw material sourcing to standardized extraction, sustaining consistent cynarin content across batches. Anklam Extrakt GmbH anchors European supply with its German manufacturing base and REACH-compliant processes. Gaia Herbs, Inc. differentiates through certified organic cultivation and transparent supply chain documentation.
Artichoke extract comprises concentrated bioactive compounds—primarily cynarin, chlorogenic acid, and luteolin—derived from Cynara scolymus leaves through solvent or supercritical CO2 extraction, standardized typically to 2.5-5% cynarin for therapeutic applications. Powder formulations dominate pharmaceutical and nutraceutical bulk procurement due to stability and blending flexibility, while liquid concentrates lead growth in functional beverage applications where rapid dissolution matters. Capsule formats occupy the premium self-directed consumer channel, with margin pools concentrating among brands validating EFSA or FDA substantiation pathways.
EFSA's health claim evaluation framework and FDA's dietary supplement CGMPs enforce stringent identity testing and contaminant thresholds that reshape competitive access across European and North American markets. China's NMPA and GB standards for botanical extracts add a third compliance layer for suppliers targeting Asia-Pacific expansion. Stakeholders must monitor evolving monograph harmonization between pharmacopeias, as divergence in cynarin assay methods creates technical barriers that favor laboratories investing in dual-validation capabilities.
Market Dynamics
Artichoke extract procurement is fragmenting as mid-sized nutraceutical firms bypass traditional distributors to contract directly with specialized botanical extractors, compressing margin pools and forcing suppliers to demonstrate batch-level cynarin consistency and dual-pharmacopeia validation capabilities.
Growth Catalysts
- EFSA Health Claim Pathways:The EU's substantiation framework for botanical liver protection claims is creating tiered market access that rewards suppliers investing in clinical cynarin bioavailability studies.
- Functional Beverage Formulation:Ready-to-digest liquid concentrates are displacing powder in beverage applications where rapid dissolution and clean-label positioning command shelf space premiums.
- German Retail Pharmacy Channel:Artichoke extract's classification as a traditional herbal medicine under Germany's Medicines Act secures reimbursement-adjacent positioning unavailable to unstandardized botanicals.
Market Restraints
- Raw Material Volatility:Spanish and Italian artichoke leaf harvests fluctuate with Mediterranean drought cycles, concentrating supply risk in two growing regions.
- REACH Compliance Burden:ECHA's registration requirements for novel extraction solvents impose fixed compliance costs that disproportionately burden smaller extractors.
- Phytosterol Substitution:Fermented red yeast rice and bergamot extracts compete for cholesterol-management positioning with lower raw material cost structures.
Strategic Opportunities
- Chinese NMPA Botanical Registration:The 2020 Traditional Chinese Medicine Law creates a formal pathway for artichoke extract as a "new food raw material" in functional foods.
- Supercritical CO2 Convergence:Combining supercritical extraction with in-line HPLC standardization enables real-time cynarin adjustment for pharmaceutical-grade contracts.
- Direct-to-Practitioner Channels:Integrative medicine clinicians in Australia and Canada are building recurring artichoke extract protocols for non-alcoholic fatty liver management.
Industry Challenges
- Dual-Pharmacopeia Analytical Talent:Laboratories capable of simultaneous USP and EP cynarin assay validation command salary premiums that extractors struggle to absorb.
- Organic Certification Timelines:Three-year conversion periods for artichoke cultivation lock suppliers out of premium organic capsule segments during transition.
- Legacy ERP Integration:Batch-level traceability requirements for FDA dietary supplement CGMPs force mid-sized extractors to replace paper-based inventory systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Artichoke Extract Market |
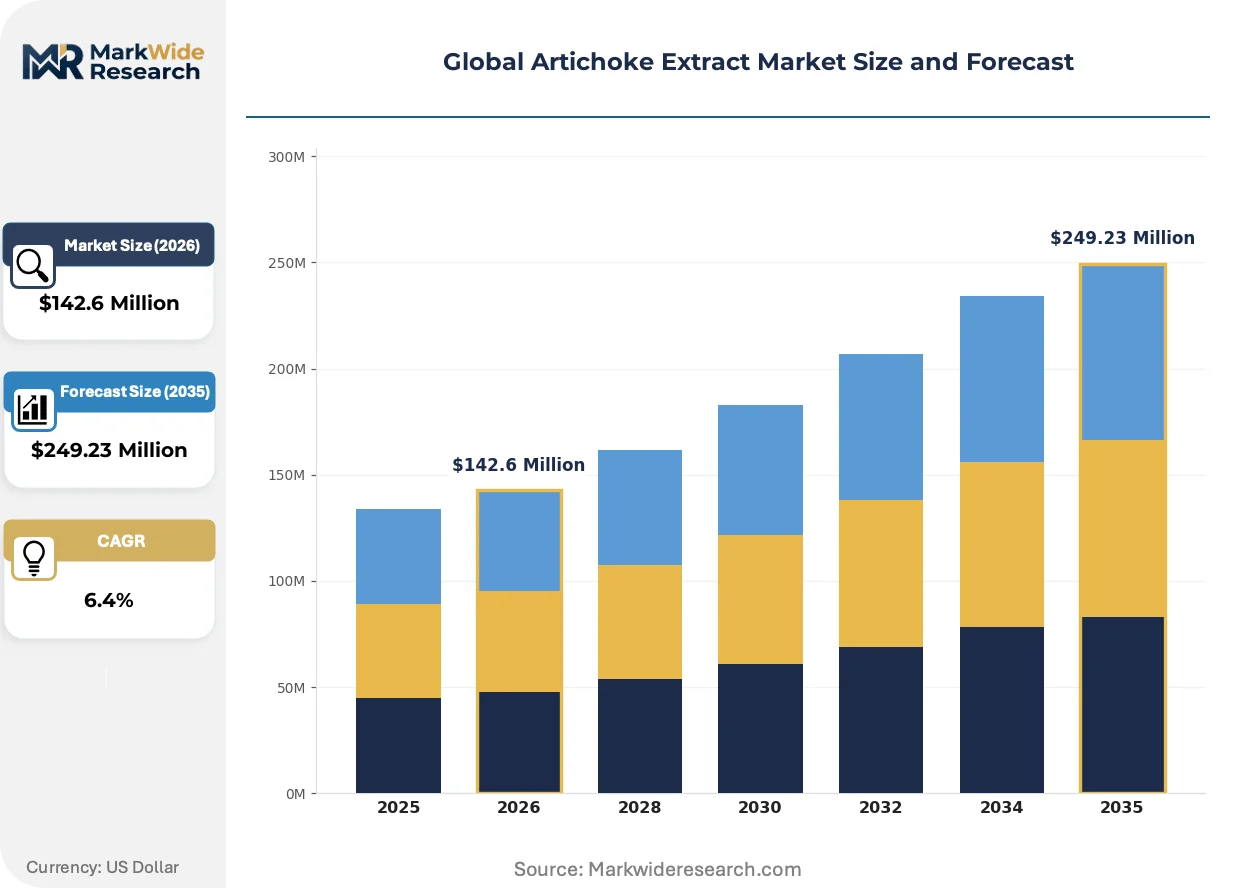
| Market Size in 2026 | $142.6 Million |
| Market Size in 2035 | $249.23 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Capsule, Tablet, Liquid Concentrate Application: Digestive Health, Liver Protection, Antioxidant Supplement, Cholesterol Management, Skin Care End User: Pharmaceutical Manufacturers, Nutraceutical Firms, Cosmetic Companies, Dietary Supplement Producers Distribution Channel: Online Retailers, Specialty Stores, Pharmacies, Health Food Outlets, Direct Sales |
| Companies Covered | Jiaherb, Inc., Nutra Green Biotechnology Co. Ltd., Hawaii Pharm LLC, Gaia Herbs, Inc., Nature’s Way Products, LLC, Anklam Extrakt GmbH, King Herbs Ltd., Agro T18 Italia S.r.l., Caprichos del Paladar S.L.U., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Artichoke Extract Market Shifts & Advancements
Extraction technology and regulatory substantiation are diverging in ways that favor suppliers capable of bridging pharmaceutical-grade validation with consumer-facing transparency, compressing the gap between bulk ingredient and finished brand value capture.
Supercritical CO2 extraction with integrated HPLC feedback loops is converging with pharmaceutical contract manufacturing requirements, enabling real-time cynarin standardization that meets USP monograph tolerances. European nutraceutical firms adopting these systems report 40% faster batch release times. The technology is converging with quality agreements that transfer analytical liability upstream to extractors, reshaping supplier-buyer risk allocation.
EFSA's 2023 updated guidance on botanical safety assessment is extending toxicological study requirements for novel extraction solvents beyond traditional ethanol and water processes. The regulation compresses innovation timelines for supercritical fluid and enzyme-assisted methods. German and Italian suppliers with existing Novel Food dossiers are accelerating dossier amendments to preempt competitor solvent switches.
Practitioner-directed dispensing is displacing retail shelf presence as the primary growth channel for high-cynarin formulations. Functional medicine clinics in the US and Australia are building recurring artichoke extract protocols into metabolic health programs, bypassing traditional supplement retail markups. This channel rotation is most visible in California and Victoria, where integrative medicine credentialing density supports direct clinical sourcing at pharmaceutical-grade specifications.
Global Artichoke Extract Market Segmentation
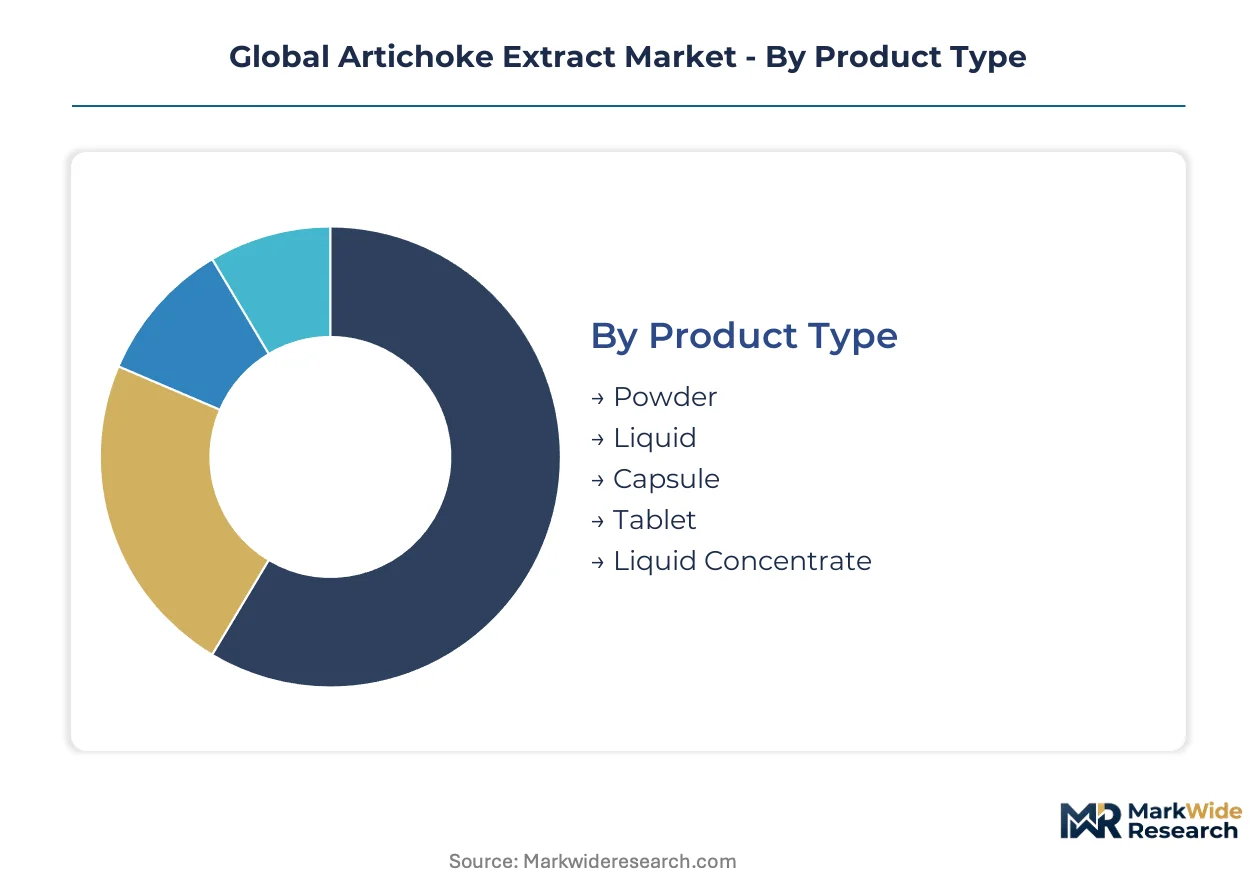
Segmentation in the artichoke extract market reveals how cynarin standardization levels and formulation formats align with distinct regulatory pathways and end-use economics. Buyers fragment procurement across pharmaceutical-grade, nutraceutical, and cosmetic specifications, each demanding different batch documentation and extraction solvent profiles.
Product Type:
Standardization intensity varies sharply across this category, from bulk powders with flexible cynarin ranges to pharmaceutical-grade concentrates with tight tolerances.
- Powder:Spray-dried or freeze-dried extracts standardized to 2.5-5% cynarin dominate pharmaceutical and nutraceutical bulk procurement. German manufacturers anchor demand for EP-compliant powder with full batch traceability documentation.
- Liquid:Hydroalcoholic tinctures and glycerites serve functional beverage formulators and practitioner-dispensing channels in Australia and Canada. Rapid dissolution properties command shelf space premiums in clean-label positioning.
- Capsule:Hard-shell gelatin and vegetable cellulose formats occupy premium self-directed consumer channels with margin pools concentrating among brands validating EFSA or FDA substantiation pathways.
- Tablet:Compressed formulations with binders and fillers target mass-market retail positioning where unit economics favor high-volume production runs.
- Liquid Concentrate:Supercritical CO2-derived concentrates with elevated bioactive density are displacing powder in beverage applications where rapid dissolution and minimal processing claims matter.
Leading the category by volume: Powder. Growing fastest: Liquid Concentrate.
Application:
Clinical substantiation depth separates segments, with liver protection commanding the most rigorous dossier requirements and skin care operating under lighter cosmetic regulatory burdens.
- Digestive Health:Cynarin's choleretic properties drive formulation into pre-meal supplements and functional bitters. Italian and Spanish heritage brands leverage regional cultivation familiarity to secure pharmacy shelf placement.
- Liver Protection:Hepatoprotective positioning requires EFSA health claim substantiation or German Medicines Act traditional use registration. Clinical cynarin bioavailability studies differentiate suppliers accessing this high-margin segment.
- Antioxidant Supplement:Chlorogenic acid and luteolin content supports broad wellness positioning with lower regulatory barriers than structure-function disease claims.
- Cholesterol Management:Competes directly with red yeast rice and bergamot extracts in metabolic health protocols, with artichoke extract's natural positioning appealing to clean-label formulators.
- Skin Care:Topical antioxidant and anti-inflammatory applications in premium cosmetic lines, particularly from French and Korean formulators seeking botanical differentiation.
Most substantiation-intensive: Liver Protection. Expanding most quickly: Cholesterol Management.
End User:
Procurement sophistication scales with regulatory exposure, from pharmaceutical manufacturers demanding USP monograph compliance to cosmetic companies prioritizing sensory and stability specifications.
- Pharmaceutical Manufacturers:Require dual-pharmacopeia validation, full impurity profiling, and quality agreements transferring analytical liability upstream. German and Swiss contract manufacturers set the specification benchmark.
- Nutraceutical Firms:Mid-sized players fragment procurement across specialized botanical suppliers, compressing margin pools and forcing batch-level cynarin consistency demonstrations.
- Cosmetic Companies:Prioritize color stability, odor masking, and INCI nomenclature compliance over standardized bioactive content. Korean and French formulators lead botanical integration.
- Dietary Supplement Producers:Range from premium brands investing in EFSA dossiers to private-label assemblers sourcing generic powder. FDA dietary supplement CGMP compliance separates tiers.
Highest specification bar: Pharmaceutical Manufacturers. Procurement fragmentation accelerating fastest: Nutraceutical Firms.
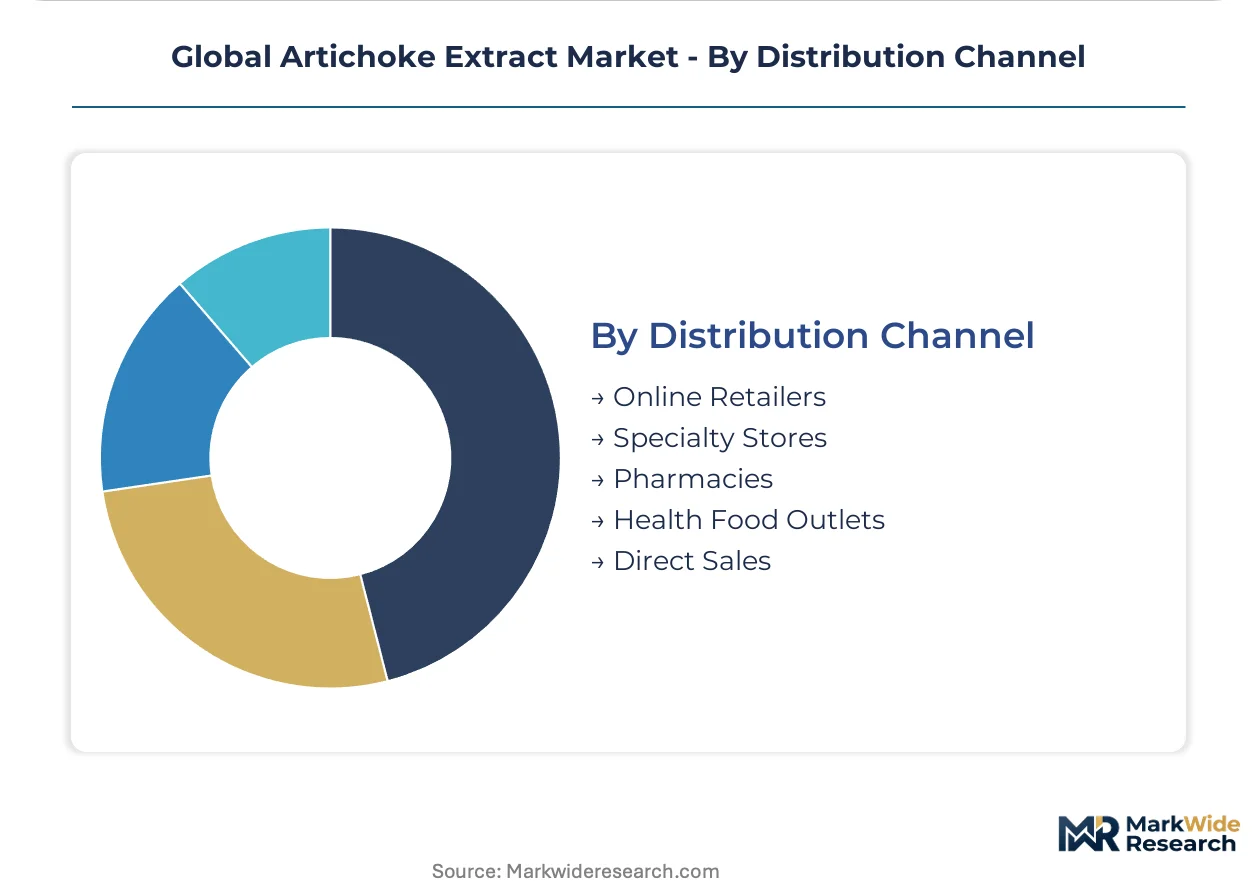
Distribution Channel:
Channel selection determines margin capture and regulatory touchpoints, from direct sales with practitioner credentialing requirements to online retail with minimal barriers.
- Online Retailers:Amazon and specialized botanical platforms dominate self-directed consumer access, with review velocity and subscription models driving replenishment economics.
- Specialty Stores:Independent health food retailers in Germany and California curate premium capsule and tincture assortments with staff training on cynarin mechanisms.
- Pharmacies:German and Italian pharmacy chains stock artichoke extract as traditional herbal medicines with reimbursement-adjacent positioning unavailable to unstandardized botanicals.
- Health Food Outlets:Natural grocery chains in North America and Australasia emphasize certified organic and transparent supply chain documentation.
- Direct Sales:Practitioner-dispensing through integrative medicine clinics in Australia, Canada, and California bypasses retail markups with recurring protocol-based purchasing.
Deepest regulatory integration: Pharmacies. Steepest expansion trajectory: Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement from German nutraceutical firms and Italian pharmaceutical manufacturers concentrates demand in Western Europe, while Chinese NMPA registration pathways and Australian practitioner networks expand the addressable market across Asia-Pacific.
Germany
Traditional herbal medicine classification under the Medicines Act secures pharmacy reimbursement positioning for cynarin-standardized extracts. EFSA health claim substantiation requirements filter out unvalidated suppliers from liver protection segments. Bavarian contract manufacturers anchor pharmaceutical-grade production with dual-pharmacopeia validation capabilities.
Italy
Regional artichoke cultivation heritage in Apulia and Sicily supports integrated supply chains from leaf harvest to extraction. ANSM notification requirements for novel food ingredients shape import documentation for non-EU suppliers. Turin and Milan host formulation specialists serving Mediterranean cosmetic and nutraceutical brands.
China
NMPA's 2020 Traditional Chinese Medicine Law creates formal registration pathways for artichoke extract as new food raw materials. GB standards for botanical extracts impose heavy metal and pesticide residue thresholds on imported powders. Zhengzhou and Xi'an extraction clusters serve domestic functional food manufacturers.
United States
FDA dietary supplement CGMP enforcement drives batch-level traceability investments among contract manufacturers. California integrative medicine clinics build recurring artichoke extract protocols for metabolic health programs. Utah and North Carolina house capsule and tablet specialists supplying direct-to-consumer brands.
Australia
TGA complementary medicine regulations require listed medicine approval for liver protection claims, elevating documentation burdens above cosmetic-grade imports. Practitioner-dispensing channels in Victoria and New South Wales bypass retail markups with pharmaceutical-grade specifications. Sydney formulation labs serve Australasian functional beverage developers.
Global Artichoke Extract Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue supercritical CO2 extraction and direct-to-practitioner distribution to bypass saturated retail channels. The supplier base fragments across three archetypes: vertically integrated botanical specialists with captive cultivation, toll extraction houses serving branded finished goods companies, and regional traders aggregating spot-market powder. Competitive positioning hinges on dual-pharmacopeia analytical capabilities and EFSA dossier completion status. Capacity expansion and quality agreement restructuring represent the dominant competitive moves.
Within the integrated cultivation tier, Jiaherb, Inc. and Nutra Green Biotechnology Co. Ltd. exemplify Chinese suppliers with backward control over raw material sourcing. Anklam Extrakt GmbH anchors European pharmaceutical-grade positioning through its German manufacturing base and REACH-compliant processes. These three occupy distinct geographic and regulatory spheres, with the Chinese pair serving Asia-Pacific functional food expansion and the German specialist capturing EU pharmacy channel requirements.
| Leading Market Players |
|---|
| Jiaherb, Inc. |
| Nutra Green Biotechnology Co. Ltd. |
| Hawaii Pharm LLC |
| Gaia Herbs, Inc. |
| Nature's Way Products, LLC |
| Anklam Extrakt GmbH |
| King Herbs Ltd. |
| Agro T18 Italia S.r.l. |
| Caprichos del Paladar S.L.U. |
| Others |
Supply & Pricing Matrix
Pharmaceutical-grade certification divergence from commodity powder tiers manifests in both cynarin assay premiums and captive cultivation investments, with EFSA dossier completion status separating suppliers who command quality-agreement pricing from spot-market traders absorbing Mediterranean harvest volatility.
Pricing Analysis
High-volume powder contracts trade at compressed margins while pharmaceutical-grade concentrates with dual-pharmacopeia validation capture premium positioning. Price differentiation hinges on batch-level cynarin consistency and REACH registration status. Cost compression in standard-grade powder is intensifying because mid-sized nutraceutical firms fragment procurement across specialized botanical suppliers. Private-label assemblers exhibit highest price sensitivity; German contract manufacturers with Medicines Act registration demonstrate lowest.
Supply Chain Analysis
Freight cost exposure from Mediterranean leaf harvests to extraction facilities in Germany and China elevates landed cost volatility for non-integrated suppliers. Raw material sourcing draws from Spanish and Italian artichoke cultivation regions, with Zhengzhou and Xi'an clusters serving Asia-Pacific functional food manufacturers. Supply chain risk centers on single-source vulnerability in Mediterranean growing regions exposed to drought cycles. Distribution runs through direct-contract channels for pharmaceutical manufacturers and specialized botanical platforms for self-directed consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EFSA health claim substantiation requirements function as a cost-of-compliance moat, filtering out undercapitalized suppliers from liver protection segments and concentrating margin pools among dossier-complete incumbents.
For Market Incumbents: Lock in dual-pharmacopeia analytical capabilities before salary premiums for qualified laboratory talent escalate further. Secure long-term leaf supply agreements with Apulian and Sicilian cultivation cooperatives to hedge drought-cycle exposure. Supercritical CO2 extraction with in-line HPLC standardization represents the priority capability investment to defend against toll-extraction competitors. For New Entrants and Emerging Players: Begin with direct-to-practitioner channels in Victoria and California where integrative medicine credentialing density supports pharmaceutical-grade sourcing bypassing retail markups. The Chinese NMPA botanical registration pathway offers the most penetrable regulatory entry point for functional food positioning. A go-to-market angle emphasizing real-time cynarin standardization documentation differentiates against legacy powder traders. For Investors and Strategic Acquirers: Re-rating potential sits with supercritical CO2-equipped extractors given EFSA's 2023 solvent safety assessment tightening competitive timelines for novel extraction methods. Long-term viability favors suppliers with backward integration into captive cultivation and completed Novel Food dossiers. The signal to watch is NMPA registration approval velocity for artichoke extract as new food raw material.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Pharmacopeia Validation Investment | Laboratories with simultaneous USP and EP cynarin capabilities command quality-agreement pricing from German pharmaceutical contract manufacturers. |
| Supercritical CO2 Extraction Scale-Up | Real-time HPLC feedback loops enable pharmaceutical-grade batch release times 40% faster than conventional solvent methods. |
| NMPA Botanical Registration | First-mover status under China's 2020 Traditional Chinese Medicine Law secures functional food channel access ahead of competitor dossiers. |
| Direct-to-Practitioner Channel Buildout | Integrative medicine clinic networks in California and Victoria bypass retail markups with recurring protocol-based purchasing. |
| Captive Cultivation Integration | Three-year organic certification timelines lock in premium capsule segment supply before competitor conversion periods complete. |
Research Methodology
Multi-period observation of cynarin standardization trends and EFSA dossier submission patterns anchored the trend analysis, supplemented by interviews with extraction facility technical directors, nutraceutical procurement managers, German pharmacy chain category buyers, and regulatory affairs specialists at botanical suppliers. Secondary validation drew from EFSA guidance documents, NMPA registration filings, USP and EP monograph updates, and customs trade data for artichoke leaf and extract flows. Bottom-up volume modeling across formulation formats and applications triangulated against top-down market sizing from identified supplier capacities.
Segment-weighting approaches applied differential growth assumptions across pharmaceutical-grade, nutraceutical, and cosmetic specification tiers, with extraction solvent profiles and regulatory pathway timelines as cross-cutting dimensions. CAGRs were derived from fitted growth curves across the projection horizon, incorporating EFSA health claim evaluation velocity and NMPA registration throughput as industry-specific forecast inputs.
Underlying measurement precision varies by segment; pharmaceutical-grade concentrates with quality agreement documentation carry tighter precision than spot-market powder trading. Forecasts reflect assumptions about regulatory timeline continuity and Mediterranean climate patterns. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
North America Food Flavor Market
Flavorings and Food Additives
Dry Powder Flavors Market
Flavorings and Food Additives
Anthocyanin Food Colors Market
Flavorings and Food Additives
Flavor Ingredients Market
Flavorings and Food Additives
Synthetic Food Colors Market
Flavorings and Food Additives
Citrus Aromatic Fractions for Mood Support Market
Flavorings and Food Additives
Sour Flavor Ingredient Market
Flavorings and Food Additives
Neotame Market
Flavorings and Food Additives
Global Bitterness Suppressors and Flavor Carriers Market
Flavorings and Food Additives
Fractionated Lecithin Market
Flavorings and Food Additives
Australia Vanilla Flavor Market
Flavorings and Food Additives
Farnesol Market
Flavorings and Food Additives
Food Texturizers Market
Flavorings and Food Additives
Feed Flavors and Sweeteners Market
Flavorings and Food Additives
Chicory Extract Market
Flavorings and Food Additives
Flavor Compounds Market