
 Flavored Butter and Oils Market | 2026-2036
Flavored Butter and Oils Market Size, Share, and Industry Trends Forecast 2026-2036
Flavored Butter and Oils Market Foresight
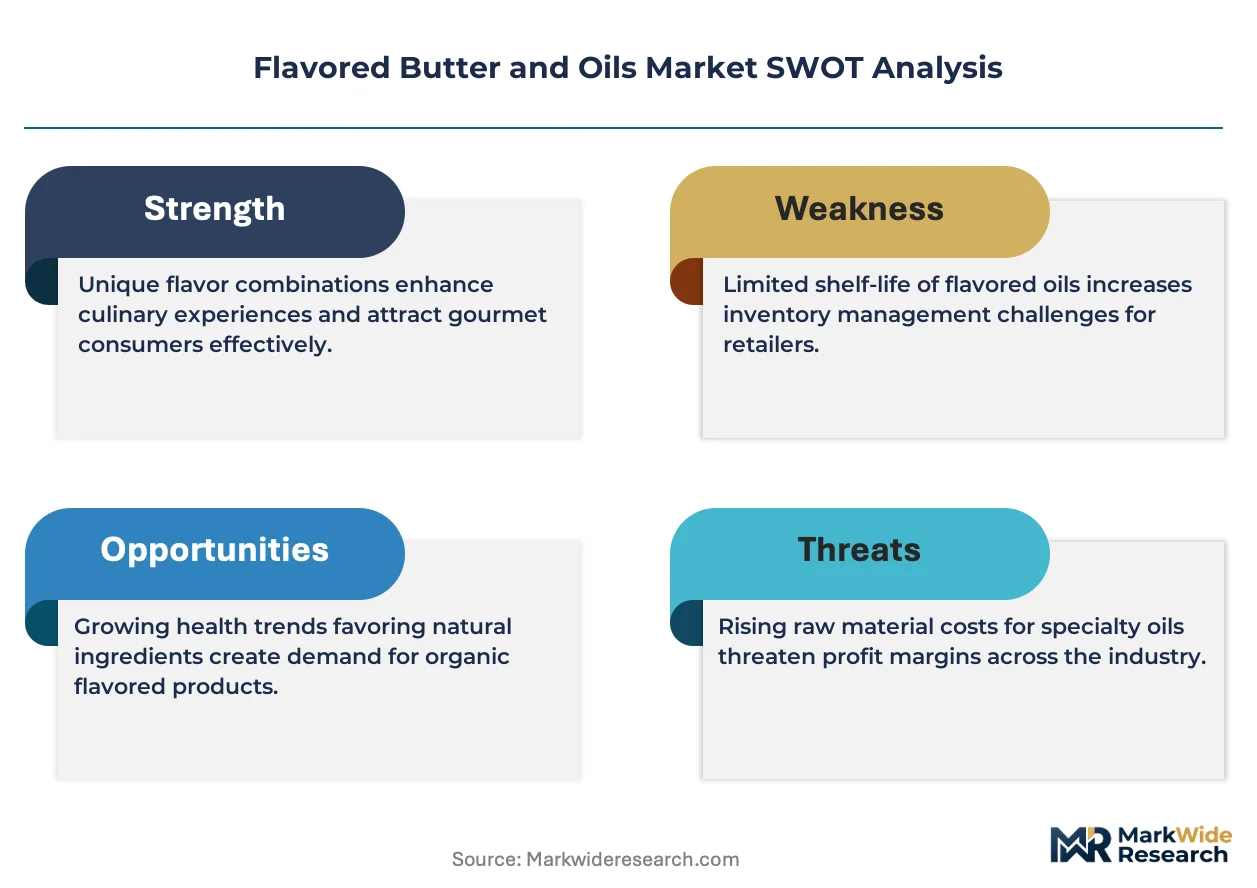
Gourmet retailers and specialty stores are redrawing procurement patterns for premium dairy and oil blends, shifting volume away from conventional foodservice contracts. Kerry Group leverages its flavor science infrastructure to supply customized compound butter bases across European gastronomy channels. Land O' Lakes anchors its position through backward integration into Midwest dairy cooperatives, securing consistent cream supply for seasonal flavor programs. Miyoko's Creamery differentiates through plant-fat fermentation technology that replicates cultured butter mouthfeel without dairy inputs.
Flavored butter and oils denote lipid-based products infused with herbs, spices, citrus extracts, or fungal derivatives through cold-compounding, enzymatic modification, or controlled oxidation processes, yielding specified flavor intensity measured in parts-per-million volatile compounds; these formulations serve as finished condiments or intermediate ingredients that reduce kitchen labor while standardizing taste profiles across commercial food production. Garlic butter and truffle oil command premium shelf positioning in gourmet retail due to concentrated umami chemistry and limited raw material sourcing. The savory flavor profile leads volume in foodservice applications, while chili butter represents the fastest-expanding segment driven by heat-seeking consumer preferences in North American and Southeast Asian markets.
The FDA's Food Safety Modernization Act mandates hazard analysis for flavored oil bottling operations, while EFSA enforces maximum residue limits for botanical extracts in dairy fat matrices under EU regulation. BIS certification requirements for India-bound imports are forcing exporters to reformulate with regionally approved colorants and preservatives. Stakeholders must monitor evolving front-of-pack labeling mandates across multiple jurisdictions to anticipate reformulation costs and shelf-space reallocation.
Market Dynamics
EU F-Gas Regulation and REACH compliance are compressing formulation flexibility for dairy-fat matrices, forcing manufacturers to rebuild supply chains around clean-label botanical sourcing and cold-compounding infrastructure.
Growth Catalysts
- Foodservice menu expansion:Commercial kitchens across France, Italy, and Spain are standardizing compound butter bases to reduce labor costs and ensure flavor consistency across locations.
- REACH chemical safety mandates:ECHA enforcement of stricter substance restrictions is accelerating reformulation toward natural extract alternatives in premium retail positioning.
- Chili butter heat-seeking demand:North American and Southeast Asian consumers are pulling volume toward spicy flavor profiles, creating new SKU opportunities for regional processors.
Market Restraints
- Truffle oil raw material concentration:Limited fungal harvesting zones in Piedmont and Perigord create supply bottlenecks that elevate input costs unpredictably.
- Cream supply cooperative dependency:Midwest dairy collective structures constrain independent processors from securing consistent fat volumes for seasonal flavor programs.
- Cold-compounding equipment capex:Precision temperature control systems for enzymatic modification require capital outlays that exclude smaller regional entrants.
Strategic Opportunities
- Plant-fat fermentation white space:Cultured butter mouthfeel replication without dairy inputs opens premium positioning for allergen-sensitive and vegan-adjacent consumer segments.
- India BIS certification pathway:Reformulation expertise developed for Indian import compliance creates transferable capabilities for other emerging market entry protocols.
- Gourmet retail channel disintermediation:Direct-to-chef subscription models for compound butter bases bypass traditional foodservice distributor markups.
Industry Challenges
- Flavor chemist talent scarcity:Specialized expertise in volatile compound measurement and parts-per-million standardization remains concentrated among a limited pool of trained professionals.
- Multi-jurisdiction labeling synchronization:Front-of-pack mandate variations across FDA, EFSA, and BIS jurisdictions force parallel packaging runs and inventory segmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flavored Butter and Oils Market |
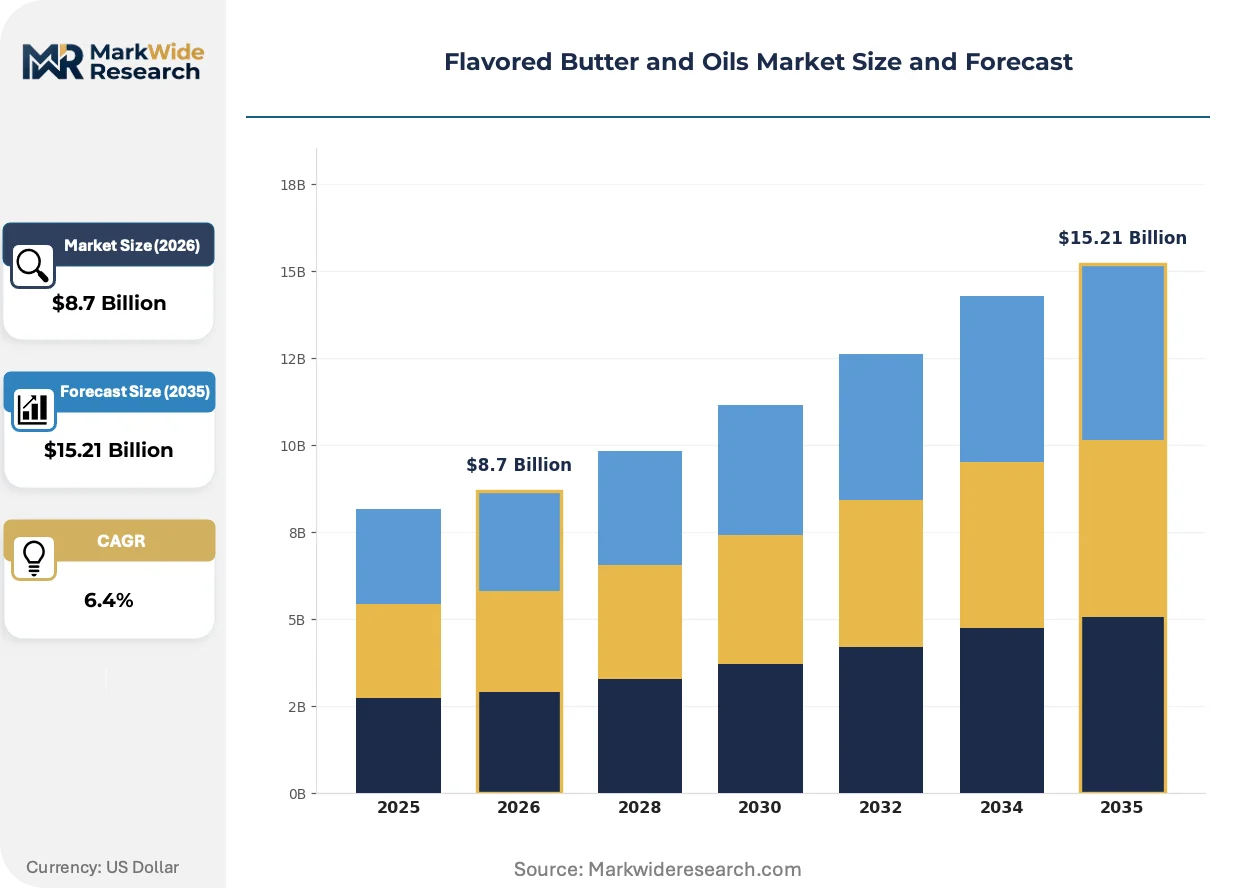
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Garlic Butter, Herb-Infused Oil, Chili Butter, Truffle Oil, Lemon Butter Flavor Profile: Spicy, Savory, Citrus, Earthy, Smoky Application: Baking, Cooking, Salad Dressing, Marinades, Spreads End User: Foodservice Providers, Gourmet Retailers, Catering Companies, Specialty Stores |
| Companies Covered | Unilever, Kerry Group, Kerrygold, Dairy Farmers of America, Cargill, Land O' Lakes, Arla Foods amba, Miyoko's Creamery, Lurpak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flavored Butter and Oils Market Shifts & Advancements
Cold-compounding and enzymatic modification techniques are redrawing competitive boundaries between artisan producers and scaled manufacturers, while regulatory chemistry constraints and procurement model evolution reshape how value flows through the channel.
Controlled oxidation processes for infused oil production are displacing traditional heat-extraction methods in premium positioning. Specialty stores and gourmet retailers are adopting these systems to preserve volatile aromatic compounds and extend shelf stability. The technology is displacing conventional bottling operations that rely on thermal pasteurization, compressing margins for processors without cold-chain infrastructure.
EFSA maximum residue limits for botanical extracts in dairy fat matrices are tightening enforcement protocols across EU member states. Manufacturers must now document extraction solvent provenance and concentration thresholds prior to market placement. French and Italian compound butter specialists are responding by vertically integrating into herb cultivation partnerships to secure audit trails.
Chef-direct procurement is fragmenting traditional foodservice distributor relationships as culinary professionals seek customized flavor intensity specifications. Independent restaurants and boutique hotel chains are building direct supplier relationships that bypass broadline distribution. This pattern concentrates in the European gastronomy cluster where kitchen labor reduction priorities intersect with premium positioning requirements.
Flavored Butter and Oils Market Segmentation
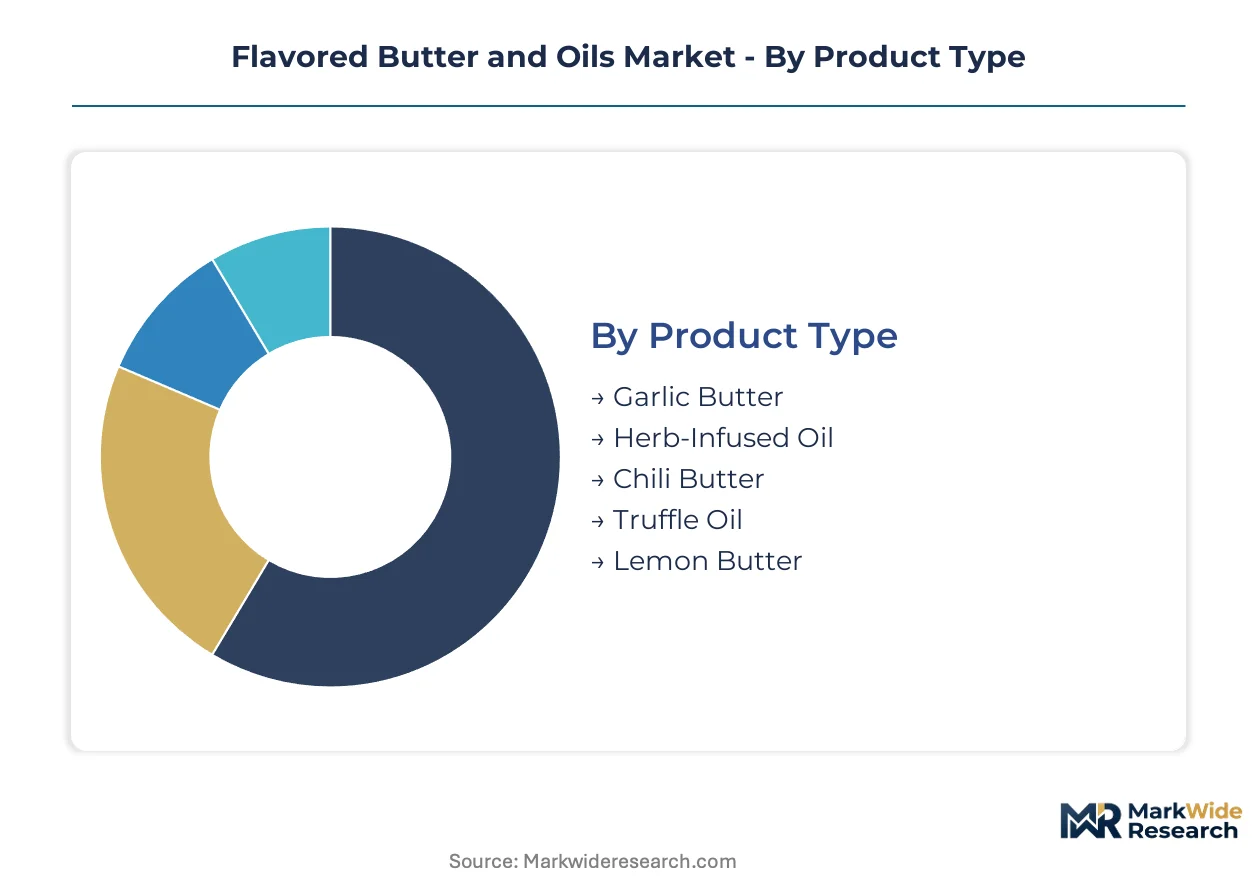
Segmentation in flavored butter and oils reveals how procurement power concentrates across distinct channel tiers and how regulatory chemistry constraints reshape viable product formulations. Manufacturers must align production infrastructure with the specific temperature control and labeling requirements of each segment.
Product Type:
Garlic butter and chili butter face the strongest substitution pressure from plant-fat fermentation alternatives, while truffle oil's concentrated umami chemistry creates natural insulation against direct replacement.
- Garlic Butter:Cold-compounded dairy-fat matrix with allicin-stabilized garlic extract, typically specified at 2-4% volatile compound concentration. Demand concentrates in French and Italian foodservice channels where kitchen labor reduction drives standardization across multi-location operators.
- Chili Butter:Capsaicin-infused compound butter produced through controlled enzymatic modification to preserve heat intensity. North American and Southeast Asian markets pull volume toward this profile as heat-seeking consumer preferences intensify.
- Herb-Infused Oil:Lipid carrier systems with cold-extracted botanical volatiles.
- Truffle Oil:Limited Piedmont and Perigord fungal sourcing constrains supply elasticity.
- Lemon Butter:Citrus terpene formulations requiring precise oxidation control.
Garlic butter retains volume leadership; chili butter holds the steepest expansion curve.
Flavor Profile:
Cost tier stratification separates premium positioning (earthy, smoky) from high-rotation foodservice staples (savory, spicy).
- Savory:Umami-dominant formulations leveraging glutamate-rich fungal or fermented bases. Foodservice applications across France, Italy, and Spain standardize this profile for cross-menu deployment.
- Spicy:Capsaicin and piperine-based heat delivery systems. North American gourmet retailers and Southeast Asian commercial kitchens drive specification intensity toward higher Scoville-equivalent ratings.
- Citrus:Terpene-forward profiles requiring cold-chain stability.
- Earthy:Truffle and porcini-derived compounds commanding premium shelf positioning.
- Smoky:Liquid smoke and charred wood extract formulations.
Savory commands the broadest channel penetration; spicy climbs the fastest on heat-seeking demand.
Application:
Volume concentrates in cooking applications where compound butters reduce mise en place labor, while marinades and spreads carry stricter front-of-pack labeling exposure.
- Cooking:High-heat stable formulations with smoke point optimization above 180°C. French and Italian foodservice providers specify these bases for sauce finishing and protein basting.
- Baking:Cream-to-fat ratio adjustments for lamination and crumb structure. European pastry chains and boutique hotel kitchens drive consistency requirements.
- Salad Dressing:Emulsion-stable infused oils with acidity tolerance.
- Marinades:Penetration-optimized viscosity and flavor carry systems.
- Spreads:Room-temperature stability with spreadability engineering.
Cooking anchors procurement volume; baking gains share fastest on pastry chain expansion.
End User:
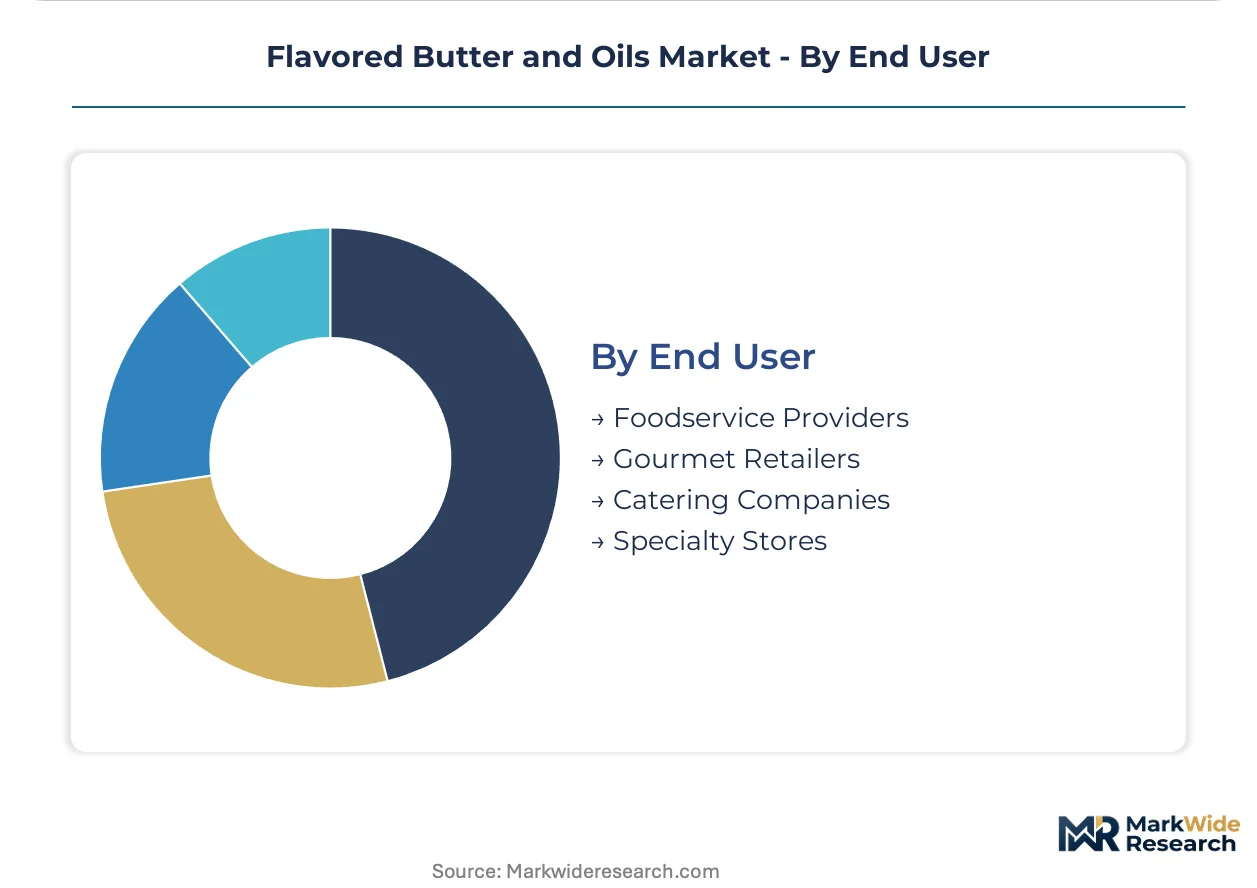
Customer type determines margin structure and regulatory compliance burden, with gourmet retailers demanding the most extensive extraction provenance documentation.
- Foodservice Providers:Multi-location operators in France, Italy, and Spain purchasing compound butter bases under annual contracts with flavor intensity specifications measured in parts-per-million volatile compounds. EU F-Gas and REACH compliance requirements elevate supplier qualification thresholds.
- Gourmet Retailers:Specialty stores and premium grocers in the European gastronomy cluster sourcing small-batch infused oils with documented botanical extraction solvent provenance. EFSA maximum residue limits force parallel inventory segmentation.
- Catering Companies:Event-scale volume with seasonal demand spikes.
- Specialty Stores:Curated assortments with direct-producer relationships.
Foodservice providers retain volume leadership; gourmet retailers hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain infrastructure underwrites the Netherlands' distribution dominance for European compound butter and infused oil transit. France's TGV rail network connects Perigord truffle harvesting zones to Parisian gastronomy channels within hours. Italy's Brenner Pass corridor funnels Alpine dairy fat southward toward Emilia-Romagna processing clusters.
France
Piedmont truffle oil demand concentrates among Parisian fine-dining establishments seeking documented fungal provenance. EFSA maximum residue limits for botanical extracts force reformulation of herb-infused compound butters before retail placement. The Lyon gastronomy cluster anchors procurement volume for savory-profile cooking bases used across Rhône-Alpes restaurant groups.
Italy
Emilia-Romagna's pasta manufacturing belt pulls standardized garlic butter volumes for sauce finishing applications. REACH compliance documentation requirements elevate supplier qualification thresholds for imported dairy fat matrices. Turin-based specialty stores cultivate direct relationships with Perigord harvesters to secure limited fungal supply for premium positioning.
Spain
Andalusian olive oil processors are diversifying into citrus-terpene infused lipid carriers for export markets. BIS certification requirements for India-bound shipments force parallel formulation runs with regionally approved preservatives. Barcelona's chef-direct procurement networks bypass traditional foodservice distributors for customized compound butter specifications.
United States
Midwest dairy cooperative structures constrain independent processors from securing consistent cream volumes for seasonal chili butter programs. FDA Food Safety Modernization Act hazard analysis mandates reshape bottling operations for infused oil producers. Chicago's broadline distribution hub remains the primary channel for foodservice compound butter procurement despite chef-direct fragmentation.
India
Maharashtra's urban foodservice sector generates specification pull for heat-stable cooking bases compatible with high-temperature applications. FSSAI labeling mandates for front-of-pack disclosure create compliance costs that favor larger processors with parallel packaging capabilities. Mumbai's gourmet retail channels are emerging as import entry points for European compound butter specialists seeking BIS certification pathway validation.
Flavored Butter and Oils Market Competitive Landscape
Listed leaders compete with private specialists across formulation technology and procurement scale. The vendor base concentrates around dairy cooperative structures in North America and flavor science infrastructure in Europe. Three archetypes dominate: multinational ingredient platforms with backward integration into dairy supply, artisan specialists with vertical control over botanical sourcing, and plant-fat fermentation innovators replicating cultured butter mouthfeel. Competitive moves center on chef-direct subscription bypass of traditional distribution and cold-compounding equipment deployment for volatile compound preservation.
Within the dairy cooperative archetype, Land O'Lakes anchors Midwest cream supply security for seasonal flavor programs. Kerry Group exemplifies the flavor science platform model with European gastronomy channel penetration. Miyoko's Creamery occupies the plant-fat fermentation tier, replicating cultured butter characteristics without dairy inputs for allergen-sensitive positioning.
| Leading Market Players |
|---|
| Unilever |
| Kerry Group |
| Kerrygold |
| Dairy Farmers of America |
| Cargill |
| Land O' Lakes |
| Arla Foods amba |
| Miyoko's Creamery |
| Lurpak |
| Others |
Supply & Pricing Matrix
Annual offtake contracts with French and Italian foodservice conglomerates lock in cream supply visibility and buffer against Piedmont truffle price volatility. These agreements tether compound butter pricing to Midwest dairy cooperative output schedules while exposing buyers to REACH compliance cost pass-throughs.
Pricing Analysis
Volume-discount tiering separates gourmet retailers procuring sub-tonnage artisan batches from multi-location foodservice operators commanding pallet-scale pricing. Three-tier pricing structure across premium, standard, and economy levels reflects botanical extraction method and EFSA documentation depth. Pricing pressure stems from cold-compounding equipment capex recovery demands among mid-tier processors. Foodservice providers exhibit highest price sensitivity due to contract-renewal timing, while specialty stores absorb premiums for provenance-verified truffle oil.
Supply Chain Analysis
Container availability constraints on Rotterdam-Genoa lanes elevate inbound logistics costs for Alpine dairy fat shipments. Supply concentrates in France, Italy, and Spain for processing infrastructure, with Piedmont and Perigord anchoring fungal raw material sourcing. Raw material dependencies include Midwest cream, Mediterranean olive oil, and limited-harvest black truffles. Single-source vulnerability runs through Perigord harvester networks. Distribution runs through chef-direct subscription channels fragmenting traditional broadline distributor dominance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chef-direct procurement platforms are reconstituting this market as a two-sided network, with flavor specification interoperability between restaurant ERP systems and supplier batch-tracking databases as the critical ecosystem enabler.
For Market Incumbents: Fortify backward integration into herb cultivation partnerships to secure EFSA audit trails against emerging clean-label specialists. Deepen capacity reservation agreements with Midwest dairy cooperatives ahead of seasonal chili butter demand spikes. Lock in cold-chain infrastructure at Port of Rotterdam to defend against logistics chokepoint vulnerability. For New Entrants and Emerging Players: Direct-to-chef subscription gaps in Barcelona and Turin boutique hotel chains offer white-space penetration before incumbent platform consolidation. Target plant-fat fermentation positioning for allergen-sensitive segments where dairy incumbents face formulation constraints. Lead with customized parts-per-million volatile compound specifications as the go-to-market wedge. For Investors and Strategic Acquirers: Capital is best deployed toward flavor science platforms with REACH-compliant extraction infrastructure and existing European gastronomy channel penetration. Long-term viability hinges on regulatory chemistry capabilities expanding across multiple jurisdiction labeling mandates. Watch for chef-direct procurement volume thresholds crossing critical mass as the inflection signal for platform economics tipping.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Compounding Equipment Deployment | Precision temperature control preserves volatile aromatic compounds for premium positioning against heat-extraction rivals. |
| Herb Cultivation Partnership Integration | Vertical control over botanical sourcing secures EFSA audit trails and reduces solvent-provenance documentation costs. |
| Chef-Direct Subscription Platform Launch | Bypassing broadline distributor markups captures margin from fragmented independent restaurant procurement networks. |
| Plant-Fat Fermentation Scale-Up | Cultured butter mouthfeel replication opens premium SKU opportunities in allergen-sensitive and vegan-adjacent segments. |
| BIS Certification Pathway Development | Reformulation expertise for Indian import compliance creates transferable capabilities for other emerging market entry protocols. |
Research Methodology
Desk research of EU regulatory filings, EFSA guidance documents, and foodservice procurement databases preceded structured interviews with flavor chemists, compound butter production managers, gourmet retail category buyers, and chef procurement officers. Primary fieldwork with French and Italian foodservice operators validated secondary trade flow data. Bottom-up volume modeling triangulated against top-down expenditure estimates from hospitality sector reports.
Variance decomposition across flavor profile, application, and end-user segments anchored the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation with macroeconomic foodservice expenditure trends. Modeled inputs included cold-compounding equipment deployment rates, REACH enforcement intensity trajectories, and chef-direct procurement adoption curves.
Underlying assumptions cover sustained EU F-Gas Regulation enforcement, stable Midwest dairy cooperative output, and continued heat-seeking preference expansion in North American markets, with deviation risk concentrated in truffle harvest yield volatility and BIS certification timeline delays. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Beverage Flavoring Agent Market
Flavorings and Food Additives
France Food Flavor and Enhancer Market
Flavorings and Food Additives
Russia Food Flavor and Enhancer Market
Flavorings and Food Additives
Tangerine Extract Market
Flavorings and Food Additives
Oryzanol Market
Flavorings and Food Additives
Feed Flavors and Sweeteners Market
Flavorings and Food Additives
Brazil Food Flavor and Enhancer Market
Flavorings and Food Additives
Smoked Dextrose Market
Flavorings and Food Additives
Chocolate Flavoring Compounds Market
Flavorings and Food Additives
Tangerine Essential Oil Market
Flavorings and Food Additives
North America Food Colorants Market
Flavorings and Food Additives
South America Food Flavor Market
Flavorings and Food Additives
Asia-Pacific Vanilla Beans and Extract Market
Flavorings and Food Additives
Orange Extract Market
Flavorings and Food Additives
Menthol Market
Flavorings and Food Additives
Mint Essential Oils Market