
 Sweet Modulator Market | 2026-2036
Sweet Modulator Market Size, Share, and Industry Trends Forecast 2026-2036
Sweet Modulator Market Insights
Flavor chemist talent scarcity is bifurcating the competitive landscape into R&D-intensive specialists and commodity-scale suppliers. Givaudan leverages its Swiss research heritage to sustain premium positioning in natural modulation systems. Tate & Lyle anchors European beverage reformulation demand through deep stevia optimization expertise. Kerry Group competes on integrated taste-nutrition platforms that span multiple application categories.
Sweet modulators are functional ingredients that enhance, suppress, or modify sweetness perception through receptor-level interactions, typically formulated at parts-per-million concentrations in finished goods. These compounds enable sugar reduction while preserving temporal flavor profiles critical to consumer acceptance. Natural sweeteners now command the fastest-expanding margin pool as clean-label mandates reshape procurement priorities across beverage and dairy applications. Powdered formats retain structural dominance in baked goods and snacks where processing thermal stability determines formulation viability.
FDA GRAS self-determination frameworks govern US market entry, while EFSA novel food assessments create stricter European access conditions for emerging modulation technologies. BIS standards in India and China's SAMR registration requirements add further compliance layers for multinational suppliers. Stakeholders must monitor evolving receptor science breakthroughs and jurisdiction-specific approval timelines to secure first-mover positioning in next-generation modulation platforms.
Market Dynamics
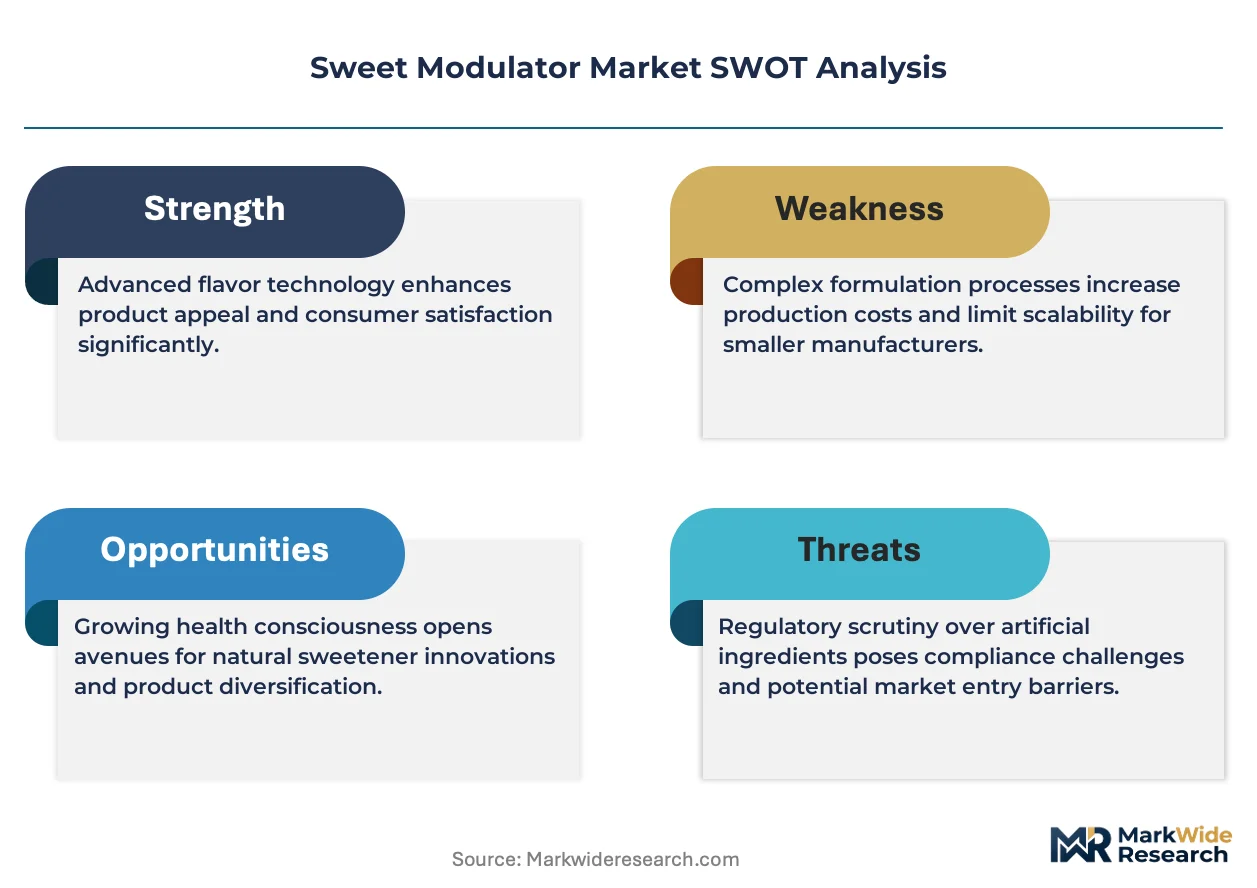
Beverage reformulation mandates are compressing development cycles as CPG manufacturers race to meet sugar-reduction targets ahead of regulatory deadlines. The F-Gas Regulation is simultaneously forcing equipment retrofits that alter thermal processing parameters for modulator stability.
Growth Catalysts
- EFSA novel food pathways:Accelerated approval frameworks for fermentation-derived sweeteners are unlocking European commercialization timelines for bio-manufactured modulation compounds.
- Stevia glycoside optimization:Enzymatic bioconversion advances are expanding the functional range of Reb M and Reb D variants in dairy applications.
- Chicago CPG headquarters density:Proximity between major beverage R&D centers and flavor houses is compressing co-development iteration cycles.
Market Restraints
- Stevia leaf supply concentration:Raw material sourcing clusters in China create input cost volatility and traceability compliance burdens for European formulators.
- Receptor specificity limitations:Lingering bitter off-notes in high-intensity natural sweeteners restrict application viability in neutral-pH beverage systems.
- SAMR registration timelines:China's extended safety assessment periods delay revenue recognition for novel modulation technologies by 18-24 months post-GRAS.
Strategic Opportunities
- India PLI scheme alignment:Domestic manufacturing incentives for food processing inputs are attracting modulator production investments to serve South Asian beverage markets.
- Precision fermentation convergence:Integration with synthetic biology platforms is enabling rare sugar production at cost parity with agricultural extraction.
- Direct-to-manufacturer digital channels:B2B ingredient marketplaces are disintermediating traditional distributor markups for mid-scale dairy processors.
Industry Challenges
- Flavor chemist scarcity:Specialized receptor pharmacology expertise is concentrating at Swiss and Dutch research institutes, creating recruitment bottlenecks for commercial scale-up teams.
- GRAS self-determination documentation:FDA notification preparation requires toxicology investment that strains early-stage modulation startups.
- Legacy ERP integration:Food safety traceability modules in established manufacturing execution systems resist real-time ingredient attribute updates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweet Modulator Market |
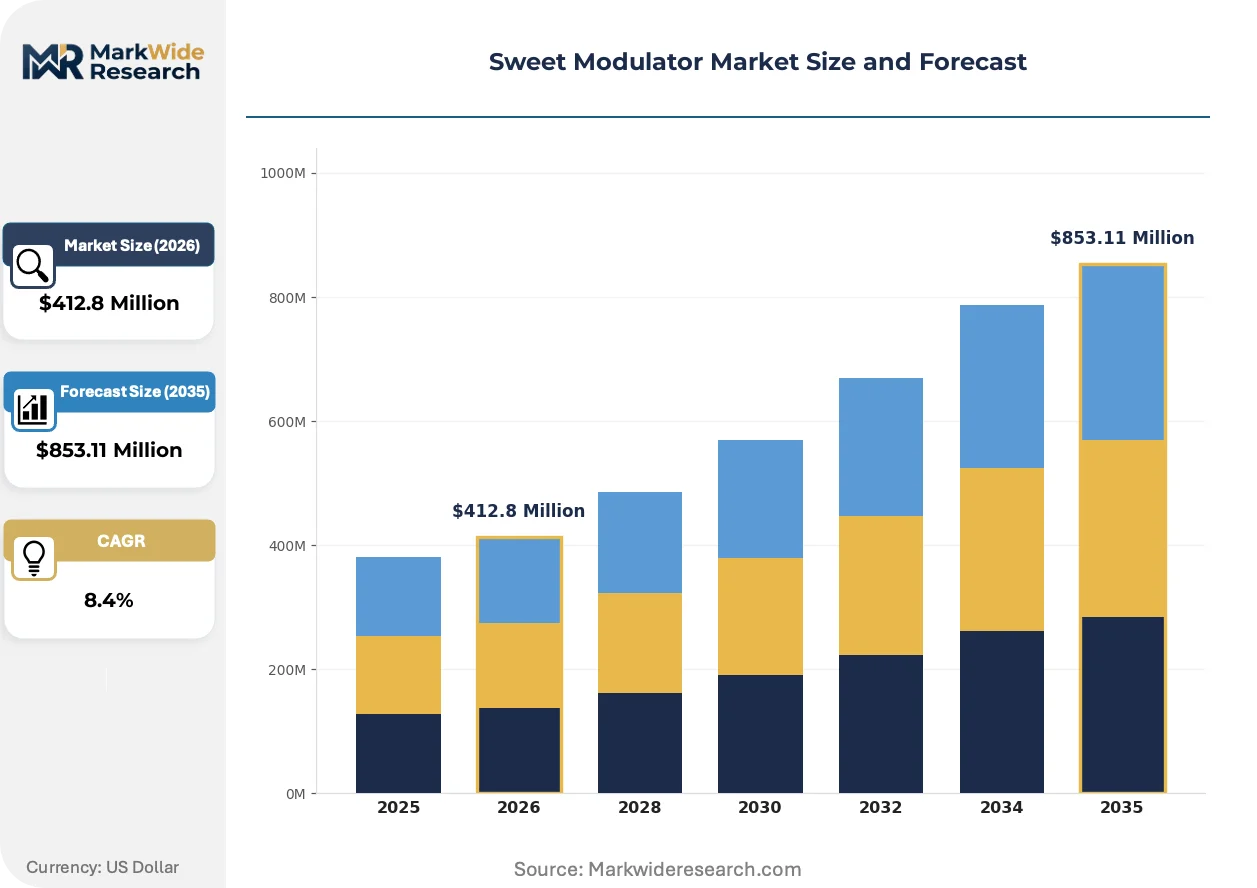
| Market Size in 2026 | $412.8 Million |
| Market Size in 2035 | $853.11 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Sweeteners, Powdered Sweeteners, Natural Sweeteners, Synthetic Sweeteners Application: Beverages, Baked Goods, Snacks, Dairy Products End User: Food Manufacturers, Beverage Producers, Retailers, Restaurants Form: Granulated, Syrup, Concentrate, Paste |
| Companies Covered | DSM, Symrise, IFF (International Flavors & Fragrances), Tate & Lyle, Sensient Technologies, Givaudan, Ingredion, Firmenich, Kerry Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweet Modulator Market Trends and Innovations
Receptor-level understanding is migrating from academic laboratories into proprietary screening platforms, compressing the discovery-to-formulation pipeline. Three convergent developments are restructuring competitive capability requirements.
AI-driven molecular docking is miniaturizing the sweetener discovery process. Beverage R&D teams at major CPG headquarters are deploying neural network models to predict T1R2/T1R3 binding affinity before bench synthesis. This computational front-loading is collapsing traditional 4-5 year development timelines and enabling rapid iteration on structural analogs.
The EU F-Gas Regulation is mandating refrigeration system retrofits across European dairy processing facilities. Thermal profile shifts from new compressor technologies are forcing reformulation of heat-sensitive modulation systems. German and French plant operators are prioritizing spray-dried encapsulation formats to maintain receptor-active compound integrity through revised pasteurization protocols.
Clean-label procurement mandates are displacing artificial high-potency sweeteners in private-label retail programs. Major US grocery chains are requiring published supplier scorecards documenting fermentation versus extraction origins. This certification-driven preference shift is most visible in the Northeast corridor, where regional dairy cooperatives are consolidating ingredient specifications to meet retailer compliance thresholds.
Sweet Modulator Market Segmentation
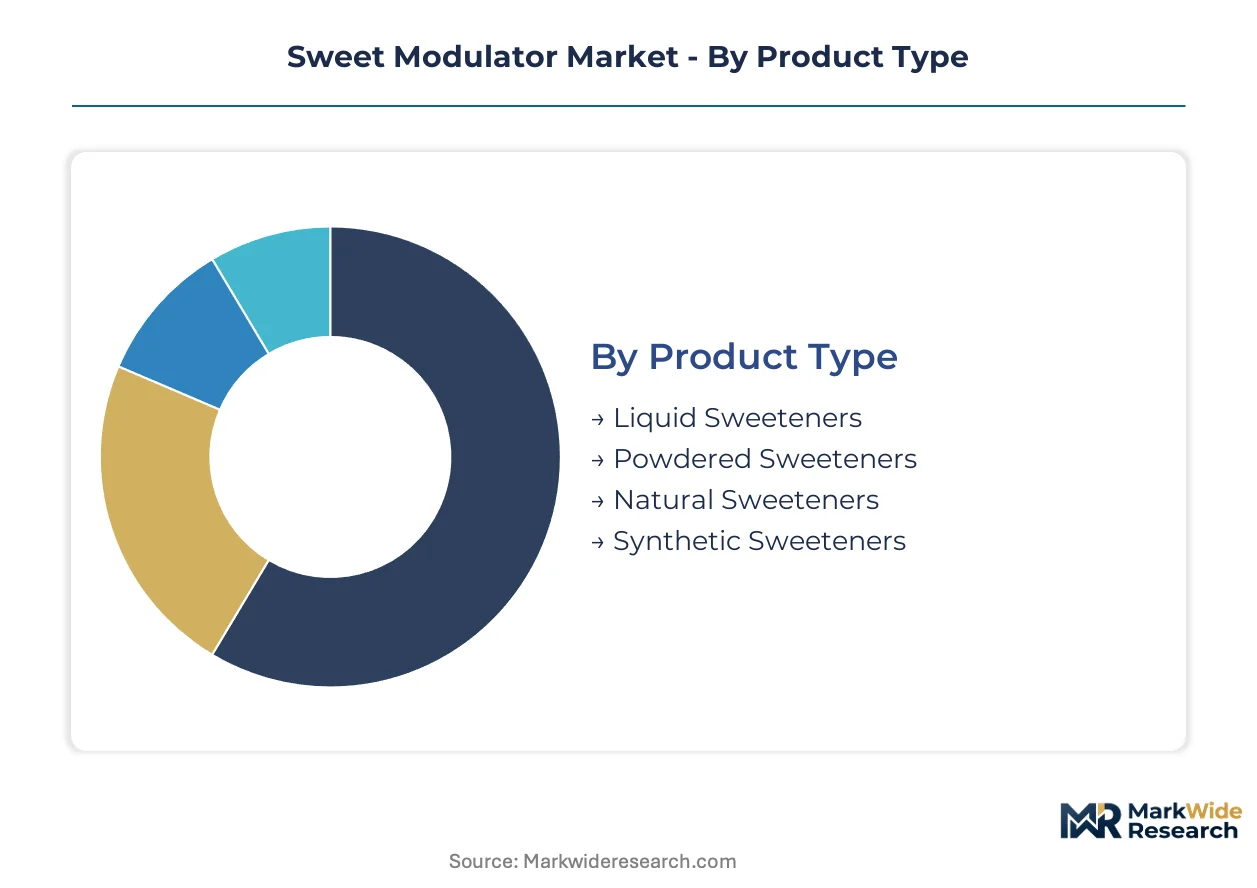
Sweet modulator segmentation determines formulation feasibility across thermal processing regimes and receptor-targeting requirements. Regulatory approval pathways vary sharply by product origin, locking suppliers into distinct commercialization timelines.
Product Type:
FDA GRAS self-determination applies to synthetic and fermentation-derived categories, while EFSA novel food assessments govern natural extract introductions into European formulations.
- Liquid Sweeteners:Aqueous solutions of high-potency compounds formulated for direct dosing into beverage processing lines. Beverage producers in the United States concentrate procurement here, driven by Chicago-area R&D co-location with flavor houses that compress iteration cycles.
- Powdered Sweeteners:Spray-dried or crystallized formats engineered for thermal stability in baked goods and extruded snacks. EFSA F-Gas Regulation compliance is forcing German and French dairy processors toward encapsulated variants that survive revised pasteurization protocols.
- Natural Sweeteners:Stevia glycosides and monk fruit extracts subject to clean-label procurement mandates from US Northeast grocery chains.
- Synthetic Sweeteners:Sucralose and acesulfame potassium compounds facing displacement from private-label retail programs demanding fermentation-origin documentation.
Powdered sweeteners handle the majority of throughput; natural sweeteners are gaining share fastest as retailer certification requirements harden.
Application:
End-use thermal profiles dictate modulator selection, with pasteurization, baking, and extrusion each imposing distinct stability thresholds.
- Beverages:Carbonated and still drinks requiring rapid dissolution and neutral-pH compatibility. US beverage producers anchor volume here, pressured by reformulation deadlines that compress supplier development cycles.
- Baked Goods:Oven-stable modulation systems resisting Maillard interaction degradation. European formulators prioritize this segment as F-Gas refrigeration retrofits alter ingredient storage conditions.
- Snacks:Extruded and fried applications demanding heat-resistant encapsulation. Indian PLI scheme incentives are attracting production investment to serve South Asian savory processing expansion.
- Dairy Products:Fermented and fresh matrices where off-note masking proves critical. Chinese SAMR registration timelines delay novel modulation entry by 18-24 months versus US GRAS pathways.
Beverages dominate current volume; snacks are climbing the fastest on South Asian capacity buildout.
End User:
Customer scale determines service model, with multinational CPGs demanding integrated taste-nutrition platforms versus spot purchasing by mid-tier processors.
- Food Manufacturers:Integrated bakery and confectionery operations specifying multi-category modulation systems. Procurement concentrates among European headquarters clusters seeking stevia optimization expertise.
- Beverage Producers:Dedicated drink formulators requiring rapid co-development iteration. Proximity to Swiss and Dutch flavor research institutes creates recruitment bottlenecks for scale-up teams serving this segment.
- Retailers:Private-label program managers imposing supplier scorecard requirements. Clean-label mandates from US grocery chains are consolidating ingredient specifications.
- Restaurants:Foodservice distributors sourcing portion-controlled formats for fountain and batch preparation. B2B ingredient marketplaces are disintermediating traditional distributor markups here.
Food manufacturers command the deepest supplier relationships; beverage producers are expanding most quickly on reformulation urgency.
Form:
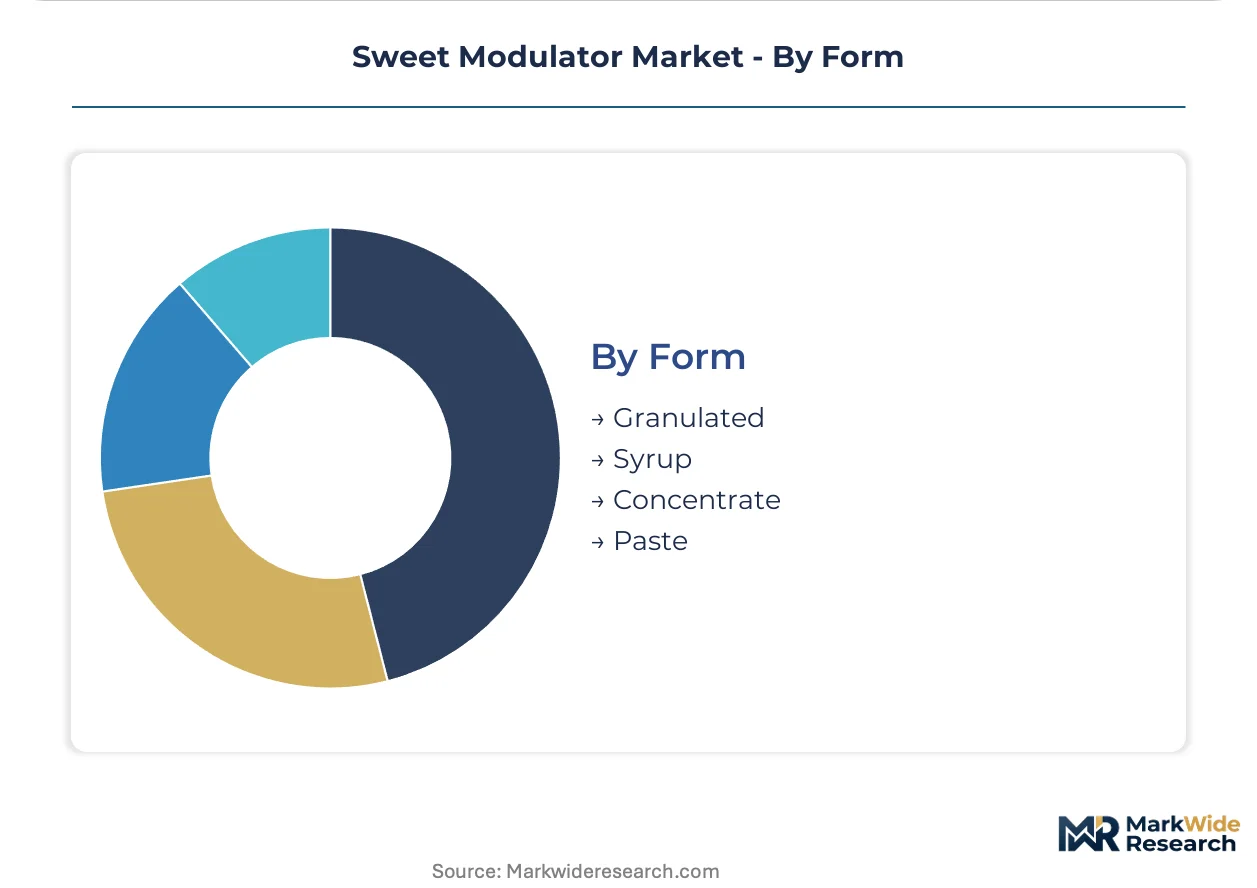
Physical state determines handling infrastructure, with granular and syrup formats requiring distinct metering and blending equipment.
- Granulated:Free-flowing crystalline products for dry blending operations. Baked goods processors specify this format for flour incorporation compatibility.
- Syrup:Viscous aqueous preparations for liquid processing lines. Beverage applications dominate absorption here.
- Concentrate:High-potency dilutions requiring precise dosing systems. Dairy applications favor this form for yogurt and flavored milk production.
- Paste:Semi-solid preparations for industrial bakery and confectionery cream fillings. European manufacturers specify paste formats where moisture control proves critical.
Granulated forms maintain the broadest equipment compatibility; concentrates are advancing fastest on precision dosing technology adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA GRAS self-determination frameworks anchor the United States as the dominant geography, while EFSA novel food assessments and China's SAMR registration requirements create divergent compliance landscapes that reshape supplier prioritization across major demand centers.
United States
Beverage producers in Chicago and New Jersey drive procurement volume as reformulation deadlines compress development cycles. FDA GRAS notification pathways enable faster commercialization timelines than European equivalents. Midwest R&D clusters co-located with flavor houses accelerate iteration on stevia glycoside optimization.
Germany
Dairy processors face thermal profile disruptions from EU F-Gas Regulation compliance retrofits. EFSA novel food assessments govern natural sweetener introductions, extending approval timelines versus US pathways. Bavarian and North Rhine-Westphalian plant operators prioritize spray-dried encapsulation formats for pasteurization stability.
China
Stevia leaf supply concentration creates input cost volatility for downstream formulators. SAMR registration timelines delay revenue recognition by 18-24 months post-GRAS, constraining multinational entry. Yangtze River Delta processing hubs concentrate extraction capacity for Reb M and Reb D variants.
India
Domestic beverage market expansion attracts modulator production investment aligned with PLI scheme incentives. BIS standards compliance requirements add certification layers for imported fermentation-derived compounds. Maharashtra and Gujarat food processing corridors anchor South Asian savory snack application growth.
Switzerland
Flavor chemist expertise concentrates at Swiss research institutes, creating recruitment bottlenecks for commercial scale-up teams. Swissmedic regulatory alignment with EU frameworks enables parallel EFSA submission strategies. Basel and Geneva clusters sustain premium positioning in natural modulation systems.
Sweet Modulator Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the sweet modulator market. The upper tier commands integrated taste-nutrition platforms spanning multiple application categories, while specialists compete on receptor-level optimization for specific thermal processing regimes. Three archetypes dominate: fermentation-derived natural sweetener innovators, stevia glycoside optimization specialists, and commodity-scale synthetic compound suppliers. Competitive moves concentrate on strategic partnerships with beverage R&D centers and portfolio diversification into encapsulation technologies.
Within the integrated platform tier, Kerry Group and Tate & Lyle exemplify archetypes spanning taste-nutrition convergence and stevia optimization expertise respectively. Givaudan anchors the premium natural modulation segment, leveraging geographic proximity to Swiss research infrastructure. These three occupy positions that reflect divergent bets on fermentation scale-up versus agricultural extraction sourcing models.
| Leading Market Players |
|---|
| DSM |
| Symrise |
| IFF (International Flavors & Fragrances) |
| Tate & Lyle |
| Sensient Technologies |
| Givaudan |
| Ingredion |
| Firmenich |
| Kerry Group |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between stevia glycoside processors and beverage R&D centers in Chicago lock in both supply access and price visibility, insulating CPG manufacturers from raw material volatility while compressing iteration cycles for reformulation projects. These contracts anchor procurement relationships as China's stevia leaf supply concentration creates input cost pressure that reverberates through European formulator margins.
Pricing Analysis
Price spreads between fermentation-derived natural sweeteners and agricultural-extraction alternatives widen most sharply across the Atlantic, with EFSA novel food assessment costs embedding regulatory premiums into European landed prices. Three-tier pricing structure across premium, standard, and economy levels separates Givaudan-grade Swiss research heritage formulations from commodity-scale synthetic compounds, with certification grade and volume scale as primary differentiation drivers. Pricing pressure stems from stevia leaf supply concentration in Chinese growing regions, squeezing mid-tier processor margins. Beverage producers demonstrate highest price sensitivity due to reformulation deadline urgency, while dairy processors accept premiums for heat-stable encapsulated formats.
Supply Chain Analysis
Strait of Malacca transit underwrites stevia leaf shipment routes from Chinese extraction hubs to European compounders, creating logistics vulnerability for EFSA-regulated formulators dependent on just-in-time Reb M and Reb D variants. Supply concentrates in China's Yangtze River Delta processing corridors and Indian PLI scheme-aligned Maharashtra production zones, with raw material dependencies on stevia leaf biomass, enzymatic bioconversion catalysts, and spray-drying encapsulation materials. Single-source vulnerability in Chinese agricultural extraction creates structural risk as SAMR registration timelines delay alternative sourcing activation. Distribution runs through integrated taste-nutrition platform providers serving multinational CPG headquarters clusters, with B2B ingredient marketplaces disintermediating traditional distributor markups for mid-scale dairy processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment protects incumbent positions: FDA GRAS self-determination expertise and EFSA novel food submission track records create switching costs that deter customer migration to unproven suppliers.
For Market Incumbents: Secure proprietary screening platforms for AI-driven molecular docking by acquiring receptor pharmacology talent from Swiss and Dutch research institutes, defending against precision fermentation startups threatening rare sugar cost parity. Lock in backward integration into stevia glycoside extraction capacity in China or India to neutralize raw material volatility, while embedding GRAS notification documentation services into customer contracts to deepen switching costs.
For New Entrants and Emerging Players: Lead with direct-to-manufacturer digital channels targeting mid-scale dairy processors in the Northeast corridor, where clean-label procurement mandates from grocery chains have consolidated ingredient specifications into accessible procurement patterns. White-space opportunity concentrates in encapsulated heat-stable formats for F-Gas Regulation-impacted European pasteurization systems, with B2B marketplace positioning as the go-to-market angle to bypass established distributor relationships.
For Investors and Strategic Acquirers: Fermentation-derived natural sweetener innovators with demonstrated SAMR registration progress represent the priority acquisition archetype, as China's extended safety assessment periods create scarcity value for pre-cleared assets. Long-term viability hinges on synthetic biology platform integration enabling rare sugar production at agricultural extraction cost parity. Watch EFSA accelerated approval framework implementation for fermentation-derived compounds as the inflection signal indicating regulatory tailwind duration for bio-manufactured modulation technologies.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Enables rare sugar production cost parity with Chinese agricultural extraction for European beverage formulators. |
| Stevia Glycoside Optimization Partnership | Compresses Reb M and Reb D development cycles through co-location with Chicago-area CPG R&D centers. |
| Encapsulation Technology Acquisition | Secures heat-stable formats required by German and French dairy processors facing F-Gas Regulation retrofits. |
| Direct-to-Manufacturer Digital Channel Launch | Disintermediates distributor markups for mid-scale Northeast corridor dairy cooperatives under retailer scorecard pressure. |
| Regulatory Submission Capability Buildout | Accelerates SAMR and EFSA parallel filing capacity to capture 18-24 month first-mover advantage windows. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with beverage formulation directors, dairy procurement leads, flavor chemists at Swiss research institutes, and regulatory affairs specialists navigating FDA and EFSA pathways. Secondary validation drew from FDA GRAS notification filings, EFSA novel food assessment registers, SAMR registration disclosure databases, and customs trade data tracking stevia glycoside import flows. Bottom-up volume modeling across application segments triangulated with top-down CPG reformulation spending analysis to anchor projection boundaries.
Across the analysis window, the forecasting framework modeled volume and value trajectories by product type, application thermal profile, end-user scale tier, and geographic regulatory cluster. CAGRs were derived from segment-level growth rate reconciliation with macro-level CPG sugar-reduction commitment tracking. Industry-specific inputs included stevia leaf harvest yield variability, enzymatic bioconversion efficiency curves, and F-Gas Regulation compliance timeline assumptions for European dairy processing capacity.
The analysis sits within stated boundaries; outcomes outside sustained CPG reformulation deadline pressure or EFSA accelerated approval pathway maintenance would require recalibration. Forecasts reflect documented assumptions regarding receptor science breakthrough timing and jurisdiction-specific approval velocity. Practitioners should keep alternative scenarios live as China's stevia supply concentration and precision fermentation cost curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Gluten-Free Sugar Syrup Market
Sweeteners
Indonesia Food Sweetener Market
Sweeteners
Reduced Sugar Products Market
Sweeteners
Asia Pacific Food Sweetener Market
Sweeteners
Xylitol Injection Market
Sweeteners
Aspartame Market
Sweeteners
United States Xylitol Market
Sweeteners
Middle East and Africa Food Sweetener Market
Sweeteners
White Sugar Market
Sweeteners
North America Plant-Derived and Synthetic Sugar Market
Sweeteners
Invert Sugar Market
Sweeteners
Vanilla Sugar Market
Sweeteners
Isomaltulose Market
Sweeteners
Rare Sugar Market
Sweeteners
Citrus Molasses Market
Sweeteners
Compressible Sugar Market