
 Salts and Flavored Salts Market | 2026-2036
Salts and Flavored Salts Market Size, Share, and Industry Trends Forecast 2026-2036
Salts and Flavored Salts Market Outlook
The gap between premium artisanal salts and bulk commodity sodium chloride is recalibrating procurement patterns across the food industry. Morton Salt, Inc. leverages its extensive North American distribution network to dominate commodity supply contracts for food manufacturers. Cargill, Incorporated anchors its position through backward integration into evaporative mining and solar salt operations across multiple continents. McCormick & Company, Inc. differentiates by specializing in value-added flavored salt blends targeting culinary professionals and premium retail channels.
Salts and flavored salts comprise sodium chloride crystals ranging from refined 99.9% pure granules to unrefined mineral-rich flakes with varying grain sizes from 0.3 mm to 4 mm, produced through solar evaporation, vacuum pan evaporation, or rock salt mining for flavor enhancement, preservation, and texture modification. Sea salt captures widening margin pools as consumers associate trace mineral content with perceived health benefits and terroir authenticity. Flavored salts represent the fastest-expanding category as manufacturers infuse smoked, herb, and spice variants to command premium pricing in specialty stores and online retail channels.
The FDA's voluntary sodium reduction targets and USDA dietary guidelines constrain formulation choices for processed food manufacturers while creating openings for potassium-based salt substitutes and reduced-sodium flavored blends. EFSA's ongoing re-evaluation of sodium intake thresholds across the European Union shapes labeling requirements and reformulation incentives for exporters serving continental markets. Stakeholders must monitor evolving front-of-pack warning label regimes and clean-label certification standards to anticipate which mineral compositions and additive-free positioning will secure shelf space in regulated retail environments.
Market Dynamics
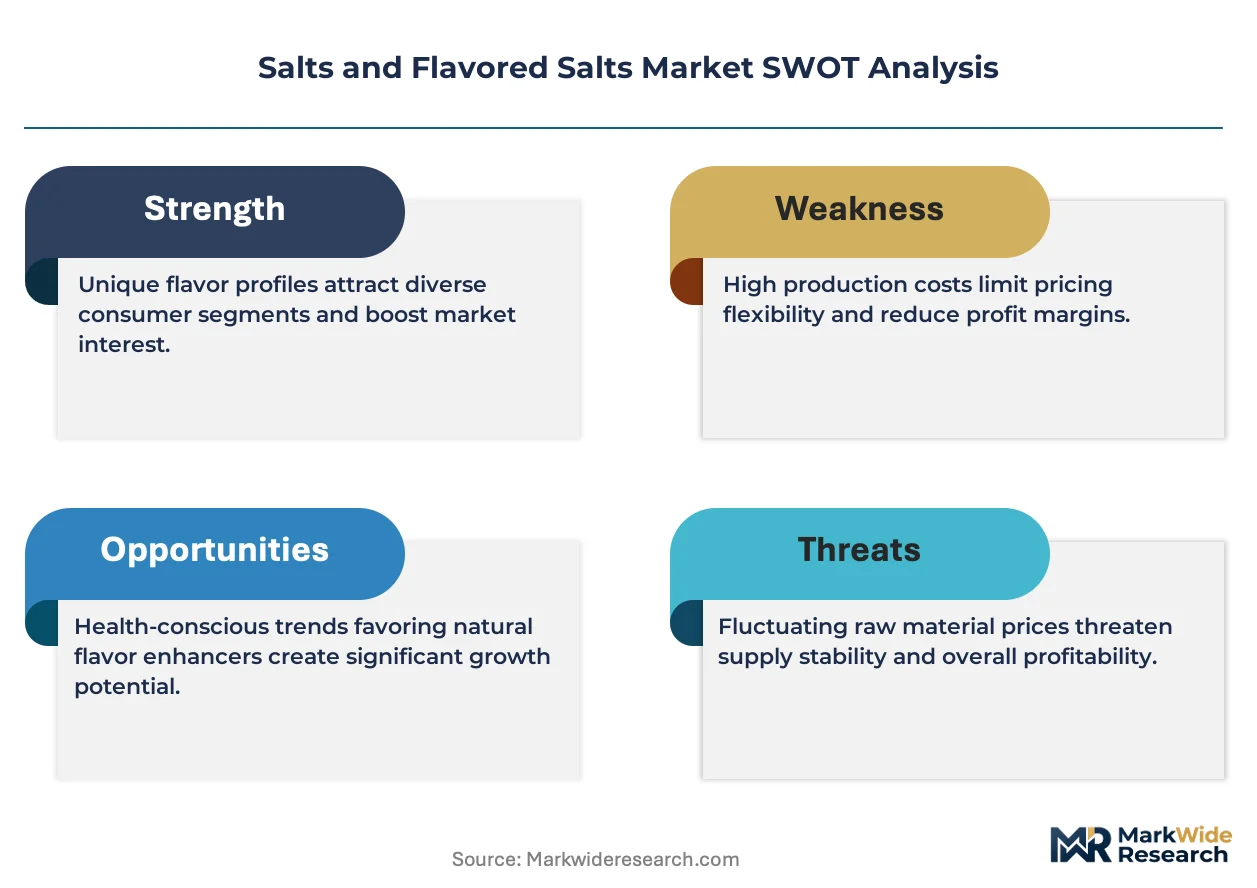
The FDA's voluntary sodium reduction targets are forcing processed food manufacturers to reformulate recipes, creating simultaneous demand for potassium-based substitutes and premium mineral salts that preserve flavor integrity.
Growth Catalysts
- EFSA sodium threshold reviews:European Union re-evaluation of dietary guidelines is accelerating clean-label salt adoption across French, Italian, and Spanish artisanal food clusters.
- Solar evaporation technology:Advanced pond management systems are expanding production capacity for fleur de sel and sel gris variants in coastal Mediterranean facilities.
- Gourmet restaurant procurement:Michelin-starred kitchens across Japan and the United States are establishing direct sourcing relationships with specialty finishing salt producers.
Market Restraints
- Energy input volatility:Vacuum pan evaporation operations face margin compression from natural gas price swings in European manufacturing zones.
- Rock salt mining concentration:Underground extraction capacity concentrates in specific geological basins, creating single-source vulnerability for industrial sodium chloride supply.
- Potassium chloride taste limitations:Metallic aftertaste profiles constrain substitution rates in baked goods and savory snack applications.
Strategic Opportunities
- USDA organic certification pathway:Certified organic mineral salts command shelf space premiums in natural retail channels.
- Direct-to-chef e-commerce platforms:Specialty food distributors are building digital procurement portals bypassing traditional wholesale intermediaries.
- Smoked salt fusion techniques:Cold-smoking technology convergence with sea salt crystallization is opening barbecue and meat processing verticals.
Industry Challenges
- Mineral content standardization:Trace element variability in unrefined salts complicates nutritional labeling compliance across multi-jurisdictional shipments.
- Legacy ERP integration:Batch tracking requirements for kosher and halal certifications strain older manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Salts and Flavored Salts Market |
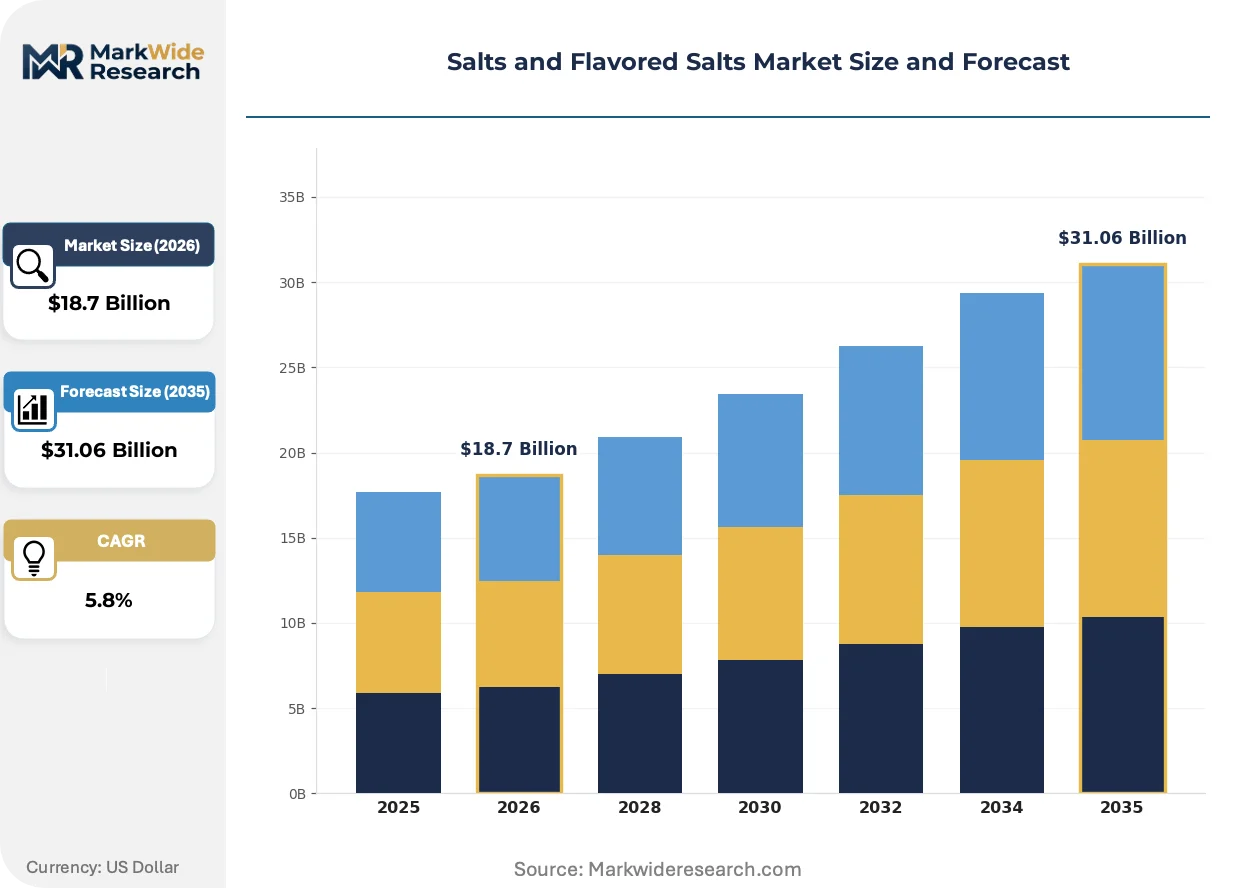
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sea Salt, Table Salt, Himalayan Salt, Flavored Salt Application: Food Seasoning, Food Preservation, Culinary Use, Industrial Processing Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesalers Customer Type: Households, Restaurants, Food Manufacturers, Chefs |
| Companies Covered | Morton Salt, Inc., Cargill, Incorporated, K+S Aktiengesellschaft, McCormick & Company, Inc., SaltWorks, Inc., Tata Chemicals Limited, Compass Minerals International, Inc., Akzo Nobel NV, United Salt Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Salts and Flavored Salts Market Strategic Shifts
Formulation science and crystallization control methods are reshaping how salt functions beyond basic sodium delivery, with texture engineering and mineral retention becoming primary value levers.
Precision-controlled vacuum pan evaporation is consolidating quality tiers in the refined salt segment. Food manufacturers seeking consistent 0.3 mm grain distribution for uniform dissolution are abandoning traditional solar methods. This consolidation is compressing mid-grade suppliers unable to achieve the narrow moisture and purity tolerances demanded by automated seasoning lines.
REACH registration requirements for sodium chloride process aids are tightening impurity disclosure obligations across European supply chains. Manufacturers must now document heavy metal content in anticaking agents at parts-per-billion thresholds. Exporters serving German and Dutch processed food facilities are reformulating with alternative flow agents to maintain market access.
Chef-driven specification authority is displacing centralized procurement in premium restaurant supply. Individual kitchen leaders now dictate exact crystal morphology and moisture content for tableside service. This pattern concentrates in coastal California and Tokyo's Ginza district, where hospitality groups compete on terroir storytelling.
Salts and Flavored Salts Market Segmentation
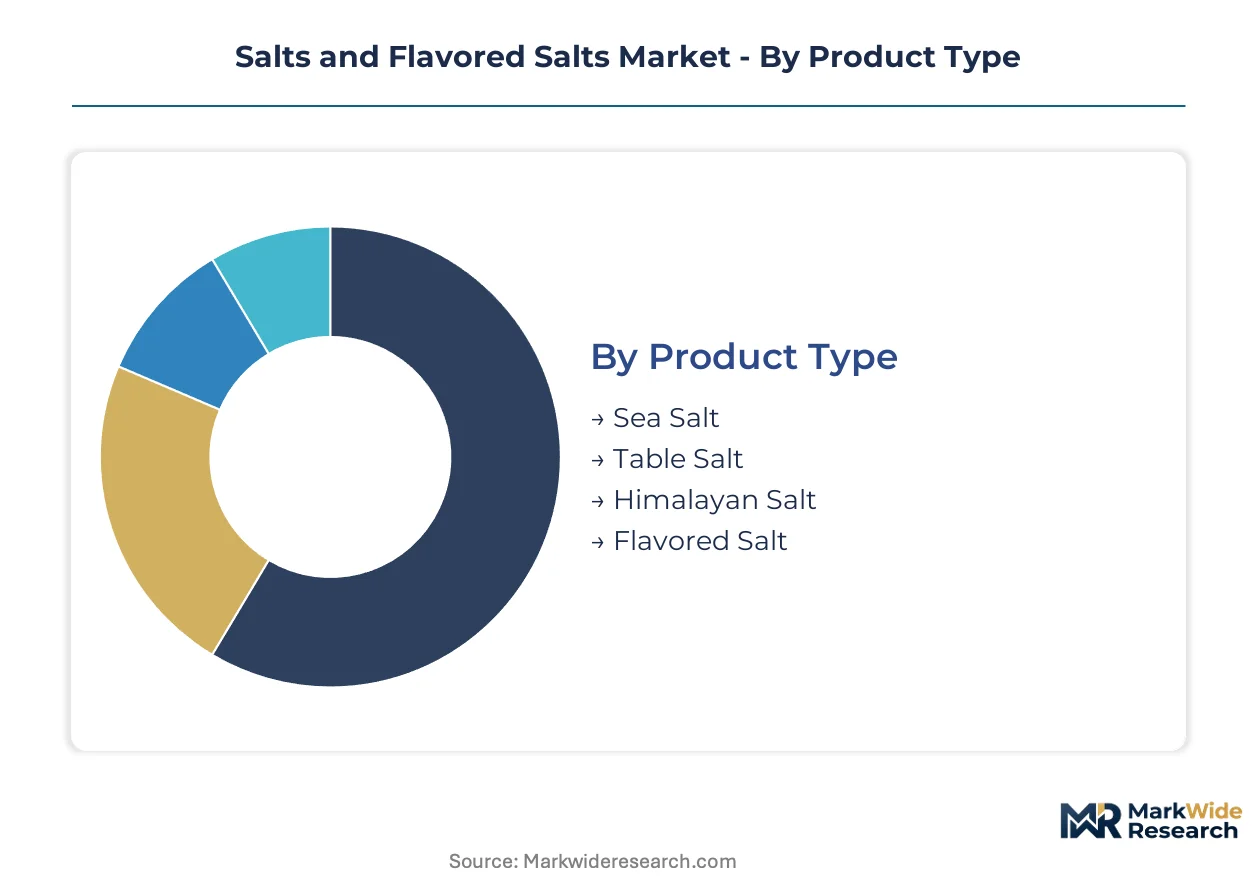
Procurement patterns in salts and flavored salts diverge sharply across product grades and end-use specifications. Manufacturers align crystallization methods and mineral content profiles to distinct customer workflows spanning industrial automation to artisanal kitchen practice.
Product Type:
Evaporative capacity concentrates in coastal Mediterranean facilities and Himalayan foothill mining zones, with crystallization technology determining purity thresholds and mineral retention.
- Sea Salt:Solar evaporation in controlled pond systems yields fleur de sel and sel gris with 2-4% residual moisture and trace magnesium-calcium content. French, Italian, and Spanish artisanal food clusters drive procurement of unrefined variants for clean-label positioning. EFSA sodium threshold reviews accelerate adoption as manufacturers seek mineral-authentic alternatives to refined sodium chloride.
- Flavored Salt:Cold-smoking and herb-infusion techniques transform base crystals into barbecue, truffle, and citrus variants commanding premium placement in specialty retail. Smoked salt fusion techniques open meat processing verticals as processors replace liquid smoke additives with dry-rub formulations.
- Table Salt:Vacuum pan evaporation achieves 99.9% sodium chloride purity with 0.3 mm uniform grain distribution for automated seasoning lines.
- Himalayan Salt:Underground mining in Pakistan's Khewra Salt Mine supplies iron-oxide-tinted crystals for wellness-positioned retail and decorative lamp applications.
Table salt absorbs the bulk of installed capacity; flavored salt is expanding most quickly.
Application:
Cost tier differentiation separates commodity sodium chloride from value-added mineral and flavored variants, with formulation requirements tightening across processed food segments.
- Food Seasoning:Precision grain sizing enables controlled dissolution rates in snack manufacturing and prepared meal formulations. FDA voluntary sodium reduction targets force reformulation toward potassium-based substitutes and reduced-sodium flavored blends that preserve taste integrity.
- Culinary Use:Michelin-starred kitchens in Japan and the United States specify exact crystal morphology for tableside finishing, creating direct sourcing relationships with specialty producers. Chef-driven specification authority displaces centralized procurement in premium restaurant supply.
- Food Preservation:Curing and brining applications require consistent sodium chloride concentration for microbial inhibition in meat and dairy processing.
- Industrial Processing:Chemical manufacturing and water treatment sectors consume high-volume refined grades with strict impurity tolerances.
Food seasoning commands the largest volume share; culinary use climbs the fastest as hospitality groups compete on terroir storytelling.
Distribution Channel:
Customer type fragmentation shapes fulfillment architecture, with institutional buyers demanding batch traceability and retail channels prioritizing shelf-stable packaging formats.
- Supermarkets:Multi-tier shelving accommodates economy iodized table salt through premium sea salt grinders, with private-label expansion compressing branded mid-tier positioning.
- Specialty Stores:Curated assortments of single-origin fleur de sel and artisan smoked variants target culinary enthusiasts in urban coastal markets.
- Online Retail:Direct-to-chef e-commerce platforms bypass wholesale intermediaries, enabling specialty distributors to capture margin from digital procurement portals.
- Wholesalers:Bulk sodium chloride supply concentrates in food service and industrial processing contracts with volume-based pricing structures.
Supermarkets absorb the bulk of installed capacity; online retail is expanding most quickly.
Customer Type:
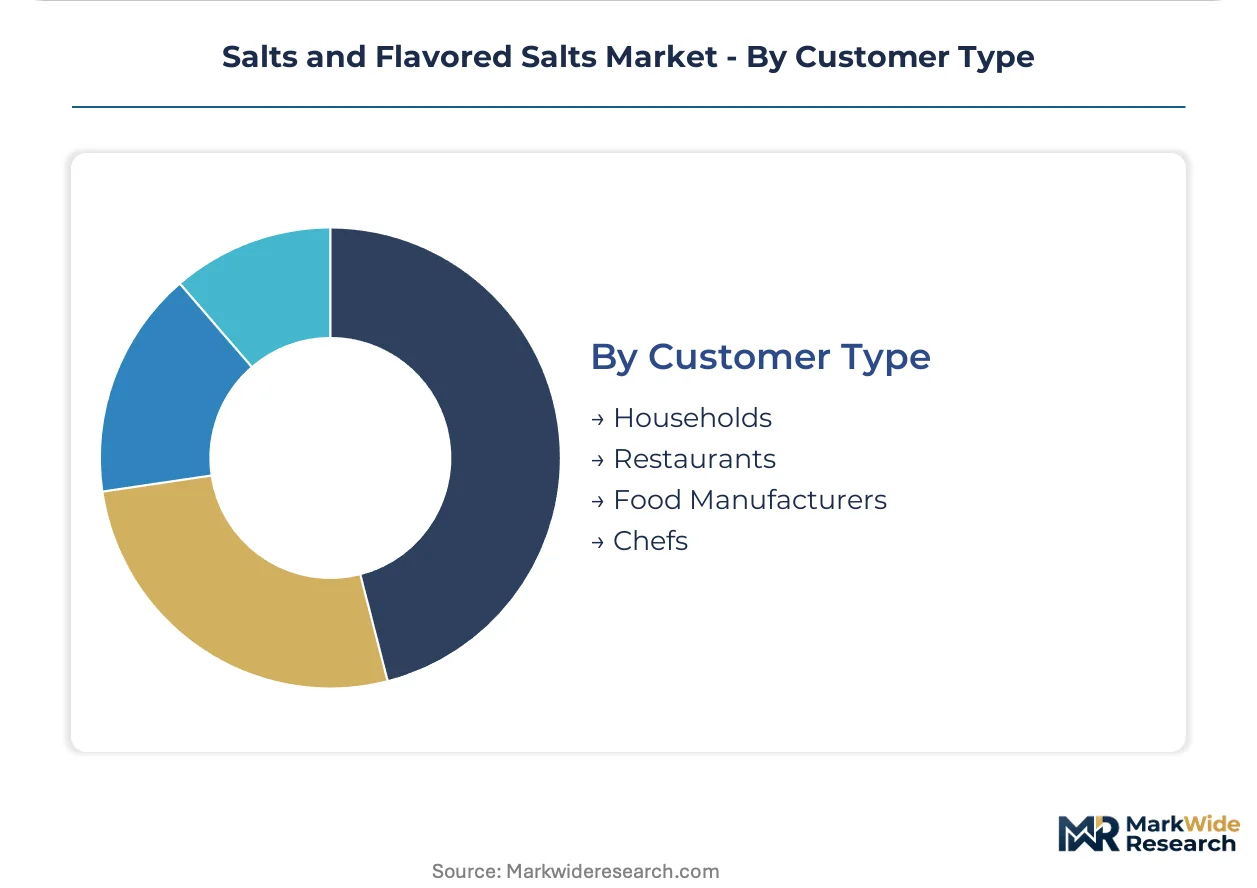
Application specificity determines procurement protocol, with automated manufacturing requiring certification documentation and artisanal users prioritizing sensory characteristics.
- Food Manufacturers:Automated seasoning lines demand 0.3 mm grain distribution with moisture content below 0.5% for uniform dissolution. REACH registration requirements for process aids tighten heavy metal disclosure obligations in European supply chains.
- Restaurants:Hospitality groups in coastal California and Tokyo's Ginza district specify exact crystal morphology for competitive terroir positioning.
- Chefs:Individual kitchen leaders now dictate mineral composition and finishing texture for tableside service, consolidating specification authority.
- Households:Retail consumers shift toward premium sea salt and flavored variants as clean-label awareness permeates home cooking practice.
Food manufacturers absorb the bulk of installed capacity; chefs are expanding most quickly as specification authority decentralizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coastal Mediterranean facilities in France's Guérande peninsula dominate artisanal fleur de sel production. Solar evaporation ponds across this corridor supply Michelin-starred kitchens worldwide. Regulatory pressure from Brussels to Washington is fragmenting formulation standards across export destinations.
United States
Gourmet restaurant procurement concentrates in California's Napa Valley and New York's Manhattan, where hospitality groups compete on terroir storytelling. FDA voluntary sodium reduction targets force processed food manufacturers toward potassium-based substitutes. Chicago's industrial corridor hosts automated seasoning line operations demanding 0.3 mm grain distribution.
France
Artisanal food manufacturing clusters in Brittany and Provence drive unrefined sea salt demand for clean-label positioning. EFSA sodium threshold reviews accelerate mineral-authentic alternatives to refined sodium chloride. Guérande's controlled pond systems yield fleur de sel with 2-4% residual moisture for premium export.
Japan
Michelin-starred kitchens in Tokyo's Ginza district specify exact crystal morphology for tableside finishing. METI standards shape impurity disclosure for imported mineral salts. Osaka's prepared meal sector adopts precision grain sizing for controlled dissolution rates in automated manufacturing.
Germany
REACH registration requirements tighten heavy metal disclosure obligations for anticaking agents at parts-per-billion thresholds. Processed food facilities in Bavaria reformulate with alternative flow agents to maintain market access. Hamburg's port infrastructure handles bulk sodium chloride supply for chemical manufacturing and water treatment.
Italy
Solar evaporation technology expands capacity for sel gris variants in Sicilian coastal facilities. EFSA labeling requirements shape reformulation incentives for exporters serving continental markets. Emilia-Romagna's cured meat processors require consistent sodium chloride concentration for microbial inhibition in traditional production.
Salts and Flavored Salts Market Competitive Environment
Premium-margin players sit above commodity-margin players across crystallization technology and distribution reach. The vendor base stratifies between evaporative specialists, mining operators, and flavor-infusion blenders. Three archetypes dominate: backward-integrated resource holders, precision-crystallization technologists, and chef-facing specialty distributors. Capacity expansion and direct-to-chef e-commerce platforms constitute the primary competitive moves reshaping channel control.
Within the commodity supply tier, Morton Salt, Inc. and Cargill, Incorporated represent scale-driven archetypes with extensive North American distribution networks. McCormick & Company, Inc. occupies a position exemplifying value-added flavored salt specialization targeting culinary professionals and premium retail channels. These three entities anchor the competitive structure without exhausting its diversity.
| Leading Market Players |
|---|
| Morton Salt, Inc. |
| Cargill, Incorporated |
| K+S Aktiengesellschaft |
| McCormick & Company, Inc. |
| SaltWorks, Inc. |
| Tata Chemicals Limited |
| Compass Minerals International, Inc. |
| Akzo Nobel NV |
| United Salt Corporation |
| Others |
Value Chain & Pricing Dynamics
EFSA sodium threshold reviews and FDA voluntary reduction mandates gate qualified supply for premium-tier mineral salts, restricting market access to producers achieving clean-label certification while compressing margins for uncertified commodity suppliers. Buyers seeking terroir-authenticated fleur de sel or reduced-sodium flavored blends must pay substantial premiums to secure compliant inventory from approved Mediterranean and Himalayan sources.
Pricing Analysis
Yield-per-ton crystallization outcomes anchor value-based pricing, with fleur de sel producers commanding premiums based on harvest labor intensity and mineral retention rates. Three-tier pricing structure across premium artisanal, standard industrial, and economy refined grades separates Michelin-starred restaurant procurement from automated seasoning line contracts. Cost compression in commodity vacuum-pan salt is intensifying because energy input volatility erodes European manufacturing margins. Food manufacturers exhibit highest price sensitivity due to volume scale and formulation cost targets, while chef-driven specialty buyers show lowest sensitivity when terroir authenticity is demonstrable.
Supply Chain Analysis
Direct-to-chef e-commerce platforms and specialty food distributors handle fragmented high-margin demand, while bulk wholesalers manage industrial sodium chloride offtake. Production gravity centers on Pakistan's Khewra Salt Mine for Himalayan pink salt, France's Guérande peninsula for fleur de sel, and coastal Mediterranean facilities for sel gris variants. Crystallization operations draw from natural gas feedstocks, solar thermal inputs, and underground brine reserves. Single-source vulnerability concentrates in Pakistani mining zones where geopolitical disruption could constrain wellness-positioned retail supply. Distribution runs through layered wholesale intermediaries for commodity grades and bypasses traditional channels for premium direct sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where REACH registration requirements and FDA sodium reduction guidelines erect barrier-to-entry moats favoring certified producers with documented heavy metal disclosure and clean-label positioning.
For Market Incumbents: Anticipate potassium chloride substitution acceleration by securing backward integration into evaporative mining assets across multiple continents. Defend margin position through capacity addition in solar pond facilities serving EFSA-compliant European export demand. Certification investment in USDA organic and kosher/halal standards protects channel control against emerging specialty blenders.
For New Entrants and Emerging Players: Specialty food distributors represent the most penetrable channel partner type for bypassing entrenched wholesale hierarchies. Target direct-to-chef e-commerce portals in coastal California and Tokyo's Ginza district where specification authority decentralizes. White-space exists in cold-smoked salt fusion for barbecue and meat processing verticals. Go-to-market angle should emphasize batch traceability and mineral content standardization for kosher certification compliance.
For Investors and Strategic Acquirers: FDA enforcement action on sodium reduction compliance is the leading indicator that premium mineral salt demand will accelerate beyond commodity substitution rates. Long-term viability favors backward-integrated resource holders with captive evaporative capacity and established chef relationships. Acquisition target archetype: mid-cap specialty distributors with digital procurement platforms and Mediterranean direct sourcing contracts. Signal to monitor: front-of-pack warning label regime expansion across additional European jurisdictions.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Solar Evaporation Assets | Captive supply of fleur de sel insulates margin from energy price volatility in European vacuum-pan operations. |
| USDA Organic Certification Investment | Certified mineral salts command shelf space premiums in natural retail channels constrained by clean-label demand. |
| Direct-to-Chef E-Commerce Platform Launch | Digital procurement portals bypass wholesale intermediaries and capture margin from specification-driven hospitality buyers. |
| Cold-Smoking Technology Convergence | Smoked salt fusion opens barbecue and meat processing verticals replacing liquid smoke additives. |
| REACH-Compliant Process Aid Reformulation | Alternative flow agents maintain German and Dutch market access under tightened heavy metal disclosure thresholds. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across salt plant managers, specialty food distribution channel partners, procurement leads at processed food manufacturers, and executive chefs at Michelin-starred establishments. FDA sodium reduction guidance documents, EFSA scientific opinions, REACH registration databases, and evaporative technology patent filings provided validation. Bottom-up crystallization capacity estimates and top-down consumption trend analysis enabled triangulation across modeling approaches.
Data-stream reconciliation across production volume surveys, import-export trade flows, and end-use consumption patterns shaped the analytical framework. Segmentation dimensions modeled include crystallization method, mineral content grade, end-use application, and customer procurement authority across the projection horizon. CAGRs derived from trend extrapolation of solar evaporation capacity expansion, vacuum pan technology adoption rates, and chef-driven specification growth. Forecast inputs incorporated EFSA regulatory timeline assumptions and FDA enforcement probability weightings without year-specific anchoring.
Several conditions sit outside the modeled scope, including abrupt geopolitical disruption to Pakistani mining operations, breakthrough potassium chloride taste masking technologies, and unilateral tariff imposition on Mediterranean salt imports. Forecasts reflect assumptions about regulatory compliance cost trajectories and clean-label consumer preference stability. Periodic stress-testing of base assumptions is recommended given energy input volatility and evolving front-of-pack warning label regimes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Asia-Pacific Food Flavor Market
Flavorings and Food Additives
Fractionated Lecithin Market
Flavorings and Food Additives
South America Food Flavor and Enhancer Market
Flavorings and Food Additives
Pumpkin Spice Products Market
Flavorings and Food Additives
Global Eucalyptus Essential Oil Market
Flavorings and Food Additives
Rose Water Market
Flavorings and Food Additives
Global Paprika Oleoresin Market
Flavorings and Food Additives
Food Flavors Market
Flavorings and Food Additives
Citrus Aromatic Fractions for Mood Support Market
Flavorings and Food Additives
Tangerine Extract Market
Flavorings and Food Additives
Carotenoids Pigment Market
Flavorings and Food Additives
Orange Essential Oil Market
Flavorings and Food Additives
Flavor Masking Agents Market
Flavorings and Food Additives
Russia Food Colorants Market
Flavorings and Food Additives
Food-Grade Gellan Gum Market
Flavorings and Food Additives
Chokeberry Extract Market