
 Electric Vehicle Ambient Lighting Market | 2026-2036
Electric Vehicle Ambient Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Ambient Lighting Market Insights
RGB programmable specification tiers is bifurcating the competitive landscape into premium system integrators and cost-optimized module suppliers. FORVIA HELLA leverages its European OEM relationships to sustain high-margin cockpit lighting programs. Valeo anchors its position through integrated electronics-software control platforms for adaptive interior illumination. Koito Manufacturing dominates Asian supply chains with manufacturing scale in LED headlamp-adjacent ambient modules.
Electric vehicle ambient lighting encompasses LED, OLED, fiber optic, and neon technologies deployed within passenger compartments to enhance cabin aesthetics, driver alertness, and brand differentiation through controlled luminous output typically ranging from 0.5 to 50 lumens per zone. These systems interface with vehicle body control modules via LIN or CAN bus protocols to enable synchronized color temperature shifts and dimming curves calibrated to driving mode or occupant preference. LED product types occupy the largest installed base due to thermal efficiency and lumen-per-watt performance, while OLED application in dashboard segments captures the fastest expansion as wraparound display surfaces merge with decorative illumination. Footwell and door panel applications concentrate margin pools where acoustic and haptic integration with ambient light creates bundled feature packages.
FDA guidelines for driver alertness and distraction, ECE R48 regulations governing interior light source placement and intensity, and China's GB standards for vehicle electrical subsystems collectively shape homologation pathways and product qualification timelines. REACH compliance for phosphor and rare-earth materials in LED dies adds supply chain certification overhead that favors vertically integrated compound semiconductor producers. Stakeholders must monitor how software-defined vehicle architectures will redistribute control logic between Tier-1 lighting suppliers and OEM central compute platforms.
Market Dynamics
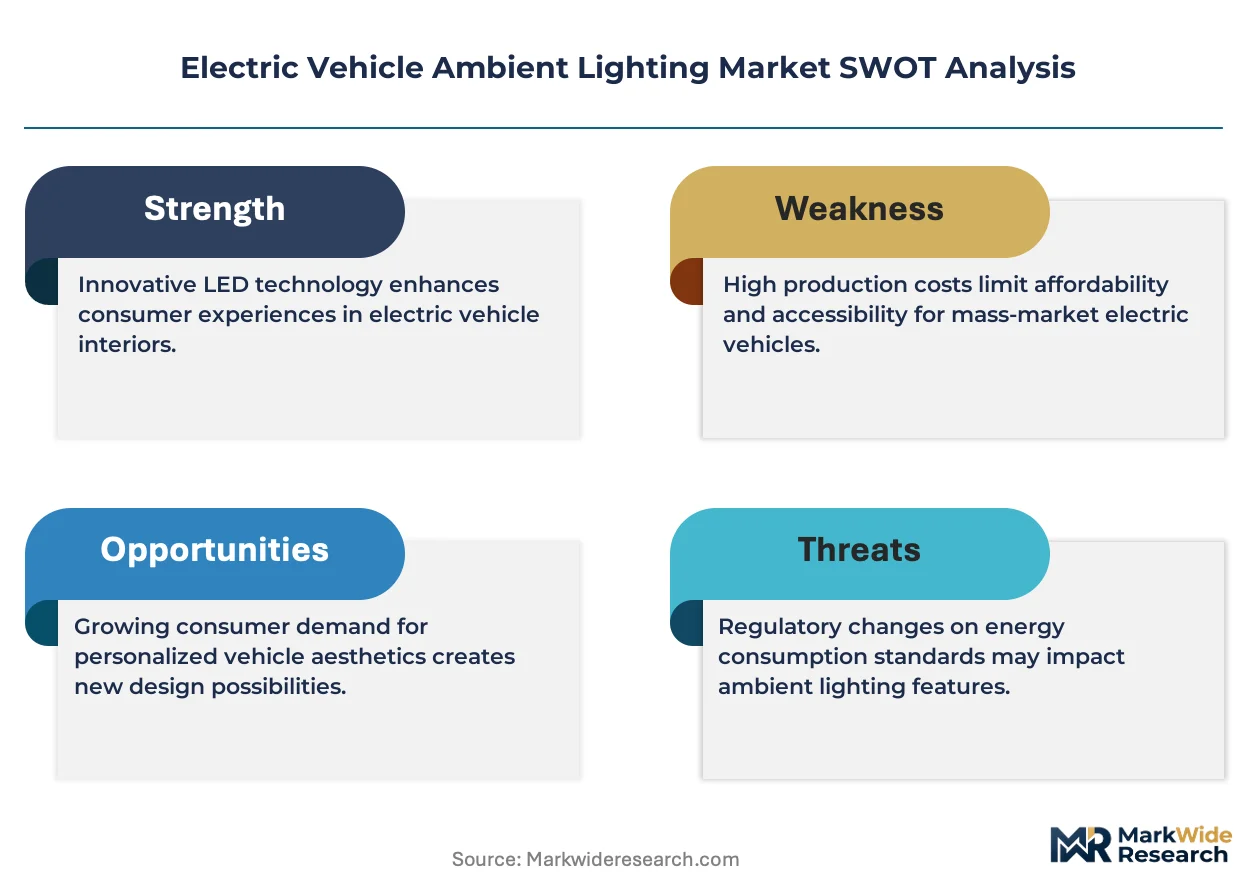
Software-defined vehicle architectures are redistributing control logic from discrete lighting modules toward centralized compute platforms, forcing Tier-1 suppliers to pivot from hardware-centric margins toward firmware and calibration services.
Growth Catalysts
- Multi-zone programmable systems:Premium passenger EV brands now specify RGB ambient lighting as standard equipment, creating specification pull through OEM engineering centers in Germany.
- ECE R48 compliance pathways:Europe's tightening interior illumination regulations are accelerating homologation investments and favoring suppliers with established certification track records.
- OLED dashboard convergence:Wraparound display surfaces merging with decorative illumination are expanding addressable cockpit real estate for lighting integration.
Market Restraints
- Phosphor material certification overhead:REACH compliance for rare-earth materials in LED dies adds supply chain qualification costs that compound for non-integrated compound semiconductor producers.
- Asian supply concentration:Manufacturing scale for LED headlamp-adjacent ambient modules clusters in specific East Asian production corridors, creating geographic dependency risk.
- Thermal management complexity:Lumen-per-watt performance gains in dense LED arrays require sophisticated heat dissipation engineering that extends development timelines.
Strategic Opportunities
- Acoustic-haptic bundling:Footwell and door panel applications where ambient light integrates with tactile feedback systems create premium feature packages commanding higher module ASPs.
- LIN bus protocol expansion:Lower-cost vehicle segments adopting simplified body control architectures present addressable volume for standardized lighting controllers.
- China's GB standard evolution:Vehicle electrical subsystem regulations under MIIT direction are creating domestic qualification pathways for localized supply chains.
Industry Challenges
- Firmware talent scarcity:Adaptive interior illumination systems require embedded software engineers capable of calibrating dimming curves to driving modes, a skill set concentrated at automotive electronics specialists.
- Homologation timeline compression:NMPA vehicle safety guidelines and ECE R48 revisions are shortening product qualification windows while expanding test scope.
- Control logic redistribution:OEM central compute platforms are absorbing functions previously resident in dedicated lighting ECUs, compressing addressable hardware value per vehicle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Ambient Lighting Market |
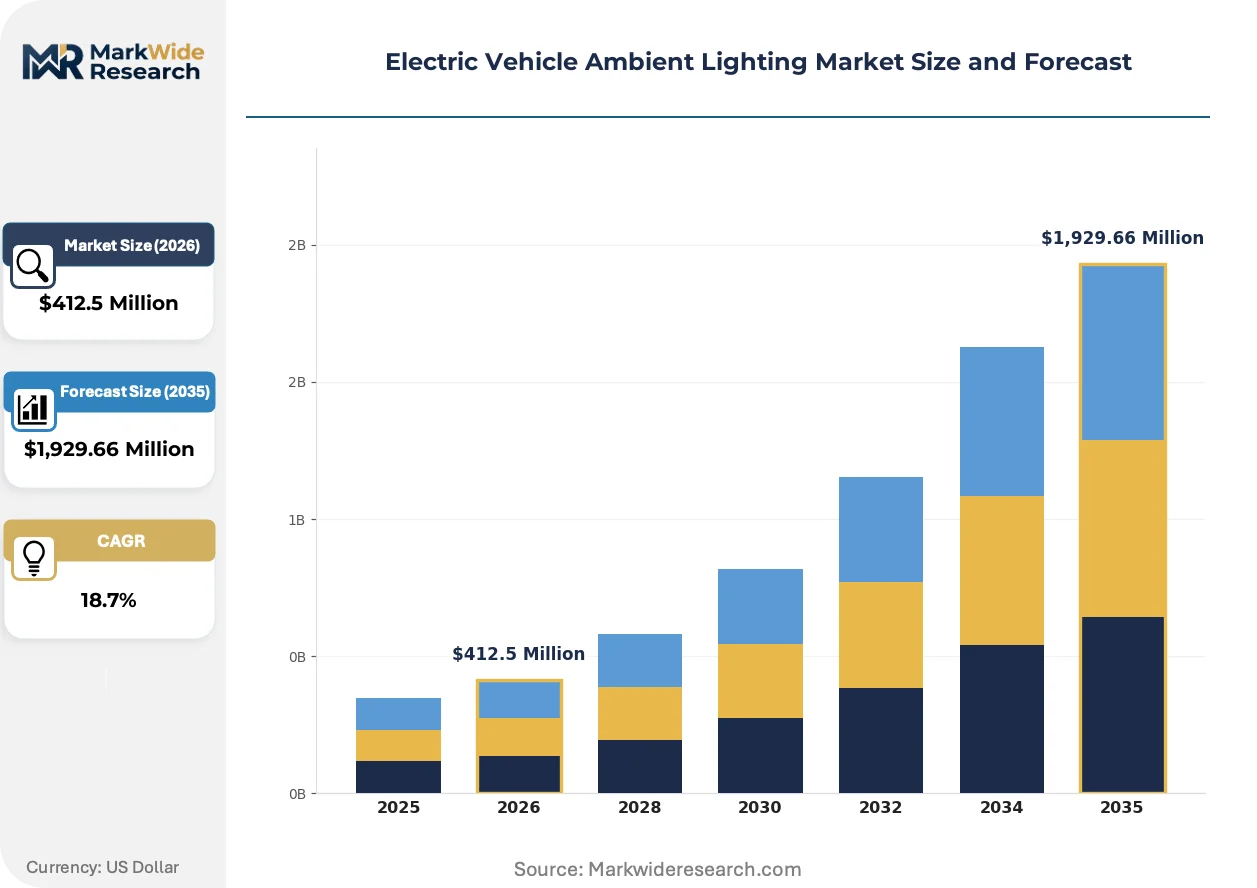
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,929.66 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, OLED, Fiber Optic, Neon Application: Dashboard, Footwell, Door Panels, Headliner End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Custom Shops Feature: Color Change, Dimming, Sound Sync, Adaptive Lighting |
| Companies Covered | FORVIA HELLA, Valeo, Koito Manufacturing, OSRAM GmbH, Grupo Antolin, Draxlmaier Group, Stanley Electric, Hyundai Mobis, Schott, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Ambient Lighting Market Trends and Innovations
OLED surface illumination is actively merging with digital cockpit displays, creating contiguous visual environments that erase traditional boundaries between information presentation and ambient mood setting.
Edge-lit fiber optic distribution is supplanting discrete point-source LED arrays in premium door panel applications, enabling thinner section profiles that preserve interior packaging volume. Luxury EV platforms from Munich and Stuttgart engineering centers are adopting this approach for 2026 model year refreshes. The shift is compressing demand for conventional LED strip assemblies while expanding specification scope for optical-grade polymer suppliers.
China's NMPA vehicle safety guidelines are tightening photobiological safety thresholds for interior light sources, extending test protocols for blue-rich LED spectra. Suppliers must now submit spectral power distribution data across 380-780nm ranges, adding weeks to qualification timelines. Domestic OEMs are responding by pre-qualifying module variants through MIIT-registered testing laboratories.
Buyer specification behavior is fragmenting across fleet procurement and retail channels, with rental and mobility-service operators prioritizing standardized monochrome systems while private buyers demand full RGB programmability. This bifurcation is forcing Tier-1 suppliers to maintain parallel product architectures. The tension is most visible in Germany, where engineering centers serve both volume OEMs and premium brands from shared supply bases.
Electric Vehicle Ambient Lighting Market Segmentation
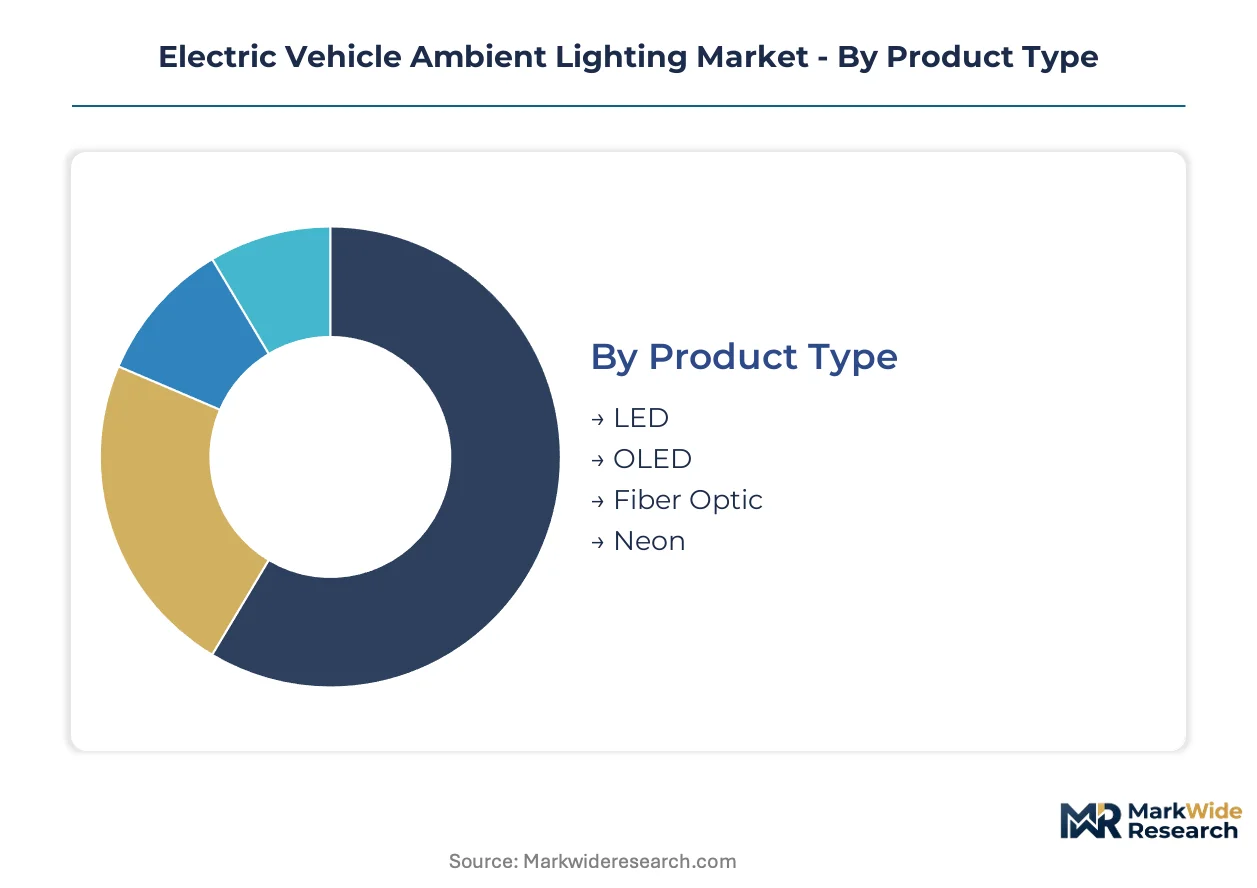
Segmentation in electric vehicle ambient lighting reveals how specification tiers map to distinct supply chain configurations. Technical differentiation across product types and applications determines margin distribution and qualification pathways for suppliers competing across German engineering centers and Asian manufacturing corridors.
Product Type:
LED modules dominate domestic supply chains serving volume OEMs, while OLED and fiber optic variants concentrate in export-led premium programs.
- LED:Thermal-efficient semiconductor dies deliver 100-150 lumens per watt across dense array configurations. German OEM engineering centers in Munich and Stuttgart source these modules for multi-zone programmable systems, though phosphor material REACH compliance adds qualification overhead for non-integrated compound semiconductor producers.
- OLED:Thin-film organic electroluminescent layers enable wraparound dashboard surfaces that merge decorative illumination with information display. Demand concentrates in premium passenger EV brands specifying contiguous visual environments, with manufacturing scale clustering in East Asian production corridors adjacent to display panel supply chains.
- Fiber Optic:Edge-lit polymer distribution enables sub-5mm section profiles for door panel integration.
- Neon:Gas-discharge tube technology persists in limited custom applications requiring distinct spectral signatures.
LED holds the largest share; momentum sits with OLED as display-illumination convergence accelerates.
Application:
Cost tier stratification separates bundled acoustic-haptic packages from standalone illumination modules.
- Dashboard:OLED surface illumination merges with digital cockpit displays to create contiguous visual environments. Premium EV platforms from German engineering centers adopt this approach for model year refreshes, expanding specification scope for optical-grade polymer and thin-film suppliers.
- Footwell:Acoustic and haptic integration with ambient light creates bundled feature packages commanding elevated module ASPs. Tier-1 suppliers target this segment for premium positioning where tactile feedback systems justify hardware complexity.
- Door Panels:Edge-lit fiber optic distribution supplants discrete LED arrays in luxury specifications.
- Headliner:Overhead illumination modules interface with body control modules via LIN bus protocols.
Dashboard applications command premium positioning; footwell integration is climbing the fastest as bundled feature packages expand.
End User:
Volume concentration sits with OEM direct procurement, while aftermarket channels fragment across standardized and custom specifications.
- OEMs:Direct specification of multi-zone programmable systems as standard equipment creates demand pull through engineering centers. China's NMPA vehicle safety guidelines and Europe's ECE R48 regulations shape homologation timelines for factory-installed modules.
- Tier-1 Suppliers:Integrated electronics-software control platforms for adaptive interior illumination anchor competitive positioning. Firmware and calibration services represent expanding addressable value as software-defined vehicle architectures redistribute control logic.
- Aftermarket Providers:Standardized monochrome systems serve rental and mobility-service operators.
- Custom Shops:Full RGB programmability targets private buyer preference for personalized cabin environments.
OEM direct procurement holds the largest share; Tier-1 supplier platforms are gaining share fastest as software-defined architectures expand.
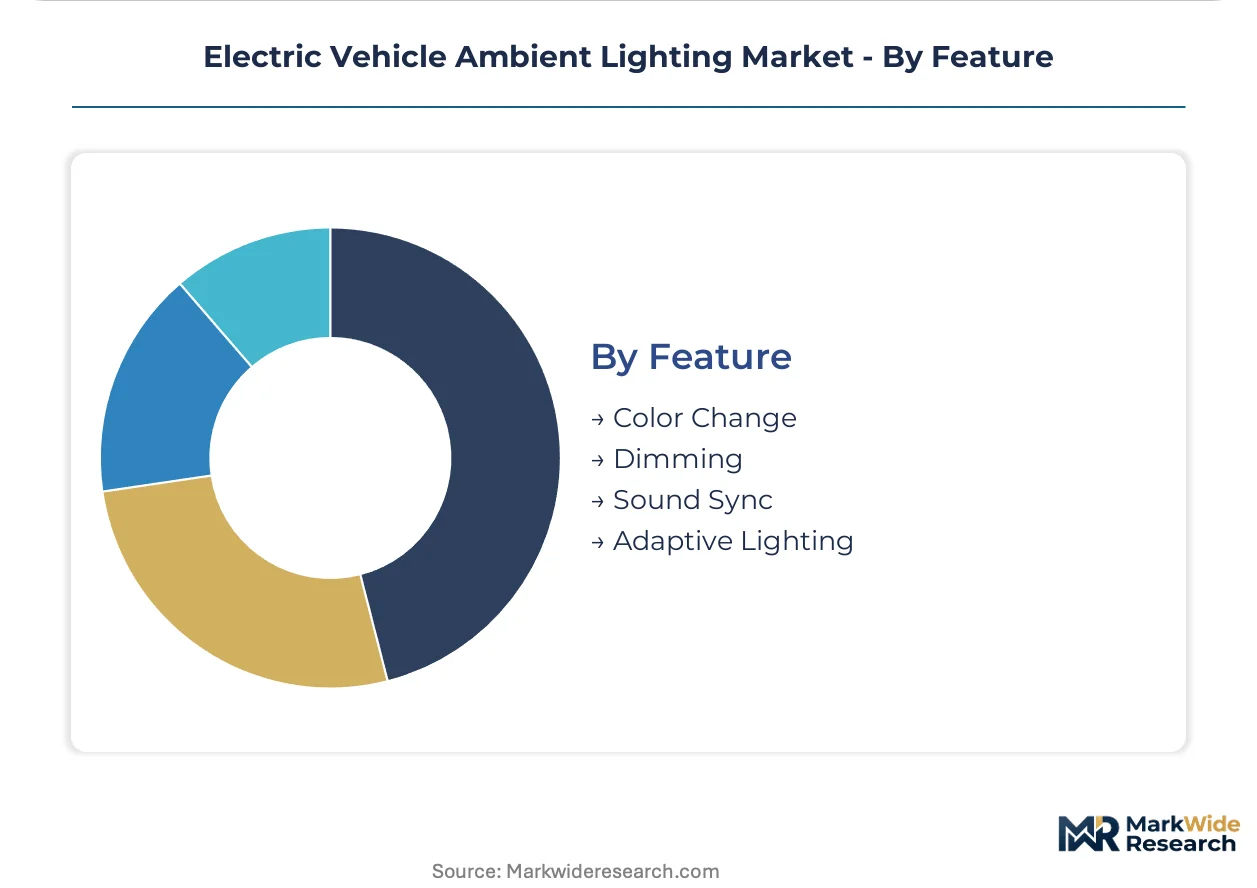
Feature:
Maturity differentiation separates established dimming functionality from emerging adaptive calibration systems.
- Color Change:RGB programmable specification tiers bifurcate the competitive landscape into premium system integrators and cost-optimized module suppliers. Multi-zone control via LIN or CAN bus protocols enables synchronized temperature shifts calibrated to occupant preference.
- Adaptive Lighting:Embedded software engineers calibrate dimming curves to driving modes, a capability concentrated at automotive electronics specialists. China's NMPA guidelines for driver alertness and Europe's ECE R48 intensity thresholds shape algorithm development.
- Dimming:Established functionality with standardized control curves across vehicle segments.
- Sound Sync:Audio-reactive illumination patterns integrate with infotainment system outputs.
Color change holds the largest share; adaptive lighting shows the steepest expansion trajectory as driving mode calibration becomes standard.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in EV ambient lighting components reveal concentrated manufacturing in East Asian corridors serving German engineering centers, with regulatory divergence between ECE R48 and China's NMPA guidelines fragmenting qualification pathways. Trade flows in LED dies and OLED panels track OEM specification tiers across premium and volume segments.
Germany
Munich and Stuttgart engineering centers specify multi-zone programmable ambient systems as standard equipment for premium passenger EV brands. ECE R48 lighting regulations govern interior light source placement and intensity, compressing homologation timelines for Tier-1 suppliers. Bavarian automotive clusters anchor cockpit module procurement for 2026 model year refreshes.
China
Domestic OEMs pre-qualify module variants through MIIT-registered testing laboratories under tightening NMPA vehicle safety guidelines. GB standards for vehicle electrical subsystems create localized qualification pathways for LED and OLED supply chains. Yangtze River Delta manufacturing corridors concentrate production scale for headlamp-adjacent ambient modules.
United States
FDA guidelines for driver alertness and distraction shape algorithm development for adaptive interior illumination systems. NHTSA regulatory frameworks influence interior light source safety thresholds, though federal preemption limits state-level fragmentation. Michigan and California engineering centers source standardized controllers for volume OEM programs.
Japan
METI industrial policy supports thin-film organic electroluminescent layer development for dashboard-illumination convergence. JIS standards provide baseline certification for LED thermal efficiency metrics. Kanto and Kansai manufacturing belts supply optical-grade polymers to German premium platforms.
South Korea
MFDS regulatory alignment with international photobiological safety standards accelerates spectral power distribution testing for blue-rich LED spectra. Seoul Capital Area electronics clusters integrate firmware calibration services with hardware module production. Domestic battery-electric vehicle platforms drive specification pull for RGB programmable systems.
Electric Vehicle Ambient Lighting Market Competitive Landscape
Listed leaders compete with private specialists across firmware calibration and hardware module supply, creating a tiered structure where scale-driven compound semiconductor producers coexist with niche optical polymer fabricators. The vendor base stratifies into premium system integrators, cost-optimized module suppliers, and integrated electronics-software platform providers. Dominant competitive moves include strategic partnerships around LIN bus protocol standardization and portfolio diversification into acoustic-haptic bundled feature packages.
Within the European premium tier, FORVIA HELLA and Valeo occupy positions anchored by established OEM relationships and integrated control platforms. Koito Manufacturing exemplifies the East Asian scale archetype with manufacturing concentration in LED-adjacent corridors. These three entities represent distinct strategic postures: European engineering proximity, software-hardware integration, and production scale leverage.
| Leading Market Players |
|---|
| FORVIA HELLA |
| Valeo |
| Koito Manufacturing |
| OSRAM GmbH |
| Grupo Antolin |
| Draxlmaier Group |
| Stanley Electric |
| Hyundai Mobis |
| Schott |
| Others |
Pricing and Supply Chain Analysis
REACH compliance for phosphor and rare-earth materials gates both supply qualification timelines and price differentiation across LED die tiers simultaneously. Certification overhead compounds for non-integrated compound semiconductor producers, compressing margins at the standard module tier while premium OLED integrators capture sustained ASP elevation through pre-qualified supply bases.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on ECE R48 certification grade and volume scale, with Munich and Stuttgart engineering centers paying premiums for pre-homologated modules. Cost compression in economy LED strips is intensifying because Asian manufacturing corridors are absorbing REACH qualification overhead into contract terms. Fleet procurement operators exhibit highest price sensitivity; private retail buyers through premium EV brands show least.
Supply Chain Analysis
Yangtze River Delta manufacturing corridors underwrite global LED die and OLED panel availability for cockpit module assembly. Production draws from China, South Korea, and Japan, with rare-earth phosphor feedstock anchored in domestic Chinese refining. Single-source vulnerability concentrates in thin-film organic electroluminescent deposition equipment. Distribution runs through Tier-1 integrated platform providers serving OEM direct procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined vehicle architectures are redistributing control logic toward central compute platforms, creating a platform-economics inflection where lighting module suppliers must capture firmware and calibration value or face hardware commoditization. Interoperability across LIN and CAN bus protocols is fragmenting competitive moats.
For Market Incumbents: Shield high-margin cockpit lighting programs by deepening firmware calibration capabilities before OEM central compute platforms absorb lighting ECU functions. Backward integration into compound semiconductor production mitigates REACH-driven phosphor cost volatility. Certification investment at MIIT-registered laboratories secures China NMPA pathway advantages against emerging Asian competitors.
For New Entrants and Emerging Players: Differentiate on acoustic-haptic bundling for footwell and door panel applications where tactile feedback integration commands premium module ASPs. White-space sits with aftermarket RGB programmability for private buyer customization, currently underserved by standardized fleet-oriented suppliers. Go-to-market through custom shop channels bypasses OEM homologation timeline compression.
For Investors and Strategic Acquirers: Carve-out targets emerge from automotive electronics divisions of diversified industrial conglomerates seeking portfolio simplification. Long-term viability favors suppliers with embedded software talent capable of adaptive dimming curve calibration. Watch ECE R48 revision scope expansion as inflection signal for qualification-capable asset premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Platform Integration | Captures value as OEM central compute platforms absorb lighting ECU functions. |
| Acoustic-Haptic Bundling | Creates premium feature packages for footwell and door panel applications. |
| MIIT Laboratory Pre-Qualification | Accelerates China NMPA homologation timelines for domestic supply chains. |
| Backward Integration into Phosphor | Reduces REACH compliance cost volatility for LED die production. |
| LIN Bus Protocol Standardization | Opens volume segments with simplified body control architectures. |
Research Methodology
A spread of perspectives from OEM platform engineers, Tier-1 supplier procurement leads, aftermarket distributors, and embedded software specialists converged on the working assumptions. Primary fieldwork combined with secondary validation against ECE R48 regulatory filings, NMPA safety guideline publications, vehicle production databases, and customs trade records. Bottom-up module demand estimates triangulated with top-down OEM specification analysis.
Segmentation dimensions modeled span product type, application, end-user channel, and feature complexity across the projection horizon. CAGRs derived from fitted growth curves applied to qualification timeline-adjusted adoption rates. Industry-specific forecast inputs include ECE R48 revision implementation schedules and MIIT laboratory certification throughput capacity.
Material uncertainties — NMPA guideline scope expansion, ECE R48 intensity threshold revisions, and software-defined architecture control redistribution — sit outside the modeled envelope. Forecasts reflect assumptions around homologation timeline stability and phosphor supply certification continuity. Practitioners should keep alternative scenarios live as regulatory divergence between European and Chinese qualification pathways evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
EV Eaxle Market
Electric Vehicles
Canada E-Bike Market
Electric Vehicles
Europe Electric Vehicle Market
Electric Vehicles
Electric Moped Market
Electric Vehicles
High Performance Battery Electric Vehicle Market
Electric Vehicles
ASEAN Countries Plug-In Hybrid Electric Vehicle Battery Market
Electric Vehicles
Electric Delivery Vans Market
Electric Vehicles
RV SLI Battery Market
Electric Vehicles
Poland E-Bike Market
Electric Vehicles
Electric Vehicle Electric Heating Film Market
Electric Vehicles
Central and Eastern Europe E-Bike Market
Electric Vehicles
Electric Two-Wheeler Market
Electric Vehicles
Electric Transporters Market
Electric Vehicles
Global Solar Powered Car Market
Electric Vehicles
Asia-Pacific Lithium-Ion Battery for Electric Vehicle Market
Electric Vehicles
Germany Electric Bus Battery Pack Market