
 Wireless Electric Vehicle Charging Market | 2026-2036
Wireless Electric Vehicle Charging Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Electric Vehicle Charging Market Intelligence
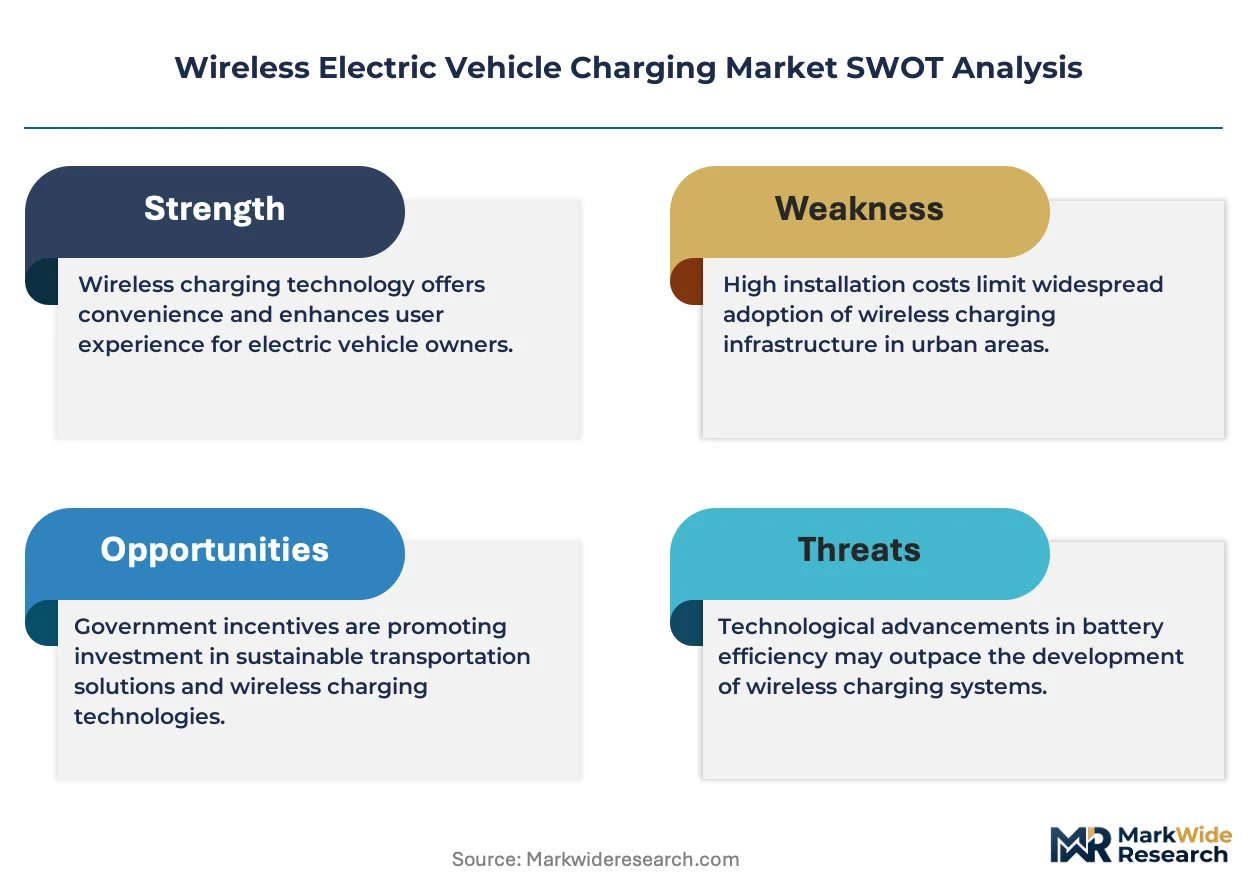
Advanced ferrite composites replacing traditional iron-based magnetic materials in charging pads is restructuring system efficiency and thermal management. This shift enables higher power transfer with less energy loss, a critical factor for commercial viability. WiTricity Corporation leverages its extensive intellectual property in magnetic resonance technology to secure partnerships with automotive OEMs. Meanwhile, Electreon Wireless Ltd. specializes in dynamic in-road charging systems, targeting public transportation routes in Sweden and Israel.
Wireless electric vehicle charging describes systems that transfer electrical energy to an EV's battery without a physical cable, using electromagnetic induction or magnetic resonance. These systems operate at frequencies typically in the 85 kHz band and are designed to achieve power transfer efficiencies above 90%. The primary purpose is to provide a convenient and automated charging experience. While Stationary Chargers for personal vehicles establish the market's base, Dynamic Chargers represent a high-growth frontier, particularly for commercial Fleet Vehicles requiring continuous operation.
Standardization is crucial for market development, with frameworks like SAE J2954 in the United States setting benchmarks for interoperability and safety. In parallel, China’s GB/T standards govern domestic charging protocols, while CE marking under European directives ensures product compliance for market access. These regulations are essential for building consumer confidence and enabling cross-vendor compatibility. The key strategic decision for stakeholders now centers on prioritizing investment in high-power static charging hubs versus deploying dynamic charging corridors.
Market Dynamics
The central force is the push for standardization, exemplified by SAE J2954, which unlocks interoperability but is constrained by the high capital investment required for widespread infrastructure deployment, particularly for dynamic charging systems.
Growth Catalysts
- Supportive Municipal Policies:Government mandates in geographies like China are accelerating the conversion of public transportation and municipal vehicle fleets to electric, creating large-scale, concentrated demand for automated charging solutions like wireless systems for electric buses.
- Technology Standardization:The maturation of technical standards, most notably SAE J2954, provides a common engineering framework for interoperability between vehicles and charging equipment from different manufacturers, building confidence for wider OEM and infrastructure investment.
- Operational Efficiency in Fleets:Commercial fleet applications, from logistics and delivery vans to public transit buses, benefit from the automated, hands-free nature of wireless charging, which reduces labor, minimizes downtime, and ensures high vehicle availability.
Market Restraints
- High Initial Capital Outlay:The cost of wireless charging systems, including ground pads, vehicle pads, and power electronics, is significantly higher than conventional Level 2 plug-in chargers, posing a barrier for individual consumers and small-scale deployments.
- Technical and Interoperability Gaps:Despite standards, challenges remain in ensuring seamless interoperability across different power levels, vehicle ground clearances, and alignment tolerances, which can impact charging efficiency and reliability in real-world conditions.
- Dominance of Conductive Charging:The existing and rapidly expanding infrastructure for plug-in DC fast charging presents a strong substitute, offering higher power transfer rates and a lower cost basis that satisfies the needs of most EV users.
Strategic Opportunities
- Retrofitting Commercial and Residential Buildings:A significant opportunity exists in equipping existing parking garages, corporate campuses, and multi-unit residential dwellings with stationary wireless chargers, offering a premium, convenient amenity for tenants and employees.
- Integration with Vehicle-to-Grid (V2G):Combining wireless charging with V2G capabilities allows parked EV fleets to act as distributed energy resources, providing grid stabilization services and creating new revenue streams for fleet operators from utility payments.
- Automated Logistics and Industrial Use:Targeting automated guided vehicles (AGVs), forklifts, and other machinery in controlled environments like warehouses, ports, and manufacturing plants represents a key opportunity for specialized, high-reliability wireless charging systems.
Industry Challenges
- Global Standards Harmonization:Aligning disparate regional standards, such as SAE J2954 in the US, GB/T standards in China, and emerging European norms, is a complex process that slows global product development and market entry for manufacturers.
- Infrastructure Investment Models:Securing funding for large-scale public infrastructure, especially capital-intensive dynamic in-road charging corridors, requires complex public-private partnerships and clear frameworks for return on investment that are still developing.
- Public Perception and Education:Overcoming end-user concerns regarding charging efficiency compared to plug-in methods, the safety of high-power magnetic fields, and the overall value proposition is critical for driving broader consumer adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Electric Vehicle Charging Market |
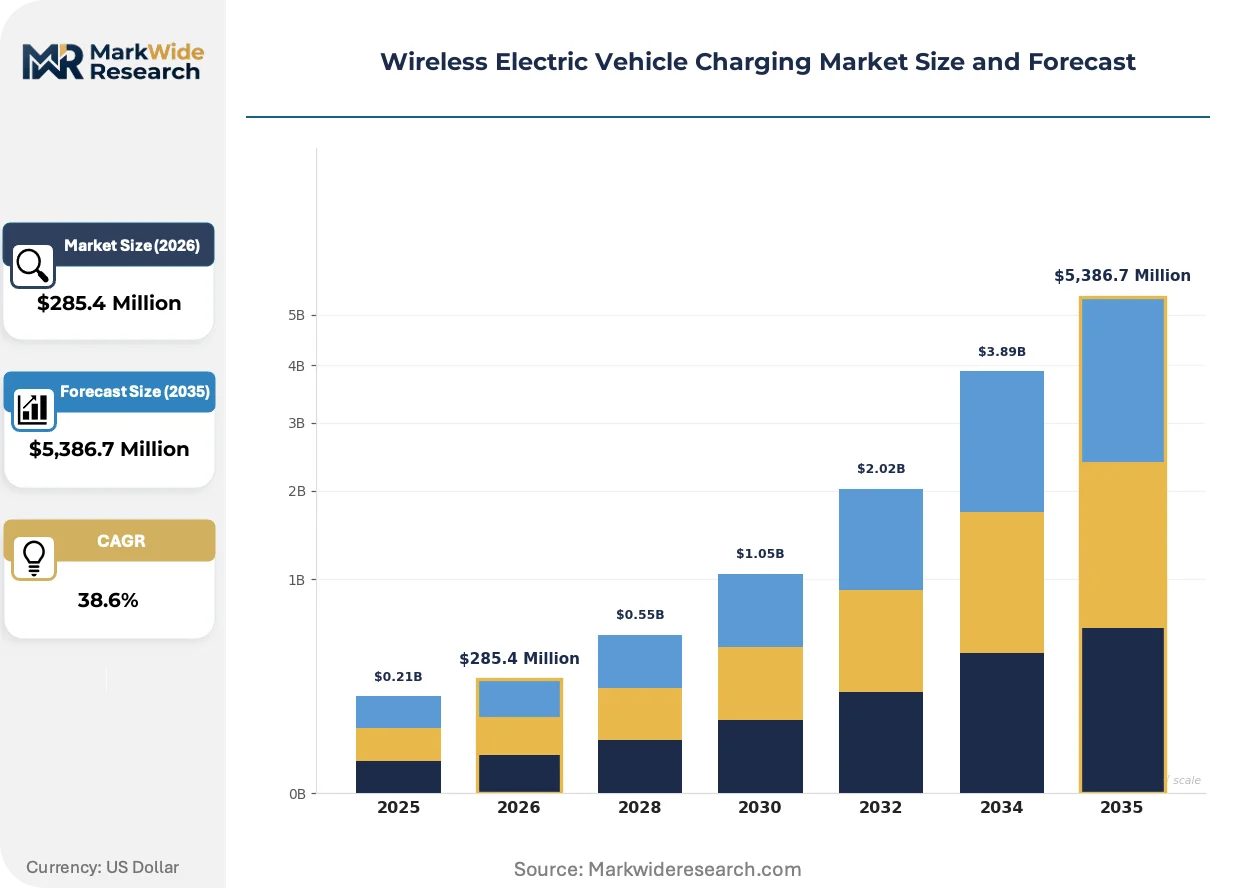
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $5,386.7 Million |
| CAGR (2026 – 2036) | 38.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stationary Chargers, Dynamic Chargers, Bidirectional Chargers, Portable Chargers Technology: Inductive Charging, Resonant Inductive Coupling, Radio Frequency Charging, Magnetic Resonance Application: Personal Vehicles, Fleet Vehicles, Public Transportation, Autonomous Vehicles End User Industry: Electric Mobility Providers, Ride Sharing Services, Logistics Companies, Municipal Transport Authorities |
| Companies Covered | WiTricity Corporation, InductEV Inc., Electreon Wireless Ltd., Plugless Power Inc., HEVO Inc., Robert Bosch GmbH, Continental AG, HELLA GmbH & Co. KGaA, Momentum Dynamics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Electric Vehicle Charging Market Strategic Shifts & Innovations
A transition from low-power convenience applications to high-power commercial systems defines the market's evolution. Advances in magnetic materials and power electronics are enabling systems capable of supporting heavy-duty vehicles and continuous fleet operations, moving beyond the passenger car segment.
Advanced ferrite composites are replacing iron-based materials in charging pads to improve heat dissipation and power transfer efficiency. Commercial fleet operators and public transit agencies are adopting these higher-performance systems for demanding duty cycles. This material innovation is electrifying key public transport routes and logistics depots by making high-power automated charging commercially viable.
Standardization under frameworks like SAE J2954 is creating a benchmark for interoperability between vehicle and charging pad manufacturers. This de-risks investment for infrastructure developers and clarifies design targets for automotive OEMs. The passenger and light commercial vehicle segments are most impacted, as compliance enables seamless charging across different public and private networks.
Procurement models are evolving from upfront capital expenditure on hardware to subscription-based Charging-as-a-Service (CaaS) contracts. This shift lowers the barrier to entry for fleet operators, converting large initial investments into predictable operating expenses. The CaaS model is gaining traction in European public transit projects, particularly for electric bus fleets in Sweden and Germany.
Wireless Electric Vehicle Charging Market Segmentation
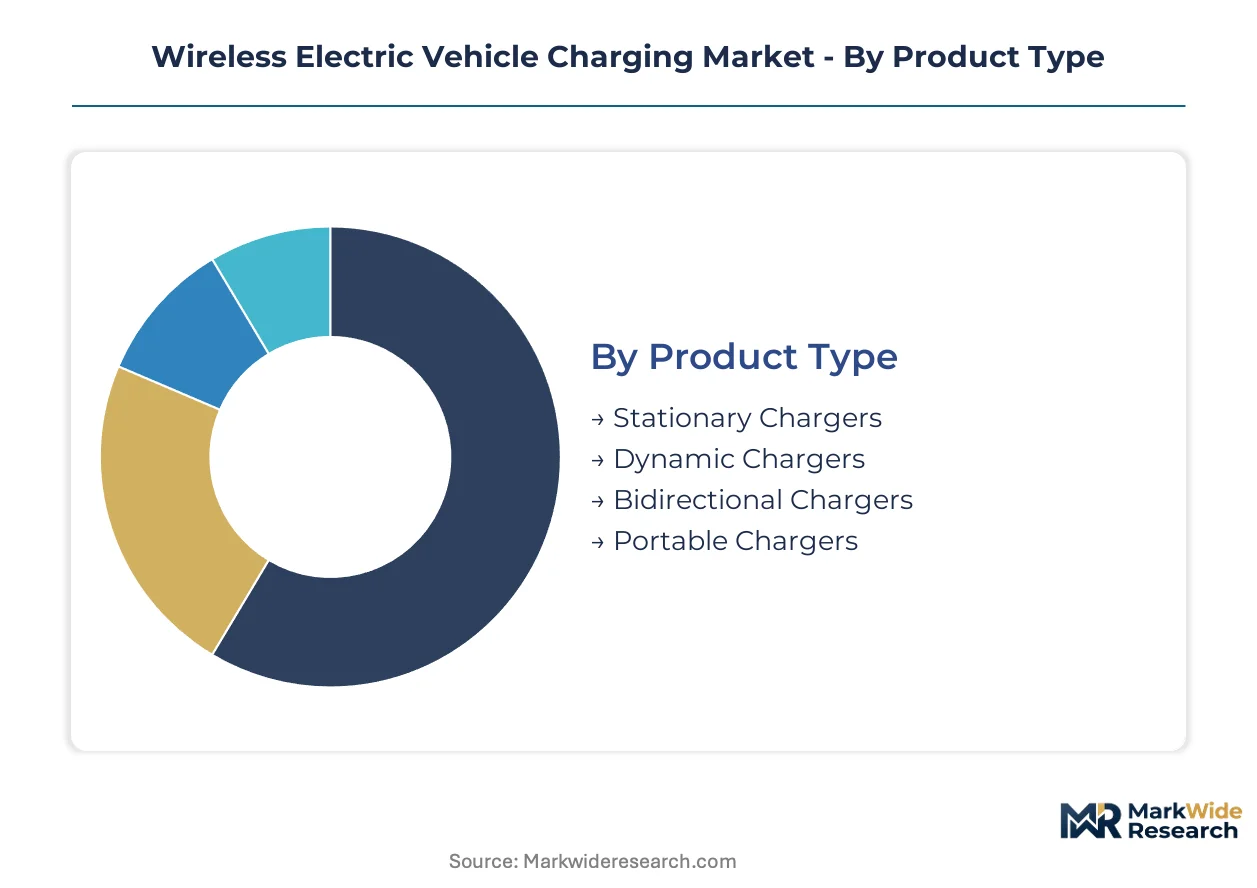
The Wireless Electric Vehicle Charging Market segmentation provides a structured view of diverse product offerings, underlying technologies, varied applications, and distinct end-user industries. Understanding these categories is essential for identifying areas of concentrated demand, technological leadership, and strategic investment within the evolving ecosystem.
Product Type:
The capital intensity of wireless charging infrastructure varies significantly across product types, with dynamic charging systems requiring substantial upfront investment for road integration.
- Stationary Chargers:These systems provide fixed-location charging for parked vehicles, typically installed in garages, parking lots, or commercial depots. Demand concentrates in private and commercial settings in the United States, supporting overnight charging and fleet depot operations.
- Dynamic Chargers:Dynamic systems enable in-motion charging while vehicles travel along specially equipped road segments, primarily targeting public transportation and heavy-duty logistics. Deployment is currently concentrated in pilot projects in Sweden and Israel, focusing on electric buses.
- Bidirectional Chargers:These advanced systems allow power flow in both directions, enabling vehicles to not only draw power from the grid but also feed electricity back, supporting Vehicle-to-Grid (V2G) applications. Grid operators in Germany are exploring these capabilities for grid stabilization.
- Portable Chargers:Compact and mobile wireless charging units offer flexible power delivery for emergency situations or temporary charging needs, providing convenience for personal EV owners.
Stationary Chargers absorb the bulk of installed capacity; Dynamic Chargers are expanding most quickly.
Technology:
Different technological approaches cater to specific power levels and operational environments, with some requiring more specialized infrastructure for effective deployment.
- Magnetic Resonance:This technology uses resonant inductive coupling at higher frequencies, allowing for greater misalignment tolerance and longer charging distances between the pad and vehicle. WiTricity Corporation leverages extensive intellectual property in this field for OEM partnerships.
- Inductive Charging:Inductive charging transfers energy through electromagnetic induction, requiring close proximity and precise alignment between coils. This method forms the foundation for many established wireless charging solutions, especially for lower power applications.
- Resonant Inductive Coupling:An evolution of inductive charging, this method utilizes resonant frequencies to improve efficiency and extend the air gap for power transfer compared to basic inductive systems.
- Radio Frequency Charging:RF charging converts electricity into radio waves for power transfer, offering potential for longer ranges but facing challenges with efficiency and regulatory constraints on power output.
The market exhibits a clear preference for Magnetic Resonance in high-power applications, while Inductive Charging is gaining market share for specific use cases.
Application:
The suitability of wireless charging solutions depends heavily on the operational demands and infrastructure requirements of the target application.
- Fleet Vehicles:Commercial fleets, including delivery vans and logistics trucks, benefit from automated, hands-free charging that minimizes downtime and optimizes operational efficiency. Demand is accelerating in China due to municipal policies supporting large-scale EV fleet conversion.
- Public Transportation:Electric buses and trams utilize wireless charging for automated, continuous operation along fixed routes, reducing the need for large on-board batteries. Electreon Wireless Ltd. specializes in dynamic in-road charging for public transit in Europe.
- Personal Vehicles:Wireless charging offers convenience for individual car owners, eliminating the need for physical cables in private garages and public parking spaces. Standardization efforts like SAE J2954 aim to improve interoperability for this segment.
- Autonomous Vehicles:Self-driving cars require automated charging solutions that integrate seamlessly with their autonomous operation, eliminating human intervention for plugging in.
Mass deployment in Fleet Vehicles drives significant volume, with Public Transportation showing the steepest expansion trajectory.
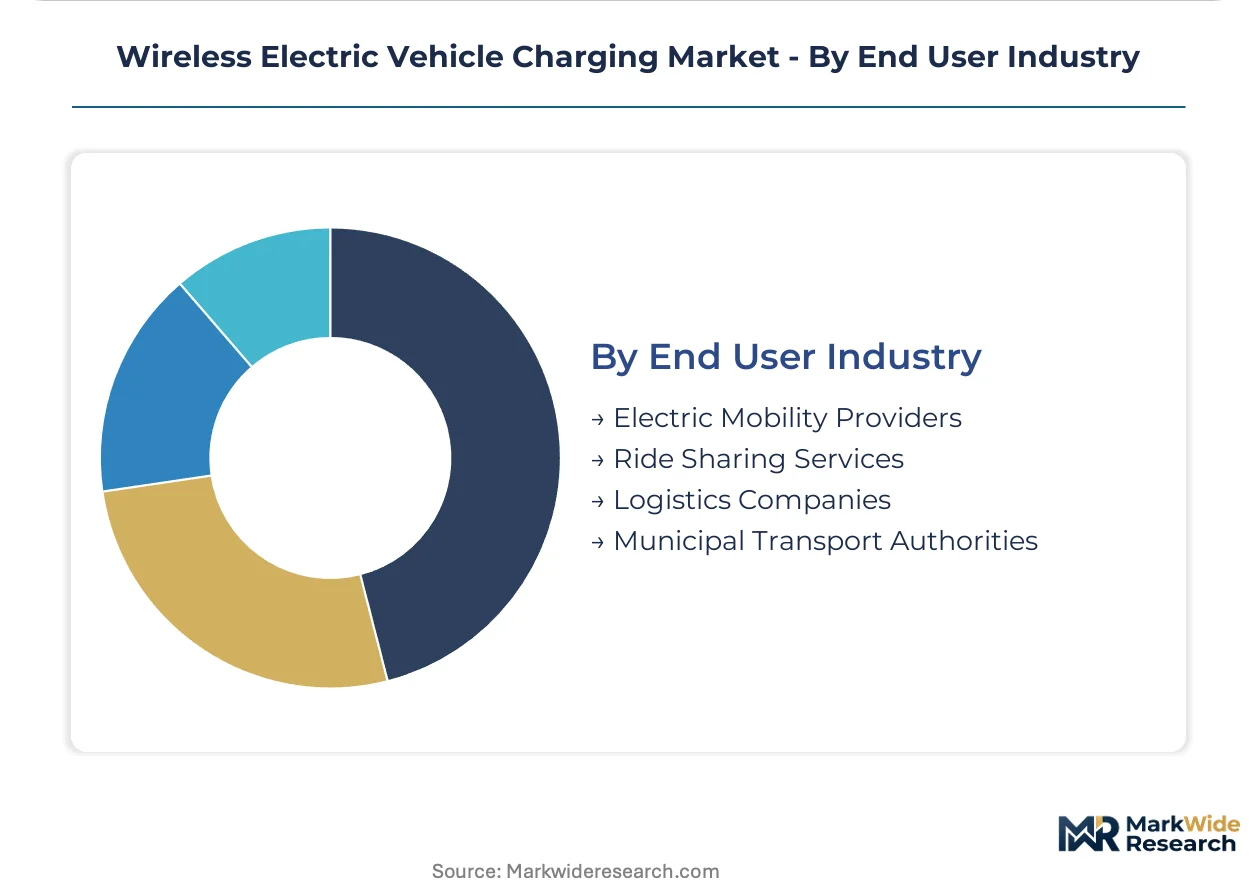
End User Industry:
Each end-user industry presents unique challenges and opportunities for wireless EV charging, driven by their operational models and regulatory environments.
- Municipal Transport Authorities:These entities manage public bus and tram fleets, requiring reliable, high-power wireless charging solutions to maintain service schedules and support fleet electrification mandates. China's municipal policies are a significant driver in this segment.
- Logistics Companies:Logistics and delivery firms seek wireless charging to maximize vehicle uptime, reduce labor costs associated with manual charging, and improve operational flow in depots and warehouses. Automated logistics in controlled environments represent a key opportunity.
- Electric Mobility Providers:Companies offering electric vehicle sharing, rental, or subscription services benefit from the convenience and automation of wireless charging to streamline vehicle turnover and maintenance.
- Ride Sharing Services:Operators of ride-sharing fleets can leverage wireless charging to ensure vehicles are always ready for service, reducing idle time and optimizing fleet utilization.
Municipal Transport Authorities represent the foundational customer base, whereas Logistics Companies demonstrate rapid adoption for efficiency gains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for wireless electric vehicle charging solutions concentrates significantly in regions actively promoting EV fleet conversion. Municipal policies supporting large-scale electric bus and logistics vehicle adoption drive this concentrated demand. These policies foster an environment for rapid infrastructure deployment and technological advancement across key urban centers.
China
Demand for wireless EV charging in China accelerates due to aggressive municipal policies for fleet electrification. The nation's GB/T standards govern domestic charging protocols, ensuring technical consistency and safety across deployments. Major cities like Shenzhen are implementing large-scale wireless charging pilots for public transport buses and logistics vehicles, showcasing significant investment.
United States
The United States observes growing demand for stationary wireless chargers within commercial depots and public parking facilities. The SAE J2954 standardization provides a crucial framework for interoperability and safety, building OEM confidence. California is seeing increased investment in wireless charging infrastructure for both personal vehicles and commercial fleet operations, driving market expansion.
Germany
Germany exhibits demand for high-power wireless charging systems, particularly for public transit and Vehicle-to-Grid (V2G) applications. CE marking under European directives ensures product compliance for market access and consumer trust. Urban centers like Berlin and Hamburg are exploring Charging-as-a-Service models for electric bus fleets, optimizing operational costs.
Sweden
Sweden demonstrates significant demand for dynamic in-road charging systems, focusing on public transportation routes. European directives for product compliance facilitate market entry for specialized wireless charging providers like Electreon. Stockholm is a key hub for pilot projects involving electric buses and taxis, proving operational viability.
Israel
Israel shows focused demand for dynamic wireless charging solutions, especially for urban public transportation networks. Domestic regulatory frameworks support the deployment of innovative EV charging technologies and infrastructure. Tel Aviv is actively implementing dynamic charging corridors for public buses, aiming for continuous vehicle operation.
Wireless Electric Vehicle Charging Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, reflecting varied market entry strategies. The wireless EV charging market currently exhibits a fragmented structure, with numerous technology developers and infrastructure providers. Strategic archetypes include core technology innovators, system integrators, and specialized infrastructure developers. Companies engage in strategic partnerships and technology licensing agreements to accelerate market penetration and de-risk investment.
Specialists in magnetic resonance technology, such as WiTricity Corporation, exemplify the core technology innovator archetype within the market. Electreon Wireless Ltd. represents a key player focusing on dynamic in-road charging systems for public transportation, showcasing specialized infrastructure development. The German-based Robert Bosch GmbH occupies a position among established automotive suppliers, diversifying into advanced charging solutions and leveraging its extensive industry presence and engineering capabilities. These companies collectively illustrate the diverse approaches to market entry and technology commercialization.
| Leading Market Players |
|---|
| WiTricity Corporation |
| InductEV Inc. |
| Electreon Wireless Ltd. |
| Plugless Power Inc. |
| HEVO Inc. |
| Robert Bosch GmbH |
| Continental AG |
| HELLA GmbH & Co. KGaA |
| Momentum Dynamics Corporation |
| Others |
Cost & Logistics Intelligence
Municipal Transport Authorities' procurement of wireless EV charging systems primarily follows a project-based pricing model. This structure reflects the high customization and infrastructure investment required for large-scale public transportation deployments.
Pricing Analysis
Volume-driven sales in the wireless EV charging market contrast with the high-margin bespoke projects. Project-based pricing dominates, influenced by system power output and the level of integration with existing infrastructure. Pricing softness emerges in the personal vehicle segment due to the cost competitiveness of plug-in alternatives. Commercial fleet operators are the least price-sensitive, valuing operational uptime and automation.
Supply Chain Analysis
Certification and qualification gating heavily influence the wireless EV charging supply chain, particularly for high-power systems. Supply for critical components concentrates in China and Germany, leveraging established electronics manufacturing bases. Advanced ferrite composites and specialized power electronics represent key material dependencies. Single-source vulnerability for niche high-power components poses a structural risk, while distribution runs through specialized system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wireless EV charging market is a vertical-integration race, with players actively pursuing control over both hardware manufacturing and software-defined charging services.
For Market Incumbents: Anticipate increased competition from specialized dynamic charging providers, necessitating strategic acquisitions in software and services. Incumbents should invest heavily in SAE J2954 compliance and expand their intellectual property portfolios in magnetic resonance technology. Capacity additions in key European markets will reinforce their market presence. This defends against emerging entrants offering lower-cost solutions.
For New Entrants and Emerging Players: Capture white-space opportunities in automated logistics and industrial use cases, where specialized high-reliability wireless charging systems are required. The most penetrable segment remains smaller commercial fleet depots, offering a clear value proposition for operational efficiency. A go-to-market angle focusing on Charging-as-a-Service (CaaS) models lowers initial capital outlay for customers.
For Investors and Strategic Acquirers: The window for entry favors strategic acquirers targeting niche technology developers with proven interoperability solutions. Long-term viability over the next decade hinges on widespread standardization and infrastructure build-out for dynamic charging. Watch for significant public-private partnerships in urban transit systems as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Standardization Compliance Investment | Ensures broad market access and interoperability for charging hardware and vehicle systems. |
| Magnetic Resonance IP Development | Secures a competitive advantage in high-power, high-efficiency wireless charging solutions. |
| Dynamic Charging Corridor Pilot Programs | Demonstrates real-world viability for continuous public transportation electrification. |
| Charging-as-a-Service (CaaS) Rollout | Lowers capital expenditure barriers for fleet operators, accelerating market adoption. |
| Integration with V2G Platforms | Unlocks new revenue streams and grid stabilization services for EV fleet owners. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this market analysis. Primary interviews were conducted with EV charging infrastructure developers, automotive OEM engineers, public transport fleet managers, and material science experts. This approach combined qualitative insights with quantitative data, triangulating findings from bottom-up and top-down perspectives.
The analytical framework reconciled disparate data streams to project market trajectories across the analysis window. Segmentation dimensions modeled included product type, technology, application, end-user industry, and regional adoption patterns. Compound annual growth rates were derived from historical data trends and projected adoption curves. Key forecast inputs included EV sales forecasts and infrastructure investment commitments.
The model holds under current regulatory and technological development assumptions; deviation in standardization timelines or material cost fluctuations would shift projections. Forecasts reflect assumptions documented through expert consensus and historical market behavior. A model refresh is warranted upon material change in government electrification mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Bike Kit Market
Electric Vehicles
Folding E-Scooter Market
Electric Vehicles
Electric Vehicle High-Voltage DC-DC Converter Market
Electric Vehicles
Electromagnetic and Radio Frequency Interference Coating for Electric Vehicles Market
Electric Vehicles
Electric Vehicle (EV) Coating Market
Electric Vehicles
Fuel-Cell Electric Vehicle Insulation Market
Electric Vehicles
South America Automotive High Performance Electric Vehicles Market
Electric Vehicles
RV SLI Battery Market
Electric Vehicles
Global Automotive Lithium Ion Battery Controller Market
Electric Vehicles
Global Electric Vehicles Market
Electric Vehicles
Global Electric All Wheel Drive (AWD) Market
Electric Vehicles
Norway E-Bike Market
Electric Vehicles
US Electric Vehicle Market
Electric Vehicles
Saudi Arabia Electric Vehicle Market
Electric Vehicles
Electric Light Commercial Vehicle Lithium-Ion Battery Market
Electric Vehicles
E-SUV Market