
 Electric Vehicle Lithium-Ion Battery Market | 2026-2036
Electric Vehicle Lithium-Ion Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Lithium-Ion Battery Market Foresight
China's Jiangsu province is rewriting the geography of lithium-ion cell manufacturing through multi-gigawatt expansions along the Yangtze River Delta. CATL leverages vertical integration from cathode materials to finished packs, sustaining cost advantages across the value chain. LG Energy Solution anchors its competitiveness through high-nickel NMC chemistry leadership in European and North American supply contracts. BYD Co. Ltd. differentiates through blade-shaped LFP cell architectures that eliminate module-level assembly.
An electric vehicle lithium-ion battery stores electrochemical energy through lithium-ion shuttling between a graphite anode and a metal-oxide cathode, typically operating at nominal voltages of 3.2–3.7 V per cell depending on chemistry, with energy densities reaching 250–300 Wh/kg in advanced NMC formulations. Its primary commercial purpose is to deliver sustained high-discharge power for electric traction motors while maintaining cycle life across thousands of charge events. NMC chemistry dominates premium passenger vehicle applications where volumetric energy density commands priority, while LFP chemistry leads in commercial vehicle and entry-level passenger segments where thermal stability and cost structure outweigh gravimetric targets. Cell assembly as a manufacturing stage concentrates the highest capital intensity and technical barrier, attracting the majority of margin capture and strategic investment.
China's NMPA enforces mandatory battery safety testing protocols including nail penetration and thermal runaway propagation standards that shape cell design architecture. The EU Green Deal's battery passport requirements and ECHA REACH substance restrictions are forcing cathode material suppliers to document full supply chain provenance and eliminate restricted substances. The US IRA domestic content incentives are restructuring where final pack assembly occurs relative to cell origin. Stakeholders must monitor how regulatory divergence between these jurisdictions fragments testing certification regimes and alters localization economics for new capacity decisions.
Market Dynamics
Passenger vehicle electrification is compressing cell development cycles while China's NMPA safety mandates and Europe's EU Green Deal sustainability rules are forcing simultaneous redesigns of thermal management architectures and supply chain documentation systems.
Growth Catalysts
- High-Nickel Cathode Chemistry:Automakers pursuing extended-range electric vehicles are specifying NMC 811 and 9-series formulations that deliver volumetric energy densities above 700 Wh/L.
- EU Green Deal Battery Passport Mandate:Full lifecycle traceability requirements are accelerating investment in digital twin platforms and blockchain-enabled provenance tracking across European supply chains.
- Jiangsu-Fujian Manufacturing Corridor Concentration:Agglomeration of cathode precursor, separator, and electrolyte production within 200 kilometers of cell assembly plants is compressing logistics costs and lead times.
Market Restraints
- Lithium Carbonate Price Volatility:Spot market fluctuations for battery-grade lithium salts are compressing margin visibility and forcing long-term offtake contracting at fixed premiums.
- Graphite Anode Supply Concentration:China's dominance in spherical natural graphite processing and synthetic graphite production creates single-source vulnerability for non-Chinese cell manufacturers.
- Cell-to-Pack Thermal Runaway Containment:Current ceramic fiber and aerogel barrier technologies add mass and volume penalties that offset gravimetric gains from advanced cathode chemistries.
Strategic Opportunities
- Sodium-Ion Chemistry Convergence:Hard carbon anode and Prussian white cathode formulations are reaching commercial scale for stationary storage and entry-level urban mobility applications where energy density requirements are relaxed.
- US IRA Domestic Content Incentives:Tax credit eligibility thresholds are pulling final pack assembly and active material production toward North American free trade agreement territories.
- Second-Life Battery Aggregation Platforms:Retired electric vehicle cells with 70-80% remaining capacity are feeding into grid-scale stationary storage through standardized testing and reconfiguration protocols.
Industry Challenges
- Dry Electrode Coating Process Engineering:Scaling solvent-free binder deposition for silicon-anode compatibility requires novel calendering equipment and contamination control systems that extend qualification timelines.
- Multi-Jurisdiction Certification Parallel Processing:Simultaneous pursuit of China's GB/T, UN 38.3 transport, and UL 9540A thermal runaway propagation testing is stretching technical documentation teams and capital allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Lithium-Ion Battery Market |
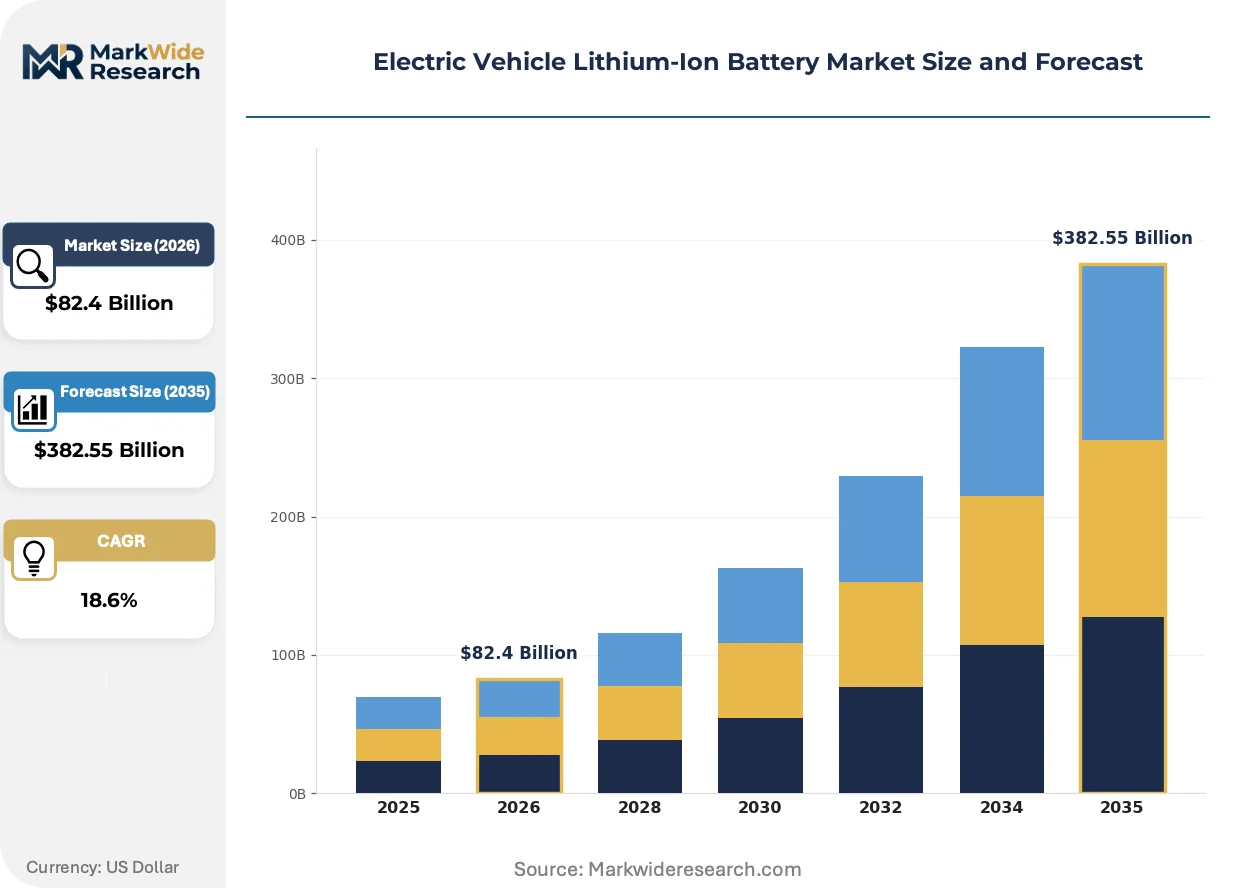
| Market Size in 2026 | $82.4 Billion |
| Market Size in 2035 | $382.55 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: LFP, NMC, NCA, LCO Application: Passenger Vehicles, Commercial Vehicles, E-Bikes, Marine End User: OEMs, Renewable Energy, Fleet Operators, Aftermarket Providers Manufacturing Process: Cell Assembly, Pack Assembly, Module Production, Recycling |
| Companies Covered | Contemporary Amperex Technology Co. Limited (CATL), LG Energy Solution, BYD Co. Ltd., Panasonic Holdings Corporation, Samsung SDI, SK On, CALB, Gotion High-Tech, EVE Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Lithium-Ion Battery Market Shifts & Advancements
Cell architecture standardization is colliding with chemistry diversification as manufacturers attempt to serve multiple vehicle platforms from common production lines while meeting divergent regional regulatory requirements.
Solid-state electrolyte development is migrating from sulfide-based formulations toward oxide and halide chemistries that promise improved air stability and reduced manufacturing complexity. Korean and Japanese cell producers are piloting these materials in premium sedan battery packs scheduled for validation cycles. The shift is compressing the competitive window for incumbent liquid electrolyte suppliers.
Europe's ECHA REACH substance restrictions are forcing cathode material suppliers to eliminate cobalt sourcing from conflict-affected regions and document full smelter provenance through third-party audit trails. The regulation is raising compliance costs for NMC chemistry producers while accelerating LFP chemistry qualification for European original equipment manufacturer supply contracts.
Fleet operators and energy service companies are consolidating procurement through multi-year service agreements that bundle cell supply, thermal management hardware, and end-of-life recycling obligations into single per-kilowatt-hour pricing structures. This unbundling of capital expenditure from operational risk is most visible in North American commercial vehicle and European bus electrification programs.
Electric Vehicle Lithium-Ion Battery Market Segmentation
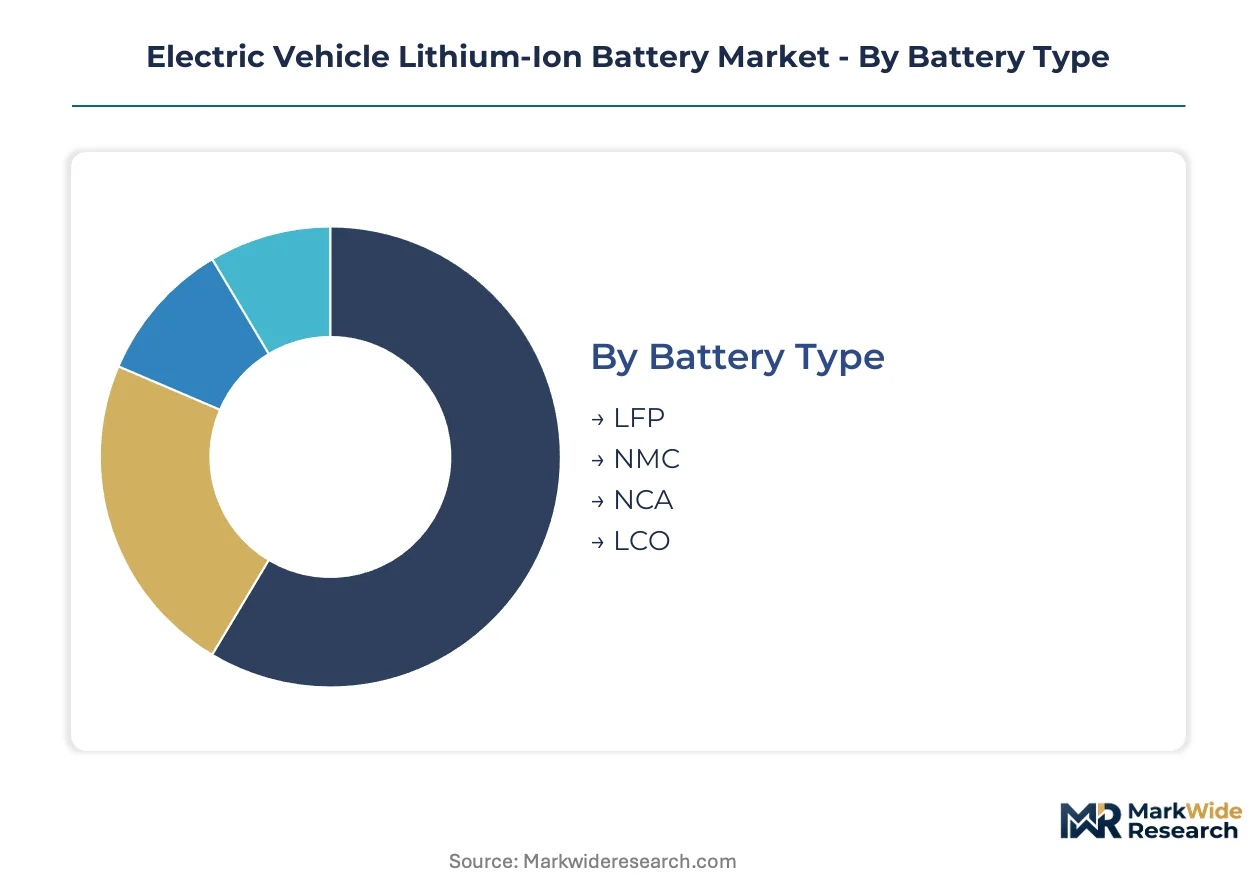
Battery chemistry and application architecture define procurement patterns across the electric vehicle value chain. Segmentation reveals how cathode material selection and manufacturing stage intensity concentrate margin capture differently across passenger, commercial, and emerging mobility platforms.
Battery Type:
Mature NMC formulations dominate premium automotive contracts while emerging LFP architectures displace nickel-dependent systems in cost-sensitive segments.
- LFP:Lithium iron phosphate chemistry operates at 3.2V nominal with olivine crystal cathode structure, delivering superior thermal stability and cycle life above 3,000 cycles. BYD's blade cell format eliminates module assembly, concentrating demand in China's entry-level passenger and commercial bus segments where NMPA safety certification favors iron phosphate stability.
- NMC:Nickel-manganese-cobalt layered oxide cathodes achieve 250-300 Wh/kg gravimetric density in 811 and 9-series formulations. European OEMs specify high-nickel variants for extended-range sedans where EU Green Deal battery passport requirements force cobalt provenance documentation through ECHA REACH audit trails.
- NCA:Nickel-cobalt-aluminum oxide delivers highest volumetric energy density among commercialized chemistries, serving premium performance segments.
- LCO:Lithium cobalt oxide retains niche positioning in specialty applications requiring maximum energy density at cell level.
LFP retains volume leadership; NMC holds the steepest expansion curve.
Application:
Cost tier stratification separates high-capacity passenger platforms from standardized commercial vehicle specifications.
- Passenger Vehicles:Battery electric and plug-in hybrid platforms specify 60-100 kWh packs with cell-to-pack architectures, driving demand in Jiangsu province where CATL's vertical integration from cathode precursor to finished assembly compresses lead times.
- Commercial Vehicles:Electric buses and delivery trucks prioritize LFP chemistry for 8-12 year operational life, with procurement concentrating through fleet operators bundling thermal management hardware and end-of-life recycling obligations.
- E-Bikes:Compact 0.5-2 kWh packs favor cylindrical cell formats with simplified battery management systems.
- Marine:Electric propulsion systems for harbor craft and short-route ferries require IP67-rated enclosures with salt corrosion resistance.
Passenger vehicles absorb the majority of cell output; commercial vehicles are gaining share fastest.
End User:
Customer type determines contract structure complexity from long-term offtake agreements to spot market procurement.
- OEMs:Automakers negotiate multi-year supply contracts with pricing indexed to lithium carbonate spot markets, requiring cell producers to maintain dual certification under China's GB/T and UN 38.3 transport standards.
- Renewable Energy:Grid-scale storage integrators source second-life EV cells through standardized testing protocols, aggregating retired packs with 70-80% remaining capacity.
- Fleet Operators:Logistics companies procure through service agreements unbundling capital expenditure from operational risk.
- Aftermarket Providers:Independent repair networks source replacement packs through distributor channels with warranty transfer requirements.
OEMs command the largest contract volumes; renewable energy integrators show the steepest expansion trajectory.
Manufacturing Process:
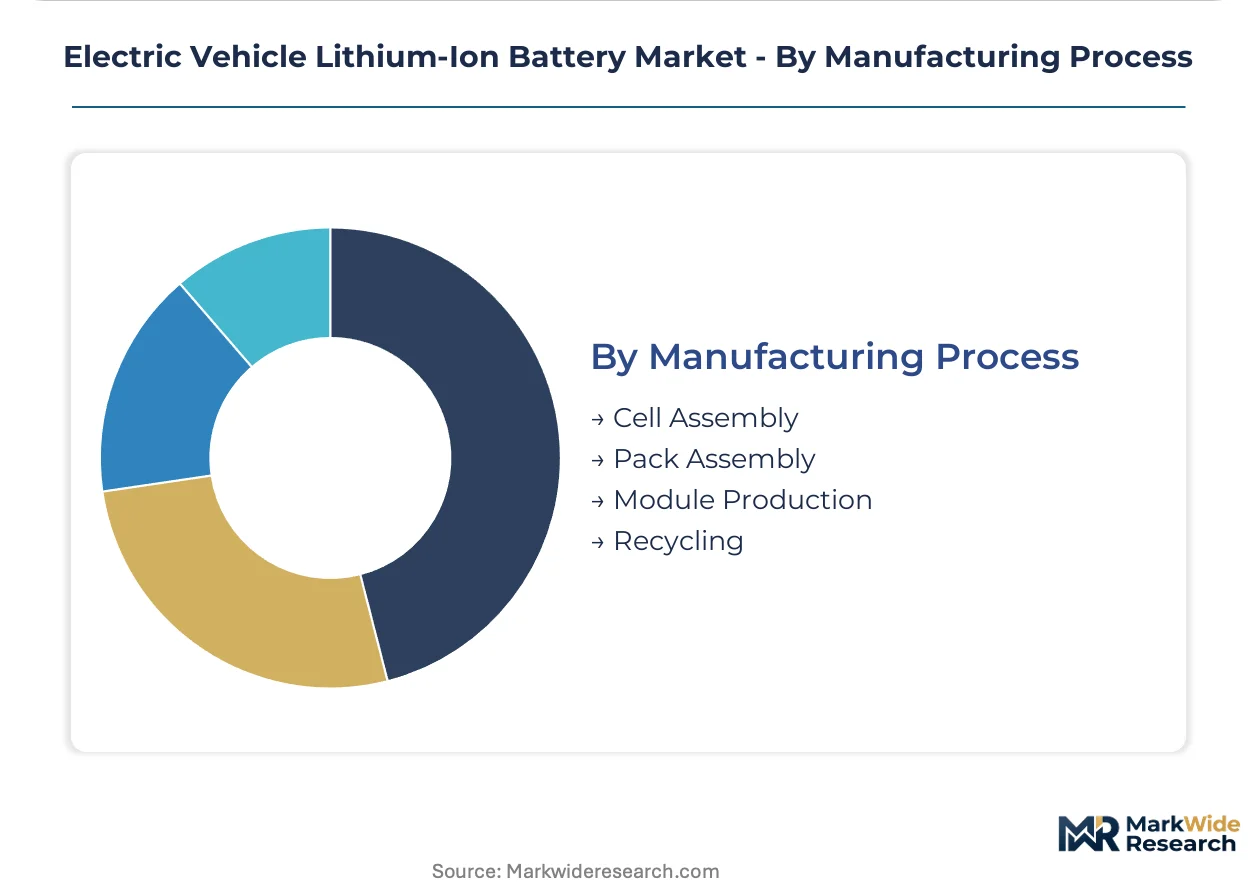
Supply concentration varies dramatically across value chain stages, with cell assembly capturing disproportionate capital investment.
- Cell Assembly:Electrode coating, winding or stacking, electrolyte filling, and formation cycling concentrate 60-70% of manufacturing capital intensity, attracting strategic investment to Jiangsu and Fujian corridors where cathode precursor, separator, and electrolyte suppliers cluster within 200 kilometers.
- Pack Assembly:Module integration, thermal management hardware installation, and battery management system programming occur closer to final vehicle assembly plants, with US IRA domestic content incentives restructuring North American localization decisions.
- Module Production:Intermediate cell grouping into standardized units is being bypassed by cell-to-pack architectures.
- Recycling:Hydrometallurgical and pyrometallurgical recovery of lithium, nickel, and cobalt is scaling to meet EU Green Deal end-of-life recovery mandates.
Cell assembly anchors margin capture; recycling demonstrates the steepest capacity expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's NMPA battery safety certification anchors the dominant geography where Jiangsu and Fujian provinces concentrate cathode precursor, separator, and electrolyte production within 200 kilometers of cell assembly plants. Regulatory divergence between Beijing, Brussels, and Washington is fragmenting testing certification regimes and altering localization economics for new capacity decisions.
China
Passenger vehicle electrification and commercial bus fleet procurement are compressing cell development cycles. NMPA enforces mandatory nail penetration and thermal runaway propagation standards that shape cell design architecture. Jiangsu province along the Yangtze River Delta hosts multi-gigawatt expansions where CATL leverages backward integration from cathode materials to finished packs.
Germany
European OEMs specify high-nickel NMC 811 and 9-series formulations for extended-range sedans. ECHA REACH substance restrictions force cobalt provenance documentation and full smelter audit trails through third-party verification. The industrial corridor around Stuttgart and Munich is attracting pack assembly investment to satisfy EU Green Deal battery passport requirements.
United States
IRA domestic content incentives are restructuring where final pack assembly occurs relative to cell origin. Tax credit eligibility thresholds pull active material production toward North American free trade agreement territories. Michigan and Tennessee are emerging as pack integration hubs serving Detroit automakers and southeastern vehicle assembly plants.
South Korea
Korean cell producers are piloting oxide and halide solid-state electrolyte formulations in premium sedan battery packs. METI-equivalent standards and KTL certification requirements govern cell export qualification. The Gyeonggi-do and Chungnam provinces concentrate electrode coating and formation cycling capacity serving European and North American supply contracts.
Japan
Japanese manufacturers retain chemistry leadership in silicon-anode compatibility and solvent-free binder deposition processes. METI oversees battery safety standards alignment with UN 38.3 transport protocols. The Kansai region around Osaka maintains specialized formation cycling and aging test facilities for high-performance automotive contracts.
Electric Vehicle Lithium-Ion Battery Market Competitive Landscape
Capability concentration sits with chemistry specialists; scale advantage sits with integrated producers. The market structures around three tiers: vertically integrated conglomerates controlling precursor-to-pack value chains, pure-play cell manufacturers serving multiple OEMs under long-term offtake contracts, and materials specialists supplying cathode active powders and electrolyte formulations. Dominant competitive moves include capacity expansion in tariff-advantaged jurisdictions and strategic partnerships securing lithium carbonate offtake at fixed premiums.
Among Asia-Pacific-based integrated producers, Contemporary Amperex Technology Co. Limited exemplifies the vertically integrated archetype through captive cathode material production. LG Energy Solution occupies a position representing high-nickel chemistry leadership in premium automotive supply contracts. BYD Co. Ltd. anchors the diversified conglomerate tier with blade-shaped cell architectures that eliminate module-level assembly.
| Leading Market Players |
|---|
| Contemporary Amperex Technology Co. Limited (CATL) |
| LG Energy Solution |
| BYD Co. Ltd. |
| Panasonic Holdings Corporation |
| Samsung SDI |
| SK On |
| CALB |
| Gotion High-Tech |
| EVE Energy |
| Others |
Supply & Pricing Matrix
The Yangtze River Delta freight corridor compresses cathode precursor logistics costs by 15-20% relative to inland routes, concentrating pricing power among Jiangsu-based cell producers while forcing European and North American buyers to absorb ocean freight premiums and tariff exposure. This geographic asymmetry feeds three-tier pricing stratification across premium NMC, standard LFP, and economy-grade commercial vehicle specifications.
Pricing Analysis
Price spreads between Jiangsu-origin cell contracts and European pack-assembly quotes exceed 30% on a per-kilowatt-hour basis, reflecting lithium carbonate offtake premiums and EU Green Deal compliance documentation costs. Contract-based long-term offtake dominates OEM procurement, with price differentiation hinging on volume scale and NMPA versus UL 9540A certification tier. Cost compression in entry-level LFP segments is intensifying because BYD's blade cell format eliminates module assembly overhead. Fleet operators show highest price sensitivity; premium sedan OEMs prioritize energy density over unit cost.
Supply Chain Analysis
CATL, LG Energy Solution, and BYD control 70% of global cell assembly capacity, with electrode coating and formation cycling concentrated in Gyeonggi-do, Chungnam, and Jiangsu provinces. The supply chain draws from Australian spodumene, Chilean lithium brine, and Chinese spherical graphite processing. Single-source vulnerability in synthetic anode production creates chokepoint risk. Distribution runs through long-term offtake contracts with automakers rather than spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell producers with captive cathode material capabilities command sustainable margin positions, while pure-play manufacturers face margin compression from lithium salt volatility and certification cost fragmentation. The scarcest capability is dry electrode coating process engineering for silicon-anode compatibility.
For Market Incumbents: Build chemistry-format lock-in through proprietary cell-to-pack architectures that embed thermal management IP. Secure lithium carbonate offtake at fixed premiums through direct offtake from Australian and Chilean producers. Add formation cycling capacity in tariff-advantaged jurisdictions to satisfy US IRA domestic content thresholds. For New Entrants and Emerging Players: Establish a beachhead in second-life battery aggregation for grid-scale storage, where standardized testing protocols lower technical barriers. Target renewable energy integrators with 70-80% state-of-health cells bypassing automotive certification requirements. Lead with battery-as-a-service pricing that unbundles capital expenditure from operational risk. For Investors and Strategic Acquirers: Solid-state electrolyte specialists with oxide and halide chemistry pilots represent the highest-conviction acquisition archetype. Long-term viability hinges on chemistry transition timing rather than incumbent scale advantages. Monitor Korean and Japanese cell producer validation cycle announcements as inflection indicators for liquid electrolyte displacement.| Strategic Initiative | Industry Significance |
|---|---|
| High-Nickel Cathode Capacity Expansion | NMC 811 and 9-series production lines satisfy European OEM extended-range sedan contracts under ECHA REACH audit requirements. |
| Backward Integration into Lithium Carbonate | Direct offtake agreements with Australian spodumene and Chilean brine producers hedge against spot market volatility. |
| Cell-to-Pack Architecture Standardization | BYD's blade format and CATL's CTP designs eliminate module assembly, compressing manufacturing capital intensity by 20-30%. |
| Second-Life Battery Aggregation Platform | Retired EV cells with 70-80% remaining capacity feed grid-scale storage through standardized testing and reconfiguration protocols. |
| Dry Electrode Coating Process Scale-Up | Solvent-free binder deposition for silicon-anode compatibility reduces energy consumption and extends cycle life in premium applications. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with cell manufacturing executives, cathode material procurement leads, OEM platform engineers, and thermal management system designers; and secondary validation against SEC filings, Chinese customs trade data, UN Comtrade lithium carbonate flows, and NMPA certification registries. Bottom-up cell production estimates triangulated against top-down vehicle electrification forecasts.
Forecast inputs span battery chemistry, vehicle class, manufacturing process stage, and regional regulatory cluster across the analysis window. Segmentation dimensions include NMC versus LFP versus solid-state chemistry, passenger versus commercial application, and cell assembly versus pack assembly versus recycling value capture. CAGRs derive from vehicle production database trajectories, lithium carbonate demand elasticity modeling, and policy incentive phase-out schedules.
Sensitivities concentrate around lithium carbonate spot price volatility, NMPA-EU Green Deal regulatory divergence, and solid-state electrolyte commercialization timelines. Forecasts embed assumptions regarding IRA domestic content threshold enforcement and ECHA REACH substance restriction expansion. Quarterly review of cathode precursor pricing, cell production utilization rates, and OEM platform launch delays is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Speed Pedelec E-Bike Market
Electric Vehicles
Automotive Intelligent Battery Sensor Market
Electric Vehicles
Latin America Automotive High Performance Electric Vehicle Market
Electric Vehicles
UK Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
Denmark Solar E-Bike Market
Electric Vehicles
Solar Golf Cart Market
Electric Vehicles
Lawn Mower Battery Market
Electric Vehicles
Electric Loader Rickshaw Market
Electric Vehicles
Europe Electric Vehicle Market
Electric Vehicles
Electric Shuttle Market
Electric Vehicles
Electric Commercial Vehicle Market
Electric Vehicles
Electric Pickup Truck Market
Electric Vehicles
Global Electric Scooter Lift and Carrier Market
Electric Vehicles
Vehicle Electrification Market
Electric Vehicles
Electric Vehicle Regenerative Braking System Market
Electric Vehicles
Vehicle Battery Market