
 Europe Electric Vehicle Market | 2026-2036
Europe Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Electric Vehicle Market Intelligence
CE marking under the EU Machinery Directive is rotating as the primary gating mechanism for charging infrastructure manufacturers seeking market access. Volkswagen leverages its MEB platform architecture to sustain modular production across multiple European plants. BMW anchors its position through vertical integration into battery cell competence centers in Germany and Hungary. Tesla competes on software-defined vehicle architecture and supercharger network density across the continent.
Europe electric vehicles encompass battery-electric, plug-in hybrid, and fuel-cell platforms designed for zero-tailpipe-emission propulsion, typically operating at 400-800V architectures with lithium-ion cell packs exceeding 60 kWh usable capacity. Battery Electric Vehicles dominate volume flows as OEMs phase out internal combustion engineering capacity, while Fast Chargers within charging infrastructure command disproportionate capital allocation due to highway corridor completion mandates. Fleet Operators represent the fastest-growing end-user category as logistics providers electrify last-mile delivery under contract sustainability requirements.
EU Green Deal carbon neutrality targets, ECHA REACH chemical compliance for battery materials, and CE marking under the EU Machinery Directive collectively shape product standards and market access conditions across member states. EMA and national type-approval authorities in Germany, France, and the Netherlands enforce divergent homologation timelines that fragment launch sequencing. Stakeholders must monitor regulatory divergence between EU-wide frameworks and accelerating national ICE phase-out schedules to calibrate production and distribution priorities.
Market Dynamics
The EU Green Deal's CO2 fleet emission targets are compressing manufacturer timelines and forcing wholesale platform redesigns across European automotive engineering centers. This regulatory pressure cascades through supplier tiers, battery chemistry selection, and charging infrastructure deployment schedules.
Growth Catalysts
- Fleet electrification mandates:Logistics operators under contract sustainability requirements from retail and e-commerce anchors are accelerating zero-emission vehicle procurement for last-mile delivery corridors.
- EU Machinery Directive CE marking:Standardized market access protocols for charging infrastructure manufacturers are reducing fragmentation across member state approval processes.
- Lithium-ion cell scale-up:Gigafactory investments in Germany, Hungary, and Poland are compressing battery pack cost curves and securing regional supply.
Market Restraints
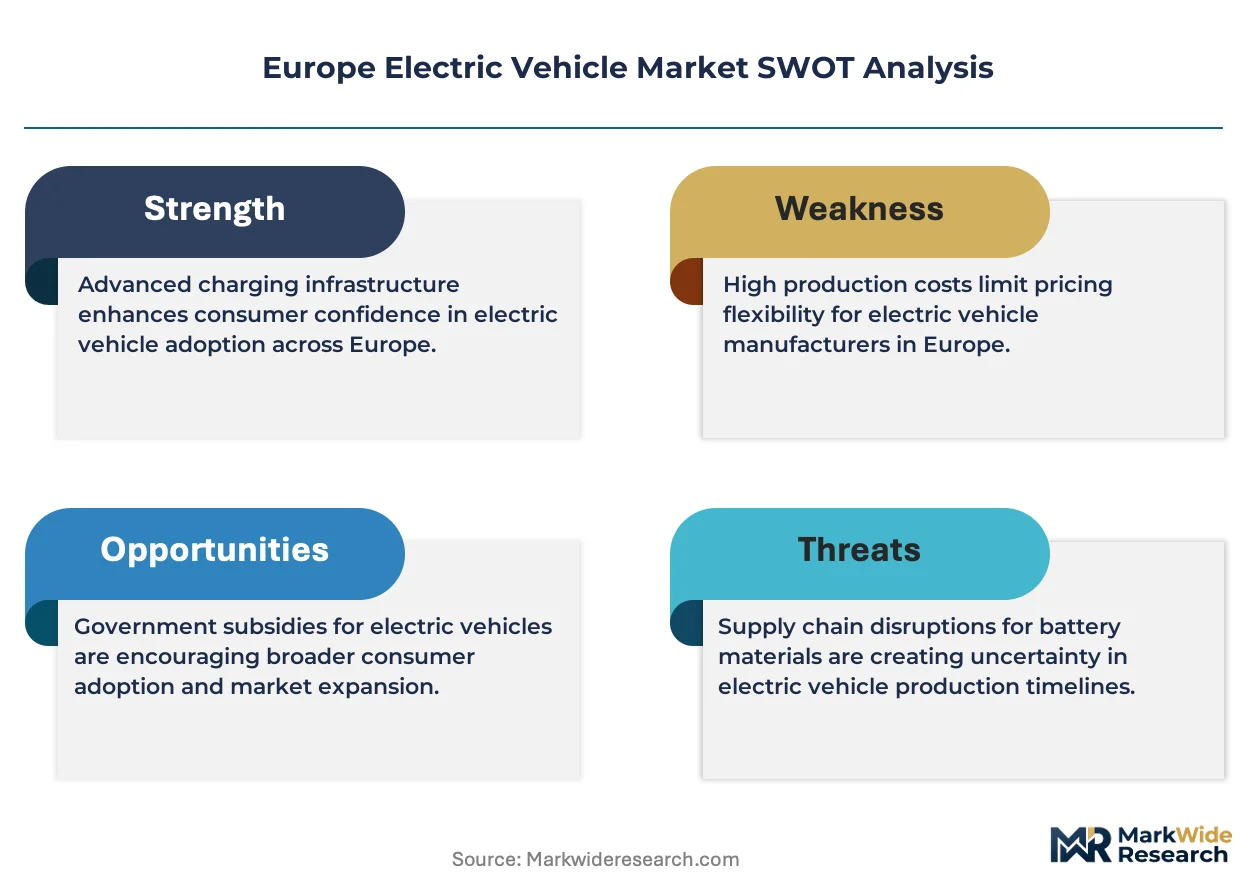
- Critical mineral concentration:Cobalt and lithium refining capacity concentrates in single-source geographies outside Europe, exposing cell manufacturers to supply disruption and price volatility.
- Grid interconnection queues:Distribution network operators in Germany and the Netherlands face 18-36 month lead times for high-capacity charging site energization.
- Residual value uncertainty:Fleet buyers hesitate on multi-year lease commitments due to unpredictable battery degradation curves and second-life market immaturity.
Strategic Opportunities
- Highway corridor fast-charger gaps:Eastern European transit routes between Germany and Bulgaria remain underserved, creating first-mover positioning for infrastructure operators.
- V2G integration:Bidirectional charging convergence with smart grid protocols opens revenue stacking for fleet operators through frequency regulation services.
- CSRD disclosure requirements:Corporate sustainability reporting mandates are elevating electrified fleet visibility in procurement scorecards, accelerating B2B demand.
Industry Challenges
- Power electronics engineering scarcity:Silicon carbide inverter design and 800V system integration expertise concentrates in a limited pool of specialists across Munich, Stuttgart, and Gothenburg clusters.
- Multi-homologation complexity:Divergent national type-approval timelines between Germany's KBA, France's DGCCRF, and the Netherlands' RDW fragment launch sequencing and inventory positioning.
- Legacy dealer network reconfiguration:Established retail channels resist margin compression from direct-to-consumer sales models and over-the-air update revenue capture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Electric Vehicle Market |
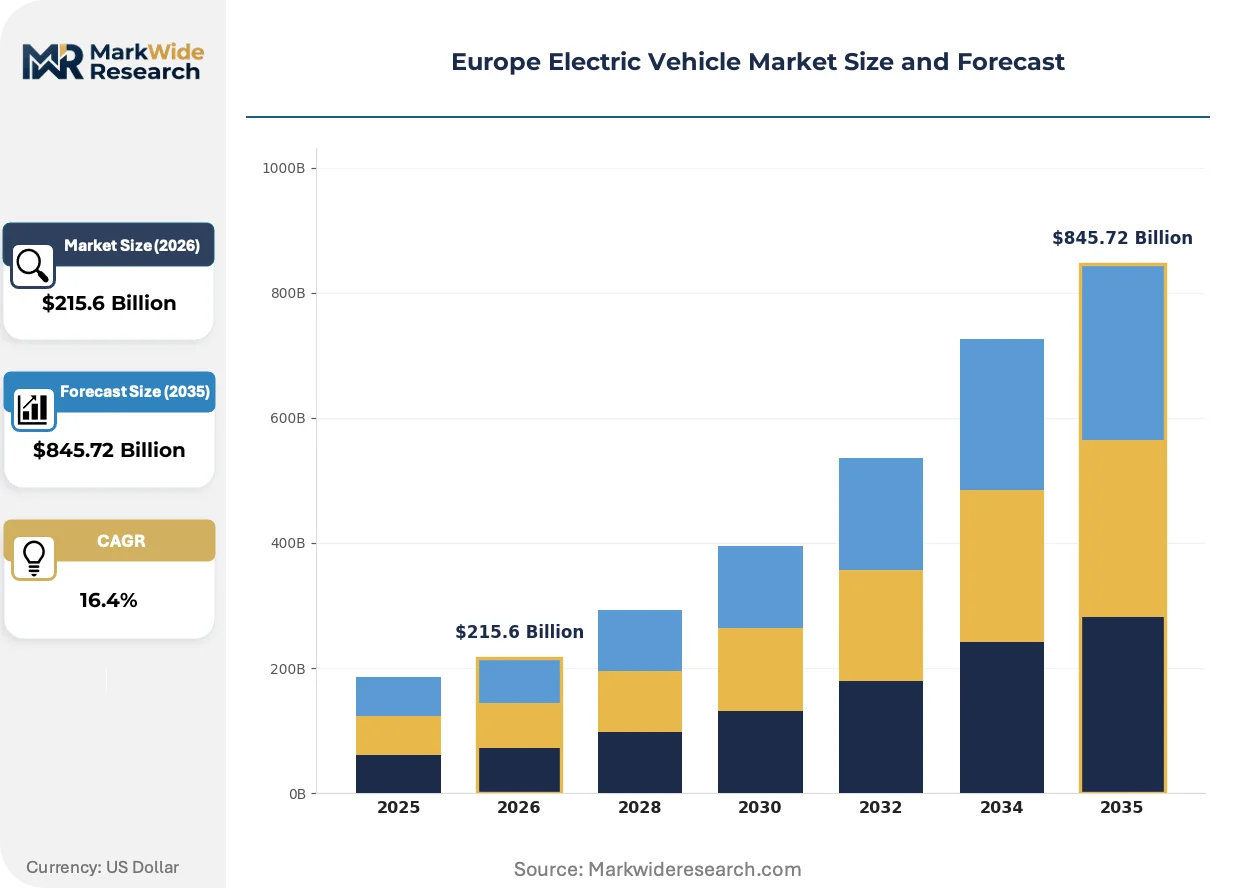
| Market Size in 2026 | $215.6 Billion |
| Market Size in 2035 | $845.72 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Battery Electric Vehicles, Plug-in Hybrid Electric Vehicles, Hybrid Electric Vehicles, Fuel Cell Electric Vehicles Charging Infrastructure: Home Charging Stations, Public Charging Points, Fast Chargers, Wireless Charging Solutions End User: Individual Consumers, Fleet Operators, Ride-Sharing Services, Government Entities Battery Technology: Lithium-Ion, Solid-State, Nickel-Metal Hydride, Lead-Acid |
| Companies Covered | Volkswagen, Tesla, BMW, Audi, Mercedes-Benz, Renault, Skoda, Toyota, BYD, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Electric Vehicle Market Strategic Shifts & Innovations
Solid-state battery architectures and silicon carbide power electronics are compressing charging times and extending range thresholds. These advances intersect with tightening chemical compliance frameworks and evolving fleet procurement models to reshape competitive positioning.
Silicon carbide MOSFETs replace traditional silicon IGBTs in traction inverters, cutting switching losses and enabling higher thermal efficiency. Tier 1 suppliers and integrated OEM powertrain divisions are adopting the technology for 800V platform launches. The component footprint is miniaturizing, allowing packaging density gains that free vehicle architecture space for battery cell volume expansion.
EU Green Deal carbon neutrality targets are tightening embedded carbon accounting for battery supply chains. ECHA REACH compliance now extends to full lifecycle chemical disclosure, affecting cell chemistry selection and recycling partnerships. German and French OEMs are restructuring supplier qualification protocols to meet these thresholds, with premium segment vehicles facing the most stringent verification requirements.
Fleet procurement is consolidating through sustainability-linked leasing structures that bundle vehicles, charging infrastructure, and energy management into single-contract arrangements. Traditional equipment finance channels face displacement from integrated mobility service providers. This pattern concentrates in German logistics corridors where contract logistics operators serve automotive and retail anchors with rigid carbon reduction clauses.
Europe Electric Vehicle Market Segmentation
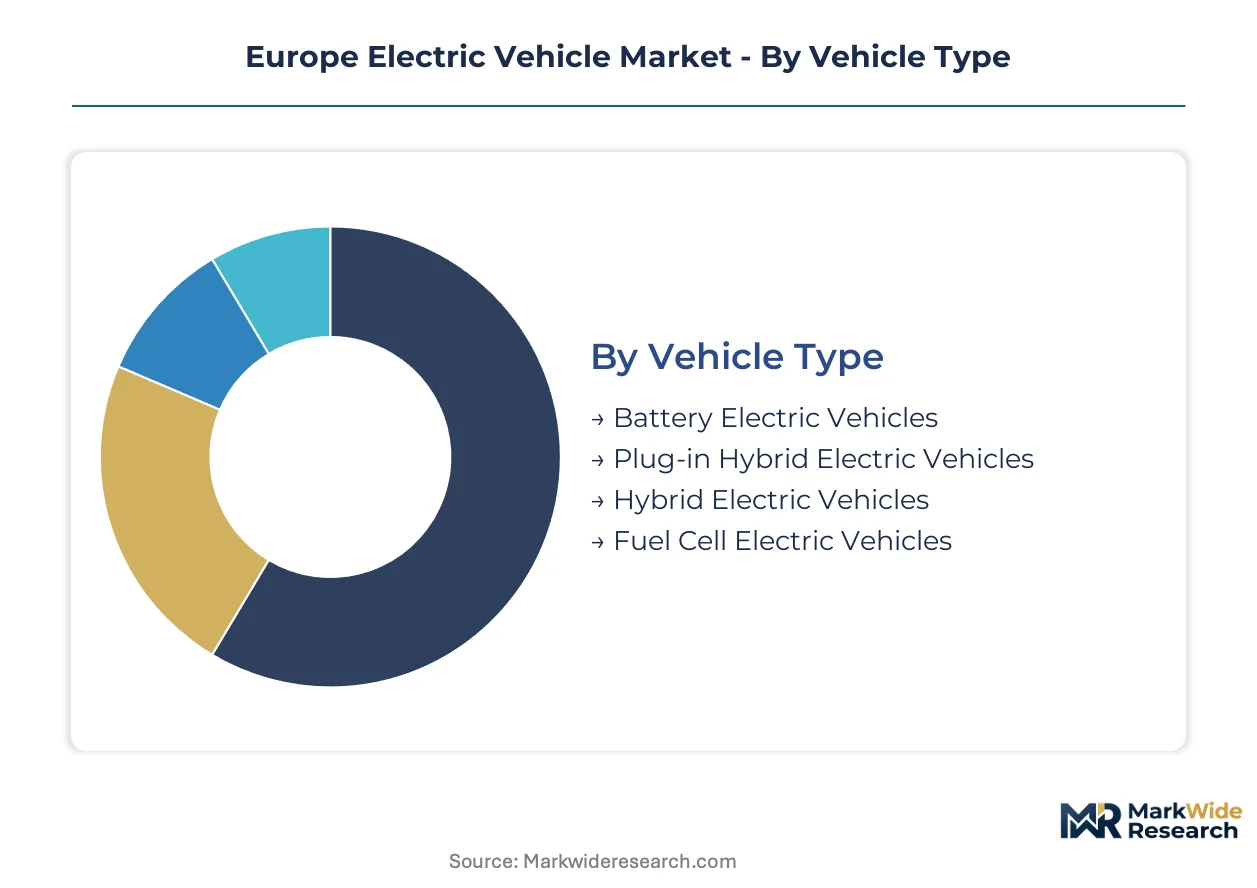
Segmentation across vehicle architecture, charging topology, and procurement channel reveals divergent margin profiles and regulatory exposure within European electrification. Manufacturers calibrate platform investments against fleet electrification timelines and national ICE phase-out schedules.
Vehicle Type:
Domestic demand concentrates on battery-dominant architectures, while fuel-cell platforms serve cross-border logistics corridors with hydrogen backbone access.
- Battery Electric Vehicles:Pure-electric architectures operating at 400-800V with lithium-ion packs exceeding 60 kWh usable capacity. German industrial clusters and Netherlands urban transit authorities are concentrating procurement under EU Green Deal compliance deadlines.
- Plug-in Hybrid Electric Vehicles:Dual-powertrain systems combining combustion range extension with electric-only urban operation. French and Italian fleet operators favor PHEVs for transitional compliance where charging density remains uneven.
- Hybrid Electric Vehicles:Non-plug-in mild-hybrid and full-hybrid systems with limited electric-only range. Eastern European markets with weaker grid infrastructure show residual demand.
- Fuel Cell Electric Vehicles:Hydrogen-fed proton exchange membrane systems targeting heavy-duty freight and intercity bus routes. German and Dutch hydrogen corridor investments are creating concentrated deployment zones.
Battery Electric Vehicles hold the largest share; momentum sits with Fuel Cell Electric Vehicles in heavy-duty applications.
Charging Infrastructure:
Capital allocation stratifies by utilization intensity, with highway corridor assets commanding premium returns against residential installations.
- Fast Chargers:DC rapid-charging stations delivering 150-350 kW for sub-30-minute replenishment. German autobahn networks and Benelux transit corridors are absorbing disproportionate infrastructure investment under EU TEN-T completion mandates.
- Home Charging Stations:Level 2 AC wallbox installations at 7-22 kW for overnight residential replenishment. Suburban owner-occupiers in France and Germany dominate installation flows as apartment dwellers face access constraints.
- Public Charging Points:Destination and on-street AC charging at 3.7-22 kW. Urban municipalities in Spain and Italy are accelerating deployment through concession tenders.
- Wireless Charging Solutions:Inductive pad systems for automated fleet depot operations. Swedish and German pilot programs for autonomous shuttle services are testing commercial viability.
Fast Chargers absorb the dominant capital share; wireless solutions are climbing the fastest despite technical immaturity.
End User:
Procurement patterns diverge sharply between price-sensitive retail consumers and sustainability-linked corporate fleet contracts.
- Fleet Operators:Logistics, delivery, and rental companies procuring under multi-year electrification mandates. German contract logistics providers serving automotive OEMs face binding carbon reduction clauses in anchor contracts.
- Individual Consumers:Private retail buyers responding to purchase incentives and taxation advantages. French bonus-malus schemes and German environmental bonuses are concentrating demand in premium and mass-market segments.
- Ride-Sharing Services:Platform-mediated mobility providers optimizing for total cost of ownership and urban access privileges. Amsterdam and Paris zero-emission zones are forcing fleet turnover.
- Government Entities:Municipal and national procurement for public transit, postal, and emergency services. Scandinavian public authorities are setting earliest electrification deadlines.
Fleet Operators command the steepest expansion trajectory; Individual Consumers retain volume dominance.
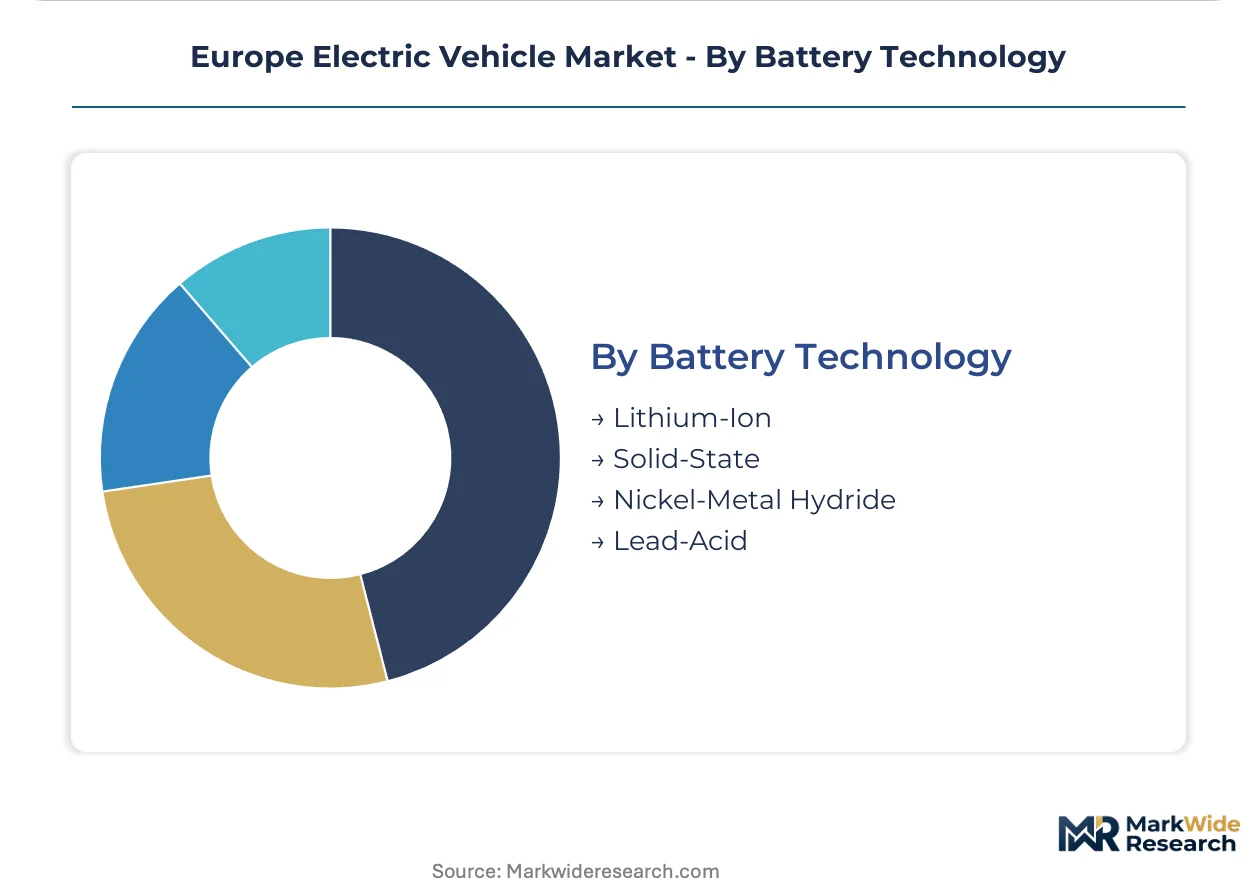
Battery Technology:
Chemistry selection balances energy density requirements against ECHA REACH compliance burdens and embedded carbon accounting.
- Lithium-Ion:NMC and LFP cell architectures with 250-300 Wh/kg gravimetric density. Hungarian and Polish gigafactory output is securing regional supply for German and Czech vehicle assembly.
- Solid-State:Next-generation ceramic or polymer electrolyte systems promising 400+ Wh/kg and enhanced thermal stability. German and French OEM research partnerships are targeting pilot production.
- Nickel-Metal Hydride:Mature chemistry retaining cost advantages for hybrid applications. Toyota's European hybrid production sustains residual demand.
- Lead-Acid:Auxiliary power and low-voltage systems in legacy platform variants. Aftermarket replacement cycles in Southern Europe sustain marginal volumes.
Lithium-Ion retains the largest share; solid-state chemistry is gaining share fastest through OEM pre-development commitments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German federal subsidies under the Umweltbonus program and French bonus-malus taxation schemes are accelerating fleet turnover across Western Europe, while Eastern European governments negotiate EU cohesion funds for charging corridor completion.
Germany
Industrial procurement from automotive OEMs and contract logistics providers drives concentrated BEV demand in the Rhine-Ruhr and Stuttgart corridors. The KBA enforces type-approval timelines that compress launch windows for new platform introductions. Bavaria's Ingolstadt and Munich clusters host MEB-platform production and battery competence center investments.
France
Paris municipal zero-emission zones and national leasing subsidies sustain consumer and fleet uptake in Île-de-France. The DGCCRF monitors compliance with bonus-malus incentive thresholds and resale price transparency. Auvergne-Rhône-Alpes hosts Stellantis electrified powertrain engineering and Lyon-based charging infrastructure manufacturing.
Netherlands
Amsterdam and Rotterdam port electrification mandates accelerate heavy-duty vehicle procurement among logistics operators. The RDW administers vehicle type-approval with lead times diverging from German KBA sequencing. Eindhoven's Brainport cluster concentrates V2G charging technology development and smart grid integration pilots.
United Kingdom
London's ultra-low emission zone expansion forces ride-sharing and delivery fleet turnover ahead of national ICE phase-out deadlines. The Driver and Vehicle Standards Agency enforces divergent homologation requirements post-Brexit. Midlands manufacturing corridors around Birmingham and Coventry retain battery assembly investments despite regulatory friction.
Poland
Eastern European logistics corridors between Germany and Ukraine sustain demand for long-range BEVs and emerging FCV trials. EU TEN-T funding priorities are accelerating fast-charger deployment on transit routes. Lower Silesia's emerging gigafactory investments are securing cell supply for Czech and German vehicle assembly plants.
Europe Electric Vehicle Market Key Industry Players
Player mix skews toward integrated OEMs with captive platform architectures and scale-driven battery supply arrangements. Market structure concentrates around German legacy manufacturers leveraging MEB and dedicated EV architectures, with Tesla's software-defined approach creating a distinct competitive vector. Strategic archetypes include vertically integrated platform specialists, modular architecture licensors, and charging network operators. Capacity expansion across Hungarian and Polish gigafactory zones and strategic partnerships for solid-state cell development represent dominant competitive moves.
Among Germany-based integrated manufacturers, Volkswagen AG, Bayerische Motoren Werke AG, and Mercedes-Benz Group AG exemplify the vertically integrated archetype through captive battery competence centers and multi-plant platform deployment. Tesla, Inc. occupies a position defined by supercharger network density and over-the-air revenue capture. BYD Company Limited represents the Chinese scale-driven entrant leveraging LFP cell cost advantages. These three named entities anchor the competitive structure without exhaustively mapping the vendor landscape.
| Leading Market Players |
|---|
| Volkswagen |
| Tesla |
| BMW |
| Audi |
| Mercedes-Benz |
| Renault |
| Skoda |
| Toyota |
| BYD |
| Others |
Cost & Logistics Intelligence
Silicon carbide MOSFET substitution for silicon IGBTs is redrawing procurement geography toward Munich, Stuttgart, and Gothenburg engineering clusters while compressing inverter cost curves for 800V architectures. This materials transition simultaneously elevates power electronics scarcity premiums and reshapes tier-1 supplier qualification protocols under EU Machinery Directive CE marking requirements.
Pricing Analysis
Certification level under EU Machinery Directive CE marking creates the primary spread between highway corridor fast-charger assets and residential wallbox installations. Three-tier pricing structure across premium DC rapid-charging, standard public AC points, and economy home charging reflects divergent utilization intensity and grid interconnection cost absorption. Cost compression in residential segments is intensifying because OEMs bundle wallbox hardware with vehicle purchase incentives. Fleet operators exhibit lowest price sensitivity due to sustainability-linked lease structures, while individual consumers in apartment-constrained markets face highest effective cost burdens.
Supply Chain Analysis
Strategic stockpiling of lithium hydroxide and nickel sulfate is displacing just-in-time cathode precursor procurement as ECHA REACH compliance extends chemical disclosure burdens across cell supply chains. Battery cell output concentrates in Hungary, Poland, and Germany's emerging gigafactory zones, drawing from cobalt refining capacity anchored in the Democratic Republic of Congo and Chilean lithium brine operations. Single-source vulnerability in cathode active material processing exposes European pack assembly to price volatility and forced labor disclosure risks. Distribution runs through captive OEM logistics networks and independent charging infrastructure operators with divergent margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's electric vehicle market is approaching a platform-economics inflection where MEB architecture licensing and supercharger network interoperability are consolidating competitive moats around software-defined vehicle ecosystems.
For Market Incumbents: Secure silicon carbide inverter supply through backward integration into Munich and Stuttgart power electronics clusters before engineering scarcity elevates procurement premiums. Defend position against Chinese LFP cell cost advantages by accelerating solid-state pilot production partnerships with German and French research consortia under EU Green Deal carbon accounting frameworks. For New Entrants and Emerging Players: Anchor in Eastern European highway corridor charging gaps between Germany and Bulgaria where EU TEN-T funding is accelerating fast-charger deployment ahead of incumbent saturation. Target fleet operators in Polish logistics corridors serving German automotive OEMs with rigid carbon reduction clauses, leveraging integrated mobility service contracts that bundle vehicles, charging infrastructure, and energy management. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed charging infrastructure operators holding concession tenders in Benelux transit corridors and German autobahn networks. Long-term viability hinges on V2G revenue stacking through frequency regulation services as smart grid protocols mature. Watch for inflection when bidirectional charging hardware penetration crosses utility-scale deployment thresholds in Netherlands pilot programs.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Polish and Hungarian gigafactory offtake secures regional cell supply for German vehicle assembly under EU Green Deal compliance timelines. |
| Platform Standardization | MEB architecture licensing across multiple European plants compresses engineering costs and accelerates model variant proliferation. |
| Charging Infrastructure Partnership | Highway corridor fast-charger deployment under EU TEN-T mandates captures first-mover positioning in underserved Eastern European transit routes. |
| Software-Defined Vehicle Investment | Over-the-air update revenue capture and autonomous feature activation create recurring income streams beyond initial vehicle sale. |
| Geographic Manufacturing Footprint | Bavarian battery competence centers and Czech vehicle assembly integration reduce logistics exposure and customs friction post-Brexit. |
Research Approach
Cross-validation between OEM platform engineering disclosures and charging infrastructure operator concession tenders anchors the qualitative findings on deployment sequencing and capital allocation priorities. Primary interviews with Tier 1 supplier procurement leads, OEM powertrain directors, fleet sustainability officers, and distribution network planners combined with secondary validation against EU Green Deal policy documents, ECHA REACH chemical filings, and national vehicle registration databases. Bottom-up cell chemistry demand modeling and top-down fleet electrification mandate tracking triangulate volume estimates.
Sensitivity analysis around lithium price volatility and grid interconnection queue duration shapes the forecast framework across the projection horizon. Segmentation dimensions span vehicle architecture, charging topology, battery chemistry, and procurement channel with regional production cluster overlays. CAGRs derive from production capacity buildout curves, fleet turnover timelines under national ICE phase-out schedules, and infrastructure investment flows under EU cohesion funding priorities.
Material uncertainties — abrupt critical mineral export restrictions, accelerated national ICE phase-out legislation, and silicon carbide wafer supply disruption — sit outside the modeled envelope. Forecasts reflect assumptions on battery cost curve compression and charging network completion rates. Revision becomes warranted when V2G protocol standardization or solid-state battery commercialization crosses mass-production thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
France Electric Vehicle Market
Electric Vehicles
EV PTC Heaters Market
Electric Vehicles
Electric Vehicle Rental Market
Electric Vehicles
Africa Electric Scooter Market
Electric Vehicles
Middle-East E-Bike Market
Electric Vehicles
Electric Vehicle Heating System Market
Electric Vehicles
Electric Vehicle Thermal Management Market
Electric Vehicles
Asia-Pacific Solar E-Bike Market
Electric Vehicles
Mexico Automotive High Performance Electric Vehicle Market
Electric Vehicles
North America Wireless Electric Vehicle Charging Market
Electric Vehicles
Asia-Pacific Electric Bus Battery Pack Market
Electric Vehicles
Italy Hybrid Electric Vehicle Battery Market
Electric Vehicles
France E-Bike Market
Electric Vehicles
Off-Highway Electric Machine Battery Pack Systems Market
Electric Vehicles
E-Bike Lithium-Ion Battery Market
Electric Vehicles
Battery-Swapping for Electric Two-Wheeler Market