
 AC BEV On-Board Charger Market | 2026-2036
AC BEV On-Board Charger Market Size, Share, and Industry Trends Forecast 2026-2036
AC BEV On-Board Charger Market Insights
Aftermarket service revenue is rewriting value capture in the AC BEV on-board charger ecosystem as warranty extensions and refurbishment cycles extend beyond initial hardware sales. BorgWarner leverages its power electronics heritage to anchor high-volume OEM contracts across European and North American passenger vehicle programs. Infineon Technologies dominates silicon carbide semiconductor supply for Tier-1 charger module suppliers, while Delta Energy Systems specializes in thermal management-integrated charger architectures for commercial vehicle duty cycles.
An AC BEV on-board charger converts alternating current from the grid into direct current suitable for battery storage, typically operating at power levels from 3.6 kW to 22 kW with isolation transformers and power factor correction circuits ensuring grid compliance and safe energy transfer. Bidirectional charger architectures are capturing disproportionate engineering investment as vehicle-to-grid functionality transitions from premium option to infrastructure requirement in multiple jurisdictions. Silicon carbide technology segments command premium positioning due to switching frequency advantages and reduced cooling overhead, while gallium nitride variants compete in cost-sensitive single-phase residential applications where power density requirements remain moderate.
China's MIIT establishes mandatory GB standards for on-board charger efficiency and electromagnetic compatibility, directly shaping product development roadmaps for suppliers targeting domestic OEM qualification. The EU Green Deal and associated F-Gas Regulation indirectly pressure thermal management design choices, favoring charger architectures with reduced cooling system refrigerant dependency. Stakeholders must monitor evolving interoperability mandates from ISO and IEC working groups, as harmonized communication protocols between chargers and grid infrastructure will determine market access eligibility across multiple regulatory domains.
Market Dynamics
Silicon carbide semiconductor technology is collapsing the thermal management overhead and physical footprint that constrained prior IGBT-based charger generations, forcing wholesale redesign of power electronics packaging across Tier-1 supplier portfolios.
Growth Catalysts
- Fleet electrification mandates:California's Advanced Clean Trucks regulation and analogous EU CO2 standards for commercial vehicles are compelling last-mile delivery operators to specify bidirectional on-board chargers as standard equipment.
- GB standards compliance:China's MIIT mandatory efficiency and electromagnetic compatibility requirements are accelerating domestic OEM qualification timelines for suppliers with localized production.
- V2G infrastructure investment:Germany's grid modernization programs are embedding bidirectional charging capability as an infrastructure requirement, pulling engineering resources toward bidirectional architectures.
Market Restraints
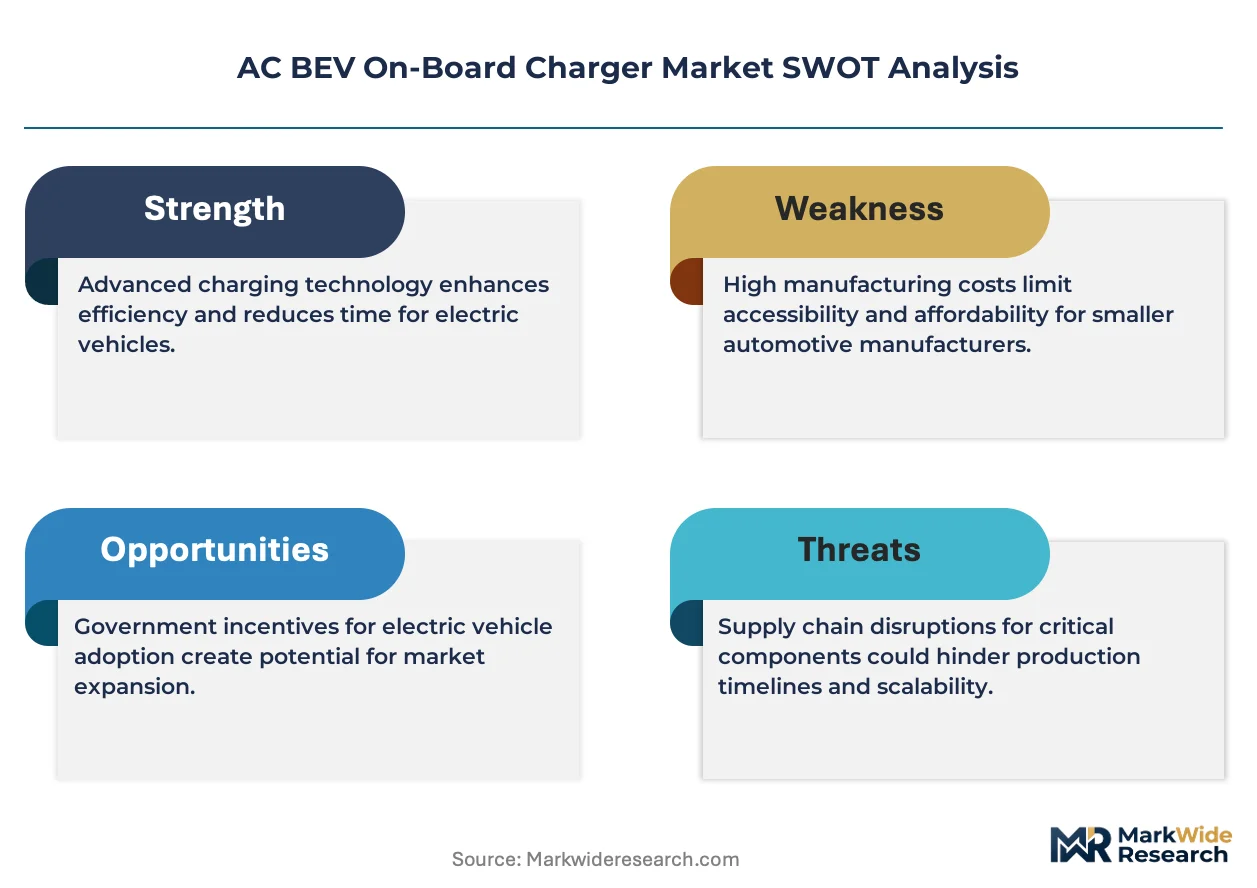
- Silicon carbide substrate concentration:Wafer supply concentrates among a limited set of crystal growth specialists, creating input cost volatility for power module manufacturers.
- Thermal management refrigerant dependency:The EU F-Gas Regulation is restricting conventional cooling system chemistries, forcing costly redesign of liquid-cooled charger architectures.
- Residential power infrastructure:Single-phase grid connections in older European housing stock impose hard power limits on home charging, capping addressable market for high-kW residential units.
Strategic Opportunities
- Commercial vehicle duty cycles:Thermal management-integrated charger architectures for heavy-duty electric trucks represent an underpenetrated application with distinct engineering requirements from passenger vehicle programs.
- ISO/IEC harmonization:Emerging interoperability mandates for grid communication protocols will privilege early movers with certified protocol stacks across multiple regulatory domains.
- Aftermarket refurbishment channels:Warranty extension programs and module replacement cycles are creating service revenue streams decoupled from initial hardware sales.
Industry Challenges
- Power electronics talent scarcity:Specialized expertise in wide-bandgap semiconductor gate drive design and magnetics optimization is concentrating among a limited pool of experienced engineers.
- OEM integration timelines:Platform-specific thermal packaging and vehicle electrical architecture requirements are compressing development cycles while expanding validation scope.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AC BEV On-Board Charger Market |
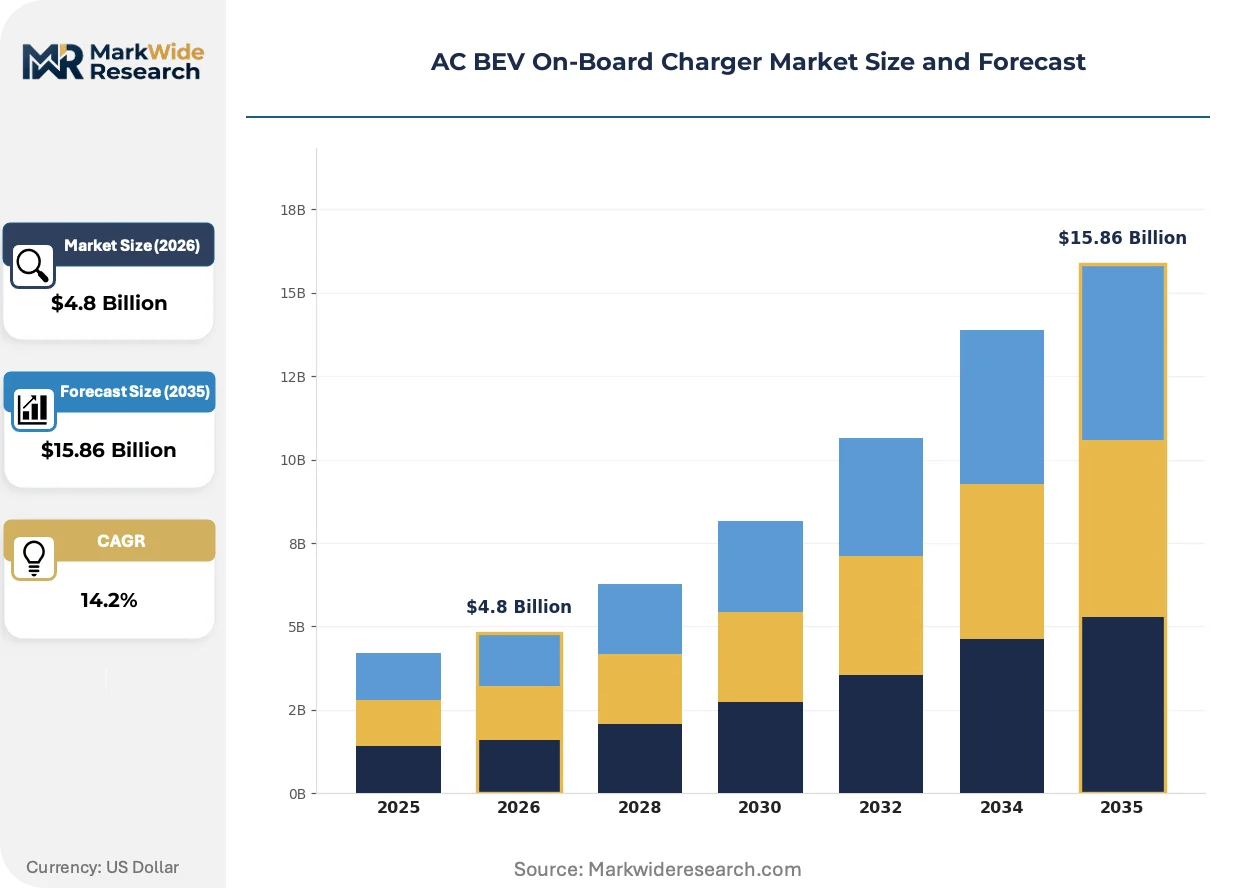
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Phase Charger, Three-Phase Charger, Bidirectional Charger, High-Power Charger Technology: Silicon Carbide, Gallium Nitride, IGBT, MOSFET, Si Transistor Application: Passenger Vehicles, Commercial Vehicles, Delivery Vans, Service Vehicles, Public Transportation End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | BorgWarner, Delta Energy Systems, Eaton Corporation, STMicroelectronics, Valeo, BRUSA Elektronik, Infineon Technologies, Toyota Industries Corporation, Bel Fuse, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AC BEV On-Board Charger Market Trends and Innovations
Engineering investment is rotating toward bidirectional functionality and wide-bandgap semiconductors as baseline requirements rather than premium differentiators, compressing the technology adoption cycle across supplier tiers.
Silicon carbide MOSFET technology is collapsing the volume and weight constraints that previously forced trade-offs between switching frequency and thermal performance in on-board charger designs. Fleet operators in commercial vehicle programs are specifying SiC-based architectures as standard equipment for duty cycles above 11 kW. The resulting power density improvements are enabling integrated charger-inverter units that eliminate separate housing and cooling loops.
The EU Green Deal and associated F-Gas Regulation are restricting hydrofluorocarbon refrigerants in thermal management systems, compelling charger suppliers to redesign liquid cooling loops around CO2 or propane-based alternatives. This regulatory pressure is accelerating adoption of air-cooled architectures in lower-power residential applications where thermal margins permit. German OEM integration programs are prioritizing suppliers with refrigerant-independent cooling strategies.
Fleet procurement departments are consolidating charger specification authority from decentralized maintenance operations into centralized sustainability procurement functions, compressing vendor qualification timelines while expanding technical compliance requirements. This concentration of buying power is favoring Tier-1 suppliers with established OEM relationships and certified quality systems. The shift is most visible in European last-mile delivery electrification programs where total cost of ownership modeling dominates capital allocation decisions.
AC BEV On-Board Charger Market Segmentation
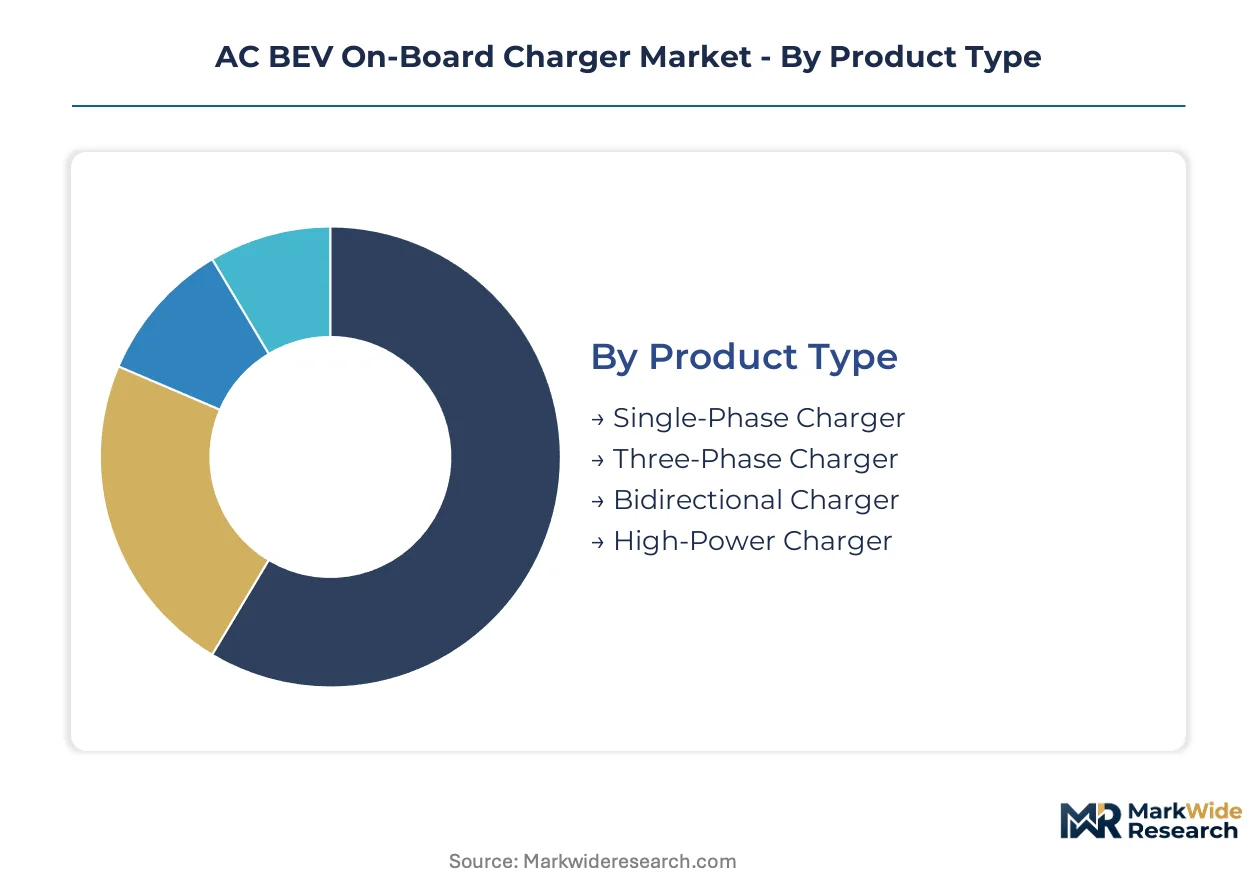
Segmentation in the AC BEV on-board charger market reveals divergent replacement cycles across product architectures, with bidirectional and high-power systems turning over faster than legacy single-phase units as fleet operators accelerate refresh schedules.
Product Type:
Cycle times vary dramatically across charger architectures, with bidirectional and high-power systems experiencing accelerated replacement as V2G mandates and commercial electrification compress fleet procurement horizons.
- Bidirectional Charger:Vehicle-to-grid capable architectures integrate isolation transformers and dual-active bridge topologies enabling AC-DC and DC-AC conversion. Fleet operators in Germany are specifying these as standard equipment under grid modernization programs that embed bidirectional capability as infrastructure requirement.
- Single-Phase Charger:Residential-focused units operating at 3.6-7.2 kW dominate replacement volume in older European housing stock with constrained grid connections. California's Advanced Clean Trucks regulation indirectly pressures passenger vehicle OEMs to phase out these lower-power units in favor of bidirectional alternatives.
- Three-Phase Charger:11-22 kW architectures serve commercial installations and newer residential developments with upgraded infrastructure.
- High-Power Charger:Systems above 22 kW target premium passenger segments and heavy-duty commercial applications with demanding duty cycles.
Single-phase chargers anchor the volume base while bidirectional chargers gain share at the steepest rate.
Technology:
Cost tiers separate wide-bandgap semiconductors from legacy silicon architectures, with silicon carbide commanding premium positioning against gallium nitride's cost-optimized residential penetration.
- Silicon Carbide:Wide-bandgap MOSFETs enable switching frequencies above 100 kHz with reduced cooling overhead and higher power density. Tier-1 suppliers in Germany and North America are redesigning entire power electronics portfolios around SiC as fleet operators above 11 kW specify these architectures as standard.
- IGBT:Insulated-gate bipolar transistors retain cost advantage in cost-sensitive applications but face displacement as SiC substrate costs decline and thermal efficiency becomes procurement priority.
- Gallium Nitride:Competes in single-phase residential segments where moderate power density requirements align with cost optimization goals.
- MOSFET:Silicon-based metal-oxide-semiconductor field-effect transistors serve legacy platform continuity and aftermarket replacement demand.
- Si Transistor:Conventional silicon transistors persist in lowest-cost regional markets with relaxed efficiency mandates.
IGBT architectures still represent the largest installed base though silicon carbide is expanding most quickly as OEM integration programs accelerate.
Application:
Customer concentration differs sharply across vehicle categories, with delivery van electrification running ahead of public transportation procurement timelines due to total cost of ownership advantages in last-mile logistics.
- Delivery Vans:Last-mile electrification programs specify bidirectional on-board chargers as standard equipment under tightening mandates. Fleet procurement departments have consolidated specification authority from decentralized maintenance operations, compressing vendor qualification timelines for Tier-1 suppliers with certified quality systems.
- Passenger Vehicles:OEM integration requirements vary by platform thermal packaging and vehicle electrical architecture, with German manufacturers prioritizing refrigerant-independent cooling strategies under EU F-Gas Regulation pressure.
- Commercial Vehicles:Heavy-duty electric trucks demand thermal management-integrated charger architectures with distinct engineering requirements from passenger programs.
- Service Vehicles:Utility and municipal fleets follow procurement patterns similar to delivery vans but with extended validation cycles.
- Public Transportation:Bus electrification programs lag due to infrastructure investment requirements and depot charging complexity.
Passenger vehicles anchor the volume base while delivery vans gain share at the steepest rate.
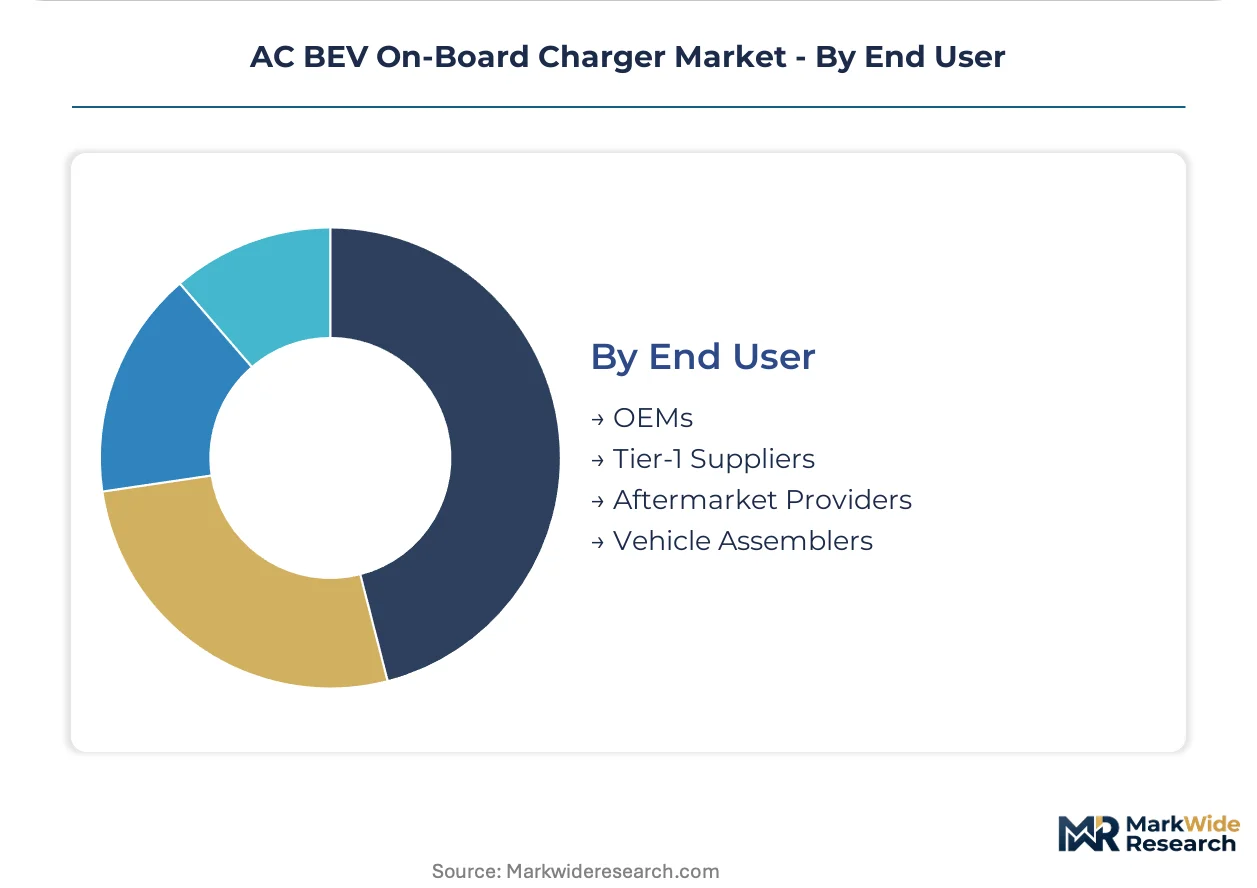
End User:
Margin capture varies across the value chain, with OEMs extracting premium pricing for integrated systems while aftermarket providers build recurring revenue through refurbishment cycles and warranty extensions.
- OEMs:Original equipment manufacturers specify platform-specific thermal packaging and vehicle electrical architecture requirements, compressing development cycles while expanding validation scope for Tier-1 suppliers.
- Tier-1 Suppliers:Module suppliers with established OEM relationships and certified quality systems capture concentrated buying power from fleet procurement consolidation.
- Aftermarket Providers:Warranty extension programs and module replacement cycles create service revenue streams decoupled from initial hardware sales as refurbishment channels mature.
- Vehicle Assemblers:Contract manufacturers and regional assembly operations source certified charger modules for localized production compliance with China's MIIT GB standards.
OEMs anchor the volume base while aftermarket providers gain share at the steepest rate as extended warranty programs proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet procurement departments in Germany demonstrate the lowest price elasticity, absorbing silicon carbide premiums for bidirectional systems, while residential buyers in older European housing stock remain highly sensitive to single-phase unit costs. China's MIIT compliance requirements compress margins for foreign suppliers despite volume opportunities. India's emerging electrification programs show mixed elasticity as commercial operators prioritize total cost of ownership over upfront hardware expenditure.
Germany
German fleet operators specify bidirectional on-board chargers as standard equipment under grid modernization programs embedding vehicle-to-grid capability as infrastructure requirement. The EU F-Gas Regulation restricts hydrofluorocarbon refrigerants in thermal management systems, compelling redesign of liquid cooling loops. Engineering resources concentrate in Baden-Württemberg and Bavaria, where OEM integration programs prioritize suppliers with refrigerant-independent cooling strategies.
China
Domestic OEM qualification timelines accelerate for suppliers with localized production under MIIT mandatory GB standards for efficiency and electromagnetic compatibility. The country's dual carbon goals tighten electrification mandates across commercial vehicle segments. Manufacturing clusters in the Yangtze River Delta and Pearl River Delta dominate module assembly for both domestic consumption and export qualification.
United States
California's Advanced Clean Trucks regulation compels last-mile delivery operators to specify bidirectional architectures, compressing refresh cycles for legacy single-phase units. The Inflation Reduction Act provisions indirectly shape procurement patterns through commercial vehicle tax incentives. Detroit-area OEM engineering centers and Austin-San Antonio corridor EV manufacturing operations anchor North American integration activity.
India
Commercial vehicle electrification programs under the PLI scheme accelerate charger specification for heavy-duty truck duty cycles with distinct thermal requirements from passenger applications. The Central Electricity Authority issues grid interconnection standards shaping product development for domestic qualification. Tamil Nadu and Gujarat manufacturing corridors attract Tier-1 suppliers establishing localized assembly for OEM qualification.
Japan
METI vehicle electrification roadmaps prioritize bidirectional charging integration for grid stabilization services in disaster-resilient infrastructure planning. JIS standards harmonization with IEC protocols reduces certification burden for export-oriented suppliers. Kanto region engineering centers and Nagoya-area automotive clusters concentrate power electronics talent for next-generation charger development.
AC BEV On-Board Charger Market Competitive Landscape
Capability concentration sits with semiconductor specialists and thermal management engineers; scale advantage sits with established Tier-1 suppliers with certified OEM quality systems. The supplier base organizes into three strategic archetypes: wide-bandgap semiconductor fabricators, integrated power electronics module suppliers, and thermal-integrated system architects. Dominant competitive moves include backward integration into semiconductor supply and geographic co-location with OEM engineering centers to compress validation timelines.
Among European-anchored power electronics specialists, Infineon Technologies and STMicroelectronics exemplify the semiconductor-capability tier, while BorgWarner occupies a position bridging Tier-1 integration scale with power electronics heritage. These three entities represent distinct competitive vectors: substrate-level technology control, foundry-scale manufacturing, and OEM relationship density.
| Leading Market Players |
|---|
| BorgWarner |
| Delta Energy Systems |
| Eaton Corporation |
| STMicroelectronics |
| Valeo |
| BRUSA Elektronik |
| Infineon Technologies |
| Toyota Industries Corporation |
| Bel Fuse |
| Others |
Pricing and Supply Chain Analysis
Silicon carbide wafer concentration in the United States and Japan funnels pricing power toward substrate specialists, while Tier-1 charger module suppliers absorb margin compression through aftermarket service bundling and extended warranty contracts.
Pricing Analysis
Aftermarket refurbishment revenue and extended warranty contracts now anchor lifetime value capture for charger suppliers, displacing pure hardware margins. Three-tier pricing structure across SiC premium, IGBT standard, and silicon economy levels reflects certification grade and thermal performance tier. Cost compression in IGBT architectures is intensifying because fleet operators above 11 kW specify wide-bandgap alternatives as standard equipment. Residential buyers in older European housing stock exhibit highest price sensitivity, while German fleet procurement departments absorb SiC premiums for bidirectional systems.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Tier-1 module suppliers are stabilizing cash flow for power electronics assemblers amid wafer cost volatility. Manufacturing concentrates in Germany, China, and the United States, with crystal growth feeding from specialist facilities in North America and Japan. The supply chain draws from silicon carbide substrates, copper magnetics, and refrigerant-grade cooling components. Single-source vulnerability in wide-bandgap semiconductor supply creates structural risk for power module manufacturers. Distribution runs through OEM direct procurement channels and certified Tier-1 supplier networks with vehicle assembler qualification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet procurement consolidation has shifted buyer power toward centralized sustainability functions, compressing vendor qualification timelines while expanding technical compliance requirements for Tier-1 suppliers.
For Market Incumbents: Entrench market position through backward integration into silicon carbide semiconductor supply and refrigerant-independent thermal management certification under EU F-Gas Regulation pressure. Deepen OEM engineering center co-location in Baden-Württemberg and Detroit to compress platform validation cycles against emerging GaN-based cost competitors. For New Entrants and Emerging Players: Build out specialized capability in thermal management-integrated architectures for heavy-duty electric truck duty cycles, where incumbent penetration remains limited. Target India's Tamil Nadu and Gujarat manufacturing corridors for localized assembly qualification under PLI scheme incentives, leveraging CEA grid interconnection standards as technical entry credential. For Investors and Strategic Acquirers: Capital is best deployed toward semiconductor-capable power electronics specialists with certified OEM quality systems and established wide-bandgap gate drive expertise. Long-term viability hinges on substrate-level technology control or foundry-scale manufacturing scale. Monitor ISO/IEC harmonization progress on grid communication protocols as inflection indicator for market access eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Substrate Supply | Captures margin pool from crystal growth specialists while insulating against wafer cost volatility. |
| Refrigerant-Independent Cooling Certification | Secures German OEM qualification under EU F-Gas Regulation restrictions on hydrofluorocarbon chemistries. |
| OEM Engineering Center Co-Location | Compresses platform-specific thermal packaging validation timelines in Baden-Württemberg and Detroit clusters. |
| ISO/IEC Protocol Stack Certification | Privileges early movers with harmonized grid communication standards across multiple regulatory domains. |
| Aftermarket Refurbishment Channel Buildout | Decouples revenue from initial hardware sales through warranty extension and module replacement cycles. |
Research Methodology
Initial hypotheses were tested against primary input from OEM platform engineers, Tier-1 supplier procurement leads, fleet sustainability directors, and power electronics R&D heads and refined through secondary validation against SEC filings, vehicle production databases, MIIT GB standard documentation, and IHS Markit registration data. Bottom-up unit economics modeling triangulated against top-down market sizing across power electronics module suppliers.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with segmentation modeled by charger architecture, semiconductor technology, vehicle application, and regional regulatory cluster. CAGRs were derived from installed base turnover rates and fleet electrification mandate timelines. Forecast inputs incorporated silicon carbide substrate cost curves, OEM platform launch schedules, and grid modernization program commitments.
Stress conditions across wafer supply disruption, refrigerant regulation acceleration, and residential grid infrastructure limits were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about technology adoption curves and regulatory enforcement intensity. Macroeconomic contraction, trade policy fragmentation, or breakthrough solid-state battery commercialization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Global Electric Vehicles Engineering Plastics Market
Electric Vehicles
Electric Vehicle Thermal Management Market
Electric Vehicles
E-Bike Smart Systems Market
Electric Vehicles
Battery Electric Vehicle (BEV) Market
Electric Vehicles
Electric Vehicle Cold Plates Market
Electric Vehicles
High Voltage PTC Heaters for Electric Vehicles Market
Electric Vehicles
Extended Range Electric Vehicle (EREV) Market
Electric Vehicles
Global Automotive High-Performance Electric Vehicles Market
Electric Vehicles
Car Battery Chargers Market
Electric Vehicles
Electric Motorcycles and Scooters Market
Electric Vehicles
South America Automotive High Performance Electric Vehicles Market
Electric Vehicles
E-Rickshaw Market
Electric Vehicles
Electric Bus Market
Electric Vehicles
Electric Scooters and Mopeds Market
Electric Vehicles
North America Electric Truck Market
Electric Vehicles
Three Wheel E-Scooter Market