
 Benzene and Its Derivatives Market | 2026-2036
Benzene and Its Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
Benzene and Its Derivatives Market Analysis
Ethylene is decoupling from traditional naphtha-based benzene co-production as US shale gas economics favor direct ethane cracking. BASF SE leverages its Ludwigshaven Verbund site to sustain integrated benzene-to-caprolactam margins. Sinopec anchors Asia-Pacific supply through its Zhenhai and Maoming refineries. Exxon Mobil Corporation competes on Gulf Coast scale with dedicated cyclohexane and cumene derivative streams.
Benzene and its derivatives comprise aromatic hydrocarbons extracted primarily via catalytic reforming or steam cracking of petroleum feedstocks, with benzene itself being a six-carbon ring structure serving as precursor to ethylbenzene, cumene, and cyclohexane for nylon and polystyrene production. Toluene and xylene isomers function as octane boosters and polyester intermediates respectively, with para-xylene commanding premium margins due to PTA-polyester chain integration. The solvents application leads volume through coatings and adhesives demand, while pharmaceuticals end-use represents the fastest-growing margin pool as API synthesis requires high-purity benzene grades. Direct sales channels dominate bulk aromatic transactions, though distributors occupy specialty chemical niches where technical service bundling differentiates supply relationships.
The EPA enforces benzene emissions limits under the Clean Air Act National Emission Standards for Hazardous Air Pollutants, forcing refinery benzene recovery unit upgrades. ECHA implements REACH authorization requirements that restrict uncontrolled benzene derivative uses in consumer-facing applications. OSHA mandates workplace exposure limits that shape handling protocols across manufacturing and automotive supply chains. Stakeholders must monitor carbon-border adjustment mechanism developments to decide whether European derivative exports warrant feedstock decarbonization investments.
Market Dynamics
Ethylene feedstock decoupling from naphtha-based benzene co-production is redirecting global aromatics flows, as US shale gas economics favor direct ethane cracking and reduce merchant benzene availability from traditional steam crackers.
Growth Catalysts
- Automotive lightweighting mandates:Styrene demand from polymer formulations for vehicle weight reduction pulls benzene derivatives into high-performance composites. OEMs specify these materials to meet fuel efficiency standards.
- REACH authorization frameworks:ECHA restrictions on uncontrolled benzene derivative uses in consumer applications create certified-grade premiums. Producers investing in purity upgrades capture margin expansion.
- China integrated refining:Sinopec and CNPC operate dedicated aromatics complexes serving domestic polyester and rubber industries, concentrating regional demand pull.
Market Restraints
- Crude oil price volatility:Benzene extraction costs track naphtha spreads, compressing margins when feedstock costs spike without derivative price pass-through.
- European supply concentration:BASF Ludwigshaven and INEOS Köln dominate EU benzene-to-caprolactam chains, creating single-source vulnerability for downstream nylon producers.
- Biobased aromatic substitution:Renewable toluene from lignocellulosic feedstocks threatens solvent-grade demand in coatings formulations.
Strategic Opportunities
- India specialty chemicals:BIS certification requirements for pharmaceutical-grade benzene create entry barriers that favor early investors in analytical-grade production.
- EU Green Deal carbon-border adjustments:CBAM implementation rewards feedstock decarbonization investments, enabling certified-low-carbon benzene derivative exports to European formulators.
- Pyrolysis oil integration:Chemical recycling of mixed plastic waste into aromatics feedstock converges with circular economy mandates, opening alternative supply channels.
Industry Challenges
- Process safety engineering talent:OSHA benzene exposure limit compliance requires specialized industrial hygiene expertise that refineries struggle to recruit.
- Refinery benzene recovery unit capex:EPA NESHAP enforcement mandates multi-million dollar extraction system upgrades at aging US Gulf Coast facilities.
- API synthesis certification timelines:Pharmaceutical customers impose 18-24 month qualification protocols for high-purity benzene grades, extending sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Benzene and Its Derivatives Market |
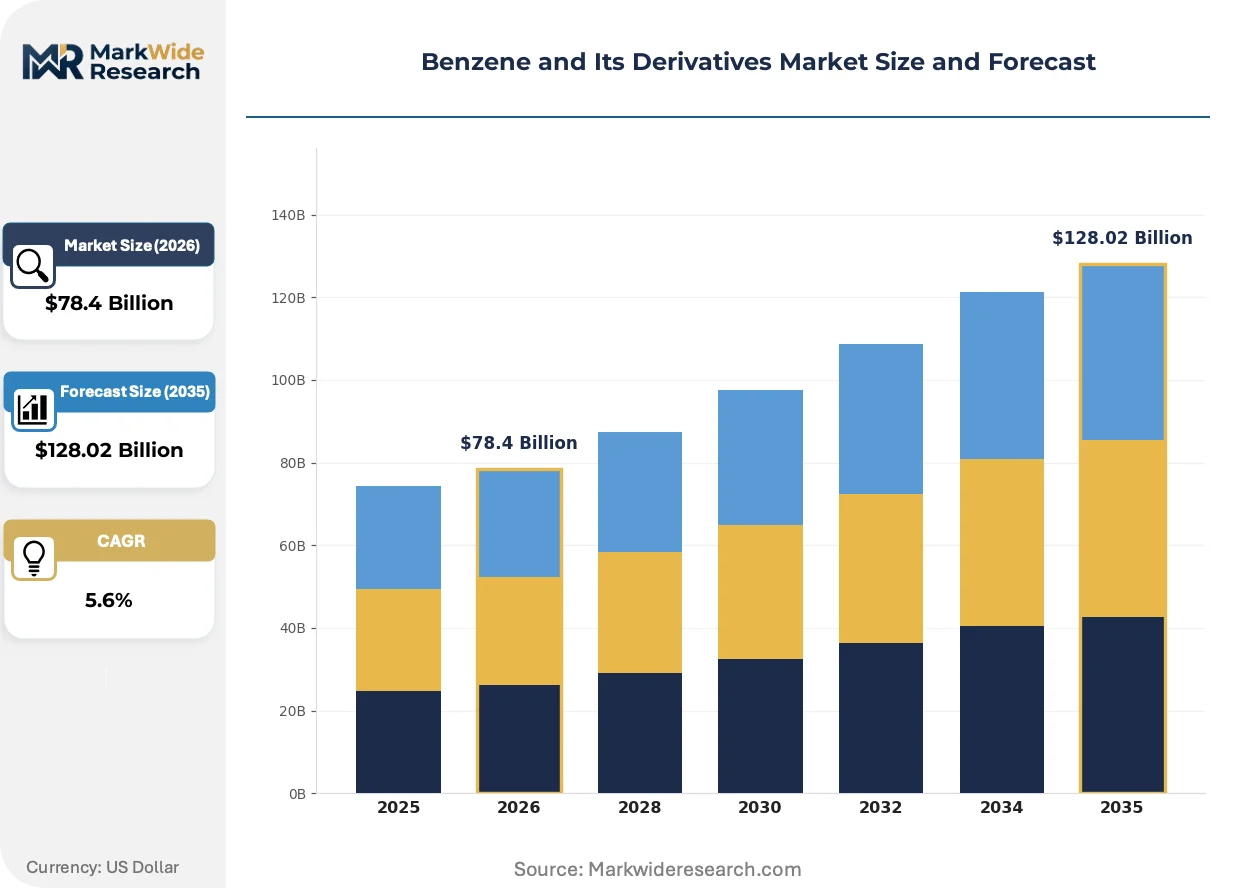
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $128.02 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benzene, Toluene, Xylene, Ethylbenzene Application: Solvents, Chemicals, Coatings, Adhesives End User: Manufacturing, Automotive, Construction, Pharmaceuticals Distribution Channel: Direct Sales, Distributors, Online Retail, Others |
| Companies Covered | BASF SE, China Petrochemical Corporation (Sinopec), Exxon Mobil Corporation, Dow Chemical Company, Royal Dutch Shell Plc, China National Petroleum Corporation, SABIC, Chevron Phillips Chemical Company LLC, Reliance Industries Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Benzene and Its Derivatives Market Emerging Trajectories
Catalytic reforming technology advances and regulatory carbon accounting are simultaneously reshaping how aromatics producers configure feedstock sourcing and derivative specialization strategies.
Alkylation catalysts enabling higher ethylbenzene selectivity from dilute ethylene streams are expanding into Asian refinery expansions. Polymer-grade styrene producers in China and South Korea adopt these systems to process refinery off-gas ethylene. The technology is expanding into merchant benzene markets by reducing reliance on dedicated ethylene crackers.
ECHA REACH authorization requirements for benzene derivatives in consumer-facing applications tightened substance evaluation protocols. Downstream formulators now demand full supply chain certification for coatings and adhesives grades. European automotive OEMs are responding by specifying REACH-compliant aromatic solvents in supplier contracts.
Long-term offtake agreements between refiners and polyester producers are displacing spot market transactions for paraxylene and PTA intermediates. Integrated PTA-polyester chains in China and the US Gulf Coast now contract directly for benzene feedstock rather than purchasing through traders. This pattern concentrates procurement leverage among vertically integrated chemical groups.
Benzene and Its Derivatives Market Segmentation
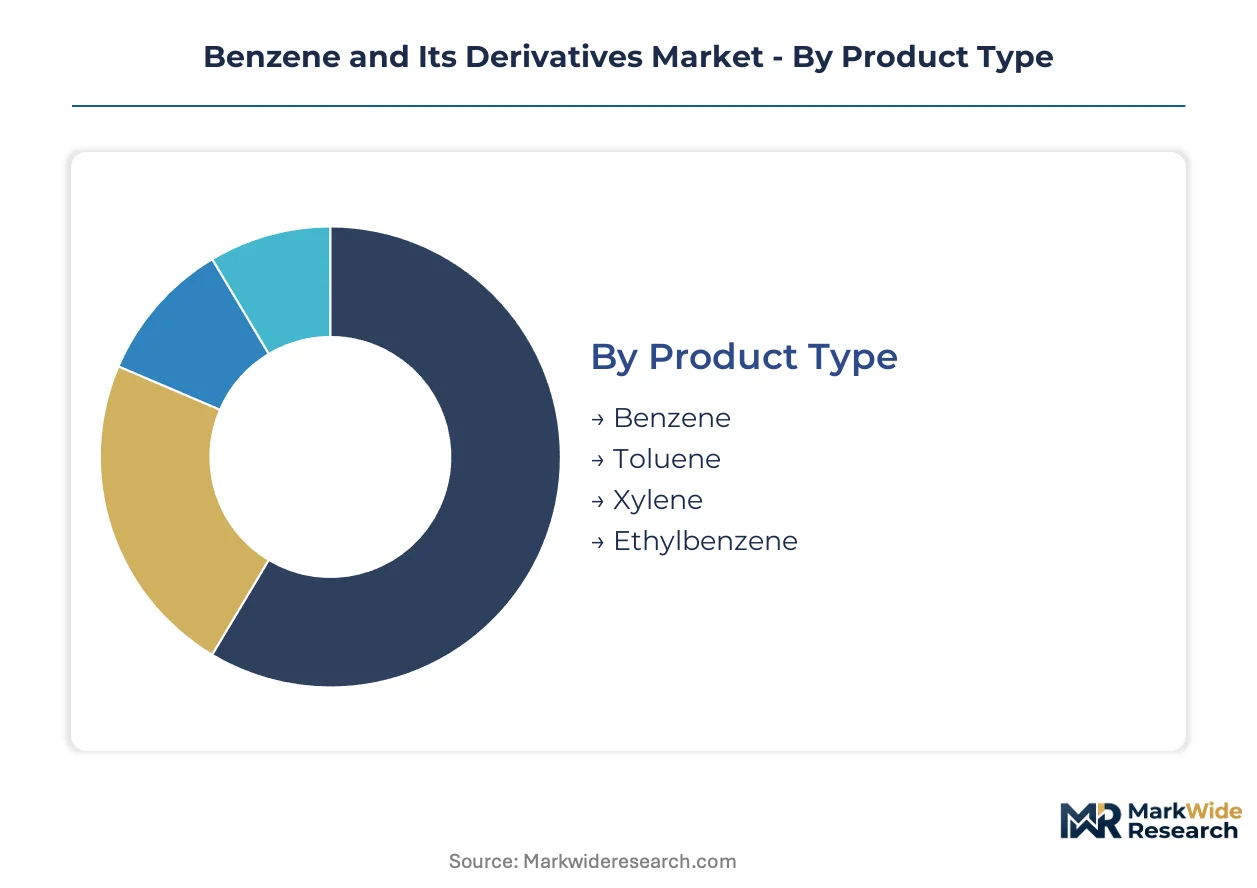
Benzene derivative specifications diverge sharply across end-use certifications, with pharmaceutical and automotive grades commanding purity premiums over industrial solvents. Segmentation strategy must align production assets with the regulatory burden each tier carries.
Product Type:
REACH authorization and API synthesis protocols impose distinct certification burdens across aromatic grades, separating pharmaceutical-specification molecules from commodity solvent streams.
- Benzene:Six-carbon aromatic ring serving as precursor to ethylbenzene, cumene, and cyclohexane. High-purity grades for API synthesis require 18-24 month customer qualification timelines at pharmaceutical manufacturers in India and Germany. EPA NESHAP compliance adds recovery unit capex for US Gulf Coast refiners.
- Toluene:Methyl-substituted aromatic functioning as octane booster and solvent intermediate. Refinery reformate streams in China and South Korea concentrate supply for coatings formulators seeking REACH-compliant solvent grades. Biobased substitution from lignocellulosic feedstocks threatens commodity demand.
- Xylene:Dimethylbenzene isomers para-, meta-, and ortho- serving polyester and coatings markets.
- Ethylbenzene:Alkylation product feeding styrene monomer production for polymer formulations.
Benzene sits at the top of the volume ranking, with ethylbenzene climbing the fastest on automotive lightweighting polymer demand.
Application:
Cost tier stratification separates specification-grade chemical intermediates from bulk solvent commodities, with coatings and adhesives carrying intermediate certification requirements.
- Solvents:Aromatic hydrocarbon blends dissolving resins in paints, coatings, and industrial degreasers. European automotive OEMs now specify REACH-compliant aromatic solvents in supplier contracts, forcing formulators to document full supply chain certification. ECHA substance evaluation protocols tightened downstream liability.
- Chemicals:Intermediate feedstocks for nylon, polyester, and rubber production. Integrated PTA-polyester chains in China and the US Gulf Coast contract directly for benzene feedstock rather than purchasing through traders, concentrating procurement leverage.
- Coatings:Protective and decorative film-forming systems for industrial and consumer substrates.
- Adhesives:Bonding agents requiring solvent carriers for viscosity control and substrate wetting.
Chemicals dominates volume through polyester and nylon intermediate demand, with solvents expanding most quickly on coatings specification upgrades.
End User:
Customer type determines volume scale and technical service intensity, with pharmaceutical buyers imposing the most rigorous qualification protocols.
- Manufacturing:Broad industrial base consuming solvents and chemical intermediates for plastics, fibers, and rubber production. Sinopec and CNPC integrated refining-aromatics complexes in China serve domestic manufacturing demand through captive supply chains. Direct sales channels dominate bulk transactions.
- Automotive:OEMs and tier suppliers specifying styrene-based polymers for vehicle lightweighting. Fuel efficiency mandates pull benzene derivatives into high-performance composites. REACH-compliant solvent specifications now appear in European supplier contracts.
- Construction:Coatings and adhesives demand from infrastructure and building applications.
- Pharmaceuticals:API synthesis requiring high-purity benzene grades with full batch traceability.
Manufacturing leads volume consumption, with pharmaceuticals gaining share fastest on purity premium capture.
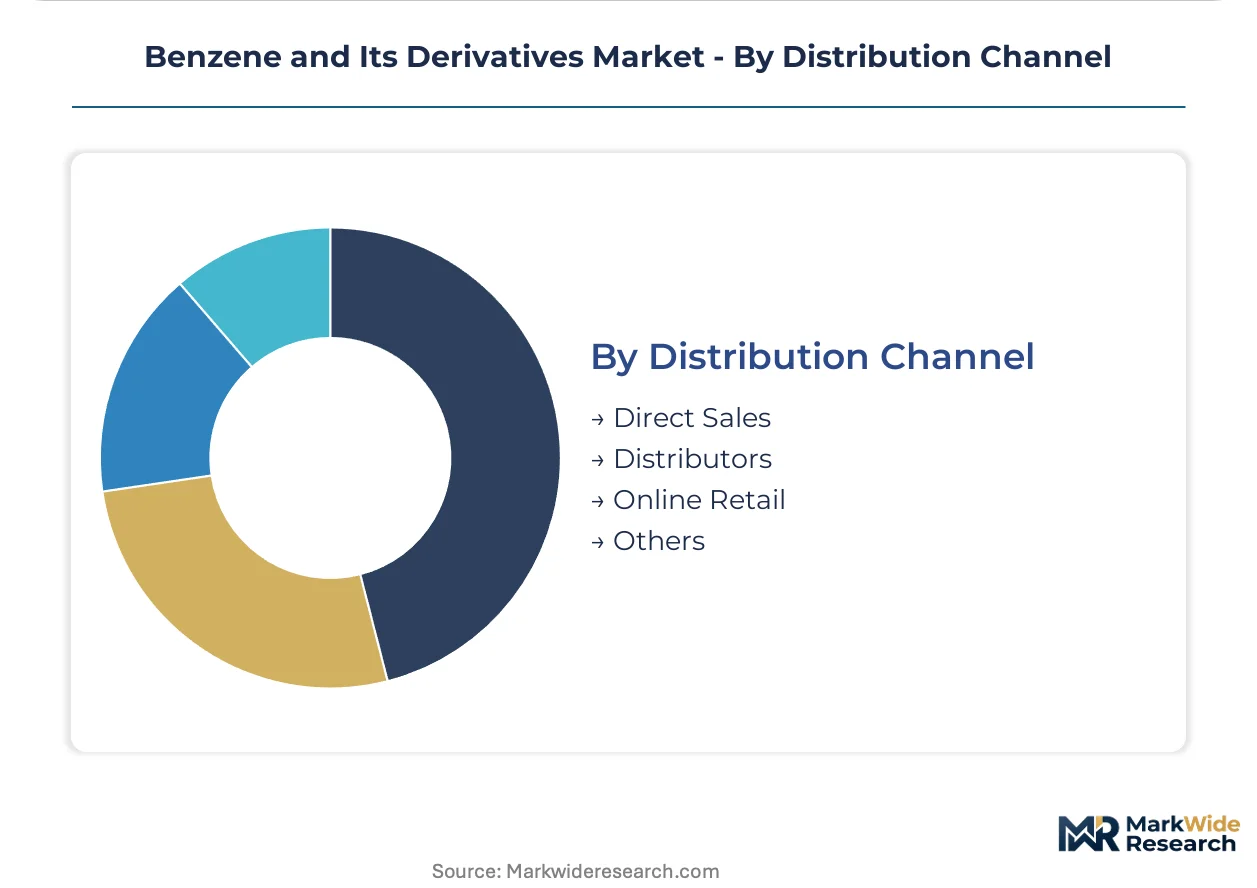
Distribution Channel:
Supply concentration shapes channel selection, with direct relationships dominating bulk aromatics and distributors occupying specialty niches.
- Direct Sales:Refiner-to-producer contracts for bulk benzene, toluene, and xylene streams. Long-term offtake agreements between integrated refiners and polyester producers displace spot market transactions for paraxylene and PTA intermediates. BASF Ludwigshaven and INEOS Köln sustain direct supply chains to European nylon producers.
- Distributors:Technical service bundling for specialty chemical niches requiring formulation support. Smaller coatings and adhesives formulators rely on distributor networks for REACH-compliant solvent grades with documented certification.
- Online Retail:Digital platforms for small-volume laboratory and pilot-scale aromatic purchases.
- Others:Brokered transactions and trader-mediated spot market activity.
Direct Sales commands the volume ranking, with Distributors expanding fastest on specialty certification service demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zhenhai and Maoming refining-aromatics complexes anchor benzene derivative production capacity, with Sinopec and CNPC integrated sites serving polyester and rubber demand chains. Regulatory frameworks across major producing jurisdictions reshape certification requirements and feedstock sourcing protocols.
China
Sinopec and CNPC operate dedicated aromatics complexes at Zhenhai and Maoming serving domestic polyester manufacturers. MEE dual carbon goals tighten feedstock decarbonization timelines for refinery benzene recovery units. Yangtze River Delta chemical clusters concentrate PTA-polyester integration with direct offtake contracting displacing spot markets.
United States
Shale gas economics favor direct ethane cracking, reducing merchant benzene availability from Gulf Coast steam crackers. EPA NESHAP enforcement mandates multi-million dollar benzene recovery unit upgrades at aging Texas and Louisiana refineries. Exxon Mobil operates dedicated cyclohexane and cumene derivative streams at Baytown and Baton Rouge complexes.
Germany
BASF Ludwigshaven Verbund sustains integrated benzene-to-caprolactam margins for European nylon producers. ECHA REACH authorization requirements restrict uncontrolled benzene derivative uses in consumer-facing coatings and adhesives. INEOS Köln anchors EU supply chains with direct sales to downstream formulators seeking certified-grade aromatics.
India
Reliance Industries Limited operates refining-aromatics integration at Jamnagar serving domestic manufacturing demand. BIS certification requirements for pharmaceutical-grade benzene create entry barriers favoring early analytical-grade investors. Gujarat chemical clusters concentrate API synthesis demand requiring high-purity benzene grades with full batch traceability.
Saudi Arabia
SABIC leverages feedstock access at Jubail industrial city for aromatics production serving Asian export markets. The country's national industrial regulator aligns petrochemical standards with EU Green Deal carbon-border adjustment timelines. Eastern Province refining-petrochemical integration captures derivative margin through captive ethylbenzene and styrene monomer streams.
Benzene and Its Derivatives Market Vendor Landscape
Global majors compete with regional champions across integrated refining-aromatics value chains, with scale advantages concentrating in Gulf Coast and Chinese coastal complexes. The market structure tiers between Verbund-integrated European producers, state-backed Asian refining giants, and independent Gulf Coast derivative specialists. Three archetypes dominate: backward-integrated oil majors controlling feedstock-to-derivative chains, national champions serving captive domestic demand, and specialty distributors bundling REACH certification services. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with pyrolysis oil integration emerging as a circular economy positioning tool.
Among state-backed Asian champions, China Petrochemical Corporation (Sinopec) and China National Petroleum Corporation occupy positions exemplifying integrated refining-aromatics dominance through Zhenhai and Maoming complexes. BASF SE represents the European Verbund archetype at Ludwigshaven, while Exxon Mobil Corporation anchors Gulf Coast scale positioning. These three entities exemplify how feedstock control, regulatory compliance infrastructure, and derivative specialization stratify competitive access across pharmaceutical-grade, automotive-specification, and commodity solvent market tiers.
| Leading Market Players |
|---|
| BASF SE |
| China Petrochemical Corporation (Sinopec) |
| Exxon Mobil Corporation |
| Dow Chemical Company |
| Royal Dutch Shell Plc |
| China National Petroleum Corporation |
| SABIC |
| Chevron Phillips Chemical Company LLC |
| Reliance Industries Limited |
| Others |
Supply Flow & Price Mechanics
EU Green Deal carbon-border adjustments gate qualified supply and premium-tier pricing access, forcing feedstock decarbonization investments that separate certified-low-carbon benzene derivatives from commodity grades. Producers meeting ECHA REACH authorization requirements capture margin premiums while uncertified supply faces exclusion from European formulator procurement.
Pricing Analysis
Input-cost pass-through from naphtha spreads dominates benzene derivative pricing, with contract-based long-term offtake agreements insulating integrated refiners from spot volatility. Price differentiation separates pharmaceutical-grade benzene commanding purity premiums from industrial solvent commodities, with certification level and volume scale as key drivers. Cost compression in commodity toluene intensifies because biobased aromatic substitution threatens coatings demand. Small coatings formulators exhibit highest price sensitivity, while pharmaceutical manufacturers prioritize batch traceability over cost.
Supply Chain Analysis
Warehouse-distribution layers concentrate around Yangtze River Delta chemical clusters and US Gulf Coast petrochemical corridors, with regional distribution centers feeding downstream PTA-polyester and nylon producers. Geographic supply concentrates in China, the United States, and Germany, with feedstock anchored in naphtha reforming and ethane cracking economics. Raw material dependencies include petroleum feedstocks, alkylation catalysts, and hydrogen for hydrotreating. Single-source vulnerability runs through BASF Ludwigshaven and INEOS Köln for European caprolactam chains. Distribution runs through direct refiner-to-producer contracts displacing spot market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Benzene and Its Derivatives Market functions as a stable compounder, with automotive lightweighting mandates pulling steady styrene demand into polymer formulations across OEM supply chains.
For Market Incumbents: To counter biobased aromatic substitution threats, BASF SE and Sinopec should deepen backward integration into pyrolysis oil feedstock streams while expanding analytical-grade production capacity at Zhenhai and Ludwigshaven to capture pharmaceutical purity premiums.
For New Entrants and Emerging Players: Begin with BIS-certified pharmaceutical-grade benzene production in Gujarat chemical clusters, targeting API synthesis demand from domestic formulators seeking import substitution. A technical service bundling approach through distributor partnerships overcomes qualification timeline barriers.
For Investors and Strategic Acquirers: Valuations sit cheapest among independent Gulf Coast derivative specialists lacking feedstock integration. The five-to-ten year viability window favors assets with EPA NESHAP-compliant recovery infrastructure. Watch for CBAM implementation acceleration as the inflection signal for feedstock decarbonization investment returns.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pyrolysis Oil | Chemical recycling of mixed plastic waste aligns with circular economy mandates at Sinopec and BASF complexes. |
| Pharmaceutical-Grade Capacity Expansion | Analytical-grade benzene production in Gujarat and Ludwigshaven captures API synthesis margin premiums. |
| Long-term Supply Agreement | Direct offtake contracts between Zhenhai refiners and polyester producers displace spot market volatility. |
| Green Manufacturing Transition | Feedstock decarbonization investments enable certified-low-carbon derivative exports under EU CBAM. |
| Joint Venture | Regional distribution partnerships in Yangtze River Delta clusters consolidate procurement leverage. |
Methodological Framework
Direct dialogue with refinery operations managers, pharmaceutical procurement leads at API manufacturers, coatings formulator technical directors, and petrochemical distribution channel partners grounded the qualitative foundation. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and EPA NESHAP compliance disclosures. Bottom-up capacity modeling and top-down demand triangulation cross-verified volume estimates across the analysis window.
Segment-level outputs across product type, application, end user, and distribution channel dimensions were generated through econometric modeling of feedstock spread correlations and derivative demand elasticity. CAGRs were derived from regression analysis against historical naphtha-benzene price relationships and polyester production forecasts. Industry-specific inputs included catalytic reforming capacity expansion schedules and REACH authorization timeline assumptions.
Several conditions sit outside the modeled scope, including unannounced refinery shutdowns, abrupt crude oil price dislocations, and regulatory acceleration beyond EU Green Deal timelines. Forecasts reflect documented assumptions regarding shale gas economics persistence and automotive lightweighting program continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Ethoxydiglycol Market
Solvents
N-Pentyl Chloride Market
Solvents
Green Solvents Market
Solvents
Global Trichloroethylene and Perchloroethylene Market
Solvents
Phenol Derivatives Market
Solvents
Ortho-Xylene Market
Solvents
N-Hexane Market
Solvents
Butyl Acetate (BAC) Market
Solvents
6-Xylenol Market
Solvents
Asia-Pacific Ethane Market
Solvents
Global Xylenols Market
Solvents
Oxygenated Solvents Market
Solvents
1,2-Ethanedithiol Market
Solvents
Acetone Market
Solvents
Hexylene Glycol Market
Solvents
Nitroglycerin Market