
 Ethoxydiglycol Market | 2026-2036
Ethoxydiglycol Market Size, Share, and Industry Trends Forecast 2026-2036
Ethoxydiglycol Market Analysis
Consolidation among multinational cosmetics manufacturers is repositioning procurement leverage toward fewer buyers with stricter solvent specifications. Dow leverages backward integration into ethylene oxide feedstock to sustain cost discipline across cosmetic-grade batches. BASF SE anchors European supply through REACH-compliant production networks. Eastman Chemical Company differentiates via pharmaceutical-grade certification that commands premium positioning.
Ethoxydiglycol is a diethylene glycol monoethyl ether, a clear hygroscopic liquid with a molecular weight of 134.17 g/mol and a boiling point of 196°C, manufactured through ethoxylation of ethanol with ethylene oxide. It functions primarily as a solubilizer, viscosity modifier, and penetration enhancer in topical formulations and industrial coatings. Cosmetic Grade leads value contribution due to stringent heavy-metal limits and GMP-adjacent documentation requirements, while Pharmaceutical Grade represents the fastest-expanding margin pool as injectable and transdermal applications multiply. Industrial Grade occupies mature volume positions in coatings and adhesives where price sensitivity limits premium capture.
EPA oversight of glycol ether emissions shapes manufacturing site selection and abatement investment in United States production facilities. REACH registration and ECHA classification protocols in Europe restrict non-compliant imports and elevate documentation burdens for cosmetic-grade suppliers. India's BIS quality standards and CDSCO pharmaceutical excipient rules are tightening as domestic formulators scale. Stakeholders must monitor regulatory divergence across these jurisdictions to anticipate reformulation costs and qualification timelines.
Market Dynamics
REACH registration deadlines and EPA emission standards are tightening purity specifications across cosmetic and pharmaceutical grades, forcing suppliers to reconfigure purification trains and documentation systems ahead of qualification timelines.
Growth Catalysts
- India personal care manufacturing expansion:Domestic formulators are scaling production of skin-conditioning products, drawing solvent demand toward BIS-compliant supply chains.
- Injectable formulation growth:Pharmaceutical-grade ethoxydiglycol serves as a penetration enhancer in transdermal and parenteral applications, expanding addressable volume beyond topical cosmetics.
- REACH registration completion:Full dossier acceptance by ECHA has clarified import compliance pathways, reducing regulatory uncertainty for European cosmetic manufacturers.
Market Restraints
- Ethylene oxide feedstock volatility:Cracker output fluctuations and derivative demand competition compress margin predictability for non-integrated producers.
- Substitution by propylene glycol derivatives:Formulators seeking lower-toxicity profiles in leave-on cosmetics are piloting alternative solubilizers with comparable humectancy.
- EPA glycol ether emission limits:Abatement capital requirements for United States production sites disadvantage smaller batch manufacturers against integrated majors.
Strategic Opportunities
- Brazil pharmaceutical excipient qualification:ANVISA registration for transdermal applications remains underpenetrated by European and North American suppliers.
- Continuous processing technology:Adoption of flow chemistry for ethoxylation reactions promises yield improvements and reduced batch-to-batch variation for pharmaceutical-grade output.
- PLI scheme alignment in India:Domestic chemical manufacturing incentives support backward integration projects that captive ethylene oxide supply for cosmetic-grade production.
Industry Challenges
- Cross-contamination control in multi-grade facilities:Shared equipment between industrial and pharmaceutical batches demands validated cleaning protocols that extend turnaround times.
- Heavy-metal analytical capability gaps:Cosmetic-grade specifications below 10 ppm for lead and arsenic require ICP-MS instrumentation that smaller toll manufacturers lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethoxydiglycol Market |
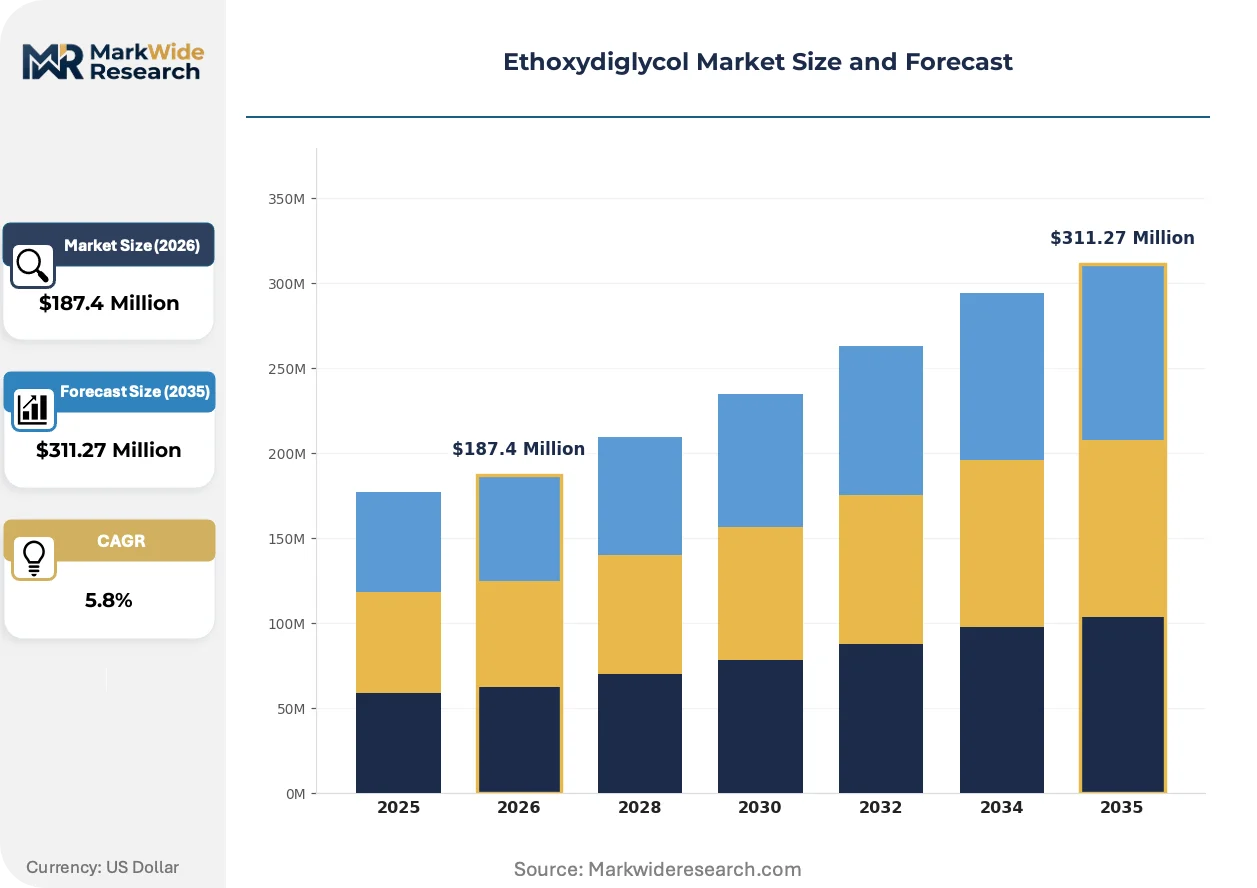
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Cosmetic Grade, Pharmaceutical Grade, Food Grade Application: Personal Care, Cleaning Products, Adhesives, Coatings End User: Cosmetics Manufacturers, Pharmaceutical Companies, Food Processors, Industrial Suppliers Distribution Channel: Online Retailers, Direct Sales, Wholesalers, Distributors |
| Companies Covered | Dow, Eastman Chemical Company, BASF SE, Merck KGaA, Gattefosse, Solvay, Wacker Chemie AG, INEOS, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethoxydiglycol Market Emerging Trajectories
Membrane filtration and continuous ethoxylation systems are displacing conventional batch processing, while regulatory documentation automation and blockchain traceability reshape supplier-customer data exchange.
Membrane-based purification is consolidating quality control for cosmetic-grade ethoxydiglycol. Korean and Japanese skincare manufacturers now mandate sub-5 ppm heavy-metal certificates as standard purchase terms. This specification compression is consolidating supplier bases toward integrated producers with captive analytical laboratories and multi-stage filtration assets.
ECHA's updated REACH dossier requirements for glycol ethers entered force in 2023, mandating extended mammalian toxicity studies for registration renewal. German and French cosmetic formulators are accelerating supplier audits to pre-qualify compliant sources ahead of 2027 deadlines. The documentation burden is compressing procurement lists toward REACH-registered producers with established IUCLID archives.
Direct supplier relationships are displacing distributor intermediaries in pharmaceutical-grade procurement. Large transdermal patch manufacturers in the United States and Germany now require batch-specific CoA data transmitted via validated electronic systems. This channel compression is visible most acutely in parenteral excipient qualification, where documentation integrity requirements exceed distributor technical capabilities.
Ethoxydiglycol Market Segmentation
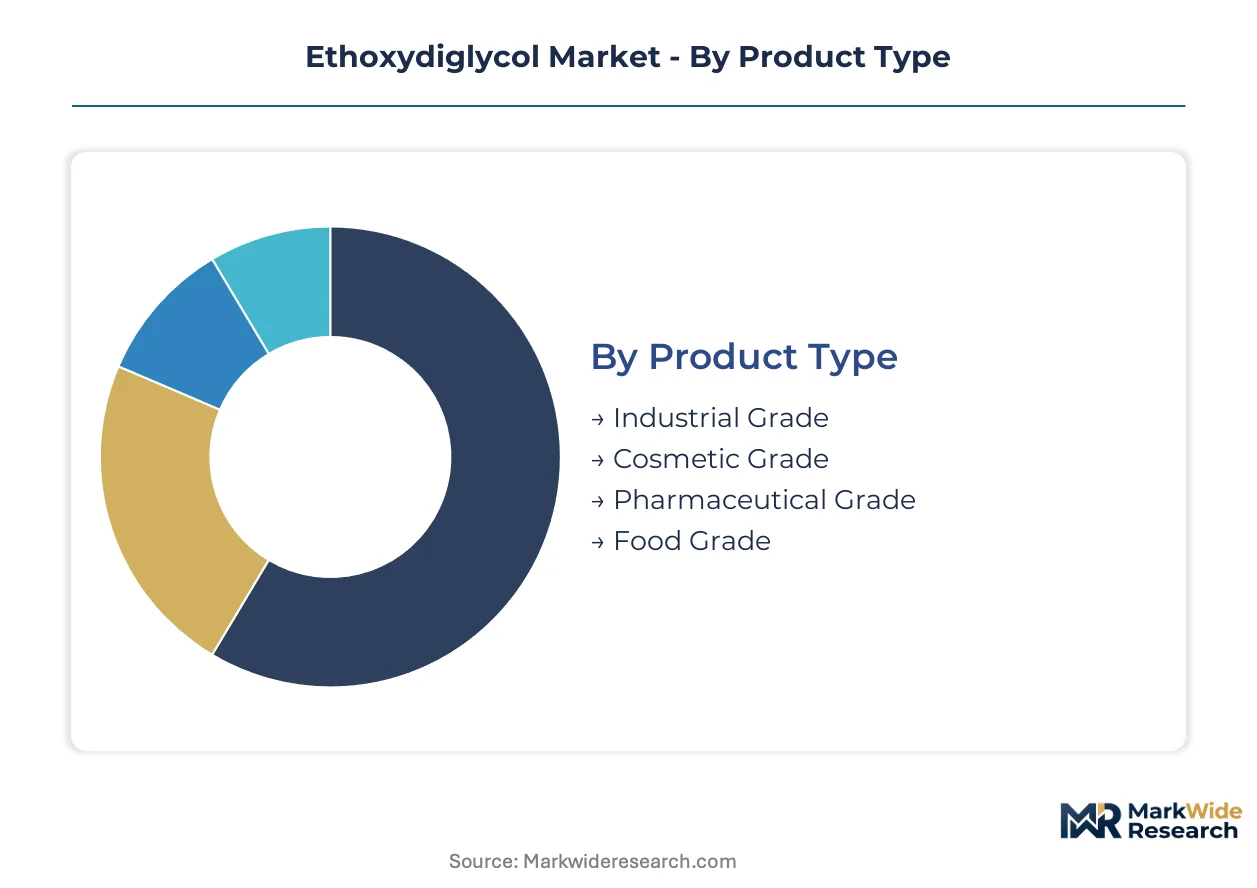
Ethoxydiglycol procurement hinges on purity thresholds that vary dramatically across end-use contexts. Buyers select grades based on regulatory exposure, performance requirements, and documentation burdens rather than price alone.
Product Type:
Purchasing decisions center on contaminant limits and certification documentation that determine qualification for regulated applications.
- Cosmetic Grade:Heavy-metal specifications below 10 ppm for lead and arsenic, validated via ICP-MS analysis. Korean and Japanese skincare manufacturers now mandate sub-5 ppm certificates as standard purchase terms, consolidating supply toward integrated producers with captive analytical laboratories.
- Pharmaceutical Grade:GMP-adjacent documentation and batch-specific CoA requirements for transdermal and parenteral applications. Injectable formulation growth is expanding addressable volume beyond topical cosmetics as transdermal patch manufacturers scale production.
- Industrial Grade:Mature volume positions in coatings and adhesives where price sensitivity limits premium capture.
- Food Grade:FSSAI and FDA compliance for limited direct-contact applications.
Cosmetic Grade leads on scale; Pharmaceutical Grade leads on momentum.
Application:
Volume distribution tracks regulatory intensity and formulation complexity across consumer and industrial sectors.
- Personal Care:Skin-conditioning formulations and solubilizer functions in leave-on products. India domestic formulators are scaling production, drawing solvent demand toward BIS-compliant supply chains with validated heavy-metal documentation.
- Adhesives:Viscosity modification and coalescing aid in industrial bonding formulations.
- Coatings:Mature demand from architectural and industrial paint manufacturers where EPA emission standards shape site selection.
- Cleaning Products:Limited penetration due to substitution by lower-cost glycol alternatives.
Personal Care commands volume concentration; Adhesives maintains steady offtake.
End User:
Customer scale determines procurement channel preferences and documentation sophistication requirements.
- Cosmetics Manufacturers:Consolidating procurement leverage toward fewer buyers with stricter solvent specifications. Large formulators now require batch-specific CoA data transmitted via validated electronic systems, displacing distributor intermediaries.
- Pharmaceutical Companies:Direct supplier relationships for parenteral excipient qualification where documentation integrity exceeds distributor technical capabilities.
- Industrial Suppliers:Price-sensitive volume procurement for coatings and adhesives applications.
- Food Processors:Niche demand constrained by limited approved applications.
Cosmetics Manufacturers dominate procurement volume; Pharmaceutical Companies drive specification escalation.
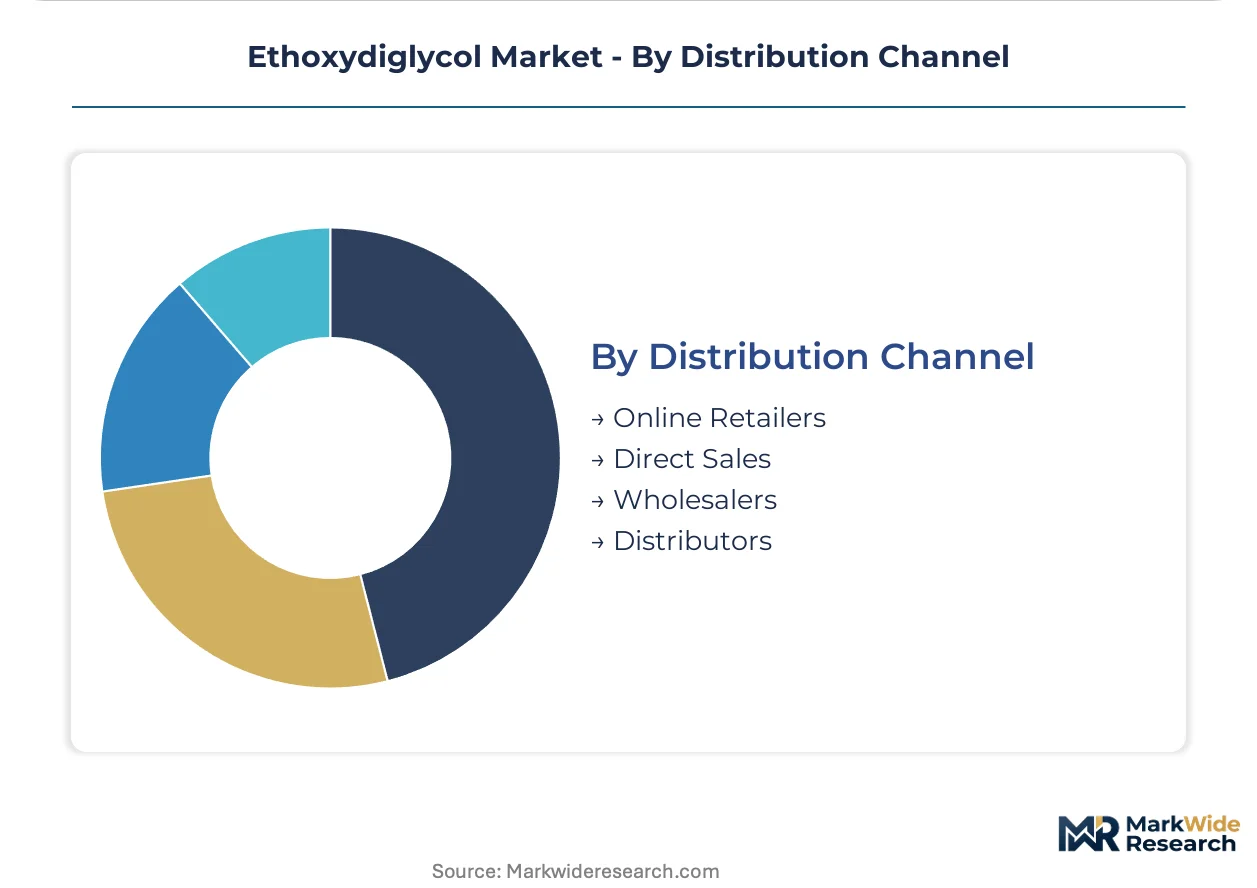
Distribution Channel:
Channel selection reflects customer technical requirements and transaction scale thresholds.
- Direct Sales:Pharmaceutical-grade procurement requiring validated electronic data exchange and audit trail integrity. Large transdermal patch manufacturers in the United States and Germany have compressed channels toward direct relationships.
- Distributors:Industrial Grade volume sales where documentation burdens remain minimal.
- Online Retailers:Emerging for small-batch cosmetic formulators with standardized grade requirements.
- Wholesalers:Legacy channel for mature industrial applications with predictable demand patterns.
Direct Sales captures premium-tier transactions; Distributors retains industrial volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's domestic personal care manufacturing is scaling faster than Germany's pharmaceutical-grade export consolidation, yet both markets face tightening purity specifications from their respective national regulators.
United States
Transdermal patch manufacturers in New Jersey and California are scaling pharmaceutical-grade procurement with validated electronic data exchange requirements. EPA glycol ether emission limits are forcing abatement investments at production sites in Texas and Louisiana. The Gulf Coast chemical corridor retains concentrated ethylene oxide feedstock access for integrated producers.
Germany
ECHA's updated REACH dossier requirements are accelerating supplier audits by cosmetic formulators in Hamburg and Frankfurt ahead of 2027 deadlines. Extended mammalian toxicity studies for glycol ether registration renewal are compressing procurement lists toward REACH-registered producers with established IUCLID archives. The Rhine-Ruhr industrial cluster anchors European supply chain qualification.
India
Domestic formulators in Maharashtra and Gujarat are scaling skin-conditioning product manufacturing, drawing solvent demand toward BIS-compliant supply chains. CDSCO pharmaceutical excipient rules are tightening as local production expands. The PLI scheme for chemical manufacturing is incentivizing backward integration projects that captive ethylene oxide supply.
China
Skincare manufacturers in Shanghai and Guangdong are mandating sub-5 ppm heavy-metal certificates as standard purchase terms. NMPA oversight of cosmetic raw materials is elevating documentation requirements for imported ethoxydiglycol. The Yangtze River Delta concentration of membrane filtration technology suppliers is consolidating quality control capabilities.
Brazil
ANVISA registration for transdermal applications remains underpenetrated by European and North American suppliers, creating qualification opportunities. São Paulo-based pharmaceutical formulators are expanding parenteral excipient sourcing as domestic production scales. The country's national pharmaceutical regulator is aligning import documentation with international GMP-adjacent standards.
Ethoxydiglycol Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across grade-specific market tiers. The vendor base segments into three strategic archetypes: integrated petrochemical majors with captive ethylene oxide supply, specialty chemical houses with pharmaceutical-grade certification, and regional toll manufacturers serving industrial-grade volume. Capacity expansion and REACH registration completion represent the dominant competitive moves, with smaller batch producers disadvantaged by analytical capability investment requirements.
Among integrated petrochemical majors, Dow and BASF SE exemplify the backward-integrated archetype with upstream control over ethylene oxide feedstock. Eastman Chemical Company occupies a position within the specialty certification tier, representing producers who differentiate via pharmaceutical-grade documentation. These three anchors illustrate how competitive positioning stratifies across feedstock security, regulatory compliance depth, and end-market grade specialization.
| Leading Market Players |
|---|
| Dow |
| Eastman Chemical Company |
| BASF SE |
| Merck KGaA |
| Gattefosse |
| Solvay |
| Wacker Chemie AG |
| INEOS |
| Thermo Fisher Scientific |
| Others |
Supply Flow & Price Mechanics
Analytical chemist concentrations in the Rhine-Ruhr corridor and Gujarat's chemical belt create labor-cost differentials that widen pricing-tier spreads between European pharmaceutical-grade batches and Indian cosmetic-grade output.
Pricing Analysis
Capacity additions in India are reshaping price floors for cosmetic-grade ethoxydiglycol as domestic membrane filtration investments compress heavy-metal certification costs. Three-tier pricing structure across pharmaceutical, cosmetic, and industrial grades anchors the market, with certification level and volume scale as the primary price differentiation drivers. Pricing pressure stems from ethylene oxide feedstock volatility as cracker output fluctuations compress margin predictability for non-integrated producers. Industrial coatings buyers exhibit the highest price sensitivity, while pharmaceutical transdermal patch manufacturers absorb premiums for validated electronic CoA systems.
Supply Chain Analysis
Freight cost differentials between bulk liquid tanker shipments and drum-container parcel deliveries shape procurement channel selection across customer tiers. Supply concentrates in the United States, Germany, and India as integrated producers leverage Gulf Coast ethylene oxide access, Rhine-Ruhr REACH-registered infrastructure, and Gujarat's PLI-supported backward integration. Raw material dependencies center on ethylene oxide, ethanol feedstock, and specialty membrane filtration media. Single-source vulnerability for pharmaceutical-grade ICP-MS analytical capability creates qualification bottlenecks. Distribution runs through direct sales for premium grades and regional distributors for industrial volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ethoxydiglycol market functions as a stable compounder, with regulatory specification tightening across REACH, EPA, and BIS jurisdictions driving steady value migration toward certified producers.
For Market Incumbents: Hedge ethylene oxide exposure through captive cracker relationships or long-term offtake agreements with Gulf Coast producers. Expand membrane filtration capacity in India to capture BIS-compliant cosmetic-grade demand as domestic formulators scale. Counter propylene glycol substitution threats by embedding batch-specific CoA data exchange into customer ERP systems, locking in pharmaceutical-grade relationships. For New Entrants and Emerging Players: The mid-tier price gap between Dow's integrated pharmaceutical-grade positioning and regional Indian toll manufacturers presents white-space opportunity. Target Brazil's ANVISA-registered transdermal excipient segment, where European and North American suppliers remain underpenetrated. Qualify through continuous processing technology partnerships with Yangtze River Delta equipment vendors to differentiate on yield consistency. For Investors and Strategic Acquirers: Specialty chemical houses with pharmaceutical-grade certification represent the most active acquirer category in this space, consolidating REACH-registered assets ahead of 2027 dossier deadlines. Five-to-ten-year viability favors integrated producers with captive ethylene oxide and multi-grade flexibility. Monitor CDSCO excipient rule harmonization as the inflection signal for Indian pharmaceutical-grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide | Dow and BASF SE anchor margin stability through captive Gulf Coast and Antwerp feedstock supply. |
| Membrane Filtration Capacity Expansion | Korean and Japanese skincare mandates for sub-5 ppm heavy-metal certificates consolidate supply toward equipped producers. |
| REACH Registration Completion | ECHA's 2023 dossier requirements compress procurement lists toward IUCLID-registered suppliers. |
| Continuous Processing Technology Adoption | Flow chemistry investments promise yield improvements and reduced batch-to-batch variation for pharmaceutical output. |
| Direct Sales Channel Compression | Transdermal patch manufacturers in New Jersey and Germany displace distributor intermediaries for excipient procurement. |
Methodological Framework
Bottom-up personal care and pharmaceutical formulation modeling reconciled against top-down ethylene oxide derivative production tracking forms the analytical core. Primary interviews with cosmetic R&D directors, pharmaceutical excipient procurement managers, chemical plant operations heads, and BIS compliance officers combined with secondary validation from REACH registration databases, CDSCO pharmaceutical excipient filings, customs trade data, and SEC chemical sector disclosures. Triangulation between demand-side qualification timelines and supply-side capacity announcements anchors volume estimates.
Historical trendline analysis of cosmetic-grade heavy-metal specification compression and pharmaceutical-grade GMP-adjacent documentation proliferation informed projection frameworks. Segmentation dimensions span grade tier, end-use application, customer scale archetype, and regional regulatory cluster. CAGRs derive from ethoxylation capacity utilization rates, personal care manufacturing expansion trajectories, and injectable formulation growth curves across the projection horizon.
Caveats apply where ethylene oxide feedstock disruptions, accelerated propylene glycol substitution in leave-on cosmetics, or unanticipated REACH dossier rejection could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
N-Hexane Market
Solvents
Global Chloroform Market
Solvents
Pharmaceutical Solvent Market
Solvents
Ketene Market
Solvents
Ethyl Pyruvate Market
Solvents
Oxygenated Solvents Market
Solvents
Trichloroacetyl Chloride Market
Solvents
Green Solvents and Bio-Solvents Market
Solvents
Diethylene Glycol Monobutyl Ether Market
Solvents
Methyl Diethanolamine Market
Solvents
Crotonaldehyde Market
Solvents
Phenylacetonitrile Market
Solvents
2-Butanone Market
Solvents
Isoparaffin Solvents Market
Solvents
C2 Chlorinated Solvents Market
Solvents
2 - Ethyl Anthraquinone Market