
 Ortho-Xylene Market | 2026-2036
Ortho-Xylene Market Size, Share, and Industry Trends Forecast 2026-2036
Ortho-Xylene Market Outlook
Asian refinery expansion is consolidating captive ortho-xylene output for downstream phthalic anhydride circuits. Exxon Mobil Corporation leverages integrated Gulf Coast aromatics infrastructure to sustain export-grade purified ortho-xylene positions. Mitsubishi Gas Chemical Company anchors high-purity supply chains serving Japanese specialty chemical and pharmaceutical offtake. Reliance Industries Limited dominates Jamnagar complex economics through backward integration into mixed xylenes and captive hydrogenation capacity.
Ortho-xylene is a C8 aromatic hydrocarbon with a 1,2-dimethylbenzene structure, boiling point of 144°C, and primary industrial purpose as feedstock for phthalic anhydride oxidation. Purified ortho-xylene commands premium pricing in pharmaceutical and high-performance coatings applications where isomer purity exceeds 99.5 percent. Mixed xylenes represent the volume base feeding integrated splitter units, while aromatic hydrocarbon production applications concentrate margin pools with refinery-chemical complexes that co-produce benzene and paraxylene. Direct sales channels control bulk terminal movements to large phthalate ester and unsaturated polyester resin manufacturers.
EPA National Emission Standards for Hazardous Air Pollutants constrain US refinery aromatics extraction emissions, while REACH and ECHA classification protocols govern European ortho-xylene handling, labeling, and downstream chemical registration. China's MEE enforces dual carbon monitoring on steam cracker and reformer units, pushing producers toward energy-efficient xylene isomerization and selective toluene disproportionation. Stakeholders must monitor how carbon border adjustment mechanisms and regional benzene-toluene-xylene spread volatility reshape locational arbitrage for purified ortho-xylene volumes.
Market Dynamics
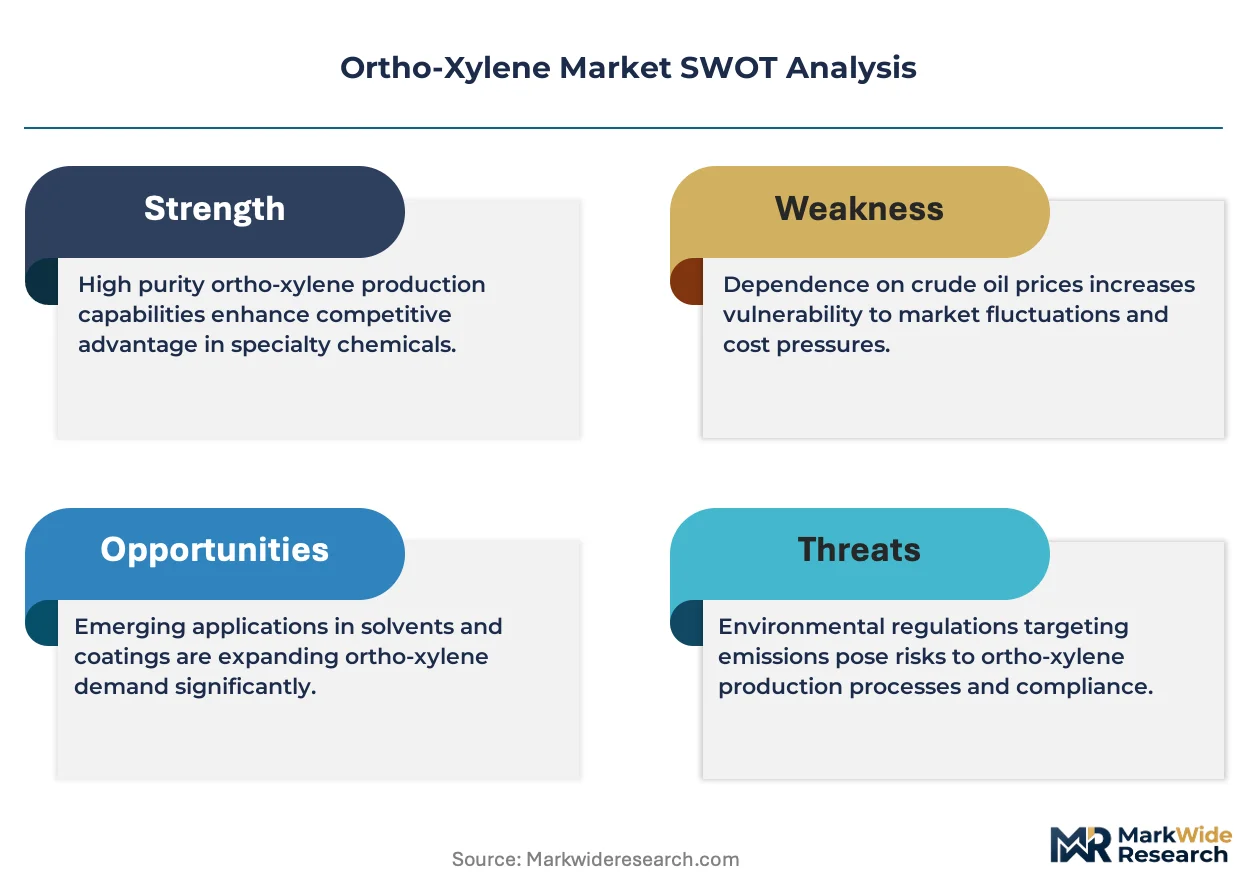
China's MEE dual carbon enforcement is compressing paraxylene-ortho-xylene production ratios across integrated petrochemical corridors, forcing refinery-chemical complexes to reconfigure aromatics extraction economics around carbon intensity rather than volume yield alone.
Growth Catalysts
- Construction sector phthalate ester consumption:Polyester resin manufacturing for infrastructure coatings and fiberglass-reinforced plastics pulls purified ortho-xylene through phthalic anhydride oxidation circuits.
- REACH downstream chemical registration:European coatings formulators seeking supply chain transparency favor high-purity isomer grades exceeding 99.5 percent for pharmaceutical and high-performance applications.
- Yangzi and Zhenhai mega-complex expansion:East China refining corridors concentrate captive hydrogenation and xylene isomerization capacity serving domestic phthalic anhydride producers.
Market Restraints
- Mixed xylene feedstock volatility:Benzene-toluene-xylene spread compression erodes margin pools for non-integrated aromatics extractors dependent on spot mixed xylene procurement.
- Paraxylene priority allocation:Integrated complexes facing carbon quotas prioritize higher-margin paraxylene for polyester fiber feedstock, constraining ortho-xylene splitter throughput.
- EPA National Emission Standards compliance costs:US Gulf Coast aromatics infrastructure faces capital-intensive emission control retrofits on extraction and fractionation units.
Strategic Opportunities
- Jamnagar complex export positioning:India's captive mixed xylenes and backward integration into hydrogenation capacity enables purified ortho-xylene export arbitrage to Southeast Asian coating resin manufacturers.
- Pharmaceutical-grade isomer demand:Japanese specialty chemical and pharmaceutical offtake commands premium pricing for ultra-high-purity ortho-xylene in active pharmaceutical intermediate synthesis.
- Selective toluene disproportionation adoption:Energy-efficient xylene isomerization technologies reduce carbon intensity per ton, aligning with China's MEE monitoring frameworks while preserving yield economics.
Industry Challenges
- Carbon border adjustment mechanism readiness:European importers face documentation and certification complexity proving embedded emissions compliance for ortho-xylene-derived phthalate esters.
- Legacy refinery-chemical integration retrofitting:Older aromatics complexes lack selective hydrogenation and advanced isomerization catalyst systems required for dual carbon compliance.
- Phthalate ester regulatory substitution pressure:Non-phthalate plasticizer alternatives in consumer goods packaging threaten long-term phthalic anhydride offtake stability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ortho-Xylene Market |
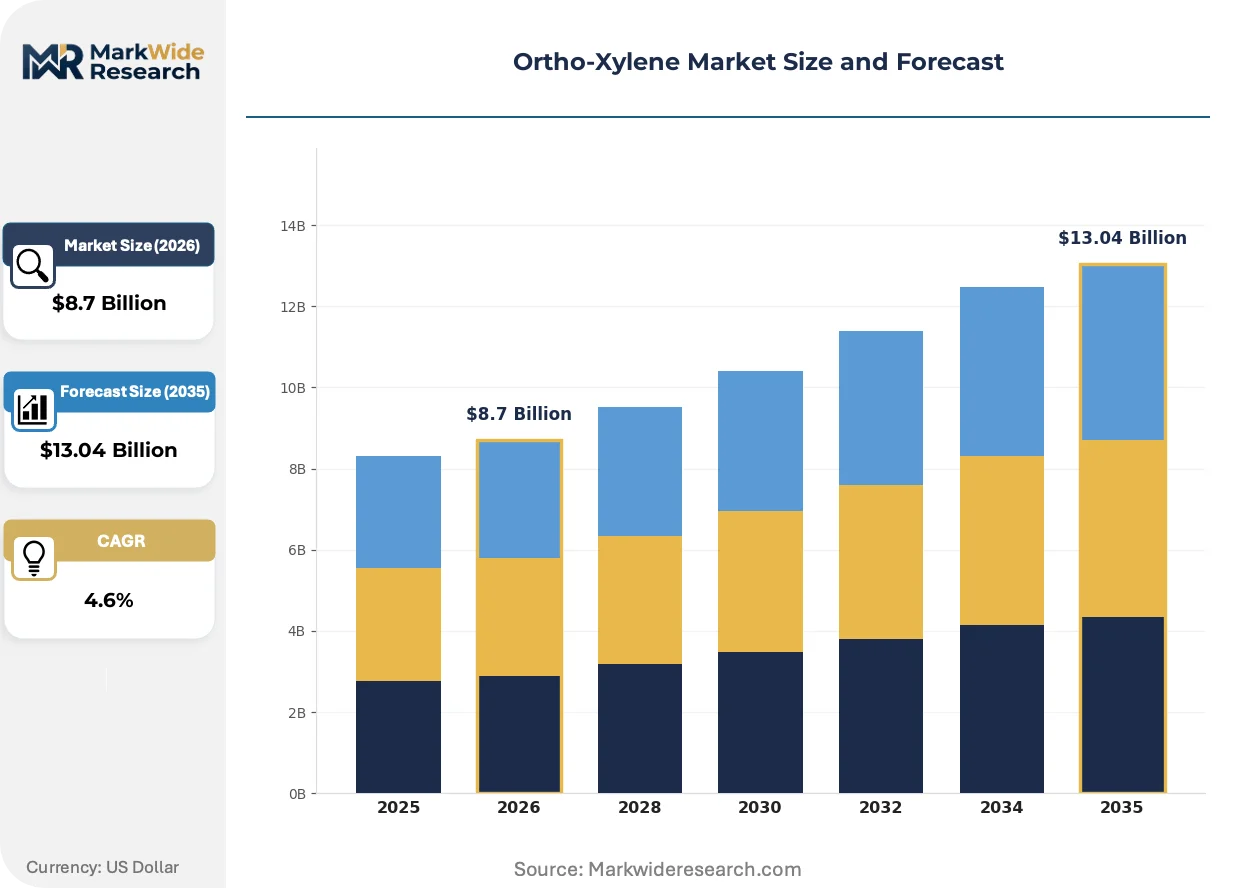
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Purified Ortho-Xylene, Mixed Xylenes, Ortho-Xylene Blend, Distillate End User: Synthetic Fibers, Solvents, Coatings, Chemicals Application: Aromatic Hydrocarbon Production, Plastic Manufacturing, Adhesives, Pharmaceuticals Distribution Channel: Direct Sales, Distributors, Online Retail, Export |
| Companies Covered | Exxon Mobil Corporation, Mitsubishi Gas Chemical Company, Royal Dutch Shell PLC, Flint Hills Resources, Sinopec Yangzi Petrochemical Company Limited, Reliance Industries Limited, Formosa Chemicals & Fibre Corp., KP Chemical Corp., China Petroleum & Chemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ortho-Xylene Market Strategic Shifts
Advanced catalyst systems and carbon-intensity tracking are restructuring how ortho-xylene purity grades align with downstream certification requirements across coating, pharmaceutical, and polyester resin value chains.
Membrane-based xylene separation technology is absorbing capital allocation from traditional crystallization and adsorption units in new Asian refinery-chemical complexes. Specialty coating manufacturers in Japan and South Korea are adopting pharmaceutical-grade specifications for automotive and marine protective systems. This technology compression is absorbing margin from conventional splitter operators unable to achieve 99.5 percent isomer purity without energy-intensive revamp investments.
REACH and ECHA classification protocols now mandate granular substance identity registration for ortho-xylene downstream derivatives in European coatings and adhesives formulations. Industrial consequence includes forced supply chain requalification for importers sourcing from non-EU aromatics complexes. Pharmaceutical and high-performance coating segments are responding by consolidating supplier bases around integrated producers with certified carbon accounting and full substance dossier transparency.
Direct terminal-to-manufacturer bulk contracting is displacing layered distributor networks for large phthalate ester and unsaturated polyester resin producers. Chemical tanker and rail terminal operators in China's East China refining corridor now offer integrated logistics-plus-certification packages. This channel compression is most visible among construction sector formulators in Jiangsu and Zhejiang provinces seeking just-in-time purified ortho-xylene delivery with embedded emissions documentation.
Ortho-Xylene Market Segmentation
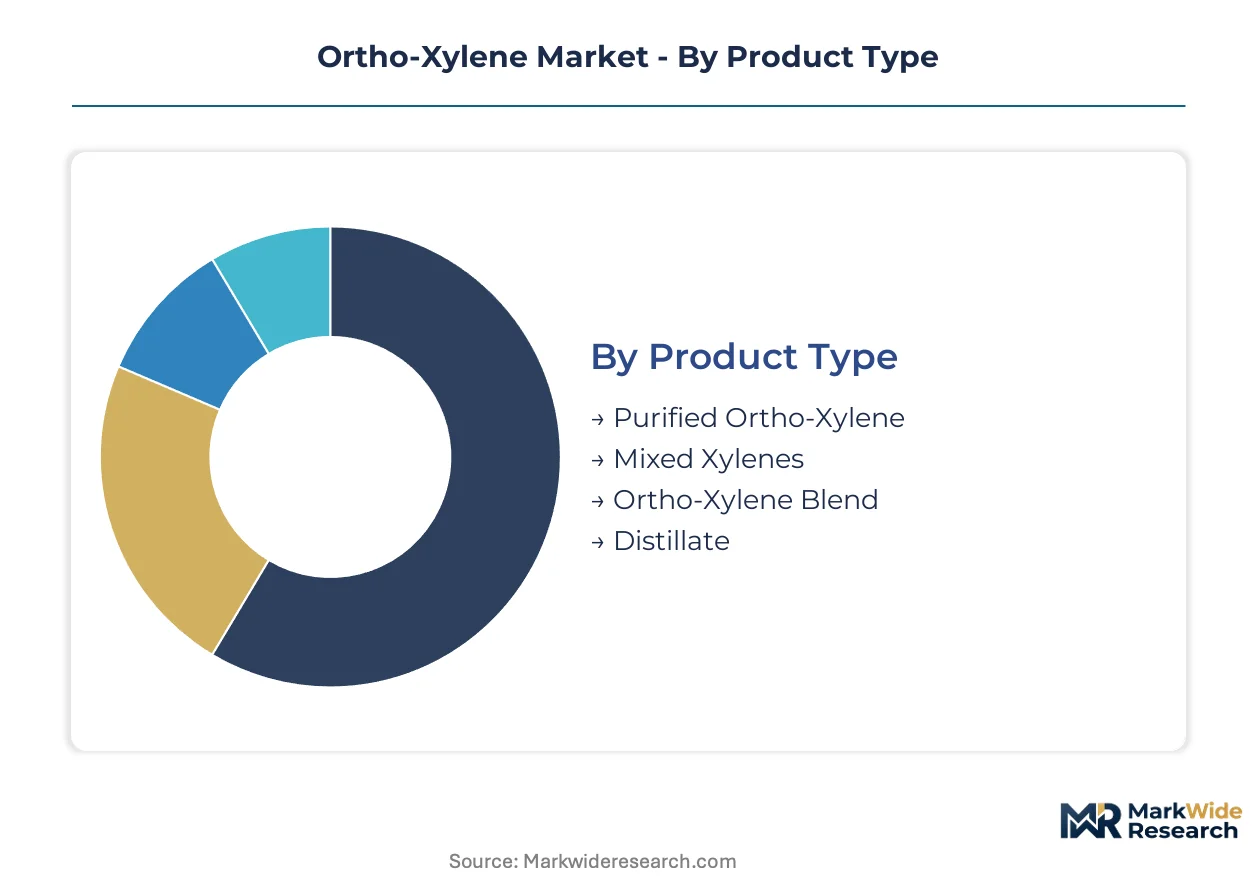
Ortho-xylene segmentation reflects the tension between bulk commodity flows and specialty purity requirements. Product grades determine integration depth into downstream value chains, from refinery-captive phthalic anhydride circuits to pharmaceutical-grade active intermediate synthesis.
Product Type:
Purified grades serve standalone specialty applications while mixed streams feed integrated chemical complexes with captive isomerization capacity.
- Purified Ortho-Xylene:Isomer purity exceeds 99.5 percent through selective crystallization or adsorptive separation. Japanese pharmaceutical and high-performance coating manufacturers in Osaka and Kobe corridors command premium offtake for active pharmaceutical intermediate synthesis.
- Mixed Xylenes:C8 aromatic streams containing ortho-, meta-, and para-isomers feed splitter units at integrated petrochemical complexes. East China refining corridors anchored by Yangzi and Zhenhai mega-complexes concentrate hydrogenation and isomerization capacity for domestic phthalic anhydride producers.
- Ortho-Xylene Blend:Intermediate purity grades serve coating resin manufacturers seeking cost-optimized phthalate ester feedstock without pharmaceutical certification requirements.
- Distillate:Refinery stream fractions with variable isomer ratios supply non-integrated aromatics extractors dependent on spot procurement economics.
Volume placements concentrate in Mixed Xylenes; the faster expansion belongs to Purified Ortho-Xylene.
End User:
Customer segments separate by technical specification tolerance and regulatory documentation burden.
- Synthetic Fibers:Paraxylene-ortho-xylene production ratio constraints from China's MEE dual carbon enforcement limit fiber-grade availability. Polyester manufacturers prioritize paraxylene allocation, squeezing ortho-xylene splitter throughput for purified grades.
- Solvents:Industrial degreasing and paint formulation applications tolerate lower isomer purity, sourcing primarily from blend and distillate grades.
- Coatings:Marine and automotive protective systems in Japan and South Korea are adopting pharmaceutical-grade specifications for enhanced performance certification.
- Chemicals:Phthalic anhydride oxidation circuits for plasticizer and unsaturated polyester resin manufacturing represent the dominant volume sink across construction sector formulators.
Margin pools favor Chemicals for volume scale; Coatings generates the steepest expansion trajectory through specification upgrades.
Application:
Use cases stratify by carbon intensity tracking requirements and substance registration protocols.
- Aromatic Hydrocarbon Production:Integrated refinery-chemical complexes co-produce benzene and paraxylene alongside ortho-xylene, concentrating margin pools with energy-efficient isomerization units.
- Plastic Manufacturing:Phthalate ester plasticizers for PVC compounding face regulatory substitution pressure from non-phthalate alternatives in consumer goods packaging.
- Adhesives:REACH downstream chemical registration mandates granular substance identity documentation for European coatings and adhesives formulations, forcing supply chain requalification.
- Pharmaceuticals:Ultra-high-purity grades for active pharmaceutical intermediate synthesis command premium pricing from Japanese specialty chemical offtake.
Production gravity centers on Aromatic Hydrocarbon Production; Pharmaceuticals climbs fastest on purity premium capture.
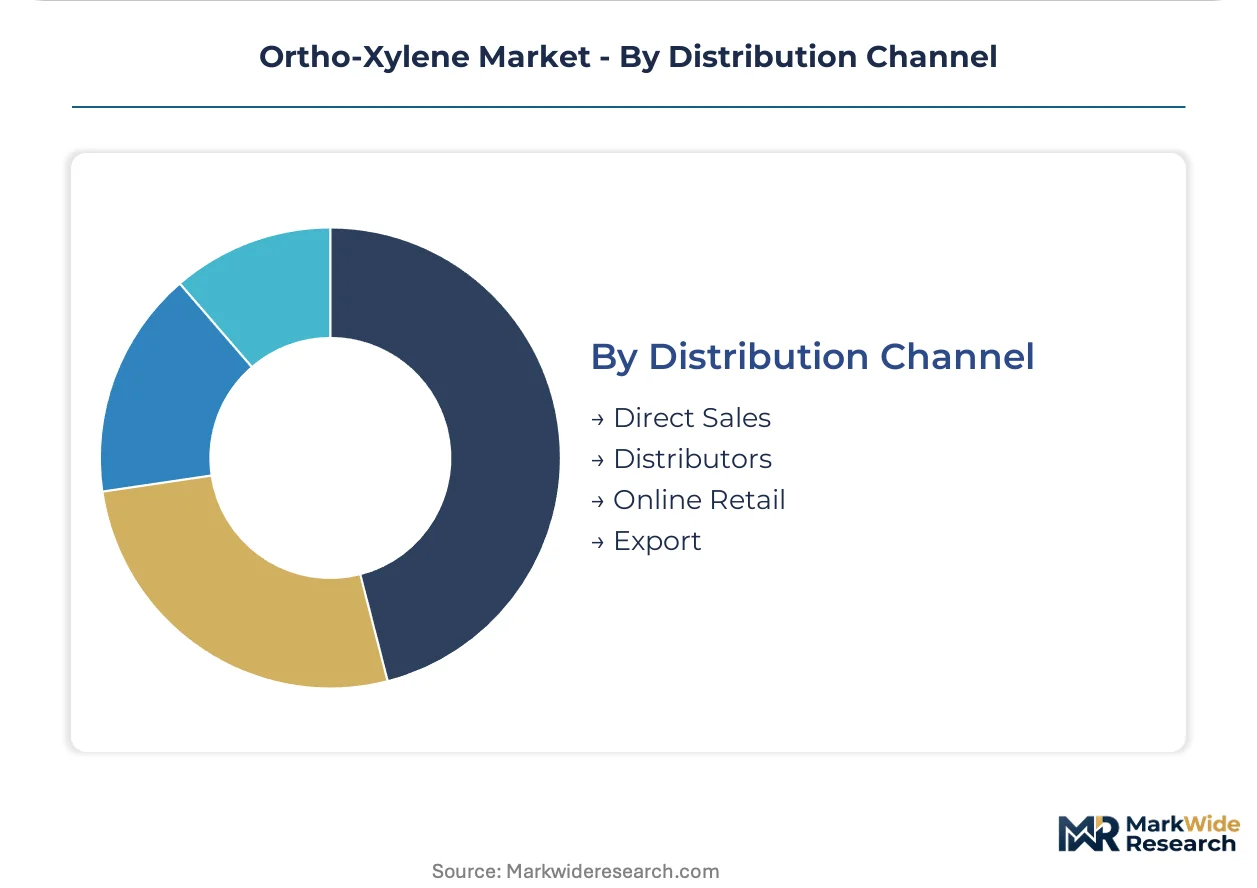
Distribution Channel:
Channel structure reflects customer scale and certification documentation requirements.
- Direct Sales:Bulk terminal movements to large phthalate ester and unsaturated polyester resin manufacturers displace layered distributor networks. Chemical tanker and rail terminal operators in China's East China refining corridor offer integrated logistics-plus-certification packages.
- Distributors:Regional chemical distributors serve mid-scale coating formulators lacking direct terminal access or volume thresholds for bulk contracting.
- Online Retail:Digital platforms facilitate spot procurement for small-batch specialty chemical purchasers seeking just-in-time delivery with embedded emissions documentation.
- Export:India's Jamnagar complex leverages captive mixed xylenes and backward integration into hydrogenation capacity for purified ortho-xylene export arbitrage to Southeast Asian coating resin manufacturers.
Direct Sales commands volume leadership; Export channels gain share fastest on regional supply-demand imbalances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Refinery-chemical integration along the US Gulf Coast and East China refining corridors anchors ortho-xylene production geography. Mixed xylenes from catalytic reforming units feed splitter infrastructure concentrated near major aromatics consumption basins. Carbon intensity regulations and benzene-toluene-xylene spread economics reshape locational competitiveness across integrated complexes.
United States
Phthalic anhydride producers along the Texas and Louisiana Gulf Coast draw purified ortho-xylene from captive reformer streams. EPA National Emission Standards for Hazardous Air Pollutants constrain aromatics extraction emissions, forcing capital-intensive retrofit investments on fractionation units. Houston and Beaumont refining clusters maintain export-grade purification capacity serving Latin American coating resin manufacturers.
China
Construction sector polyester resin manufacturing pulls ortho-xylene through Yangzi and Zhenhai mega-complex oxidation circuits. MEE dual carbon monitoring compresses paraxylene-ortho-xylene production ratios, forcing reconfiguration around carbon intensity metrics. East China refining corridors in Jiangsu and Zhejiang provinces concentrate hydrogenation and isomerization capacity for domestic phthalate ester producers.
Japan
Specialty chemical and pharmaceutical manufacturers in Osaka and Kobe corridors command premium offtake for ultra-high-purity grades exceeding 99.5 percent isomer content. METI industrial policy frameworks incentivize energy-efficient xylene isomerization technology adoption. Chubu and Kansai region petrochemical complexes maintain pharmaceutical-grade certification infrastructure for active pharmaceutical intermediate synthesis.
India
Jamnagar complex economics leverage backward integration into mixed xylenes and captive hydrogenation capacity for export arbitrage. BIS standards govern industrial chemical purity specifications for domestic coating and adhesive formulators. Gujarat refining infrastructure positions purified ortho-xylene volumes toward Southeast Asian construction sector demand.
Germany
REACH downstream chemical registration mandates granular substance identity documentation for European coatings and adhesives formulations. ECHA classification protocols govern ortho-xylene handling, labeling, and derivative registration across the EU single market. Ludwigshafen and Cologne chemical corridors maintain integrated aromatics extraction serving phthalate ester manufacturers facing carbon border adjustment mechanism documentation requirements.
Ortho-Xylene Market Competitive Environment
Global majors compete with regional champions across refinery-chemical integration depth and carbon-accounting certification capabilities. Market structure tilts toward consolidated integrated producers with captive mixed xylenes feedstock, fragmenting among non-integrated aromatics extractors exposed to spot procurement volatility. Three archetypes dominate: Gulf Coast export-oriented majors, East China state-integrated complexes, and Indian backward-integrated refiners. Capacity expansion and selective technology licensing constitute the primary competitive moves, with selective toluene disproportionation adoption reducing carbon intensity per ton.
Among US-based integrated majors, Exxon Mobil Corporation occupies a position exemplifying Gulf Coast aromatics infrastructure leverage. Mitsubishi Gas Chemical Company represents the Japanese specialty chemical archetype, sitting within high-purity supply chains serving pharmaceutical offtake. Reliance Industries Limited anchors the Indian backward-integrated model, with Jamnagar complex positioning enabling export arbitrage to Southeast Asian markets.
| Leading Market Players |
|---|
| Exxon Mobil Corporation |
| Mitsubishi Gas Chemical Company |
| Royal Dutch Shell PLC |
| Flint Hills Resources |
| Sinopec Yangzi Petrochemical Company Limited |
| Reliance Industries Limited |
| Formosa Chemicals & Fibre Corp. |
| KP Chemical Corp. |
| China Petroleum & Chemical Corporation |
| Others |
Value Chain & Pricing Dynamics
Construction sector formulators in Jiangsu and Zhejiang provinces operate on direct terminal-to-manufacturer bulk contracting, compressing layered distributor margins and embedding carbon-accounting documentation into base pricing. This buyer concentration enables integrated producers to extract premium capture for certified purity grades while squeezing spot-market arbitrageurs.
Pricing Analysis
Service-unbundled carbon certification now commands separate line-item pricing, with REACH-compliant substance dossiers and embedded emissions documentation carrying distinct premiums from base chemical costs. Three-tier pricing structure across pharmaceutical-grade, industrial-purity, and uncertified blend levels separates Japanese pharmaceutical offtake from Southeast Asian coating resin procurement. Cost compression in standard industrial grades is intensifying because Yangzi and Zhenhai mega-complexes are flooding East China corridors with captive output. Small-batch specialty chemical purchasers exhibit highest price sensitivity, while pharmaceutical manufacturers tolerate steep premiums for 99.5 percent isomer purity with full audit trails.
Supply Chain Analysis
Certification gating through REACH substance identity registration and China's MEE dual carbon monitoring now determines supplier eligibility for European and East Asian corridors, disqualifying non-integrated aromatics extractors lacking audit infrastructure. Manufacturing concentrates in China, the United States, and India, with Jamnagar complex economics leveraging backward integration into captive mixed xylenes. Feedstock supply draws from catalytic reformer streams, selective toluene disproportionation units, and hydrogenation capacity investments. Single-source vulnerability runs through East China refining corridors where Yangzi and Zhenhai complexes control domestic splitter throughput. Distribution runs through chemical tanker and rail terminal operators offering integrated logistics-plus-certification packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's MEE dual carbon enforcement functions as a cost-of-compliance moat, elevating capital requirements for carbon-accounting infrastructure and selective isomerization technology to levels that fragment non-integrated competitors.
For Market Incumbents: Lock in carbon-border adjustment readiness by securing REACH substance dossier transparency and MEE monitoring compliance ahead of documentation mandates. Prioritize selective toluene disproportionation adoption to reduce carbon intensity per ton while preserving yield economics against paraxylene priority allocation threats. Extend captive hydrogenation capacity in East China corridors to defend margin pools from Jamnagar export arbitrage. For New Entrants and Emerging Players: Begin with pharmaceutical-grade isomer demand in Japanese specialty chemical corridors, where ultra-high-purity specifications exceed 99.5 percent and premium capture remains insulated from bulk commodity volatility. Target coating resin manufacturers in Southeast Asia seeking just-in-time delivery with embedded emissions documentation. Pursue digital platform spot procurement channels for small-batch specialty chemical purchasers lacking direct terminal access. For Investors and Strategic Acquirers: The window for entry favors backward-integrated refiners with captive mixed xylenes and hydrogenation infrastructure positioned for carbon-accounting certification. Long-term viability hinges on dual carbon compliance capabilities across the 5-10 year regulatory enforcement horizon. Monitor benzene-toluene-xylene spread compression as the inflection signal for integrated versus non-integrated producer margin divergence.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive mixed xylenes and hydrogenation capacity insulate Jamnagar complex from feedstock volatility. |
| Green Manufacturing Transition | Selective toluene disproportionation adoption aligns with MEE dual carbon monitoring frameworks. |
| Long-term Supply Agreement | Direct terminal contracting with Jiangsu construction formulators locks in volume offtake certainty. |
| Capacity Expansion | East China refining corridors concentrate splitter infrastructure near Yangzi and Zhenhai demand basins. |
| Joint Venture | Technology licensing partnerships accelerate carbon-efficient isomerization adoption across Asian complexes. |
Study Parameters
Multi-period observation of benzene-toluene-xylene spreads, refinery-chemical integration depth, and carbon intensity metrics anchored the trend analysis, supplemented by interviews with plant managers at integrated aromatics complexes, procurement leads at phthalate ester manufacturers, distribution channel partners in East China corridors, and technical R&D directors at catalyst system suppliers. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from listed petrochemical majors, and MEE regulatory disclosure databases. Bottom-up volume modeling triangulated against top-down refinery capacity assessments.
Segment-weighting across product type, end user, application, and distribution channel dimensions calibrated volume and value outputs across the projection horizon. CAGRs were derived from elasticity-adjusted demand projections for phthalic anhydride oxidation circuits and pharmaceutical-grade isomer synthesis. Forecast inputs incorporated paraxylene-ortho-xylene production ratio constraints from MEE enforcement and membrane-based xylene separation technology adoption curves.
Underlying measurement precision varies by segment; pharmaceutical-grade purity tiers carry tighter precision than unstandardized distillate fractions due to certification audit trail completeness. Forecasts reflect assumptions around carbon border adjustment implementation timelines and selective hydrogenation catalyst performance. A model refresh is warranted upon material change in MEE dual carbon enforcement intensity or benzene-toluene-xylene spread volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
2-Phenylethanol Market
Solvents
Global Aliphatic Hydrocarbon Solvents Market
Solvents
6-Xylenol Market
Solvents
Mixed Xylene Market
Solvents
Meta-Xylene Market
Solvents
Trichloroacetyl Chloride Market
Solvents
Methyl Acetate Market
Solvents
Nitromethane Market
Solvents
Global Green and Bio-Based Solvents Market
Solvents
Ketone-Based Solvents Market
Solvents
Dihydromyrcene Market
Solvents
Japan Acetonitrile Market
Solvents
3-Methyl-3-Penten-2-One (3M3P) Market
Solvents
Propylene Glycol Methyl Ether Market
Solvents
Global Solvent Evaporation Market
Solvents
Global Ethyl Lactate Market