
 6-Xylenol Market | 2026-2036
6-Xylenol Market Size, Share, and Industry Trends Forecast 2026-2036
6-Xylenol Market Outlook
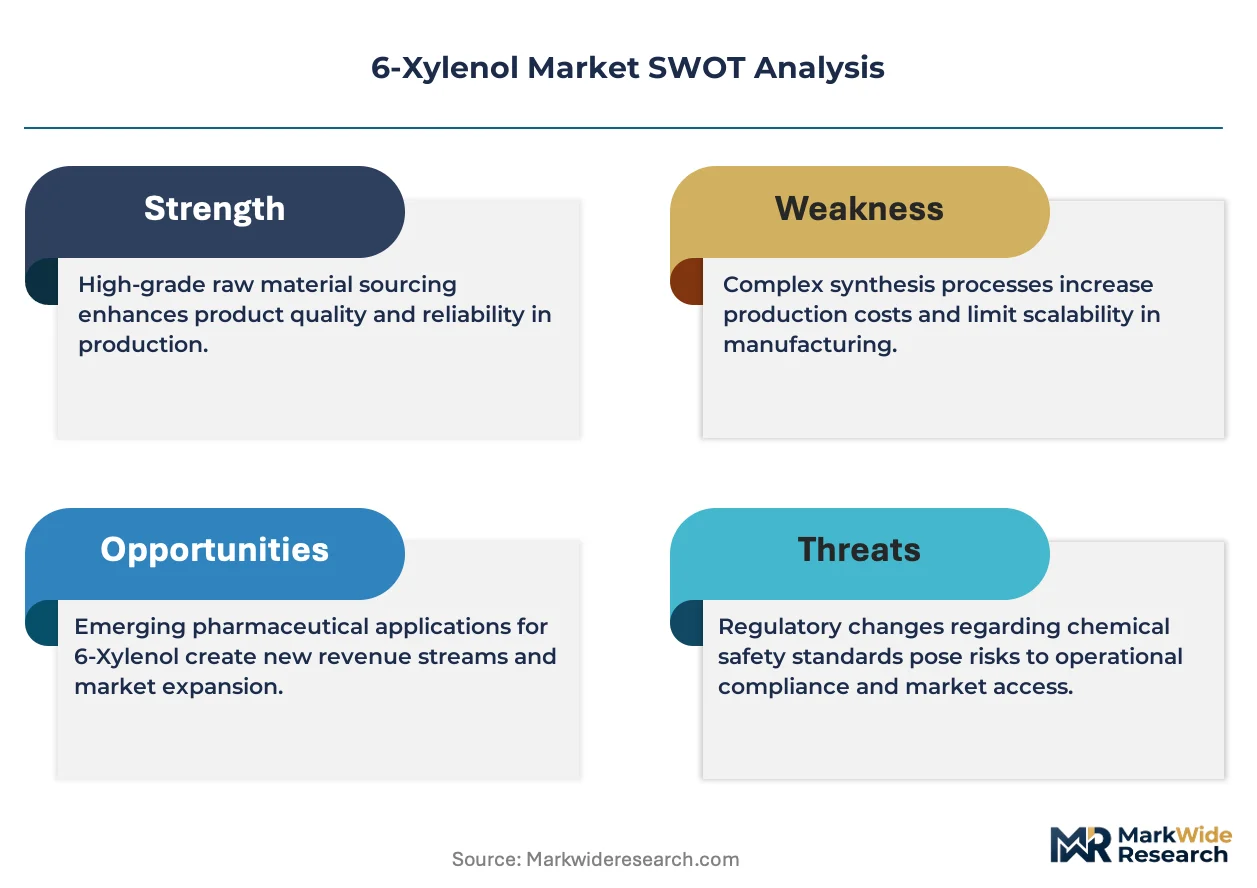
REACH is rebalancing the cost-of-entry calculus for European suppliers of 6-xylenol, forcing upstream investment in purification and documentation systems. SABIC leverages its integrated aromatics platform to sustain feedstock cost advantages across Middle Eastern and Asian markets. Qingdao Welltech Chemical anchors its position through specialized production of technical-grade material for domestic agrochemical clients.
6-Xylenol is a dimethylphenol isomer with a hydroxyl group at the para position relative to one methyl substituent, typically manufactured via alkylation of phenol or separation from mixed xylenol streams, and serves primarily as an intermediate for antioxidants, agrochemicals, and specialty resins. Pharmaceutical-grade 6-xylenol commands premium pricing due to stringent impurity limits and batch certification requirements, while industrial-grade volumes dominate tonnage flows into antioxidant and solvent applications. The additive application segment shows structural momentum as lubricant and fuel formulators seek phenolic derivatives with enhanced thermal stability profiles.
EPA oversees environmental release thresholds for xylenol isomers in US manufacturing facilities, while REACH mandates registration and hazard communication for 6-xylenol imports into the European Union. China's MEE enforces emission standards that shape operating costs for domestic producers of mixed cresol and xylenol streams. Stakeholders must monitor regulatory divergence on phenol derivative classifications to anticipate compliance-driven restructuring of supply routes and qualification protocols.
Market Dynamics
REACH compliance in Europe is tightening purity thresholds for chemical intermediates, forcing upstream investment in purification and documentation systems that reshapes cost structures across the 6-xylenol supply base.
Growth Catalysts
- Agrochemical formulation expansion:Domestic capacity buildout in China is concentrating demand for technical-grade 6-xylenol intermediates used in pesticide synthesis.
- Antioxidant thermal stability requirements:Lubricant and fuel formulators are specifying phenolic derivatives with enhanced performance profiles, pulling higher-purity material through the value chain.
- REACH registration mandates:ECHA's hazard communication requirements for 6-xylenol imports into the European Union are accelerating qualification protocols among registered suppliers.
Market Restraints
- Feedstock phenol volatility:Benzene and propylene cost swings transmit directly into 6-xylenol production economics, compressing margin visibility for non-integrated producers.
- Isomer separation complexity:Technical limitations in isolating 6-xylenol from mixed xylenol streams constrain yield rates and elevate unit costs versus synthetic routes.
- Substitution by hindered phenols:Butylated hydroxytoluene and other synthetic antioxidants are displacing 6-xylenol in cost-sensitive industrial applications.
Strategic Opportunities
- Pharmaceutical-grade certification:Stringent impurity limits and batch documentation requirements create pricing premiums for qualified producers serving API intermediates.
- Specialty resin applications:Epoxy and polycarbonate formulators are specifying high-purity dimethylphenol isomers for enhanced thermal and mechanical properties.
- Direct procurement channels:Agrochemical manufacturers are bypassing distributors to secure dedicated offtake agreements with technical-grade producers.
Industry Challenges
- Process analytical chemistry expertise:Isomer identification and purity verification require specialized chromatography capabilities that remain scarce in regional production clusters.
- Multi-jurisdiction registration timelines:Concurrent ECHA, EPA, and NMPA filings for 6-xylenol derivatives extend commercialization cycles by 18-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 6-Xylenol Market |
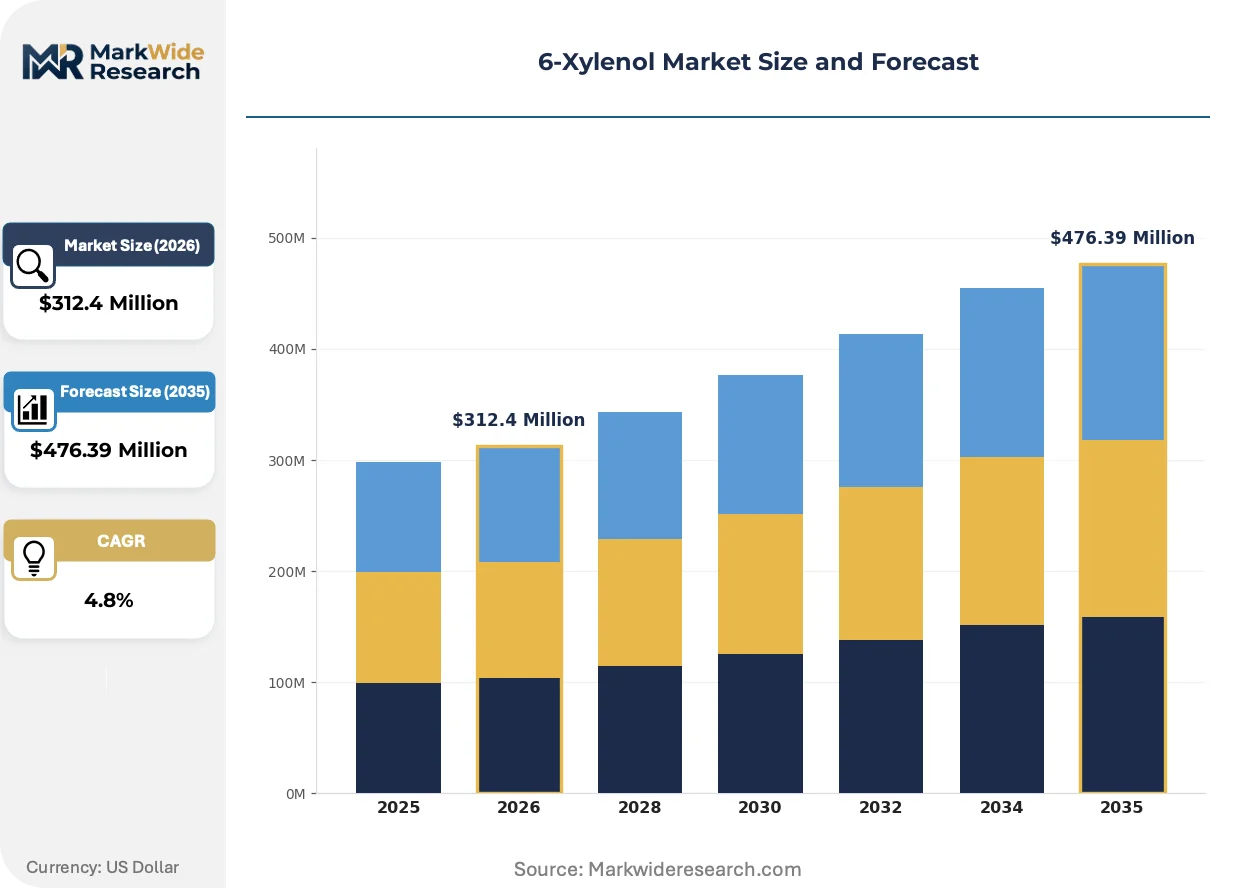
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $476.39 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Technical Grade, Pharmaceutical Grade, Industrial Grade, Analytical Grade Application: Solvent, Additive, Intermediate, Chemical Synthesizer End User: Pharmaceuticals, Agriculture, Chemicals, Coatings Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | SABIC, SI Group, Qingdao Welltech Chemical, Nanjing Datang Chemical, Deepak Novochem Technologies Limited, Solvay, LANXESS, Mitsubishi Gas Chemical, Tokyo Chemical Industry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
6-Xylenol Market Strategic Shifts
Membrane separation technology is modularizing purification workflows for mixed xylenol streams, enabling smaller-scale producers to achieve pharmaceutical-grade specifications without capital-intensive distillation investments.
Continuous flow alkylation systems are modularizing phenol methylation processes, allowing agrochemical intermediate suppliers to adjust output ratios in response to real-time demand signals from formulation clients. Specialty chemical producers in China and India are piloting these units to reduce batch cycle times and improve isomer selectivity.
REACH's tightening purity thresholds for chemical intermediates are forcing documentation system upgrades across European supply chains. Importers must now maintain batch-level traceability records that satisfy ECHA audit protocols, with agrochemical-grade material facing heightened scrutiny. German and Dutch distributors are consolidating supplier panels to reduce qualification overhead.
Specification-driven procurement is compressing supplier evaluation cycles as agrochemical formulators prioritize pre-qualified 6-xylenol sources with established REACH registrations. Long-term offtake agreements are displacing spot market purchases in antioxidant and pesticide intermediate channels, with volume commitments increasingly tied to purity band guarantees rather than base chemical pricing.
6-Xylenol Market Segmentation
6-Xylenol segmentation reveals how purity specifications and application requirements partition the market into distinct commercial channels. Technical-grade volumes flow to agrochemical synthesis, while pharmaceutical-grade material commands qualification-intensive procurement protocols.
Product Type:
Technical-grade material operates as standalone commodity feedstock, whereas pharmaceutical and analytical grades embed into regulated supply chains with documentation requirements.
- Technical Grade:Contains 95-98% 6-xylenol with controlled isomer distribution, serving pesticide intermediate manufacturers in Shandong and Jiangsu provinces. Chinese agrochemical formulators specify this grade for cost-sensitive synthesis of organophosphate derivatives.
- Pharmaceutical Grade:Meets USP/EP monograph standards with sub-0.1% impurity thresholds and full batch traceability. API intermediate producers in Germany and Switzerland require REACH-registered sources with established DMF documentation pathways.
- Industrial Grade:Blended material for antioxidant and solvent applications where isomer specificity matters less than bulk availability.
- Analytical Grade:Ultra-high purity reference standards for chromatography calibration and regulatory assay methods.
Volume placements concentrate in Technical Grade; the faster expansion belongs to Pharmaceutical Grade.
Application:
Cost tiers separate commodity solvent use from performance-driven additive and intermediate applications where specification rigor determines supplier selection.
- Intermediate:Dominant consumption channel where 6-xylenol undergoes further functionalization into agrochemical actives and polymer stabilizers. Chinese pesticide manufacturers account for the majority of offtake volume through direct procurement arrangements.
- Additive:Lubricant and fuel formulators incorporate 6-xylenol derivatives for thermal oxidation resistance. Basf and Infineum specify phenolic antioxidants with defined melting point ranges for synthetic base stock compatibility.
- Solvent:Niche extraction and cleaning applications where dimethylphenol polarity profiles match specific solubility requirements.
- Chemical Synthesizer:Laboratory-scale reagent use in academic and industrial R&D settings.
Intermediate applications anchor current volume; additive specifications are climbing the fastest as lubricant performance standards tighten.
End User:
Customer maturity varies sharply—agriculture and chemicals operate on contract volume logic, while pharmaceuticals demand qualification-heavy supplier relationships.
- Agriculture:Pesticide formulators in China, India, and Brazil consume technical-grade material through annual offtake agreements tied to planting season demand cycles.
- Chemicals:Antioxidant and resin manufacturers specify purity bands according to downstream application requirements.
- Pharmaceuticals:API intermediate producers require pharmaceutical-grade certification with full regulatory documentation packages.
- Coatings:Specialty epoxy and polycarbonate formulators seeking thermal stability enhancement.
Agriculture dominates absolute volume; pharmaceuticals show the steepest expansion trajectory as oncology and cardiovascular API pipelines diversify.
Distribution Channel:
Supply concentration shapes channel selection—bulk agriculture moves direct, while fragmented pharmaceutical demand routes through qualified distributors.
- Direct Sales:Agrochemical manufacturers in China bypass intermediaries for technical-grade volumes exceeding 500 metric tons annually. SABIC and Qingdao Welltech maintain dedicated account teams for top ten pesticide formulators.
- Distributors:European and North American pharmaceutical-grade material flows through REACH-registered distributors with established ECHA audit compliance. Brenntag and Univar Solutions consolidate supplier panels to reduce qualification overhead.
- Wholesalers:Regional stocking points for industrial-grade solvent applications.
- Online Retail:Small-volume analytical and laboratory reagent sales through specialty chemical platforms.
Direct Sales capture the largest volume share; Distributors are gaining share fastest as REACH documentation requirements raise barriers to self-managed procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong province's chemical industrial parks attract 6-xylenol producers through tax incentives and streamlined environmental permitting. This zone anchors Asia-Pacific supply concentration alongside specialty chemical clusters in Germany and the US Gulf Coast.
China
Agrochemical formulators in Jiangsu and Shandong provinces drive technical-grade consumption through direct procurement contracts. MEE emission standards tighten operating permits for mixed cresol-xylenol producers. Qingdao's chemical industrial park hosts integrated aromatics facilities serving domestic pesticide manufacturers.
Germany
API intermediate producers in Ludwigshafen and Leverkusen require REACH-registered pharmaceutical-grade material with full DMF documentation. ECHA audit protocols force distributors to consolidate supplier panels. The Rhine-Ruhr chemical corridor maintains specialized purification capacity for European pharmaceutical clients.
United States
Lubricant additive formulators in Houston and Baytown specify phenolic antioxidants with defined thermal stability profiles. EPA release thresholds shape environmental compliance costs for Gulf Coast phenol derivative producers. Texas petrochemical complexes leverage integrated feedstock access for cost-advantaged output.
India
Pesticide manufacturers in Gujarat and Maharashtra scale imports of technical-grade 6-xylenol for organophosphate synthesis. CDSCO import regulations govern pharmaceutical-grade material for API production. Ankleshwar's chemical estate houses formulators building backward integration into intermediate sourcing.
Japan
Specialty resin producers in Chiba and Yokkaichi seek high-purity dimethylphenol isomers for epoxy and polycarbonate applications. METI chemical safety standards enforce rigorous impurity documentation. The Keiyo industrial zone maintains precision separation capabilities for electronics-grade material.
6-Xylenol Market Competitive Environment
Chinese producers anchor one tier; European and Japanese specialists hold qualification-intensive positions. The structure fragments across three tiers: integrated petrochemical majors, regional agrochemical-grade suppliers, and pharmaceutical-grade certification holders. Strategic archetypes include backward-integrated aromatics platforms, membrane-technology purification specialists, and distributor-dependent qualification managers. Competitive moves center on capacity expansion in Shandong province and REACH registration consolidation among European distributors.
Among Middle Eastern and Asian integrated producers, SABIC exemplifies the petrochemical-major archetype through captive feedstock access. Qingdao Welltech Chemical occupies a position within China's technical-grade supplier tier, while Deepak Novochem Technologies Limited represents Indian specialists navigating multi-jurisdiction registration requirements. These anchors illustrate how geographic concentration and certification breadth separate competitive positions.
| Leading Market Players |
|---|
| SABIC |
| SI Group |
| Qingdao Welltech Chemical |
| Nanjing Datang Chemical |
| Deepak Novochem Technologies Limited |
| Solvay |
| LANXESS |
| Mitsubishi Gas Chemical |
| Tokyo Chemical Industry |
| Others |
Value Chain & Pricing Dynamics
Feedstock phenol costs transmit directly into 6-xylenol production economics, with benzene and propylene volatility cascading through technical-grade contract pricing to pharmaceutical-grade premiums. Chinese agrochemical formulators leverage direct procurement at scale to compress margins, while European API intermediate producers absorb REACH-registered purity documentation costs into tiered pricing structures.
Pricing Analysis
Short lead-time premiums distinguish pharmaceutical-grade spot purchases from annual offtake agreements in technical-grade channels. Three-tier pricing structure across pharmaceutical, technical, and industrial grades reflects certification burden and batch documentation intensity. Cost compression in technical-grade material is intensifying because agrochemical manufacturers consolidate supplier panels for volume leverage. Pesticide formulators in Shandong and Jiangsu provinces exhibit highest price sensitivity; Swiss and German API producers show lowest sensitivity due to qualification lock-in effects.
Supply Chain Analysis
REACH registration and DMF documentation requirements gate European pharmaceutical-grade supply, forcing distributor consolidation and supplier panel reduction. Production concentrates in China, Germany, and the United States, with Shandong province and the Rhine-Ruhr corridor anchoring regional purification capacity. Raw material flows draw from mixed cresol-xylenol streams, synthetic phenol alkylation routes, and membrane separation technology inputs. Single-source vulnerability runs through Chinese technical-grade concentration amid MEE emission permit tightening. Distribution runs through direct sales for agrochemical volumes exceeding 500 metric tons annually, with REACH-registered distributors handling fragmented pharmaceutical demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane separation technology is displacing legacy distillation-based purification, compressing capital barriers for pharmaceutical-grade entry and reshaping competitive economics across producer tiers.
For Market Incumbents: Extend REACH registration coverage into derivative product lines before ECHA audit protocols tighten further. Deepen backward integration into captive phenol supply to defend margin position against benzene cost volatility. SABIC and integrated aromatics platforms should consolidate technical-grade capacity in Shandong to preempt Chinese domestic competition.
For New Entrants and Emerging Players: REACH registration in the European Union opens a window for membrane-technology specialists to capture pharmaceutical-grade share without capital-intensive distillation investments. Target analytical-grade reference standards for chromatography calibration where qualification overhead remains lower than API intermediate channels. Partner with established distributors to bypass self-managed ECHA compliance costs.
For Investors and Strategic Acquirers: Qingdao Welltech's capacity expansion announcements are the leading indicator that technical-grade supply is approaching overcapacity in China. Position for 5-10 year viability around membrane-technology purification specialists with existing pharmaceutical-grade certification. Watch CDSCO import regulation tightening in India as signal for regional supply restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Separation Technology Deployment | Enables pharmaceutical-grade purity without distillation capital intensity for mid-scale producers. |
| REACH Registration Consolidation | Reduces distributor qualification overhead as ECHA audit protocols tighten batch traceability requirements. |
| Direct Procurement Channel Expansion | Bypasses distributor margins for agrochemical formulators securing volumes above 500 metric tons annually. |
| Backward Integration into Phenol Supply | Captures feedstock cost advantages against benzene and propylene volatility for integrated aromatics platforms. |
| Continuous Flow Alkylation Piloting | Reduces batch cycle times and improves isomer selectivity for agrochemical intermediate suppliers in China and India. |
Study Parameters
Multi-period observation of phenol derivative pricing spreads, REACH registration timelines, and agrochemical formulation capacity buildouts anchored the trend analysis, supplemented by interviews with plant managers at mixed cresol-xylenol facilities, procurement leads at pesticide formulators, distribution channel partners in European chemical distribution, and technical R&D directors at antioxidant manufacturers. Secondary validation drew from customs and trade data, Cefic and ACC industry reports, SEC 10-K filings of listed chemical producers, and ECHA registration databases. Bottom-up volume triangulation across grade tiers and top-down value reconciliation against feedstock cost structures ensured analytical consistency.
Input-output matrices mapped phenol cost transmission, membrane separation yield improvements, and regulatory compliance cost absorption across product grades and regional production hubs. Segmentation dimensions included purity grade tier, end-use industry application, and regional regulatory cluster. CAGRs were derived from trend extrapolation of historical volume flows adjusted for capacity expansion announcements and regulatory phase-in schedules. Forecast inputs incorporated MEE emission permit issuance rates and CDSCO import regulation evolution.
The model assumes a particular technology adoption path; alternative pathways for continuous flow alkylation diffusion would alter the outlook for synthetic route economics relative to mixed stream separation. Forecasts reflect documented assumptions on REACH implementation timing and phenol feedstock cost trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Global Nitrochlorobenzene Market
Solvents
Crotonaldehyde Market
Solvents
Ethane Market
Solvents
Piperylene Market
Solvents
Oxygenated Solvents Market
Solvents
Solvent Green 7 Market
Solvents
Japan Acetonitrile Market
Solvents
Aliphatic Hydrocarbon Solvents and Thinners Market
Solvents
Ketene Market
Solvents
Epoxy Thinner Market
Solvents
Methyl Formate Market
Solvents
Global Solvent Evaporation Market
Solvents
Global Ethyl Lactate Market
Solvents
Ethoxydiglycol Market
Solvents
Ortho-Xylene Market
Solvents
Electronic Cleaning Solvents Market