
 Global Trichloroethylene and Perchloroethylene Market | 2026-2036
Global Trichloroethylene and Perchloroethylene Market Size, Share, and Industry Trends Forecast 2026-2036
Global Trichloroethylene and Perchloroethylene Market Foresight
Electronics manufacturing is broadening its share of chlorinated solvent consumption as semiconductor foundries and printed circuit board fabricators scale precision cleaning operations. Westlake Chemical leverages integrated chlor-alkali infrastructure to secure feedstock economics across North American production networks. Olin Corporation sustains diversified supply positions through its chlorinated organics portfolio serving both metal finishing and chemical synthesis channels. AGC Chemicals anchors Asia-Pacific availability with fluorinated and chlorinated solvent manufacturing concentrated in Japanese and Thai facilities.
Trichloroethylene and perchloroethylene are chlorinated hydrocarbon solvents characterized by high vapor density, non-flammability, and strong degreasing efficacy; manufacturers produce them through acetylene-based chlorination or ethylene oxychlorination routes, yielding products with boiling points of 87°C and 121°C respectively for targeted industrial cleaning and chemical intermediate applications. The perchloroethylene product category dominates revenue contribution due to entrenched textile dry cleaning infrastructure and sustained chemical intermediate demand, while metal degreasing applications within the application dimension represent the fastest-expanding consumption pool as automotive and aerospace component fabricators prioritize residue-free precision cleaning. Electronics manufacturing as an end user industry commands premium pricing for ultra-high-purity grades, whereas pharmaceutical production applications remain a comparatively mature, specification-intensive segment with slower volume expansion.
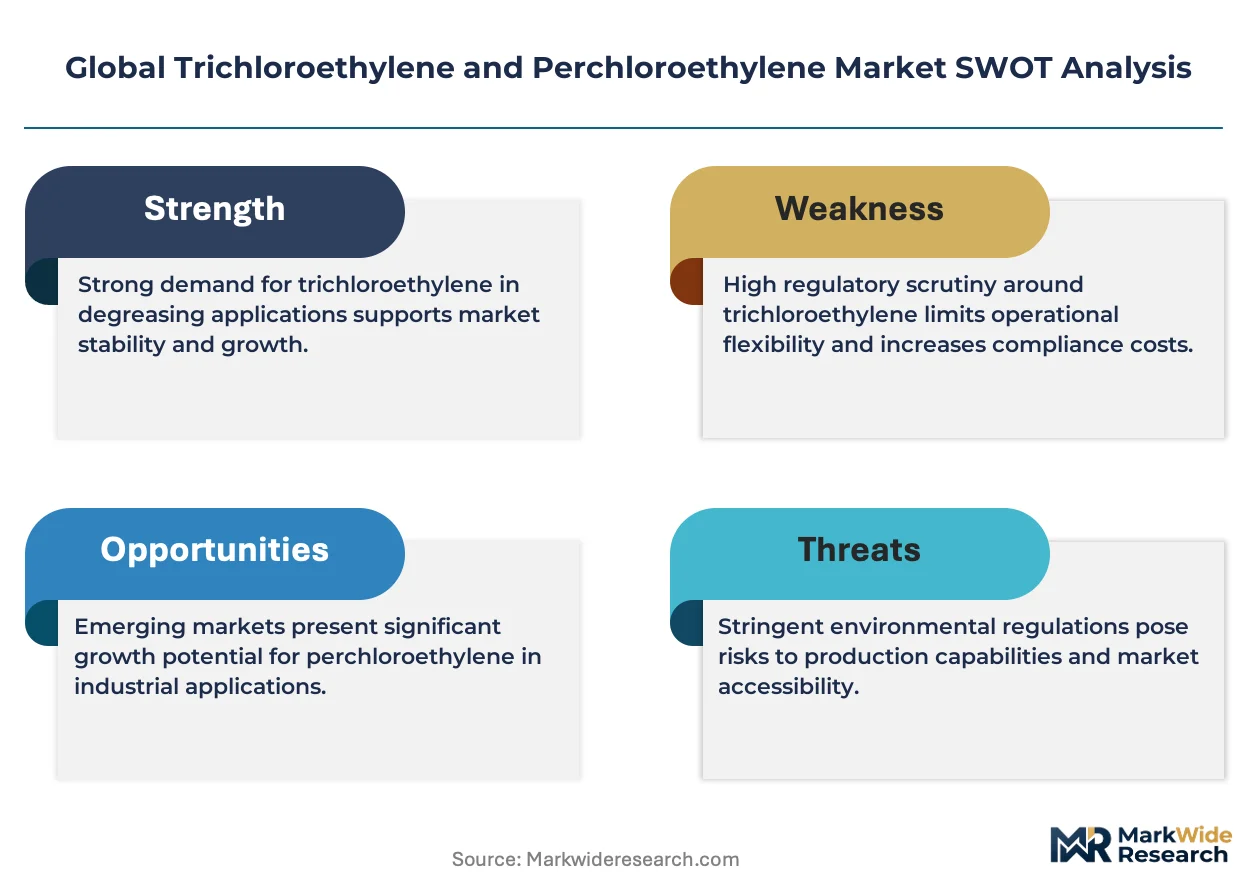
The EPA regulates trichloroethylene under the Toxic Substances Control Act with proposed bans on most commercial uses, while REACH restrictions in Europe classify perchloroethylene as a substance of very high concern with authorization requirements, and China's MEE enforces emission standards for volatile organic compounds from chlorinated solvent operations. These frameworks are forcing producers to reformulate product lines, invest in closed-loop recovery systems, or redirect supply toward less regulated geographies. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate where production capacity and demand migration will concentrate.
Market Dynamics
Regulatory divergence across the United States, European Union, and China is fragmenting production economics and redirecting supply flows toward jurisdictions with less stringent volatile organic compound emission controls.
Growth Catalysts
- Semiconductor fabrication scaling:Advanced node production in Taiwan and South Korea requires ultra-high-purity chlorinated solvents for photoresist stripping and wafer cleaning, expanding specification-grade demand.
- REACH authorization timelines:Extended transition periods for perchloroethylene in European chemical intermediate applications preserve revenue streams while producers reformulate.
- China's MEE enforcement gaps:Regional variance in VOC emission inspection intensity allows continued capacity expansion for metal degreasing solvents in inland provinces.
Market Restraints
- Acetylene feedstock volatility:Calcium carbide production costs in China fluctuate with electricity pricing and environmental shutdowns, compressing margins for acetylene-based chlorination routes.
- EPA proposed commercial bans:The Toxic Substances Control Act rulemaking threatens to eliminate most US trichloroethylene uses within degreasing and consumer product categories.
- Aqueous and hydrocarbon substitution:Modified alcohol blends and supercritical CO2 systems displace chlorinated solvents in precision cleaning applications below 100°C operating thresholds.
Strategic Opportunities
- India's PLI scheme for electronics:Domestic semiconductor and PCB manufacturing incentives create virgin demand for import-dependent solvent supply chains.
- Closed-loop recovery systems:On-site distillation and carbon adsorption installations enable service-based revenue models that circumvent virgin solvent regulatory limits.
- Vietnam's industrial zone expansion:Northern manufacturing clusters near Hanoi attract textile and metalworking investment seeking less restricted solvent access than China.
Industry Challenges
- Process safety engineering scarcity:Chlorinated solvent handling expertise concentrates among aging workforces in Germany and Japan, constraining capacity transfer to emerging production sites.
- Cross-border waste classification disputes:Spent solvent shipments between OECD and non-OECD jurisdictions face inconsistent Basel Convention interpretations, disrupting circular economy claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Trichloroethylene and Perchloroethylene Market |
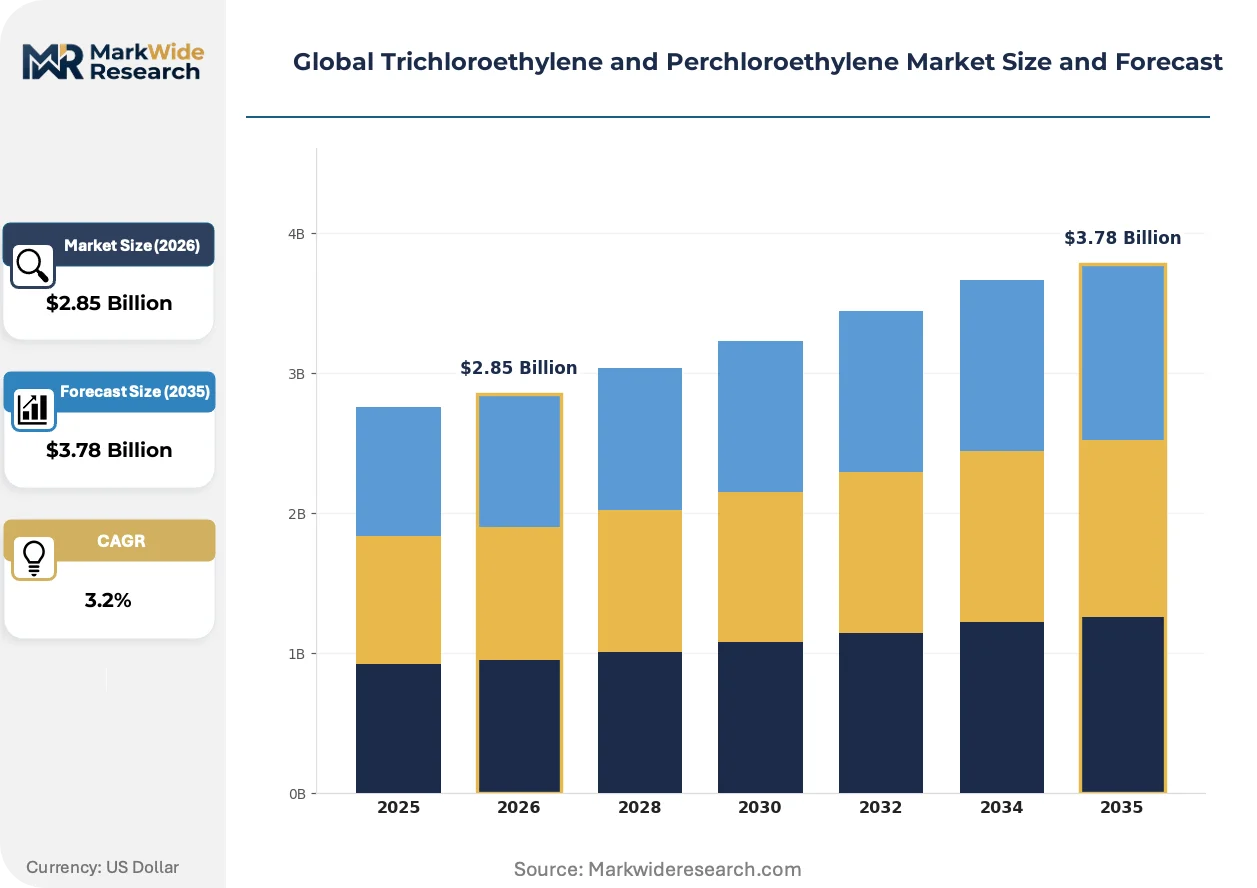
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $3.78 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Trichloroethylene, Perchloroethylene, Chlorinated Solvents, Dechlorination Agents Application: Metal Degreasing, Textile Dry Cleaning, Chemical Intermediates, Adhesive Formulation, Laboratory Solvent End User Industry: Electronics Manufacturing, Automotive Component Fabrication, Textile Care Providers, Pharmaceutical Production Packaging Type: Drums, Bulk Containers, Intermediate Bulk Containers, Cylinders |
| Companies Covered | Westlake Chemical, Olin Corporation, AGC Chemicals, Occidental Petroleum, Befar Group, SPOLCHEMIE, TOAGOSEI, Kanto Denka Kogyo, Dow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Trichloroethylene and Perchloroethylene Market Shifts & Advancements
Refrigerant-grade perchloroethylene specifications are diverging from industrial solvent grades as fluorochemical feedstock demand reshapes purification priorities and capacity allocation across integrated producers.
Vapor degreasing equipment is converging with hermetically sealed vacuum chamber designs that eliminate atmospheric emissions during solvent cycling. Automotive transmission manufacturers in Germany and aerospace component fabricators in France are adopting these systems to maintain process efficacy under tightening workplace exposure limits. This convergence is preserving chlorinated solvent viability in precision applications where open-top systems face phase-out.
REACH's perchloroethylene authorization requirement entered full enforcement for dry cleaning uses in 2016, with chemical intermediate applications facing 2026 review deadlines. German textile service operators accelerated hydrocarbon solvent transitions, while Italian and Spanish operators consolidated toward centralized wet cleaning facilities. The regulation is compressing European perchloroethylene demand toward fluorochemical intermediate consumption, which retains authorization exemptions.
Specification-driven procurement now dominates electronics-grade solvent contracting, with semiconductor foundries in Taiwan and South Korea imposing batch-level purity certifications that exclude commodity traders from direct supply relationships. Original equipment manufacturers are consolidating vendor bases to three qualified suppliers per facility to reduce qualification overhead. This pattern is most pronounced in Hsinchu Science Park and Pyeongtaek semiconductor clusters, where solvent procurement integrates directly with fab environmental health and safety audits.
Global Trichloroethylene and Perchloroethylene Market Segmentation
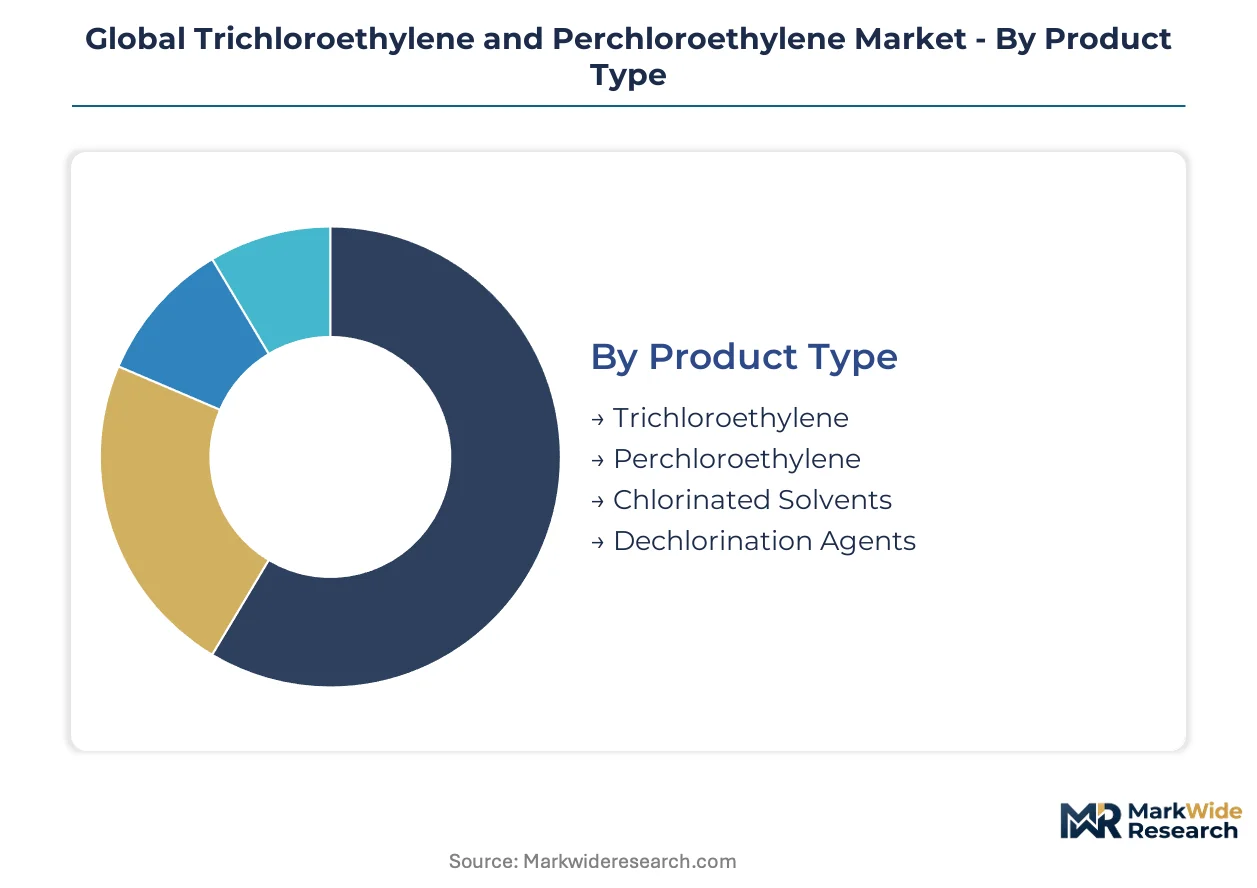
Chlorinated solvent procurement diverges sharply across end-use specifications, purity grades, and regulatory exposure profiles. Manufacturers configure product lines and distribution networks around these fault lines to defend margin structures against tightening emission controls.
Product Type:
Standardization dominates commodity grades while specification-grade production requires customized purification protocols and dedicated batch certification.
- Perchloroethylene:This chlorinated hydrocarbon carries a 121°C boiling point and superior thermal stability, making it the default choice for closed-loop vapor degreasing systems in Germany and France. REACH authorization exemptions for fluorochemical feedstock applications preserve European manufacturing economics despite dry cleaning phase-outs.
- Trichloroethylene:Acetylene-based chlorination yields this 87°C boiling point solvent with aggressive degreasing efficacy for precision metal components. EPA proposed bans under the Toxic Substances Control Act are compressing US demand toward chemical synthesis and export-oriented metal finishing.
- Chlorinated Solvents:Blended formulations combine multiple halogenated compounds to achieve specific evaporation rates and solvency parameters for niche adhesive and coating applications.
- Dechlorination Agents:Chemical additives facilitate spent solvent treatment and regulatory compliance in jurisdictions with strict halogenated waste discharge limits.
Most installed capacity flows through perchloroethylene. Expansion is steepest in dechlorination agents as waste treatment regulations tighten across OECD jurisdictions.
Application:
Volume concentration sits with mature industrial cleaning while value capture shifts toward chemical transformation and precision manufacturing inputs.
- Metal Degreasing:Automotive transmission manufacturers in Germany and aerospace fabricators in France deploy hermetically sealed vacuum vapor degreasing to maintain process efficacy under tightening workplace exposure limits. Closed-loop system adoption is preserving chlorinated solvent viability where open-top configurations face phase-out.
- Chemical Intermediates:Perchloroethylene serves as a feedstock for hydrofluorocarbon and hydrofluoroolefin production, with fluorochemical demand reshaping purification priorities at integrated producers in Japan and China.
- Textile Dry Cleaning:Entrenched infrastructure in Italy and Spain is consolidating toward centralized wet cleaning facilities as REACH authorization deadlines eliminate virgin solvent access for garment care.
- Adhesive Formulation:Specialty grades provide controlled solvency for pressure-sensitive adhesive manufacturing in industrial tape and label production.
- Laboratory Solvent:Analytical-grade specifications support chromatography and extraction protocols in pharmaceutical quality control laboratories.
Metal degreasing commands the largest volume footprint. Chemical intermediates are gaining share fastest as fluorochemical feedstock demand escalates.
End User Industry:
Customer procurement sophistication ranges from specification-intensive semiconductor foundries to price-sensitive textile service operators.
- Electronics Manufacturing:Taiwan's Hsinchu Science Park and South Korea's Pyeongtaek semiconductor clusters impose batch-level purity certifications that exclude commodity traders from direct supply relationships. Foundries consolidate vendor bases to three qualified suppliers per facility to reduce qualification overhead.
- Automotive Component Fabrication:Transmission and engine part manufacturers prioritize residue-free precision cleaning for high-performance drivetrain assemblies.
- Textile Care Providers:German operators accelerated hydrocarbon solvent transitions ahead of REACH deadlines, while Italian consolidation toward wet cleaning eliminated perchloroethylene demand in garment finishing.
- Pharmaceutical Production:Specification-intensive active pharmaceutical ingredient synthesis and extraction applications remain a mature segment with slower volume expansion.
Electronics manufacturing absorbs the highest specification-grade volume. India's PLI scheme for semiconductor and PCB manufacturing is creating virgin demand for import-dependent solvent supply chains.
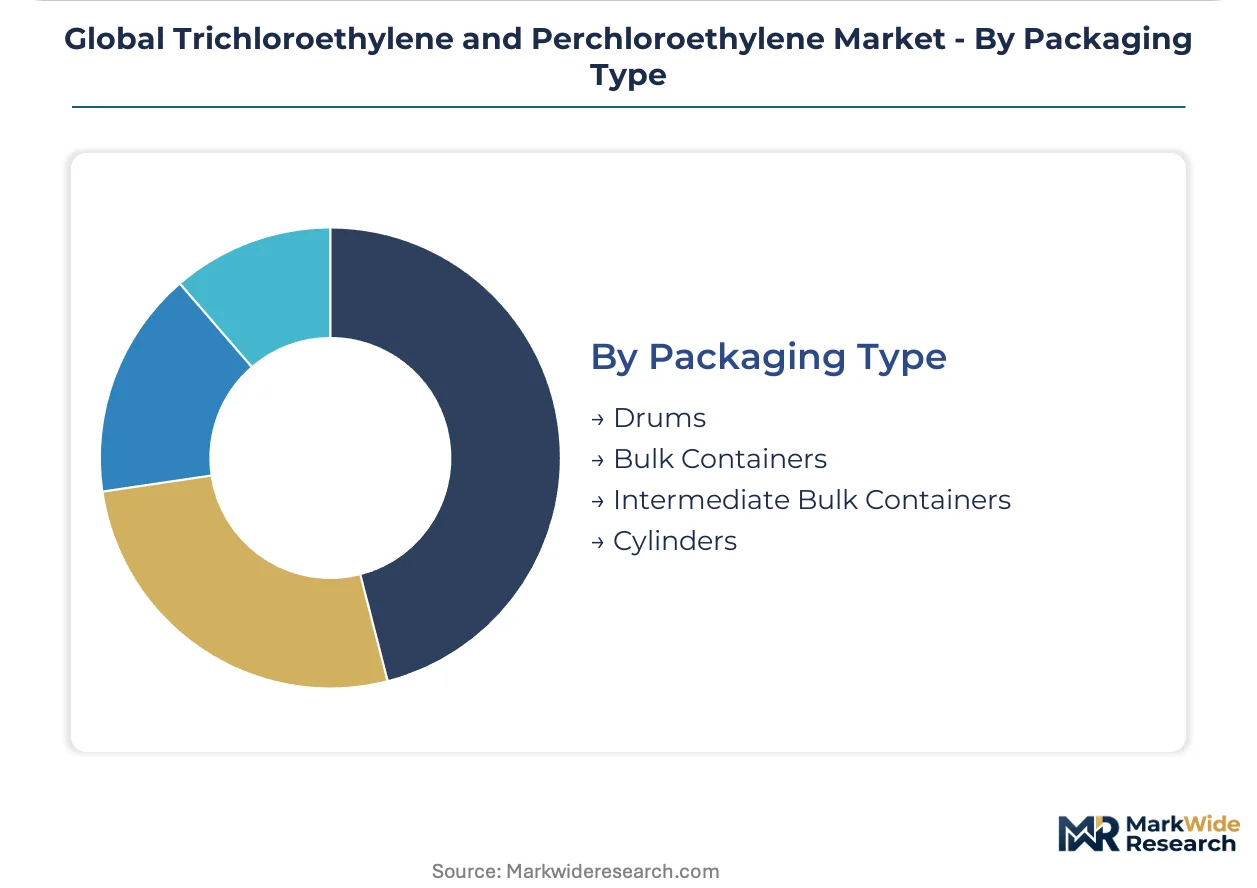
Packaging Type:
Logistics configuration tracks customer scale, with bulk formats dominating integrated chemical processors and unitized packaging serving dispersed industrial users.
- Bulk Containers:Integrated chlor-alkali producers in the US and integrated fluorochemical manufacturers in Japan receive tanker deliveries to minimize handling costs and emission exposure.
- Intermediate Bulk Containers:Mid-scale metal finishing operations and regional chemical distributors favor tote formats for operational flexibility.
- Drums:Small-batch chemical synthesis and laboratory procurement rely on standardized 200-liter steel drums with specialized linings.
- Cylinders:High-purity electronics grades require pressurized cylinder delivery to maintain contamination-free specifications for semiconductor fabrication.
Bulk containers move the largest tonnage. Cylinders are expanding most quickly as electronics-grade purity requirements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity migrates toward jurisdictions where volatile organic compound enforcement remains fragmented, creating cost-of-compliance arbitrage between established OECD markets and emerging manufacturing hubs. Chlorinated solvent manufacturers redirect investment toward inland Chinese provinces and Southeast Asian industrial zones where emission inspection intensity lags coastal benchmarks. This geographic divergence concentrates supply growth outside traditional North American and European production centers.
United States
EPA rulemaking under the Toxic Substances Control Act threatens most commercial trichloroethylene applications, compressing domestic demand toward chemical synthesis and export-oriented metal finishing. Gulf Coast integrated chlor-alkali producers leverage feedstock proximity to serve Latin American export markets. Texas and Louisiana chemical corridors maintain solvent production despite regulatory headwinds, with capacity increasingly dedicated to fluorochemical intermediate manufacturing rather than domestic degreasing supply.
Germany
REACH authorization requirements for perchloroethylene eliminated dry cleaning demand while preserving chemical intermediate exemptions for fluorochemical feedstock production. Bavarian and North Rhine-Westphalia industrial clusters deploy hermetically sealed vapor degreasing systems to maintain automotive and aerospace component cleaning under tightening workplace exposure limits. German equipment engineering expertise in closed-loop recovery systems creates service-based revenue models that circumvent virgin solvent regulatory constraints.
China
Domestic metal degreasing operations and semiconductor fabrication scale drive chlorinated solvent consumption, with MEE enforcement gaps in inland provinces allowing continued capacity expansion. Shandong and Jiangsu chemical processing zones concentrate acetylene-based chlorination capacity despite periodic environmental shutdowns affecting calcium carbide feedstock economics. Yangtze River Delta electronics manufacturers import ultra-high-purity grades for wafer cleaning as domestic purification capabilities mature.
Japan
Integrated fluorochemical producers anchor perchloroethylene demand as hydrofluorocarbon and hydrofluoroolefin feedstock requirements reshape purification priorities at domestic manufacturing sites. Chubu and Kanto industrial corridors maintain specification-grade solvent production for semiconductor and electronics component cleaning. Japanese process safety engineering expertise concentrates among aging workforces, constraining knowledge transfer to emerging Asian production sites despite sustained domestic demand.
India
PLI scheme incentives for semiconductor and printed circuit board manufacturing create virgin demand for import-dependent chlorinated solvent supply chains as domestic production capacity remains limited. Maharashtra and Gujarat chemical processing zones attract regional distribution investment to serve emerging electronics manufacturing clusters. Central pollution control board enforcement of volatile organic compound emission standards lags OECD benchmarks, allowing metal finishing capacity expansion without closed-loop recovery system mandates.
Global Trichloroethylene and Perchloroethylene Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with specification-grade electronics applications consolidating around qualified supplier bases while commodity metal degreasing tolerates broader vendor participation. The vendor base fragments across three operational tiers: integrated chlor-alkali producers with captive feedstock economics, regional chemical distributors with blending and logistics capabilities, and specialty purification houses serving semiconductor foundry certification requirements. Strategic moves concentrate on backward integration into acetylene or ethylene feedstock control and geographic expansion toward jurisdictions with less stringent emission enforcement.
Among North American integrated producers, Westlake Chemical and Olin Corporation exemplify the chlor-alkali-backed archetype with captive supply chain positioning. AGC Chemicals anchors Asia-Pacific availability from Japanese and Thai manufacturing bases. These three companies represent distinct geographic anchoring strategies—Gulf Coast feedstock access, diversified North American production networks, and Asia-Pacific fluorochemical integration—without overlapping direct competition in identical specification segments.
| Leading Market Players |
|---|
| Westlake Chemical |
| Olin Corporation |
| AGC Chemicals |
| Occidental Petroleum |
| Befar Group |
| SPOLCHEMIE |
| TOAGOSEI |
| Kanto Denka Kogyo |
| Dow |
| Others |
Supply & Pricing Matrix
Captive chlor-alkali integration at Gulf Coast producers anchors both feedstock security and pricing power against acetylene-based competitors in Shandong. This upstream control allows integrated manufacturers to absorb calcium carbide volatility while commanding premium positions in specification-grade electronics solvents.
Pricing Analysis
Distributor margin compression in commodity metal degreasing grades contrasts with direct-to-OEM premiums for semiconductor-certified batches. Three-tier pricing structure across electronics-grade, industrial-specification, and commodity solvent levels separates foundry procurement from textile service operators. Cost compression in standard grades intensifies because aqueous substitution systems displace open-top vapor degreasing below precision thresholds. Textile dry cleaners in Italy and Spain exhibit highest price sensitivity; Taiwan semiconductor foundries accept substantial premiums for batch-level contamination certification.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Houston coordinate hub-and-spoke patterns for bulk solvent movements. Manufacturing concentrates in China, the United States, and Japan, with Shandong and Jiangsu provinces hosting acetylene-based chlorination clusters. Feedstock economics rest on calcium carbide availability, ethylene oxychlorination capacity, and integrated chlor-alkali output. Single-source vulnerability runs through Chinese calcium carbide supply subject to electricity pricing and environmental shutdown cycles. Distribution runs through tanker deliveries for integrated processors, tote formats for regional distributors, and pressurized cylinders for electronics-grade purity maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where REACH authorization timelines and EPA proposed bans under the Toxic Substances Control Act are forcing demand migration toward jurisdictions with fragmented enforcement.
For Market Incumbents: Extend closed-loop recovery system deployment to convert virgin solvent sales into service-based revenue streams that circumvent regulatory limits. Deepen backward integration into acetylene or ethylene feedstock control to defend margin position against Shandong producers facing electricity volatility. Aqueous substitution technologies threaten open-top degreasing applications; hermetically sealed vacuum chamber investments preserve process viability in German and French aerospace clusters. For New Entrants and Emerging Players: The price-point gap between premium electronics-grade certification and economy metal degreasing commodities creates entry space for mid-tier regional suppliers. India's PLI scheme for semiconductor manufacturing offers the most penetrable geography, with import-dependent supply chains and lagging domestic purification capacity. A toll-manufacturing go-to-market angle serving Yangtze River Delta electronics fabricators bypasses capital-intensive distillation infrastructure requirements. For Investors and Strategic Acquirers: Roll-up economics work for regional chemical distributors with blending capabilities because specification-grade procurement consolidation at semiconductor foundries is compressing vendor bases to three qualified suppliers per facility. Target mid-scale distributors in Maharashtra and Gujarat serving emerging Indian electronics clusters. The signal to watch is MEE enforcement intensity variance across Chinese inland provinces, which would accelerate capacity migration toward Vietnam and India.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acetylene Feedstock | Captive calcium carbide supply insulates Shandong producers from electricity-driven cost volatility. |
| Hermetically Sealed Vapor Degreasing Deployment | German automotive transmission manufacturers adopt vacuum chamber designs to maintain process efficacy under tightening workplace exposure limits. |
| Electronics-Grade Purification Investment | Taiwan Hsinchu Science Park foundries impose batch-level purity certifications that exclude commodity traders. |
| Regional Distribution Hub Expansion | Maharashtra and Gujarat chemical zones attract investment to serve India's PLI-scheme electronics manufacturing incentives. |
| Closed-Loop Recovery System Installation | On-site distillation enables service-based revenue models circumventing virgin solvent regulatory limits in REACH jurisdictions. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to capture both volume trajectories and regulatory implementation timelines. Primary discussions engaged plant managers at chlor-alkali facilities, procurement leads at semiconductor foundries, distribution channel partners in European solvent networks, and technical R&D directors at fluorochemical producers. Secondary validation drew from customs and trade data, SEC 10-K filings, ECHA authorization registries, and MEE emission standard disclosures. Bottom-up capacity modeling and top-down demand segmentation were cross-referenced to anchor projections.
Historical reference periods established baseline consumption patterns across metal degreasing, chemical intermediate, and electronics cleaning applications before modeling forward. The forecast framework segments by product grade tier, end-use industry concentration, packaging format, and regional production hub economics. CAGRs were derived from supply-demand balance modeling across the projection horizon. Industry-specific inputs include semiconductor node migration rates affecting ultra-high-purity solvent intensity and REACH authorization timeline assumptions for perchloroethylene chemical intermediate exemptions.
The model assumes a particular technology adoption path; alternative pathways for aqueous and supercritical CO2 substitution systems would alter the outlook for chlorinated solvent demand. Forecasts reflect documented assumptions regarding regulatory enforcement intensity variance across Chinese provinces and REACH authorization continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Propylene Glycol Methyl Ether Market
Solvents
Mono Propylene Glycol Market
Solvents
Dimethyl Sulfoxide Market
Solvents
Propylene Glycol Market
Solvents
Decanol Market
Solvents
Global Chloroform Market
Solvents
Chloromethane Market
Solvents
Asia Pacific Industrial Solvents Market
Solvents
Crotonaldehyde Market
Solvents
Green Solvents Market
Solvents
Xylene Market
Solvents
Methyl Ethyl Ketone (MEK) Market
Solvents
Aliphatic Hydrocarbon Solvents and Thinners Market
Solvents
Diethylene Glycol Monobutyl Ether Market
Solvents
Nitrobenzene Market
Solvents
2 - Ethyl Anthraquinone Market