
 Hexylene Glycol Market | 2026-2036
Hexylene Glycol Market Size, Share, and Industry Trends Forecast 2026-2036
Hexylene Glycol Market Outlook
Multi-pack bundling of industrial-grade and technical-grade hexylene glycol is expanding as a procurement option for mid-sized paint producers seeking inventory flexibility. BASF SE leverages its integrated C6 chemistry platform to sustain feedstock cost advantages across European and Asian supply points. Dow Chemical Company anchors North American availability through its Gulf Coast manufacturing infrastructure, while Solvay S.A. competes on specialty-grade purity for pharmaceutical and cosmetic channels.
Hexylene glycol is a six-carbon diol produced via catalytic hydration of diacetone alcohol or direct synthesis from hexene derivatives, functioning primarily as a coupling solvent, viscosity modifier, and freeze-point depressant in aqueous and solvent-based formulations. Industrial-grade material dominates volume throughput for paint and coatings applications where cost efficiency outweighs purity thresholds, while cosmetic-grade and pharmaceutical-grade segments command premium positioning due to stringent impurity limits and certification requirements for skin-contact and ingestible uses. The solvents application category leads absolute consumption, though personal care products and plasticizers represent faster-growing demand pools as formulators substitute phthalate-based alternatives.
REACH registration requirements in Europe, EPA National Emission Standards for Hazardous Air Pollutants in the United States, and China's GB standards for industrial chemical purity collectively shape product specifications, testing protocols, and cross-border market access conditions. ECHA substance evaluation dossiers and SAMR quality inspections in China are tightening traceability and documentation burdens for importers and domestic producers alike. Stakeholders must monitor evolving grade-specific certification demands and regional feedstock cost differentials to optimize production allocation and customer targeting.
Market Dynamics
Waterborne coating formulations are displacing solvent-based systems across industrial and architectural segments, forcing hexylene glycol producers to recalibrate grade purity specifications and technical service capabilities for paint manufacturers facing REACH and EPA emission ceilings.
Growth Catalysts
- EPA NESHAP solvent-emission limits:United States paint producers are accelerating technical-grade hexylene glycol procurement to comply with hazardous air pollutant thresholds, expanding the addressable market for compliant coupling solvents.
- Phthalate substitution in plasticizers:Formulators across personal care and flexible packaging are adopting hexylene glycol-derived alternatives to banned orthophthalates, opening volume growth in historically stagnant segments.
- Industrial solvent demand in China:Coastal manufacturing clusters in Jiangsu and Zhejiang provinces are scaling waterborne coating capacity, concentrating regional consumption of industrial-grade material.
Market Restraints
- Acetone feedstock volatility:Diacetone alcohol production costs fluctuate with propylene-derived acetone pricing, compressing margin stability for non-integrated producers lacking captive ketone supply.
- European supply concentration:BASF SE and Solvay S.A. control majority European technical-grade capacity, creating procurement risk for mid-sized paint producers without multi-source contracts.
- Propylene glycol substitution:Lower-cost C3 diols are capturing share in freeze-point depressant applications where purity thresholds permit formulation flexibility.
Strategic Opportunities
- Pharmaceutical-grade certification:USP and EP monograph compliance for hexylene glycol is unlocking parenteral drug formulation contracts previously served by higher-cost specialty glycols.
- India personal care expansion:CDSCO cosmetic ingredient registration and BIS quality standards are formalizing import channels for cosmetic-grade material into underpenetrated domestic brands.
- Biobased C6 platform development:Catalytic hydrogenation of bio-derived hexenal intermediates is electrifying renewable pathway economics for sustainability-positioned coatings customers.
Industry Challenges
- ECHA substance evaluation dossier preparation:REACH registrants face escalating toxicological data requirements and extended evaluation timelines, stretching regulatory affairs staffing and documentation budgets.
- Multi-grade inventory complexity:Paint producers managing simultaneous technical-grade, cosmetic-grade, and pharmaceutical-grade specifications report SKU proliferation and quality segregation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hexylene Glycol Market |
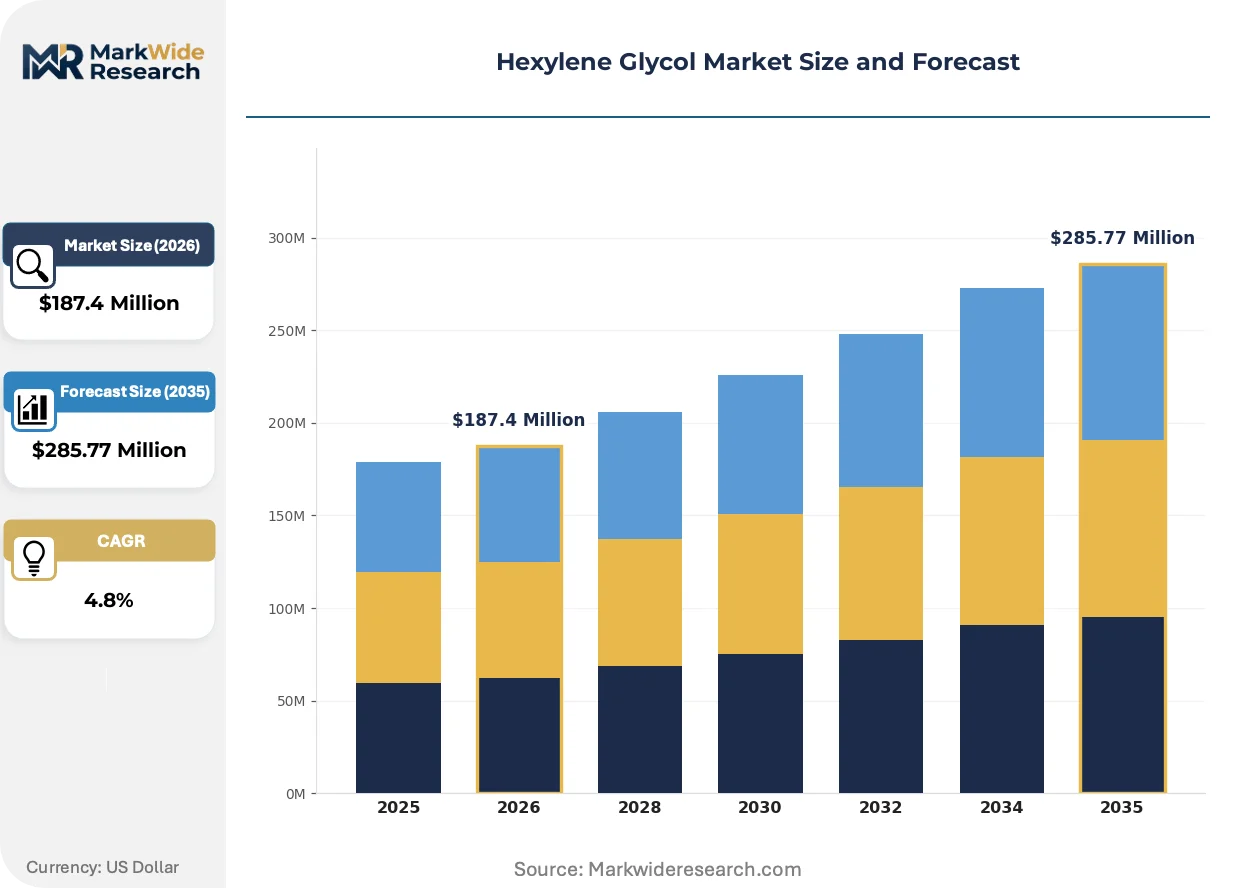
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Technical Grade, Cosmetic Grade, Pharmaceutical Grade Application: Solvents, Plasticizers, Paints, Personal Care Products End User: Cosmetics Manufacturers, Paint Producers, Industrial Users, Pharmaceutical Companies Grade: Premium Quality, Standard Quality, Basic Quality, Others |
| Companies Covered | BASF SE, Solvay S.A., Dow Chemical Company, Eastman Chemical Company, Arkema Group, Monument Chemicals, Inc., Lonza Group, Solventis Ltd., LyondellBasell Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hexylene Glycol Market Strategic Shifts
Continuous processing technology and catalytic system refinement are compressing unit economics for hexylene glycol production, while regulatory tightening across major economies is elevating purity certification from commercial preference to market access requirement.
Membrane separation technology for residual acetone recovery is electrifying yield rates in diacetone alcohol hydrogenation trains. German specialty chemical producers are retrofitting existing batch facilities with continuous membrane units, reducing solvent losses by half. This capital deployment is enabling price competitiveness against Middle Eastern propylene glycol imports in European coating applications.
REACH restriction proposals for microplastics in leave-on cosmetics are tightening purity specifications for hexylene glycol used as fragrance solubilizer. ECHA guidance documents now require sub-ppm particulate testing for cosmetic-grade certification. French and German formulators are demanding extended contaminant panels, forcing suppliers to revalidate analytical methods and certificate of analysis formats.
Direct mill-supply contracting is compressing distributor margins in North American industrial solvent channels. Large paint manufacturers in Ohio and Texas are negotiating frame contracts with hexylene glycol producers for annual volume commitments with quarterly price adjustments. This disintermediation is visible most acutely in automotive OEM coating supply chains, where just-in-time inventory requirements favor producer-direct logistics over regional chemical distribution.
Hexylene Glycol Market Segmentation
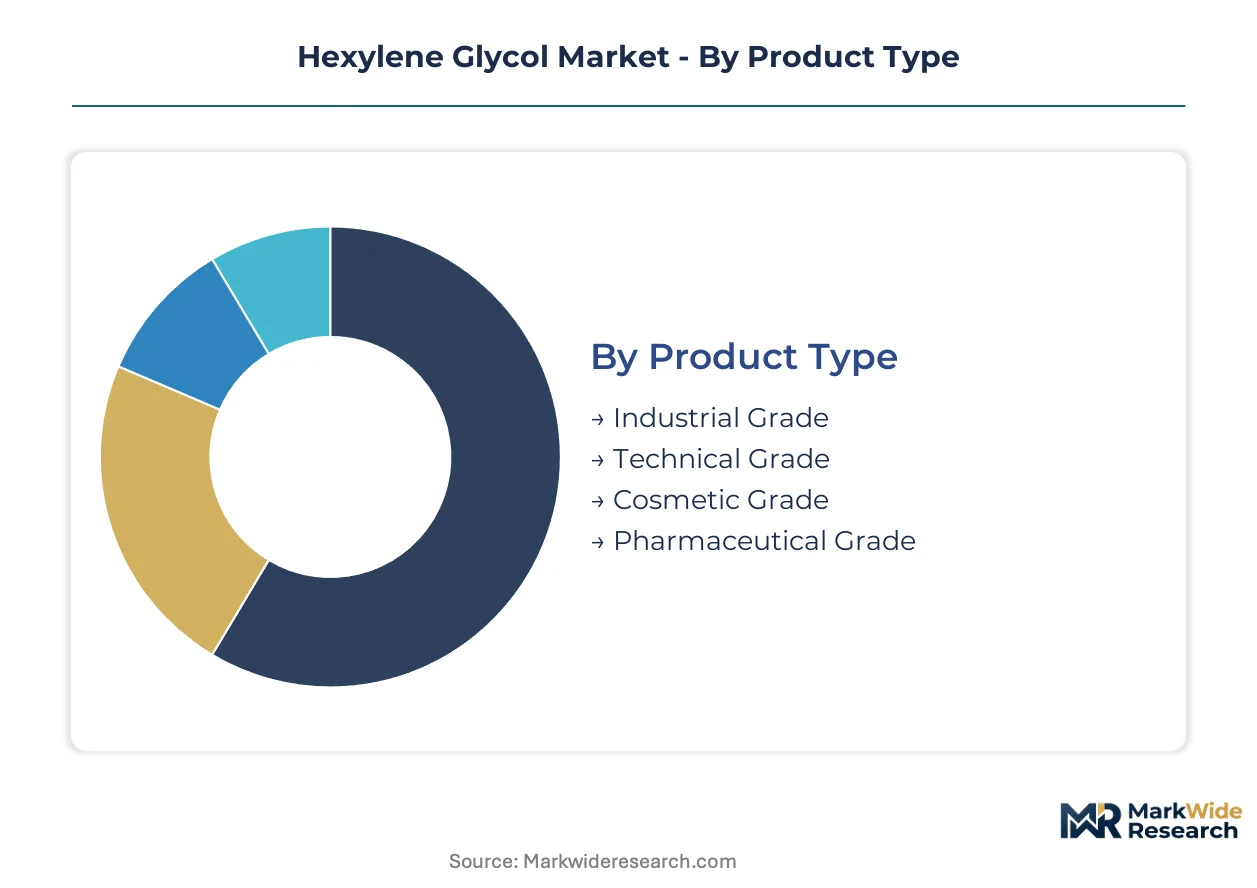
Hexylene glycol's value chain fragments sharply across purity thresholds and certification requirements. Grade-specific pricing spreads and regulatory compliance burdens create distinct competitive arenas that reward specialized positioning over undifferentiated volume play.
Product Type:
Purity specifications and impurity tolerances define the technical axis across all four product categories.
- Industrial Grade:Material with 95-98% purity serves coupling solvent and viscosity modification roles in waterborne coatings. Paint producers in Germany and the United States scale procurement under EPA NESHAP and REACH emission ceilings, prioritizing cost efficiency over trace contaminant control.
- Technical Grade:Higher purity specifications (98-99.5%) support precision applications requiring consistent freeze-point depression and humectant performance. Demand concentrates in industrial solvent formulations across China's Jiangsu and Zhejiang manufacturing clusters.
- Cosmetic Grade:Sub-ppm particulate certification under ECHA microplastic guidance enables fragrance solubilizer and skin-contact applications.
- Pharmaceutical Grade:USP and EP monograph compliance unlocks parenteral drug formulation contracts with stringent endotoxin and heavy metal limits.
Mature deployment sits with Industrial Grade. Newer deployment is concentrated in Pharmaceutical Grade.
Application:
Functional roles in formulation chemistry separate the four application categories by performance requirements and substitution dynamics.
- Solvents:Coupling and coalescing functions dominate volume throughput as waterborne coating systems displace solvent-based alternatives. REACH and EPA emission limits are accelerating technical-grade procurement for compliant formulation.
- Personal Care Products:Humectant and solubilizer applications in skincare and fragrance formulations are climbing the fastest as phthalate substitution drives glycol-derived alternatives.
- Plasticizers:Flexibility modification in packaging films and personal care products benefits from orthophthalate bans across European and North American jurisdictions.
- Paints:Architectural and industrial coating segments anchor steady demand for viscosity control and freeze-point depression in aqueous systems.
Volume leadership rests with Solvents. Steepest expansion trajectory belongs to Personal Care Products.
End User:
Procurement scale and certification sophistication distinguish the four customer categories.
- Paint Producers:Mid-sized and large manufacturers negotiate direct mill-supply contracts with quarterly price adjustments, compressing distributor margins in North American channels.
- Industrial Users:Diverse manufacturing operations across coatings, adhesives, and cleaning formulations purchase industrial-grade material through regional chemical distribution.
- Cosmetics Manufacturers:French and German formulators demand extended contaminant panels and revalidated analytical methods for cosmetic-grade certification.
- Pharmaceutical Companies:Parenteral and topical drug developers require USP and EP monograph documentation with batch-specific traceability.
Contract sophistication peaks with Pharmaceutical Companies. Procurement scale concentrates with Paint Producers.
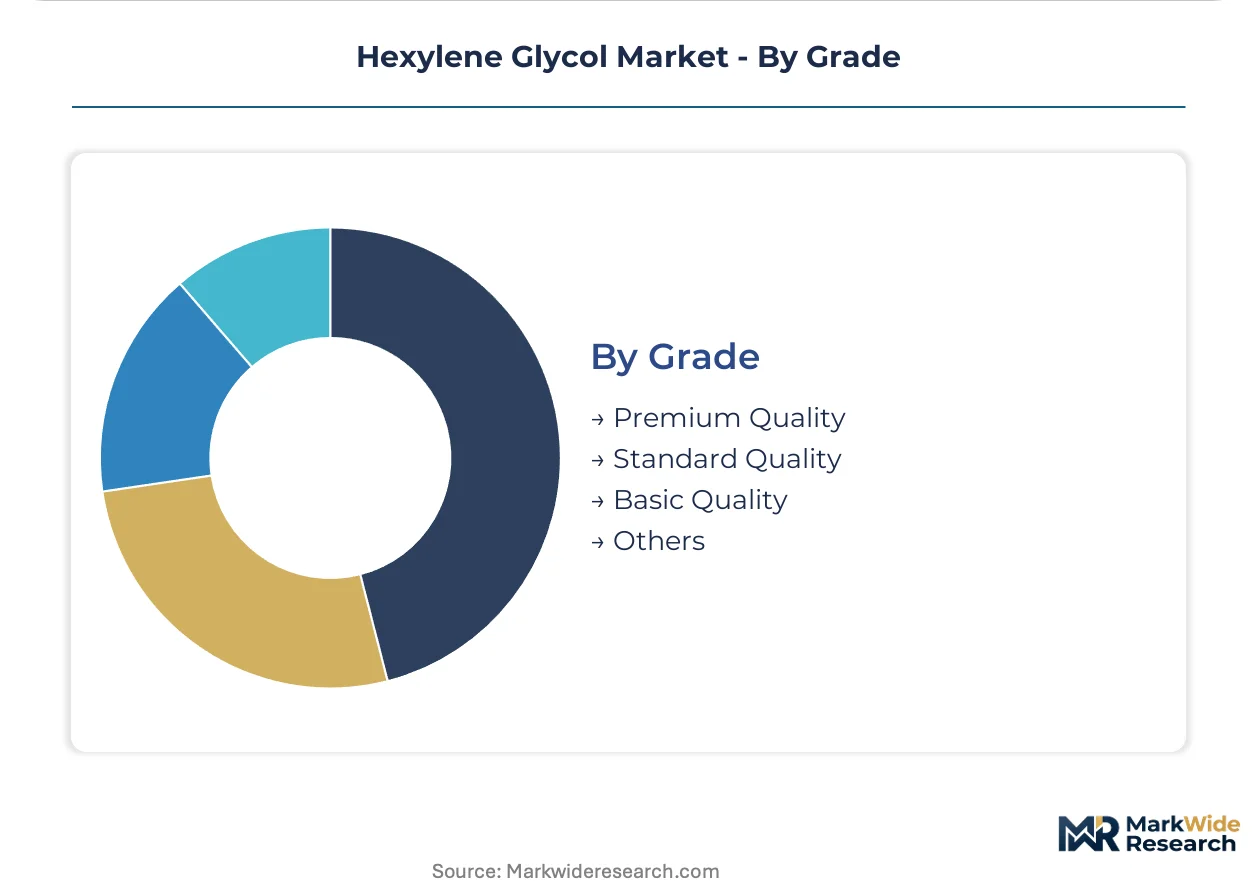
Grade:
Quality tiering reflects certification burden and price positioning across the value chain.
- Standard Quality:Balanced purity and cost positioning serves mid-tier industrial solvent and coating applications with moderate regulatory exposure.
- Premium Quality:Elevated impurity controls and documentation packages command price premiums in pharmaceutical and cosmetic channels where certification failures carry recall liability.
- Basic Quality:Minimal processing meets bulk industrial applications with limited performance sensitivity and high volume requirements.
- Others:Custom specifications and transitional grades address niche applications and contract manufacturing arrangements.
Margin compression is most severe in Basic Quality. Value capture concentrates in Premium Quality.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in Germany and the United States while consumption tilts toward China's coastal manufacturing zones and India's expanding personal care sector. This geographic split creates trade flows from integrated petrochemical hubs to formulation-intensive markets. Regulatory divergence between REACH-mandated Europe and EPA-governed North America shapes grade specifications and certification burdens differently across regions.
Germany
BASF SE's Ludwigshafen complex anchors European supply through captive C6 chemistry integration. ECHA substance evaluation dossiers and REACH registration requirements tighten toxicological documentation for all grades. Paint producers in North Rhine-Westphalia's Ruhr industrial belt are expanding technical-grade procurement as waterborne coating formulations displace solvent-based systems under emission ceilings.
United States
Dow Chemical Company's Gulf Coast infrastructure secures domestic availability for industrial solvent and coating applications. EPA National Emission Standards for Hazardous Air Pollutants compel paint manufacturers in Ohio and Texas to accelerate compliant coupling solvent adoption. Direct mill-supply contracting is compressing distributor margins in automotive OEM coating supply chains across the Midwest and Southeast.
China
SAMR quality inspections and GB standards for industrial chemical purity formalize import channels and domestic production protocols. Coastal manufacturing clusters in Jiangsu and Zhejiang provinces are scaling waterborne coating capacity, concentrating regional consumption of industrial-grade material. The country's dual carbon goals are electrifying interest in biobased C6 platform development for sustainability-positioned coatings customers.
India
CDSCO cosmetic ingredient registration and BIS quality standards are formalizing import channels for cosmetic-grade hexylene glycol into underpenetrated domestic brands. Maharashtra and Gujarat host expanding personal care formulation operations seeking phthalate-substitute plasticizers. Industrial solvent demand from Tamil Nadu's textile and leather processing clusters is climbing as waterborne systems penetrate traditional manufacturing.
France
Solvay S.A.'s specialty-grade production serves pharmaceutical and cosmetic channels with stringent purity certification. ECHA microplastics guidance for leave-on cosmetics now requires sub-ppm particulate testing, forcing analytical method revalidation. Formulators in the Île-de-France region are demanding extended contaminant panels for fragrance solubilizer applications, elevating documentation burdens for suppliers.
Hexylene Glycol Market Competitive Environment
The competitive structure tilts toward integrated petrochemical majors with captive feedstock positions. Three to five multinational chemical conglomerates control majority capacity in Europe and North America through backward integration into propylene-derived ketone supply. Mid-sized regional specialists compete on grade-specific certification and technical service rather than scale. Capacity expansion and strategic partnerships represent the dominant competitive moves, with producers seeking to secure multi-year supply contracts with large paint manufacturers.
Within the integrated multinational tier, BASF SE, Dow Chemical Company, and Solvay S.A. exemplify divergent strategic positioning. BASF represents the fully integrated archetype with European and Asian supply point coordination through its C6 chemistry platform. Dow occupies a position anchored in North American Gulf Coast manufacturing infrastructure with emphasis on industrial-grade volume throughput. Solvay sits within the specialty-grade vector, competing on purity certification for pharmaceutical and cosmetic channels where documentation failures carry recall liability. Monument Chemicals and Eastman Chemical exemplify mid-cap specialists pursuing grade-specific differentiation rather than undifferentiated scale play.
| Leading Market Players |
|---|
| BASF SE |
| Solvay S.A. |
| Dow Chemical Company |
| Eastman Chemical Company |
| Arkema Group |
| Monument Chemicals, Inc. |
| Lonza Group |
| Solventis Ltd. |
| LyondellBasell Industries |
| Others |
Value Chain & Pricing Dynamics
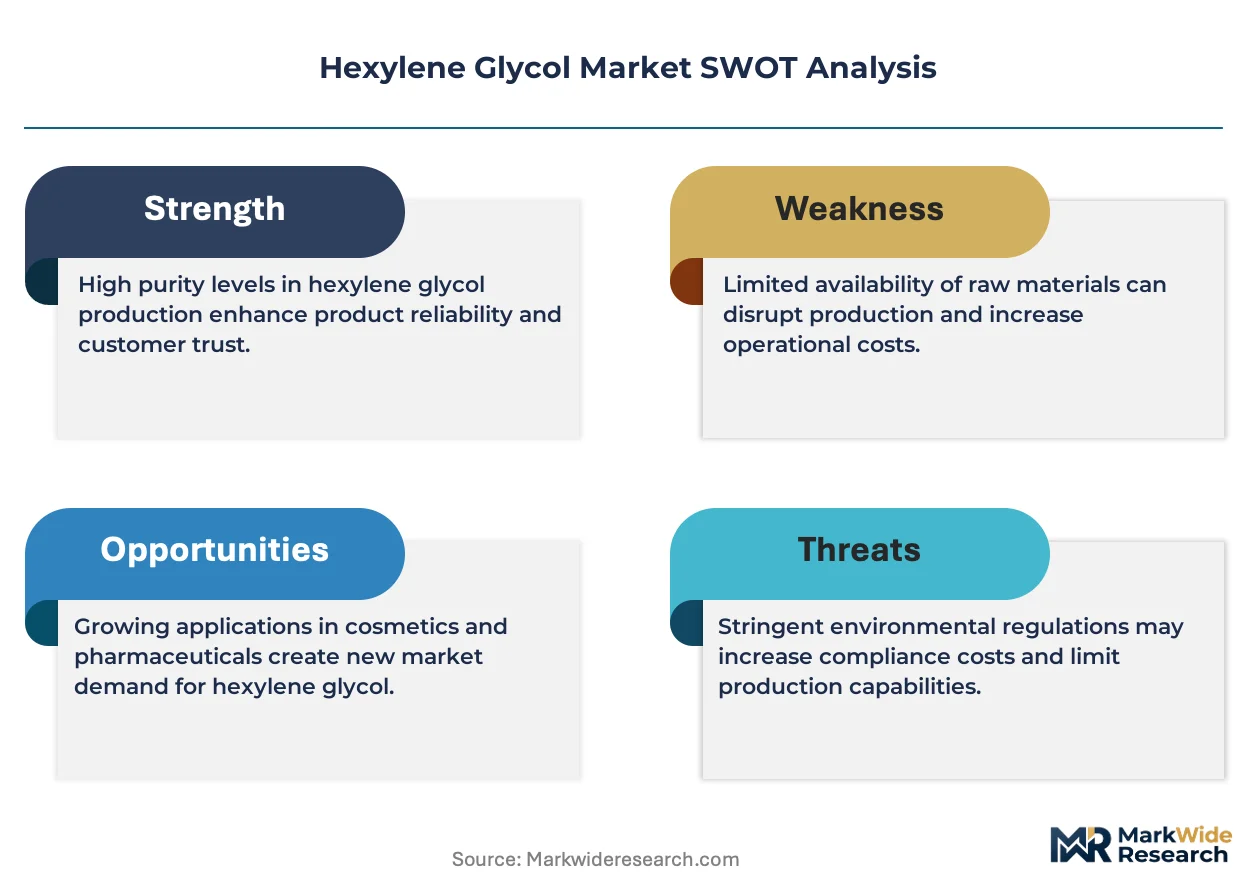
REACH registration requirements and EPA emission ceilings gate qualified supply for premium-tier hexylene glycol grades while elevating certification costs that feed through to price premiums for pharmaceutical and cosmetic channels. Paint manufacturers face tiered access where compliant technical-grade material commands sustained premiums over industrial-grade alternatives.
Pricing Analysis
Margin tightening in industrial-grade tiers reflects acetone feedstock volatility and propylene glycol substitution pressure from lower-cost C3 diols. Three-tier pricing structure across pharmaceutical, cosmetic, and industrial certification levels separates buyers by purity threshold and documentation burden. Price differentiation rests on USP/EP monograph compliance and ECHA microplastic guidance adherence. Mid-sized paint producers show highest price sensitivity due to direct mill-supply contracting leverage, while pharmaceutical companies absorb premiums for batch-specific traceability.
Supply Chain Analysis
Skilled chemical process operator availability constrains continuous processing retrofits in Germany's Ludwigshafen and North Rhine-Westphalia manufacturing zones. Supply concentrates in Germany, the United States, and China through BASF SE's C6 platform, Dow's Gulf Coast infrastructure, and Jiangsu/Zhejiang coastal clusters. Raw material dependencies center on propylene-derived acetone, diacetone alcohol, and catalytic hydrogenation reagents. Single-source vulnerability persists for European technical-grade capacity controlled by integrated majors. Distribution runs through direct mill-supply contracts for large paint manufacturers and regional chemical distributors for mid-tier industrial users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Waterborne coating formulations are displacing solvent-based systems as the dominant technology transition, with membrane separation and continuous processing retrofits replacing legacy batch hydrogenation trains.
For Market Incumbents: Cement backward integration into captive ketone supply to defend against acetone price volatility and propylene glycol substitution threats. Expand pharmaceutical-grade certification capacity to capture parenteral drug formulation contracts. Prioritize continuous membrane unit deployment over batch facility maintenance to sustain yield advantages against Middle Eastern imports. For New Entrants and Emerging Players: Begin with India's underpenetrated cosmetic-grade segment where CDSCO registration formalizes import channels for domestic personal care brands. Target Maharashtra and Gujarat formulation operations seeking phthalate-substitute plasticizers. Pursue toll manufacturing arrangements with existing C6 chemistry platforms rather than greenfield capacity builds. For Investors and Strategic Acquirers: ECHA substance evaluation timeline extensions are the leading indicator that regulatory affairs capabilities will separate viable acquisition targets from stranded assets. Five-to-ten year viability favors mid-cap specialists with grade-specific certification depth over undifferentiated volume players. Watch for SAMR quality inspection enforcement in China as the signal for import channel consolidation opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ketone Supply | BASF SE's captive C6 chemistry platform demonstrates margin protection against propylene feedstock swings. |
| Pharmaceutical-Grade Certification Investment | USP and EP monograph compliance unlocks parenteral contracts previously served by higher-cost specialty glycols. |
| Continuous Processing Retrofit | German producers halve solvent losses through membrane separation technology deployment in hydrogenation trains. |
| Direct Mill-Supply Contracting | Ohio and Texas paint manufacturers compress distributor margins through frame contracts with quarterly adjustments. |
| Biobased C6 Platform Development | Catalytic hydrogenation of bio-derived hexenal intermediates electrifies renewable pathway economics for sustainability customers. |
Study Parameters
Independent corroboration across plant managers at integrated petrochemical complexes, procurement leads at downstream paint manufacturers, distribution channel partners, and technical R&D directors underwrites the qualitative findings. Secondary validation draws from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and ECHA substance evaluation dossiers. Bottom-up grade-specific volume estimates and top-down regional consumption patterns were reconciled through iterative triangulation.
Rate-of-change decomposition across the analysis window segments volume and value trajectories by grade tier, end-use industry, and regional production hub. CAGRs were derived from modeled substitution dynamics between waterborne and solvent-based coating systems, phthalate substitution elasticity in personal care, and propylene glycol cross-elasticity in freeze-point applications. Forecast inputs incorporate REACH restriction proposal timelines and EPA NESHAP enforcement intensity assumptions.
Underlying measurement precision varies by segment; pharmaceutical-grade and cosmetic-grade volumes carry tighter precision than industrial-grade bulk throughput given documentation traceability requirements. Forecasts reflect assumptions about regulatory enforcement continuity and feedstock cost stabilization. Material deviation in acetone pricing volatility or ECHA evaluation timeline acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
India High Purity Solvents Market
Solvents
Allyl Cyanide Market
Solvents
Solvent Cement Market
Solvents
Hydrophobic Solvents Market
Solvents
Global Solvent Dyes Market
Solvents
Para Nitrochlorobenzene Market
Solvents
3-Methyl-3-Penten-2-One (3M3P) Market
Solvents
Global Ethyl Lactate Market
Solvents
Monochlorobenzene Market
Solvents
Dimethyl Sulfoxide Market
Solvents
Natural Distillates Market
Solvents
Chloroacetonitrile Market
Solvents
Coating Solvents Market
Solvents
3-Butylene Glycol Market
Solvents
Global Acetonitrile Market
Solvents
Fluorinated Solvents Market