
 Benzene Market | 2026-2036
Benzene Market Size, Share, and Industry Trends Forecast 2026-2036
Benzene Market Intelligence
Downstream derivative licensing is reshaping how petrochemical houses capture value from benzene streams. INEOS Group leverages its integrated aromatics platform across European crackers and reformers to sustain margin capture from ethylbenzene and cumene chains. BASF SE anchors its position through backward integration into naphtha cracking and proprietary catalyst technology for benzene yield optimization. SABIC competes on feedstock cost advantage tied to Saudi ethane and naphtha flexibility at its Yanbu complex.
Benzene is an aromatic hydrocarbon with molecular formula C₆H₆, produced primarily via catalytic reforming of naphtha and steam cracking of hydrocarbon feedstocks, serving as a foundational building block for styrene, phenol, and nylon intermediates. Ethylbenzene dominates product-type value generation due to its lockstep relationship with styrene demand in packaging and construction. Cyclohexane represents the fastest-expanding product category as adipic acid and caprolactamide requirements for nylon 6,6 strengthen. Industrial grade commands the largest grade share, though reagent grade concentrates margin pools in pharmaceutical and agrochemical precursor applications.
EPA benzene emissions standards under the Clean Air Act constrain refinery and petrochemical operations in the United States, while REACH registration requirements in Europe mandate toxicological dossiers for benzene derivative manufacturers. China's MEE enforces stricter volatile organic compound limits around aromatics clusters in Shandong and Zhejiang provinces. Stakeholders must monitor feedstock slates, regulatory tightening trajectories, and derivative margin cycles to time capacity commitments effectively.
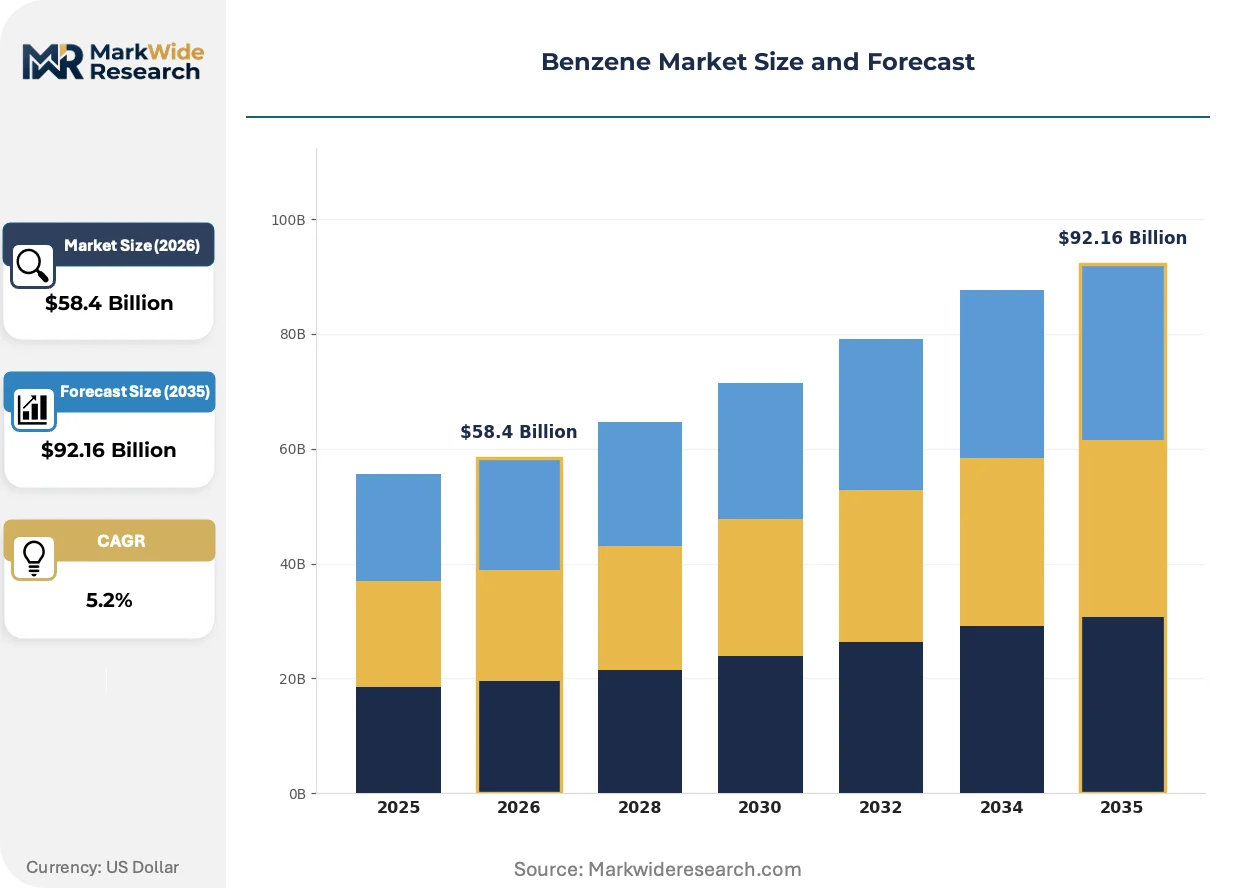
Market Dynamics
Styrene-to-polystyrene demand cycles and catalytic reforming capacity additions in Asia are compressing benzene margin windows faster than derivative pricing can adjust.
Growth Catalysts
- REACH registration tiers:ECHA's escalating data requirements for benzene derivatives are forcing consolidation among European formulators, concentrating volume with compliant integrated producers.
- Nylon 6,6 fiber expansion:Adipic acid and caprolactamide pull-through from automotive lightweighting programs is accelerating cyclohexane offtake from benzene streams.
- Shandong aromatics cluster:Private Chinese refiners are expanding continuous catalytic reforming units to capture benzene for domestic styrene and phenol chains.
Market Restraints
- Naphtha feedstock volatility:Crude-linked naphtha pricing exposes reformer economics to OPEC+ supply decisions and Asian refining margins.
- MEE VOC enforcement:China's Ministry of Ecology and Environment is tightening benzene emission limits around Zhejiang chemical parks, raising compliance capital intensity.
- Bio-based BDO substitution:Fermentation-derived 1,4-butanediol is displacing some cyclohexane-adipic acid routes in sustainable textile applications.
Strategic Opportunities
- India specialty chemicals:PLI scheme incentives for agrochemical intermediates are opening benzene derivative demand outside traditional polymer channels.
- Pyrolysis oil integration:Chemical recycling of mixed plastics into aromatics feedstock is converging with refinery co-processing technology at European crackers.
- Reagent grade arbitrage:Pharmaceutical precursor specifications are creating margin pools above industrial grade commoditization in FDA-inspected supply chains.
Industry Challenges
- Catalytic reforming catalyst expertise:Bimetallic platinum-rhenium formulation know-how is concentrating among a narrowing supplier base, extending procurement timelines.
- Cross-border REACH dossier alignment:Only representative structures for non-EU manufacturers are creating registration bottlenecks and licensing complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Benzene Market |
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $92.16 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ethylbenzene, Cumene, Cyclohexane, Chlorobenzene End Use Industry: Plastics, Synthetic Fibers, Rubber, Coatings Application: Solvents, Fuel Additives, Intermediates, Adhesives Grade: Industrial Grade, Commercial Grade, Laboratory Grade, Reagent Grade |
| Companies Covered | Chevron Phillips Chemical Company LLC, INEOS Group, BASF SE, China Petroleum & Chemical Corporation, LyondellBasell Industries, ExxonMobil Corporation, Dow Inc., SABIC, Royal Dutch Shell Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Benzene Market Strategic Shifts & Innovations
Process intensification and emissions traceability are reconfiguring how aromatics platforms capture value, with digital layer investments outpacing traditional hardware cycles.
Advanced process control systems using real-time reactor analytics are digitizing yield optimization across catalytic reforming units. European integrated producers are deploying these platforms fastest, compressing the margin advantage previously held by feedstock-cheap Middle Eastern operators. The technology is digitizing how reformer severity and benzene recovery rates respond to naphtha quality variation.
EU Green Deal carbon border adjustments are tightening embodied emissions accounting for imported benzene derivatives. Downstream formulators must now document Scope 3 aromatics sourcing or face tariff exposure, forcing supply chain re-documentation. Styrene-based packaging producers serving EU consumer goods brands are most affected, accelerating requests for mass-balance certified feedstock.
Long-term offtake contracting is displacing spot market exposure for integrated derivatives producers. Petrochemical houses are locking ethylbenzene and cumene volumes directly with polystyrene and phenol resin makers, bypassing merchant benzene trading desks. This pattern is most visible in China, where Sinopec and private refiners are securing captive demand ahead of new reforming capacity startups.
Benzene Market Segmentation
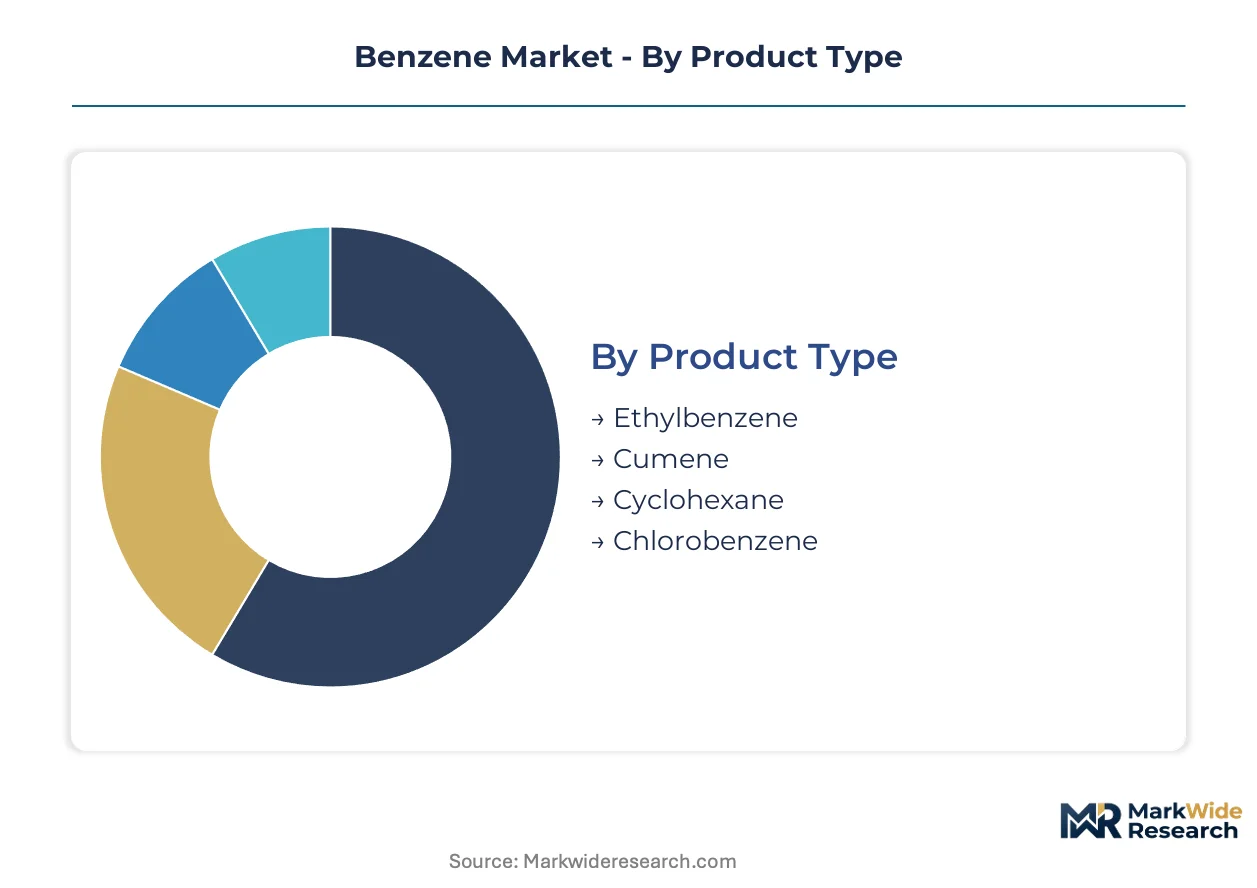
Benzene derivatives serve divergent margin pools across polymer, fiber, and specialty chemical channels. Segmentation reveals where integrated producers capture value versus where merchant traders operate on thinner spreads.
Product Type:
Mature commodity derivatives anchor volume throughput while emerging specialty streams reshape margin composition.
- Ethylbenzene:Styrene precursor manufactured through acid-catalyzed alkylation of benzene with ethylene. Demand concentrates in China where Sinopec and private refiners expand catalytic reforming to feed domestic polystyrene expansion.
- Cyclohexane:Saturated ring compound produced via catalytic hydrogenation of benzene. Automotive lightweighting programs in Germany and Japan are pulling adipic acid and caprolactamide requirements upward fastest.
- Cumene:Isopropylbenzene intermediate for phenol-acetone chains, tied to bisphenol-A and phenolic resin demand.
- Chlorobenzene:Halogenated aromatic for nitrochlorobenzene and pesticide intermediate production, serving agrochemical formulators.
Ethylbenzene handles the majority of throughput; cyclohexane is the fastest mover on share.
End Use Industry:
Cost tier stratification separates commodity polymer applications from performance-grade specialty outlets.
- Plastics:Polystyrene, ABS, and polycarbonate resin production consumes the largest benzene derivative volumes. Packaging and construction cycles in the United States and China drive styrene offtake volatility.
- Synthetic Fibers:Nylon 6,6 and polyester intermediate demand. Caprolactam and adipic acid requirements are climbing fastest as automotive textile specifications tighten.
- Rubber:Styrene-butadiene and nitrile rubber polymerization, tied to tire manufacturing.
- Coatings:Alkyd resins and epoxy curing agents, serving industrial maintenance and marine applications.
Plastics commands the dominant value share; synthetic fibers is expanding most quickly as automotive specifications evolve.
Application:
Customer type segmentation distinguishes captive integrated consumption from merchant market exposure.
- Intermediates:Chemical building blocks for downstream derivative synthesis. Phenol, aniline, and maleic anhydride producers in the US Gulf Coast and Rotterdam-Antwerp corridor represent concentrated demand.
- Solvents:Degreasing and extraction applications in pharmaceutical and electronics manufacturing. Semiconductor fabrication facilities in South Korea and Taiwan specify ultra-high purity grades.
- Fuel Additives:Octane enhancement and gasoline blending components, declining as refinery reformate yields shift toward chemical feedstocks.
- Adhesives:Hot-melt and pressure-sensitive formulations, serving packaging assembly and automotive bonding.
Intermediates absorbs the largest volume; solvents is gaining share fastest on electronics-grade purity premiums.
Grade:
Margin concentration separates specification-driven pharmaceutical and agrochemical precursors from commodity industrial streams.
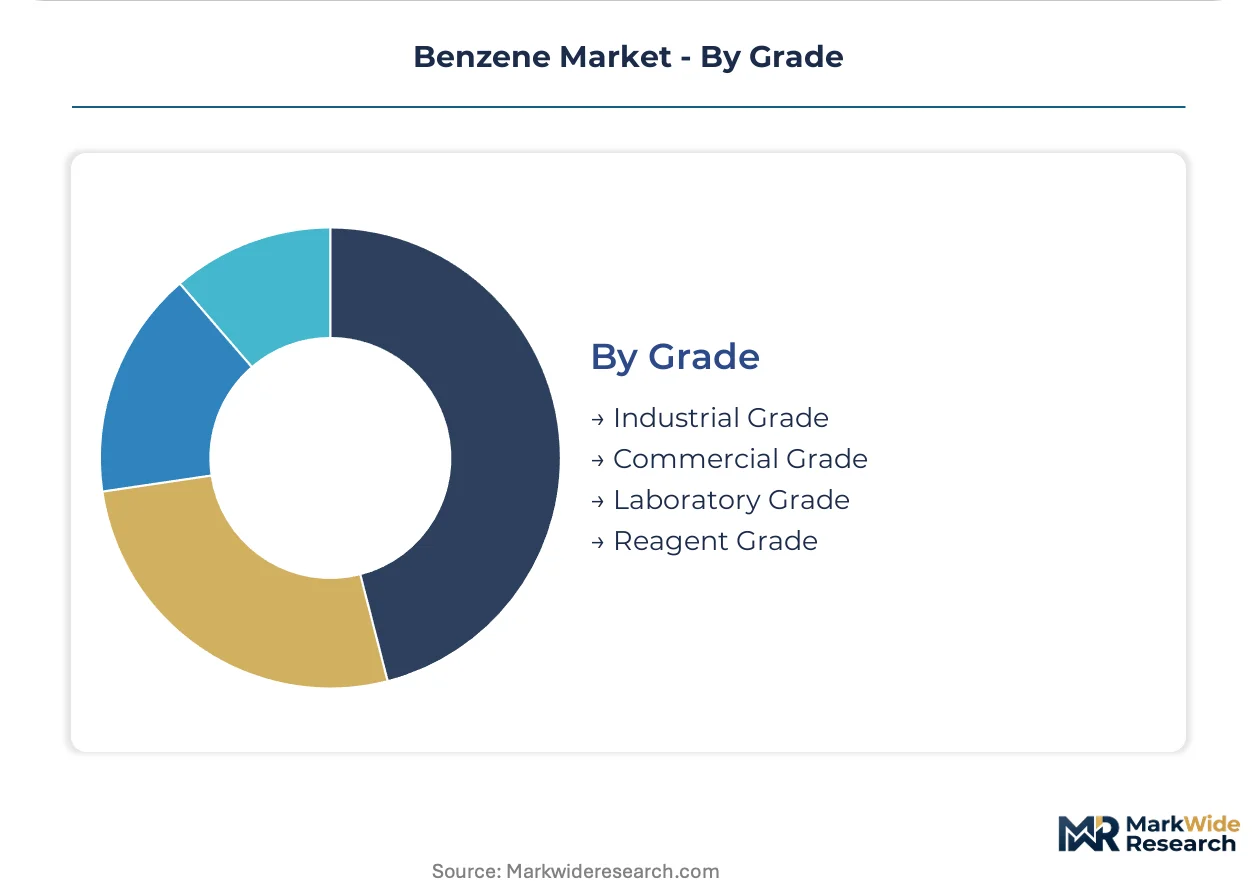
- Industrial Grade:Standard purity benzene for ethylbenzene and cumene production. Refinery and petrochemical complex output in Shandong and Zhejiang provinces supplies the dominant Chinese merchant market.
- Reagent Grade:High-purity specification for analytical and pharmaceutical precursor applications. FDA-inspected supply chains and EMA-registered manufacturers pay substantial premiums for certified batch documentation.
- Commercial Grade:Mid-tier purity for general chemical synthesis, bridging industrial and specialty specifications.
- Laboratory Grade:Research and analytical applications with variable purity tolerances.
Industrial grade moves the bulk of physical volume; reagent grade captures the steepest margin expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity for benzene derivatives varies sharply by end-use: polystyrene packaging buyers in the United States absorb cost pass-throughs fastest, while European specialty chemical formulators face regulatory compliance premiums that insulate margin structures from pure commodity volatility.
United States
Gulf Coast petrochemical complexes drive styrene and phenol derivative consumption for packaging and automotive supply chains. EPA benzene emissions standards under the Clean Air Act constrain refinery and petrochemical operations, tightening venting limits around Houston and Corpus Christi aromatics clusters. Texas and Louisiana host the densest concentration of catalytic reforming capacity, with integrated producers capturing ethylbenzene margins through backward naphtha cracking control.
China
Sinopec and private refiners expand catalytic reforming capacity to feed domestic polystyrene, ABS, and nylon intermediate expansion. MEE volatile organic compound enforcement tightens benzene emission limits around Shandong and Zhejiang chemical parks, raising scrubber and leak detection capital requirements. The Shandong aromatics cluster sees continuous catalytic reforming unit additions targeting captive styrene and phenol chain integration.
Germany
Automotive lightweighting programs pull adipic acid and caprolactamide requirements through cyclohexane offtake from benzene streams. REACH registration tiers and ECHA escalating data requirements force consolidation among European formulators, concentrating volume with compliant integrated producers. The Ludwigshafen and Cologne-Godorf chemical corridors anchor aromatics platform investments tied to nylon 6,6 fiber specifications.
Saudi Arabia
SABIC and integrated petrochemical houses leverage feedstock cost advantage tied to Saudi ethane and naphtha flexibility at Yanbu and Jubail complexes. SAMR standards alignment with international chemical safety protocols shapes export certification requirements for derivative shipments. The Eastern Province concentrates benzene extraction capacity alongside ethylene crackers serving Asian styrene and phenol resin makers.
India
PLI scheme incentives for agrochemical intermediates open benzene derivative demand outside traditional polymer channels, with chlorobenzene and nitrochlorobenzene precursors gaining traction. BIS purity specifications and CDSCO pharmaceutical precursor registration requirements tighten documentation burdens for reagent grade imports. Gujarat and Maharashtra chemical estates see specialty chemical investments targeting export-oriented agrochemical and pharmaceutical intermediate production.
Benzene Market Key Industry Players
Integrated petrochemical majors and national oil company affiliates split the market between margin-capture through feedstock control and scale-driven derivative throughput. The vendor base concentrates around three strategic archetypes: naphtha-cracking integrated houses with proprietary catalyst technology, Middle Eastern feedstock-cheap operators with ethane-naphtha flexibility, and Chinese state-private hybrid refiners expanding reforming capacity. Dominant competitive moves include long-term offtake contracting displacing spot market exposure, and pyrolysis oil co-processing technology licensing for circular aromatics claims.
Among integrated Western majors, Chevron Phillips Chemical Company LLC and ExxonMobil Corporation exemplify the naphtha-cracking archetype with Gulf Coast reforming and cracking integration. INEOS Group occupies a position representing the European integrated aromatics platform model, leveraging cross-cracker and reformer networks for ethylbenzene and cumene chain margin capture. SABIC anchors the Middle Eastern feedstock-advantaged tier, with Yanbu complex economics tied to Saudi ethane and naphtha slate flexibility. China Petroleum & Chemical Corporation represents the state-refiner hybrid model expanding catalytic reforming capacity for domestic styrene and phenol captive demand.
| Leading Market Players |
|---|
| Chevron Phillips Chemical Company LLC |
| INEOS Group |
| BASF SE |
| China Petroleum & Chemical Corporation |
| LyondellBasell Industries |
| ExxonMobil Corporation |
| Dow Inc. |
| SABIC |
| Royal Dutch Shell Plc |
| Others |
Cost & Logistics Intelligence
Catalytic reforming overcapacity in China's Shandong province is compressing spot benzene margins while forcing integrated producers toward long-term offtake contracting. This utilization dynamic rewards backward-integrated naphtha crackers with captive derivative demand while squeezing merchant traders dependent on spot market exposure.
Pricing Analysis
After-sales service bundling around technical catalyst support and yield optimization consulting drives lifetime value capture for reforming technology licensors. Contract-based long-term offtake dominates pricing structure, with price differentiation anchored in reagent grade certification tiers versus industrial grade commoditization. Pricing pressure stems from Shandong aromatics cluster capacity additions outpacing derivative absorption. Polystyrene packaging buyers in the United States show highest price sensitivity, while FDA-inspected pharmaceutical precursor buyers accept substantial premiums for certified batch documentation.
Supply Chain Analysis
Contract reforming capacity concentration among Sinopec, private Chinese refiners, and Gulf Coast integrated producers shapes supply availability. Geographic supply concentrates in China, the United States, and Saudi Arabia. Raw material dependencies rest on naphtha feedstock quality, platinum-rhenium catalyst formulations, and hydrogen supply for cyclohexane saturation. Single-source vulnerability around bimetallic catalyst expertise extends procurement timelines. Distribution runs through dedicated aromatics pipelines and coastal tanker networks serving Rotterdam-Antwerp and US Gulf Coast chemical corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bio-based BDO substitution threatens cyclohexane-adipic acid routes in sustainable textile applications, forcing incumbents to defend position through certification and integration levers.
For Market Incumbents: Harden margin structures by securing captive naphtha supply through backward integration into refinery operations or long-term feedstock agreements with Middle Eastern suppliers. Deepen reagent grade certification investments to capture pharmaceutical precursor premiums above industrial grade commoditization. Lock styrene and phenol derivative demand through direct offtake contracting before new Shandong reforming capacity startups flood merchant markets. For New Entrants and Emerging Players: Pursue specialty chemical white space in India's agrochemical intermediate channels where PLI scheme incentives reduce import dependency for chlorobenzene and nitrochlorobenzene precursors. Target reagent grade arbitrage opportunities in FDA-inspected supply chains where documentation premiums exceed industrial grade spreads. Position through pyrolysis oil co-processing partnerships with European crackers seeking circular aromatics claims. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated producers with captive reforming capacity and long-term derivative offtake contracts. Five-to-ten year viability favors naphtha-cracking integrated houses with proprietary catalyst technology over feedstock-dependent merchant traders. Watch Shandong reforming utilization rates and MEE enforcement intensity as inflection signals for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Naphtha Cracking | Captive feedstock control insulates margin from crude-linked volatility at Gulf Coast and Yanbu complexes. |
| Long-term Supply Agreement | Direct ethylbenzene and cumene contracting with polystyrene makers bypasses merchant benzene trading desks. |
| Green Manufacturing Transition | Mass-balance certified feedstock documentation satisfies EU Green Deal carbon border adjustment requirements. |
| Capacity Expansion | Continuous catalytic reforming additions in Shandong target domestic styrene and phenol captive demand. |
| Joint Venture | Pyrolysis oil co-processing partnerships with European crackers enable circular aromatics claims for packaging producers. |
Research Approach
Operator-level perspectives from catalytic reforming unit managers, downstream derivative procurement leads at polystyrene and nylon resin makers, aromatics trading desk heads, and catalyst technology licensors anchored the qualitative base. Primary interview insights combined with secondary validation from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and EPA emissions disclosure databases. Bottom-up capacity and utilization estimates triangulated against top-down consumption models across derivative demand segments.
Scenario-bracketing around regulatory enforcement intensity, feedstock slate flexibility, and derivative margin cycles shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include grade tier, end-use industry, and regional production hub concentration. CAGRs derived from capacity expansion schedules, demand elasticity by derivative channel, and substitution threat penetration curves. Industry-specific inputs encompass catalytic reforming severity optimization trends and REACH registration tier compliance costs.
Macroeconomic conditions sit as an overlay; deviation in crude oil price trajectories, OPEC+ supply decisions, and Asian refining margins would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and technology substitution rates. Quarterly review of Shandong reforming utilization rates, MEE VOC enforcement actions, and bio-based BDO capacity announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Organic Solvents Market
Solvents
Global Bio Solvents Market
Solvents
Green Solvents Market
Solvents
Isoamylene Market
Solvents
Propylene Glycol Methyl Ether Market
Solvents
Ethyl Acetate Market
Solvents
Vapor Degreasing Solvents Market
Solvents
4-Dichlorobenzyl Alcohol (DCBA) Market
Solvents
Methyl Diethanolamine Market
Solvents
Dipropylene Glycol N-Propyl Ether Market
Solvents
N-Pentyl Chloride Market
Solvents
Benzylamine Market
Solvents
Dimethyl Ether (DME) Market
Solvents
Global Furfural Solvent Market
Solvents
N-Hexane Market
Solvents
Chloromethane Market