
 Intussusception Market | 2026-2036
Intussusception Market Size, Share, and Industry Trends Forecast 2026-2036
Intussusception Market Outlook
Biologic enema formulations are restructuring treatment economics by reducing surgical conversion rates versus traditional contrast protocols. Novartis AG leverages its pediatric biologics pipeline to anchor European hospital formularies. Abbott Laboratories sustains competitive positioning through integrated diagnostic-therapeutic device ecosystems. Pfizer Inc. competes on manufacturing scale for contrast media supply chains serving North American emergency networks.
Intussusception denotes the telescoping of one intestinal segment into an adjacent section, most commonly ileocolic in infants under two years, diagnosed via ultrasound or fluoroscopic imaging with hydrostatic or pneumatic reduction as first-line intervention. Biologics and surgical devices command the deepest margin pools as hospitals prioritize non-operative resolution pathways. Emergency care and pediatric treatment applications lead volume, while diagnostic imaging equipment faces replacement-cycle pressure from refurbished system availability.
FDA, EMA, and WHO standards govern contrast agent labeling, pediatric dosing thresholds, and surgical device biocompatibility requirements, with FDA 510(k) clearance timelines directly shaping product launch sequencing for manufacturers. Stakeholders must monitor reimbursement parity between air enema and surgical reduction across national health systems to anticipate volume shifts between product categories.
Market Dynamics
FDA guidance on contrast agent safety is tightening eligibility criteria for air enema procedures, forcing hospitals to restructure pediatric emergency protocols and accelerating investment in biologic enema formulations that reduce surgical conversion risk.
Growth Catalysts
- Biologic enema formulations:These reduce surgical conversion rates versus traditional contrast protocols, creating economic incentives for hospital formularies in Germany and Japan.
- EMA pediatric biologics pathways:Accelerated review timelines for pediatric indications are compressing product launch cycles across European hospital networks.
- Ultrasound-first diagnostic protocols:Non-radiation imaging adoption in Brazilian pediatric centers is expanding addressable patient pools for non-surgical interventions.
Market Restraints
- Contrast agent supply concentration:Manufacturing of iodinated and barium-based agents concentrates among limited North American and European chemical suppliers, creating vulnerability to batch contamination recalls.
- FDA 510(k) clearance timelines:Extended review periods for pneumatic reduction devices delay commercialization by 18-24 months versus historical baselines.
- Air enema substitution risk:Hydrostatic reduction protocols using saline rather than air or contrast are gaining traction in cost-constrained health systems, compressing addressable revenue for contrast manufacturers.
Strategic Opportunities
- Brazilian public hospital expansion:SUS-funded pediatric emergency infrastructure builds in São Paulo and Minas Gerais states are creating first-mover advantages for integrated diagnostic-therapeutic device suppliers.
- AI-assisted ultrasound interpretation:Machine learning algorithms trained on pediatric abdominal imaging are enabling point-of-care diagnosis in community clinics without pediatric radiologist coverage.
- Japan's pediatric emergency network consolidation:METI-directed regional hub rationalization is concentrating procedure volumes in designated high-capacity centers, favoring suppliers with centralized service capabilities.
Industry Challenges
- Pediatric interventional radiologist scarcity:Fellowship-trained specialists capable of fluoroscopically-guided reduction are concentrated in academic medical centers, limiting protocol expansion to community hospitals.
- Device-hospital EMR integration complexity:Pneumatic reduction systems require HL7 FHIR-compliant data exchange with Epic and Cerner installations, extending implementation timelines and IT resource demands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intussusception Market |
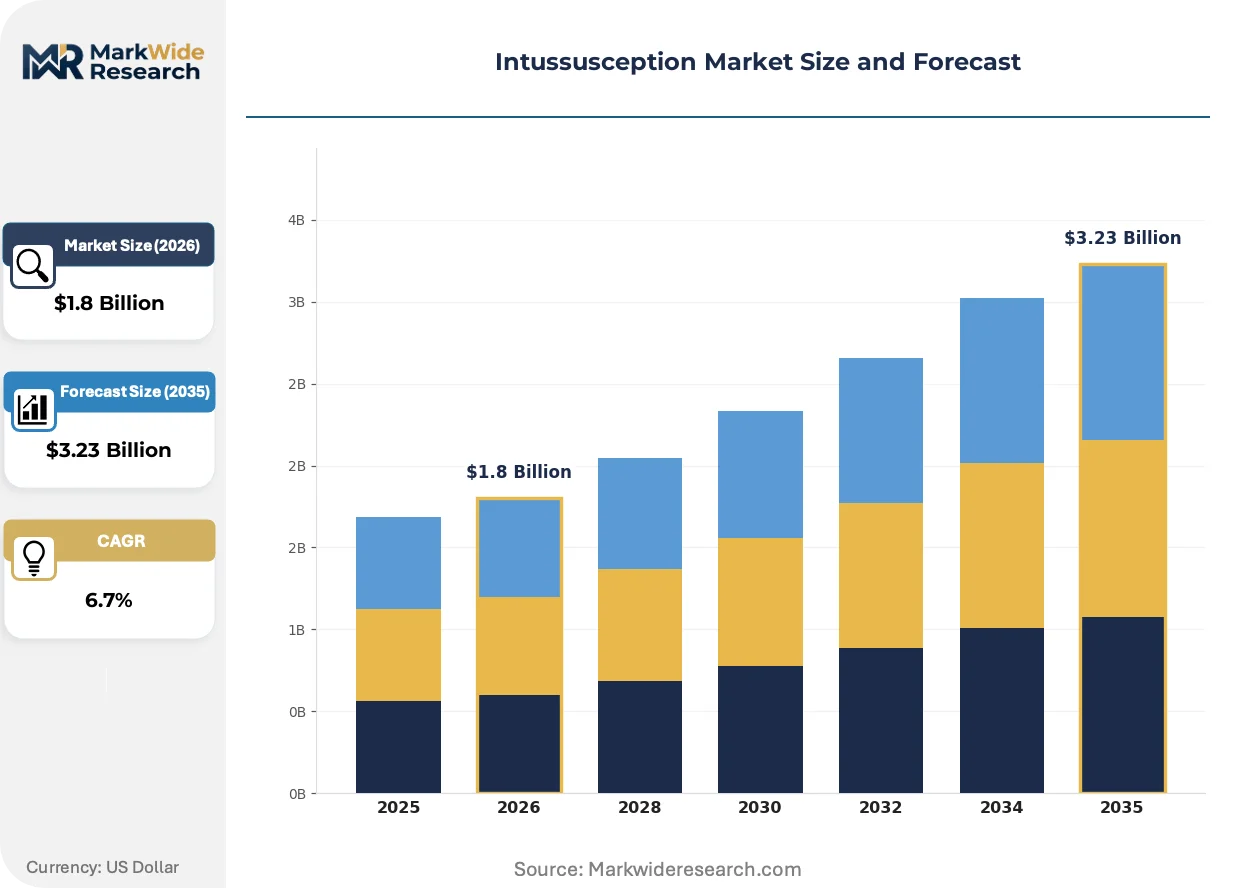
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Contrast Agents, Biologics, Surgical Devices, Diagnostic Imaging Equipment Application: Emergency Care, Pediatric Treatment, Surgical Intervention, Radiology End User: Hospitals, Outpatient Clinics, Urgent Care Centers, Diagnostic Labs Delivery Mode: Intravenous, Oral, Subcutaneous, Intra-arterial |
| Companies Covered | Novartis AG, Abbott Laboratories, Pfizer Inc., GlaxoSmithKline plc, Sanofi S.A., Merck & Co. Inc., Bristol-Myers Squibb Company, Stryker Corporation, Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intussusception Market Strategic Shifts
Automation of diagnostic workflows and biologic formulation advances are compressing time-to-treatment metrics while regulatory pressure on ionizing radiation exposure is reshaping first-line intervention hierarchies across pediatric emergency networks.
AI-powered ultrasound interpretation software is automating real-time detection of ileocolic intussusception patterns in emergency department triage settings. Pediatric emergency departments in Germany and Japan are deploying these systems at scale, reducing reliance on overnight radiologist coverage. This automation is compressing diagnostic-to-intervention intervals and expanding non-surgical eligibility windows.
REACH regulation amendments governing per- and polyfluoroalkyl substances are restricting fluoropolymer coatings in pneumatic reduction catheters sold across EU member states. Manufacturers are reformulating device surfaces with silicone-based alternatives that meet biocompatibility requirements under MDR Class IIa rules. German and French notified bodies are prioritizing review of PFAS-free submissions, creating competitive advantage for early reformulators.
Hospital purchasing consortia in the United States are consolidating contrast media procurement through multi-year sole-source agreements with integrated health networks. Group purchasing organizations are displacing individual hospital formulary committees as the primary decision node for enema agent selection. This concentration is most visible in California and Texas, where Kaiser Permanente and HCA systems respectively control substantial pediatric emergency volumes.
Intussusception Market Segmentation
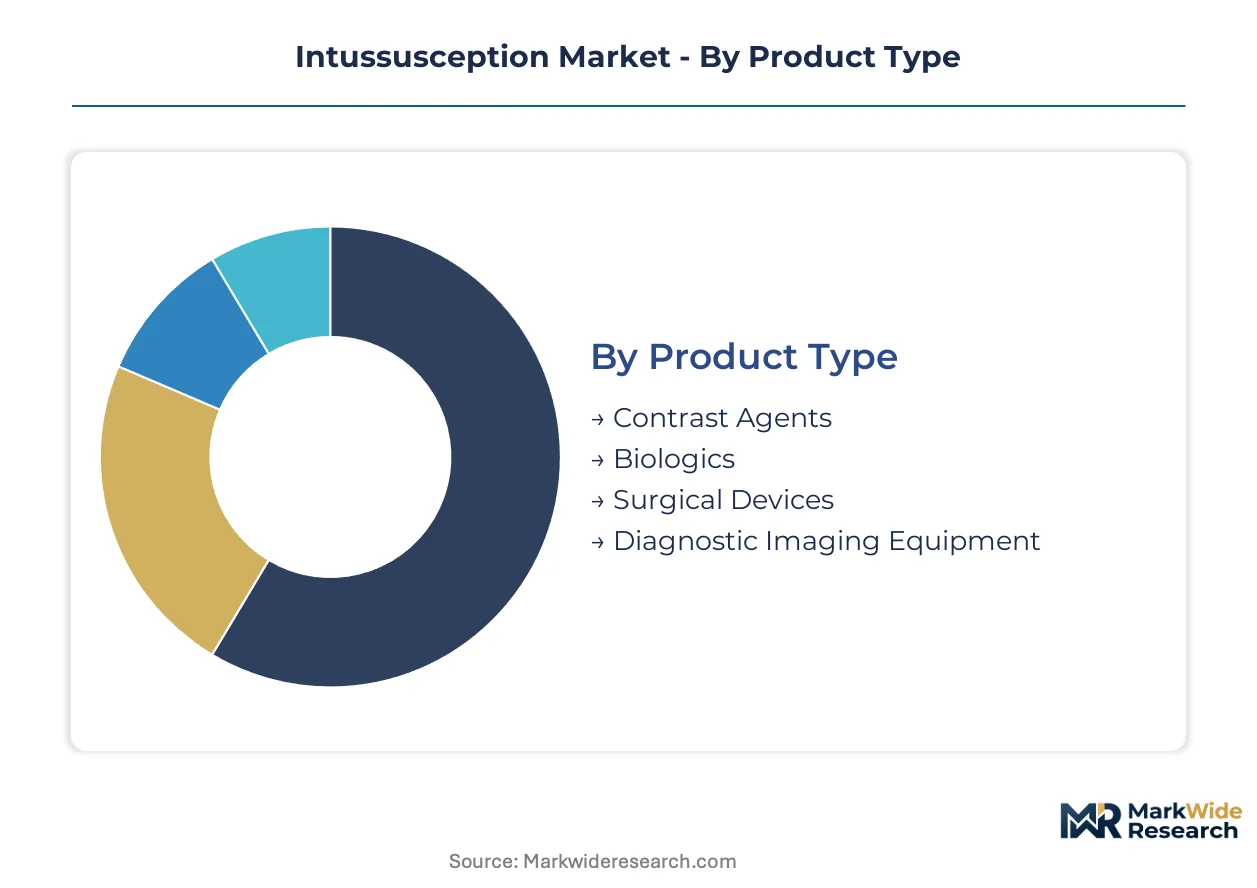
Segmentation in the intussusception market tracks how regulatory pathways, reimbursement structures, and clinical workflow requirements fragment demand across product categories. Each segment carries distinct certification burdens and margin profiles that shape supplier competitive positioning.
Product Type:
Certification requirements diverge sharply: contrast agents face FDA and EMA pharmacovigilance protocols, biologics navigate accelerated pediatric pathways, surgical devices require MDR Class IIa or 510(k) clearance, and diagnostic imaging equipment demands IEC 60601 electrical safety validation.
- Contrast Agents:Iodinated and barium-based formulations enable fluoroscopic visualization during hydrostatic or pneumatic reduction procedures. Demand concentrates in United States pediatric emergency networks where air enema protocols remain standard, though FDA safety guidance is tightening eligibility and compressing volumes. Supply batch concentration among North American chemical manufacturers creates contamination recall vulnerability.
- Biologics:Enema formulations incorporating mucosal adhesion promoters or anti-inflammatory agents reduce surgical conversion rates versus traditional contrast protocols. Hospital formularies in Germany and Japan are prioritizing these products following EMA pediatric biologics pathway approvals, creating economic incentives through avoided operative costs.
- Surgical Devices:Manual reduction instruments and laparoscopic platforms for failed non-operative cases.
- Diagnostic Imaging Equipment:Ultrasound and fluoroscopy systems for ileocolic intussusception detection.
Leading the category by volume: Contrast Agents. Growing fastest: Biologics.
Application:
Volume distribution tracks pediatric emergency network density and non-surgical protocol penetration, with procedure reimbursement parity determining whether hospitals invest in enema-capable infrastructure or default to operative management.
- Emergency Care:First-line non-operative reduction in pediatric emergency departments using pneumatic or hydrostatic enema protocols. Brazilian public hospital expansion in São Paulo and Minas Gerais states is building SUS-funded infrastructure, expanding addressable patient pools for intervention-capable centers.
- Pediatric Treatment:Comprehensive management including post-reduction observation and recurrence monitoring. Japan's METI-directed regional hub rationalization is concentrating volumes in designated high-capacity centers, favoring suppliers with centralized service and training capabilities.
- Surgical Intervention:Operative reduction for perforation, peritonitis, or failed enema cases.
- Radiology:Imaging interpretation and interventional guidance services.
Highest procedure volume: Emergency Care. Steepest expansion trajectory: Pediatric Treatment.
End User:
Purchasing authority is shifting from individual hospital formulary committees to consolidated procurement structures, with group purchasing organizations and integrated health networks controlling pediatric emergency volumes in California and Texas.
- Hospitals:Academic medical centers and community hospitals with pediatric emergency departments and interventional radiology coverage. Pediatric interventional radiologist scarcity limits protocol expansion beyond major metropolitan clusters in the United States and European capitals.
- Outpatient Clinics:Community-based pediatric practices with ultrasound-first diagnostic capabilities. AI-assisted ultrasound interpretation is enabling point-of-care diagnosis without overnight radiologist coverage, expanding non-surgical eligibility windows.
- Urgent Care Centers:Limited-service facilities for initial triage and stabilization.
- Diagnostic Labs:Independent imaging centers with pediatric abdominal ultrasound expertise.
Dominant procurement node: Hospitals. Gaining share fastest: Outpatient Clinics.
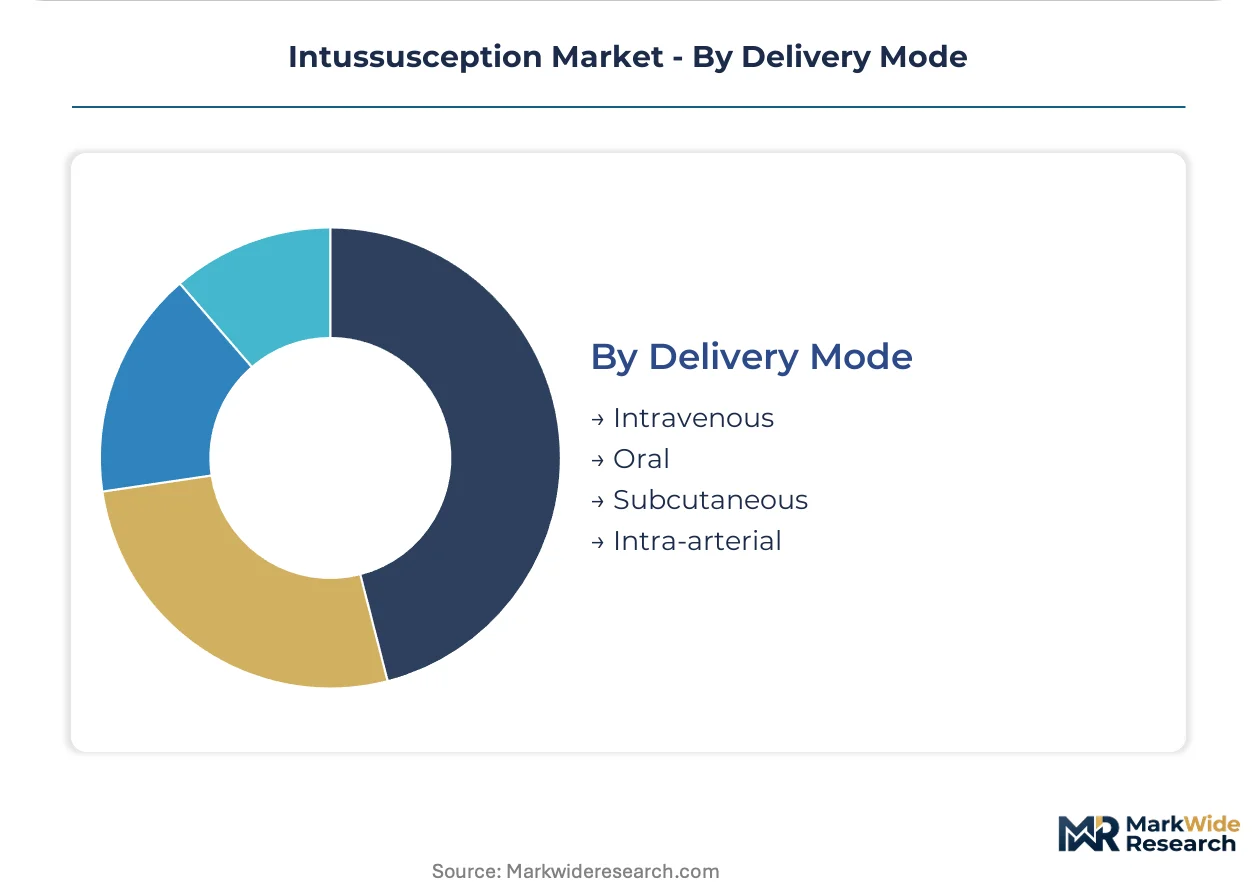
Delivery Mode:
Route selection follows intervention type and agent pharmacokinetics, with regulatory labeling specifying pediatric dosing thresholds and contraindication profiles that vary by national health authority.
- Intravenous:Sedation and contrast administration for fluoroscopic procedures. United States pediatric emergency protocols favor IV access for monitored anesthesia care during pneumatic reduction, driving device ecosystem integration with EMR systems.
- Oral:Pre-procedural bowel preparation and contrast ingestion protocols. Cost-constrained health systems in emerging markets are exploring oral contrast alternatives to reduce procedure costs, though efficacy data remains limited.
- Subcutaneous:Adjunctive medication delivery in perioperative settings.
- Intra-arterial:Specialized interventional radiology access for complex cases.
Standard of care by volume: Intravenous. Expanding most quickly: Oral.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pediatric emergency networks concentrate procedure volumes in designated high-capacity centers across Germany, Japan, Brazil, and the United States. National health system reimbursement structures and regulatory labeling requirements reshape intervention hierarchies in each market.
United States
Pediatric emergency departments in California and Texas are expanding non-surgical intervention protocols through Kaiser Permanente and HCA system networks. FDA guidance on contrast agent safety tightens eligibility criteria for air enema procedures, forcing hospitals to restructure pediatric emergency workflows. Academic medical centers in Boston and New York Metro concentrate fellowship-trained interventional radiologists capable of fluoroscopically-guided reduction.
Germany
Hospital formularies prioritize biologic enema formulations following EMA pediatric biologics pathway approvals that accelerate review timelines. REACH regulation amendments restrict fluoropolymer coatings in pneumatic reduction catheters, prompting manufacturers to reformulate with silicone-based alternatives. Medical device clusters in Bavaria and Baden-Württemberg host notified bodies prioritizing PFAS-free MDR Class IIa submissions.
Japan
METI-directed regional hub rationalization concentrates intussusception procedure volumes in designated high-capacity pediatric emergency centers across Kanto and Kansai regions. PMDA accelerated pathways for pediatric indications compress product launch cycles for biologic enema formulations. Tokyo and Osaka academic medical centers anchor centralized service capabilities for integrated diagnostic-therapeutic device suppliers.
Brazil
SUS-funded pediatric emergency infrastructure builds in São Paulo and Minas Gerais states expand addressable patient pools for non-surgical intervention-capable centers. ANVISA governs contrast agent labeling and pediatric dosing thresholds for hydrostatic reduction protocols. Public hospital procurement in Southeast region concentrates demand for cost-effective enema formulations amid budget-constrained health system expansion.
Intussusception Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical conglomerates commanding biologics and contrast agent categories while device fabricators compete on EMR integration capabilities. The vendor base organizes into three tiers: diversified multinationals with pediatric portfolios, regional hospital supply specialists, and niche diagnostic-therapeutic integrators. Consolidation pressures favor players with centralized service networks capable of training pediatric interventional radiologists. Dominant competitive moves include strategic partnerships with group purchasing organizations and backward integration into contrast chemical supply.
Among Swiss-based pharmaceutical conglomerates, Novartis AG exemplifies the diversified multinational archetype leveraging pediatric biologics pipelines. Abbott Laboratories and Pfizer Inc. represent contrasting strategic positions within North American supply chains—Abbott anchoring integrated diagnostic-therapeutic device ecosystems, Pfizer occupying scale-driven manufacturing positions for contrast media serving emergency networks.
| Leading Market Players |
|---|
| Novartis AG |
| Abbott Laboratories |
| Pfizer Inc. |
| GlaxoSmithKline plc |
| Sanofi S.A. |
| Merck & Co. Inc. |
| Bristol-Myers Squibb Company |
| Stryker Corporation |
| Bayer AG |
| Others |
Value Chain & Pricing Dynamics
REACH regulation amendments governing per- and polyfluoroalkyl substances gate qualified supply for pneumatic reduction catheters in Germany and France, with silicone-based alternatives commanding premium-tier pricing access for manufacturers who secure prioritized MDR Class IIa review from notified bodies in Bavaria and Baden-Württemberg.
Pricing Analysis
Volume concentrates in contrast agents while margins pool deepest in biologic enema formulations certified through EMA pediatric pathways. Price differentiation hinges on FDA 510(k) clearance tier and biocompatibility certification grade under MDR rules. Cost compression in standard contrast media runs through group purchasing organization consolidation across California and Texas health systems. Public hospital procurement in Brazil exhibits highest price sensitivity; Japanese academic medical centers anchored to METI-directed hubs show lowest.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and the United States coordinate hub-and-spoke patterns for pneumatic reduction devices and contrast media. Manufacturing of iodinated and barium-based agents concentrates in North American and European chemical facilities. Raw material dependencies span fluoropolymers, silicone coatings, and pediatric-grade contrast compounds. Single-source vulnerability permeates batch production of enema formulations. Distribution runs through hospital purchasing consortia and group purchasing organizations displacing individual formulary committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where backward control over contrast chemical supply chains and biologic formulation R&D represents the decisive upstream lever separating margin leaders from price-takers.
For Market Incumbents: Cement formulary anchoring through exclusive multi-year supply agreements with Kaiser Permanente and HCA network pediatric emergency departments. Deepen backward integration into PFAS-free silicone coating production to outpace REACH compliance timelines and capture prioritized notified body review in Germany.
For New Entrants and Emerging Players: Launch via AI-assisted ultrasound interpretation software partnerships with Brazilian SUS-funded outpatient clinics in São Paulo and Minas Gerais states. Target community-based pediatric practices lacking overnight radiologist coverage as the most penetrable white-space segment, deploying point-of-care diagnostic capabilities that expand non-surgical eligibility windows.
For Investors and Strategic Acquirers: FDA 510(k) clearance timeline extensions for pneumatic reduction devices are the leading indicator that device-hospital EMR integration capabilities will concentrate acquisition value in integrated diagnostic-therapeutic platform players. Long-term viability favors suppliers with centralized training networks for pediatric interventional radiologists and HL7 FHIR-compliant data exchange architectures.
| Strategic Initiative | Industry Significance |
|---|---|
| Biologic Enema Formulation Development | EMA pediatric pathway approvals compress launch cycles for German and Japanese hospital formularies. |
| PFAS-Free Device Surface Reformulation | Silicone-based alternatives meet MDR Class IIa biocompatibility requirements ahead of REACH deadlines. |
| AI-Assisted Ultrasound Platform Integration | Machine learning algorithms enable point-of-care diagnosis in Brazilian community clinics without radiologist coverage. |
| Hospital System Partnership | Exclusive agreements with Kaiser Permanente and HCA networks lock in California and Texas pediatric emergency volumes. |
| Reimbursement Strategy | Parity between air enema and surgical reduction across national health systems determines volume allocation between product categories. |
Study Parameters
FDA filings, EMA submission databases, and hospital procurement records formed the secondary backbone, cross-referenced with primary interviews involving pediatric emergency department directors, interventional radiologists, GPO contracts managers, and biomedical engineers. Bottom-up procedure volume estimates across German, Japanese, Brazilian, and United States pediatric networks triangulated against top-down market sizing from regulatory approval data and contrast agent manufacturing disclosures.
Historical trendline analysis of pediatric emergency protocol adoption and non-surgical intervention success rates informed projection frameworks across the analysis window. Segmentation dimensions encompassed product type, application setting, end-user purchasing authority, and delivery mode. CAGRs derived from procedure volume trajectories, reimbursement parity shifts, and biologic formulation penetration curves in designated high-capacity centers.
Regulatory approval delays, batch contamination recalls in concentrated chemical supply, and pediatric interventional radiologist training pipeline constraints are the dominant revision risks. Forecasts reflect documented assumptions regarding EMA pathway acceleration and METI-directed hub consolidation timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Dyschromia Therapeutics Market
Specialty Medicine
Ovarian Cysts Market
Specialty Medicine
Checkpoint Inhibitor Refractory Cancer Market
Specialty Medicine
Sports Medicine Market
Specialty Medicine
Dry Eye Disease Market
Specialty Medicine
United States Sports Medicine Market
Specialty Medicine
Neuroendocrine Carcinoma Treatment Market
Specialty Medicine
Mantle Cell Lymphoma Market
Specialty Medicine
Global Specialty Injectable Generics Market
Specialty Medicine
Eosinophilic Granulomatosis Market
Specialty Medicine
Endometrial Cancer Treatment Market
Specialty Medicine
Eisenmenger Complex Management Market
Specialty Medicine
Pseudobulbar Treatment Market
Specialty Medicine
Pulmonary Arterial Hypertension (PAH) Market
Specialty Medicine
North America Cancer Therapy Market
Specialty Medicine
South America Kidney Cancer Therapeutics and Diagnostics Market