
 Pharyngitis Treatment Market | 2026-2036
Pharyngitis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Pharyngitis Treatment Market Analytics
Amoxicillin-clavulanate is consolidating its position as the first-line oral antibiotic for bacterial pharyngitis, displacing legacy macrolide alternatives on cost and resistance-profile grounds. Pfizer Inc. leverages its manufacturing scale to anchor supply contracts with major hospital systems across North America. GSK plc competes through sustained R&D investment in pediatric formulation technologies. Novartis AG differentiates via its specialized portfolio in immunomodulatory throat preparations for recurrent cases.
Pharyngitis treatment encompasses pharmacological and non-pharmacological interventions targeting acute or persistent inflammation of the pharynx, typically involving oral antibiotic courses of five to ten days for confirmed streptococcal infections, topical analgesic sprays, and corticosteroid adjuncts for severe edema. The primary commercial purpose centers on reducing symptom duration, preventing rheumatic fever sequelae, and minimizing inappropriate antibiotic exposure. Antibiotics occupy the largest value share within product type categories, while analgesics represent the fastest-expanding segment driven by over-the-counter self-medication trends. Home care delivery is gaining structural importance as post-pandemic patients favor remote management of uncomplicated cases.
The FDA enforces antibiotic stewardship guidelines that restrict broad-spectrum prescribing, directly shaping physician selection of narrow-spectrum agents for confirmed Group A streptococcal cases. The EPA regulates pharmaceutical manufacturing discharge standards, elevating compliance costs for active ingredient producers and favoring larger manufacturers with integrated environmental controls. Clinicians and procurement officers must monitor evolving resistance surveillance data from the CDC to align formulary decisions with regional pathogen patterns.
Market Dynamics
Antibiotic stewardship mandates from the FDA are compressing prescribing volumes while simultaneously elevating the value of narrow-spectrum agents, fundamentally restructuring how manufacturers prioritize their development pipelines and commercial strategies.
Growth Catalysts
- Telehealth Diagnostic Expansion:Direct-to-consumer platforms in the United States now capture a growing share of initial pharyngitis assessments, channeling patients toward standardized treatment protocols and reducing unnecessary emergency department utilization.
- REACH Compliance Differentiation:European pharmaceutical manufacturers investing in green chemistry processes for active ingredient synthesis gain preferential procurement status from hospital systems with embedded sustainability criteria.
- Point-of-Care Testing:Rapid molecular diagnostics deployed in retail pharmacy chains accelerate pathogen confirmation, reducing empiric broad-spectrum prescribing and aligning treatment with resistance surveillance data.
Market Restraints
- Raw Material Concentration:Penicillin G and amoxicillin active pharmaceutical ingredient production concentrates in China and India, exposing formulators to geopolitical supply disruptions and freight cost volatility.
- Regulatory Friction:The FDA's antibiotic stewardship guidelines impose documentation burdens on clinicians prescribing broad-spectrum agents, lengthening decision cycles and compressing volumes for legacy macrolide portfolios.
- Substitution Pressure:Over-the-counter analgesics and topical anesthetics increasingly satisfy patient symptom management expectations without prescription requirements, limiting antibiotic course initiation rates.
Strategic Opportunities
- Pediatric Formulation Gaps:Palatable liquid antibiotic presentations with extended stability profiles remain underdeveloped for children under five in Germany and France, where parental compliance concerns drive brand switching.
- Integrated Care Contracts:Accountable care organizations in the United States are piloting bundled payment models for upper respiratory infections, creating procurement pathways for manufacturers offering diagnostic-plus-treatment packages.
- AI-Assisted Triage:Machine learning symptom checkers converging with pharmacy CRM systems enable risk-stratified patient routing, identifying high-probability bacterial cases for expedited prescription fulfillment.
Industry Challenges
- Microbiology Talent Scarcity:Clinical laboratories face persistent shortages of trained phlebotomists and microbiologists capable of performing rapid streptococcal antigen testing at volume, delaying result turnaround in peak season.
- Legacy EHR Integration:Telehealth platforms and retail pharmacy diagnostic systems struggle to synchronize patient records with hospital-based electronic health records, fragmenting treatment histories and complicating allergy screening.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharyngitis Treatment Market |
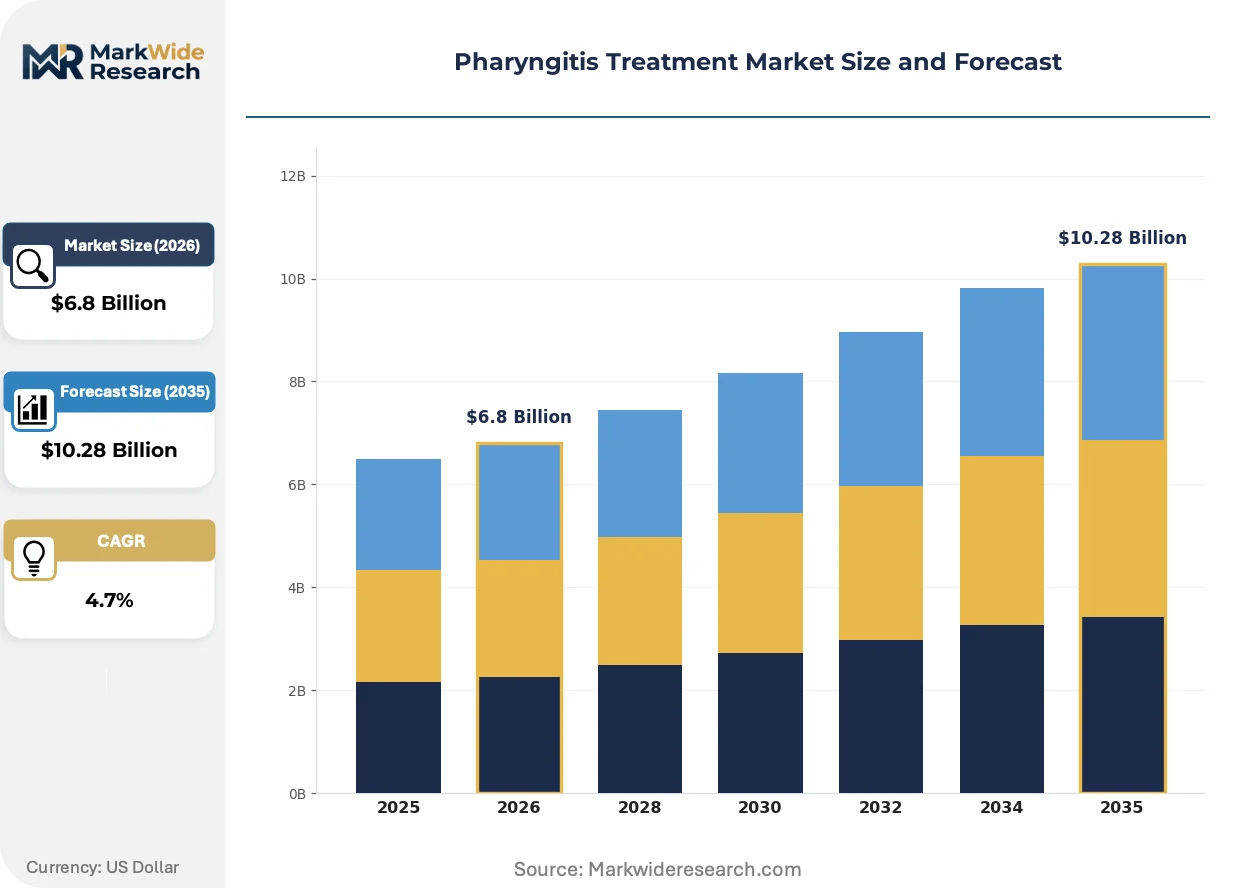
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Analgesics, Antiseptics, Corticosteroids End User: Clinics, Hospitals, Home Care, Pharmacies Delivery Mode: Oral, Topical, Intravenous, Sublingual Treatment Stage: Acute, Chronic, Recurrent, Palliative |
| Companies Covered | Pfizer Inc., GSK plc, Novartis AG, Teva Pharmaceutical Industries Ltd, Bausch Health Companies Inc., AbbVie Inc., Amneal Pharmaceuticals LLC., Sanofi, Viatris Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharyngitis Treatment Market Evolving Landscape
Digital diagnostic integration and formulation science advances are compressing the interval between symptom onset and targeted therapy, while regulatory pressure on environmental discharge reshapes manufacturing investment priorities.
Narrow-spectrum penicillin derivatives with optimized pharmacokinetic profiles are absorbing market share from legacy macrolide alternatives as hospital formularies prioritize resistance-sparing agents. Pediatric specialists and urgent care networks in the United States are adopting these agents at accelerating rates. This technology shift is absorbing development resources previously allocated to broad-spectrum combination therapies, consolidating R&D concentration among manufacturers with established beta-lactam platforms.
The EPA's pharmaceutical manufacturing discharge standards are elevating capital requirements for active ingredient producers, particularly for facilities operating near watersheds with sensitive ecological designations. Compliance investments now exceed prior environmental control outlays by substantial margins. Manufacturers with integrated wastewater treatment infrastructure in the United States are capturing contract renewals from systems with deferred upgrade timelines.
Self-directed care patterns are compressing the traditional physician-patient consultation model for uncomplicated pharyngitis presentations. Retail pharmacy chains and telehealth platforms are displacing primary care offices as the initial touchpoint for symptom assessment across urban and suburban United States markets. This channel rotation is most pronounced among insured patients under forty seeking same-day resolution without appointment scheduling friction.
Pharyngitis Treatment Market Segmentation
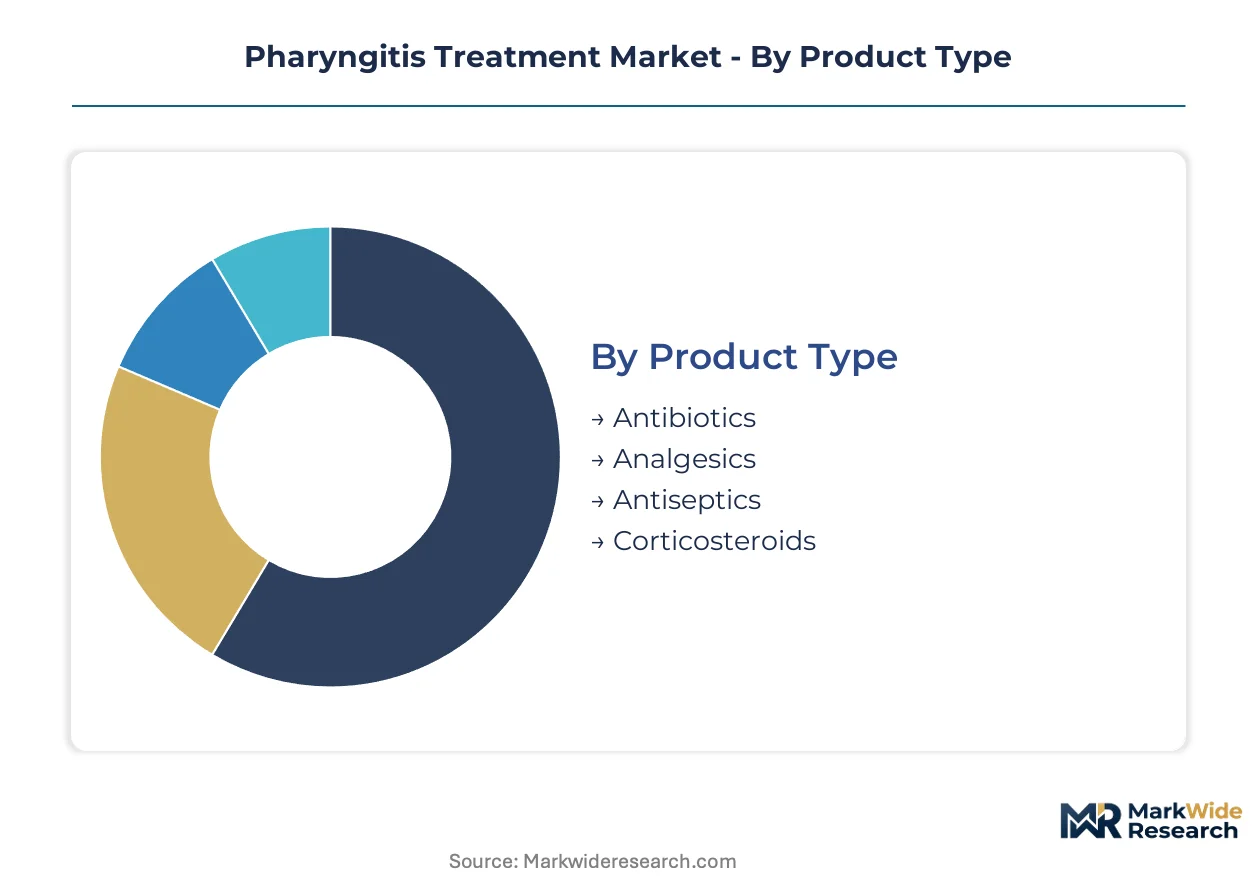
Pharyngitis treatment segmentation reveals how regulatory pathways, reimbursement codes, and patient acuity stratify commercial opportunity across formulation types and care settings. Manufacturers must align development priorities with the specific approval burdens and procurement mechanisms governing each segment.
Product Type:
Antibiotics carry the heaviest FDA premarket documentation requirements under antimicrobial stewardship protocols, while analgesics navigate OTC monograph pathways with lighter regulatory lift. Corticosteroids and antiseptics occupy intermediate tiers with distinct efficacy substantiation standards.
- Antibiotics:Beta-lactam derivatives dominate hospital formularies for confirmed streptococcal infections, requiring resistance surveillance data submission to FDA. Demand concentrates in United States hospital systems where narrow-spectrum prescribing mandates elevate amoxicillin-clavulanate procurement above legacy macrolides.
- Analgesics:Topical benzocaine and systemic NSAID formulations serve symptom management without prescription requirements. United States retail pharmacy chains capture volume through private-label ibuprofen and acetaminophen SKUs as patients bypass clinical visits for uncomplicated cases.
- Antiseptics:Povidone-iodine and chlorhexidine preparations target viral pharyngitis symptom relief with shorter regulatory timelines than antibiotic NDA submissions.
- Corticosteroids:Dexamethasone adjuncts for severe edema require prescription oversight and carry boxed warnings limiting pediatric application scope.
Leading the category by volume: Antibiotics. Growing fastest: Analgesics.
End User:
Procurement authority and reimbursement rates diverge sharply across settings, with hospitals negotiating formulary placement through GPO contracts while home care relies on direct-to-consumer price elasticity.
- Clinics:Urgent care networks and primary care offices initiate the majority of antibiotic prescriptions following rapid streptococcal antigen testing. United States clinic chains standardize on narrow-spectrum protocols to satisfy HEDIS quality metrics.
- Hospitals:Inpatient admissions for complicated pharyngitis represent a smaller volume but command premium pricing for intravenous antibiotic administration. Pharmacy and therapeutics committees enforce strict stewardship compliance.
- Home Care:Post-discharge oral antibiotic completion and symptomatic management dominate this channel, with telehealth platforms now directing prescription fulfillment to mail-order pharmacies.
- Pharmacies:Retail chains in the United States deploy point-of-care diagnostics to capture diagnosis-to-treatment workflow, converting walk-in traffic into prescription and OTC product sales.
Dominant by prescription volume: Clinics. Expanding most quickly: Pharmacies.
Delivery Mode:
Manufacturing complexity and bioequivalence requirements scale with systemic exposure, compressing margins for oral generics while protecting novel topical formulations from rapid commoditization.
- Oral:Tablets and suspensions account for the majority of antibiotic courses, with pediatric liquid formulations commanding formulation stability investments that deter generic entry.
- Topical:Sprays and lozenges deliver localized anesthetic and antiseptic action with minimal systemic absorption, satisfying patient preference for immediate symptom relief in Germany and France.
- Intravenous:Reserved for hospitalized patients with severe complications or penicillin allergy requiring alternative antibiotic classes.
- Sublingual:Emerging delivery for rapid corticosteroid absorption in emergency department settings, limited by taste masking challenges and higher unit costs.
Highest shipment volume: Oral. Steepest expansion trajectory: Topical.
Treatment Stage:
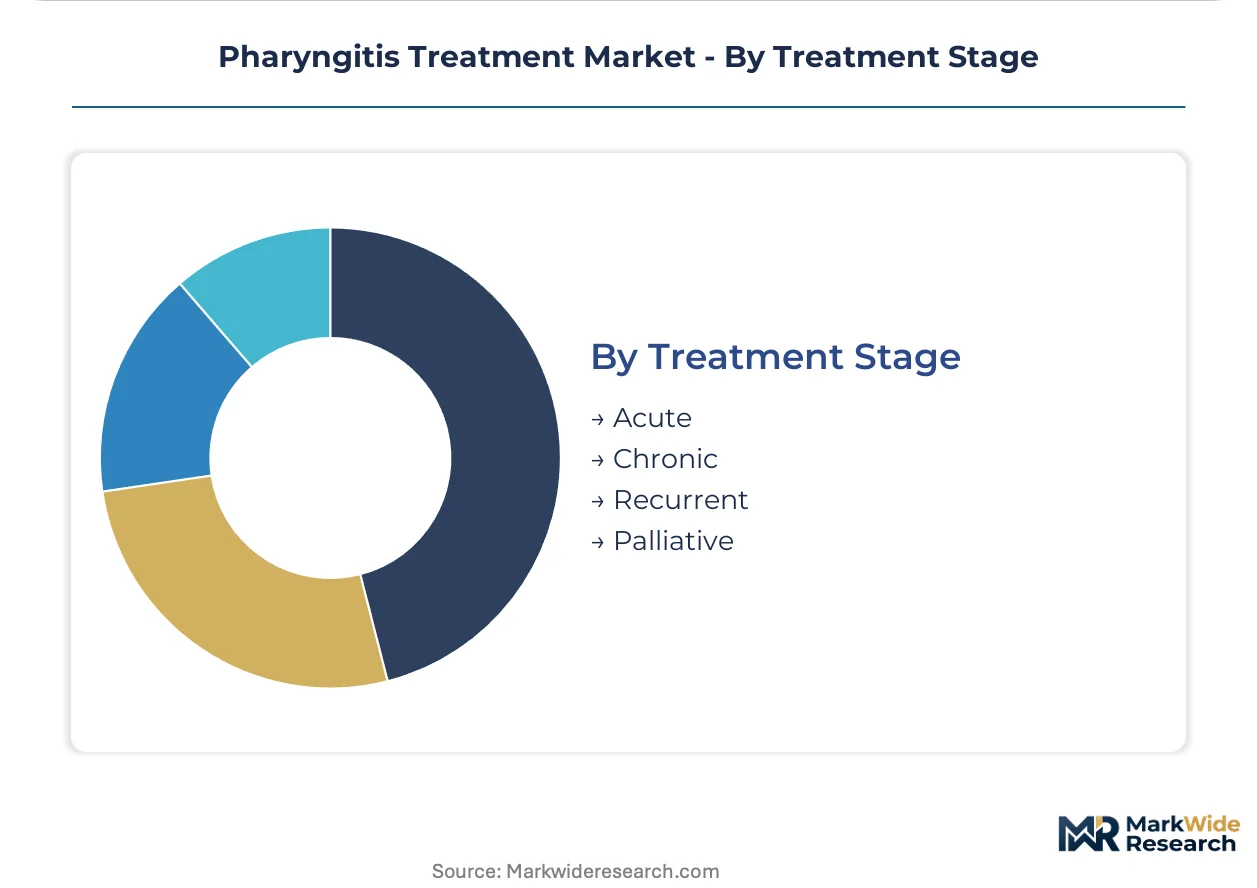
Clinical evidence requirements intensify with disease chronicity, as recurrent and palliative indications demand longitudinal safety data that acute-phase therapies circumvent.
- Acute:Standard five-to-ten day antibiotic courses for confirmed bacterial infection, with diagnosis hinging on rapid antigen or molecular testing availability.
- Chronic:Persistent pharyngeal inflammation exceeding three months drives specialist referral and immunomodulatory investigation in United States otolaryngology practices.
- Recurrent:Multiple annual episodes trigger tonsillectomy evaluation and prophylactic antibiotic strategies with distinct reimbursement coding.
- Palliative:Symptom-focused care for oncology patients with treatment-related mucositis, requiring formulation compatibility with immunocompromised status protocols.
Greatest prescription frequency: Acute. Gaining share fastest: Recurrent.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States households generate the highest per-capita demand for pharyngitis therapeutics, with direct-to-consumer telehealth platforms capturing substantial diagnostic volume and channeling patients toward retail pharmacy fulfillment.
United States
Telehealth platforms and retail pharmacy chains now handle the majority of uncomplicated case assessments, displacing traditional primary care entry points. FDA antibiotic stewardship protocols enforce narrow-spectrum prescribing documentation, compressing legacy macrolide volumes. The Boston-Cambridge corridor anchors specialized pediatric formulation development, with several manufacturers locating stability-testing facilities near major academic medical centers.
Germany
Parental compliance concerns for liquid antibiotic presentations drive brand-switching behavior in pediatric populations under five years. REACH compliance investments in green chemistry synthesis confer preferential procurement status from hospital systems with embedded sustainability criteria. The Rhine-Ruhr metropolitan region concentrates pharmaceutical manufacturing infrastructure, with several active ingredient producers upgrading wastewater treatment systems to meet tightened EPA-equivalent discharge standards.
France
Topical analgesic sprays and lozenges satisfy patient preference for immediate symptom relief without prescription requirements. ANSM pharmacovigilance monitoring shapes formulary placement for corticosteroid adjuncts in severe edema cases. The Île-de-France region hosts headquarters operations for major immunomodulatory throat preparation developers targeting recurrent pharyngitis indications.
India
Domestic penicillin G and amoxicillin active pharmaceutical ingredient production supplies global formulators, though geopolitical exposure and freight volatility create intermittent supply pressure. CDSCO manufacturing facility inspections enforce quality standards for export-oriented production. The Hyderabad-Visakhapatnam corridor anchors bulk antibiotic synthesis capacity, with several integrated manufacturers expanding environmental control investments to maintain contract renewals.
United Kingdom
Urgent care networks standardize narrow-spectrum protocols to satisfy NHS quality metrics and antimicrobial resistance reduction targets. MHRA post-Brexit regulatory autonomy has streamlined pediatric formulation approval timelines for established agents. The Oxford-Cambridge arc concentrates rapid molecular diagnostic development, with several point-of-care testing manufacturers locating R&D facilities near clinical trial networks.
Pharyngitis Treatment Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers scale narrow-spectrum beta-lactam production to capture stewardship-driven formulary shifts. The vendor base stratifies across three tiers: multinational pharmaceutical conglomerates with integrated manufacturing networks, mid-cap generic specialists with regional distribution strength, and emerging biotechnology firms developing immunomodulatory adjuncts. Primary competitive vectors include M&A activity consolidating pediatric formulation capabilities and strategic partnerships binding diagnostic platforms to pharmaceutical fulfillment workflows.
Among the established multinational tier, Pfizer Inc. and GSK plc occupy positions reflecting manufacturing scale advantages and sustained R&D commitments respectively. Novartis AG exemplifies the specialized immunomodulatory portfolio approach for recurrent case management. These three entities represent divergent strategic archetypes—scale-driven supply contracting, formulation technology investment, and niche therapeutic specialization—each capturing distinct procurement pathways across hospital, clinic, and retail pharmacy channels.
| Leading Market Players |
|---|
| Pfizer Inc. |
| GSK plc |
| Novartis AG |
| Teva Pharmaceutical Industries Ltd |
| Bausch Health Companies Inc. |
| AbbVie Inc. |
| Amneal Pharmaceuticals LLC. |
| Sanofi |
| Viatris Inc. |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up generic specialists have consolidated penicillin G and amoxicillin active pharmaceutical ingredient sourcing networks, tightening supply discipline and compressing margin capture for downstream formulators dependent on spot market exposure. This ownership concentration in India and China simultaneously elevates pricing leverage for integrated producers while exposing non-vertically integrated competitors to freight cost volatility and geopolitical disruption premiums.
Pricing Analysis
High-volume oral antibiotic courses trade on thin margins against commoditized generic benchmarks, while narrow-spectrum beta-lactam formulations with pediatric stability profiles command premium positioning through FDA stewardship-aligned procurement. Price differentiation rests on bioequivalence certification tier and volume scale commitments to hospital GPO contracts. Pricing pressure stems from REACH compliance investments elevating manufacturing overhead for European producers. Retail pharmacy chains exhibit acute price sensitivity, whereas hospital systems prioritize formulary compliance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with penicillin G fermentation capacity concentrated in China, India, and select facilities in the United States, exposing formulators to regulatory inspection delays and export license friction. Raw material dependencies center on corn steep liquor for fermentation media, specialized enzyme catalysts, and pharmaceutical-grade packaging resins. Supply chain risk centers on single-source vulnerability for streptococcal rapid antigen test components tethered to Taiwanese semiconductor fabrication. Distribution runs through three-tier wholesale networks serving retail pharmacy chains, with direct-to-hospital contracting gaining share for narrow-spectrum antibiotic categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pharyngitis treatment sector is executing a technology transition from empiric broad-spectrum prescribing to molecular diagnostic-directed narrow-spectrum therapy, with rapid point-of-care platforms displacing legacy culture-based confirmation methods.
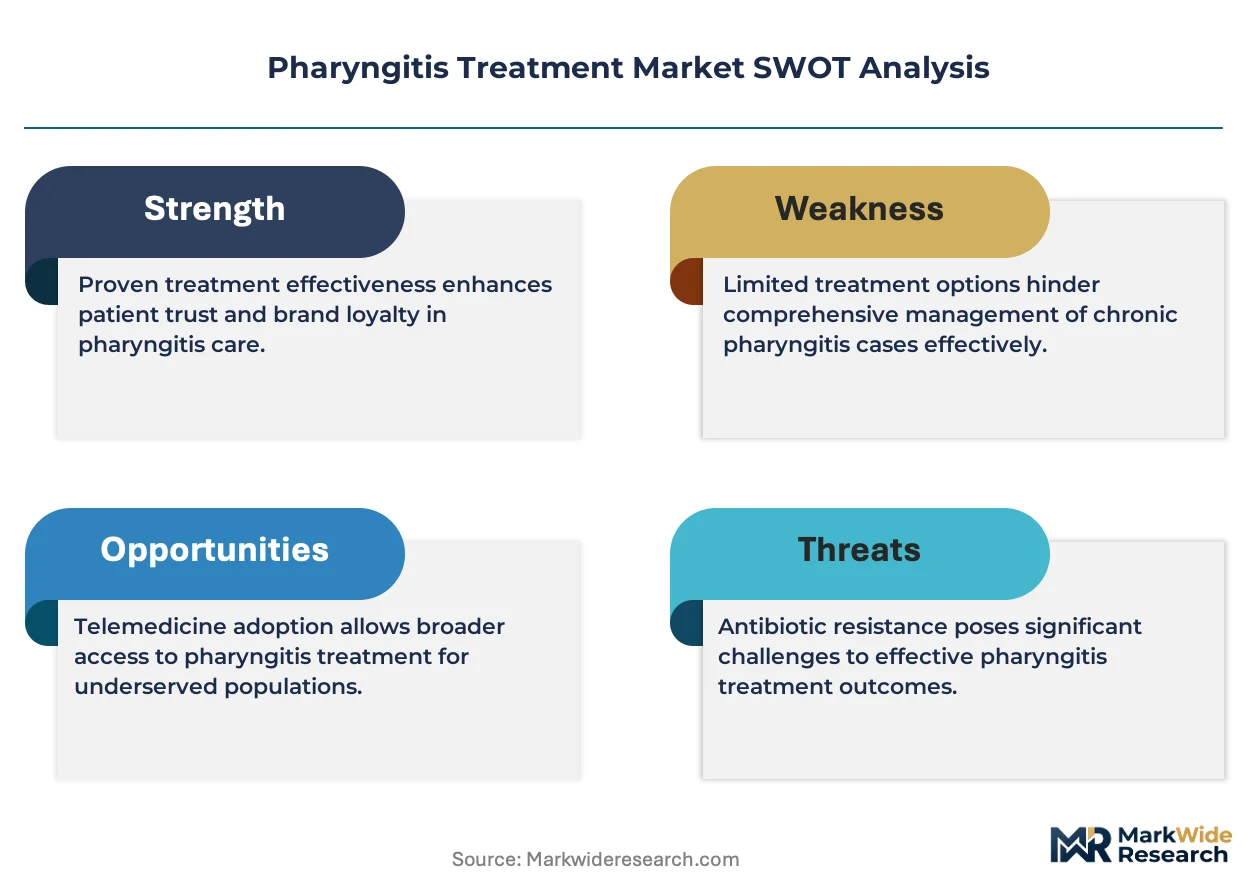
For Market Incumbents: Deploy backward integration into penicillin G active pharmaceutical ingredient production to secure supply continuity against Indian and Chinese export volatility. Consolidate pediatric formulation capabilities through targeted capability acquisitions in Germany and France, where parental compliance concerns drive brand loyalty. Channel control investments in telehealth platform partnerships will defend position against retail pharmacy diagnostic capture.
For New Entrants and Emerging Players: Retail pharmacy chains represent the most penetrable channel partner type for AI-assisted triage tools that risk-stratify bacterial probability before prescription fulfillment. White-space targets include palatable liquid antibiotic presentations for children under five in Western European markets, and bundled diagnostic-plus-treatment contracts for United States accountable care organizations. A direct-to-consumer go-to-market angle through telehealth symptom checker integration offers lowest customer acquisition friction.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap generic specialists with captive API supply in India facing deferred environmental compliance upgrade timelines. Long-term viability across a five-to-ten year window hinges on stewardship-aligned narrow-spectrum portfolio concentration rather than legacy macrolide exposure. The signal to watch is FDA approval velocity for rapid molecular diagnostic platforms, which will accelerate formulary displacement of empiric prescribing protocols.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Capacity expansion in narrow-spectrum beta-lactam production secures GPO contract renewals with United States hospital systems. |
| Regulatory Approval Pathway | FDA clearance for rapid molecular diagnostic platforms accelerates stewardship-compliant prescribing workflow integration. |
| Strategic Partnership | Telehealth platform alliances channel diagnostic volume toward affiliated retail pharmacy fulfillment networks. |
| Green Manufacturing Transition | REACH-compliant synthesis investments confer preferential procurement status from European hospital sustainability committees. |
| Pipeline Diversification | Immunomodulatory throat preparation development targets recurrent pharyngitis segments with distinct reimbursement coding. |
Research Methodology
Multi-period observation of antibiotic prescribing volume trends, resistance surveillance patterns, and telehealth platform transaction growth anchored the trend analysis, supplemented by interviews with hospital pharmacy directors, retail chain procurement executives, pediatric formulation specialists, and CDSCO regulatory consultants. Secondary validation drew from FDA antimicrobial stewardship guidance documents, EMA pediatric investigation plan filings, CDC resistance tracking databases, and Indian pharmaceutical export statistics. Bottom-up prescription volume modeling and top-down market sizing triangulation ensured cross-verification of segment-level estimates.
Input-output matrix framing structured the analytical framework, linking active pharmaceutical ingredient production capacity through formulation stages to end-user channel demand across the projection horizon. Segmentation dimensions encompassed product type, delivery mode, treatment stage, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted volume projections and price trajectory assumptions. Forecast inputs included point-of-care diagnostic adoption curves and antibiotic stewardship compliance enforcement intensity by geography.
Caveats apply where FDA stewardship guideline revisions, CDSCO manufacturing inspection outcomes, or telehealth regulatory reclassification could materially shift the outlook. Forecasts reflect documented assumptions regarding resistance pattern evolution and generic entry timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
North America Sports Medicine Market
Specialty Medicine
Global Allergic Rhinitis Market
Specialty Medicine
HPV Associated Disorders Market
Specialty Medicine
Pituitary Stalk Interruption Syndrome Treatment Market
Specialty Medicine
Nonerosive Reflux Disease Treatment Market
Specialty Medicine
Epistaxis Market
Specialty Medicine
Ovarian Cancer Therapeutics Market
Specialty Medicine
Splenomegaly Therapeutics Market
Specialty Medicine
Seasonal Allergy Market
Specialty Medicine
Scleritis Market
Specialty Medicine
Acrocallosal Syndrome Therapeutics Market
Specialty Medicine
Global Pigmentation Disorders Treatment Market
Specialty Medicine
Global Amyotrophic Lateral Sclerosis (ALS) Treatment Market
Specialty Medicine
Epilepsy Treatment Market
Specialty Medicine
Global Bladder Disorders Market
Specialty Medicine
Barlow's Syndrome Market