
 Essential Thrombocythemia Market | 2026-2036
Essential Thrombocythemia Market Size, Share, and Industry Trends Forecast 2026-2036
Essential Thrombocythemia Market Analysis
Specialty pharmacy distribution is tilting toward integrated oncology networks that manage oral JAK inhibitor dispensing directly. Novartis AG leverages its established myeloproliferative neoplasm franchise to sustain prescriber loyalty across academic medical centers. Bristol Myers Squibb Company anchors its position through deep relationships with community hematology practices. Incyte Corporation differentiates via focused investment in biomarker-driven patient identification protocols.
Essential thrombocythemia is a clonal myeloproliferative neoplasm characterized by sustained platelet elevation exceeding 450,000 per microliter, driven by JAK2, CALR, or MPL driver mutations, with primary clinical purposes of thrombosis prevention and transformation risk mitigation. JAK inhibitors command the dominant revenue position among product types due to their disease-modifying profile and superior cytoreductive control in high-risk patients. Oral delivery mode occupies the largest volume share, though subcutaneous formulations are gaining traction in patients with adherence challenges or gastrointestinal intolerance. Disease modifying treatment approaches concentrate margin pools where long-term therapy contracts and monitoring services bundle with drug supply.
The FDA's orphan drug designation framework and EMA's priority medicines scheme jointly shape clinical development timelines and market access trajectories for novel cytoreductive agents. Health Canada and the FDA both enforce pharmacovigilance requirements that extend post-approval commitment burdens across the product lifecycle. Stakeholders must monitor evolving JAK inhibitor safety signals and their impact on prescribing guidelines, as regulatory label changes could rapidly redistribute market share among mechanistic classes.
Market Dynamics
First-line JAK inhibitor adoption is compressing the therapeutic window for traditional cytoreductive agents, forcing repositioning of hydroxyurea and anagrelide toward intolerance populations and forcing manufacturers to bundle monitoring services with drug supply contracts.
Growth Catalysts
- FDA Accelerated Approval Pathways:Orphan drug designation for rare myeloproliferative neoplasms compresses Phase II-to-approval timelines, incentivizing developers to prioritize cytoreductive endpoints over surrogate markers.
- Specialized Cancer Center Expansion:Academic medical centers in the United States are establishing dedicated myeloproliferative neoplasm clinics that standardize JAK inhibitor protocols and drive referral concentration.
- CALR Mutation Screening:Next-generation sequencing panels in hospital-based hematology departments are identifying mutation-negative patients eligible for targeted cytoreductive selection.
Market Restraints
- JAK Inhibitor Safety Surveillance:Cardiovascular event signals in post-marketing pharmacovigilance databases are triggering FDA label revisions that restrict high-risk patient eligibility.
- Active Pharmaceutical Ingredient Concentration:Synthetic chemistry manufacturing for JAK2-selective inhibitors clusters in Chinese and Indian contract development organizations, creating single-source vulnerability.
- Substitution from Pegylated Interferon:Recombinant interferon-alpha formulations are capturing pregnancy-eligible and young patient segments where teratogenicity concerns limit hydroxyurea use.
Strategic Opportunities
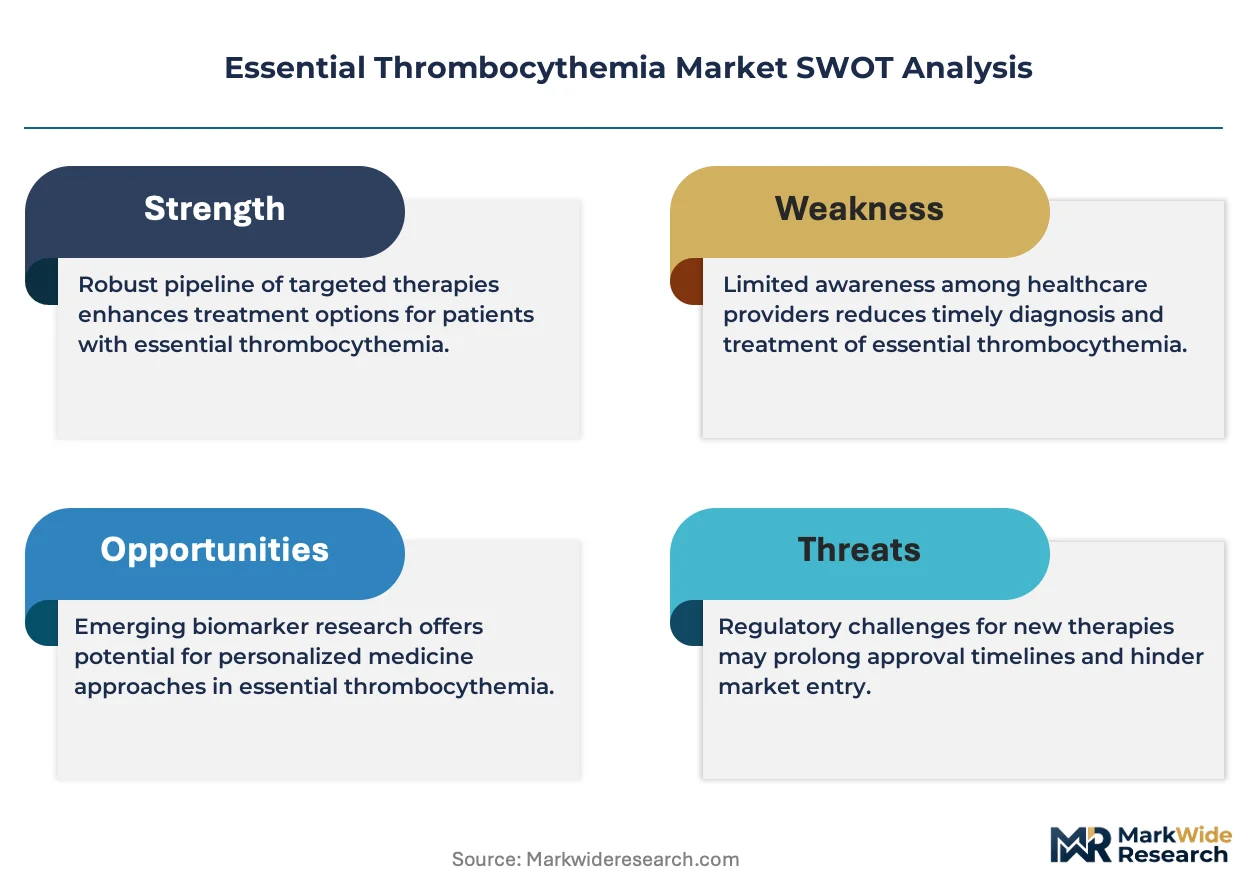
- Biomarker-Driven Patient Stratification:CALR and MPL mutation status is enabling precision cytoreductive selection protocols that match mechanism to molecular profile.
- Subcutaneous Formulation Development:Injectable delivery systems address gastrointestinal intolerance in oral JAK inhibitor populations, opening adherence-challenged segments.
- Integrated Oncology Network Partnerships:Specialty pharmacy direct-dispensing arrangements with community hematology practices capture margin from traditional wholesale channels.
Industry Challenges
- Hematopathology Diagnostic Capacity:Bone marrow morphology expertise shortages delay clonal confirmation and mutation testing turnaround in community settings.
- Long-Term Cytoreductive Monitoring Infrastructure:Thrombosis and transformation event tracking requires prospective registry investment that strains mid-cap developer resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Essential Thrombocythemia Market |
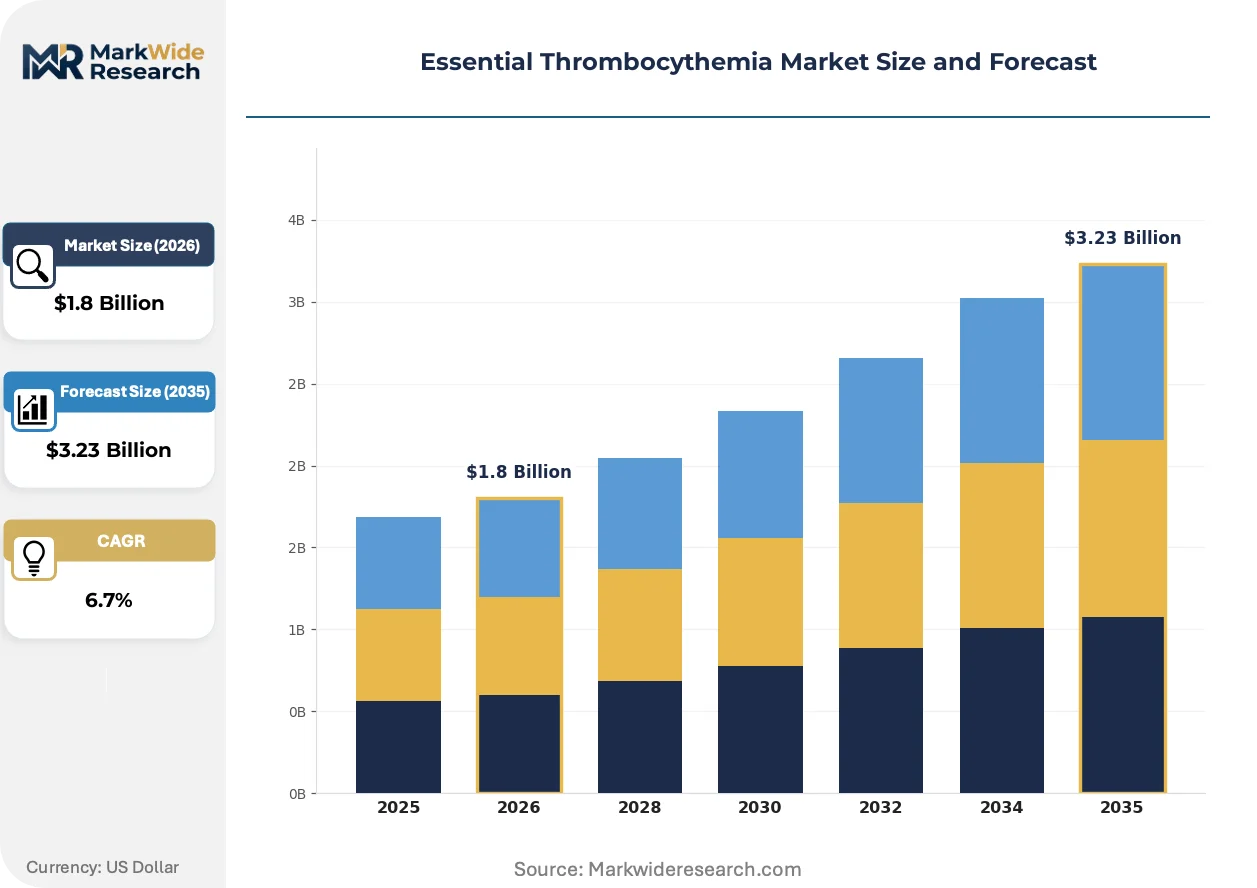
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: JAK Inhibitors, Thrombopoietin Receptor Agonists, Cytoreductive Agents, Chemotherapy Agents Delivery Mode: Oral, Subcutaneous, Intravenous, Intramuscular End User: Hospitals, Clinics, Home Healthcare, Research Laboratories Treatment Approach: Symptomatic Management, Disease Modifying, Watchful Waiting, Combination Therapy |
| Companies Covered | Novartis AG, Bristol Myers Squibb Company, Incyte Corporation, PharmaEssentia Corporation, Geron Corporation, Merck & Co., Inc., Pfizer Inc., Takeda Pharmaceutical Company Limited, CTI BioPharma Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Essential Thrombocythemia Market Emerging Trajectories
Next-generation sequencing integration and real-world evidence generation are rewriting how cytoreductive agents demonstrate value, compressing traditional randomized trial timelines and elevating biomarker-driven prescribing algorithms.
Mutation-agnostic JAK inhibitors with improved selectivity profiles are rendering obsolete the historical binary of JAK2-positive versus triple-negative patient stratification. Academic medical centers are adopting these agents across CALR and MPL mutation subtypes previously managed with hydroxyurea. The structural consequence is collapsing the addressable patient pool for non-targeted cytoreductives into residual intolerance and contraindication niches.
EMA's priority medicines scheme and FDA's breakthrough therapy designation are synchronizing European and American regulatory timelines for novel myeloproliferative neoplasm therapeutics. Developers now design single pivotal trials with dual-primary endpoints satisfying both agencies' evidentiary thresholds. High-risk patient subsets with prior thrombotic events are receiving accelerated access, compressing commercialization lag between approval and reimbursement.
Hospital-based specialty pharmacies are displacing traditional wholesale distribution for oral JAK inhibitors through 340B program participation and in-house dispensing incentives. Community hematology practices are consolidating procurement through integrated delivery network contracts that bundle drug acquisition with laboratory monitoring. The United States exhibits the most pronounced channel compression, where vertical integration between cancer centers and specialty pharmacy operations captures patient volume from independent retail channels.
Essential Thrombocythemia Market Segmentation
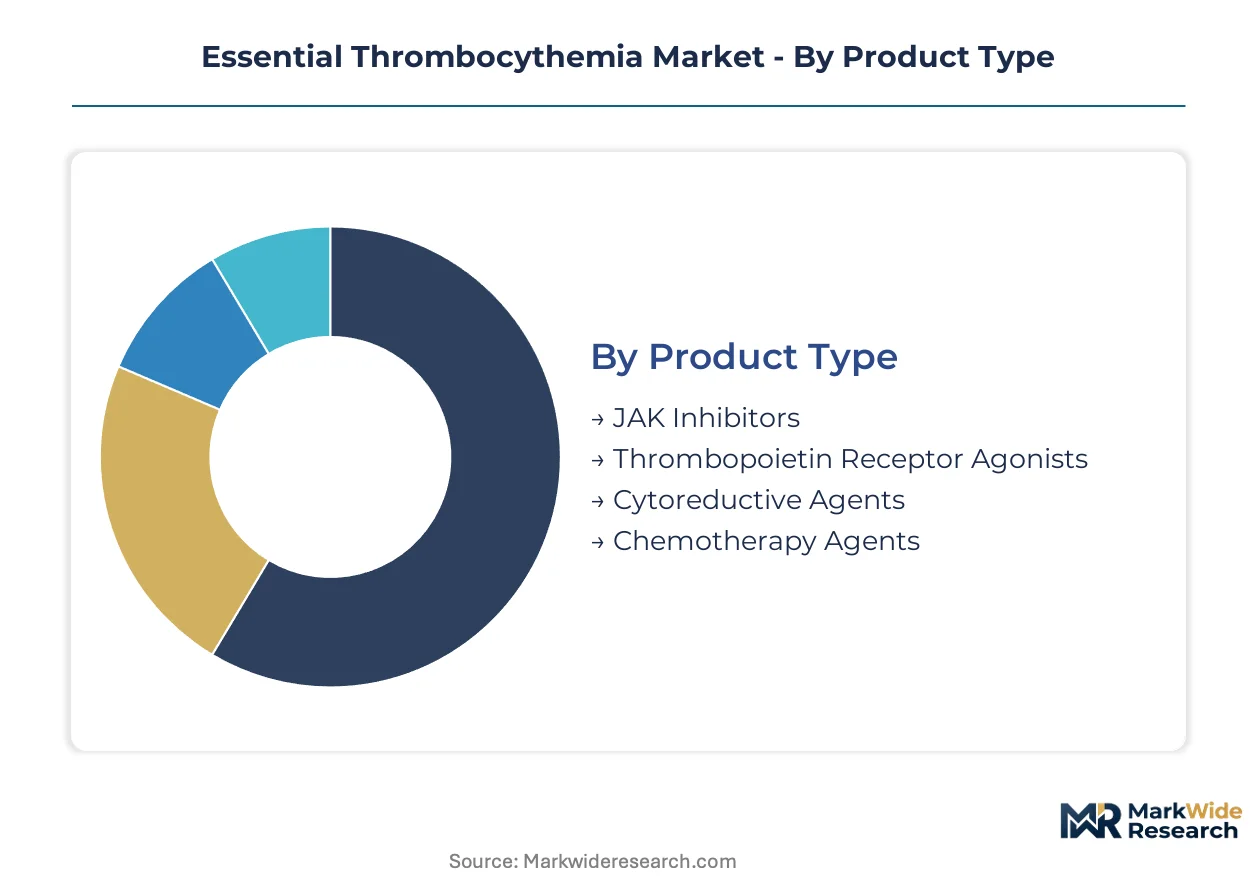
Essential thrombocythemia treatment selection hinges on mutation status, thrombotic risk stratification, and patient-specific tolerability profiles. Segmentation reveals how cytoreductive protocols bifurcate between disease-modifying JAK inhibitors and legacy agents relegated to niche populations.
Product Type:
After-sales monitoring intensity varies sharply across mechanistic classes, with JAK inhibitors demanding intensive pharmacovigilance and laboratory surveillance compared to legacy cytoreductives.
- JAK Inhibitors:Small-molecule agents targeting the JAK-STAT signaling cascade deliver superior platelet control in high-risk patients with JAK2V617F mutations. Academic medical centers in the United States concentrate demand for these agents, driven by thrombosis prevention protocols and long-term cytoreductive contracts bundling drug supply with monitoring services.
- Cytoreductive Agents:Hydroxyurea and anagrelide remain staple options for intolerance populations and resource-constrained settings where JAK inhibitor access is limited. Demand concentrates in community hematology practices across India and Brazil, constrained by reimbursement gaps and the need for cytopenia monitoring.
- Thrombopoietin Receptor Agonists:Platelet production modulators occupy a narrow niche in ET-related thrombocytopenia management protocols.
- Chemotherapy Agents:Alkylating agents and radioactive phosphorus persist in transformation-phase salvage regimens with limited contemporary utilization.
By volume, Cytoreductive Agents leads. By growth pace, JAK Inhibitors is ahead.
Delivery Mode:
Cost tier stratification separates premium oral formulations from infrastructure-heavy parenteral alternatives requiring clinical administration support.
- Oral:Tablet and capsule formulations dominate first-line cytoreductive therapy, enabling outpatient management and direct specialty pharmacy dispensing. Hospital-based specialty pharmacies in the United States capture margin through 340B program participation and in-house dispensing incentives.
- Subcutaneous:Injectable delivery systems address gastrointestinal intolerance in oral JAK inhibitor populations, opening adherence-challenged segments. Pegylated interferon-alpha formulations gain traction in pregnancy-eligible cohorts across Germany and France where teratogenicity concerns limit hydroxyurea use.
- Intravenous:Infusion-dependent agents concentrate in inpatient transformation management and acute thrombotic event protocols.
- Intramuscular:Depot formulations serve narrow long-acting cytoreductive applications with limited commercial footprint.
Oral administration commands absolute volume share. Subcutaneous formulations are climbing the fastest as adherence engineering and interferon-alpha alternatives reshape prescribing patterns.
End User:
Customer type fragmentation tracks diagnostic complexity, with mutation testing capability and bone marrow pathology expertise concentrating in tertiary settings.
- Hospitals:Academic medical centers and specialized cancer centers anchor ET protocol development, housing next-generation sequencing panels and dedicated myeloproliferative neoplasm clinics. The FDA's orphan drug designation framework shapes how these institutions participate in accelerated access programs for novel cytoreductive agents.
- Clinics:Community hematology practices manage stable patients on maintenance cytoreductive therapy, consolidating procurement through integrated delivery network contracts. Germany's Kassenärztliche Bundesvereinigung reimbursement structures influence how these practices select between hydroxyurea and interferon-alpha alternatives.
- Home Healthcare:Subcutaneous administration training and remote monitoring services expand patient-managed therapy options.
- Research Laboratories:Biomarker discovery and real-world evidence generation facilities support mutation-driven patient stratification protocols.
Hospitals dominate value capture. Home Healthcare represents the steepest expansion trajectory as subcutaneous interferon-alpha and patient-administered JAK inhibitor programs mature.
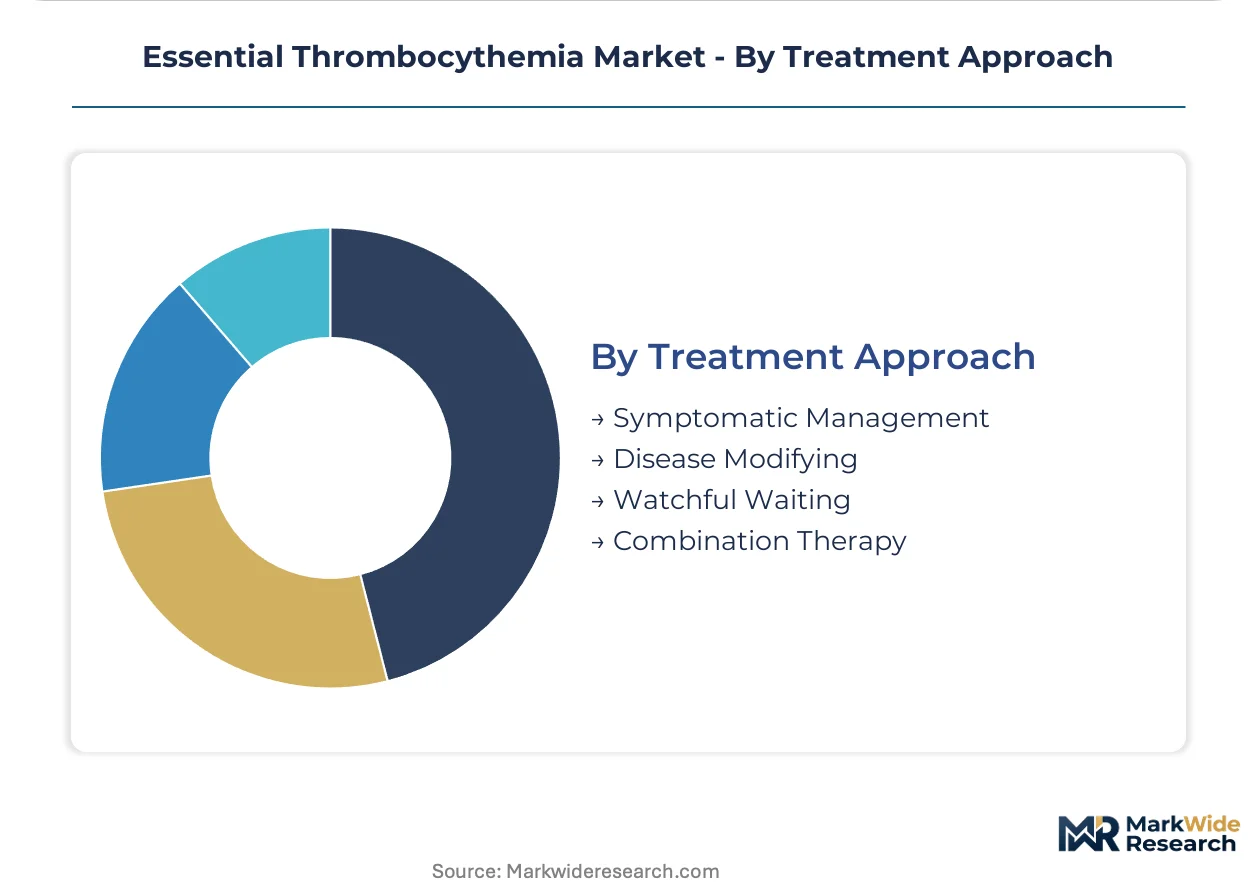
Treatment Approach:
Margin concentration aligns with therapy duration and monitoring service bundling, favoring chronic disease-modifying regimens over episodic symptomatic management.
- Disease Modifying:Long-term cytoreductive therapy targeting clonal burden reduction and transformation risk mitigation commands premium positioning. JAK inhibitor contracts bundle laboratory monitoring and thrombosis event tracking, creating recurring revenue streams for specialty pharmacy networks.
- Symptomatic Management:Microvascular disturbance control and acute thrombosis prevention address immediate patient burden without altering disease trajectory. Low-dose aspirin and phlebotomy protocols concentrate in low-risk CALR-mutated populations across community settings in Italy and Spain.
- Watchful Waiting:Observation protocols for very low-risk patients defer cytoreductive initiation pending thrombotic event or platelet threshold progression.
- Combination Therapy:Dual-agent regimens address refractory cytoreduction or overlapping myeloproliferative neoplasm features in select high-complexity cases.
Disease Modifying leads by patient-year volume. Combination Therapy is gaining share fastest as resistance patterns and mutation heterogeneity drive protocol complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Memorial Sloan Kettering Cancer Center corridor along New York's East River anchors North American myeloproliferative neoplasm protocol development. Germany's dense hospital network along the Rhine-Ruhr industrial belt supports Europe's highest per-capita hematology specialization. Japan's Kanto region concentrates Asia-Pacific clinical trial infrastructure for JAK inhibitor development.
United States
Academic medical centers in Boston and Houston drive JAK inhibitor protocol standardization through dedicated myeloproliferative neoplasm clinics. The FDA's orphan drug designation framework accelerates cytoreductive agent approvals for rare disease subsets. The MD Anderson Cancer Center in Texas anchors real-world evidence generation that shapes global prescribing guidelines.
Germany
Community hematology practices in Bavaria and Baden-Württemberg consolidate procurement through integrated delivery networks. The Kassenärztliche Bundesvereinigung reimbursement structures influence interferon-alpha selection in pregnancy-eligible cohorts. Heidelberg's university hospital cluster advances CALR mutation screening protocols for precision cytoreductive matching.
Japan
PMDA's sakigake designation system compresses regulatory timelines for novel JAK inhibitors targeting high-risk patient subsets. Tokyo's St. Luke's International Hospital anchors biomarker-driven patient stratification research. The Osaka-Kobe medical corridor concentrates subcutaneous formulation development partnerships between domestic and multinational developers.
United Kingdom
NHS England's specialized commissioning framework concentrates ET treatment in designated cancer centers across London and Manchester. The MHRA's early access to medicines scheme enables pre-approval JAK inhibitor use in transformation-risk patients. Cambridge's biomedical cluster supports next-generation sequencing integration into routine hematology diagnostics.
India
CDSCO's accelerated approval pathway for orphan indications attracts JAK inhibitor developers seeking reduced clinical trial burdens. Mumbai's Tata Memorial Hospital anchors hydroxyurea access programs for resource-constrained populations. Bangalore's contract research organization cluster supports pharmacovigilance infrastructure for post-marketing surveillance.
Essential Thrombocythemia Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in mutation testing and monitoring services. The essential thrombocythemia market structures around three archetypes: multinational pharmaceutical conglomerates with established myeloproliferative neoplasm franchises, mid-cap biotech developers with JAK inhibitor specialization, and emerging innovators targeting interferon-alpha alternatives. Dominant competitive moves include specialty pharmacy network integration and biomarker-driven patient identification protocol partnerships.
Within the multinational tier, Novartis AG and Bristol Myers Squibb Company exemplify platform-scale players with deep prescriber relationships across academic and community hematology settings. Incyte Corporation occupies a position representing focused JAK inhibitor investment and biomarker protocol development. These three anchors demonstrate how geographic origin and corporate structure correlate with divergent channel strategies.
| Leading Market Players |
|---|
| Novartis AG |
| Bristol Myers Squibb Company |
| Incyte Corporation |
| PharmaEssentia Corporation |
| Geron Corporation |
| Merck & Co., Inc. |
| Pfizer Inc. |
| Takeda Pharmaceutical Company Limited |
| CTI BioPharma Corp. |
| Others |
Supply Flow & Price Mechanics
The Rotterdam-Antwerp pharmaceutical corridor channels active pharmaceutical ingredient shipments from Indian and Chinese contract development organizations into European formulation facilities, with freight cost volatility amplifying margin compression at the standard-formulation tier while specialty pharmacy networks in the United States extract premium pricing through bundled monitoring services.
Pricing Analysis
Volume-discount tiering structures separate long-term cytoreductive therapy contracts from spot procurement, with JAK inhibitor manufacturers anchoring premium positioning through disease-modifying efficacy claims and integrated laboratory surveillance bundles. Price differentiation hinges on mutation-specific indication breadth and FDA orphan drug exclusivity status. Pricing pressure stems from pegylated interferon-alpha substitution in pregnancy-eligible segments. Community hematology practices in India and Brazil exhibit highest price sensitivity, while academic medical centers in the United States prioritize clinical outcomes over acquisition cost.
Supply Chain Analysis
Upstream feedstock synthesis for JAK2-selective inhibitors concentrates in Chinese and Indian contract development organizations, with key intermediate production anchored in Zhejiang province and Hyderabad's pharmaceutical cluster. Synthetic chemistry inputs draw from specialized catalyst suppliers and chiral resolution technology providers. Single-source vulnerability in high-purity reagent supply creates exposure to export licensing disruptions. Distribution runs through hospital-based specialty pharmacies displacing traditional wholesale channels, particularly under 340B program participation in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in mutation-agnostic patient segments where next-generation sequencing adoption outpaces prescriber protocol standardization, creating niches for biomarker-driven cytoreductive selection tools.
For Market Incumbents: Insulate prescriber loyalty through captive specialty pharmacy networks and longitudinal patient monitoring data assets. Deepen backward integration into pharmacovigilance infrastructure to preempt FDA label revision impacts. Lock in academic medical center formulary positioning via real-world evidence generation partnerships that shape global treatment guidelines.
For New Entrants and Emerging Players: Community hematology practices in India's tier-two cities offer the most penetrable white space, with CDSCO accelerated approval pathways reducing clinical trial burdens compared to FDA timelines. Target subcutaneous formulation gaps in gastrointestinal intolerance populations. Pursue integrated delivery network procurement consolidation as the primary go-to-market angle.
For Investors and Strategic Acquirers: FDA breakthrough therapy designation reshapes the acquisition landscape by compressing Phase II-to-approval timelines and elevating early-stage asset valuations. Long-term viability centers on disease-modifying mechanism durability across the 5-10 year cytoreductive therapy window. Mid-cap developers with JAK inhibitor specialization and existing pharmacovigilance infrastructure represent priority acquisition archetypes. Monitor EMA priority medicines scheme admission decisions as inflection indicators for European market access trajectory.
| Strategic Initiative | Industry Significance |
|---|---|
| Biomarker-Driven Patient Stratification | CALR and MPL mutation screening enables precision matching of cytoreductive mechanism to molecular profile. |
| Subcutaneous Formulation Development | Injectable delivery systems capture adherence-challenged segments with gastrointestinal intolerance to oral JAK inhibitors. |
| Specialty Pharmacy Network Integration | Direct dispensing arrangements with community hematology practices capture margin from traditional wholesale channels. |
| Real-World Evidence Generation | Prospective registry investment at academic medical centers shapes global prescribing guidelines and formulary positioning. |
| Regulatory Acceleration Pathway | Orphan drug designation compresses clinical development timelines and extends market exclusivity for novel cytoreductive agents. |
Methodological Framework
Desk research of FDA orphan drug designation filings, EMA priority medicines scheme submissions, and ClinicalTrials.gov protocol registrations preceded structured interviews with drug development executives, regulatory affairs leads, formulary directors at academic medical centers, and payer access specialists. Secondary validation drew from SEC 10-K therapeutic segment disclosures, hospital procurement database extracts, and specialty pharmacy dispensing records. Bottom-up patient flow modeling triangulated against top-down market size estimates from manufacturer reported sales.
Assumptions held fixed across the projection horizon include JAK inhibitor first-line adoption trajectories and FDA pharmacovigilance enforcement intensity, while variables included pegylated interferon-alpha competitive erosion rates and next-generation sequencing panel penetration in community hematology settings. Segmentation dimensions encompassed product type, delivery mode, end user facility type, and treatment approach philosophy. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns, with inputs from thrombosis event incidence registries and transformation risk epidemiology.
Practitioners should monitor FDA label revision triggers and EMA safety signal assessments for early signals of mechanistic class repositioning. Forecasts reflect assumptions about regulatory enforcement continuity and biomarker test reimbursement stability. Quarterly review of pharmacovigilance database alerts and prescriber guideline update cadence is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Systemic Lupus Erythematosus (SLE) Market
Specialty Medicine
Global Pigmentation Disorders Treatment Market
Specialty Medicine
Herpes Zoster (Shingles) Market
Specialty Medicine
Healthcare Specialty Enzymes Market
Specialty Medicine
North America Dry Eye Syndrome Market
Specialty Medicine
Acute Hepatic Porphyria (APH) Market
Specialty Medicine
Brain Metastasis Therapeutics Market
Specialty Medicine
Pemphigus Vulgaris (PV) Treatment Market
Specialty Medicine
Hyperuricemia Market
Specialty Medicine
Castrate Resistant Prostate Cancer Therapeutics Market
Specialty Medicine
Liver Fibrosis Treatment Market
Specialty Medicine
Leukocyte Adhesion Deficiency Management Market
Specialty Medicine
Mental Retardation Treatment Market
Specialty Medicine
Animal Hormone Therapy Market
Specialty Medicine
Global Cough Hypersensitivity Syndrome Treatment Market
Specialty Medicine
ADHD Therapeutics Market