
 Premenstrual Dysphoric Disorder Market | 2026-2036
Premenstrual Dysphoric Disorder Market Size, Share, and Industry Trends Forecast 2026-2036
Premenstrual Dysphoric Disorder Market Analytics
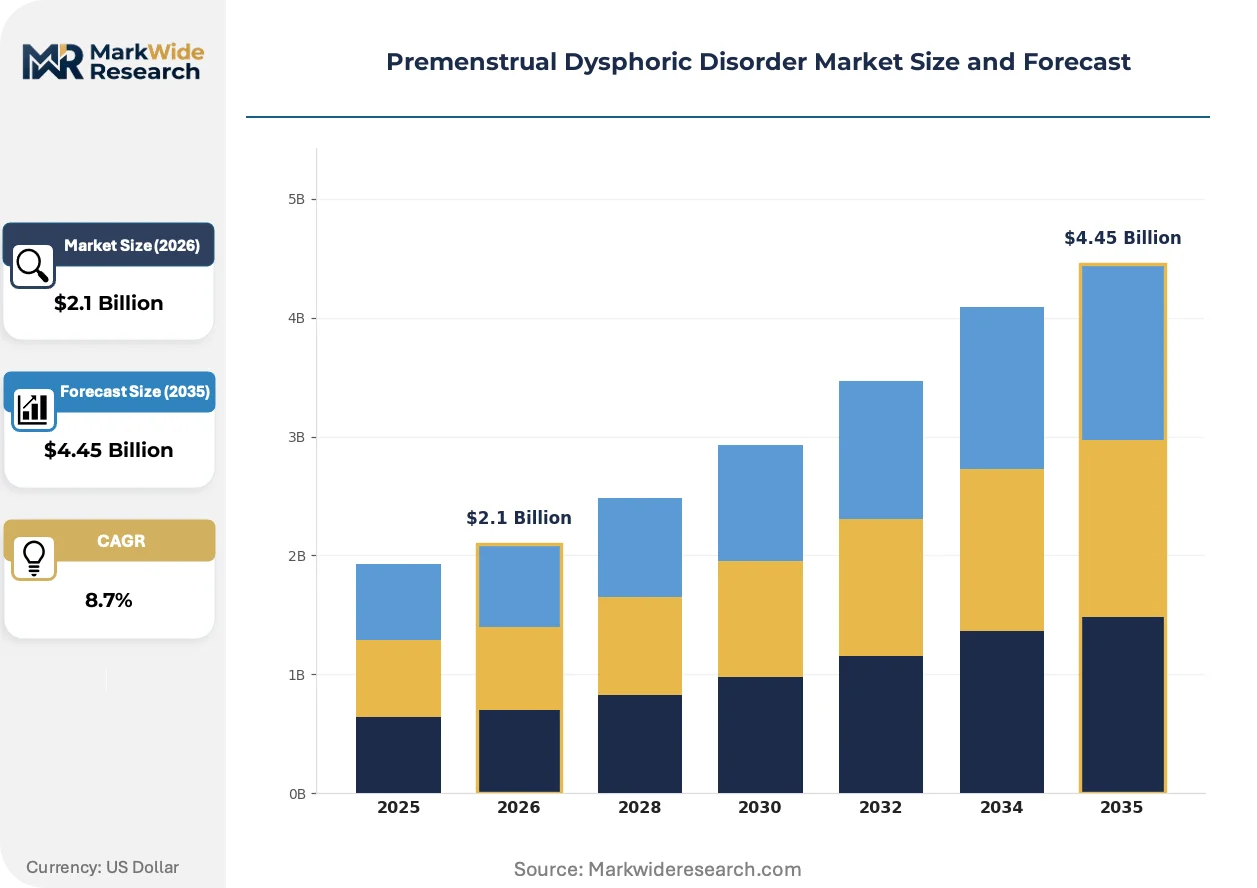
Diagnostic specificity upgrades is unwinding the market upward as clinicians move beyond generic premenstrual syndrome coding toward validated PMDD biomarker panels and structured diagnostic interviews. Eli Lilly and Company leverages its neuroscience R&D infrastructure to sustain leadership in serotonergic modulation therapies. Pfizer Inc. anchors its position through broad psychiatric portfolio integration and established hospital formulary access. Bayer AG differentiates via hormonal intervention expertise that spans contraceptive and therapeutic applications.
Premenstrual dysphoric disorder constitutes a severe, cyclical mood disorder characterized by affective lability, irritability, and functional impairment during the late luteal phase, with diagnostic confirmation requiring prospective symptom charting across at least two menstrual cycles per DSM-5 criteria. The condition's primary commercial purpose centers on reducing occupational disability and healthcare utilization costs associated with misdiagnosed or untreated presentations. Oral delivery mode dominates current prescribing patterns due to patient familiarity and generic availability, though intranasal formulations represent the fastest-expanding segment as manufacturers target rapid onset of action for acute mood episodes. Homecare settings are capturing disproportionate growth as telehealth platforms enable remote psychiatric monitoring and prescription management.
The FDA maintains stringent efficacy thresholds for PMDD-specific labeling, while the EMA's centralized assessment pathway shapes European market entry timelines and evidence requirements. HIPAA compliance frameworks constrain how digital therapeutics platforms collect and share menstrual cycle data for treatment optimization. Stakeholders must monitor evolving payer policies on hormonal versus serotonergic first-line therapy positioning as cost-effectiveness data matures across health systems.
Market Dynamics
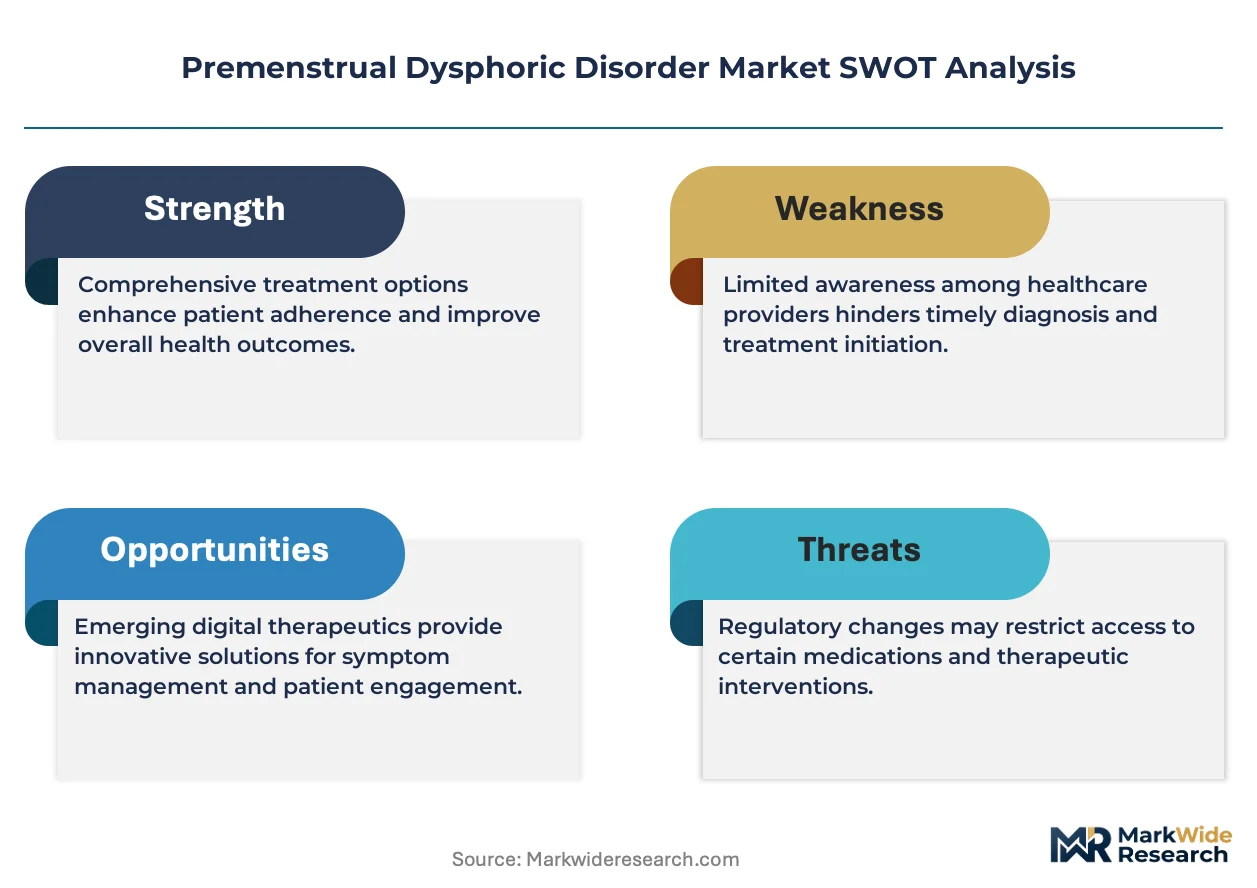
Diagnostic specificity mandates from the FDA and EMA are forcing clinicians to abandon generic premenstrual syndrome coding in favor of validated biomarker panels and structured DSM-5 interviews, compressing misdiagnosis rates and expanding addressable patient pools.
Growth Catalysts
- Reproductive Mental Health Guidance:The FDA's updated guidance on reproductive mental health therapies has streamlined clinical trial pathways. Investigators now face clearer efficacy thresholds for PMDD-specific labeling.
- Telehealth Infrastructure:Remote psychiatric monitoring platforms are capturing disproportionate growth in homecare settings. These systems enable cycle-tracking integration with prescription management.
- Hospital Screening Expansion:Hospital-based psychiatric departments across the United States are implementing standardized PMDD screening protocols. This institutional push normalizes specialist referrals.
Market Restraints
- Serotonergic Manufacturing Concentration:Active pharmaceutical ingredient production for SSRIs concentrates in specific Asian manufacturing clusters. Geopolitical friction threatens supply continuity for first-line therapies.
- Hormonal Intervention Cost Volatility:Synthetic progestin input costs fluctuate with petrochemical feedstock pricing. This volatility compresses margin predictability for combination hormonal therapies.
- EMA Centralized Assessment Friction:The European Medicines Agency's unified pathway imposes extended evidence requirements. Market entry timelines for novel mechanisms stretch substantially versus US pathways.
Strategic Opportunities
- Intranasal Formulation White Space:Rapid-onset delivery mechanisms for acute luteal-phase mood episodes remain underdeveloped. Manufacturers targeting this modality face limited direct competition.
- Digital Therapeutics Integration:HIPAA-compliant menstrual cycle data collection enables algorithmic treatment optimization. Platforms bridging symptom tracking with clinician dashboards represent unclaimed territory.
- Specialized Women's Health Clinic Networks:Proliferating dedicated clinics in the United States create concentrated prescription channels. Partnership models with these facilities bypass crowded hospital formulary competition.
Industry Challenges
- Prospective Symptom Charting Compliance:DSM-5 diagnostic confirmation requires two-cycle prospective documentation. Patient dropout from this logging burden inflates screening-to-treatment conversion costs.
- Payer Positioning Uncertainty:Health systems lack mature cost-effectiveness data comparing hormonal versus serotonergic first-line approaches. Reimbursement policies remain fragmented across commercial and public plans.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Premenstrual Dysphoric Disorder Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SSRIs, SNRIs, Oral Contraceptives, GnRH Agonists End User: Hospitals, Clinics, Pharmacies, Homecare Settings Delivery Mode: Oral, Injectable, Transdermal, Intranasal Therapy Area: Mental Health, Reproductive Health, Hormonal Disorders, Women's Health |
| Companies Covered | Pfizer Inc., Eli Lilly and Company, Bayer AG, GlaxoSmithKline plc, Teva Pharmaceutical Industries Ltd., Novartis AG, Merck & Co., Inc., AbbVie Inc., Bristol-Myers Squibb Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Premenstrual Dysphoric Disorder Market Evolving Landscape
Biomarker validation and delivery mechanism innovation are actively restructuring competitive positioning in PMDD therapeutics, with rapid-onset modalities and digital integration commanding disproportionate development investment.
Intranasal serotonergic modulation is bifurcating the oral-dominant prescribing landscape. Specialized women's health clinics and hospital psychiatric departments are piloting these formulations for patients with acute functional impairment. The technology is bifurcating treatment protocols into maintenance oral regimens versus rescue intranasal interventions, forcing manufacturers to develop dual-product portfolios.
The EMA's centralized assessment pathway for reproductive mental health therapies is compressing European market entry timelines for sponsors with existing FDA approvals. This regulatory convergence pressures developers to prioritize US-first filing strategies. Combination hormonal therapies face heightened scrutiny under this framework, diverting investment toward non-hormonal mechanisms.
Remote psychiatric monitoring via telehealth platforms is displacing traditional in-person luteal-phase assessments. Homecare settings now capture prescription initiation and titration decisions previously concentrated in hospital outpatient departments. This channel shift is most visible in the United States, where specialized women's health clinics integrate synchronous video consultation with asynchronous symptom tracking.
Premenstrual Dysphoric Disorder Market Segmentation
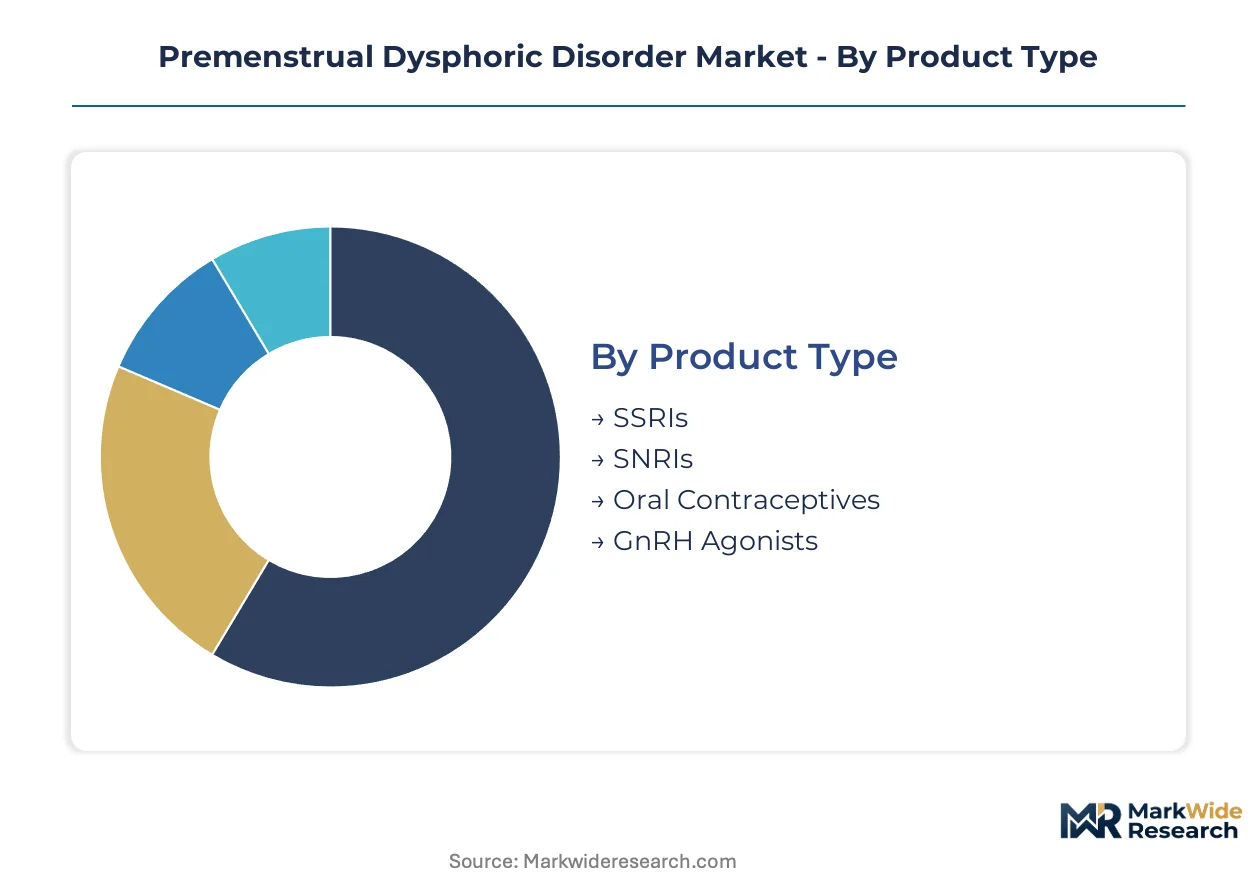
PMDD treatment pathways diverge sharply across product mechanisms and care settings, with substitution pressures intensifying where generic availability overlaps with novel delivery formats. Segmentation clarity enables stakeholders to isolate margin pools from volume drains.
Product Type:
Substitution pressure concentrates where serotonergic mechanisms compete with hormonal interventions for first-line positioning.
- SSRIs:Selective serotonin reuptake inhibitors modulate synaptic serotonin availability through presynaptic reuptake blockade. Demand clusters in hospital psychiatric departments across the United States where FDA-cleared PMDD-specific labeling drives formulary preference. Generic fluoxetine and sertraline availability compresses branded pricing power.
- SNRIs:Serotonin-norepinephrine reuptake inhibitors offer dual monoamine modulation for patients with comorbid pain or anxiety phenotypes. Specialized women's health clinics in urban US markets favor this class where SSRI non-response rates exceed institutional thresholds.
- Oral Contraceptives:Continuous or drospirenone-containing regimens suppress ovulation to eliminate cyclic symptom triggers. These face cost volatility from synthetic progestin feedstock pricing.
- GnRH Agonists:Gonadotropin-releasing hormone analogs induce medical menopause for refractory cases, reserved for severe presentations due to bone density concerns.
SSRIs retain volume leadership; intranasal serotonergic formulations hold the steepest expansion curve.
End User:
Cost tier stratification separates institutional reimbursement from out-of-pocket homecare channels.
- Hospitals:Inpatient psychiatric units and emergency departments manage acute luteal-phase crises requiring supervised stabilization. These settings concentrate high-acuity cases with elevated per-episode reimbursement.
- Clinics:Outpatient psychiatric and OB-GYN practices conduct prospective symptom charting and maintenance therapy titration. US-based specialized women's health clinics drive disproportionate new prescription generation through screening protocol implementation.
- Pharmacies:Retail and specialty dispensing channels handle generic SSRI fulfillment with minimal clinical intervention.
- Homecare Settings:Remote monitoring platforms enable asynchronous cycle tracking and prescription adjustments, expanding fastest where telehealth infrastructure integrates with asynchronous clinician dashboards.
Clinics capture the highest prescription initiation rates; homecare settings are climbing the fastest as telehealth platforms displace in-person luteal-phase assessments.
Delivery Mode:
Application urgency dictates modality selection between maintenance regimens and acute rescue interventions.
- Oral:Tablet and capsule formulations dominate maintenance therapy due to patient familiarity and extensive generic availability. US pharmacy benefit managers favor this route for cost containment.
- Injectable:Depot formulations of GnRH agonists and long-acting contraceptives suit adherence-challenged patients. Hospital outpatient departments administer these where compliance monitoring is critical.
- Transdermal:Patch-based delivery offers steady-state hormone absorption with reduced hepatic first-pass metabolism. This modality serves patients with gastrointestinal intolerance or swallowing difficulties.
- Intranasal:Rapid-onset serotonergic modulation targets acute mood episodes within the luteal phase, with manufacturers targeting this white space for functional impairment rescue.
Oral delivery retains volume leadership; intranasal formulations are gaining share fastest through rapid-onst positioning.
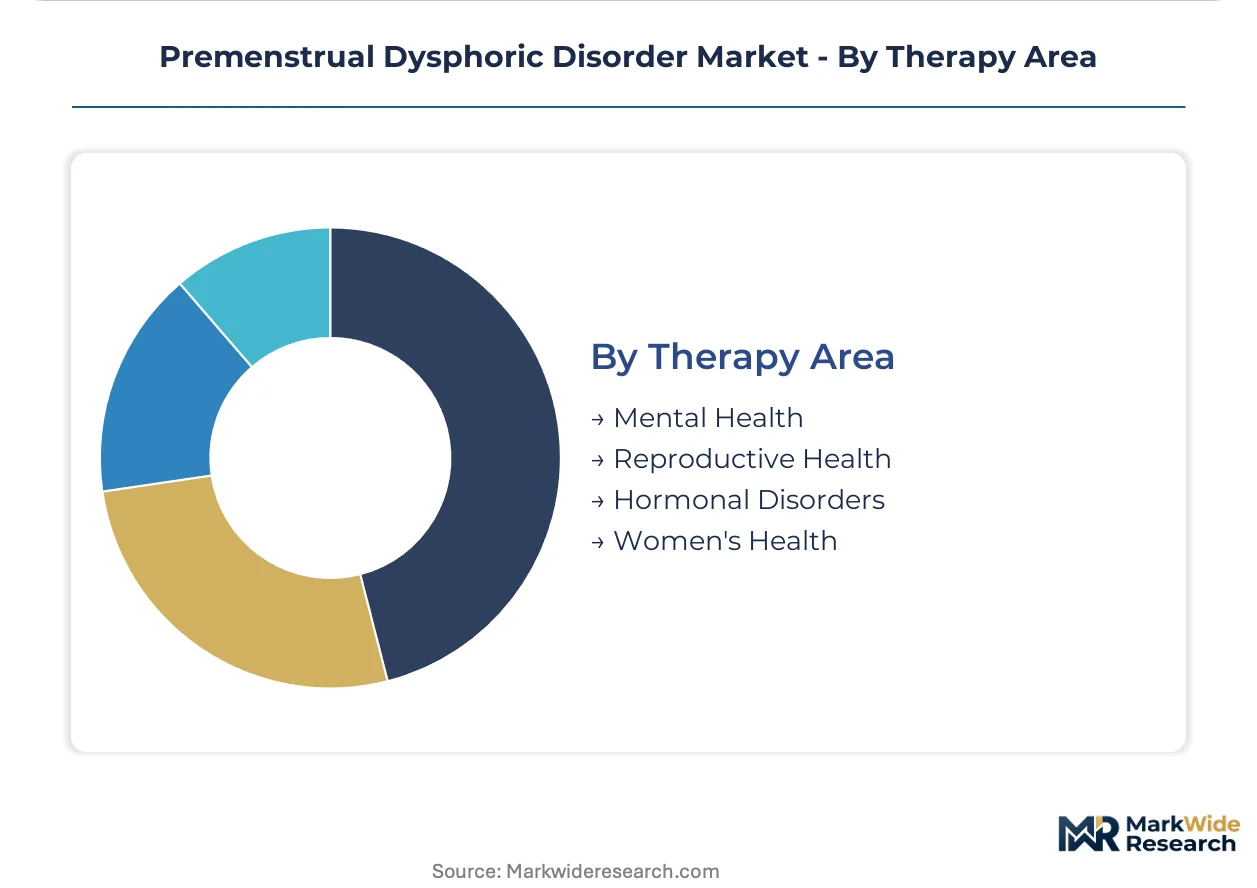
Therapy Area:
Customer type fragmentation reflects whether payers classify PMDD under psychiatric or gynecologic benefit categories.
- Mental Health:Psychiatric coding emphasizes affective lability and functional disability, qualifying for behavioral health parity protections under US commercial insurance.
- Reproductive Health:Gynecologic framing highlights menstrual cycle linkage and hormonal etiology, influencing prior authorization requirements.
- Hormonal Disorders:Endocrine classification positions treatments within metabolic and reproductive endocrinology formularies.
- Women's Health:Integrated specialty clinics collapse these boundaries through multidisciplinary care models spanning psychiatry and gynecology.
Mental Health retains volume leadership; Women's Health integrated clinics are expanding most quickly as specialized facilities proliferate across the United States.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States generates substantial pharmaceutical export revenue from PMDD therapeutics while importing active pharmaceutical ingredients from concentrated Asian manufacturing clusters. Germany and Switzerland balance domestic production of hormonal interventions with API sourcing dependencies. Japan maintains near-autonomous supply chains for serotonergic compounds through domestic fermentation capabilities.
United States
Specialized women's health clinics in metropolitan corridors drive prescription volume expansion through standardized screening protocols. The FDA's updated reproductive mental health guidance streamlines clinical trial pathways for PMDD-specific labeling. Hospital-based psychiatric departments in Boston and New York implement structured DSM-5 diagnostic interviews, compressing misdiagnosis rates and expanding addressable patient pools.
Germany
Integrated women's health networks spanning gynecology and psychiatry services concentrate demand in urban centers. The EMA's centralized assessment pathway shapes European market entry timelines through extended evidence requirements. Pharmaceutical manufacturing clusters in Baden-Württemberg produce hormonal interventions while sourcing synthetic progestin feedstocks from petrochemical suppliers.
Switzerland
Specialized endocrinology practices in Zurich and Geneva manage refractory PMDD cases through medical menopause protocols. Swissmedic maintains stringent efficacy thresholds for novel delivery mechanisms including intranasal formulations. Basel-based research institutions collaborate with hospital networks on biomarker validation panels for diagnostic specificity upgrades.
Japan
Telehealth platforms in Tokyo and Osaka enable remote psychiatric monitoring for luteal-phase symptom management. The PMDA's reproductive mental health framework emphasizes prospective symptom charting compliance across two menstrual cycles. Domestic fermentation facilities in Kansai supply serotonin-modulating compounds with reduced import dependency.
United Kingdom
Mental health parity protections under commercial insurance frameworks expand reimbursement access for psychiatric-coded PMDD treatments. NICE guidelines influence prescribing patterns toward serotonergic first-line approaches versus hormonal interventions. London-based specialist clinics integrate cycle-tracking applications with clinician dashboards for asynchronous care delivery.
Premenstrual Dysphoric Disorder Market Competitive Landscape
Listed leaders compete with private specialists across R&D infrastructure and hospital formulary access. The market exhibits tiered concentration where large-cap pharmaceutical firms anchor serotonergic and hormonal portfolios while mid-size developers target intranasal delivery white space. Three archetypes dominate: neuroscience-integrated conglomerates with psychiatric infrastructure, hormonal therapy specialists leveraging contraceptive expertise, and rapid-onset delivery innovators. Competitive moves center on portfolio diversification into dual-product maintenance-rescue regimens and strategic partnerships with proliferating women's health clinic networks.
Within the neuroscience-integrated tier, Eli Lilly and Company and Pfizer Inc. occupy positions reflecting established psychiatric portfolio breadth and hospital access infrastructure. Bayer AG exemplifies the hormonal intervention archetype through spanning contraceptive and therapeutic applications. These three firms represent divergent strategic anchors: serotonergic modulation expertise, broad psychiatric formulary integration, and endocrine-based cyclical symptom suppression.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Eli Lilly and Company |
| Bayer AG |
| GlaxoSmithKline plc |
| Teva Pharmaceutical Industries Ltd. |
| Novartis AG |
| Merck & Co., Inc. |
| AbbVie Inc. |
| Bristol-Myers Squibb Company |
| Others |
Value Network & Pricing Analysis
Generic SSRI substitution for branded serotonergic therapies is compressing pricing power while simultaneously shifting API sourcing toward concentrated Asian manufacturing clusters and away from European fermentation facilities.
Pricing Analysis
Hospital formulary buyers anchor three-tier pricing stratification across premium intranasal rescue therapies, standard branded oral maintenance regimens, and economy generic SSRI fulfillment. Price differentiation hinges on FDA PMDD-specific labeling tier and volume scale through pharmacy benefit manager negotiations. Pricing pressure intensifies in the oral maintenance segment as generic fluoxetine and sertraline availability expands. Retail pharmacy channels exhibit highest price sensitivity; hospital psychiatric departments maintain lowest sensitivity due to institutional reimbursement frameworks.
Supply Chain Analysis
India and China anchor active pharmaceutical ingredient production for serotonergic compounds, while Japan maintains domestic fermentation capabilities for specialized serotonin modulators. Synthetic progestin feedstocks for hormonal interventions draw from petrochemical suppliers in Germany and the United States. Single-source vulnerability concentrates in specific Asian manufacturing clusters for SSRI precursors. Distribution runs through hospital procurement systems, specialty pharmacy networks, and direct-to-patient telehealth platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sustains defensive moats through regulatory entrenchment, where FDA PMDD-specific labeling requirements create multi-year barriers to generic substitution for novel delivery mechanisms.
For Market Incumbents: Fortify formulary access through dual-product portfolios spanning oral maintenance and intranasal rescue modalities. Deepen hospital psychiatric department relationships against emerging delivery innovators. Secure backward integration into API supply through partnerships with Indian and Chinese manufacturers to mitigate geopolitical exposure. Prioritize certification investment for HIPAA-compliant digital therapeutics platforms. For New Entrants and Emerging Players: Lead with intranasal rapid-onset formulations targeting acute luteal-phase functional impairment, the most penetrable white space with limited direct competition. Target specialized women's health clinic networks in United States metropolitan corridors for prescription channel access. Deploy algorithmic symptom-tracking platforms with asynchronous clinician dashboards as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward rapid-onset delivery innovators with FDA-submitted intranasal formulations and established women's health clinic partnerships. Long-term viability favors developers bridging maintenance-rescue protocol bifurcation. Monitor EMA centralized assessment pathway convergence with FDA timelines as the critical inflection signal for European market entry acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Intranasal Formulation Development | Rapid-onset delivery addresses acute luteal-phase rescue needs with limited competitor presence. |
| Digital Therapeutics Integration | HIPAA-compliant cycle tracking enables algorithmic treatment optimization and remote monitoring scale. |
| Women's Health Clinic Partnerships | Specialized clinic networks bypass crowded hospital formulary competition for prescription generation. |
| API Supply Security Investment | Backward integration into Indian and Chinese manufacturing mitigates geopolitical supply disruption risks. |
| Regulatory Pathway Convergence | EMA-FDA alignment strategies compress European market entry timelines for novel mechanisms. |
Research Methodology
Desk research of FDA filings, ClinicalTrials.gov protocols, EMA assessment reports, and hospital formulary databases preceded structured interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists. Primary fieldwork captured prescription pattern dynamics across hospital psychiatric departments and specialized women's health clinics. Secondary validation drew from SEC 10-K pharmaceutical disclosures and CMS Medicare reimbursement data. Bottom-up patient population estimates and top-down pharmaceutical revenue triangulation anchored market sizing.
Variance decomposition across product mechanism, delivery mode, end-user setting, and regional regulatory cluster shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include serotonergic versus hormonal first-line positioning, oral versus intranasal administration route, and hospital versus homecare prescribing location. CAGRs were derived from fitted growth curves against historical prescription volume trajectories and pipeline progression timelines. Forecast inputs incorporated DSM-5 diagnostic specificity upgrade adoption curves and telehealth infrastructure penetration rates.
The analysis sits within stated boundaries; outcomes outside sustained FDA reproductive mental health guidance enforcement or accelerated EMA pathway convergence would require recalibration. Forecasts reflect assumptions regarding payer policy stabilization on hormonal versus serotonergic first-line positioning and synthetic progestin feedstock cost volatility containment. Recalibration cycles align with material shifts in regulatory guidance, biomarker panel validation, and telehealth reimbursement frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Aarskog Syndrome Treatment Market
Specialty Medicine
Polycystic Kidney Disease Treatment Market
Specialty Medicine
Transient Ischemic Attack Market
Specialty Medicine
Global Axial Spondyloarthritis (Axspa) Market
Specialty Medicine
Cerebral Palsy Market
Specialty Medicine
Idiopathic Pulmonary Fibrosis (IPF) Market
Specialty Medicine
Pigmentosa Treatment Market
Specialty Medicine
Rhabdomyosarcoma Treatment Market
Specialty Medicine
Head and Neck Cancer Therapeutics Market
Specialty Medicine
Animal Hormone Therapy Market
Specialty Medicine
Cerebral Vasospasm Market
Specialty Medicine
Dyschromia Therapeutics Market
Specialty Medicine
Latin America Bladder Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Tonsil Cancer Market
Specialty Medicine
Tropical Spastic Paraparesis Market
Specialty Medicine
Global Endometriosis Treatment Market