
 Blood Bank Refrigerators Market | 2026-2036
Blood Bank Refrigerators Market Size, Share, and Industry Trends Forecast 2026-2036
Blood Bank Refrigerators Market Analysis
IoT-enabled remote temperature monitoring is reshaping blood bank refrigerator architecture, replacing standalone units with networked cold-chain nodes. Thermo Fisher Scientific Inc. leverages its laboratory instrumentation heritage to integrate sensor telemetry across hospital networks. Helmer Scientific anchors North American manufacturing with FDA-validated designs for blood centers. Haier Smart Home Co. Ltd. dominates Asian supply through scale production of dual-stage compression systems.
Blood bank refrigerators are precision cooling appliances engineered to maintain temperatures between 1°C and 6°C with alarm-triggered deviation protocols, preserving erythrocyte viability for transfusion medicine. Units employ forced-air circulation, insulated cabinet construction, and digital data logging to meet biological material storage standards. Ultra-low temperature freezers command premium positioning as plasma and cryoprecipitate storage expands, while the 200-300 liter capacity tier captures the highest hospital procurement volume due to ward-scale footprint optimization. Laboratory refrigerators trail in growth velocity as blood banks and donation centers prioritize dedicated units over general-purpose cold storage.
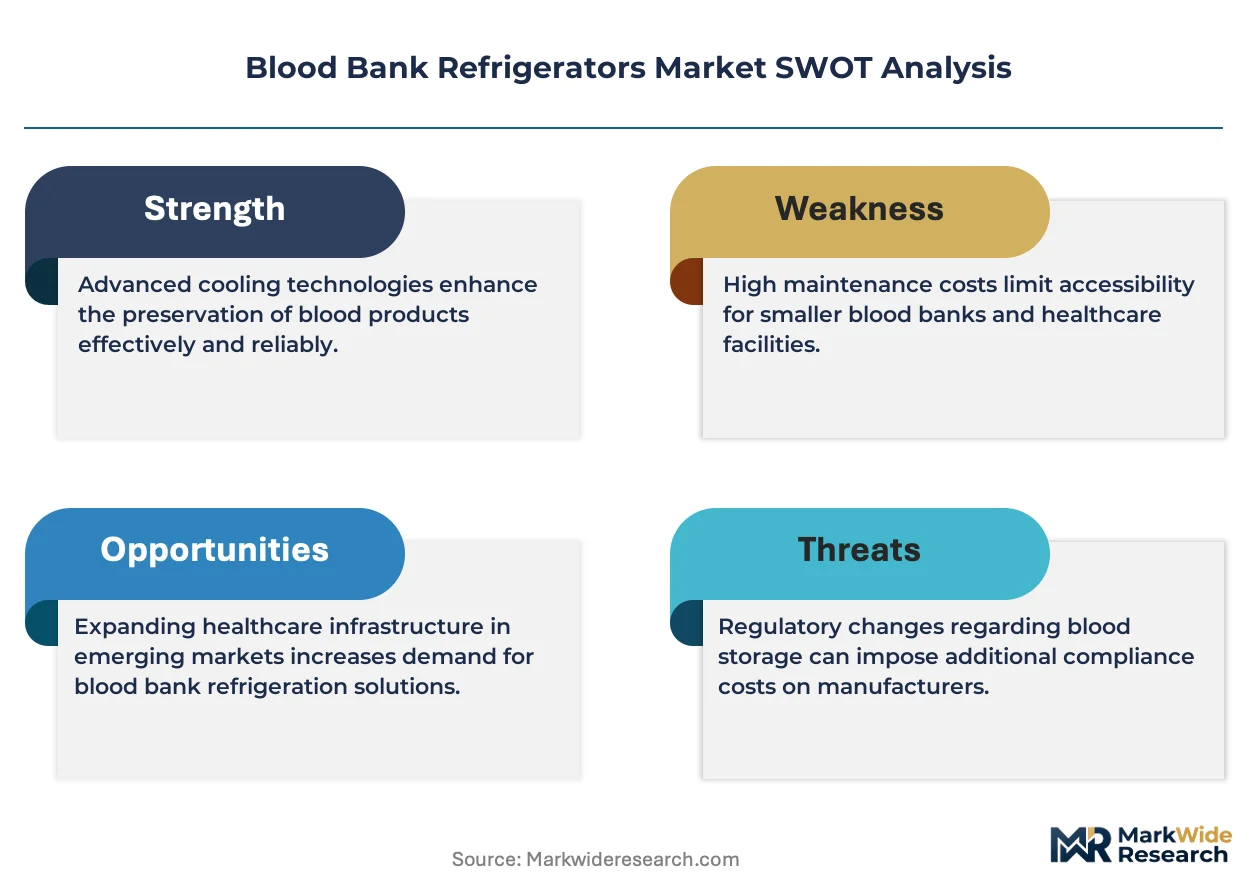
FDA 21 CFR Part 820 quality system regulation and AABB standards govern device validation and temperature documentation, compelling manufacturers to embed redundant sensors and audit-trail software. The EU MDR and CE marking framework impose post-market surveillance obligations that extend compliance costs for European distribution. Stakeholders must weigh refrigerant transition timelines against compressor technology investments as F-Gas regulation and EPA SNAP program restrictions phase down hydrofluorocarbon compounds.
Market Dynamics
IoT-enabled remote temperature monitoring is collapsing the traditional standalone refrigerator model into networked cold-chain nodes, forcing manufacturers to reengineer hardware architectures around sensor telemetry and hospital network integration rather than isolated mechanical cooling.
Growth Catalysts
- FDA 21 CFR Part 820:Quality system regulations mandate continuous temperature documentation and redundant sensor systems, compelling blood centers to upgrade legacy units with validated alarm protocols.
- Plasma fractionation expansion:Cryoprecipitate and plasma-derived therapeutic manufacturing is driving procurement of ultra-low temperature freezers alongside standard blood bank refrigerators.
- Japan transfusion infrastructure:METI-supported hospital modernization programs prioritize dedicated blood storage over general-purpose laboratory cold equipment.
Market Restraints
- Hydrofluorocarbon phase-down:EPA SNAP program and EU F-Gas Regulation restrictions on HFC refrigerants force compressor technology transitions before amortization cycles complete.
- Stainless steel and copper volatility:Insulated cabinet construction depends on metal inputs subject to commodity price swings that compress manufacturing margins.
- Validation documentation burden:AABB standards require extensive temperature mapping studies that extend sales-to-commissioning timelines and strain hospital capital planning.
Strategic Opportunities
- India blood banking modernization:CDSCO facility registration requirements and expanding transfusion medicine infrastructure create first-mover advantage for compliant equipment suppliers.
- Blockchain-IoT convergence:Immutable temperature logging paired with real-time telemetry enables outcome-based service contracts that shift revenue from capital sales to uptime guarantees.
- German hospital network consolidation:Centralized procurement by large Klinikum groups favors vendors offering fleet management software and remote diagnostics.
Industry Challenges
- Biomedical equipment technician shortage:FDA-validated calibration and alarm testing requires specialized training that hospital engineering departments struggle to staff.
- Legacy BAS integration:Building automation system protocols vary across hospital vintages, forcing custom middleware development for networked refrigerator deployment.
- CE marking transition under EU MDR:Post-market surveillance obligations and notified body capacity constraints delay European market entry for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blood Bank Refrigerators Market |
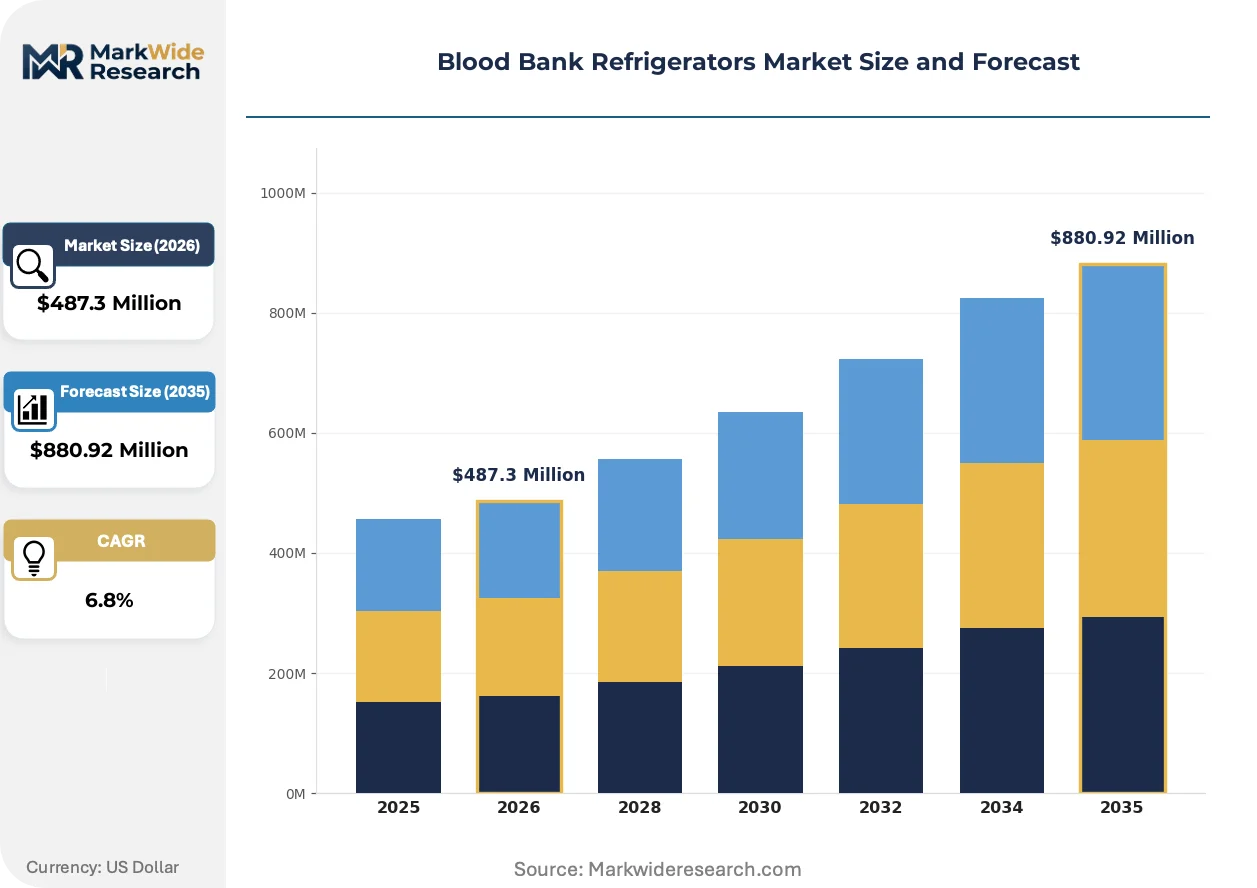
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blast Freezers, Ultra-Low Temperature Freezers, Cryogenic Freezers, Laboratory Refrigerators Capacity: Below 100 Liters, 100-200 Liters, 200-300 Liters, Above 300 Liters End User: Hospitals, Blood Donation Centers, Research Institutes, Blood Banks Technology: Single Stage, Dual Stage, Cascade, Magnetic |
| Companies Covered | Azenta US, Inc, Helmer Scientific, Thermo Fisher Scientific Inc., Liebherr International AG, Follett Corporation, Haier Smart Home Co. Ltd., ARCTIKO AS, Eppendorf SE, PHC Holdings Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blood Bank Refrigerators Market Emerging Trajectories
Sensor telemetry and predictive maintenance algorithms are transforming blood bank refrigerators from passive storage vessels into active data nodes within hospital cold-chain infrastructure. Three developments dominate current engineering priorities.
Solid-state cooling based on thermoelectric modules is collapsing the traditional compressor-dependent architecture in mid-capacity units. Blood centers in Japan and Germany are piloting these systems for reduced vibration and precise temperature stability. The technology is collapsing preventive maintenance schedules and extending erythrocyte viability margins through tighter thermal control.
EU F-Gas Regulation phase-down schedules are accelerating natural refrigerant adoption across European manufacturing. Hydrocarbon and CO2 cascade systems now dominate new platform development, with CE marking timelines adjusted to accommodate safety testing protocols. Ultra-low temperature plasma freezers face the steepest redesign requirements given energy density demands.
Hospital group purchasing organizations are consolidating supplier relationships around vendors offering integrated fleet management platforms. Blood bank directors now prioritize remote diagnostics and automated audit trails over standalone mechanical specifications. This consolidation is most visible in United States health system networks where centralized biomedical engineering departments manage multi-site refrigerator deployments.
Blood Bank Refrigerators Market Segmentation
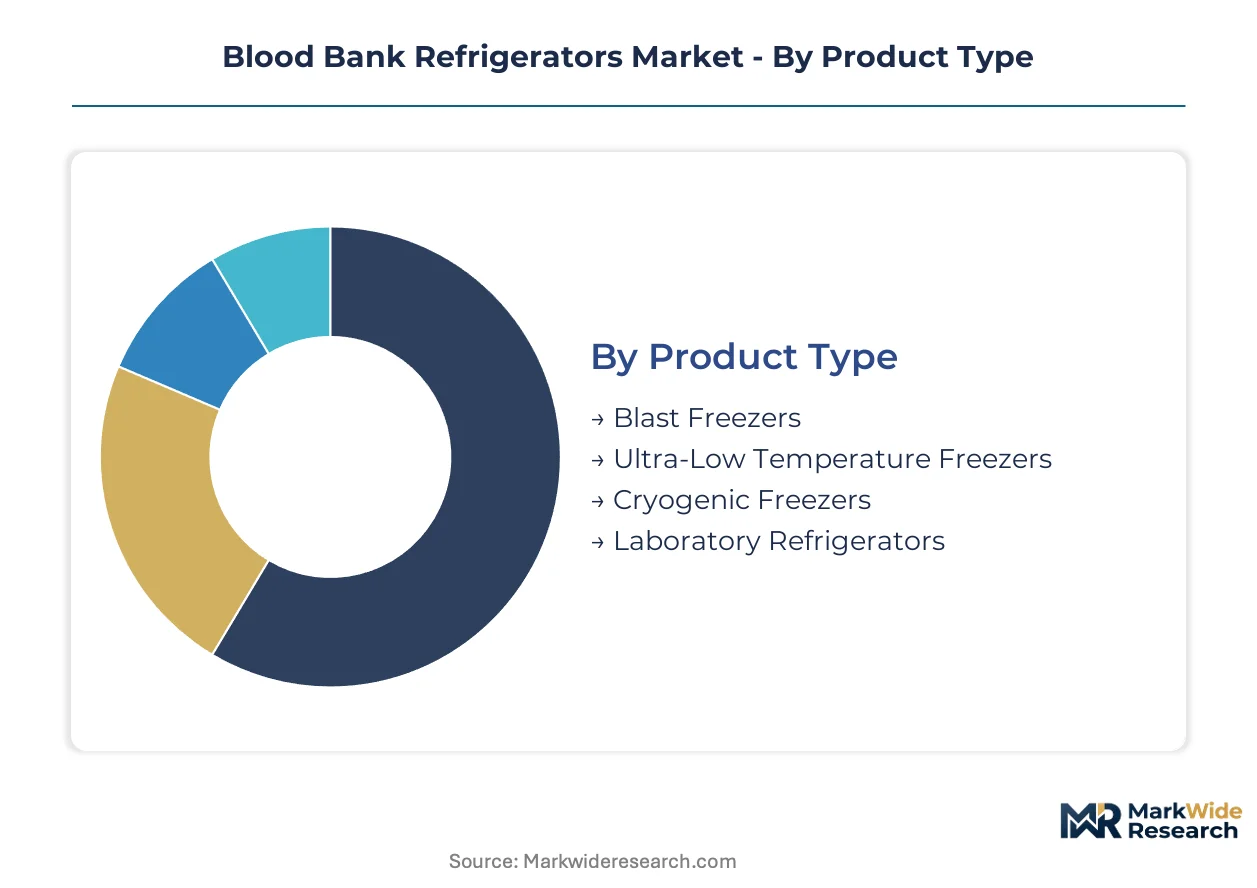
Blood bank refrigerator procurement varies sharply across installation settings, with hospital biomedical engineering departments demanding networked fleet management while blood donation centers prioritize standalone reliability. Segmentation reveals how regulatory validation requirements and capacity constraints reshape vendor positioning across distinct buyer archetypes.
Product Type:
After-sales service intensity escalates with cooling depth, as ultra-low temperature platforms require specialized technician certification and refrigerant handling protocols that standard blood bank units do not.
- Ultra-Low Temperature Freezers:Cascade compressor architectures achieve temperatures below -40°C for plasma and cryoprecipitate preservation. Blood centers in Germany and Japan are expanding procurement of these units as fractionation-derived therapeutic manufacturing scales, though EPA SNAP refrigerant restrictions are compressing design timelines.
- Blast Freezers:Rapid cooling systems with forced-air circulation reduce erythrocyte metabolic activity within minutes of collection. Hospital blood banks in the United States prioritize these for trauma center emergency reserves, where FDA 21 CFR Part 820 validation documentation extends commissioning cycles.
- Cryogenic Freezers:Liquid nitrogen or mechanical systems reaching -150°C serve rare cell therapy applications.
- Laboratory Refrigerators:General-purpose cold storage units without blood-specific alarm protocols.
By volume, Laboratory Refrigerators lead. By growth pace, Ultra-Low Temperature Freezers are gaining share fastest.
Capacity:
Footprint optimization drives procurement economics, with ward-scale installations favoring mid-capacity units that balance storage density against biomedical engineering space constraints.
- 200-300 Liters:Forced-air circulation cabinets with digital data logging dominate hospital ward deployments. This tier captures the highest procurement volume in the United States as health system networks standardize fleet specifications across multi-site blood storage operations.
- Below 100 Liters:Countertop and under-counter units serve satellite clinics and emergency department trauma bays. Blood donation centers in Japan deploy these for mobile collection vehicles where METI-supported infrastructure modernization prioritizes compact validated cooling.
- 100-200 Liters:Intermediate footprint for mid-sized blood banks and regional hospital laboratories.
- Above 300 Liters:Central blood bank and plasma fractionation facility scale requiring redundant compressor systems.
By installed base, 200-300 Liters holds the largest share. By expansion trajectory, Below 100 Liters is climbing the fastest.
End User:
Buyer sophistication stratifies sharply, with hospital centralized procurement departments demanding integrated fleet software while independent blood banks prioritize standalone mechanical reliability.
- Hospitals:Multi-site health system networks in the United States are consolidating supplier relationships around vendors offering remote diagnostics and automated audit trails. FDA-mandated temperature documentation compels upgrade cycles for legacy units lacking networked sensor telemetry.
- Blood Donation Centers:Independent collection facilities prioritize validated alarm protocols and redundant cooling circuits over connectivity features. AABB standards require extensive temperature mapping studies that strain capital planning timelines.
- Blood Banks:Central storage and distribution hubs with high-throughput inventory rotation requirements.
- Research Institutes:Academic and clinical trial sites with specialized cell therapy preservation protocols.
By revenue concentration, Hospitals dominate. By procurement velocity, Blood Donation Centers are expanding most quickly.
Technology:
Compressor architecture selection determines refrigerant compliance pathways, with EU F-Gas Regulation phase-down schedules accelerating transitions away from hydrofluorocarbon-dependent designs.
- Dual Stage:Two-step compression systems with intermediate cooling deliver precise temperature stability for erythrocyte viability. Haier Smart Home Co. Ltd. dominates Asian supply through scale production of these platforms, with natural refrigerant variants now entering European certification pipelines.
- Cascade:Stacked independent refrigeration circuits achieve ultra-low temperatures for plasma preservation. Thermo Fisher Scientific Inc. leverages laboratory instrumentation heritage to integrate these systems with hospital network telemetry, though redesign requirements for hydrocarbon and CO2 alternatives are extending CE marking timelines.
- Single Stage:Standard compression for basic blood bank temperature maintenance.
- Magnetic:Emerging solid-state cooling based on magnetocaloric effect, currently piloted in Japan and Germany for reduced vibration applications.
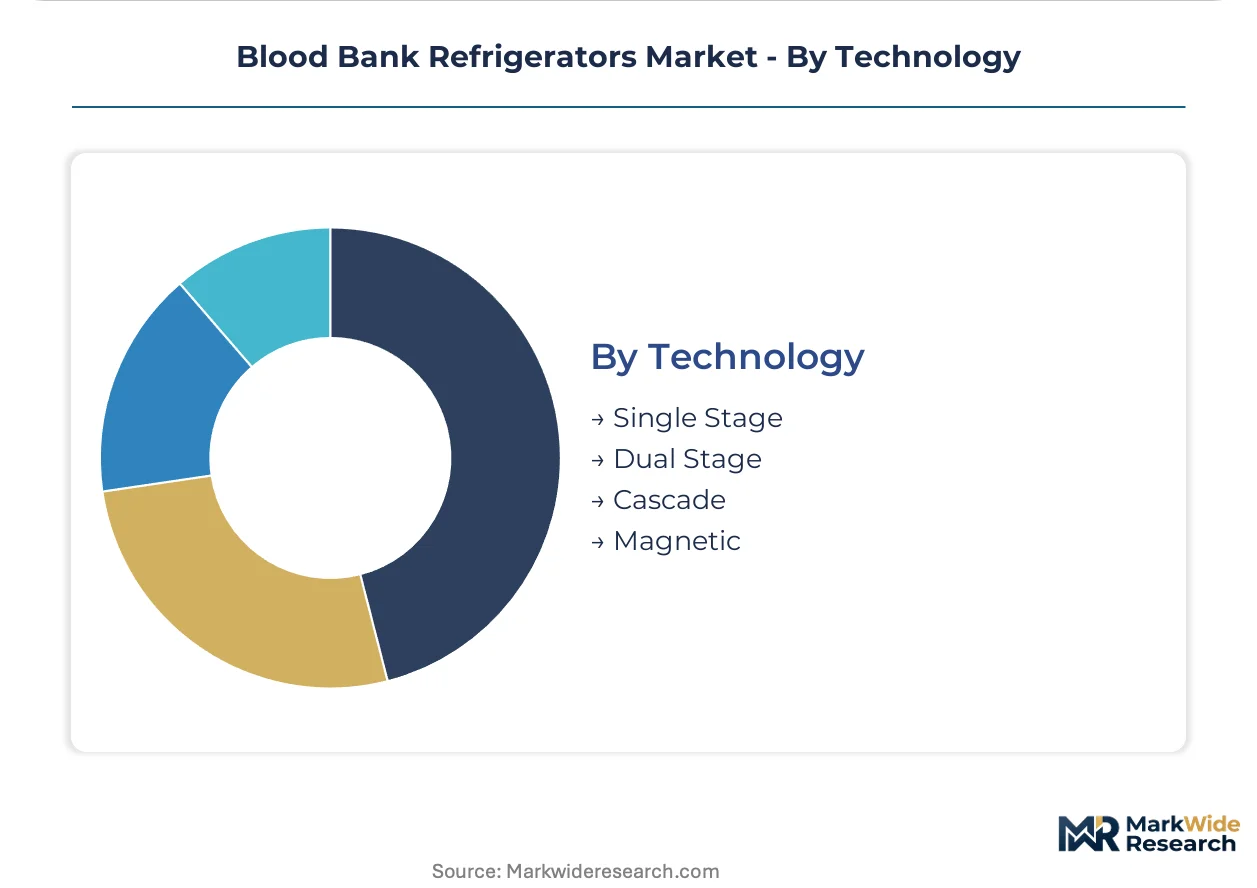
By deployment scale, Dual Stage leads. By technology transition momentum, Cascade systems face the steepest redesign requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export precision-engineered blood bank refrigerators to hospital networks across the United States and Japan, establishing the primary trade corridor for validated cold-chain equipment.
United States
FDA 21 CFR Part 820 quality system regulations compel blood centers to upgrade legacy units with continuous temperature documentation and redundant sensor systems. Hospital biomedical engineering departments in the United States prioritize networked fleet management platforms that integrate with building automation systems. The Boston-Cambridge medical technology cluster anchors domestic procurement concentration, with health system networks standardizing specifications across multi-site blood storage operations.
Germany
Large Klinikum hospital groups drive centralized procurement of ultra-low temperature freezers for plasma fractionation expansion. EU F-Gas Regulation phase-down schedules accelerate natural refrigerant adoption, compressing redesign timelines for compressor-dependent architectures. The Baden-Württemberg industrial corridor hosts manufacturing facilities serving European blood centers with CE-marked equipment incorporating hydrocarbon and CO2 cascade systems.
Japan
METI-supported hospital modernization programs prioritize dedicated blood storage units over general-purpose laboratory cold equipment. Blood donation centers deploy compact validated cooling systems for mobile collection vehicles serving rural prefectures. The Kanto region surrounding Tokyo concentrates transfusion medicine infrastructure investment, with academic medical centers piloting solid-state thermoelectric cooling modules for reduced vibration applications.
India
CDSCO facility registration requirements and expanding transfusion medicine infrastructure create procurement opportunities for compliant equipment suppliers. State-level blood bank modernization initiatives in Maharashtra and Karnataka prioritize temperature-controlled storage units meeting international validation standards. The Delhi-NCR corridor emerges as a distribution hub for imported cold-chain equipment serving northern Indian hospital networks.
United Kingdom
NHS Blood and Transplant procurement frameworks emphasize automated audit trails and remote diagnostics for centralized blood bank operations. Post-Brexit regulatory alignment with EU MDR extends CE marking recognition timelines for new equipment introductions. The Cambridge-Oxford-London life sciences triangle concentrates research institute demand for cryogenic preservation systems supporting cell therapy applications.
Blood Bank Refrigerators Market Vendor Landscape
Channel-controlling players compete with product-specialist players for procurement contracts across hospital networks and independent blood donation centers. The market exhibits tiered concentration, with laboratory instrumentation conglomerates anchoring premium positioning while regional manufacturers capture volume through standardized platform production. Three archetypes dominate: precision cooling specialists with FDA-validated designs, diversified life sciences conglomerates leveraging hospital network integration, and scale-oriented appliance manufacturers optimizing production economics. Competitive dynamics center on technology licensing agreements for natural refrigerant compressor systems and strategic partnerships with group purchasing organizations.
Among diversified life sciences conglomerates, Thermo Fisher Scientific Inc. exemplifies the hospital network integration archetype, while Helmer Scientific occupies a position within the precision cooling specialist tier. Haier Smart Home Co. Ltd. anchors the scale-oriented manufacturing archetype through volume production capabilities. These three entities collectively represent the competitive positioning spectrum visible across procurement decisions in transfusion medicine infrastructure.
| Leading Market Players |
|---|
| Azenta US, Inc |
| Helmer Scientific |
| Thermo Fisher Scientific Inc. |
| Liebherr International AG |
| Follett Corporation |
| Haier Smart Home Co. Ltd. |
| ARCTIKO AS |
| Eppendorf SE |
| PHC Holdings Corp. |
| Others |
Supply Flow & Price Mechanics
The Baden-Württemberg industrial corridor anchors European manufacturing capacity for precision cooling systems, with its compressor technology cluster translating upstream component access into pricing leverage for validated blood bank equipment. German manufacturers command premium positioning through FDA-validated designs while Asian scale producers compress mid-tier pricing through dual-stage compression platform standardization.
Pricing Analysis
Next-generation solid-state thermoelectric modules command substantial premiums over conventional compressor-dependent architectures, while legacy single-stage systems face price erosion from refrigerant transition mandates. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated fleet management platforms from basic alarm-compliant units and non-validated laboratory alternatives. Pricing pressure stems from EU F-Gas Regulation compliance costs accelerating redesign cycles before equipment amortization completes. Blood donation centers exhibit highest price sensitivity due to capital planning constraints, while United States hospital networks prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Contract manufacturing for compressor systems concentrates among specialized industrial refrigeration foundries in Germany, Japan, and China, with final assembly and validation testing retained by branded equipment vendors. Stainless steel cabinet fabrication and copper refrigerant tubing draw from metal processors subject to commodity volatility. Single-source vulnerability in specialized sensor telemetry modules creates procurement risk for IoT-enabled platform rollouts. Distribution runs through biomedical equipment distributors serving hospital procurement departments and direct sales teams for blood center networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The blood bank refrigerator market functions as a defensive-moat sector where FDA 21 CFR Part 820 validation requirements and AABB certification standards create entrenched switching costs that protect incumbent positioning.
For Market Incumbents: Entrench market position through backward integration into sensor telemetry module production, securing supply chain control over IoT-enabled fleet management components. Accelerate natural refrigerant platform certification ahead of EU F-Gas phase-down deadlines to capture replacement demand from compliance-driven upgrade cycles. Compressor technology transitions represent the primary margin threat; vertical control over refrigerant system engineering offsets this pressure.
For New Entrants and Emerging Players: Pursue white-space opportunity in India's CDSCO-registered blood bank modernization, where transfusion infrastructure expansion outpaces established vendor presence. Target compact below-100-liter validated cooling systems for mobile collection vehicles, a segment where METI-supported Japanese programs demonstrate procurement velocity. Go-to-market through regional biomedical equipment distributors with established hospital relationships accelerates validation documentation acceptance.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-entrenchment play because FDA and AABB validation requirements create durable barriers that compound with each equipment generation transition. Acquisition focus should center on precision cooling specialists with established notified body relationships and active CE marking pipelines under EU MDR. Monitor refrigerant technology patent filings as the inflection signal for next-generation platform leadership.
| Strategic Initiative | Industry Significance |
|---|---|
| Natural Refrigerant Platform Development | EU F-Gas Regulation compliance secures European market access through hydrocarbon and CO2 cascade systems. |
| IoT Fleet Management Software Integration | Remote diagnostics capability meets United States health system network consolidation procurement requirements. |
| FDA 21 CFR Part 820 Validation Investment | Quality system documentation enables blood center upgrade cycles and replacement revenue capture. |
| India Distribution Partnership Establishment | CDSCO facility registration support positions vendors for state-level blood bank modernization initiatives. |
| Solid-State Thermoelectric Cooling Pilot | Reduced vibration applications in Japanese academic medical centers open premium positioning pathways. |
Methodological Framework
Cross-validation between primary interviews with blood bank directors, biomedical engineering managers, GPO contracts specialists, and regulatory affairs leads anchors the qualitative findings against secondary validation. FDA 510(k) filings, AABB accreditation databases, EU MDR notified body certificates, and hospital procurement contract disclosures provide regulatory and commercial benchmarks. Bottom-up equipment shipment analysis triangulates against top-down healthcare infrastructure spending patterns across transfusion medicine networks.
Calibration against historical validation timelines and refrigerant transition schedules shapes the projection framework across the analysis window. Segmentation modeling incorporates product type cooling depth, capacity tier footprint economics, end-user procurement sophistication, and compressor technology compliance pathway. CAGR derivation reflects equipment replacement cycles, regulatory mandate effective dates, and plasma fractionation capacity expansion announcements without year-specific anchoring.
Macroeconomic conditions sit as an overlay; deviation in healthcare capital expenditure budgets, biomedical equipment technician labor availability, or copper and stainless steel commodity indices would shift the trajectory. Quarterly review of FDA warning letter trends, notified body capacity announcements, and blood center consolidation activity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Portable Beds Market
Medical Equipment
Medical Gas Cylinders Market
Medical Equipment
Surgical Generators Market
Medical Equipment
Operating Table Market
Medical Equipment
Hybrid Operating Room Market
Medical Equipment
Refurbished Medical Equipment Market
Medical Equipment
Global Medical Vacuum System Market
Medical Equipment
Medical Suction Units Market
Medical Equipment
US Biomedical Refrigerators and Freezers Market
Medical Equipment
Medical Oxygen Concentrators and Oxygen Cylinders Market
Medical Equipment
Medical Equipment Maintenance Market
Medical Equipment
Medical Equipment Rental Market
Medical Equipment
Medical Ultrasonic Cleaners Market
Medical Equipment
Medical Oxygen Systems Market
Medical Equipment
Proton and Ion Beam Therapy Dosimetry and QA Test Equipment Market
Medical Equipment
Mercury Thermometer Market