
 Global Platelet Agitator Market | 2026-2036
Global Platelet Agitator Market Size, Share, and Industry Trends Forecast 2026-2036
Global Platelet Agitator Market Foresight
China's manufacturing base for precision laboratory equipment is fragmenting as domestic suppliers scale capacity alongside established multinationals. Thermo Fisher Scientific leverages its cryopreservation expertise to extend control over adjacent temperature-controlled workflows. Sarstedt AG & Co. KG anchors European distribution through specialized cold-chain logistics partnerships. Helmer Scientific differentiates via integrated monitoring systems that compete on traceability compliance.
Platelet agitators are electromechanical devices that maintain platelet concentrates in continuous gentle motion at controlled temperatures to preserve viability for transfusion, typically operating at 22°C with agitation rates calibrated to prevent aggregation. Rotary agitators dominate hospital blood banking due to proven reliability in high-volume processing environments, while portable devices represent the fastest-expanding deployment type as point-of-care transfusion protocols decentralize storage requirements. Research laboratories sustain steady demand for benchtop units with programmable motion profiles supporting protocol customization.
FDA blood component storage guidelines, EU MDR device classification requirements, and WHO blood safety standards collectively shape product validation burdens and market access pathways for manufacturers. The EU AI Act introduces emerging compliance dimensions for smart agitators with predictive maintenance algorithms. Stakeholders must monitor regulatory divergence between FDA 510(k) pathways and EU notified body expectations when prioritizing geographic launch sequencing.
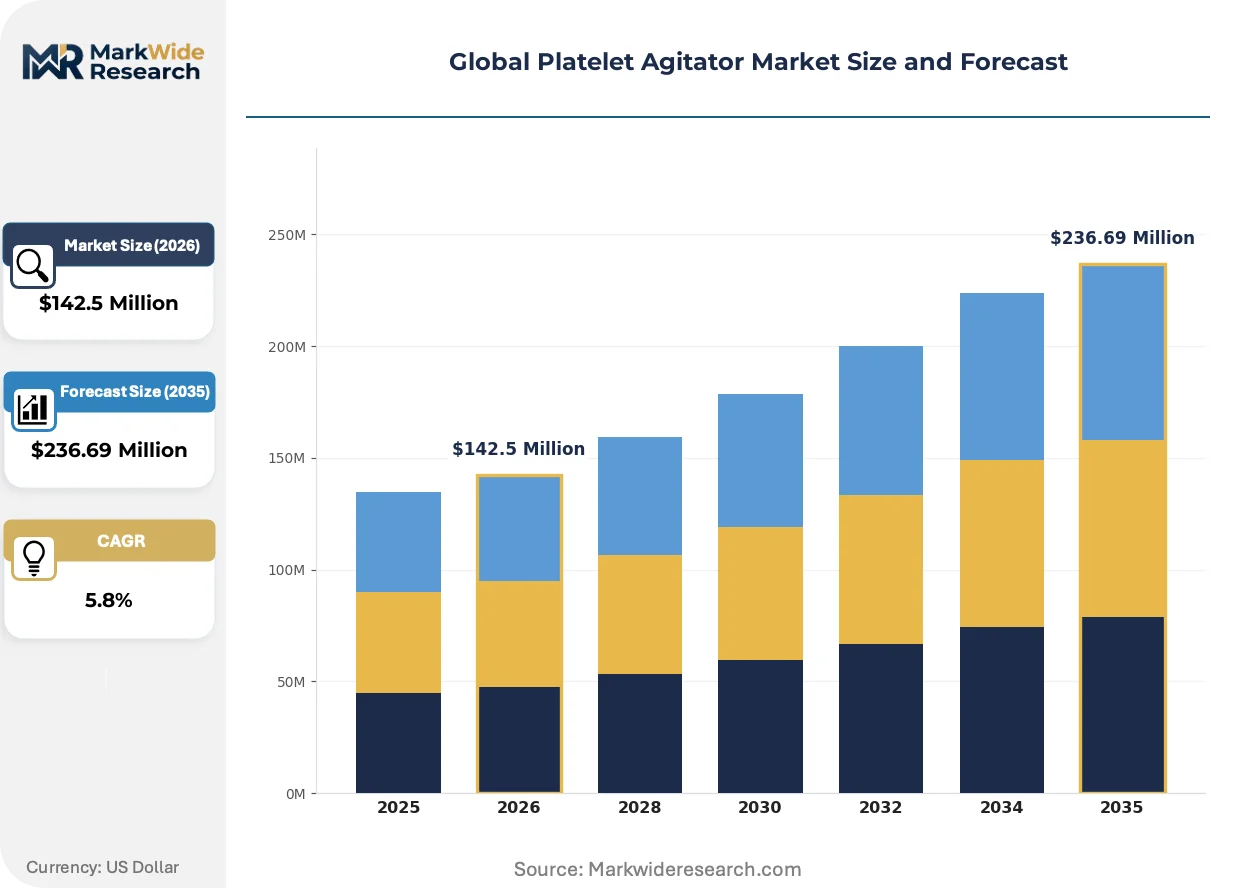
Market Dynamics
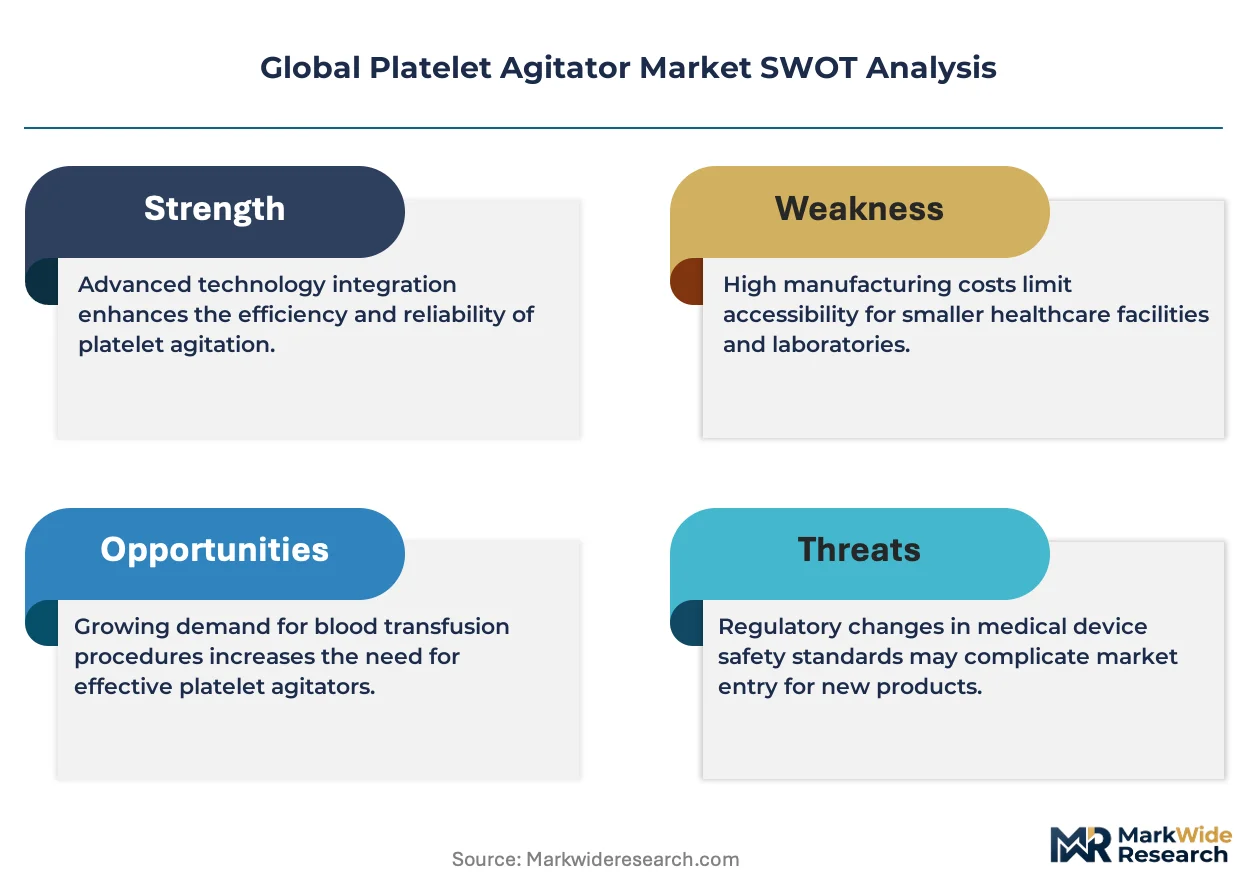
EU MDR device classification requirements are compressing validation timelines for platelet agitator manufacturers, forcing simultaneous compliance with FDA 510(k) pathways and notified body expectations while hospital networks consolidate procurement across transfusion infrastructure upgrades.
Growth Catalysts
- EU MDR quality mandates:Blood banking facilities in Germany and France must replace legacy equipment to meet traceability and performance documentation standards, accelerating replacement cycles for rotary agitators.
- Point-of-care transfusion protocols:Decentralized storage requirements in emergency departments and surgical suites are expanding portable agitator deployment beyond centralized blood banks.
- WHO blood safety standards:National health systems across Southeast Asia and Latin America are mandating temperature-controlled agitation for platelet concentrates to reduce wastage and transfusion complications.
Market Restraints
- Precision motor and sensor input costs:Semiconductor shortages and rare earth price volatility for stepper motors and thermal sensors compress margins for mid-tier equipment suppliers.
- Dual notified body bottleneck:EU MDR designation delays at TÜV SÜD and BSI extend time-to-market for new agitator models by 12-18 months compared to pre-2021 CE marking pathways.
- Cryopreservation alternatives:Advances in platelet cryopreservation at blood centers in California and Texas threaten to displace ambient-temperature agitation for select inventory categories.
Strategic Opportunities
- India's hospital infrastructure expansion:Government-funded medical colleges and district hospitals under the Ayushman Bharat scheme lack compliant platelet storage, creating first-mover advantage for validated equipment suppliers.
- EU AI Act predictive maintenance:Smart agitators with algorithm-driven failure prediction qualify for expedited review and premium reimbursement in German and Dutch hospital networks.
- Cloud-connected monitoring convergence:Integration of IoT temperature logging with laboratory information systems enables subscription-based service models for blood bank equipment fleets.
Industry Challenges
- Biomedical equipment technician certification gaps:Specialized training for electromechanical calibration and thermal validation is scarce in secondary cities across Brazil and Mexico, limiting service network expansion.
- Legacy LIS integration complexity:Hospital blood banks in the US and UK operate fragmented software architectures that resist standardized API connectivity for real-time agitator monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Platelet Agitator Market |
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $236.69 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotary Agitators, Oscillating Agitators, Magnetic Stirred, Pneumatic Agitators, Hydraulic Agitators Application: Blood Banking, Transfusion Centers, Research Laboratories, Pharmaceutical Manufacturing, Diagnostic Facilities End User: Hospitals, Clinical Centers, Blood Banks, Biotechnology Firms, Academic Institutions Deployment Type: Benchtop Units, Portable Devices, Integrated Systems, Standalone Equipment |
| Companies Covered | Thermo Fisher Scientific, Sarstedt AG & Co. KG, Helmer Scientific, Meditech Technologies India Private Limited, Biobase, Fanem Ltda, Boekel Scientific, Labcold, Terumo Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Platelet Agitator Market Shifts & Advancements
Solid-state thermoelectric cooling is collapsing the mechanical complexity of platelet agitation systems, while regulatory frameworks in Europe and Asia-Pacific accelerate validation requirements for connected devices.
Solid-state Peltier modules are replacing compressor-based cooling in next-generation agitators, eliminating refrigerant handling and reducing maintenance intervals. Academic medical centers in Switzerland and Japan are piloting these units for satellite blood storage. This technology is collapsing the traditional distinction between laboratory-grade and clinical-grade temperature control, enabling single-platform designs across hospital and research settings.
The EU AI Act's risk classification system now captures smart agitators with predictive algorithms as high-risk medical devices. Manufacturers must submit technical documentation on algorithmic transparency and clinical validation to notified bodies in Germany and the Netherlands. Blood bank procurement committees in France and Belgium are prioritizing AI Act-compliant equipment to preempt 2026 enforcement deadlines.
Consolidated purchasing through group purchasing organizations is displacing individual hospital negotiations for agitator fleets. US hospital networks including CommonSpirit and HCA are mandating standardized equipment platforms across their transfusion services. This concentration is most visible in the southeastern United States, where regional blood centers now contract directly with manufacturers for ten-year service-inclusive agreements.
Global Platelet Agitator Market Segmentation
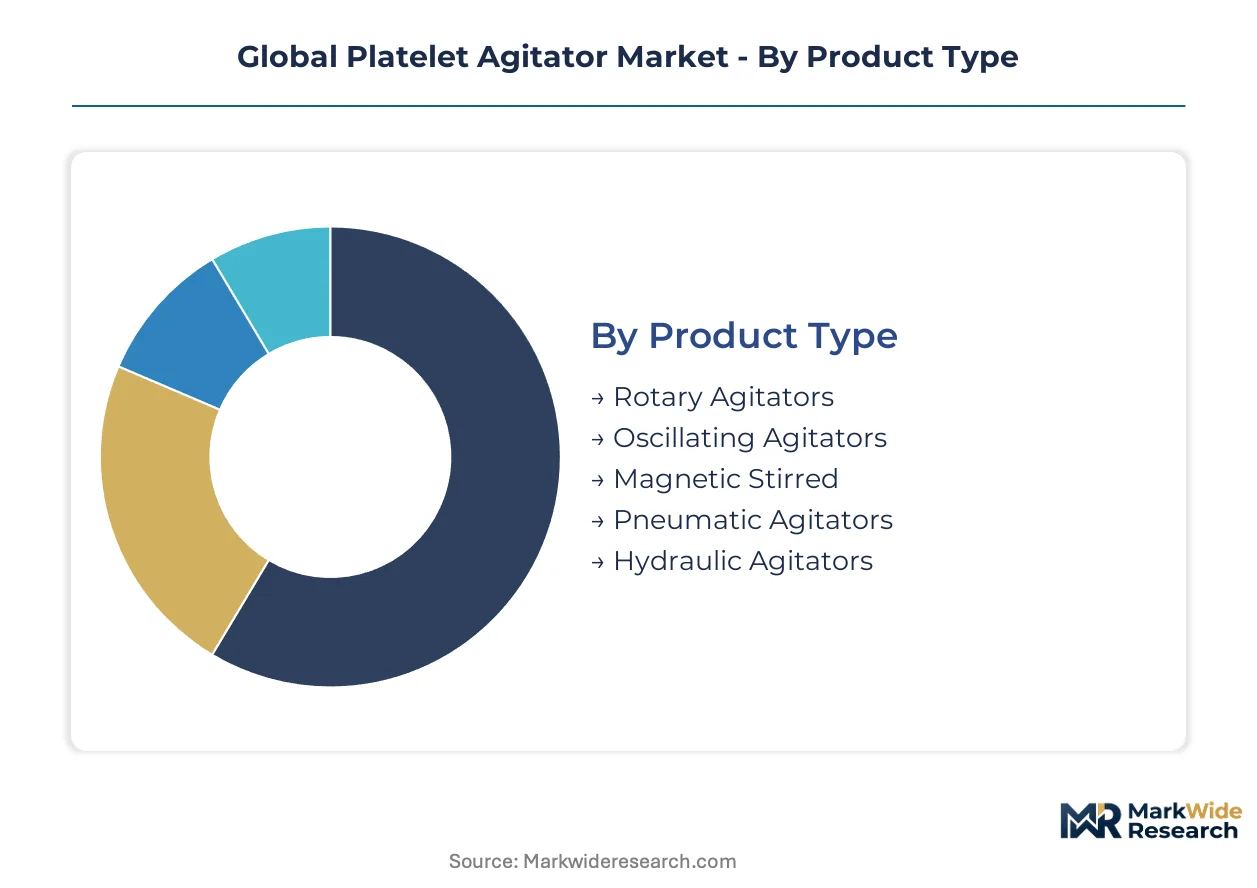
Platelet agitator procurement patterns diverge sharply across clinical versus research settings, with replacement cycles stretching from three years in high-volume transfusion centers to eight-plus years in academic laboratories. Understanding these segment-specific turnover rhythms enables suppliers to align inventory, service contracts, and regulatory filings with actual demand velocity.
Product Type:
Rotary agitators turn inventory fastest in hospital blood banks, while pneumatic and hydraulic systems linger in industrial-scale pharmaceutical settings with decade-long amortization schedules.
- Rotary Agitators:Electromechanical platforms employ continuous circular motion at calibrated speeds to prevent platelet aggregation while maintaining 22°C thermal stability. Demand concentrates in German and French hospital networks replacing legacy equipment under EU MDR traceability mandates.
- Oscillating Agitators:Reciprocal linear motion systems suit smaller-volume processing environments with gentile agitation profiles for extended storage protocols. Research laboratories in Switzerland and Japan favor these units for protocol customization where throughput requirements remain modest.
- Magnetic Stirred:Compact units deploy rare-earth magnetic couplings for silent operation in confined clinical spaces.
- Pneumatic Agitators:Compressed-air driven systems serve pharmaceutical manufacturing cleanrooms with explosion-proof requirements.
- Hydraulic Agitators:Heavy-duty platforms handle industrial-scale platelet pooling operations with minimal vibration transmission.
Rotary agitators dominate installed base. Portable configurations are where expansion concentrates.
Application:
Cost tiering separates emergency transfusion infrastructure from research instrumentation, with blood banking commanding premium pricing for validated compliance documentation.
- Blood Banking:Centralized processing facilities require high-capacity platforms with redundant temperature monitoring and automated alarm systems. US hospital networks including CommonSpirit and HCA are consolidating procurement through ten-year service-inclusive agreements.
- Transfusion Centers:Satellite facilities demand rapid-access storage with minimal footprint for same-day surgical support. Point-of-care protocols in emergency departments across Texas and California are decentralizing agitator deployment beyond traditional blood bank locations.
- Research Laboratories:Benchtop units with programmable motion profiles support protocol customization for platelet function studies.
- Pharmaceutical Manufacturing:GMP-validated systems support biologic production with batch documentation requirements.
- Diagnostic Facilities:Lower-throughput units serve reference laboratories with intermittent platelet processing needs.
Blood banking commands premium pricing tiers. Research laboratories represent the price-sensitive volume base.
End User:
Customer type determines service intensity, with hospitals demanding 24-hour technician response and academic institutions accepting depot maintenance models.
- Hospitals:Integrated health systems mandate standardized equipment platforms across transfusion services with centralized quality oversight. India's Ayushman Bharat scheme is funding medical colleges and district hospitals lacking compliant platelet storage.
- Clinical Centers:Outpatient surgical facilities require compact units for same-day procedures with rapid turnaround protocols.
- Blood Banks:Regional collection centers operate high-throughput processing lines with validated cold-chain continuity.
- Biotechnology Firms:Cell therapy developers need research-grade units with protocol flexibility for product characterization.
- Academic Institutions:University medical centers balance teaching requirements with research publication timelines.
Hospitals drive replacement demand. Biotechnology firms are climbing the fastest as cell therapy pipelines mature.
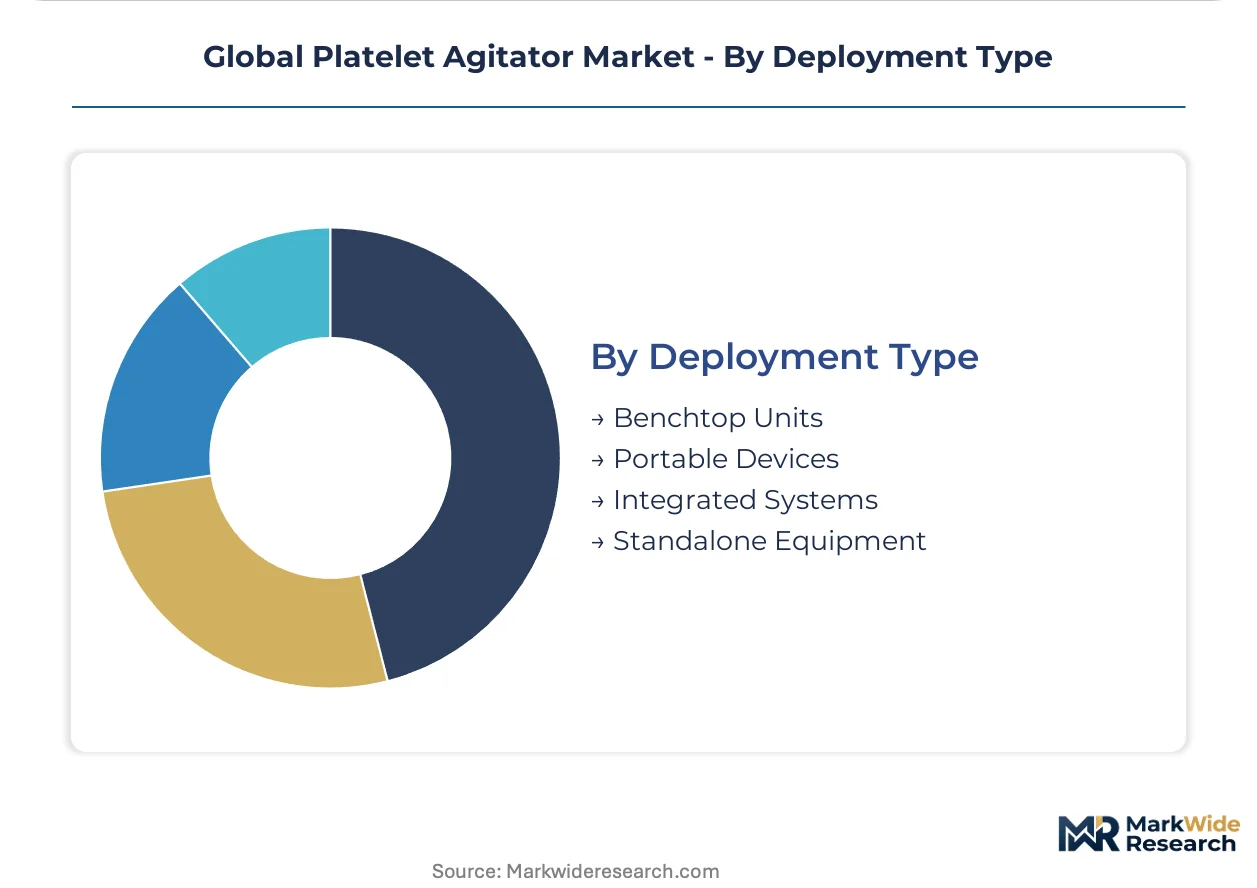
Deployment Type:
Volume concentration favors benchtop units in consolidated blood banks, while margin expansion tracks portable devices for decentralized clinical deployment.
- Benchtop Units:Fixed-installation platforms anchor centralized processing facilities with maximum capacity per square meter. Academic medical centers in Japan and Switzerland are piloting solid-state Peltier-cooled variants for satellite storage.
- Portable Devices:Battery-backed mobile units enable point-of-care transfusion in emergency departments and surgical suites. WHO blood safety standards across Southeast Asia are mandating temperature-controlled agitation to reduce wastage in resource-limited settings.
- Integrated Systems:LIS-connected platforms with IoT logging support subscription-based fleet management models.
- Standalone Equipment:Basic units serve secondary markets with limited connectivity requirements.
Benchtop units anchor revenue base. Portable devices are gaining share fastest as point-of-care protocols proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA blood component storage guidelines anchor procurement patterns in the United States, while EU MDR traceability mandates reshape equipment replacement cycles across German and French hospital networks. National health systems in India and Southeast Asia are mandating temperature-controlled agitation under WHO blood safety standards.
United States
Hospital networks including CommonSpirit and HCA are consolidating transfusion infrastructure through ten-year service-inclusive agreements for rotary agitator fleets. FDA 510(k) pathways govern validation timelines for new equipment submissions. Blood centers in California and Texas are piloting platelet cryopreservation alternatives that threaten ambient-temperature agitation for select inventory categories.
Germany
Blood banking facilities must replace legacy equipment under EU MDR quality mandates for traceability and performance documentation. TÜV SÜD and BSI designation delays extend time-to-market by 12-18 months compared to pre-2021 CE marking pathways. Procurement committees in Berlin and Munich are prioritizing AI Act-compliant smart agitators with predictive maintenance algorithms.
India
Government-funded medical colleges and district hospitals under the Ayushman Bharat scheme lack compliant platelet storage, creating first-mover advantage for validated equipment suppliers. CDSCO device registration requirements are tightening import pathways for laboratory equipment. Manufacturing clusters in Maharashtra and Karnataka are scaling domestic production of precision laboratory equipment.
Japan
Academic medical centers in Tokyo and Osaka are piloting solid-state Peltier-cooled agitators for satellite blood storage applications. PMDA quality management system inspections govern market access for foreign manufacturers. METI funding programs support next-generation cold-chain logistics infrastructure for cell therapy distribution networks.
Brazil
ANVISA biomedical equipment regulations mandate thermal validation documentation for imported agitators serving regional blood centers. Specialized training gaps for electromechanical calibration in secondary cities limit service network expansion. São Paulo and Rio de Janeiro anchor demand from consolidated hospital groups upgrading transfusion services.
Global Platelet Agitator Market Competitive Landscape
Multinational laboratory equipment conglomerates and specialized cold-chain fabricators split the market between integrated platform dominance and niche compliance expertise. Consolidated purchasing through group purchasing organizations is displacing individual hospital negotiations. Three archetypes prevail: diversified life science conglomerates with cryopreservation adjacencies, European cold-chain specialists with logistics partnerships, and precision equipment manufacturers with monitoring system integration. Geographic expansion through distribution partnerships and technology licensing for predictive maintenance algorithms represent the dominant competitive moves.
Within the diversified conglomerate tier, Thermo Fisher Scientific leverages cryopreservation expertise to extend control over adjacent temperature-controlled workflows. Sarstedt AG & Co. KG anchors European distribution positioning through specialized cold-chain logistics partnerships. Helmer Scientific occupies a differentiated position via integrated monitoring systems that compete on traceability compliance requirements.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Sarstedt AG & Co. KG |
| Helmer Scientific |
| Meditech Technologies India Private Limited |
| Biobase |
| Fanem Ltda |
| Boekel Scientific |
| Labcold |
| Terumo Corporation |
| Others |
Supply & Pricing Matrix
Maharashtra's precision equipment manufacturing clusters in India are scaling domestic agitator production capacity alongside established multinationals, compressing import premiums and redistributing pricing power toward regional distributors with localized service networks. This geographic capacity expansion interacts with semiconductor input volatility to create divergent cost trajectories across equipment tiers.
Pricing Analysis
Price spreads between German-engineered rotary agitators and Chinese-manufactured benchtop units span approximately 3:1 at equivalent capacity ratings, with premium tiers anchored by EU MDR traceability documentation and FDA 510(k) clearance status. Three-tier pricing structure across premium, standard, and economy levels separates validated hospital-grade systems from research laboratory units and unvalidated secondary market equipment. Cost compression in mid-tier rotary platforms is intensifying because rare earth magnet price volatility for stepper motors compresses margins for independent suppliers. Academic institutions and district hospitals in emerging markets exhibit highest price sensitivity, while consolidated US hospital networks prioritize total cost of ownership over acquisition price.
Supply Chain Analysis
Contract manufacturing for precision electromechanical assemblies concentrates with Foxconn, Jabil, and Flex facilities in Shenzhen, Dongguan, and Penang, which handle thermal management subsystems and motor control boards for multiple agitator OEMs. Final assembly draws from component ecosystems in Germany, Japan, and China, with Peltier modules sourced primarily from Japanese and Chinese suppliers and precision sensors from German and US vendors. Single-source vulnerability around stepper motor controllers creates exposure to foundry allocation decisions at TSMC and GlobalFoundries. Distribution runs through specialized cold-chain logistics partners in Europe and medical equipment distributors in North America, with direct manufacturer-to-hospital contracting displacing traditional dealer networks in consolidated health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The platelet agitator market functions as a regulatory entrenchment story, where EU MDR and FDA validation documentation create switching costs that protect incumbent positions against price-based competition from unvalidated alternatives.
For Market Incumbents: Insulate installed base positions by embedding predictive maintenance algorithms qualifying for EU AI Act expedited review, while acquiring specialized cold-chain logistics capabilities to capture service contract renewals. Cryopreservation advances at blood centers in California and Texas threaten displacement of ambient-temperature agitation for select inventory categories. Certification investment in CDSCO registration for India's Ayushman Bharat infrastructure expansion represents the priority defensive lever. For New Entrants and Emerging Players: Pursue white-space capture in India's district hospital tier, where government-funded medical colleges under Ayushman Bharat lack compliant platelet storage and procurement processes remain fragmented versus consolidated US networks. Portable agitator deployment for point-of-care transfusion protocols in emergency departments offers the most penetrable application segment. A software-first go-to-market angle emphasizing IoT temperature logging integration with laboratory information systems enables subscription-based revenue models that circumvent capital equipment procurement bottlenecks. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified laboratory equipment conglomerates seeking to divest non-core temperature-controlled workflow assets, particularly units with cryopreservation adjacencies that strategic buyers can integrate across blood banking product portfolios. Long-term viability over the coming decade hinges on regulatory entrenchment depth and connected device platform adoption curves. The signal to watch is consolidation velocity among US group purchasing organizations, where CommonSpirit and HCA procurement standardization creates winner-take-most dynamics for fleet contract awards.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Traceability Compliance Investment | Accelerates replacement cycles in German and French hospital networks under quality mandates. |
| Predictive Maintenance Algorithm Development | Qualifies equipment for expedited review under EU AI Act risk classification frameworks. |
| India Distribution Partnership Expansion | Captures first-mover advantage in Ayushman Bharat-funded medical college infrastructure. |
| IoT Temperature Logging Platform Integration | Enables subscription-based fleet management models for consolidated hospital networks. |
| Solid-State Peltier Cooling Technology Transition | Collapses mechanical complexity and reduces maintenance intervals for satellite storage deployment. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, hospital procurement databases, and trade flow records, combining structured interviews with blood bank directors, biomedical equipment technicians, GPO contracts managers, and cold-chain logistics specialists with validation against FDA 510(k) submissions, EU MDR technical documentation, WHO blood safety standards, and customs import data for precision laboratory equipment. Bottom-up equipment unit economics triangulate against top-down market sizing derived from hospital bed counts and transfusion service infrastructure investment patterns.
Forecast inputs span product type segmentation across rotary, oscillating, and portable configurations; application tiering between blood banking, transfusion centers, and research laboratories; end-user concentration among hospitals, blood banks, and biotechnology firms; and deployment type differentiation between benchtop and mobile units. CAGRs derive from replacement cycle analysis weighted by regulatory mandate acceleration effects and point-of-care protocol expansion trajectories. Modeling incorporates semiconductor input cost volatility, notified body designation backlog durations, and cryopreservation technology substitution elasticity.
Sensitivities concentrate around EU MDR enforcement timeline acceleration, stepper motor supply allocation disruptions, and cryopreservation viability breakthroughs at major US blood centers. Quarterly review of GPO contract award announcements, CDSCO registration application volumes, and Peltier module foundry capacity utilization is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Birthing Beds Market
Medical Equipment
Hemodialysis Equipment Market
Medical Equipment
Global Laminar Airflow Cabinets Market
Medical Equipment
Histology Embedding System Market
Medical Equipment
Medical CO2 Carboxytherapy Machine Market
Medical Equipment
Bone Marrow Processing Systems Market
Medical Equipment
Middle East and Africa Thermal Cyclers Market
Medical Equipment
Radiotherapy Motion Management Market
Medical Equipment
Medical Device and Equipment Tags Market
Medical Equipment
PMMA Healthcare Market
Medical Equipment
India Massage Equipment Market
Medical Equipment
US Radiotherapy Market
Medical Equipment
Global Portable Beds Market
Medical Equipment
Global Medical Lighting Technologies Market
Medical Equipment
Cath Lab Market
Medical Equipment
Mercury Thermometer Market