
 Residential Battery Market | 2026-2036
Residential Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Battery Market Intelligence
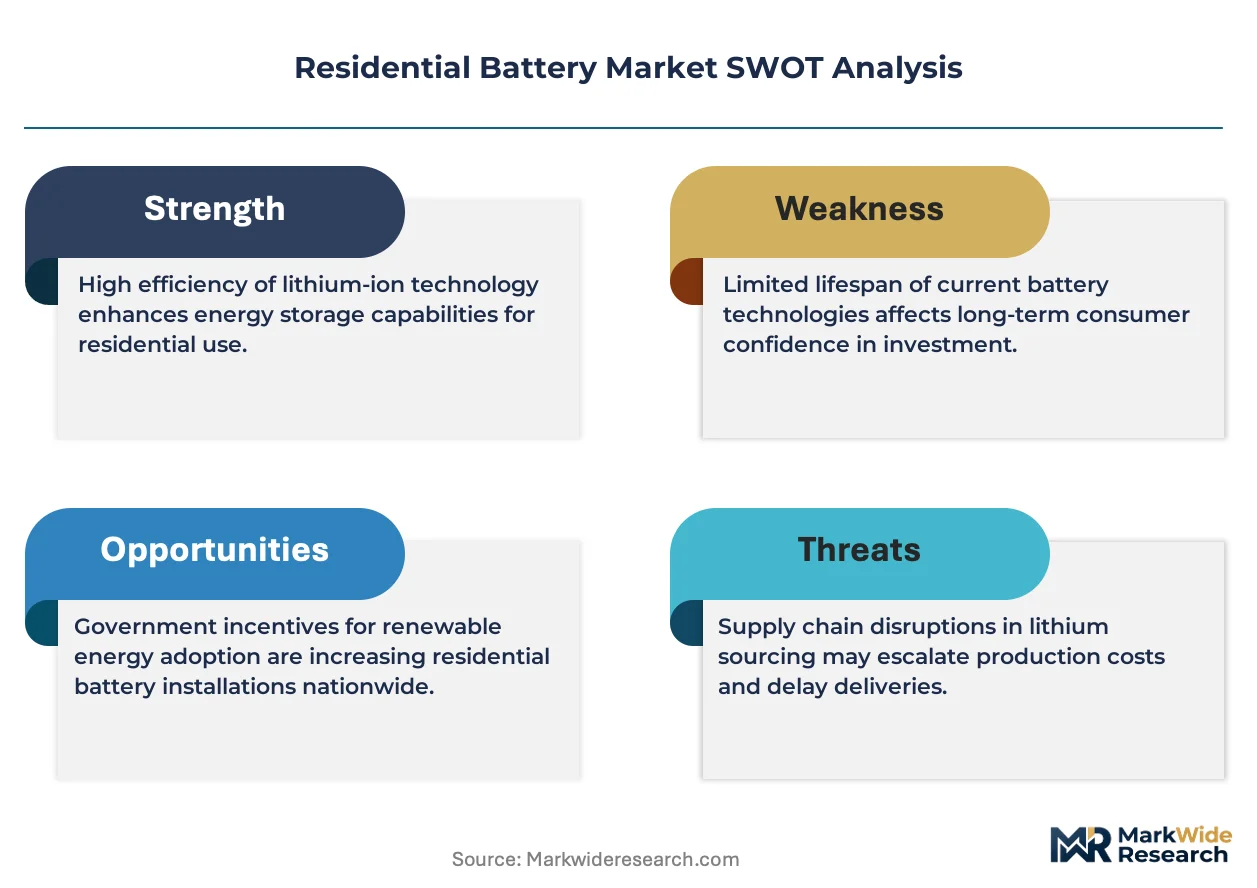
China's gigafactory corridor is rewriting cost curves for lithium iron phosphate cells. Tesla Energy leverages its Nevada cell production to anchor North American supply. LG Energy Solution sustains competitive positioning through integrated cathode material operations. BYD Energy Storage dominates vertical scope from mine to module, controlling cost architecture.
A residential battery stores electrical energy in electrochemical cells, typically lithium iron phosphate or nickel manganese cobalt oxide, with nominal voltages from 48 V to 400 V and cycle life exceeding 6,000 cycles at 80 percent depth of discharge. Its primary purpose is to buffer intermittent renewable generation, arbitrage time-of-use electricity rates, and provide backup power during grid outages. Lithium-ion chemistry occupies the dominant share of new installations due to energy density and declining cell costs. Solar Energy Storage application segments attract the fastest capacity additions as rooftop PV pairing becomes standard. Smart Battery Management System technology leads margin pools by enabling warranty validation, remote diagnostics, and utility-controlled dispatch.
The US IRA storage tax credit, Germany's KfW subsidy programs, and Australia's state-level battery rebate schemes collectively lower payback periods and accelerate homeowner procurement decisions. California's Title 24 building code mandates solar-ready construction, indirectly priming battery attachment rates in new housing. Stakeholders must monitor evolving interconnection standards and utility rate reform timelines that determine project economics.
Market Dynamics
The US Inflation Reduction Act's standalone storage tax credit has fundamentally altered residential battery project economics, converting marginal payback periods into compelling homeowner investments while simultaneously pulling forward demand from future years.
Growth Catalysts
- California Title 24 Mandate:The state's building code requires solar-ready construction in new housing, creating a captive pre-wired infrastructure base that accelerates battery attachment rates without incremental installation labor.
- Time-of-Use Rate Arbitrage:Homeowners in Germany and Australia exploit retail electricity pricing spreads by charging batteries during low-rate periods and discharging during peak pricing windows, compressing payback timelines.
- Lithium Iron Phosphate Chemistry:The chemistry's thermal stability and extended cycle life enable warranty terms that reduce homeowner risk perception, particularly in fire-prone regions with strict installation codes.
Market Restraints
- Lithium Carbonate Volatility:Cell cost structures remain exposed to lithium compound price swings, creating margin pressure for integrators unable to pass through input fluctuations to rate-sensitive residential buyers.
- Nevada-Texas Cell Concentration:North American cell production clusters in two states, exposing supply continuity to localized weather events, labor actions, or grid instability affecting cathode precursor processing.
- Nickel Manganese Cobalt Obsolescence Risk:NMC chemistries face displacement from LFP alternatives in stationary applications, stranding manufacturing capacity optimized for higher energy density formulations.
Strategic Opportunities
- Virtual Power Plant Aggregation:Utility-controlled dispatch of aggregated residential batteries creates grid services revenue streams that supplement homeowner bill savings, expanding addressable market beyond pure backup applications.
- Retrofit Attachment to Existing Solar:The installed base of 2015-2020 rooftop PV systems without storage represents a retrofit opportunity as inverter replacement cycles coincide with battery cost declines.
- Queensland State Rebate Expansion:Australia's northeastern state has signaled program extension beyond current sunset dates, creating policy visibility for distributors to build inventory and installer capacity.
Industry Challenges
- Interconnection Queue Delays:Utility approval timelines for behind-the-meter storage systems stretch to 8-14 weeks in high-penetration territories, creating working capital strain for installation contractors.
- UL 9540A Certification Bottleneck:Fire safety testing capacity for large-format residential battery systems operates at saturation, delaying product launches and geographic expansion for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Residential Battery Market |
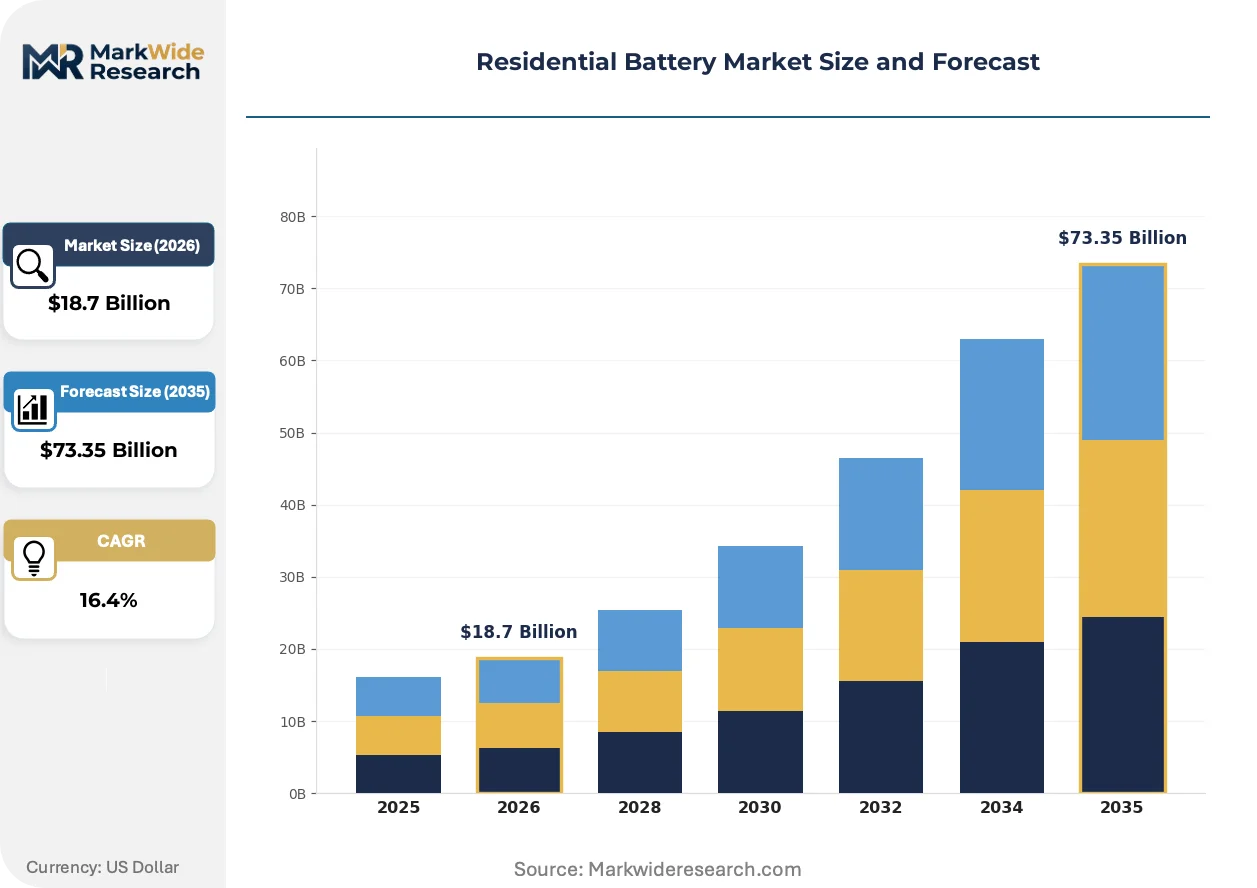
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Lead Acid, Nickel Cadmium, Flow Battery Technology: Smart Battery Management System, Thermal Management, Modular Design, Grid Integration Application: Backup Power, Load Shifting, Peak Shaving, Solar Energy Storage End User: Homeowners, Residential Developers, Small Business Owners, Renewable Energy Installers |
| Companies Covered | Pylontech, Enphase Energy, Tesla Energy, EVE Energy, Huawei Digital Power, LG Energy Solution, Sonnen GmbH, SolarEast BESS, BYD Energy Storage, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Battery Market Strategic Shifts & Innovations
Software-defined battery management is displacing hardware-centric competitive advantages, with algorithmic warranty validation and predictive degradation modeling becoming primary vendor differentiation rather than raw cell specifications.
Solid-state electrolyte research is rendering obsolete conventional liquid electrolyte thermal management systems in premium residential segments. Early adopters in California's fire-conscious municipalities are specifying solid-state architectures despite 40-60% cost premiums. The technology is compressing the competitive window for incumbent liquid-electrolyte suppliers to establish brand loyalty before performance gaps widen.
The EU Battery Regulation's carbon footprint disclosure requirements are forcing supply chain reconfiguration for cells sold in Germany, France, and the Netherlands. Manufacturers must document lifecycle emissions from mining through module assembly, favoring producers with captive renewable-powered production. European integrators are responding by dual-sourcing from Nordic and Iberian cell assembly plants to minimize transport emissions and compliance documentation burden.
Homeowner preference for integrated solar-plus-storage procurement is consolidating installer channels around vertically capable electrical contractors. Pure-play battery distributors are losing shelf space to roofing and solar specialists offering single-point accountability. This channel compression is most visible in Australia's southeastern states, where the top 15 solar retailers now capture over 60% of battery attachment transactions.
Residential Battery Market Segmentation
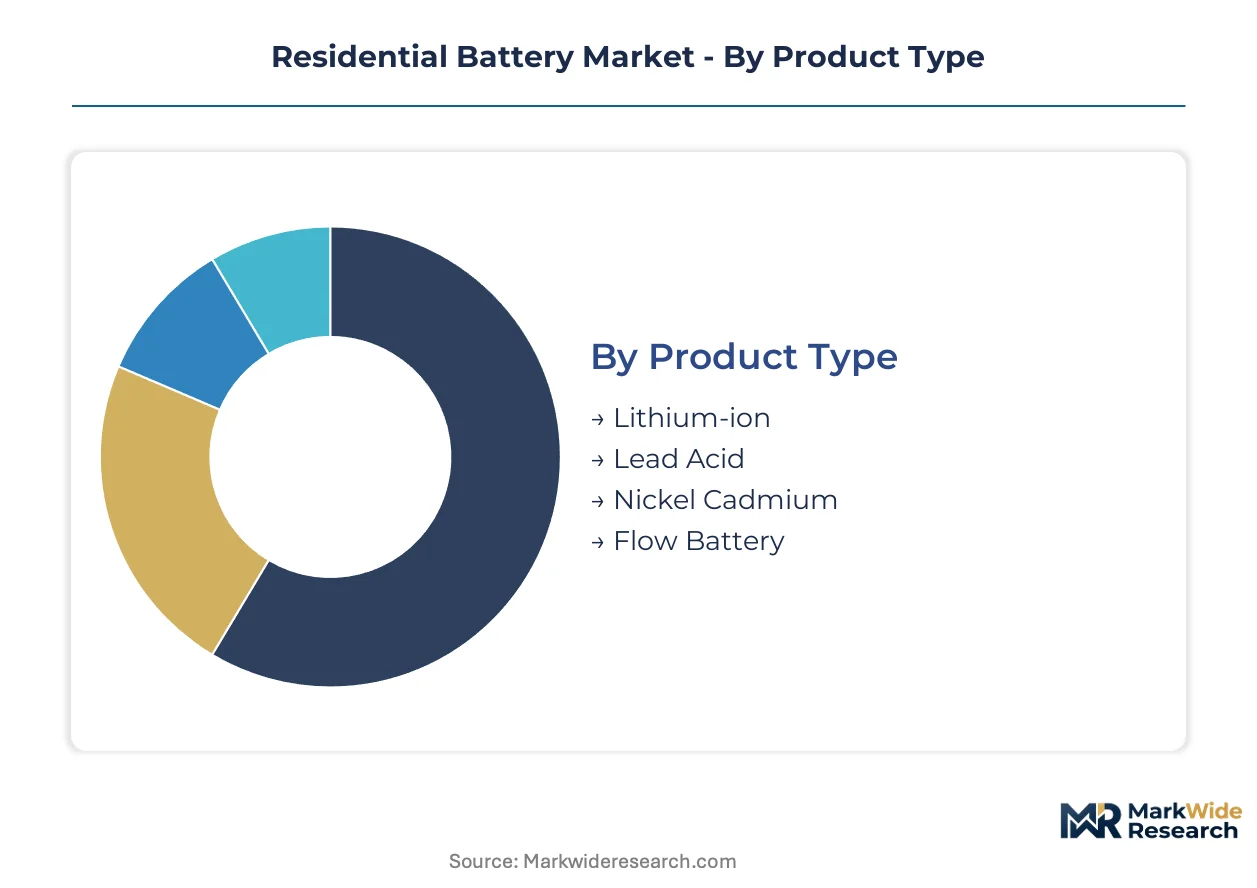
Residential battery procurement decisions hinge on installation context and technical specifications. Segmentation reveals where hardware margins concentrate versus where software-enabled services extract value. Understanding these divides clarifies which product configurations align with homeowner risk profiles and regulatory incentives.
Product Type:
Lithium-ion cells turn over fastest as chemistry improvements compress replacement cycles, while flow batteries operate on decade-long refresh timelines that slow revenue recognition for vendors.
- Lithium-ion:Lithium iron phosphate and nickel manganese cobalt oxide formulations deliver 48-400V nominal output with 6,000+ cycle life at 80% depth of discharge. California, Germany, and Australia concentrate procurement where retail rate spreads and grid instability justify premium pricing. IRA tax credits and KfW subsidies accelerate homeowner adoption decisions.
- Lead Acid:Mature flooded and absorbed glass mat technologies occupy budget backup applications in regions with weak incentive structures or price-sensitive rural markets. Shorter cycle life and lower energy density limit attach rates to basic outage protection rather than daily cycling economics.
- Nickel Cadmium:Robust performance across temperature extremes sustains niche demand in cold-climate off-grid installations where lithium-ion thermal management adds cost complexity.
- Flow Battery:Vanadium redox systems offer unlimited cycling without capacity fade, appealing to homeowners prioritizing 20-year asset life over upfront capital efficiency.
Lithium-ion dominates installed base. Flow battery represents the steepest expansion trajectory among non-lithium chemistries as fire safety codes tighten.
Technology:
Cost tier separation runs deepest here, with basic thermal hardware at economy pricing and AI-enabled management systems commanding premium margins.
- Smart Battery Management System:Algorithmic warranty validation and predictive degradation modeling enable remote diagnostics and utility-controlled dispatch. Software-defined architectures displace hardware-centric advantages as primary vendor differentiation.
- Thermal Management:Liquid cooling and passive heat dissipation systems protect cell longevity in high-temperature installations. Fire-prone California municipalities increasingly specify enhanced thermal architectures despite cost premiums.
- Modular Design:Stackable capacity configurations allow homeowners to right-size initial investment and expand storage incrementally as load profiles evolve or EV charging demands emerge.
- Grid Integration:IEEE 1547-compliant inverters and IEEE 2030.5 communication protocols enable virtual power plant participation, creating grid services revenue streams beyond bill savings.
Smart Battery Management System captures margin concentration. Grid Integration is climbing the fastest as utility rate reform creates dispatchable value pools.
Application:
Volume concentrates in daily-cycling use cases rather than standby-only deployments, shifting attach rates toward rate-arbitrage economics.
- Solar Energy Storage:Rooftop PV pairing has become standard procurement, with California Title 24 solar-ready mandates priming battery attachment in new housing without incremental installation labor.
- Load Shifting:Time-of-use rate arbitrage exploits retail pricing spreads by charging during low-rate periods and discharging during peak windows, compressing payback timelines in Germany and Australia.
- Backup Power:Outage protection remains the entry-level value proposition in grid-unstable territories, though pure backup configurations face displacement by multi-use economics.
- Peak Shaving:Demand charge reduction for homeowners with high intermittent loads creates commercial-grade economics in residential settings with steep demand ratchets.
Solar Energy Storage leads capacity additions. Load Shifting is gaining share fastest as dynamic pricing spreads widen across deregulated retail markets.
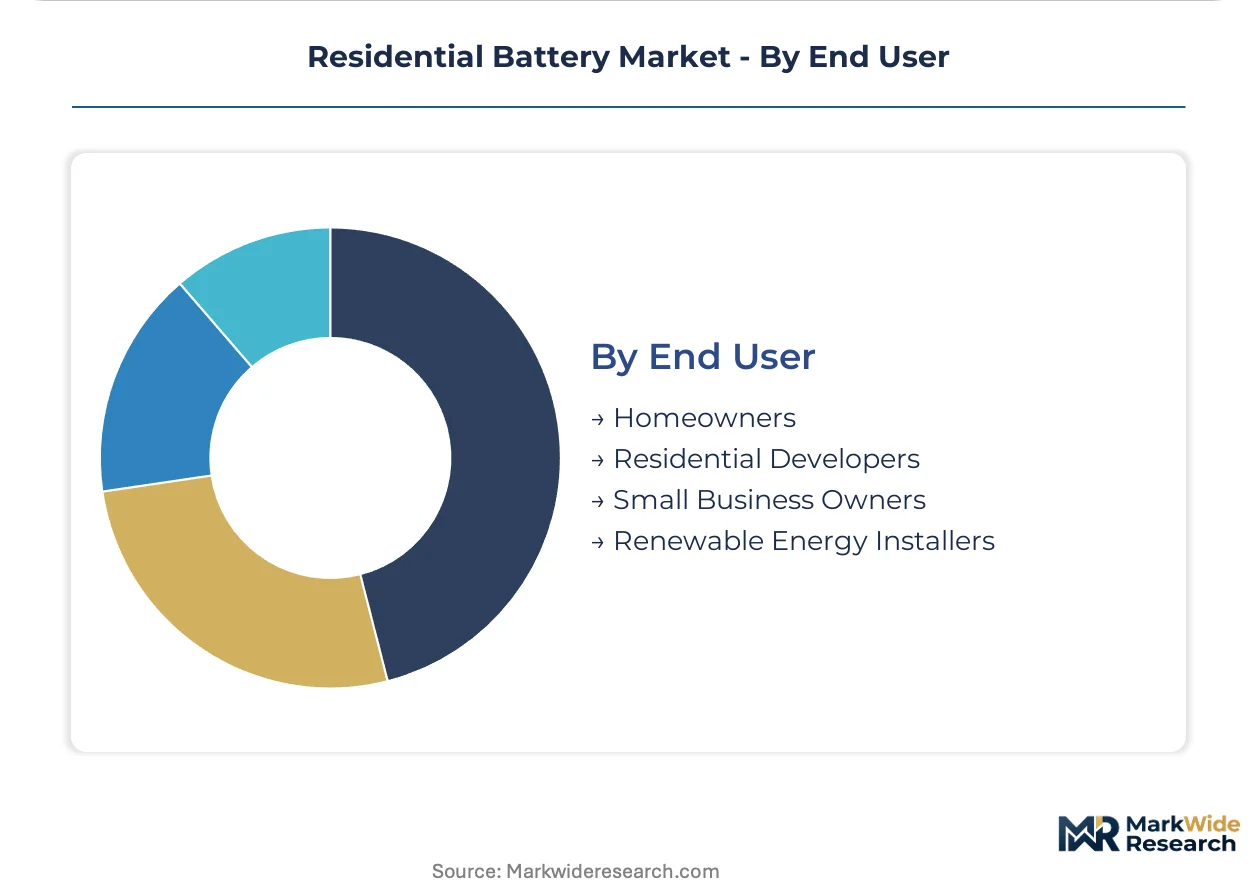
End User:
Customer type determines channel configuration and working capital requirements, with developers offering volume predictability absent in fragmented homeowner markets.
- Homeowners:Distributed decision-making across millions of individual households creates marketing complexity, though IRA tax credits and state rebate schemes lower acquisition friction.
- Residential Developers:California's Title 24 mandates and similar building codes in fire-prone regions create captive pre-wired infrastructure bases that accelerate battery attachment rates at construction stage.
- Small Business Owners:Home-based enterprises with critical uptime requirements justify larger capacity installations and faster payback tolerance than pure residential loads.
- Renewable Energy Installers:Vertically capable electrical contractors consolidating around integrated solar-plus-storage procurement are displacing pure-play battery distributors in Australia's southeastern states.
Homeowners anchor volume base. Residential Developers represent the most concentrated expansion vector as building code mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The IRA anchors US demand acceleration through standalone storage tax credits that compress homeowner payback periods. California's Title 24 building code mandates solar-ready construction, priming battery attachment in new housing stock. Germany's KfW subsidy programs and Australia's state-level rebate schemes complete the policy triad driving procurement decisions.
United States
California's Title 24 mandate creates captive pre-wired infrastructure for battery attachment in new construction, while the IRA's 30% standalone storage credit pulls forward demand from future years. FERC interconnection standards and state-level net metering reforms determine project economics across high-penetration territories. The Nevada-Texas cell production corridor concentrates cathode precursor processing capacity.
Germany
Retail electricity rate spreads exceeding 30 cents per kilowatt-hour enable time-of-use arbitrage economics for residential storage systems. KfW 270 low-interest loan programs and federal battery storage subsidies lower acquisition barriers for homeowners. Industrial clusters in Bavaria and Baden-Württemberg host system integrators serving the retrofit solar base.
Australia
Queensland's state-level battery rebate expansion beyond current sunset dates creates policy visibility for distributor inventory builds. Grid instability and bushfire-related outage risks drive backup power procurement in New South Wales and Victoria. The southeastern states concentrate installer channel consolidation around vertically capable solar retailers.
China
Gigafactory corridors in Fujian and Jiangsu provinces rewrite lithium iron phosphate cell cost curves through scale manufacturing. MIIT industrial policy and dual carbon goals accelerate domestic storage deployment alongside export capacity expansion. BYD Energy Storage and CATL anchor vertical scope from mine to module.
Residential Battery Market Key Industry Players
Capability concentration sits with integrated cell producers; scale advantage sits with system integrators with captive installation channels. The market structures around three tiers: gigafactory-backed chemistry specialists, solar-origin platform players, and regional system integrators. Competitive moves center on cathode material backward integration and virtual power plant software licensing. Geographic expansion through certified installer network density represents the second dominant vector.
Within the chemistry-specialist tier, BYD Energy Storage and EVE Energy exemplify vertical scope from raw material through module assembly. Tesla Energy occupies a position bridging manufacturing scale with direct-to-consumer channel control. LG Energy Solution anchors the integrated materials tier through captive cathode operations. Sonnen GmbH represents the European system-integrator archetype with utility partnership density.
| Leading Market Players |
|---|
| Pylontech |
| Enphase Energy |
| Tesla Energy |
| EVE Energy |
| Huawei Digital Power |
| LG Energy Solution |
| Sonnen GmbH |
| SolarEast BESS |
| BYD Energy Storage |
| Others |
Cost & Logistics Intelligence
Overcapacity in China's Fujian-Jiangsu gigafactory corridor is compressing lithium iron phosphate cell margins and forcing suppliers into aggressive pricing postures that reshape procurement negotiations across downstream markets. This utilization dynamic concentrates pricing power with integrated cathode producers while squeezing standalone module assemblers into defensive cost positions.
Pricing Analysis
California-Germany-Australia price spreads exceed 40% for equivalent lithium iron phosphate systems, reflecting divergent incentive structures and installation labor costs. Three-tier pricing structure across premium solid-state, standard liquid-cooled, and economy passive-thermal configurations separates warranty-backed utility partnerships from basic backup-only deployments. Cost compression in economy tiers is intensifying because Chinese cell exports are flooding price-sensitive retrofit segments. Residential developers with mandated solar-ready infrastructure show least price sensitivity, while rural off-grid homeowners in weak-incentive territories exhibit highest elasticity.
Supply Chain Analysis
Contract manufacturing concentration sits with BYD Energy Storage, EVE Energy, and CATL module assembly facilities across China's coastal provinces. Raw material dependencies draw from Australian spodumene, Chilean lithium brine, and Indonesian nickel processing. Single-source vulnerability concentrates in cathode precursor supply from South Korean chemical conglomerates. Distribution runs through vertically capable solar retailers displacing pure-play battery distributors in high-penetration territories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The residential battery market is cycling through a lithium carbonate price correction that resets input cost baselines and creates margin recovery windows for integrated producers. IRA incentive pull-forward effects and building code mandates sustain demand visibility through the trough.
For Market Incumbents: Entrench algorithmic warranty validation capabilities as primary differentiation against solid-state challengers. Deepen backward integration into cathode precursor production to insulate margin architecture from lithium compound volatility. Lock installer channel capacity through exclusive VPP software licensing before regional solar retailers consolidate further.
For New Entrants and Emerging Players: Pursue retrofit attachment to Australia's 2015-2020 rooftop PV installed base where inverter replacement cycles coincide with battery cost declines. Target Queensland's extended rebate window for distributor partnership formation. Lead with modular capacity configurations that allow homeowners to expand storage incrementally as EV charging loads emerge.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across solid-state electrolyte R&D as manufacturing scale approaches, shifting viable return thresholds for premium segment entrants. Acquisition targets should display captive renewable-powered production for EU Battery Regulation compliance. Watch for UL 9540A certification queue clearance as signal of product launch velocity inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Virtual Power Plant Software Licensing | Utility-controlled dispatch creates recurring revenue streams beyond hardware sales for Tesla Energy and Sonnen GmbH. |
| Cathode Material Backward Integration | LG Energy Solution's captive precursor operations insulate margin architecture from lithium carbonate volatility. |
| Solid-State Electrolyte Manufacturing Scale-Up | Early production lines in California municipalities command 40-60% premiums over liquid-electrolyte alternatives. |
| Certified Installer Network Density Expansion | Australia's top 15 solar retailers now capture over 60% of battery attachment transactions through channel consolidation. |
| EU Battery Regulation Compliance Program | Nordic and Iberian cell assembly plants minimize transport emissions documentation for German and Dutch integrators. |
Research Approach
Cross-validation between utility interconnection databases and state-level rebate program records anchors the qualitative findings on installer capacity constraints and homeowner procurement timing. Primary interviews with utility planning officers, EPC contractors, grid operators, and solar retailer operations heads combined with secondary analysis of FERC filings, EIA capacity data, IEA technology roadmaps, and project development databases. Bottom-up unit economics modeling triangulates against top-down policy impact assessments.
Calibration against historical IRA uptake curves and KfW loan disbursement patterns validates the projection framework across the analysis window. Segmentation dimensions include chemistry formulation, thermal management architecture, application use case, and end-user type. CAGRs derive from installed base growth rates adjusted for replacement cycle compression and incentive phase-out schedules. Forecast inputs incorporate lithium compound price trajectory assumptions and interconnection queue clearance timelines.
Sensitivities concentrate around lithium carbonate price volatility, utility rate reform implementation delays, and solid-state technology performance gap widening. Forecasts reflect documented assumptions on policy continuity and manufacturing scale achievement. Quarterly review of cathode precursor inventory levels, UL 9540A certification throughput, and state-level rebate program extensions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Myanmar Battery Market
Batteries
USA Forklift Battery Market
Batteries
Heavy-Duty Truck Megapack Battery Systems Market
Batteries
Lithium Starters Market
Batteries
Japan Battery Market
Batteries
Forklift Battery Charger Market
Batteries
Nas Battery Market
Batteries
Modular Battery Market
Batteries
Medical Batteries Market
Batteries
Potassium-Ion Battery Market
Batteries
Lithium Battery Testing System Market
Batteries
Malaysia Battery Market
Batteries
Iron-Chromium Flow Battery Market
Batteries
Battery Coolant-Antifreeze Refractometer Market
Batteries
China Rechargeable Battery Market
Batteries
Industrial Backup Battery Market