
 Beef Bouillon Market | 2026-2036
Beef Bouillon Market Size, Share, and Industry Trends Forecast 2026-2036
Beef Bouillon Market Analysis
Foodservice channels is broadening as quick-service restaurants and institutional kitchens reduce scratch cooking. Nestlé leverages its global distribution infrastructure to supply commercial kitchens across multiple continents. Unilever sustains competitive pressure through concentrated base formats tailored to high-volume operators. McCormick & Company, Incorporated specializes in premium flavor extracts that command preferential placement in specialty food channels.
Beef bouillon comprises dehydrated beef extract, hydrolyzed vegetable proteins, salt, and seasonings rendered into concentrated form through low-temperature vacuum evaporation and subsequent spray-drying or compression into cubes. The product serves primarily as a flavor foundation for soups, sauces, and prepared meals in both household and commercial food production. Granular formats lead volume sales due to faster dissolution rates preferred by food manufacturers, while liquid concentrates capture expanding demand from chefs seeking immediate usability without reconstitution. Distribution through supermarket chains still dominates absolute value, though online channels are accelerating as direct-to-restaurant replenishment platforms mature.
FDA standards govern ingredient labeling and sodium disclosure for beef bouillon sold in the United States, while EFSA and national EU regulators enforce additive restrictions and origin labeling under broader food information regulations. These frameworks compel manufacturers to reformulate with reduced sodium profiles and cleaner ingredient decks to maintain shelf placement. Stakeholders must monitor evolving clean-label certification requirements and regional sodium thresholds that will determine which product formats retain market access.
Market Dynamics
Clean-label reformulations and sodium reduction mandates from food safety regulators are compressing formulation margins while forcing manufacturers to rebuild product architectures around natural flavor precursors and alternative salt technologies.
Growth Catalysts
- Concentrated Base Formats:Foodservice operators in Brazil are replacing scratch stocks with concentrated beef bases to reduce kitchen labor and inventory complexity.
- FDA Sodium Disclosure Rules:U.S. labeling requirements are accelerating clean-label innovation as manufacturers reformulate to retain retail shelf placement.
- Protein-Rich Convenience Foods:Urban consumers in China are driving bouillon integration into instant noodle and ready-meal formulations.
Market Restraints
- Beef Input Cost Volatility:Cattle feed grain prices and pasture availability fluctuations constrain margin predictability for extract-based producers.
- Supply Concentration in Brazil:Beef processing capacity clusters in specific Brazilian states, creating geographic vulnerability to climate and logistics disruptions.
- Plant-Based Substitution Threat:Mushroom and yeast-extract alternatives are capturing label-conscious consumers seeking animal-free umami foundations.
Strategic Opportunities
- Direct-to-Restaurant Platforms:Online replenishment channels are bypassing traditional distributor markups for independent kitchen operators.
- EFSA Additive Restrictions:European clean-label mandates are creating first-mover advantage for manufacturers with natural preservative systems.
- Spray-Drying Technology Convergence:Low-temperature vacuum evaporation paired with precision granulation is enabling custom particle size for industrial clients.
Industry Challenges
- Flavor Chemist Talent Scarcity:Natural beef flavor replication without synthetic enhancers requires specialized expertise that outpaces current training pipelines.
- Clean-Label Certification Timelines:Third-party non-GMO and organic validations extend product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beef Bouillon Market |
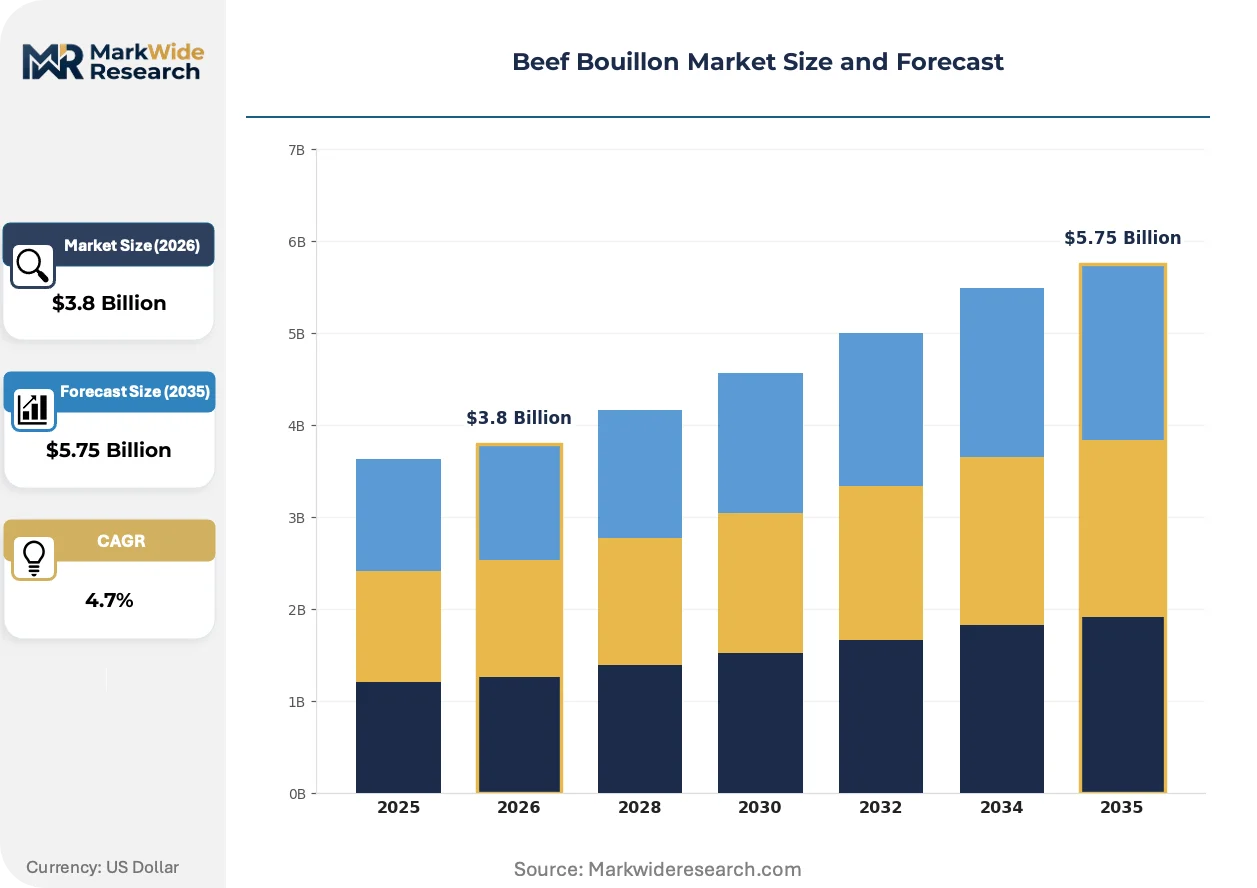
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Powdered, Liquid, Cubes Packaging Type: Bottles, Sachets, Pouches, Jars Distribution Channel: Supermarkets, Online, Convenience Stores, Specialty Shops Application: Soups, Sauces, Marinades, Gravies |
| Companies Covered | Nestlé, Unilever, The Kraft Heinz Company, Hormel Foods Corporation, McCormick & Company, Incorporated, International Dehydrated Foods, Inc., Goya Foods, Inc., Proliver, Southern Mills, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beef Bouillon Market Emerging Trajectories
Formulation science and distribution infrastructure are undergoing parallel reinvention as manufacturers reconcile regulatory pressure with operational efficiency demands.
Precision fermentation-derived beef flavor precursors are rewriting the economics of natural extract production. Ingredient technology firms are supplying these biosynthesized compounds to bouillon manufacturers seeking to eliminate traditional hydrolyzed proteins. The technology is compressing reliance on commodity beef inputs while complicating supply chain authentication.
EFSA's evolving stance on flavor enhancer additives is forcing European manufacturers toward single-ingredient positioning. The regulatory friction is eliminating multi-additive formulations from premium retail segments. German and French bouillon producers are responding with shortened ingredient decks that highlight beef content percentage.
Foodservice procurement teams are consolidating supplier relationships around full-line flavor houses capable of custom base development. Independent restaurant groups are displacing single-product vendors with integrated partners offering formulation collaboration. This concentration is most visible in U.S. metropolitan markets where multi-unit operators negotiate direct manufacturing agreements.
Beef Bouillon Market Segmentation
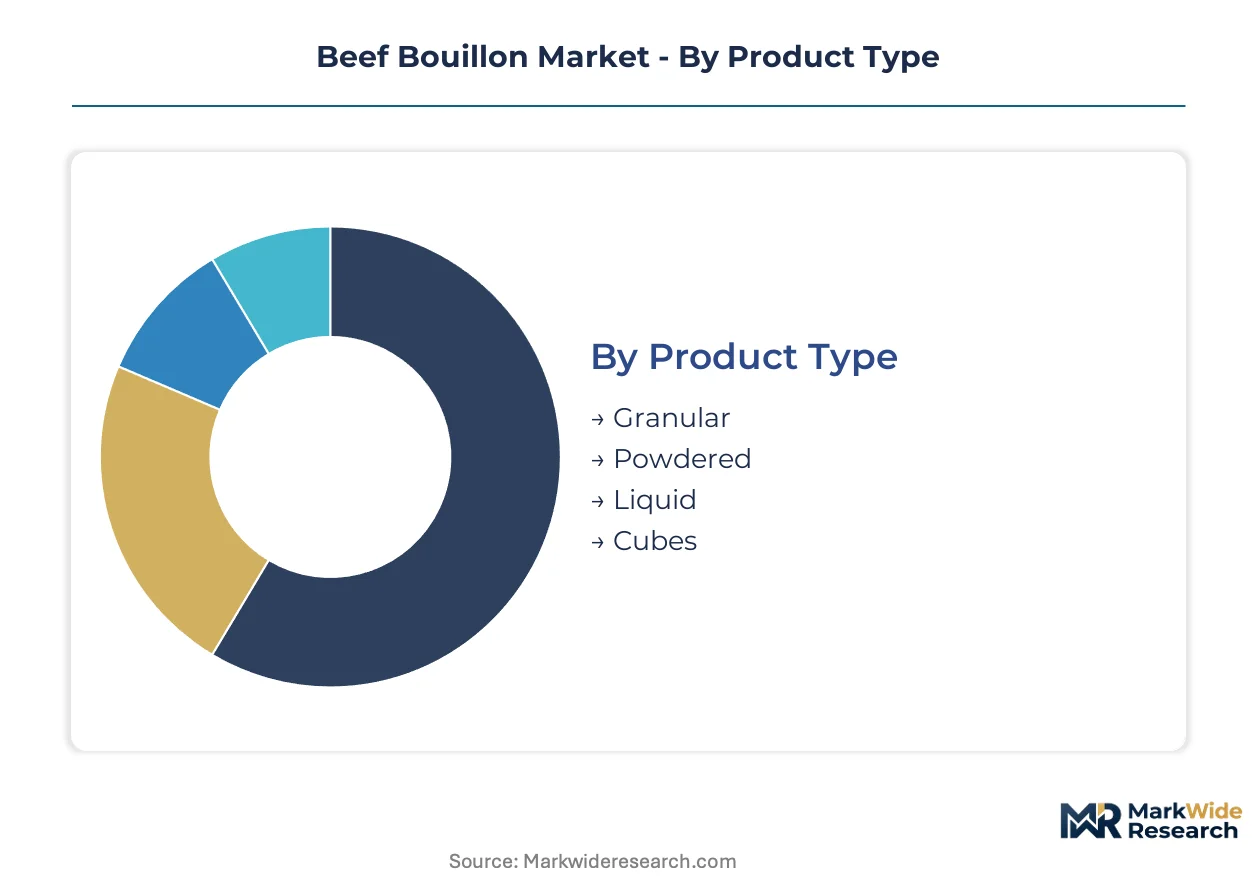
Product architecture in beef bouillon determines integration depth across food manufacturing and foodservice channels. Format selection dictates dissolution speed, shelf stability, and reformulation flexibility under tightening sodium regulations.
Product Type:
Granular and powdered formats serve standalone reconstitution by end-users, while liquid concentrates embed directly into industrial production lines without hydration steps.
- Granular:Rapid-dissolving crystalline particles manufactured through spray-drying of concentrated beef extract. Food manufacturers in the United States favor this format for instant soup and sauce bases where hydration speed determines production line throughput. Sodium reduction mandates from the FDA are forcing reformulation of granule binders to maintain flow properties without synthetic anti-caking agents.
- Liquid:Ready-to-use concentrated extracts requiring no reconstitution. High-volume restaurant chains in Brazil are adopting liquid formats to eliminate kitchen labor associated with stock preparation. EFSA additive restrictions in Europe are compressing available preservative options for ambient-stable liquid products.
- Powdered:Fine-milled dehydrated extract with extended shelf stability. Retail sachet packaging in China leverages powdered formats for single-use convenience in urban households.
- Cubes:Compressed dehydrated blocks requiring dissolution in hot water. Traditional household cooking in European markets sustains residual demand despite slower adoption in commercial channels.
Granular leads volumes today; liquid is gaining share fastest.
Packaging Type:
Packaging economics stratify across cost tiers, with bulk formats serving high-rotation foodservice and premium single-serve units capturing specialty retail markup.
- Bottles:Rigid containers for liquid concentrates with controlled pour spouts. Institutional kitchens in the United States specify bottle formats for inventory tracking and portion control compliance.
- Sachets:Single-serve foil laminates preserving aroma integrity. Brazilian quick-service restaurants deploy sachets for front-of-house customer self-service stations.
- Pouches:Flexible stand-up bags with resealable closures. Chinese e-commerce platforms favor pouches for shipping efficiency in direct-to-consumer replenishment.
- Jars:Glass or plastic wide-mouth containers for granular products. European specialty shops stock jar formats to signal premium positioning against mass-market alternatives.
Pouches are climbing the fastest in channel penetration; bottles retain the largest absolute volume base.
Distribution Channel:
Channel selection reflects customer type bifurcation between planned pantry stock-up and immediate need fulfillment.
- Supermarkets:Dominant retail channel for household pantry replenishment with extended SKU variety. Clean-label reformulations in France and Germany are reshaping shelf placement negotiations with chain buyers.
- Online:Direct-to-restaurant platforms and consumer subscription services. Independent kitchen operators in U.S. metropolitan markets are bypassing traditional distributors through specialized replenishment apps.
- Convenience Stores:Emergency purchase locations for single-serve formats. Urban density in Chinese tier-one cities sustains high rotation of compact sachet SKUs.
- Specialty Shops:Curated selection emphasizing origin labeling and artisan positioning. Premium beef content claims in Italian and Spanish markets command price multiples through this channel.
Supermarkets anchor current volume; online is expanding most quickly in foodservice penetration.
Application:
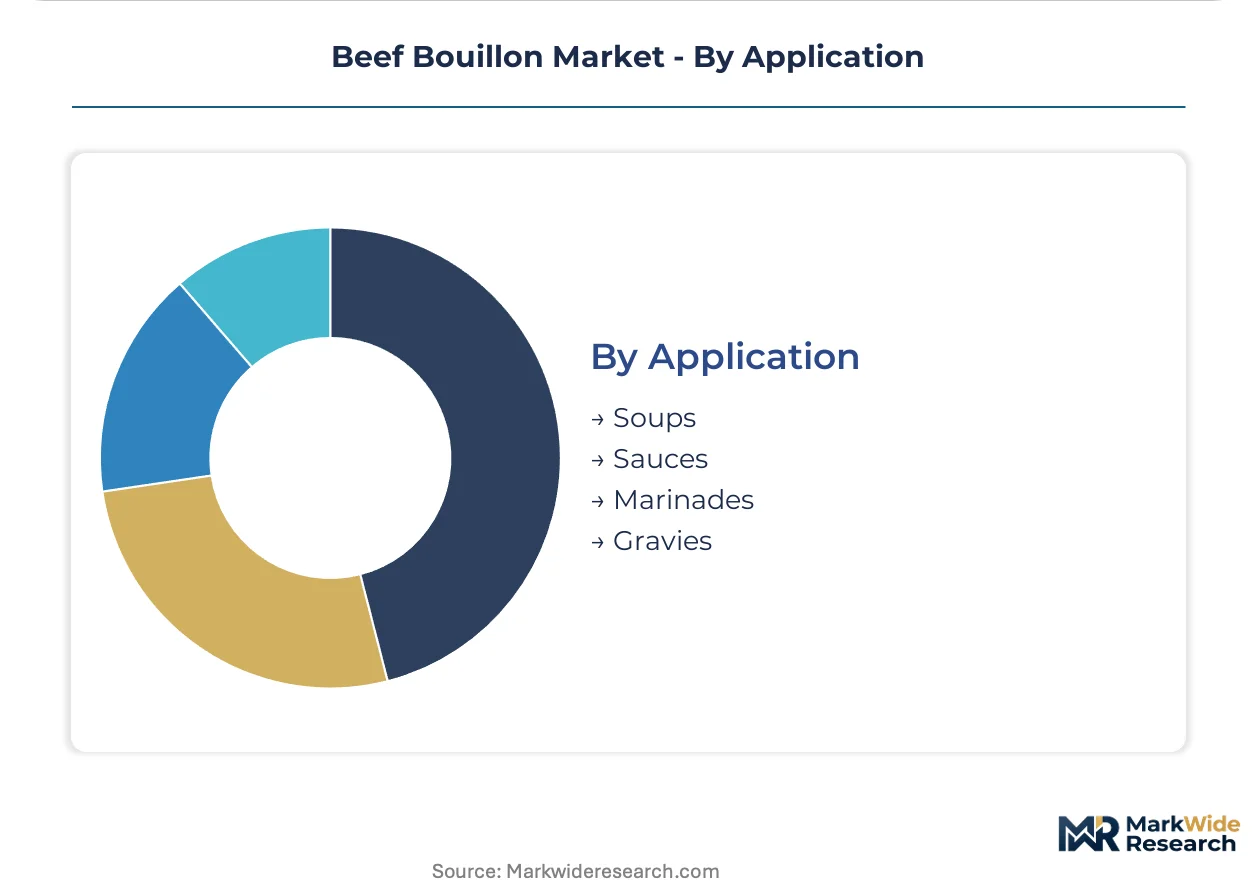
Application segmentation tracks formulation maturity, with soups representing established integration and marinades showing emergent reformulation activity.
- Soups:Primary historical use case for bouillon as foundational flavor base. Instant noodle manufacturers in China embed beef bouillon into seasoning oil packets for protein-rich positioning.
- Sauces:Concentrated base integration into ready-to-serve and cooking sauces. Brazilian food processors are reformulating traditional meat sauces with reduced-sodium bouillon to meet export standards.
- Marinades:Emerging application for tenderization and umami delivery. U.S. meat processing facilities are testing bouillon-based injection marinades for commodity beef value addition.
- Gravies:Traditional accompaniment format in European and North American household cooking. Sodium disclosure rules are compressing traditional high-salt gravy base formulations.
Soups retain the steepest volume concentration; marinades show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is steering production investment toward jurisdictions with moderate compliance costs and abundant cattle supply. Brazil and Argentina attract extract-processing capacity due to lower feedstock expenses and less stringent additive rules than the European Union. Manufacturers balance FDA disclosure requirements in the United States against EFSA additive restrictions when locating spray-drying facilities.
United States
Quick-service restaurant chains and institutional foodservice operators drive concentrated base consumption. FDA sodium disclosure rules compel reformulation of granular products to maintain retail shelf placement. Chicago and Omaha host major food manufacturing clusters where bouillon processors co-locate with meatpacking facilities to secure fresh extract supply.
Brazil
Foodservice operators replace scratch stocks with liquid concentrates to reduce kitchen labor and inventory complexity. ANVISA maintains additive approval frameworks less restrictive than European counterparts, attracting regional production investment. São Paulo state concentrates beef processing capacity, though climate disruptions periodically constrain pasture availability and feed grain flows.
China
Urban consumers in tier-one cities integrate bouillon into instant noodle and ready-meal formulations for protein-rich convenience positioning. SAMR enforces national food safety standards that increasingly align with international sodium disclosure norms. Yangtze River Delta manufacturing hubs supply seasoning oil packets to domestic instant noodle producers expanding into Southeast Asian export markets.
Germany
EFSA additive restrictions and clean-label certification requirements compress available formulation options for retail bouillon products. Bavaria and North Rhine-Westphalia host specialty food channels emphasizing shortened ingredient decks and beef content percentage claims. German producers lead European reformulation efforts around natural flavor precursors and alternative salt technologies.
France
Traditional household cooking sustains residual cube format demand despite slower commercial channel adoption. National regulations under EU food information frameworks enforce strict origin labeling and additive transparency. Paris-region specialty shops curate premium jar formats signaling artisan positioning against mass-market supermarket alternatives.
Beef Bouillon Market Vendor Landscape
Portfolio diversification dominates the current landscape as manufacturers expand format ranges to capture foodservice and retail channels simultaneously. The vendor base stratifies across three tiers: multinational flavor houses with integrated distribution, regional extract processors serving industrial clients, and specialty firms focused on clean-label certification. Strategic archetypes include full-line flavor houses offering custom base development, commodity extract suppliers competing on input cost, and premium positioning specialists leveraging shortened ingredient decks. M&A activity and capacity expansion in spray-drying infrastructure represent the dominant competitive moves as firms reconcile regulatory pressure with operational scale.
Within the multinational tier, Nestlé and Unilever occupy positions anchored by global distribution infrastructure spanning multiple continents. McCormick & Company, Incorporated sits within the premium flavor extract segment where specialty channel placement commands price differentiation. These three firms exemplify divergent strategic postures: Nestlé leverages commercial kitchen supply relationships, Unilever concentrates concentrated base formats for high-volume operators, and McCormick extracts margin from curated retail positioning.
| Leading Market Players |
|---|
| Nestlé |
| Unilever |
| The Kraft Heinz Company |
| Hormel Foods Corporation |
| McCormick & Company, Incorporated |
| International Dehydrated Foods, Inc. |
| Goya Foods, Inc. |
| Proliver |
| Southern Mills, Inc. |
| Others |
Supply Flow & Price Mechanics
Clean-label certification tiers create a bifurcated cost structure where organic and non-GMO validated products command shelf placement premiums while conventional formulations compete on input cost efficiency. This tier divergence maps directly onto supply chain configurations: premium SKUs source traceable beef extracts through audited Brazilian processors, while commodity lines aggregate spot-market hydrolyzed proteins from multiple origins.
Pricing Analysis
Distributor margin layers absorb the steepest compression as foodservice procurement teams consolidate around direct-to-manufacturer agreements. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and sodium reduction compliance rather than extract concentration alone. Pricing pressure stems from plant-based umami substitutes capturing label-conscious consumers in European retail channels. Quick-service restaurant chains exhibit highest price sensitivity due to volume scale and menu cost engineering, while specialty shops accept premium markups for shortened ingredient decks.
Supply Chain Analysis
Dual-sourcing requirements from major food manufacturers mandate qualified backup suppliers for beef extract to mitigate climate-driven pasture disruptions in Brazil. Raw material flows concentrate in Brazil, Argentina, and the United States as primary cattle processing jurisdictions. Supply chains draw from feed grain markets, fresh extract availability, and hydrolyzed vegetable protein alternatives. Single-source vulnerability intensifies during Brazilian drought cycles that constrain pasture carrying capacity. Distribution runs through foodservice distributors for commercial accounts and supermarket chains for household replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
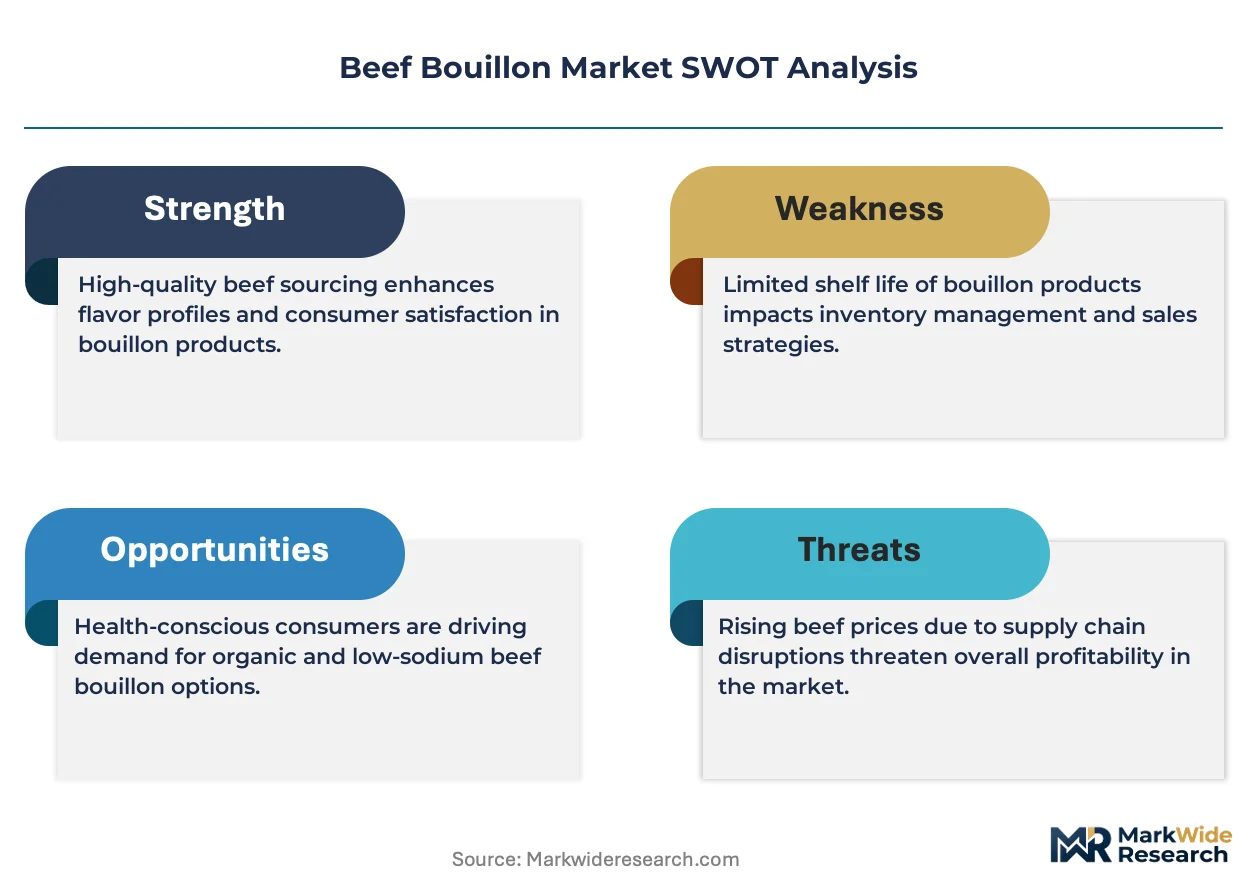
The beef bouillon market functions as a stable compounder anchored by irreversible foodservice substitution of scratch stocks for operational efficiency. This structural shift sustains volume growth independent of cyclical consumer discretionary patterns.
For Market Incumbents: Acquire spray-drying capacity in Brazilian cattle-processing corridors to secure captive extract supply. Nestlé and Unilever should consolidate regional flavor house partnerships before independent operators gain scale. Defensive positioning requires sodium reduction R&D investment ahead of FDA disclosure rule expansion. Channel control through direct-to-restaurant platforms limits distributor margin erosion. For New Entrants and Emerging Players: Independent restaurant groups in U.S. metropolitan markets represent the most penetrable channel entry point. White-space exists in precision fermentation-derived flavor precursors serving European clean-label mandates. Target marinades and injection applications for commodity beef value addition where formulation collaboration replaces transactional supply. Go-to-market should emphasize custom base development partnerships rather than catalog SKU distribution. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap extract processors holding ANVISA-approved Brazilian facilities and EFSA-compliant European formulation capabilities. Long-term viability favors operators with backward integration into cattle processing and forward integration into foodservice direct platforms. The signal to watch is SAMR alignment with international sodium disclosure norms that would accelerate clean-label reformulation demand in Chinese manufacturing hubs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cattle Processing | Captures margin from extract supply through Brazilian facility ownership. |
| Precision Fermentation Partnership | Biosynthesized flavor precursors eliminate commodity beef input volatility. |
| Direct-to-Restaurant Platform Launch | Bypasses distributor markups for independent kitchen operator replenishment. |
| Clean-Label Certification Investment | Non-GMO and organic validation secures premium retail shelf placement. |
| Custom Base Development Capability | Full-line flavor house positioning captures consolidated procurement relationships. |
Methodological Framework
Bottom-up foodservice and food manufacturer modeling reconciled against top-down beef extract production tracking forms the analytical core of this study. Primary interviews with R&D directors at multinational flavor houses, procurement leads at quick-service restaurant chains, plant managers at Brazilian extract processors, and category buyers at supermarket chains were validated against secondary sources including FDA sodium disclosure filings, ANVISA additive approval registers, EFSA scientific opinions, customs trade data for hydrolyzed protein flows, and SEC filings from publicly traded ingredient suppliers. Triangulation between demand-side consumption patterns and supply-side capacity utilization ensures coherence in volume estimates.
Historical trendline analysis of granular, liquid, powdered, and cube format shipments established baseline growth trajectories across the projection horizon. The analytical framework models product type, packaging configuration, distribution channel, and application segmentation dimensions with regional regulatory cluster overlays. CAGRs derive from curve-fitting against observed substitution rates of scratch stocks by concentrated bases. Industry-specific forecast inputs include cattle feed grain price indices and clean-label certification adoption curves in key retail markets.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EFSA additive restriction expansion and precision fermentation technology maturation. Forecasts reflect assumptions about sustained foodservice labor cost pressure and stable Brazilian pasture availability. Deviation in SAMR sodium disclosure alignment with international norms would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Beef Liver Market
Meat Products
Europe Bacon Market
Meat Products
Organic Eggs Market
Meat Products
Bacon Flavors Market
Meat Products
Meat, Poultry and Seafood Market
Meat Products
Edible Offal Market
Meat Products
United States Processed Pork Meat Market
Meat Products
Asia-Pacific Edible Meat Market
Meat Products
Germany Poultry Meat Market
Meat Products
Global Poultry Meat Market
Meat Products
Organic Pork Market
Meat Products
Vegan Meatball Market
Meat Products
United Arab Emirates Edible Meat Market
Meat Products
Beef Bone Broth Market
Meat Products
Low-Fat Ham Market
Meat Products
Dehydrated Meat Products Market