
 Europe Bacon Market | 2026-2036
Europe Bacon Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Bacon Market Foresight
Foodservice distribution is narrowing as butcher shops and specialty retailers capture premium spend from supermarkets across Northern Europe. Danish Crown A/S anchors its position through integrated pork processing from farm to packaged product. WH Group Ltd (Smithfield) leverages its scale advantages across multiple European countries. Finnebrogue Artisan differentiates through nitrite-free curing technology that commands shelf space in premium channels.
Bacon comprises cured and smoked pork belly or back cuts, preserved through salt, nitrates or nitrites, and thermal processing to achieve shelf stability and characteristic flavor profiles; standard products contain sodium nitrite at regulated maximum levels to control botulism risk while clean-label variants employ natural curing agents such as celery powder. Streaky bacon dominates volume across retail and foodservice due to its fat content and cooking performance, while back bacon sustains higher margins in the United Kingdom and Ireland where leaner cuts command consumer preference. Vacuum-sealed packaging leads shelf-life extension and logistics efficiency, though tray packs gain traction in convenience-oriented retail formats.
EFSA sets maximum residual nitrite levels that manufacturers must verify through batch testing, while EU Green Deal agricultural targets influence feed sourcing and farm-level carbon accounting for pork suppliers. National regulators in Germany, France, and the United Kingdom enforce cold-chain standards and labeling requirements that vary in stringency. Stakeholders must monitor evolving nitrite-restriction proposals and alternative-curing validation timelines to secure formulation pipelines before compliance deadlines tighten.
Market Dynamics
EFSA nitrite-reduction guidelines are compressing formulation timelines across European curing operations, forcing manufacturers to validate alternative preservation pathways before enforcement windows tighten. This regulatory pressure intersects with butcher shop channel expansion to reshape competitive positioning between premium and conventional retail tiers.
Growth Catalysts
- EU Green Deal agricultural targets:Carbon accounting mandates for pork suppliers are accelerating feed sourcing transparency and farm-level certification investments across Germany and Denmark.
- Clean-label curing innovation:Celery powder and natural nitrite alternatives are gaining shelf space validation in premium channels as retailers respond to consumer ingredient scrutiny.
- Butcher shop channel expansion:Specialty retail formats in Northern Europe are capturing margin-rich premium spend previously concentrated in supermarket bacon aisles.
Market Restraints
- Input cost volatility:Pork belly supply fluctuations and feed grain price instability compress margins for processors operating on fixed retail contracts.
- Regulatory friction:EFSA batch testing requirements for residual nitrite levels add verification costs and extend product release timelines.
- Technical limitation:Natural curing agents deliver shorter shelf stability than synthetic nitrites, constraining distribution radius for clean-label products.
Strategic Opportunities
- Underpenetrated geography:Poland and Romania present expansion potential for vacuum-sealed premium bacon as cold-chain infrastructure modernizes.
- Regulatory tailwind:EFSA alternative-curing validation pathways offer first-mover advantage to manufacturers securing approved formulation pipelines.
- Channel innovation:Direct-to-consumer subscription models for artisan cured meats are emerging in the United Kingdom and Netherlands.
Industry Challenges
- Reformulation timeline compression:Compliance deadlines for nitrite reduction are forcing parallel development tracks that strain R&D capacity.
- Cold-chain reconfiguration:Shorter shelf-life natural cure products require logistics network upgrades and retailer inventory turnover coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Bacon Market |
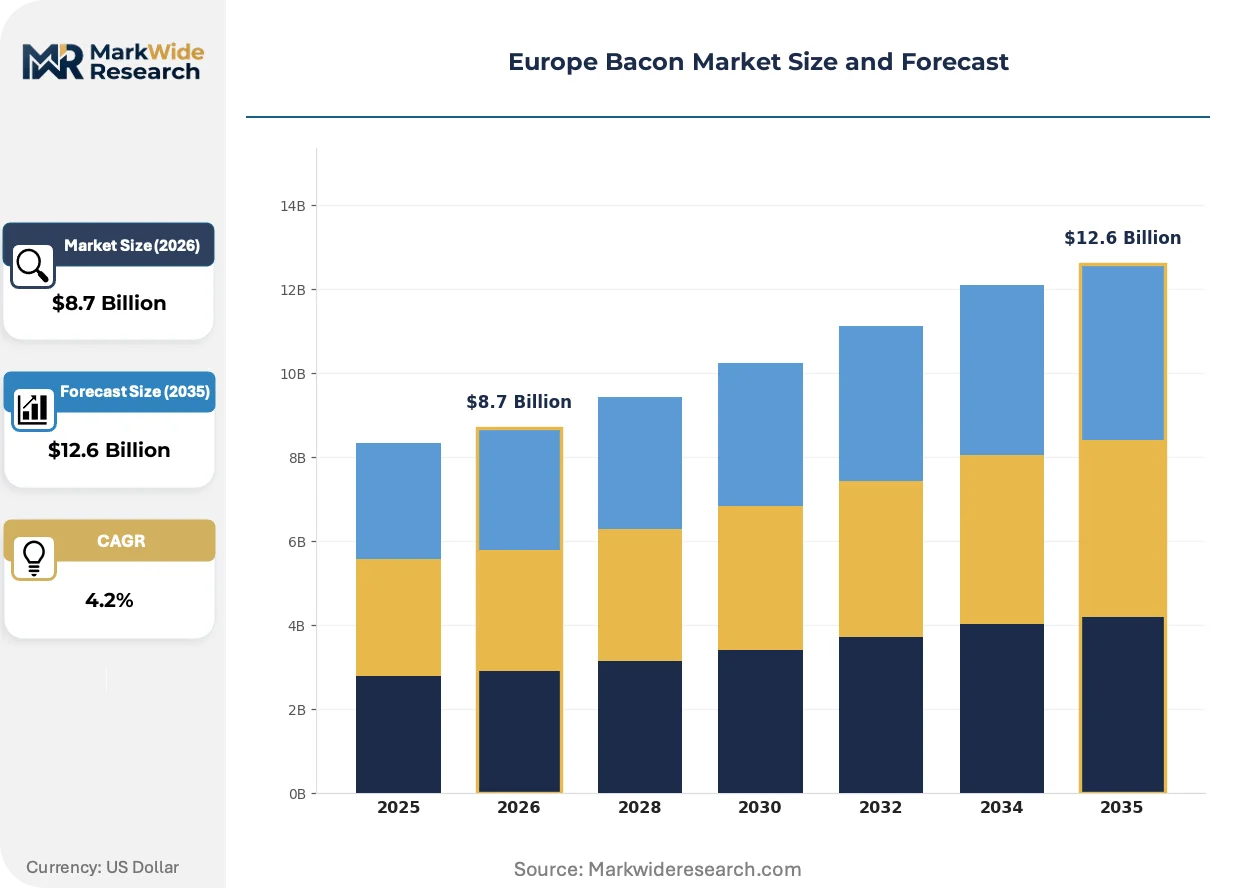
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.6 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Streaky, Back, Pancetta, Lardons Packaging Type: Vacuum Sealed, Tray Packs, Canned, Slices Sales Channel: Online Retail, Supermarkets, Butcher Shops, Specialty Stores Consumer Type: Households, Restaurants, Caterers, Food Service |
| Companies Covered | WH Group Ltd (Smithfield), JBS SA (Tulip Ltd), Danish Crown A/S, OSI Group, Sofina Foods, Karro Food Group, Finnebrogue Artisan, LT Brookes Ltd, Vion Food Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Bacon Market Shifts & Advancements
European bacon production is undergoing preservation technology transformation while distribution channels fragment between convenience retail and premium artisan formats. These shifts are compressing traditional supermarket dominance and elevating traceability requirements.
High-pressure processing equipment is digitizing quality assurance workflows across Danish and German curing facilities. Mid-tier processors are adopting sensor-based monitoring systems to replace manual batch inspection protocols. This technology is digitizing compliance documentation and reducing release-to-market timelines for export-bound shipments.
EFSA maximum residual nitrite regulations are forcing reformulation investments across the supply base. Manufacturers must verify compliance through standardized batch testing protocols that add laboratory capacity requirements. Back bacon producers in the United Kingdom and Ireland face the steepest adaptation curves due to existing consumer preference for milder cure profiles.
Buyer concentration in foodservice is fragmenting as independent restaurants and boutique hotels source directly from regional curing houses. Specialty distributors are building direct relationships with farm-branded bacon operations to bypass consolidated wholesale channels. This disintermediation is most visible in France and Belgium where provenance marketing commands measurable price premiums.
Europe Bacon Market Segmentation
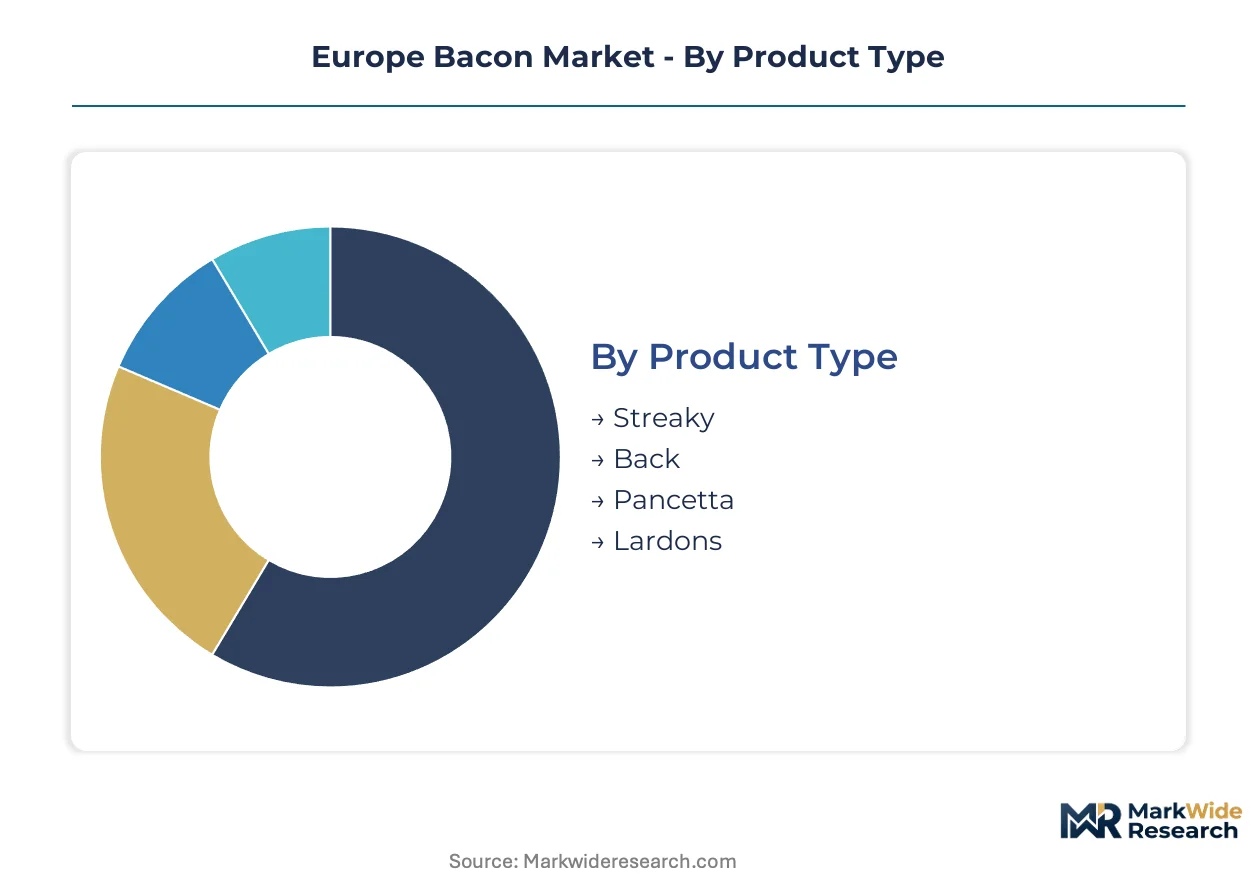
Segmentation in the Europe bacon market reveals how curing methods, packaging formats, and channel strategies align with diverging consumer priorities across the region. Manufacturers must match product specifications to specific use-cases ranging from foodservice volume procurement to premium retail artisan positioning.
Product Type:
The use-case spectrum spans from high-fat cooking applications to lean breakfast presentations across Northern and Western European markets.
- Streaky:High fat-content belly cuts deliver superior crisping performance in frying applications. Demand concentrates in German and French retail and foodservice channels where cooking versatility drives repeat purchase.
- Back:Leaner loin cuts with minimal intermuscular fat cater to preference for reduced-fat breakfast presentations. United Kingdom and Ireland households sustain premium positioning for this cut through established consumption rituals.
- Pancetta:Italian-style unsmoked cured belly, typically rolled or flat, serves charcuterie boards and recipe ingredient applications.
- Lardons:Pre-cut rectangular pieces designed for lardons de bacon applications in French cuisine and ready-meal manufacturing.
Established volume favors Streaky; emerging adoption favors Back as health-positioned formulations gain shelf space.
Packaging Type:
Cost tier differentiation separates logistics-optimized formats from convenience-oriented presentations targeting distinct retail environments.
- Vacuum Sealed:Oxygen-barrier films extend shelf life to 12-16 weeks, enabling centralized production and pan-European distribution from Danish and German curing facilities. Cold-chain efficiency makes this the default for discount retail and export-bound shipments.
- Tray Packs:Modified atmosphere packaging with easy-open features targets convenience-seeking urban households in United Kingdom and Netherlands supermarkets. Shorter shelf life requires tighter retailer inventory coordination.
- Canned:Shelf-stable retort packaging serves emergency stockpiling and military procurement specifications.
- Slices:Pre-portioned lay-flat packs reduce preparation time for breakfast service in hospitality and healthcare catering.
Volume concentration sits with Vacuum Sealed; margin expansion favors Tray Packs in premium urban retail.
Sales Channel:
Customer type fragmentation is redirecting procurement patterns from consolidated wholesale toward direct and specialty relationships.
- Supermarkets:Consolidated retail chains in Germany, France, and United Kingdom drive standardized product specifications and promotional calendar dependency. Private label penetration here compresses branded margin structures.
- Butcher Shops:Independent curing houses and specialty meat counters in Belgium, Netherlands, and Denmark command provenance premiums through farm-branded narratives and custom slicing services.
- Online Retail:Subscription and direct-to-consumer platforms in United Kingdom and Netherlands bypass traditional wholesale markups for artisan producers.
- Specialty Stores:Delicatessen and fine food retailers in France and Italy curate regional curing traditions for gift and occasion purchasing.
Supermarkets retain volume dominance; Butcher Shops capture the steepest expansion trajectory in premium tier positioning.
Consumer Type:
Application maturity separates established institutional procurement from emerging artisan hospitality sourcing patterns.
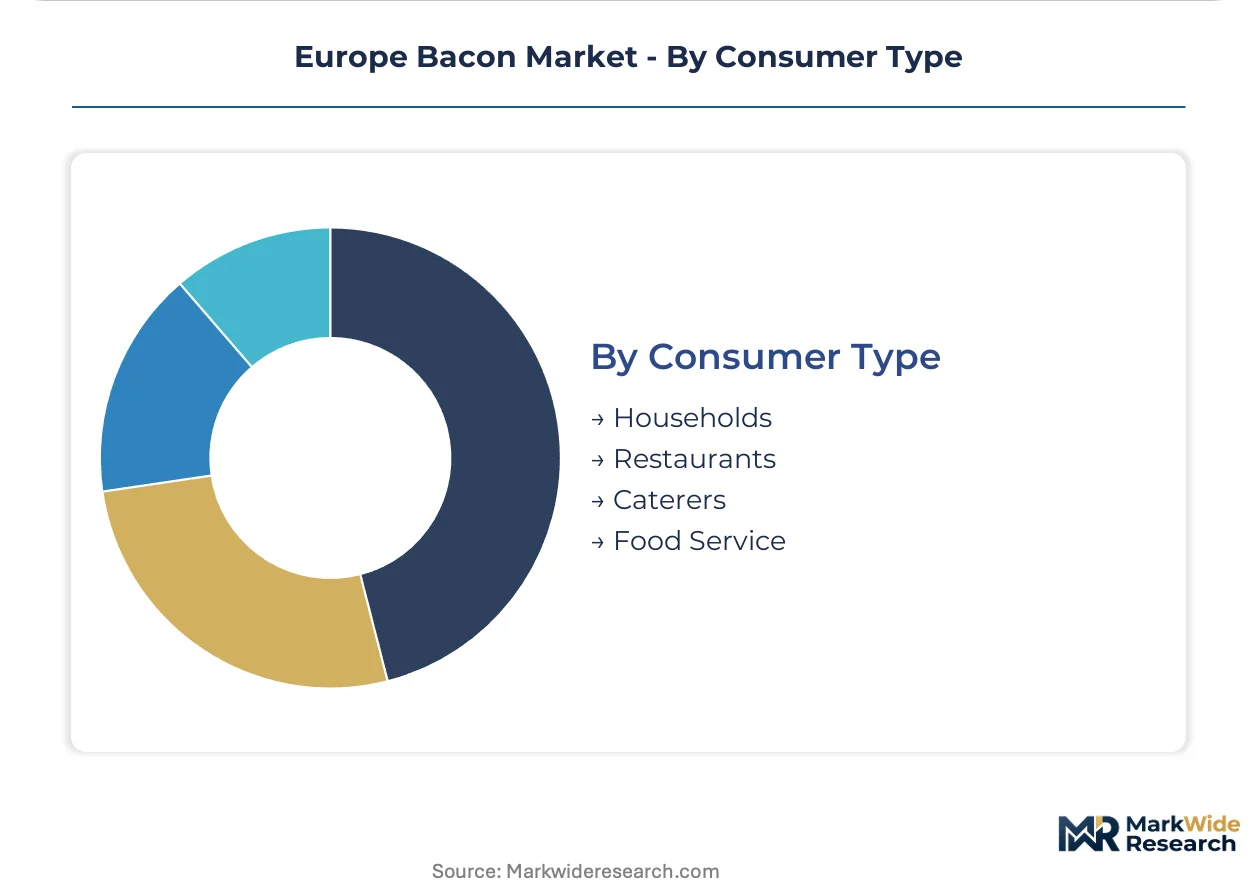
- Households:Retail purchasing across all European markets follows weekly shopping rhythms with strong private label acceptance in Germany and branded preference persistence in United Kingdom.
- Restaurants:Independent dining establishments in France and Belgium increasingly source direct from regional curing houses, bypassing consolidated foodservice distribution.
- Food Service:Contract catering and institutional feeding in Germany and Netherlands prioritizes specification consistency and cost control over provenance differentiation.
- Caterers:Event and hospitality specialists in United Kingdom and Ireland demand flexible portion formats and reliable cold-chain delivery windows.
Households anchor baseline demand; Restaurants are expanding most quickly in direct-procurement premium sourcing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal agricultural targets and EFSA nitrite-reduction mandates are redirecting investment flows across European pork supply chains. Member states are accelerating cold-chain modernization and feed certification programs to align with carbon accounting requirements. Regional curing capacity is consolidating around Denmark, Germany, and the Netherlands while premium artisan production expands in France and the United Kingdom.
Germany
Discount retail chains and foodservice distributors drive standardized bacon procurement across German markets. EFSA batch testing protocols for residual nitrite levels add verification costs for processors supplying Aldi, Lidl, and REWE networks. North Rhine-Westphalia hosts concentrated curing operations near Düsseldorf and Cologne logistics corridors serving pan-European distribution.
United Kingdom
Back bacon preference sustains premium positioning for leaner cuts in British breakfast consumption rituals. National regulators enforce cold-chain standards and labeling requirements that exceed baseline EU specifications. East Anglia and the Midlands concentrate large-scale curing facilities supplying Tesco, Sainsbury's, and Morrisons private label programs.
France
Provenance marketing commands measurable price premiums in French delicatessen and fine food retail channels. ANSM and DGCCRF coordinate enforcement of origin labeling and nitrite maximum limits across regional curing traditions. Brittany and Normandy maintain artisan lardons and pancetta production clusters supplying Parisian restaurant direct-procurement networks.
Denmark
Integrated farm-to-package pork processing anchors Danish export competitiveness across Northern European markets. EU Green Deal carbon accounting mandates accelerate feed sourcing transparency investments in Jutland farming cooperatives. Danish Crown A/S operations in Randers and Horsens exemplify vertical coordination from breeding through packaged bacon distribution.
Netherlands
Convenience-oriented retail formats and online subscription models are expanding rapidly in Dutch urban markets. ECHA and national food safety authorities monitor alternative-curing validation pathways for celery powder and natural nitrite substitutes. Gelderland and North Brabant host mid-tier processors adopting high-pressure processing equipment for quality assurance digitization.
Europe Bacon Market Competitive Landscape
On the supply side, the industry is consolidating around integrated pork processors with captive farm networks while artisan specialists carve premium niches through provenance differentiation. Scale-driven operators compete on cold-chain efficiency and private label contract density. Strategic archetypes include vertically integrated agribusiness conglomerates, regional curing specialists with direct retail relationships, and clean-label innovators exploiting regulatory tailwinds. Dominant competitive moves encompass backward integration into feed and breeding operations and technology licensing for natural curing validation.
Among integrated agribusinesses, WH Group Ltd (Smithfield) and Danish Crown A/S occupy positions exemplifying scale-driven consolidation. Finnebrogue Artisan represents the clean-label innovation archetype, anchoring premium channel expansion through nitrite-free curing technology validation.
| Leading Market Players |
|---|
| WH Group Ltd (Smithfield) |
| JBS SA (Tulip Ltd) |
| Danish Crown A/S |
| OSI Group |
| Sofina Foods |
| Karro Food Group |
| Finnebrogue Artisan |
| LT Brookes Ltd |
| Vion Food Group |
| Others |
Supply & Pricing Matrix
North Rhine-Westphalia's curing facility cluster near Düsseldorf and Cologne anchors pan-European bacon supply, translating concentrated production capacity into pricing leverage for processors serving Aldi, Lidl, and REWE discount networks. This geographic concentration enables batch-scale efficiency that downstream buyers struggle to fragment through multi-sourcing.
Pricing Analysis
Certification level (EFSA-compliant vs. clean-label validated) creates the primary spread between economy and premium tiers. Three-tier pricing structure across premium, standard, and economy levels stratifies by residual nitrite verification, organic feed certification, and provenance traceability. Cost compression in the standard tier is intensifying because fixed retail contracts expose processors to pork belly spot volatility. Discount retail chains in Germany exhibit highest price sensitivity, while artisan butcher shops in Belgium and France absorb premiums for farm-branded narratives.
Supply Chain Analysis
EU Green Deal agricultural targets function as de facto export-control mechanisms limiting non-compliant feed flows into premium curing operations. Geographic supply concentration centers on Denmark, Germany, and the Netherlands, with Brittany and Normandy anchoring artisan capacity. Raw material dependencies rest on Danish Jutland farming cooperatives for certified feed, German engineering for high-pressure processing equipment, and French regional curing traditions for specialty formats. Single-source vulnerability concentrates in Danish Crown A/S integrated operations. Distribution runs through cold-chain logistics corridors serving pan-European retail and direct-to-restaurant networks in Paris and London.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated discount retail chains in Germany and fragmenting toward independent restaurants in France and Belgium, compressing margin structures for mid-tier processors caught between volume and provenance demands.
For Market Incumbents: Insulate margin position through backward integration into Jutland feed certification programs and captive breeding operations. EFSA nitrite-reduction deadlines threaten processors lacking validated alternative-curing pipelines. Prioritize laboratory capacity expansion for batch testing compliance and secure shelf space in REWE and Aldi private label programs before reformulation costs accelerate. For New Entrants and Emerging Players: Build out direct-to-restaurant procurement relationships in Paris and London, bypassing consolidated wholesale channels. Poland and Romania present the most penetrable geographies as cold-chain infrastructure modernizes. Target vacuum-sealed premium bacon for urban convenience retail in the Netherlands, leveraging subscription platform economics validated in UK markets. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because EFSA alternative-curing validation pathways offer first-mover advantage to manufacturers securing approved formulation pipelines ahead of compliance deadlines. Acquisition target archetype: mid-tier processors with laboratory infrastructure and retailer relationships but lacking clean-label R&D capacity. Watch EFSA enforcement timeline acceleration as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Curing Validation | EFSA approval for celery powder and natural nitrite substitutes secures premium channel shelf space ahead of regulatory deadlines. |
| Backward Integration into Feed Certification | EU Green Deal carbon accounting mandates require farm-level transparency investments across Danish and German supplier networks. |
| Direct-to-Restaurant Distribution Buildout | Bypassing consolidated foodservice wholesalers captures provenance premiums in Paris and London boutique hospitality markets. |
| High-Pressure Processing Equipment Deployment | Danish and German facilities digitize quality assurance workflows to compress release-to-market timelines for export shipments. |
| Poland and Romania Cold-Chain Expansion | Vacuum-sealed premium bacon penetration depends on modernized logistics infrastructure in underpenetrated Eastern European markets. |
Research Methodology
Desk research of EU regulatory filings, EFSA scientific opinions, pork industry trade data, and retail audit databases preceded structured interviews with curing facility operations managers, discount retail category buyers, artisan butcher shop proprietors, and restaurant procurement directors. Primary fieldwork combined telephone and in-person exchanges across Germany, France, United Kingdom, Denmark, and Netherlands. Secondary validation drew from Danish Crown A/S sustainability disclosures, national cold-chain standards documentation, and customs records for pork product flows. Bottom-up segment sizing triangulated against top-down market value estimates.
Assumptions held EFSA nitrite-reduction enforcement timelines and EU Green Deal feed certification requirements constant across the analysis window, while varying pork belly supply volatility and discount retail promotional intensity. Segmentation modeling incorporated curing method, packaging format, sales channel, and consumer type dimensions with regional production hub clustering. CAGRs derived from trend extrapolation of volume and value trajectories, calibrated against historical elasticity patterns for premium versus economy tier demand. Forecast inputs included cold-chain infrastructure investment pipelines and alternative-curing technology validation statuses.
The forecast holds incumbent behavior within observed patterns; aggressive moves by clean-label specialists or accelerated EFSA enforcement would shift outcomes. Material shifts in feed grain price stability, discount retail consolidation, or natural curing shelf-life breakthroughs would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Europe Poultry Meat Market
Meat Products
North America Low Fat Sausage Market
Meat Products
Hot Dog and Sausages Market
Meat Products
Meat-Based FPP Market
Meat Products
Middle East Poultry Meat Market
Meat Products
Reduced Fat Meat Market
Meat Products
Bacon Flavors Market
Meat Products
Canned Beef Market
Meat Products
Rendered Poultry Products Market
Meat Products
Grassfed Jerky Market
Meat Products
United States Frozen Meat Market
Meat Products
Low-Fat Chorizo Market
Meat Products
South Africa Processed Meat Market
Meat Products
Organic Eggs Market
Meat Products
Meat Products Market
Meat Products
Nitrate-Free Bacon Market