
 Organic Eggs Market | 2026-2036
Organic Eggs Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Eggs Market Outlook
Restaurant procurement is unwinding conventional shell egg purchasing as premium foodservice operators seek certified supply chains with full traceability. Cal-Maine Foods leverages its integrated feed-to-retail infrastructure to dominate volume supply for conventional retail channels. Vital Farms differentiates through pasture-raised certification and premium positioning in specialty grocery. Pete and Gerry's anchors the Northeast with distributed small-farmer networks that compete on regional freshness claims.
Organic eggs are shell or processed egg products derived from hens fed certified organic, non-GMO diets without antibiotics or synthetic hormones, meeting USDA Organic or equivalent national standards for outdoor access and animal welfare. Shell eggs occupy the mature volume base while liquid eggs capture margin in food processing and bakery manufacturing where pasteurized convenience commands premium pricing. Specialty stores and farmers' markets sustain the fastest-growing channel segment as direct-to-consumer relationships build price resilience against supermarket commoditization.
USDA Organic certification and FDA food safety rules govern product standards and interstate commerce, while state-level mandates in California and Massachusetts dictate cage-free housing requirements that reshape production economics. The EU Green Deal and EFSA welfare standards constrain import access for non-compliant suppliers. Stakeholders must monitor evolving patchwork regulations across multiple jurisdictions to anticipate compliance cost shifts and sourcing strategy adjustments.
Market Dynamics
State-level cage-free mandates in California and Massachusetts are forcing production infrastructure upgrades across the supply base. These compliance pressures concentrate cost burdens on mid-scale producers while advantaging integrated operators with capital reserves.
Growth Catalysts
- USDA Organic certification:Foodservice operators in metropolitan clusters demand certified supply chains with full traceability, pulling volume toward compliant producers.
- Pasteurization technology:Liquid egg processing advances enable margin capture in bakery manufacturing where convenience commands premium positioning.
- Pacific Northwest demand concentration:Urban consumer density in Seattle and Portland sustains direct-to-channel relationships that resist supermarket commoditization.
Market Restraints
- Feed input volatility:Organic grain supply tightness creates cost pressure that squeezes producer margins during weather-driven harvest shortfalls.
- EU Green Deal constraints:EFSA welfare standards block import access for non-compliant suppliers, limiting sourcing flexibility for European buyers.
- Conventional shell egg substitution:Cage-free (non-organic) alternatives capture price-sensitive demand segments with lower certification burdens.
Strategic Opportunities
- Farmers' market channel expansion:Direct-to-consumer relationships in specialty retail build price resilience and brand loyalty outside conventional grocery.
- Blockchain traceability convergence:Distributed ledger integration with existing certification systems enables premium positioning through verified provenance claims.
- Massachusetts Act to Prevent Cruelty:State-level housing mandates create compliant supply scarcity that rewards early-adopting producers with volume commitments.
Industry Challenges
- Outdoor access infrastructure:Pasture-raised certification requires land conversion and rotational systems that extend capital deployment timelines.
- Multi-jurisdiction compliance:Producers operating across state lines face overlapping USDA Organic, FDA safety, and state housing rule requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Eggs Market |
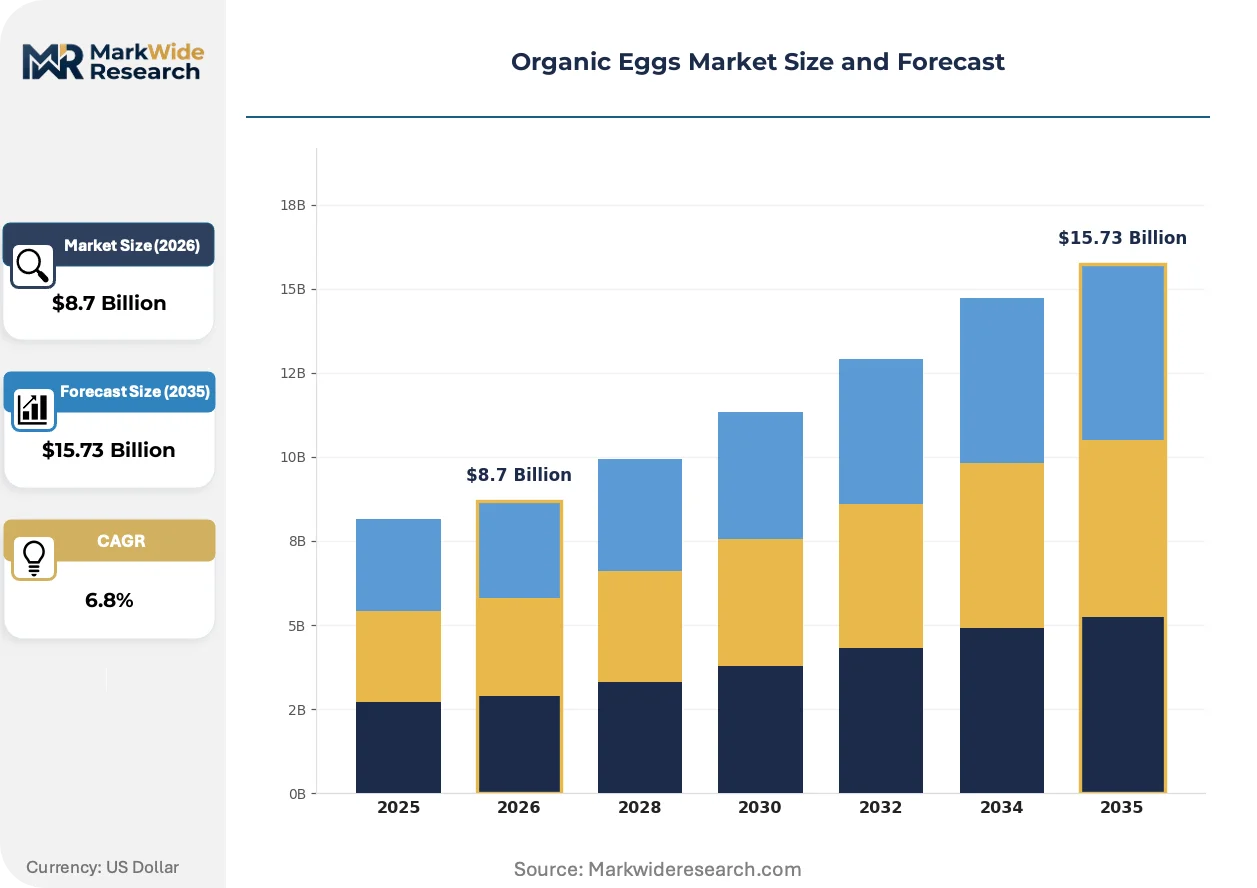
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shell Eggs, Liquid Eggs, Dried Eggs, Hard-Boiled Eggs Distribution Channel: Supermarkets, Online Retail, Farmers' Markets, Specialty Stores Packaging Type: Cartons, Trays, Eco-Friendly Packaging, Bulk Packaging End User: Households, Restaurants, Bakeries, Food Processing |
| Companies Covered | Cal-Maine Foods, Organic Valley, Vital Farms, Happy Egg Co., Eggland's Best, Blue Sky Family Farms, Farmhouse Eggs, Pete and Gerry's, NestFresh Eggs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Eggs Market Strategic Shifts
Technology and certification standards are restructuring competitive advantage around traceability infrastructure. Producers investing in verification systems capture margin from buyers seeking defensible sourcing claims.
Automated environmental monitoring systems track hen welfare metrics in real-time through sensor networks deployed across pasture and housing facilities. Premium foodservice operators in the Northeast are adopting these verification tools to satisfy procurement audit requirements. This sensor infrastructure is supplanting manual inspection protocols that previously dominated third-party certification workflows.
The EU Green Deal's Farm to Fork strategy tightens animal welfare benchmarks for imported egg products entering European retail channels. Domestic producers in France and Germany face accelerated barn conversion timelines to meet EFSA standards ahead of enforcement deadlines. Specialty stores in Northern Europe are responding by consolidating supplier relationships around verified compliant sources.
Restaurant procurement teams are bundling shell and liquid egg contracts with traceability requirements that extend beyond conventional specifications. Large-format bakery manufacturing in the Midwest is replacing spot-market purchasing with annual agreements tied to certified supply pools. This contract consolidation is most visible in metropolitan foodservice clusters where operator scale enables direct producer negotiations.
Organic Eggs Market Segmentation
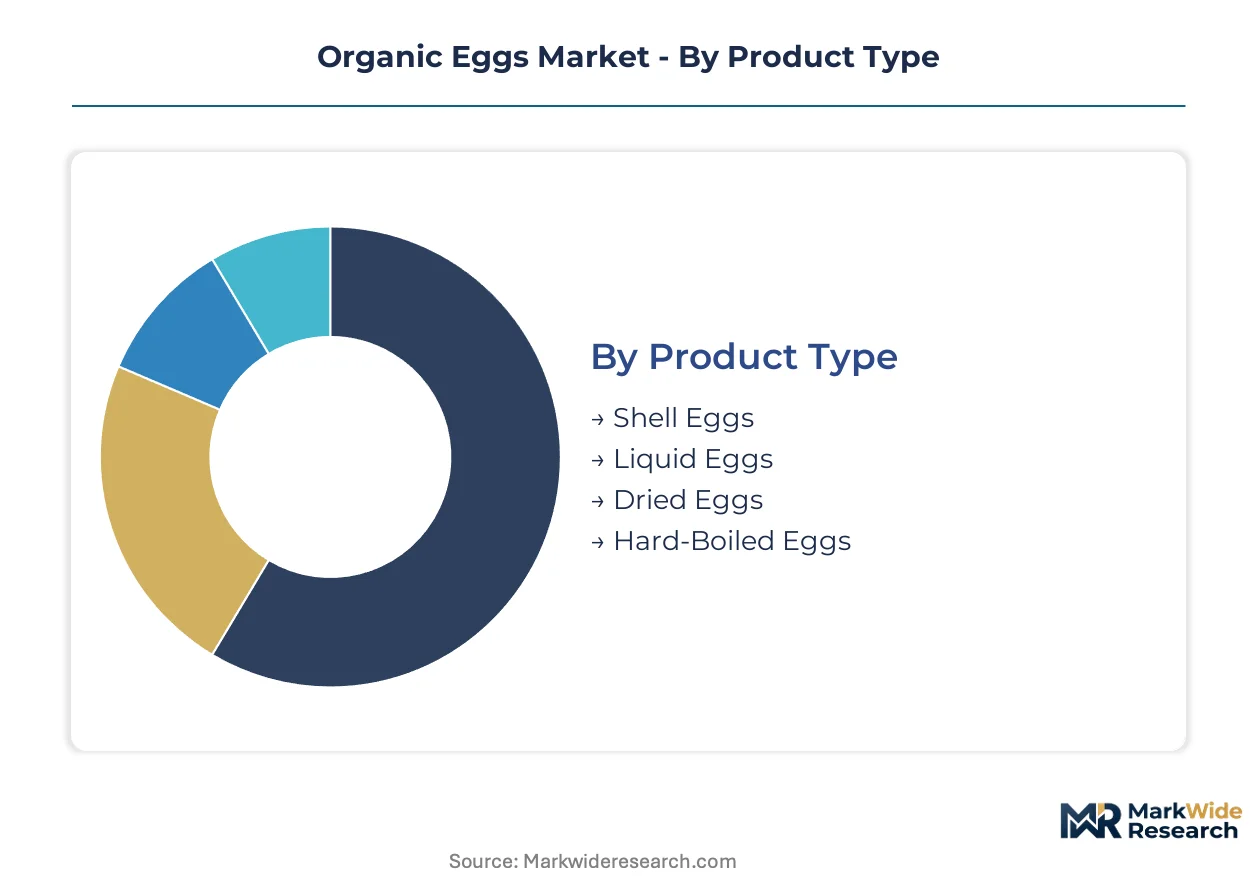
Segmentation in the organic eggs market reveals how certification tiers and channel structures create distinct competitive battlegrounds. Producers must align product form, packaging investment, and distribution strategy with the specific compliance and traceability demands of each buyer category.
Product Type:
Shell eggs face the most intense substitution pressure from cage-free alternatives that undercut on price while mimicking welfare claims. Liquid and dried formats benefit from higher switching costs in industrial applications.
- Shell Eggs:Whole eggs in their natural form dominate retail shelves and household consumption. Foodservice procurement in Seattle and Portland metropolitan clusters prioritizes shell eggs with full USDA Organic traceability for menu transparency requirements. Substitution risk from lower-cost cage-free shell eggs compresses margin in conventional grocery channels.
- Liquid Eggs:Pasteurized egg products supplied in refrigerated or frozen form eliminate shell handling for industrial users. Bakery manufacturing in the Midwest consolidates purchasing around certified liquid supply pools to secure consistent volume for automated production lines. FDA pasteurization standards create compliance barriers that protect incumbent suppliers.
- Dried Eggs:Dehydrated egg powder extends shelf stability for remote distribution and emergency food programs. Powdered formats concentrate in institutional procurement and export markets where refrigeration infrastructure remains limited.
- Hard-Boiled Eggs:Pre-cooked peeled eggs serve ready-to-eat retail and foodservice convenience segments. Grab-and-go demand in airport and hospital food contracts drives regional processing capacity expansion.
Shell eggs retain volume leadership; liquid eggs hold the steepest expansion curve.
Distribution Channel:
Channel selection directly determines pricing power and customer acquisition economics, with cost-to-serve varying dramatically across the four pathways.
- Supermarkets:Conventional grocery chains move the highest absolute volumes but commoditize organic eggs through promotional pricing and private label substitution. Slotting fees and margin pressure from retail consolidation favor suppliers with national scale.
- Online Retail:E-commerce platforms enable subscription models and direct-to-door delivery for convenience-focused urban households. Cold-chain logistics investments separate viable entrants from speculative players.
- Farmers' Markets:Direct producer-consumer relationships in Pacific Northwest metropolitan clusters sustain price premiums through narrative differentiation and freshness claims. Seasonal supply fluctuations limit year-round penetration.
- Specialty Stores:Natural food retailers and co-ops curate assortment around certification depth and local sourcing stories. These channels capture the highest margin per dozen but constrain volume through footprint limitations.
Supermarkets dominate absolute volume; specialty stores gain share fastest among premium-positioned suppliers.
Packaging Type:
Packaging investment reflects downstream channel requirements and sustainability positioning, with material choices increasingly subject to state-level environmental mandates.
- Cartons:Molded pulp containers remain the standard for dozen-count retail presentation. California and Massachusetts packaging waste regulations are accelerating fiber-based material adoption.
- Trays:Plastic or fiber flats optimize foodservice and bakery procurement for volume handling. Reusable tray systems in institutional contracts reduce per-unit packaging cost.
- Eco-Friendly Packaging:Compostable or recyclable materials command shelf space premiums in specialty retail and satisfy corporate sustainability procurement criteria.
- Bulk Packaging:Palletized loose eggs or large-format containers minimize unit cost for industrial food processing and bakery manufacturing where downstream handling occurs in controlled environments.
Cartons maintain category volume leadership; eco-friendly formats expand most quickly in coastal metropolitan markets.
End User:
End-user segmentation maps directly to certification stringency and contract structure, with commercial buyers extracting traceability requirements that exceed retail standards.
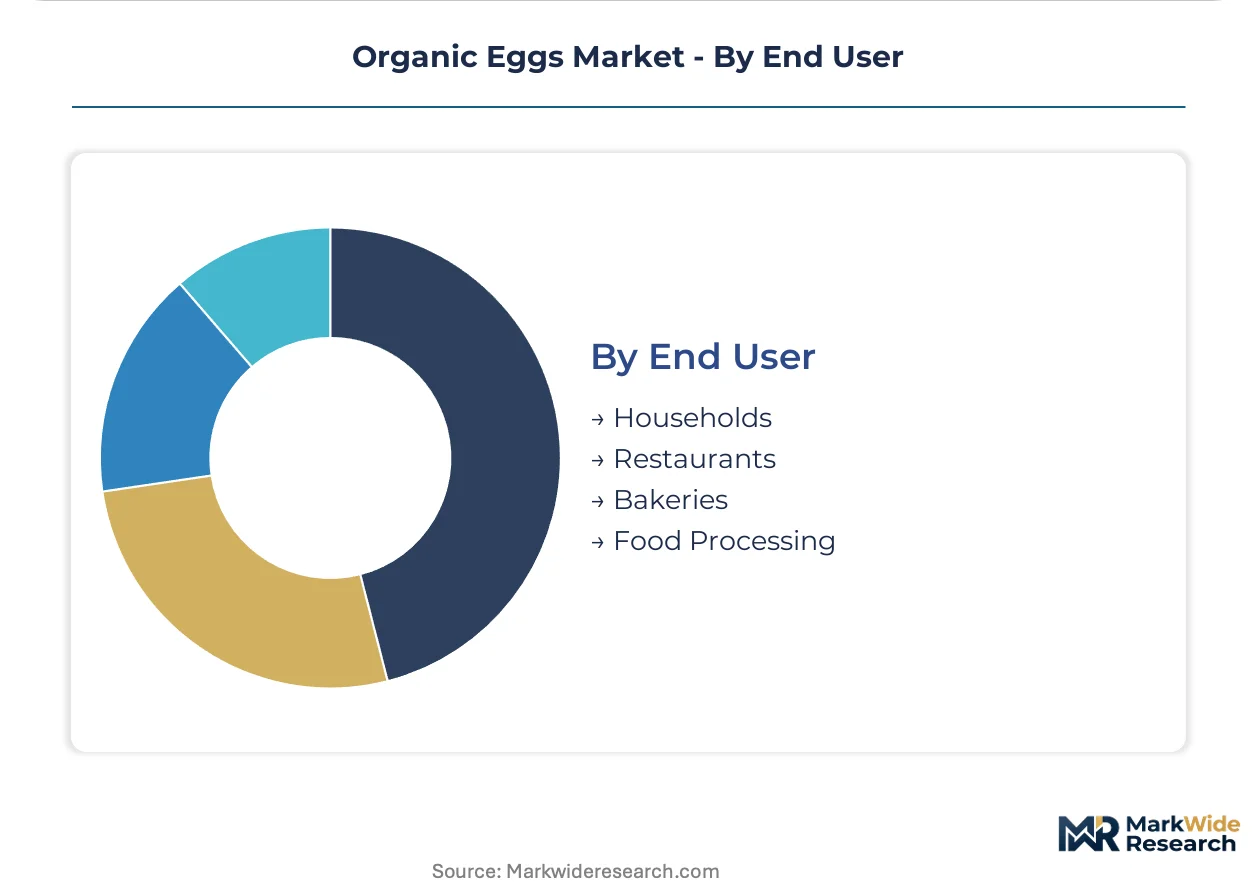
- Households:Individual consumers purchase through retail channels with price sensitivity moderated by health and welfare concerns. Subscription models in online retail build recurring revenue for direct-to-consumer brands.
- Restaurants:Premium foodservice operators in metropolitan clusters demand certified supply chains with full provenance documentation for menu storytelling. Annual contract structures are replacing spot purchasing for volume security.
- Bakeries:Manufacturing-scale users prioritize liquid and dried egg formats for production efficiency. Pasteurization requirements and consistent protein specification drive supplier consolidation.
- Food Processing:Industrial manufacturers of mayonnaise, pasta, and prepared foods source bulk formats with stringent safety certification. Multi-year supply agreements with penalty clauses dominate procurement practice.
Households retain volume leadership; restaurants pursue the steepest expansion trajectory as premium dining accelerates certified sourcing adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States organic egg exports flow primarily into Canadian retail channels and select European foodservice buyers seeking USDA Organic certified supply. This trade corridor concentrates value capture among integrated producers with cold-chain logistics spanning the border.
United States
Pacific Northwest metropolitan clusters in Seattle and Portland sustain direct-to-channel relationships that resist supermarket commoditization. California Proposition 12 and Massachusetts Act to Prevent Cruelty mandate cage-free housing requirements that reshape production economics across state lines. Texas and Iowa production zones supply volume to Northeast retail chains seeking regional freshness claims.
Germany
Natural food retailers and co-ops in Berlin and Hamburg curate assortment around certification depth and local sourcing stories. EU Green Deal Farm to Fork strategy tightens animal welfare benchmarks for domestic producers and import suppliers alike. Bavarian farming cooperatives convert barn infrastructure to meet EFSA standards ahead of enforcement deadlines.
France
Specialty stores in Paris and Lyon consolidate supplier relationships around verified compliant sources as import standards tighten. ANSM and national agricultural regulators enforce welfare labeling requirements that differentiate organic from cage-free alternatives. Brittany and Normandy production regions face accelerated conversion timelines for existing facilities.
United Kingdom
Premium foodservice operators in London demand certified supply chains with full provenance documentation for menu storytelling. Post-Brexit regulatory divergence from EU standards creates compliance complexity for cross-border sourcing. Midlands and Yorkshire farming networks supply regional freshness claims to metropolitan retail buyers.
Netherlands
Randstad urban consumer density sustains subscription models and direct-to-door delivery for convenience-focused households. EFSA welfare standards and national environmental regulations constrain expansion of conventional housing systems. Gelderland and Overijssel production zones specialize in pasture-raised certification for export markets.
Organic Eggs Market Competitive Environment
Listed leaders compete with private specialists across certification tiers and channel access. The vendor base separates into integrated feed-to-retail operators, pasture-raised specialists, and distributed small-farmer networks. Three archetypes dominate: scale-driven conventional suppliers, premium-positioned welfare certifiers, and regional freshness aggregators. Capacity expansion and strategic partnerships represent the dominant competitive moves as producers secure compliant housing infrastructure ahead of state mandate deadlines.
Within the scale-driven tier, Cal-Maine Foods occupies a position exemplifying integrated infrastructure dominance across conventional retail channels. Vital Farms and Pete and Gerry's represent the premium-positioned archetype, with the former anchoring pasture-raised certification and the latter sitting within distributed small-farmer network structures. These three companies illustrate how certification depth and channel strategy determine competitive positioning.
| Leading Market Players |
|---|
| Cal-Maine Foods |
| Organic Valley |
| Vital Farms |
| Happy Egg Co. |
| Eggland's Best |
| Blue Sky Family Farms |
| Farmhouse Eggs |
| Pete and Gerry's |
| NestFresh Eggs |
| Others |
Value Chain & Pricing Dynamics
USDA Organic certification gates both supply qualification and price differentiation simultaneously, filtering producers through feed sourcing and outdoor access mandates that compress margins for non-compliant operators while enabling premium capture for certified suppliers. State-level housing rules in California and Massachusetts layer additional compliance costs that reshape competitive economics across the supply base.
Pricing Analysis
Conventional shell egg pricing, pasture-raised premium tiers, and liquid pasteurized formats stratify across certification depth and channel access. Price differentiation hinges on USDA Organic tier and regional freshness claims, with Pacific Northwest metropolitan buyers absorbing the steepest premiums. Pricing pressure stems from cage-free non-organic alternatives that undercut welfare-positioned shell eggs in conventional grocery. Food processing manufacturers exhibit highest price sensitivity due to volume scale and format substitutability, while specialty retail channels demonstrate lowest sensitivity through narrative-driven procurement.
Supply Chain Analysis
Container availability constraints on trans-Pacific lanes elevate inbound logistics costs for organic feed grain shipments originating in Argentina and Ukraine. Production concentrates in the United States, Germany, and the Netherlands, drawing from organic corn, soybean meal, and rotational pasture land. The supply chain rests on single-source vulnerability in certified feed grain origination. Distribution runs through integrated feed-to-retail operators, regional farmer networks, and direct-to-channel relationships in metropolitan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
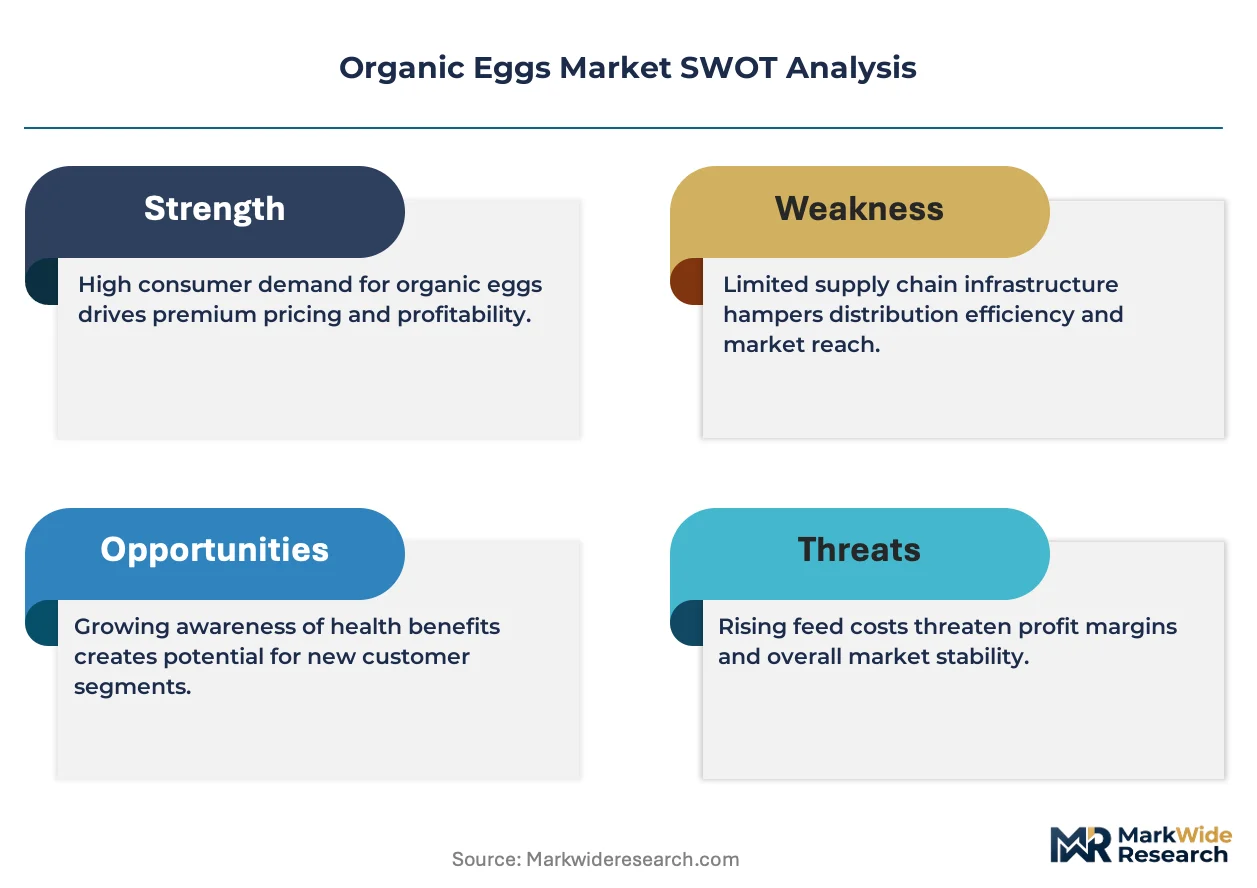
Organic eggs represent a high-growth disruption as blockchain traceability and automated welfare monitoring converge to restructure competitive advantage around verification infrastructure. State mandate deadlines for cage-free housing accelerate capital deployment timelines and consolidate supply around compliant producers.
For Market Incumbents: Shield market position through backward integration into certified organic feed production and accelerated barn conversion ahead of Massachusetts and California enforcement timelines. Secure long-term supply agreements with foodservice operators in Seattle and Portland metropolitan clusters to lock in volume commitments before compliant supply scarcity intensifies. Invest in sensor-based welfare verification systems to satisfy procurement audit requirements from premium restaurant buyers.
For New Entrants and Emerging Players: Differentiate on pasture-raised certification depth and direct-to-consumer channel relationships outside conventional grocery commoditization. Target farmers' market and specialty retail white space in Pacific Northwest urban clusters where narrative differentiation sustains price premiums. Pursue subscription-based online retail models that bypass slotting fee barriers and build recurring revenue through cold-chain logistics investment.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across compliant housing infrastructure as state mandates force accelerated barn conversion timelines. Long-term viability favors integrated operators with captive feed supply and multi-jurisdiction compliance capabilities. Acquisition targets should demonstrate existing USDA Organic certification, distributed small-farmer network access, or established direct-channel relationships in high-premium metropolitan markets. Monitor EU Green Deal enforcement deadlines as signal for import access compression and domestic European producer consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Feed | Captive supply of certified grain insulates margin from harvest volatility and tightens traceability claims. |
| Blockchain Traceability Deployment | Distributed ledger integration with USDA Organic certification enables premium positioning through verified provenance. |
| Compliant Housing Infrastructure Expansion | Accelerated barn conversion ahead of Massachusetts and California deadlines secures volume commitments from foodservice buyers. |
| Direct-to-Channel Relationship Building | Farmers' market and specialty retail presence builds price resilience against supermarket promotional pressure. |
| Liquid Egg Processing Capacity Addition | Pasteurization infrastructure captures margin in Midwest bakery manufacturing where convenience commands premium positioning. |
Study Parameters
Desk research of USDA Organic certification databases, FDA food safety filings, and state regulatory mandate documents preceded structured interviews with feed mill operators, egg processing facility managers, foodservice procurement directors, and specialty retail category buyers. Secondary validation drew from agricultural trade association publications, customs import records, and SEC filings from publicly traded producers. Bottom-up volume estimates from production facility capacity and top-down demand segmentation from channel consumption data were triangulated to reconcile supply-demand balances.
Variance decomposition across product form, certification tier, distribution channel, and end-user segment shaped the analytical framework over the projection horizon. CAGRs were derived from trend extrapolation of certified flock expansion rates and channel shift dynamics. Modeled inputs included organic feed grain price indices, state mandate compliance timelines, and metropolitan consumer density metrics for direct-channel viability assessment.
Material uncertainties — feed input volatility from weather-driven harvest shortfalls, regulatory enforcement timing variations across jurisdictions, and substitution elasticity between cage-free and organic tiers — sit outside the modeled envelope. Forecasts reflect assumptions about certification adoption trajectories and channel migration patterns. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Asia-Pacific Red Meat Market
Meat Products
Fresh Organic Chicken Market
Meat Products
Europe Animal Protein Market
Meat Products
Global Edible Meat Market
Meat Products
Middle East Edible Meat Market
Meat Products
Shark Meat Market
Meat Products
North America Processed Meat Market
Meat Products
Meat Flavors Market
Meat Products
Meat Ingredients Market
Meat Products
Hot Dog and Sausages Market
Meat Products
Meat Emulsions Market
Meat Products
Beef Extract Market
Meat Products
Global Beef Market
Meat Products
Global Lab-Based Meat Market
Meat Products
Poultry Processing Meat Market
Meat Products
Meat Paste Market