
 Beef Liver Market | 2026-2036
Beef Liver Market Size, Share, and Industry Trends Forecast 2026-2036
Beef Liver Market Insights
The price gap between premium grass-fed liver and commodity grain-fed product is hardening as certification requirements proliferate. Tyson Foods leverages its integrated feedlot-to-retail network to sustain volume leadership in commodity tiers. Danish Crown A/S differentiates through specialized cold-chain logistics that preserve organoleptic quality for European premium buyers.
Beef liver comprises the hepatic organ of cattle, characterized by dense concentrations of heme iron, vitamin A retinol, and B12 cyanocobalamin, typically harvested at 12-18 months and flash-frozen within 4 hours to preserve nutritional density. Its primary commercial purpose spans human consumption, pet nutrition formulations, and pharmaceutical-grade desiccated extract production. Fresh product commands margin concentration in specialty retail channels, while powdered form is expanding fastest within nutritional supplements due to encapsulation compatibility. Frozen whole liver retains maturity in foodservice procurement, where institutional buyers prioritize yield consistency over provenance labeling.
USDA-FSIS mandates continuous inspection and HACCP compliance for all domestic beef liver processing, while EU Regulation 853/2004 imposes specific hygiene requirements for fresh offal destined for human consumption. These frameworks elevate capital barriers for new entrants and redirect investment toward certified facilities. Stakeholders must monitor evolving maximum residue limits for veterinary pharmaceuticals in liver tissue, as regulatory tightening in major consuming jurisdictions will reshape supplier qualification criteria and sourcing geography decisions.
Market Dynamics
USDA-FSIS inspection mandates and EU cold-chain directives are tightening traceability requirements, forcing processors to redirect capital toward certified facilities and reshape sourcing geography decisions across the value chain.
Growth Catalysts
- Pet nutrition expansion:Formulators are expanding liver-derived ingredient sourcing for premium kibble and raw diets, creating dedicated off-take agreements with Brazilian processors.
- EU Regulation 853/2004 compliance:Specific hygiene requirements for fresh offal destined for human consumption are elevating capital barriers and redirecting investment toward certified facilities that capture premium margins.
- São Paulo processing cluster:Demand is concentrating in Brazil's São Paulo state, where integrated slaughter-to-freeze infrastructure supports flash-frozen export volumes within the 4-hour nutritional preservation window.
Market Restraints
- Veterinary pharmaceutical residue limits:Regulatory tightening in major consuming jurisdictions is reshaping supplier qualification criteria and forcing geographic sourcing pivots away from high-antibiotic-use regions.
- Flash-freeze infrastructure concentration:Dense heme iron and vitamin A retinol preservation requires capital-intensive blast-freeze capacity, limiting viable processing sites to established cold-chain hubs.
- Plant-based iron supplementation:Ferrous bisglycinate and microencapsulated mineral blends are displacing desiccated liver in mid-tier nutritional supplements, compressing powder-form margins.
Strategic Opportunities
- Pharmaceutical-grade desiccated extract:B12 cyanocobalamin isolation for injectable formulations represents an underpenetrated high-margin channel requiring GMP-certified processing lines.
- Direct-to-consumer frozen subscription:Specialty retail channels are bypassing traditional foodservice procurement through temperature-controlled last-mile logistics targeting organoleptic-conscious households.
- Grass-fed certification premiums:Provenance labeling requirements from EFSA-aligned auditors are creating tiered pricing separation between pasture-raised and commodity grain-fed product lines.
Industry Challenges
- HACCP compliance timeline:Continuous inspection mandates from USDA-FSIS extend facility qualification periods, delaying revenue recognition for new processing entrants by 12-18 months.
- Cold-chain reconfiguration friction:EU directive alignment requires retrofitting legacy blast-freeze tunnels with real-time temperature logging and blockchain traceability integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beef Liver Market |
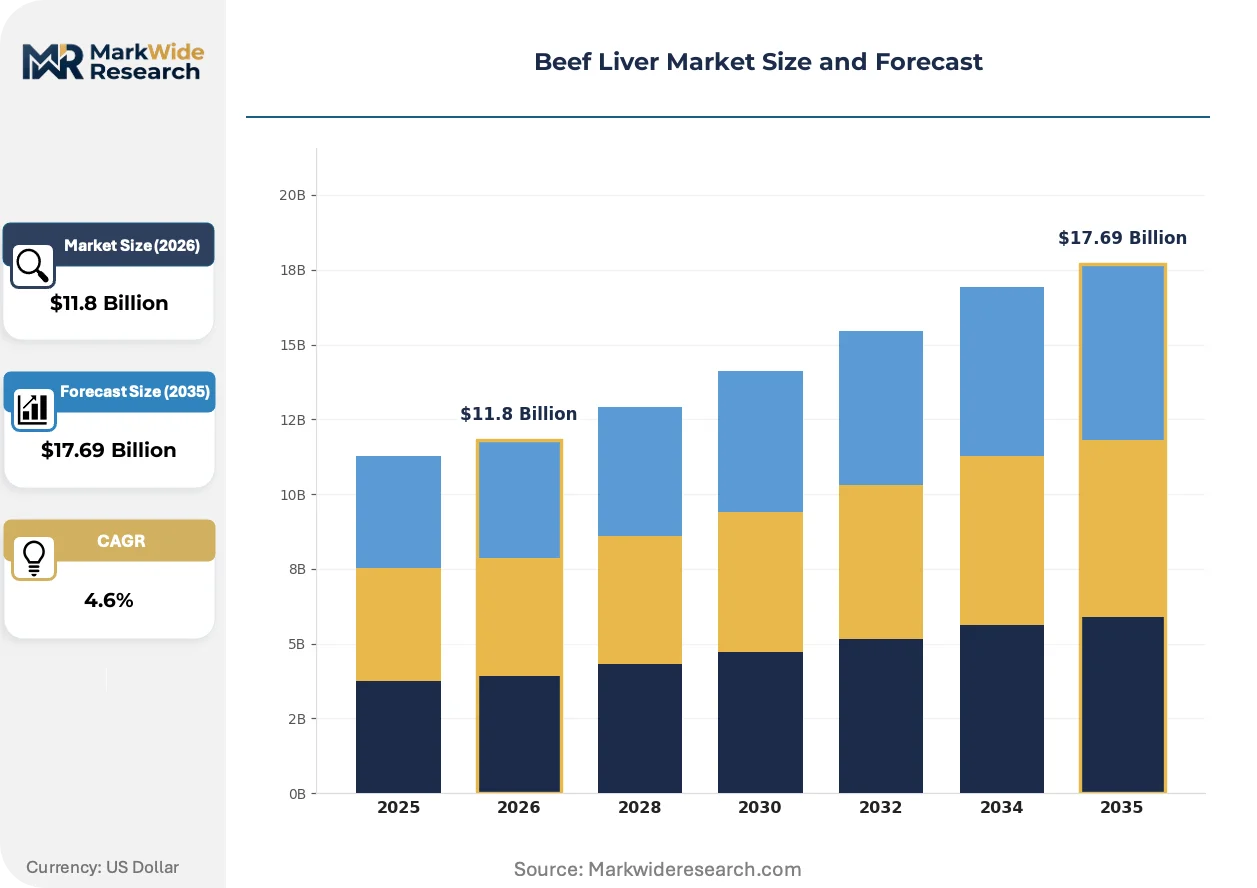
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $17.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh, Frozen, Dried, Processed Form: Whole, Slices, Cubes, Powder Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesalers End User: Households, Restaurants, Food Manufacturers, Nutritional Supplements |
| Companies Covered | Tyson Foods, Inc., Cargill, Incorporated, JBS USA Holdings, Inc., National Beef Packing Company, LLC, OSI Group, Hormel Foods Corporation, Danish Crown A/S, Greater Omaha Packing, Vion Food Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beef Liver Market Trends and Innovations
Flash-freeze technology and encapsulation chemistry are actively rewriting how nutritional density is preserved and delivered, compressing traditional processing windows while opening new formulation channels for liver-derived inputs.
Blast-freeze tunnel systems with liquid nitrogen injection are rewriting the economics of heme iron preservation. Pharmaceutical extractors and premium pet food formulators are adopting these systems at replacement cycle pace. The technology is rewriting yield-loss calculations by reducing cellular rupture during temperature descent, enabling higher retinol recovery rates for capsule-grade powder.
EU Regulation 853/2004 annex amendments are tightening specific hygiene requirements for fresh offal handling. Slaughterhouses must now deploy dedicated offal processing rooms with positive-pressure airlocks. Premium human-consumption tiers in Germany and France are responding by segregating liver harvest streams at the kill floor, creating parallel supply chains with distinct capital requirements.
Institutional foodservice buyers are unbundling yield-consistency contracts from provenance specifications. Quick-service restaurant chains now source frozen whole liver through direct processor agreements rather than broadline distributors. This pattern is most visible in Brazil's São Paulo state, where vertical beef processors are capturing margin previously allocated to foodservice redistribution networks.
Beef Liver Market Segmentation
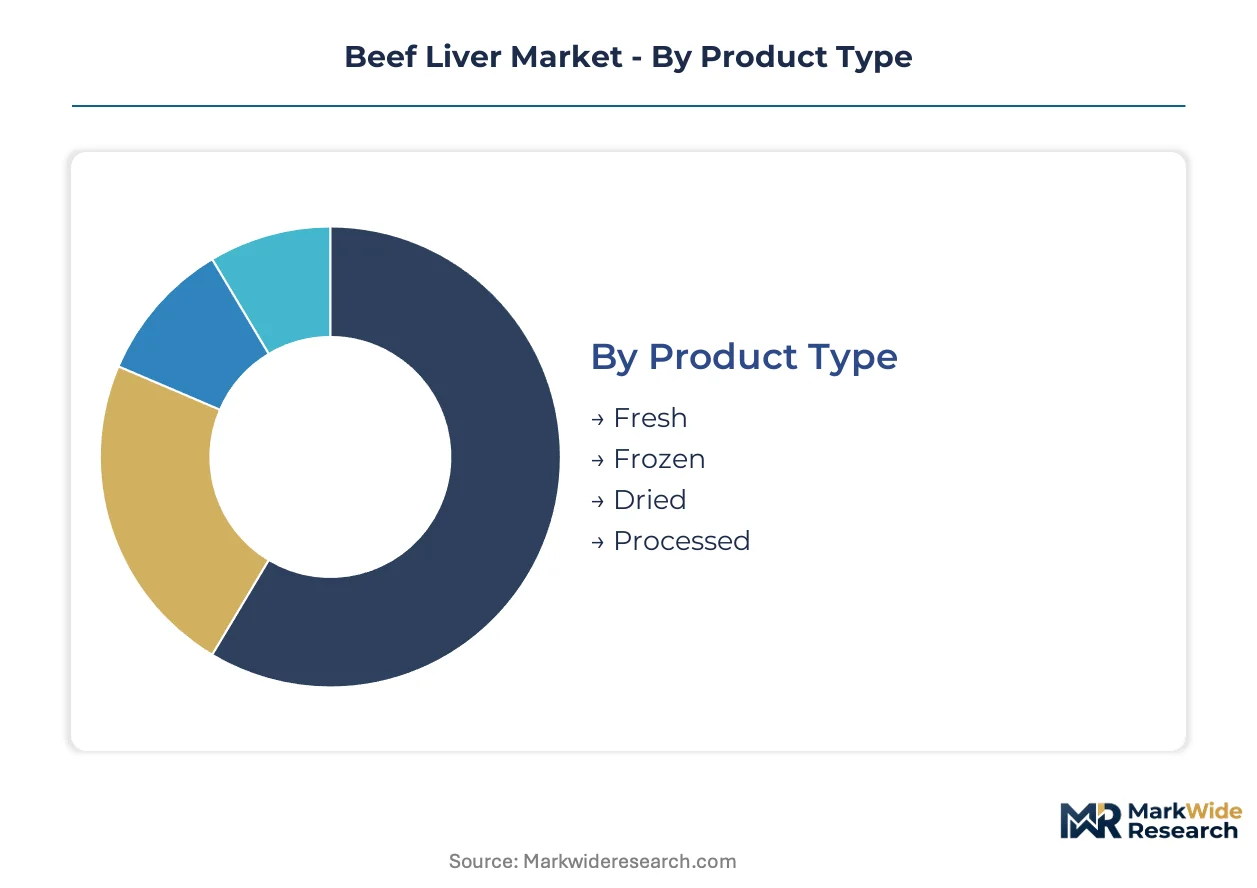
Beef liver segmentation tracks how preservation technology, form factor, and channel economics partition value capture across the supply chain. Each dimension carries distinct capital requirements and margin profiles that reshape processor investment priorities.
Product Type:
Upgrade cycles in blast-freeze infrastructure and desiccation equipment are redefining which preservation formats command premium placement.
- Fresh:Unprocessed hepatic tissue maintained at 0-4°C with 48-72 hour shelf life. Demand concentrates in Germany's specialty butcher networks where EFSA-aligned auditors enforce cold-chain documentation for premium human consumption tiers.
- Frozen:Blast-frozen within four hours post-slaughter to lock heme iron and retinol density. São Paulo state processors capture institutional foodservice procurement through direct agreements that bypass traditional redistribution networks.
- Dried:Low-temperature dehydration for shelf-stable nutritional inputs. Brazilian exporters supply capsule-grade powder to supplement formulators seeking encapsulation compatibility.
- Processed:Value-added preparations including pâtés and pre-portioned packs. Retail-ready formats serve time-constrained household segments in urban European markets.
Volume placements concentrate in Frozen; the faster expansion belongs to Dried.
Form:
Customer procurement patterns split between yield-optimized institutional buyers and convenience-seeking household segments.
- Whole:Intact organ presentation for foodservice yield calculations. Quick-service restaurant chains in Brazil's processing cluster negotiate direct processor agreements prioritizing consistency over provenance labeling.
- Slices:Uniform thickness cuts for portion-controlled food manufacturing. Pet nutrition formulators in North American markets source sliced liver for premium kibble integration.
- Cubes:Pre-diced formats for raw feeding protocols and recipe-ready household use. Direct-to-consumer subscription services bypass traditional retail through temperature-controlled last-mile logistics.
- Powder:Micronized desiccated product for encapsulation and fortification. Pharmaceutical extractors isolate B12 cyanocobalamin for injectable formulations requiring GMP-certified processing lines.
Institutional procurement favors Whole; Powder is gaining share fastest in high-margin extract channels.
Distribution Channel:
Channel margins reflect cold-chain complexity and traceability documentation burdens.
- Online Retail:Temperature-controlled logistics enabling direct household delivery. Specialty subscription services capture organoleptic-conscious consumers seeking grass-fed certification premiums.
- Supermarkets:Scale retail with standardized packaging and labeling requirements. Commodity grain-fed product dominates volume placement through price-competitive positioning.
- Specialty Stores:Curated selection with provenance documentation and staff expertise. EFSA-aligned audit trails support tiered pricing separation between pasture-raised and conventional lines.
- Wholesalers:Redistribution networks serving foodservice and manufacturing intermediaries. São Paulo vertical processors are capturing margin previously allocated to these traditional channels.
Supermarkets move the largest tonnage; Online Retail shows the steepest expansion trajectory.
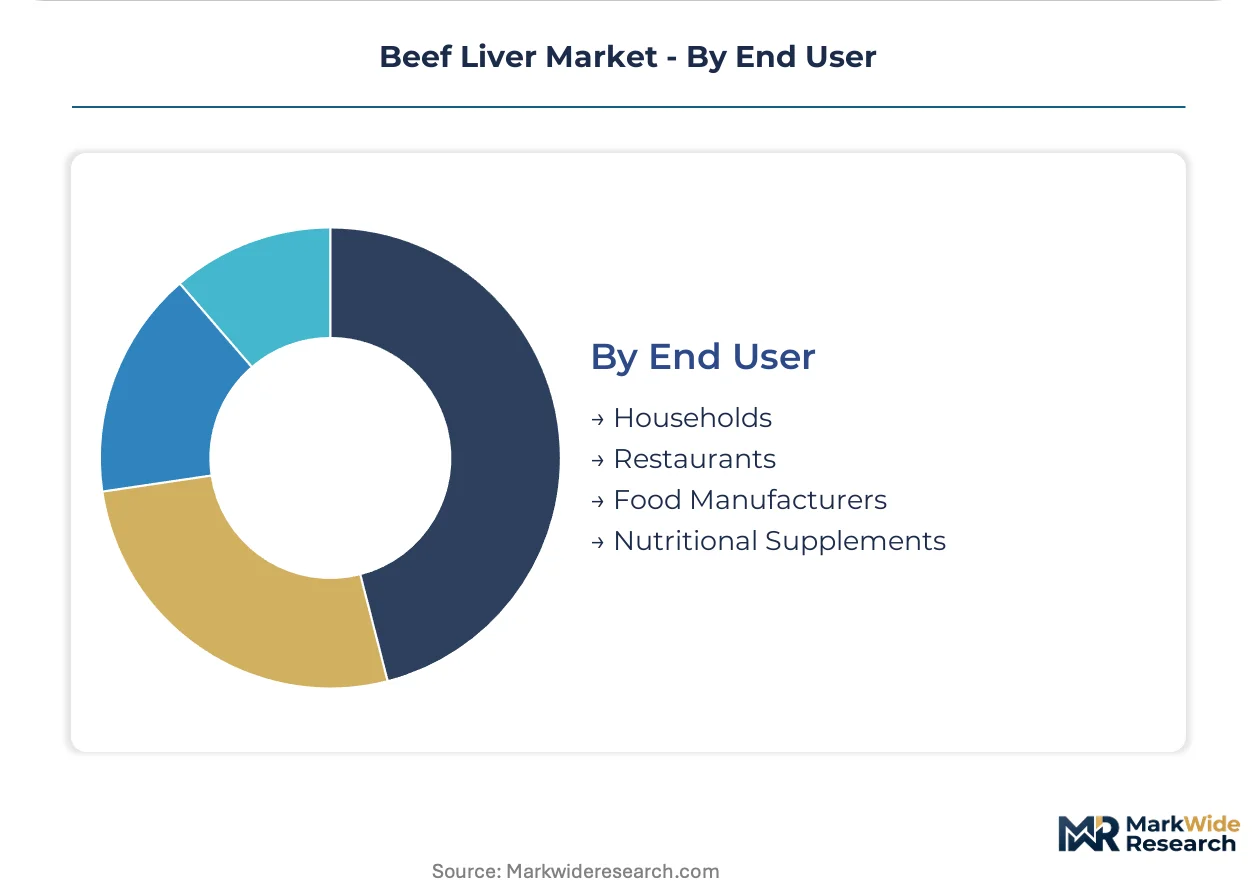
End User:
Application-specific quality standards drive divergent sourcing requirements and supplier qualification criteria.
- Households:Direct consumption across fresh, frozen, and processed preparations. Urban European demand concentrates in specialty retail channels with visible cold-chain credentials.
- Restaurants:Foodservice procurement prioritizing yield consistency and portion predictability. Brazilian quick-service chains source frozen whole liver through direct processor agreements.
- Food Manufacturers:Ingredient inputs for prepared meals and pet nutrition formulations. Dedicated off-take agreements with São Paulo processors secure flash-frozen supply for premium kibble production.
- Nutritional Supplements:Desiccated extract and isolate production for capsule and tablet fortification. GMP-certified facilities isolate B12 cyanocobalamin for pharmaceutical-grade applications.
Food Manufacturers represent the anchor volume base; Nutritional Supplements deliver the highest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo state's integrated slaughter-to-freeze corridor anchors global beef liver processing capacity, with flash-freeze infrastructure concentrated in municipalities surrounding the state capital.
United States
Pet nutrition formulators and pharmaceutical extractors drive specialized demand for USDA-FSIS inspected liver. The USDA mandates continuous inspection and HACCP compliance for all domestic processing. Nebraska and Kansas packing clusters supply flash-frozen product to nutritional supplement manufacturers seeking encapsulation-grade inputs.
Brazil
Quick-service restaurant chains and premium pet food exporters compete for flash-frozen whole liver volumes. ANVISA enforces veterinary pharmaceutical residue limits that reshape supplier qualification criteria. São Paulo state's vertical processors capture margin through direct procurement agreements that bypass traditional redistribution networks.
Germany
Specialty butcher networks and EFSA-aligned auditors enforce cold-chain documentation for premium human consumption tiers. EU Regulation 853/2004 imposes specific hygiene requirements for fresh offal handling. Bavarian and North Rhine-Westphalian processors deploy dedicated offal processing rooms with positive-pressure airlocks.
China
Desiccated extract producers and traditional medicine formulators source liver-derived inputs for B12 isolation. The country's national food safety regulator maintains evolving maximum residue limits for veterinary pharmaceuticals. Shandong Peninsula processing hubs supply micronized powder to domestic capsule manufacturers.
Denmark
European premium buyers prioritize organoleptic quality preserved through specialized cold-chain logistics. EFSA-aligned audit trails support tiered pricing separation between pasture-raised and commodity product lines. Danish processing facilities serve German and French retail channels with provenance-documented fresh offal.
Beef Liver Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a consolidated structure where integrated packers hold volume leadership and specialized processors capture premium tiers. Tyson Foods and JBS USA exemplify scale-driven archetypes with feedlot-to-retail network control. Danish Crown A/S occupies a specialized cold-chain logistics position. Danish Crown A/S and Greater Omaha Packing represent mid-cap specialists with regional concentration. Competitive moves center on backward integration into captive cattle supply and certification-driven portfolio diversification toward grass-fed provenance tiers.
Among US-based integrated packers, Tyson Foods, Inc., Cargill, Incorporated, and JBS USA Holdings, Inc. anchor the commodity volume tier through in-house production of feedlot cattle and captive liver processing capacity. These entities exemplify scale-driven competitive positioning where yield consistency and direct foodservice procurement agreements outweigh provenance differentiation. Danish Crown A/S occupies a distinct archetype as a European cooperative structure with specialized cold-chain capabilities serving EFSA-aligned premium channels.
| Leading Market Players |
|---|
| Tyson Foods, Inc. |
| Cargill, Incorporated |
| JBS USA Holdings, Inc. |
| National Beef Packing Company, LLC |
| OSI Group |
| Hormel Foods Corporation |
| Danish Crown A/S |
| Greater Omaha Packing |
| Vion Food Group |
| Others |
Pricing and Supply Chain Analysis
Blast-freeze technician pools concentrated in São Paulo state and Nebraska packing corridors create labor-cost differentials that widen spreads between commodity grain-fed and premium grass-fed liver tiers. Cold-chain certification premiums capture these regional wage arbitrages while EU hygiene mandates add compliance layers that reshape sourcing economics.
Pricing Analysis
Yield-consistent foodservice contracts anchor value-based pricing for institutional quick-service restaurant procurement. Three-tier pricing structure across grass-fed certified, standard commodity, and economy grain-fed levels separates EFSA-aligned audit premiums from volume-scale spot purchases. Cost compression in dried powder supplements is intensifying because plant-based ferrous bisglycinate alternatives displace mid-tier desiccated liver. Food Manufacturers demonstrate highest price sensitivity through direct processor negotiations, while Nutritional Supplements buyers absorb premiums for GMP-certified B12 isolation.
Supply Chain Analysis
Direct-to-foodservice channels handle hyperscale institutional demand while specialty subscription services bypass traditional redistribution. Supply concentrates in Brazil, the United States, and Denmark, with São Paulo state flash-freeze infrastructure, Nebraska-Kansas packing clusters, and Danish Crown cold-chain logistics serving distinct tier requirements. Raw material flows draw from feedlot cattle procurement, veterinary pharmaceutical compliance documentation, and blast-freeze capacity allocation. Single-source vulnerability concentrates in liquid nitrogen injection equipment for retinol preservation. Distribution runs through vertical processor agreements that capture margin from legacy wholesaler networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Beef Liver Market sits in a preservation-technology transition where liquid nitrogen blast-freeze systems replace legacy mechanical cooling tunnels. This equipment refresh cycle rewrites yield-loss calculations and retinol recovery economics.
For Market Incumbents: Acquire captive blast-freeze infrastructure in São Paulo state and Nebraska corridors to lock in heme iron preservation capacity before regulatory qualification timelines extend. Tyson Foods and JBS USA should retrofit existing tunnels with real-time temperature logging to preempt EU blockchain traceability mandates. Danish Crown A/S must defend its EFSA-aligned premium positioning against Brazilian entrants by deepening cold-chain documentation capabilities.
For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the most penetrable route for grass-fed certified liver cubes targeting organoleptic-conscious households in urban European markets. White-space exists in pharmaceutical-grade desiccated extract production requiring GMP-certified processing lines for B12 cyanocobalamin isolation. Pet nutrition formulators seeking dedicated off-take agreements represent a second entry vector bypassing incumbent foodservice dominance.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap specialists possessing EFSA-aligned audit trails given EU Regulation 853/2004 annex amendments tightening fresh offal hygiene requirements. Long-term viability favors processors with integrated slaughter-to-freeze infrastructure and provenance-documented pasture-raised supply chains. Monitor ANVISA veterinary pharmaceutical residue limit enforcement as an inflection indicator for Brazilian supplier qualification pivots.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Cattle Supply | Tyson Foods controls feedlot-to-retail liver volumes through in-house production networks. |
| GMP-Certified Processing Line Investment | Pharmaceutical extractors isolate B12 cyanocobalamin for injectable formulations. |
| Direct-to-Consumer Subscription Launch | Temperature-controlled last-mile logistics target organoleptic-conscious households. |
| EU Regulation 853/2004 Compliance Retrofit | Positive-pressure airlock installation captures premium human consumption tiers. |
| Blockchain Traceability Integration | Real-time temperature logging satisfies tightening USDA-FSIS and EU cold-chain directives. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with beef packing plant managers, pet nutrition formulators, pharmaceutical extractors, and EFSA-aligned auditors combined with USDA-FSIS inspection reports, ANVISA residue limit documentation, and EU Commission hygiene regulation annexes. Bottom-up volume modeling from processor capacity utilization and top-down demand triangulation from end-use consumption patterns validated projections.
Reconciliation of production volume disclosures, cold-chain infrastructure investment flows, and channel shipment data shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include preservation technology, form factor, distribution channel, and end-user application with regional regulatory cluster overlays. CAGRs derived from fitted trend extrapolation anchored in historical flash-freeze capacity expansion and pet nutrition formulation growth trajectories.
The model holds under stable veterinary pharmaceutical residue enforcement and intact cold-chain infrastructure investment; deviation in ANVISA tightening or liquid nitrogen supply constraints would shift volume and value outputs. Forecasts reflect documented assumptions about certification adoption curves and channel migration patterns. Practitioners should monitor EU annex amendment implementation timelines and Brazilian processor qualification rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Brisket Market
Meat Products
Organic Meat Products Market
Meat Products
North America Edible Meat Market
Meat Products
Global Canned Meat Market
Meat Products
Chilled Meat Market
Meat Products
Smokehouse Market
Meat Products
Global Lab-Based Meat Market
Meat Products
Mexico Meat Products Market
Meat Products
Global Beef Market
Meat Products
Beef Fat Powder Market
Meat Products
Europe Processed Meat Market
Meat Products
North America Processed Pork Meat Market
Meat Products
Bahrain Poultry Meat Market
Meat Products
United Arab Emirates Edible Meat Market
Meat Products
Meat, Poultry and Seafood Market
Meat Products
Meat-Based FPP Market