
 Global Poultry Meat Market | 2026-2036
Global Poultry Meat Market Size, Share, and Industry Trends Forecast 2026-2036
Global Poultry Meat Market Outlook
Antibiotic-free certification tiers is reorganizing procurement priorities across the Global Poultry Meat Market. Tyson Foods leverages its vertically integrated feed-to-retail network to sustain volume leadership in North American broiler supply. JBS S.A. anchors its position through dense slaughterhouse and processing plant networks across Brazil's southern production belt. BRF S.A. differentiates via halal-certified export capacity targeting Middle Eastern buyers.
Poultry meat comprises muscle tissue from domesticated avian species, primarily broiler chickens, characterized by protein content exceeding 20 percent and fat profiles below 5 percent in lean cuts, produced through controlled-environment grow-out operations and mechanical slaughter processing for human consumption. The broiler segment dominates volume due to feed conversion efficiency and short grow-out cycles that compress working capital requirements. Turkeys occupy premium positioning in North American holiday and deli channels where per-unit margins exceed standard broiler cuts. Food service end users represent the fastest-expanding demand pool as QSR chains and cloud kitchen operators standardize poultry-centric menus across emerging markets.
The USDA enforces pathogen reduction and Hazard Analysis Critical Control Point standards that shape plant design and microbiological testing regimes for US-export-eligible facilities. Brazil's Ministry of Agriculture and China's customs administration operate bilateral sanitary protocols that determine market access eligibility for frozen and chilled shipments. Stakeholders must monitor evolving carbon accounting requirements under the EU Green Deal and corresponding feed-origin traceability mandates that will restructure supplier qualification criteria.
Market Dynamics
The EU Green Deal's farm-to-fork sustainability mandates are compressing supplier qualification timelines while antibiotic-free certification tiers reorganize procurement priorities across processing and retail channels.
Growth Catalysts
- EU Green Deal Feed Traceability:Mandatory carbon accounting and feed-origin documentation under EU Green Deal protocols are accelerating facility upgrades among export-qualified processors seeking continued market access.
- Cloud Kitchen Standardization:QSR chains and cloud kitchen operators across Southeast Asia are expanding poultry-centric menu offerings, driving contracted volume commitments from integrated suppliers.
- Halal Export Corridor Expansion:Brazil's integrated south-central export corridor is capturing rising procurement from Middle Eastern buyers seeking chilled and frozen shipment reliability.
Market Restraints
- Soybean Meal Price Volatility:Feed input cost swings tied to South American crop conditions compress margin buffers for non-integrated grow-out operations.
- Slaughterhouse Concentration Risk:Brazil's southern production belt exhibits dense processing plant clustering, creating regional supply vulnerability during sanitary protocol disruptions.
- Refrigerated Chain Technical Limits:Chilled shipment shelf-life constraints restrict market reach for premium product lines absent continuous cold-chain infrastructure.
Strategic Opportunities
- Vietnam Food Service Penetration:Underdeveloped branded poultry distribution in Vietnamese urban centers offers first-mover positioning for cold-chain-capable suppliers.
- Cellular-Cultured Hybrid Convergence:Blended plant-cultured poultry formulations are opening regulatory discussion pathways in Singapore and Israel.
- USDA Organic Premium Channel:Expanded retail shelf allocation for organic-certified products creates volume absorption capacity above commodity pricing floors.
Industry Challenges
- Veterinary Antibiotic Stewardship Expertise:Shortage of qualified poultry health specialists delays transition to reduced-antibiotic production protocols.
- EU Welfare Upgrade Capex Burden:Housing density reduction mandates require barn reconstruction investments that strain mid-scale operator balance sheets.
- Multi-Tier Certification Complexity:Simultaneous pursuit of organic, antibiotic-free, and animal welfare certifications extends audit timelines and documentation overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Poultry Meat Market |
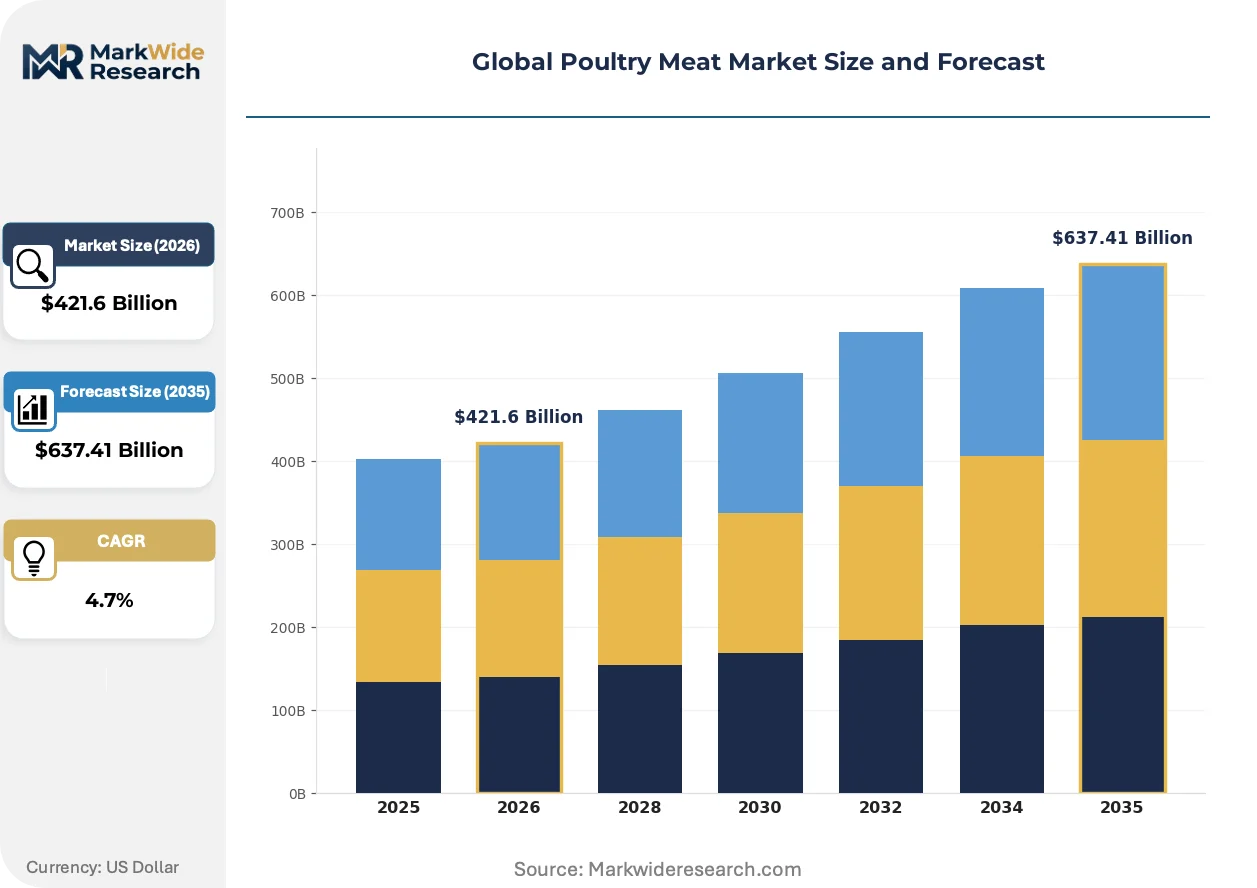
| Market Size in 2026 | $421.6 Billion |
| Market Size in 2035 | $637.41 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Broilers, Turkeys, Ducks, Others End User: Retail, Food Service, Processing, Export Distribution Channel: Supermarkets, Online Retail, Wholesale, Direct Sales Packaging Type: Bags, Cartons, Trays, Vacuum Sealed |
| Companies Covered | Cargill, Wens Foodstuff Group Co., Tyson Foods, Inc., Koch Foods Inc., CP Group, BRF S.A., Pilgrim's Pride Corporation, Hormel Foods Corporation, JBS S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Poultry Meat Market Strategic Shifts
Automation in live-hang and evisceration lines is compressing labor dependency while precision fermentation for alternative protein feed additives gains regulatory traction across major production jurisdictions.
Computer vision-guided robotic cutting systems are supplanting manual portioning in high-throughput facilities. North American processors with volume contracts to QSR chains are deploying these systems at accelerated replacement cycles. Labor cost arbitrage is narrowing as machine learning-enabled yield optimization recovers an additional two to three percent of carcass value previously lost to inconsistency.
China's SAMR and Brazil's Ministry of Agriculture are tightening bilateral sanitary protocol alignment for frozen shipment eligibility. Facilities seeking cross-border market access must now maintain dual-standard documentation regimes. Chilled export specialists are absorbing compliance overhead fastest, converting protocol familiarity into procurement preference from Asian importers.
Food service buyers are consolidating supplier relationships around vertically integrated partners capable of certifying full chain-of-custody documentation. Independent distributors in European urban markets are losing share to direct-processor accounts. This concentration is most visible in German and Dutch food service procurement, where sustainability scorecard requirements favor integrated network transparency over fragmented sourcing flexibility.
Global Poultry Meat Market Segmentation
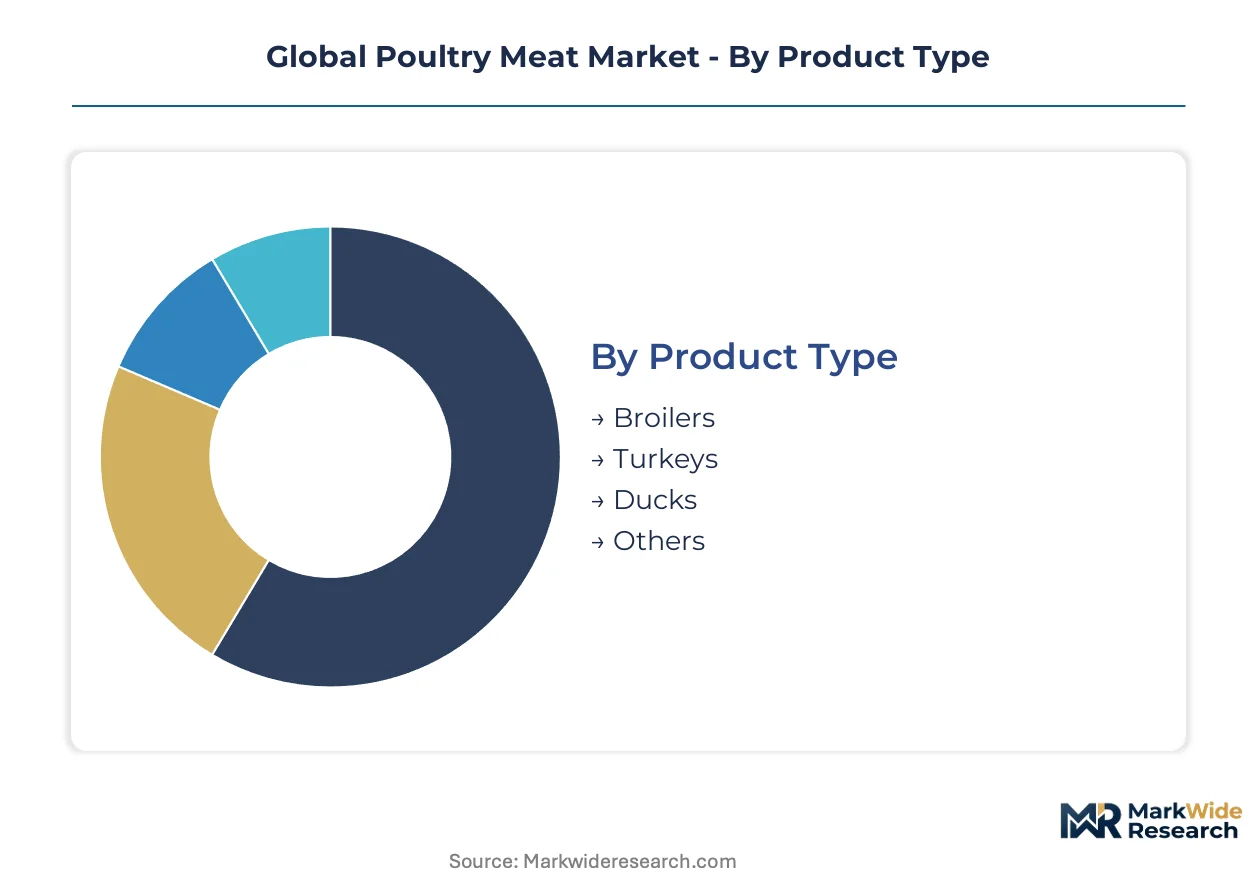
Poultry meat segmentation reveals divergent margin profiles across species and channel configurations. Product type determines feed conversion economics while end-user mix shapes cold-chain investment requirements and certification complexity.
Product Type:
Broilers dominate domestic consumption volumes across Brazil, the US, and China, while turkeys and ducks concentrate in export-specialized production belts and ethnic food service channels.
- Broilers:White-feathered meat-type chickens reach market weight in 35-42 days with feed conversion ratios below 1.7:1, making them the cost-optimized foundation for retail and QSR procurement. Brazilian integrators in Paraná and Mato Grosso do Sul leverage broiler density to supply Middle Eastern chilled export contracts.
- Turkeys:Slower-growing broad-breasted varieties require 14-20 weeks to mature, yielding breast portions with protein content exceeding 29 percent. North American processors concentrate turkey output around Thanksgiving and Christmas retail windows, with year-round deli meat demand absorbing processing plant fixed costs.
- Ducks:Pekin and Muscovy varieties serve specialized Asian food service markets in Vietnam, Thailand, and China's Guangdong province, with fat-rendering applications supporting secondary revenue streams.
- Others:Guinea fowl, quail, and squab occupy niche premium channels in France, Italy, and UAE hospitality procurement.
Broilers hold the largest share; momentum sits with turkeys as antibiotic-free and organic certifications command retail shelf allocation premiums.
End User:
Channel selection determines regulatory exposure, with food service buyers demanding batch-level traceability while export channels absorb bilateral sanitary protocol compliance overhead.
- Retail:Supermarket chains in Germany, the UK, and Japan specify shelf-life, labeling, and welfare-tier requirements that filter back to grow-out barn specifications. Private-label programs consolidate volume around three to five approved supplier groups per retail banner.
- Food Service:QSR chains and cloud kitchen operators across Indonesia, the Philippines, and Vietnam standardize portion-controlled cuts, driving contracted volume commitments from Thai and Brazilian integrators capable of certifying full chain-of-custody documentation.
- Processing:Further-manufacturing facilities in the Netherlands and Poland convert raw carcasses into marinated, breaded, and ready-to-cook products for EU food service and retail private-label programs.
- Export:Chilled and frozen shipments to Saudi Arabia, UAE, and China require dual-standard documentation regimes aligned with USDA, EU, and destination-country veterinary protocols.
Food service channels are expanding most quickly; retail maintains volume concentration but faces margin compression from private-label substitution.
Distribution Channel:
Channel structure reflects cold-chain maturity and buyer consolidation patterns, with direct-processor accounts displacing independent distributors in sustainability-scorecard-driven procurement.
- Supermarkets:Hypermarket and supermarket banners in Brazil, Mexico, and South Korea dominate branded poultry placement, with shelf fees and promotional calendars structuring supplier cash flow cycles.
- Online Retail:E-commerce platforms in China's tier-one cities and India's metropolitan corridors aggregate demand for premium cuts and value-added products, with 30-minute delivery windows requiring urban micro-fulfillment infrastructure.
- Wholesale:Traditional wet markets and cash-and-carry operators in Southeast Asia and sub-Saharan Africa remain price-sensitive volume channels with limited cold-chain penetration.
- Direct Sales:Processor-to-food-service contracts in the Netherlands, Germany, and US food service procurement bypass distributor margins while locking in volume commitments.
Supermarkets retain the largest share; online retail is gaining share fastest as urban delivery logistics mature.
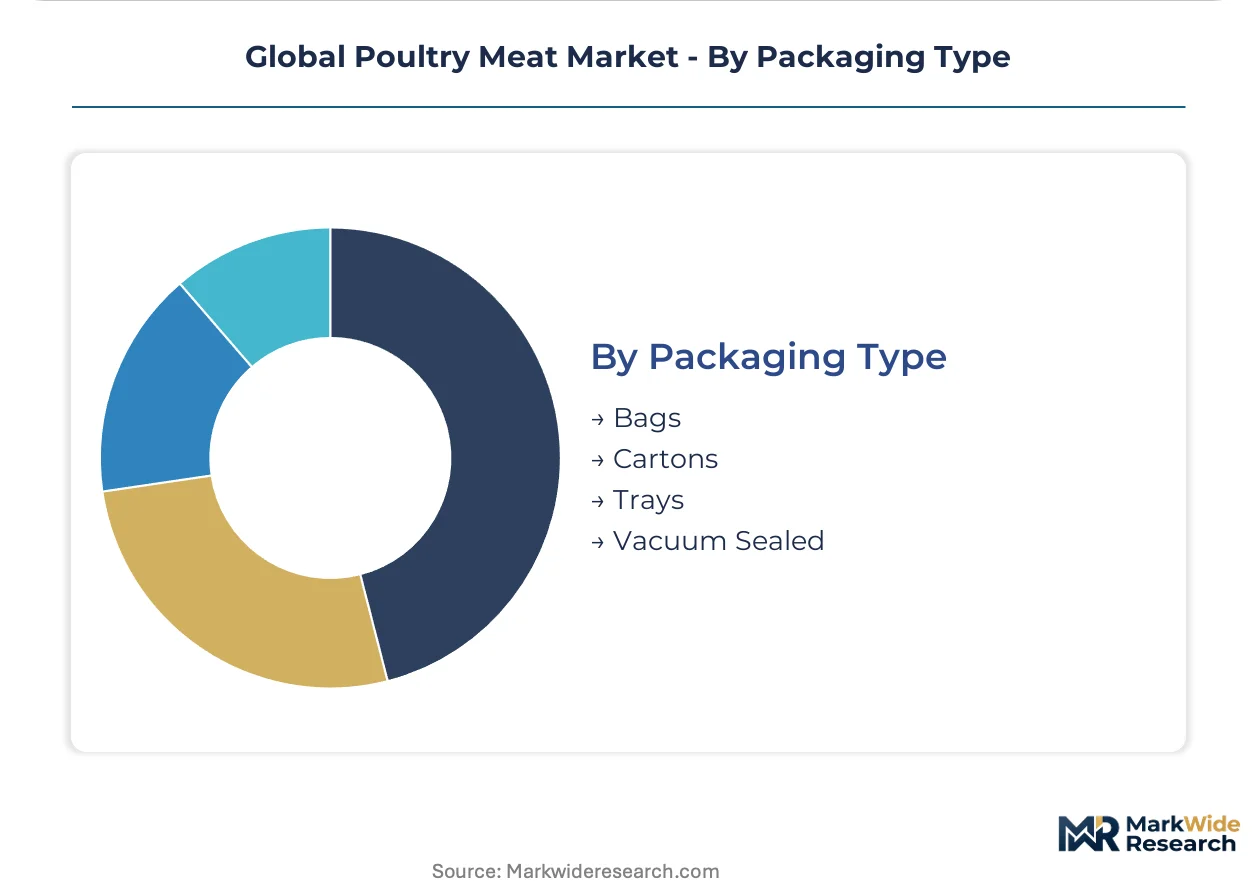
Packaging Type:
Packaging selection balances shelf-life extension against material cost and recyclability mandates under EU Green Deal and emerging extended producer responsibility frameworks.
- Bags:Polyethylene and bio-based film bags serve commodity frozen portions in retail and wholesale channels, with multi-layer structures providing 12-18 month frozen storage stability.
- Cartons:Paperboard cartons with polyethylene liners support branded fresh and frozen product lines in US and European retail, with graphic surface area enabling welfare-tier and certification messaging.
- Trays:Expanded polystyrene and fiber-based trays with overwrap film dominate fresh retail case-ready presentation, with modified atmosphere options extending chilled shelf life to 10-14 days.
- Vacuum Sealed:High-barrier vacuum and skin-pack formats enable 21-35 day chilled shelf life for premium export and food service channels, with oxygen exclusion supporting color retention and microbiological stability.
Trays hold the largest share; vacuum sealed formats are climbing the fastest as export and premium retail channels absorb unit cost premiums for extended shelf life.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentrates in Brazil's southern states and the US Southeast, with export corridors radiating toward Middle Eastern and Asian procurement hubs. Regulatory divergence between USDA, EU, and destination-country protocols fragments qualification requirements across supply basins.
United States
QSR chains and cloud kitchen operators drive contracted volume growth for portion-controlled cuts. USDA enforces pathogen reduction and HACCP standards that shape plant design and microbiological testing regimes. Georgia and Arkansas processing clusters supply domestic retail and export channels with integrated feed-to-slaughter coordination.
Brazil
Middle Eastern buyers seeking halal-certified chilled shipments anchor export demand from Paraná and Mato Grosso do Sul integrators. The Ministry of Agriculture operates bilateral sanitary protocols with China and Saudi Arabia that determine frozen shipment eligibility. Santa Catarina's dense slaughterhouse networks capture procurement preference through protocol familiarity and cold-chain reliability.
China
Urban food service expansion and tier-one city retail premiumization absorb domestic broiler output and imported chilled volumes. SAMR tightens bilateral sanitary alignment with Brazil for frozen shipment eligibility, requiring dual-standard documentation. Guangdong province's processing belt converts raw carcasses into value-added products for food service and retail private-label programs.
Germany
Supermarket private-label consolidation and sustainability scorecard procurement filter volume toward integrated suppliers with full chain-of-custody documentation. EU Green Deal farm-to-fork mandates compress supplier qualification timelines and accelerate barn reconstruction investments. Lower Saxony's grow-out operations face housing density reduction requirements that strain mid-scale operator balance sheets.
Vietnam
Underdeveloped branded poultry distribution in Ho Chi Minh City and Hanoi urban centers offers first-mover positioning for cold-chain-capable suppliers. Food safety regulations from the Ministry of Agriculture and Rural Development tighten traceability requirements for retail and food service channels. Mekong Delta grow-out clusters supply domestic wet markets while integrated operators build direct-processor accounts with QSR chains.
Global Poultry Meat Market Competitive Environment
Concentration sits with vertically integrated multinationals and national-scale processors that control feed-to-retail networks across multiple geographies. The competitive structure tiers into three archetypes: global integrators with cross-border export capacity, regional specialists with halal or organic certification positioning, and domestic champions serving protected home markets with cost-optimized supply chains. M&A activity targets feed mill and hatchery assets to secure input cost control, while capacity expansion concentrates in Brazil's south-central corridor and the US Southeast to capture Asian and Middle Eastern procurement growth.
Among Brazil-based S.A.-structured exporters, JBS S.A. and BRF S.A. exemplify the integrated archetype with dense southern processing networks and halal-certified export positioning. Tyson Foods, Inc. anchors North American supply through vertically coordinated feed-to-retail operations. Wens Foodstuff Group Co. occupies the domestic champion position within China's protected market structure.
| Leading Market Players |
|---|
| Cargill |
| Wens Foodstuff Group Co. |
| Tyson Foods, Inc. |
| Koch Foods Inc. |
| CP Group |
| BRF S.A. |
| Pilgrim's Pride Corporation |
| Hormel Foods Corporation |
| JBS S.A. |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal farm-to-fork mandates gate both supplier qualification timelines and price differentiation tiers across procurement channels. Certification overhead compresses margins for mid-scale operators while creating premium absorption capacity for integrated networks with full chain-of-custody documentation.
Pricing Analysis
EU Green Deal protocols dictate the pricing tier structure across export-qualified processors seeking continued market access. Three-tier pricing stratifies across organic-certified premium, antibiotic-free standard, and conventional economy levels, with feed-origin traceability and housing density compliance as primary differentiation drivers. Cost compression in the conventional tier intensifies due to soybean meal price volatility, while food service buyers in Germany and the Netherlands demonstrate lowest price sensitivity as sustainability scorecards override unit cost considerations.
Supply Chain Analysis
Inventory cycles compress from 35-42 day broiler grow-out schedules, with chilled export shelf-life constraints limiting geographic reach absent continuous cold-chain infrastructure. Supply concentrates in Brazil's Paraná and Mato Grosso do Sul states alongside the US Southeast Georgia-Arkansas corridor, with feed input anchored in South American soybean and corn harvests. Single-source vulnerability clusters around Santa Catarina's dense slaughterhouse networks during sanitary protocol disruptions. Distribution runs through direct-processor accounts displacing independent distributors in sustainability-scorecard-driven European procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating around vertically integrated processors capable of certifying full chain-of-custody documentation, as QSR chains and cloud kitchen operators consolidate supplier relationships and displace fragmented independent distribution across Southeast Asian and European urban markets.
For Market Incumbents: Fortify halal-certified export capacity and backward integration into feed mill assets to defend against Brazilian southern belt processing plant clustering risks. Prioritize barn reconstruction investments ahead of EU housing density reduction mandates to sustain qualification timelines. Channel control through direct-processor accounts with German and Dutch food service buyers offers defensive positioning against private-label substitution. For New Entrants and Emerging Players: Antibiotic-free certification fast-tracks open positioning in Vietnamese urban centers where branded poultry distribution remains underdeveloped and cold-chain infrastructure gaps create first-mover windows. Target Ho Chi Minh City and Hanoi QSR chain procurement with contracted volume commitments. A go-to-market angle anchored in cloud kitchen portion-controlled cut standardization bypasses supermarket shelf fee barriers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across EU welfare upgrade compliance and precision fermentation feed additive manufacturing. Long-term viability favors processors with demonstrated bilateral sanitary protocol familiarity and dual-standard documentation regimes. Acquisition target archetypes include mid-scale Brazilian integrators with latent halal certification capacity. The signal to watch is SAMR-Brazil Ministry of Agriculture protocol alignment tightening as inflection indicator for frozen shipment eligibility restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feed Mills | Soybean meal cost control secures margin buffers for Brazilian and US integrators against South American crop volatility. |
| Halal Certification Expansion | Middle Eastern chilled export contracts from Paraná and Mato Grosso do Sul capture procurement preference through protocol reliability. |
| Precision Fermentation Feed Additives | Alternative protein inputs gain regulatory traction across USDA, EU, and SAMR jurisdictions, reducing conventional soybean dependency. |
| Direct-Processor Account Development | Bypassing distributor margins locks volume commitments with German and Dutch food service buyers under sustainability scorecard procurement. |
| Cloud Kitchen Portion Standardization | QSR chains across Indonesia, Philippines, and Vietnam consolidate supplier relationships around contracted cut specifications and traceability documentation. |
Study Parameters
A spread of perspectives from integrator procurement directors, feed mill operations managers, QSR chain supply chain leads, and cold-chain logistics operators converged on the working assumptions shaping volume and value outputs. Primary interview insights combined with secondary validation drawn from USDA export eligibility records, EU Green Deal regulatory filings, Brazil Ministry of Agriculture sanitary protocol documentation, and SAMR bilateral alignment announcements. Bottom-up grow-out capacity modeling and top-down trade flow analysis triangulated across the projection horizon.
Segmentation dimensions modeled span product type (broiler, turkey, duck, other species), end user (retail, food service, processing, export), distribution channel (supermarket, online retail, wholesale, direct sales), and packaging format (bags, cartons, trays, vacuum sealed). CAGRs derived from historical trade volume trajectories and contracted procurement commitment pipelines across the analysis window. Industry-specific forecast inputs include feed conversion ratio improvements and automated evisceration line deployment cycles.
The analysis sits within stated boundaries; outcomes outside sustained bilateral sanitary protocol alignment or abrupt feed input cost dislocation would require recalibration. Forecasts reflect documented assumptions regarding EU barn reconstruction investment pacing and Southeast Asian cold-chain infrastructure buildout. Avian disease outbreaks, trade restriction imposition, or regulatory timeline acceleration present specific revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Middle East Red Meat Market
Meat Products
Europe Bacon Market
Meat Products
Lab-Grown Meat Market
Meat Products
Hams Market
Meat Products
Organic Meat Market
Meat Products
Chilled Meat Market
Meat Products
3D Printed Meat Market
Meat Products
US Meat Market
Meat Products
Global Beef Market
Meat Products
Raw Chicken Feet Market
Meat Products
North America Processed Pork Meat Market
Meat Products
Binders and Scaffolders for Meat and Meat Substitutes Market
Meat Products
Bahrain Poultry Meat Market
Meat Products
Chicken Fat Market
Meat Products
United Arab Emirates Edible Meat Market
Meat Products
Ham Slicers Market