
 Bouillon Market | 2026-2036
Bouillon Market Size, Share, and Industry Trends Forecast 2026-2036
Bouillon Market Analysis
Foodservice buyer concentration is decoupling as independent restaurant chains fragment procurement across regional suppliers while institutional catering consolidates into national contracts. McCormick & Company leverages its spice sourcing infrastructure to control input costs for bouillon concentrates. Nestlé S.A. sustains global manufacturing scale across multiple form factors. Unilever Group anchors European private-label supply through dedicated production facilities.
Bouillon denotes a dehydrated or concentrated flavor base produced by simmering meat, vegetables, or seafood with aromatics, then reducing the liquid through evaporation or spray-drying to achieve shelf-stable solids typically containing 25-45 percent salt by weight, designed to reconstitute into broth or season dishes directly. Chicken bouillon dominates retail volume in North American and European households where familiarity with poultry-based soups drives repeat purchase, while vegetable bouillon captures the fastest growth in food manufacturing as plant-based formulation requirements expand. Powder form leads developing-market penetration due to lower logistics cost and ambient storage tolerance, though paste formats command premium positioning in professional kitchens where dissolving speed and flavor intensity determine operational throughput.
EFSA sodium reduction targets and FDA nutrition labeling rules reshape product formulation thresholds, compelling manufacturers to reformulate with potassium chloride blends and yeast extract enhancers. India's FSSAI import standards for processed food concentrates affect market access for foreign brands seeking entry through Mumbai and Delhi distribution hubs. Stakeholders must monitor evolving clean-label certification schemes and regional salt-intake policies to align R&D pipelines with compliance timelines.
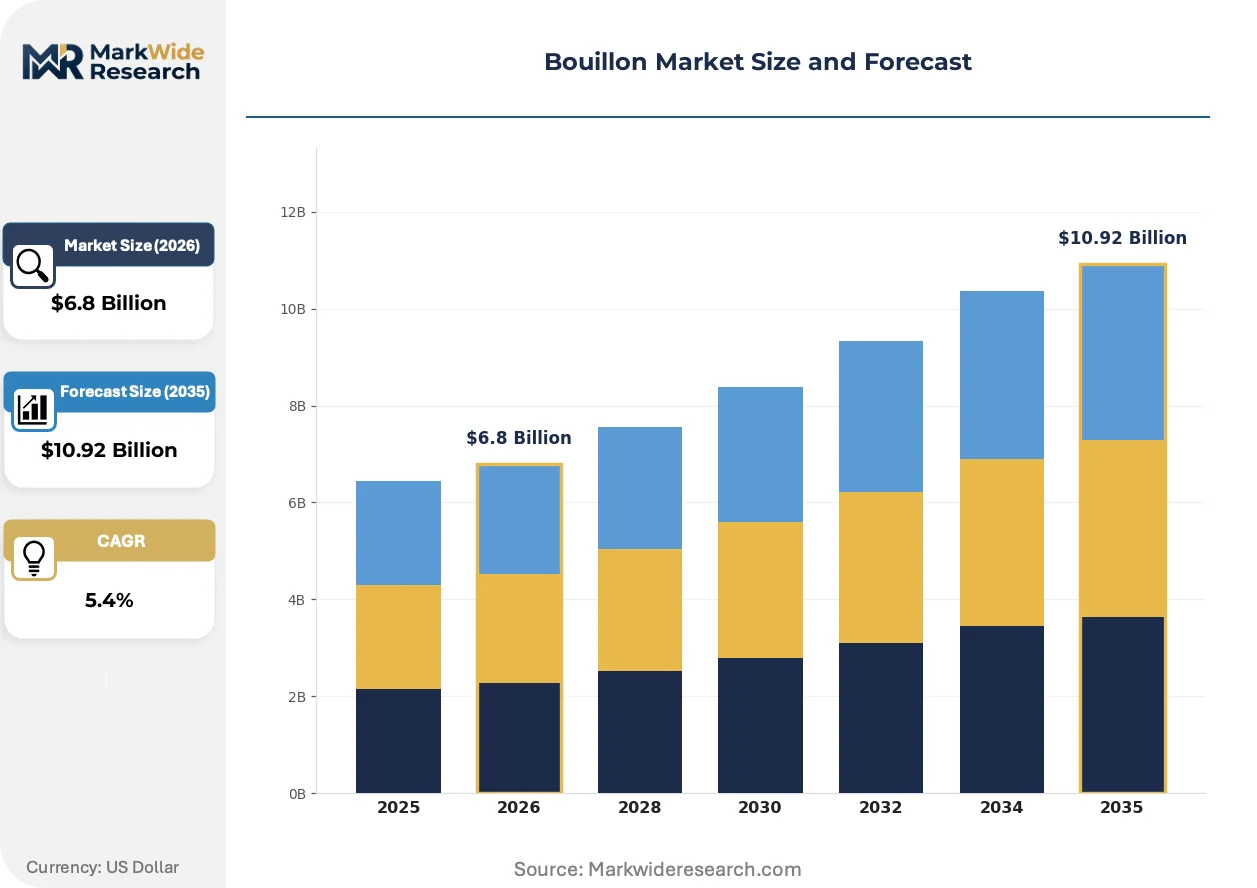
Market Dynamics
EFSA sodium reduction mandates and FDA nutrition labeling rules are forcing manufacturers to reformulate bouillon concentrates with potassium chloride blends and yeast extract enhancers, compressing traditional salt-dependent production economics.
Growth Catalysts
- Urban foodservice corridors:Indonesia's dense metropolitan restaurant clusters generate concentrated demand for paste-format bouillon concentrates that accelerate kitchen throughput.
- Plant-based formulation requirements:Food manufacturers across Europe are expanding vegetable bouillon volumes to meet clean-label certification schemes for meat-free product lines.
- REACH compliance alignment:EU chemical safety standards for food contact materials are streamlining cross-border ingredient sourcing for bouillon producers.
Market Restraints
- Salt input cost volatility:Evaporation-dependent sodium chloride supply from Mediterranean solar facilities creates margin pressure during drought cycles.
- Technical limitation in sodium mimicry:Potassium chloride aftertaste persistence in reduced-sodium formulations degrades repeat purchase rates among taste-sensitive households.
- Regulatory friction from FSSAI:India's processed food concentrate import standards create customs clearance delays for foreign brands at Mumbai and Delhi distribution hubs.
Strategic Opportunities
- Underpenetrated professional kitchens:Vietnam's independent restaurant sector lacks dedicated bouillon paste distribution, creating first-mover channel openings.
- Technology convergence:Spray-drying equipment paired with precision fermentation-derived flavor precursors enables clean-label intensity without synthetic additives.
- EU Green Deal procurement incentives:Public institutional catering contracts now prioritize low-carbon footprint concentrate suppliers, advantaging regional European manufacturers.
Industry Challenges
- Flavor chemist talent scarcity:Salt reduction expertise combining sensory science with regulatory compliance commands premium compensation in European R&D centers.
- Capex intensity of reformulation:Pilot-scale spray-dryer modifications for yeast extract integration require dedicated capital allocation before volume scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bouillon Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetable Bouillon, Chicken Bouillon, Beef Bouillon, Fish Bouillon Form: Powder, Cubes, Liquid, Paste End User: Households, Restaurants, Catering Services, Food Manufacturers Packaging Type: Bottles, Sachets, Cans, Jars |
| Companies Covered | McCormick & Company, Ariake Group, Nestlé S.A., Goya Foods Inc., Hormel Foods Corporation, Unilever Group, Ajinomoto Co., Inc., Premier Foods plc, Kraft Heinz Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bouillon Market Emerging Trajectories
Clean-label fermentation technologies and precision-drying methods are reshaping how bouillon concentrates achieve intensity without synthetic additives, while regulatory sodium thresholds compress permissible formulation space.
Precision fermentation-derived nucleotides and amino acid precursors are consolidating flavor intensity delivery in reduced-sodium bouillon formulations. Mid-sized European food manufacturers are adopting these inputs at accelerating rates to meet EFSA targets. The technology is consolidating competitive position around biotech-enabled suppliers with captive fermentation capacity.
EFSA's updated sodium intake benchmarks and front-of-pack labeling requirements are tightening permissible salt content thresholds across EU member states. Manufacturers must reformulate existing product lines or face delisting from major retail banners. Powder-format bouillon in German and French supermarkets faces the steepest compliance timeline pressure.
Foodservice procurement is fragmenting across independent restaurant chains while institutional catering consolidates into national contract vehicles. Regional distributors in Southeast Asia are losing share to direct manufacturer relationships with large hospitality groups. This bifurcation is most visible in Indonesia's Jakarta-Surabaya corridor where procurement scale determines supplier access terms.
Bouillon Market Segmentation
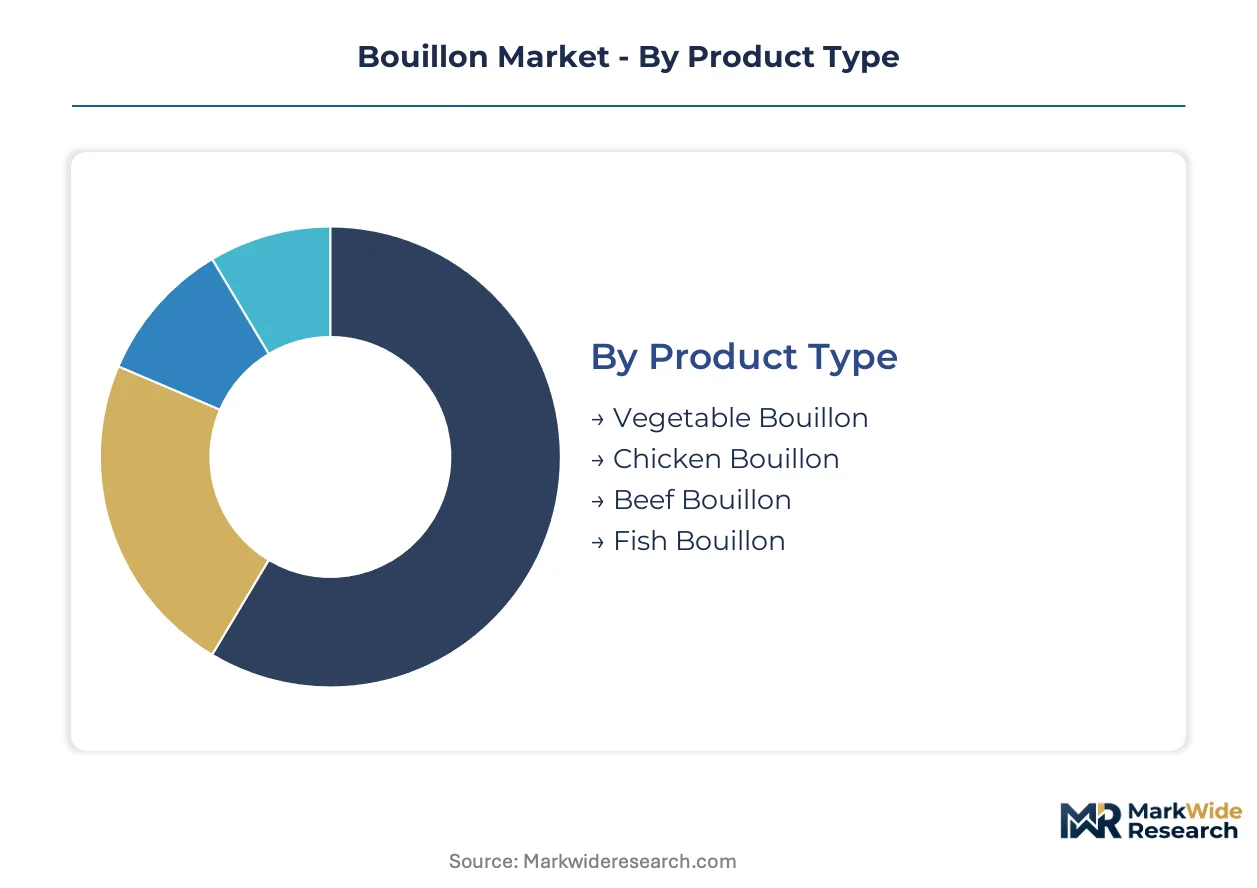
Bouillon segmentation reveals divergent profit pools across product chemistry, physical state, and procurement context. Form-factor economics and sodium-regulation pressure reshape which segments capture manufacturer investment priority.
Product Type:
Volume concentration tilts toward poultry-based formulations while plant-derived alternatives command reformulation premiums.
- Chicken Bouillon:Dehydrated concentrate derived from simmered poultry bones and meat with 25-35 percent sodium content by weight. North American and European households drive repeat purchase through soup preparation familiarity, though EFSA sodium thresholds now compress permissible salt levels in retail formulations.
- Vegetable Bouillon:Plant-based flavor base produced from reduced vegetable stocks with mirepoix aromatics. European food manufacturers are expanding procurement volumes to satisfy clean-label certification requirements for meat-free product lines, with yeast extract enhancers substituting for salt-dependent intensity.
- Beef Bouillon:Concentrated extract from bovine bones and connective tissue delivering umami depth through glutamate and nucleotide content.
- Fish Bouillon:Seafood-derived reduction common in Southeast Asian foodservice corridors where regional cooking traditions prioritize marine flavor foundations.
Today's leader: Chicken Bouillon. Tomorrow's challenger: Vegetable Bouillon.
Form:
Logistics cost and kitchen workflow speed determine format penetration across customer tiers.
- Powder:Spray-dried particulate with ambient storage tolerance and lowest per-unit shipping cost. Developing-market penetration concentrates in Indonesia's urban foodservice corridors where distributor margins favor shelf-stable, lightweight inventory.
- Paste:Concentrated semi-solid requiring refrigeration but delivering instant solubility and flavor intensity. Professional kitchens in Jakarta and Surabaya procurement clusters specify paste for throughput acceleration, though cold-chain requirements limit rural distribution reach.
- Cubes:Compressed dehydrated blocks with standardized portion control for household measurement convenience.
- Liquid:Ready-to-use broth concentrate with shortest preparation time but highest water content and shipping cost burden.
Cost efficiency favors Powder. Operational speed favors Paste.
End User:
Procurement scale and specification complexity fragment across consumer and institutional buyer types.
- Restaurants:Independent chains across Southeast Asia fragment supplier relationships across regional distributors while large hospitality groups consolidate into direct manufacturer contracts. Paste format specification dominates kitchen-level purchasing for dissolving speed.
- Food Manufacturers:Industrial buyers of vegetable bouillon volumes for clean-label meat-free product line expansion. European plant-based formulation requirements drive specification tightening around sodium content and synthetic additive exclusion.
- Households:Retail purchasers of powder and cube formats for home soup preparation and direct seasoning applications.
- Catering Services:Institutional volume buyers with national contract consolidation trends, particularly in EU public procurement corridors where EU Green Deal low-carbon supplier incentives reshape vendor selection.
Fragmentation defines Restaurants. Consolidation defines Catering Services.
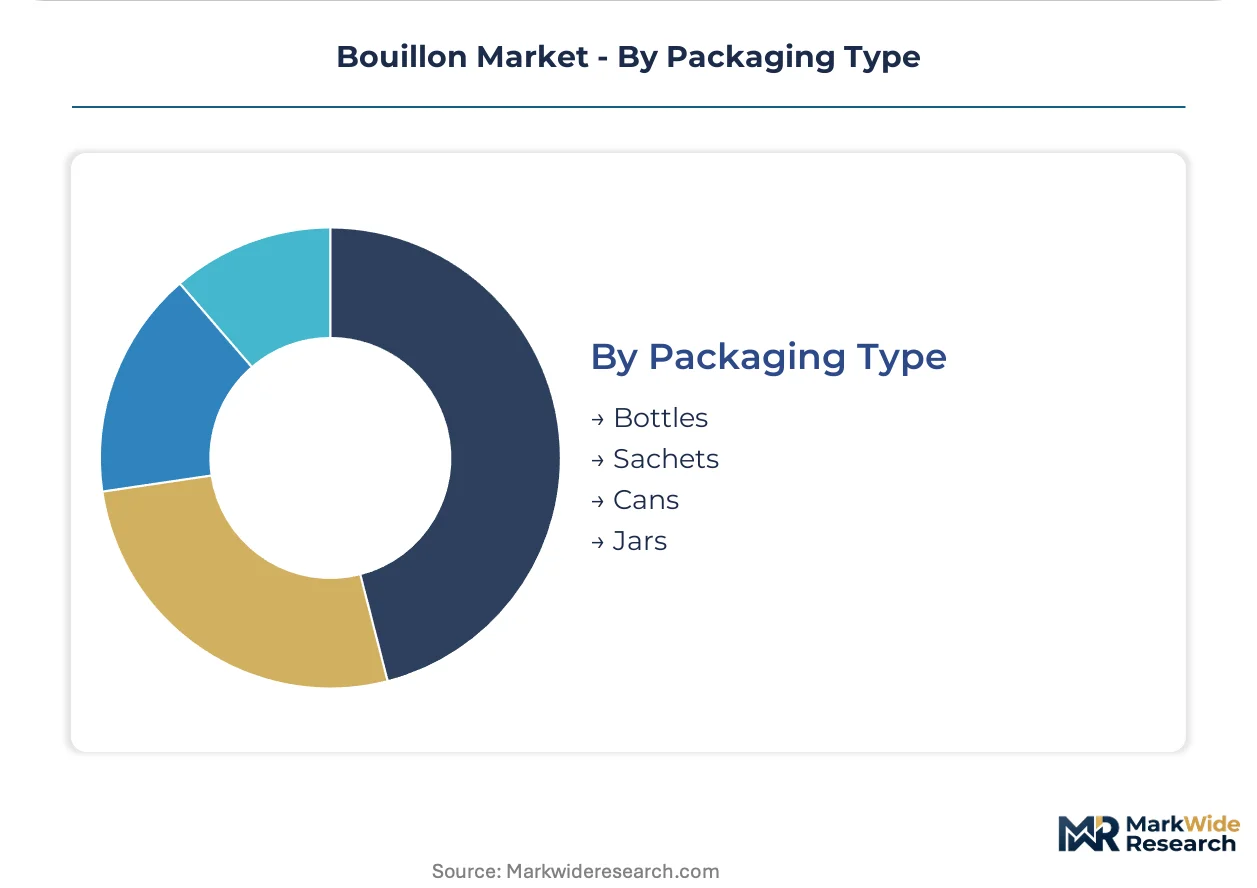
Packaging Type:
Portion control and shelf-life extension drive material selection across distribution channels.
- Sachets:Single-serve flexible film packets with minimal material cost and portion precision. Powder bouillon sachets dominate developing-market retail where price-point sensitivity and trial-size accessibility determine shelf placement.
- Jars:Rigid container formats for paste and powder with resealability and moisture protection. Professional kitchen procurement in Indonesia's metropolitan clusters favors jar packaging for inventory visibility and portion control.
- Bottles:Liquid concentrate containment with pour-controlled dispensing and label visibility for retail differentiation.
- Cans:Metal containment for liquid formats with extended shelf stability and thermal processing tolerance.
Accessibility leadership: Sachets. Professional preference: Jars.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flavor chemist talent pools in Basel, Paris, and Singapore anchor reformulation capability for sodium-reduced bouillon concentrates. These technical concentrations determine which manufacturers can meet tightening regulatory thresholds.
United States
Household soup preparation traditions sustain chicken bouillon powder demand through retail channels. FDA nutrition labeling rules compel sodium disclosure on front-of-pack designs. Chicago-based food manufacturers expand vegetable bouillon procurement for plant-based product lines.
Indonesia
Jakarta-Surabaya restaurant clusters generate concentrated paste-format bouillon procurement for kitchen throughput acceleration. National food safety standards administered by BPOM affect import clearance timelines for foreign concentrate brands. Metropolitan foodservice corridors fragment supplier relationships across regional distributors.
Germany
EFSA sodium reduction benchmarks compress permissible salt content in retail bouillon formulations. EU Green Deal procurement incentives reshape vendor selection for public institutional catering contracts. Bavarian production facilities anchor European private-label supply capacity.
India
Urban household seasoning applications drive powder bouillon penetration in Mumbai and Delhi distribution hubs. FSSAI processed food concentrate import standards create customs clearance friction for foreign brands. Western Maharashtra food manufacturers expand regional sourcing of vegetable-based flavor precursors.
France
Clean-label certification requirements accelerate yeast extract enhancer adoption in reduced-sodium formulations. EFSA front-of-pack labeling mandates tighten compliance timelines for supermarket banner listings. Lyon-area flavor houses consolidate biotech-enabled fermentation capacity for nucleotide production.
Bouillon Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across form-factor and end-use segments. The vendor base organizes around three strategic archetypes: spice infrastructure leveraged for input cost control, captive fermentation capacity for clean-label intensity, and dedicated production facilities for private-label scale. M&A activity targets regional flavor houses with sodium-reduction expertise. Capacity expansion concentrates in Southeast Asian paste-format production.
Within the diversified conglomerate tier, McCormick & Company and Nestlé S.A. occupy positions defined by upstream supply infrastructure and multi-format manufacturing scale respectively. Unilever Group anchors European private-label supply through dedicated production facilities. Ajinomoto Co., Inc. represents the fermentation-specialist archetype with captive biotech capacity for nucleotide-derived flavor enhancement.
| Leading Market Players |
|---|
| McCormick & Company |
| Ariake Group |
| Nestlé S.A. |
| Goya Foods Inc. |
| Hormel Foods Corporation |
| Unilever Group |
| Ajinomoto Co., Inc. |
| Premier Foods plc |
| Kraft Heinz Company |
| Others |
Supply Flow & Price Mechanics
Foodservice procurement clusters in Indonesia's Jakarta-Surabaya corridor anchor volume-based contract pricing for paste-format bouillon concentrates, while retail powder segments compete on distributor margin compression.
Pricing Analysis
Three-tier pricing structure across premium paste, standard powder, and economy cube levels segments buyer access by operational sophistication and cold-chain capability. Price differentiation rests on certification grade for EFSA sodium compliance and volume scale in institutional catering contracts. Pricing pressure stems from potassium chloride blend costs in reduced-sodium formulations. Household retail buyers exhibit highest price sensitivity, while professional kitchen procurement prioritizes dissolving speed over per-unit cost.
Supply Chain Analysis
Dual-sourcing requirements from large hospitality groups in Southeast Asia mandate multi-supplier qualification for yeast extract enhancers and spray-drying capacity. Geographic supply concentration centers on Indonesia for regional paste production, Germany for private-label powder manufacturing, and France for fermentation-derived nucleotides. Raw material dependencies include Mediterranean solar-evaporated sodium chloride, precision fermentation feedstocks, and vegetable stock precursors from Western Maharashtra. Single-source vulnerability in flavor chemist talent pools at Basel and Lyon creates R&D bottleneck risk. Distribution runs through regional distributors in developing markets and direct manufacturer relationships with consolidated institutional buyers in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bouillon market functions as a stable compounder, with urban foodservice corridor expansion in Southeast Asia generating steady volume growth across paste and powder formats.
For Market Incumbents: Lock in captive fermentation capacity for yeast extract and nucleotide production to defend against biotech-enabled specialists entering the sodium-reduction space. Secure direct procurement relationships with Indonesia's largest hospitality groups before regional distributors consolidate. Prioritize EFSA compliance certification as a channel access lever for German and French retail listings. For New Entrants and Emerging Players: EFSA sodium reduction mandates in Europe open a window for clean-label fermentation specialists to capture share in vegetable bouillon reformulation. Vietnam's independent restaurant sector offers the most penetrable geography for paste-format distribution. Pursue channel partnerships with regional foodservice distributors rather than direct sales infrastructure. For Investors and Strategic Acquirers: Diversified food conglomerates are the most active acquirer in this space, targeting mid-sized European flavor houses with sodium-reduction expertise. The five-to-ten-year viability thesis rests on regulatory compliance capability as a moat. Acquisition target archetype: regional bouillon producers with captive spray-drying capacity and established BPOM or FSSAI registration. Monitor EFSA front-of-pack labeling enforcement timelines as the inflection indicator for reformulation capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captive yeast extract production insulates margin pressure from biotech input suppliers. |
| EFSA Compliance Certification Investment | Front-of-pack labeling alignment secures shelf placement in German and French retail banners. |
| Direct Distribution Expansion in Vietnam | First-mover channel control captures underpenetrated independent restaurant procurement. |
| Spray-Drying Equipment Modernization | Precision-drying technology enables clean-label intensity without synthetic additive inclusion. |
| Long-Term Supply Agreement with Hospitality Groups | National contract consolidation in EU institutional catering locks in volume commitments. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining executive interviews with foodservice procurement managers, flavor chemists at European R&D centers, and distribution channel partners in Southeast Asia. Secondary validation draws from EFSA regulatory filings, FSSAI import clearance records, BPOM food safety registrations, and customs trade data for bouillon concentrate flows. Bottom-up volume modeling triangulates against top-down category expenditure estimates.
Granularity-level framing applies product type, physical form, and end-use segmentation with regional regulatory cluster overlays across the projection horizon. CAGRs derive from trend-line extrapolation of urban foodservice corridor expansion rates and sodium-reduction compliance timelines. Industry-specific forecast inputs include Jakarta-Surabaya restaurant cluster growth and EU Green Deal procurement incentive adoption curves.
Revisions become necessary when EFSA sodium threshold enforcement accelerates, FSSAI import standards tighten, or drought cycles disrupt Mediterranean solar salt production. Deviation in any of these triggers would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Rooster Comb Extract Market
Ingredients
Cocoa Fiber Market
Ingredients
Potato Fiber Market
Ingredients
Self-Rising Flour Market
Ingredients
Asia-Pacific Protein Market
Ingredients
Food Colors Market
Ingredients
North America Rice Bran Oil Market
Ingredients
Organic Starch Market
Ingredients
L-Arabinose Market
Ingredients
Amaranth Seed Oil Market
Ingredients
Halal Ingredients Market
Ingredients
Canada Soy Protein Market
Ingredients
Boysenberry Extract Market
Ingredients
Soy Lecithin Market
Ingredients
Europe Edible Oil Market
Ingredients
Camelina Oil Market