
 Bacon Flavors Market | 2026-2036
Bacon Flavors Market Size, Share, and Industry Trends Forecast 2026-2036
Bacon Flavors Market Outlook
North American flavor houses is repositioning production assets toward concentrated smoke and savory reaction flavors that replicate bacon character without direct meat derivatives. McCormick sustains retail seasoning dominance through proprietary encapsulation technologies that preserve volatile smoke notes. Kerry Group leverages its integrated taste and nutrition platform to supply both food manufacturers and foodservice operators with customized bacon flavor systems. International Flavors & Fragrances competes through biotechnology-derived flavor molecules that reduce reliance on traditional thermal processing.
Bacon flavors denote thermally processed or chemically synthesized aromatic compounds, smoke condensates, and yeast extracts formulated to replicate the organoleptic profile of cured pork belly, typically standardized by volatile carbonyl content and phenolic intensity for batch consistency. These flavor systems serve industrial food processors seeking to impart savory umami and smoky characteristics across plant-based proteins, snacks, and condiments without incorporating actual meat substrates. Maple and smoked variants anchor current revenue pools in the flavor type dimension, while BBQ profiles capture faster growth in snack and sauce applications. Food processing commands the largest application share, though sauces and seasonings present higher per-unit margin opportunities for specialized flavor houses.
FDA oversight of natural and artificial flavor labeling under the Food Safety Modernization Act shapes how suppliers classify smoke-derived ingredients, while EFSA evaluations of polycyclic aromatic hydrocarbons in smoke condensates constrain European formulation options. The USDA's meat inspection and labeling rules create compliance boundaries for products marketed with bacon imagery or claims even when flavor-only. Stakeholders must monitor evolving clean-label definitions across FDA, EFSA, and Health Canada jurisdictions to anticipate reformulation requirements and preempt supply chain disruption.
Market Dynamics
Clean-label reformulation mandates from FDA and EFSA are forcing flavor houses to abandon synthetic smoke additives and rebuild bacon profiles from yeast extracts, natural condensates, and controlled thermal reactions. This regulatory compression is consolidating procurement around suppliers with verified natural ingredient pipelines and analytical capabilities for volatile carbonyl standardization.
Growth Catalysts
- Plant-based protein expansion:Meat analog manufacturers require bacon flavor systems to bridge sensory gaps in burgers, crumbles, and breakfast strips. Yeast-extract and smoke-condensate formulations now dominate their supplier qualification processes.
- FDA Food Safety Modernization Act implementation:Enhanced documentation requirements for natural flavor claims are accelerating supplier consolidation toward houses with integrated analytical and regulatory affairs capabilities.
- Reaction flavor technology maturation:Advanced Maillard control systems enable precise replication of cured-meat carbonyl profiles without pork derivatives, opening formulation flexibility for kosher and halal applications.
Market Restraints
- Polycyclic aromatic hydrocarbon limits:EFSA evaluations of smoke condensate safety are constraining European formulation options and forcing costly purification investments.
- Natural extract supply concentration:Premium smoke wood sourcing clusters in specific North American and European forest regions, creating geographic vulnerability to climate and harvest volatility.
- Clean-label cost structure:Natural bacon flavor systems command 40-60% raw material premiums over synthetic equivalents, compressing margins in price-sensitive snack applications.
Strategic Opportunities
- Asia-Pacific food processing expansion:South Korean and Japanese processed snack manufacturers are adopting Western savory profiles, creating import substitution opportunities for regional flavor production.
- Biotechnology-derived molecules:Precision fermentation of key bacon volatiles offers pathway to natural-label compliance with batch-to-batch consistency unattainable through thermal processing alone.
- Foodservice custom formulation:QSR chains require proprietary bacon flavor systems for limited-time offerings, shifting value capture toward solution-based relationships from commodity sales.
Industry Challenges
- Volatile compound stabilization:Preserving reactive carbonyl and phenolic notes through shelf life demands sophisticated encapsulation expertise scarce in mid-tier suppliers.
- Cross-jurisdictional label compliance:Divergent FDA, EFSA, and Health Canada natural flavor definitions force parallel formulation tracks and inventory segmentation.
- Sensory translation across substrates:Bacon profiles optimized for dairy or wheat matrices fail in pea or soy proteins, requiring application-specific redevelopment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bacon Flavors Market |
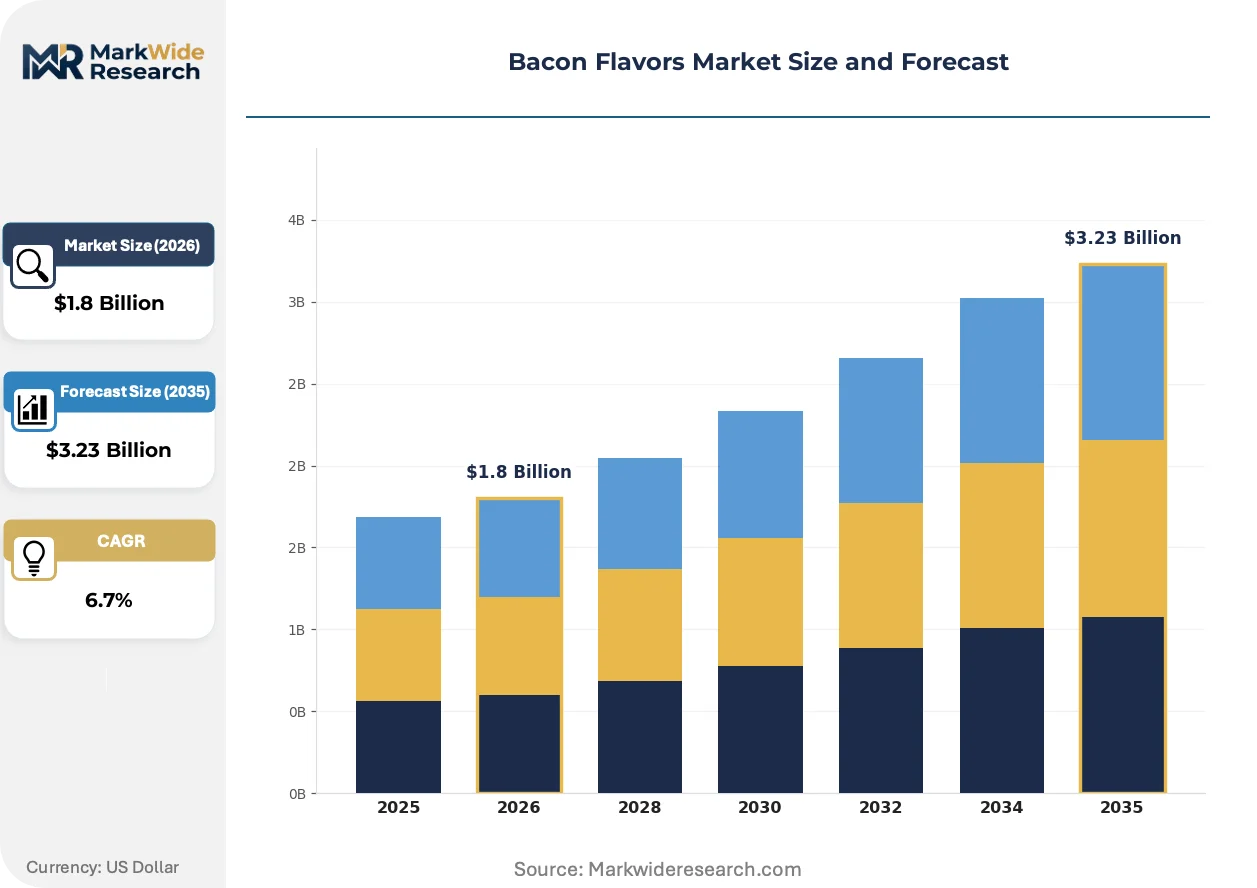
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Flavor Type: Smoked, Maple, BBQ, Sweet Application: Food Processing, Snacks, Sauces, Seasonings Distribution Channel: Online, Retail, Foodservice, Direct Sales End User: Consumers, Restaurants, Catering, Food Manufacturers |
| Companies Covered | Conmax Flavors, LorAnn Oils, McCormick, International Flavors & Fragrances, Omega Ingredients, Abelei Flavors, Mission Flavors & Fragrances, Kerry Group, Fleurchem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bacon Flavors Market Strategic Shifts
Flavor houses are rebuilding core capabilities around biotechnology and precision thermal processing to deliver clean-label bacon profiles with analytical consistency. Three converging developments are restructuring competitive positioning and supplier-buyer relationships.
Precision fermentation of key bacon volatiles—specifically 2,4-decadienal and guaiacol derivatives—is consolidating supplier tiers around houses with biotech partnerships or captive fermentation capacity. Snack and plant-based meat manufacturers are accelerating qualification timelines for these ingredients. The technology is consolidating R&D spending toward molecular biology capabilities and away from traditional flavorist-led compounding.
EFSA's ongoing reassessment of polycyclic aromatic hydrocarbon thresholds in smoke condensates is forcing European flavor houses to invest in liquid smoke fractionation and purification infrastructure. Industrial consequence includes delayed product launches and reformulation costs for existing sauce and seasoning lines. German and French snack manufacturers are responding by dual-sourcing from suppliers with verified low-PAH processes.
Direct technical partnerships between flavor houses and plant-based protein manufacturers are displacing traditional distributor-mediated sales. Ingredient suppliers now embed application scientists within customer R&D facilities to co-develop matrix-specific bacon systems. This collaboration model is most visible in United States and Netherlands innovation clusters where alternative protein venture funding concentrates.
Bacon Flavors Market Segmentation
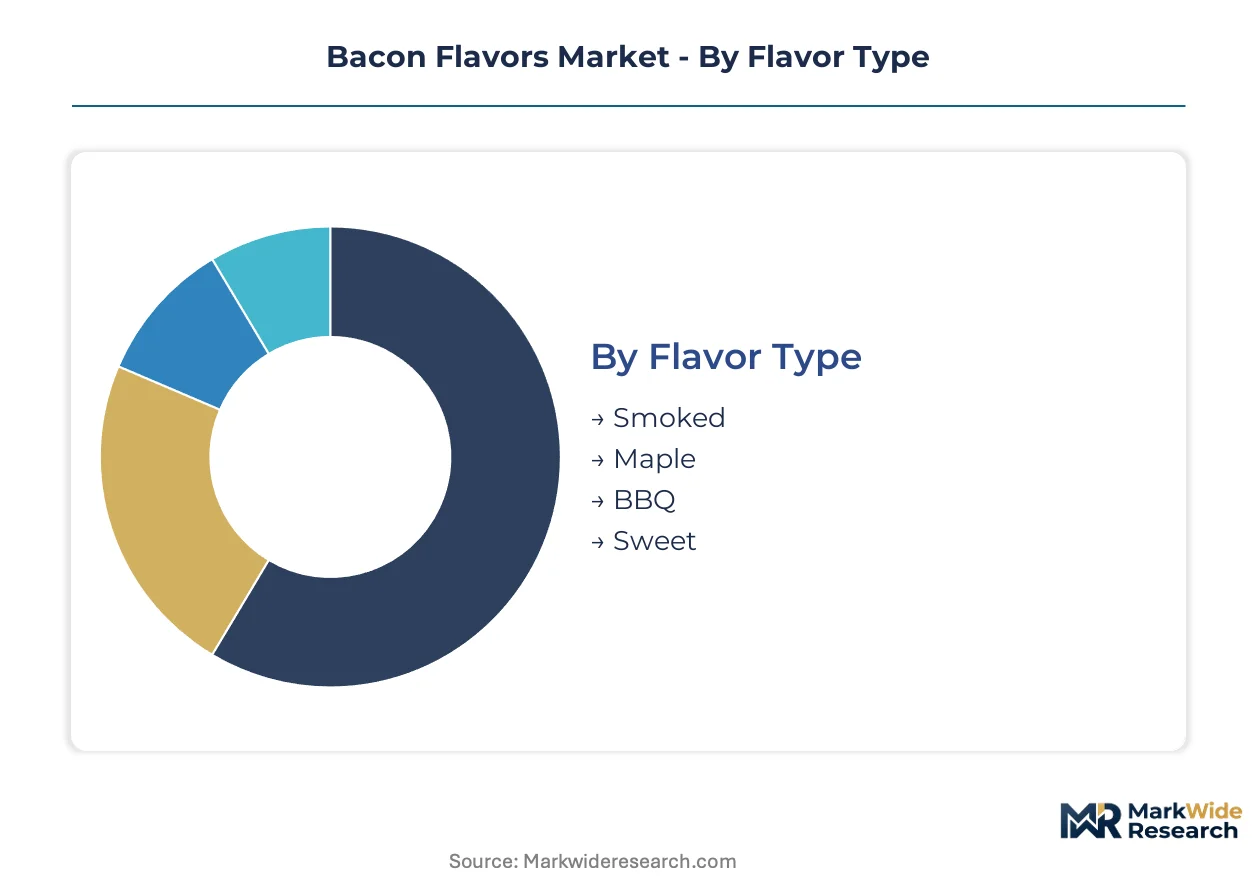
Segmentation in bacon flavors reveals how formulation complexity, regulatory compliance, and supply chain configuration fragment procurement decisions across buyer types. Understanding these dimensions exposes where margin concentrates and where suppliers must build differentiated capabilities.
Flavor Type:
Buyer selection hinges on substrate compatibility and clean-label positioning rather than price alone.
- Smoked:Derived from controlled pyrolysis of hardwoods or liquid smoke condensates, standardized by volatile phenolic content and carbonyl intensity. Concentrated demand from plant-based meat manufacturers in the United States seeking authentic cured-pork aroma without meat derivatives, constrained by EFSA polycyclic aromatic hydrocarbon limits in European formulations.
- Maple:Blends natural or synthetic maple lactones with smoke bases to replicate breakfast-style bacon profiles. Breakfast cereal and snack bar manufacturers in Canada and the United States drive procurement, prioritizing FDA-compliant natural flavor documentation for retail label claims.
- BBQ:Composite profiles combining smoke, molasses, and spice reaction flavors for bold savory applications. Snack seasoning houses favor this variant for coated nut and chip applications where intensity masks base ingredient variability.
- Sweet:Sugar-cured bacon analogs leveraging Maillard-derived furans and maltol for dessert and confectionery crossovers. Limited adoption outside premium ice cream and bakery inclusions due to narrow application fit.
Smoked leads on scale; BBQ leads on momentum.
Application:
Volume concentration and margin structure diverge sharply across these four use cases.
- Food Processing:Industrial bacon flavor systems for processed meat, plant-based analogs, and ready meals, typically delivered as oil-soluble or spray-dried powders. Massive throughput requirements from United States and German meat alternative producers compress per-unit margins while demanding batch-to-batch analytical consistency.
- Sauces:High-viscosity emulsions and water-dispersible liquid concentrates for barbecue sauces, salad dressings, and condiments. Specialty flavor houses capture premium pricing here through customized viscosity and heat-stability specifications for foodservice chains.
- Snacks:Surface-applied seasonings for chips, popcorn, and extruded products requiring aggressive flavor impact at low usage rates. Snack manufacturers prioritize cost-per-pound and volatile retention through shelf life over ingredient pedigree.
- Seasonings:Retail and foodservice dry blends combining bacon flavor with salt, sugar, and anti-caking agents. Private-label concentration in United States grocery channels drives formulation standardization and scale economics.
Food Processing dominates volume contribution; Sauces delivers the steepest margin expansion.
Distribution Channel:
Channel selection determines technical service intensity and pricing architecture.
- Direct Sales:Long-term supply agreements with major food manufacturers involving embedded application scientists and joint R&D protocols. Plant-based protein startups in California and Netherlands innovation clusters favor this channel for co-development of matrix-specific systems.
- Foodservice:Specialized distributors supplying QSR chains and contract foodservice operators with proprietary limited-time offering formulations. Value capture shifts toward solution-based relationships with menu development support.
- Retail:Branded and private-label seasonings through grocery and mass merchandise channels. McCormick and comparable houses dominate through proprietary encapsulation technologies preserving volatile smoke notes.
- Online:Direct-to-consumer and small-batch ingredient sales, currently marginal but expanding for artisan smoke condensates and craft flavor kits.
Direct Sales anchors strategic accounts; Foodservice is expanding most quickly through QSR customization demand.
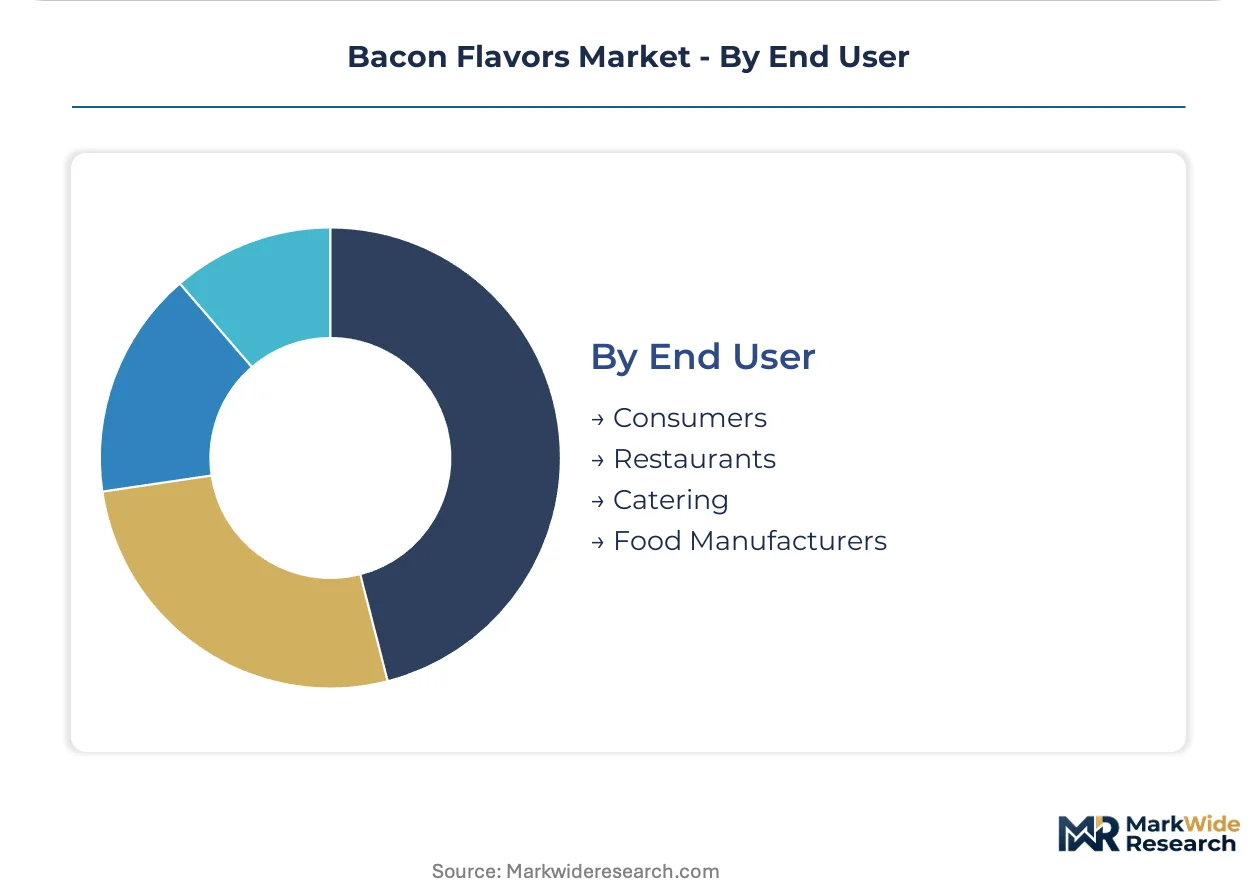
End User:
User type dictates specification rigor, order frequency, and regulatory documentation requirements.
- Food Manufacturers:Industrial processors of meat, dairy, and plant-based products requiring certified kosher, halal, or organic bacon flavor systems. Procurement teams prioritize supplier audit trails and analytical certificates for volatile carbonyl standardization.
- Restaurants:Independent and chain operators sourcing through broadline distributors or direct from flavor houses for proprietary menu items. Limited-time offerings drive spot purchasing with compressed lead times.
- Catering:Institutional and event catering operations requiring cost-optimized liquid smoke and seasoning blends in bulk formats. Price sensitivity exceeds specification complexity in this tier.
- Consumers:Retail purchasers of bottled seasonings and bacon-flavored snacks, influenced by clean-label claims and front-of-package messaging rather than technical specifications.
Food Manufacturers command supplier attention through volume and compliance complexity; Restaurants generate the fastest share gains via menu innovation cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States demand for bacon flavor systems outpaces German procurement volumes by a factor of three, though both markets now prioritize identical clean-label specifications. Regulatory divergence between FDA and EFSA frameworks is fragmenting formulation strategies across Atlantic supply chains.
United States
Plant-based meat manufacturers and snack seasoning houses drive concentrated procurement of smoke condensate and yeast-extract systems. FDA Food Safety Modernization Act documentation requirements favor suppliers with integrated analytical laboratories. Chicago and California innovation clusters host embedded application scientists from major flavor houses co-developing matrix-specific bacon profiles for pea and soy protein substrates.
Germany
EFSA polycyclic aromatic hydrocarbon limits constrain liquid smoke sourcing for sauce and seasoning applications. German snack manufacturers dual-source from verified low-PAH suppliers to mitigate reformulation risk. Bavaria-based flavor houses invest in fractionation infrastructure to purify smoke condensates for compliant European formulations.
United Kingdom
Breakfast cereal and savory snack producers sustain steady demand for maple-smoke composite profiles. Health Canada alignment pressures create parallel formulation tracks for cross-border product lines. Greater London food technology incubators partner with flavor houses on biotechnology-derived volatile development.
Netherlands
Plant-based protein startups in Wageningen and Amsterdam accelerate qualification timelines for precision-fermented bacon volatiles. EFSA natural flavor definitions guide supplier selection toward houses with captive fermentation capacity. Dutch flavor houses leverage agricultural biotechnology clusters for reaction flavor research partnerships.
Japan
Processed snack manufacturers adopt Western savory profiles for premium positioning in convenience retail. METI food technology initiatives support domestic smoke condensate purification research. Osaka and Tokyo flavor application centers customize bacon systems for regional palate preferences in soy-based matrices.
Bacon Flavors Market Competitive Environment
North American producers anchor the premium tier through proprietary encapsulation and biotechnology capabilities; European specialists hold compliance-advantaged positions in purified smoke systems. Market structure concentrates around ten to fifteen houses with verified natural ingredient pipelines, while mid-tier compounders face procurement exclusion from major food manufacturers. Three archetypes dominate: integrated taste-and-nutrition platforms, precision-fermentation biotech partners, and application-embedded solution providers. Competitive moves center on strategic partnerships with plant-based protein manufacturers and geographic expansion of low-PAH production assets.
Among integrated platforms, McCormick and Kerry Group exemplify the scale-driven archetype with captive supply chains spanning seasoning through industrial flavor systems. International Flavors & Fragrances occupies a distinct position through biotechnology-derived molecule development. These three houses collectively represent the supplier tier capturing disproportionate value from clean-label reformulation mandates and plant-based meat expansion cycles.
| Leading Market Players |
|---|
| Conmax Flavors |
| LorAnn Oils |
| McCormick |
| International Flavors & Fragrances |
| Omega Ingredients |
| Abelei Flavors |
| Mission Flavors & Fragrances |
| Kerry Group |
| Fleurchem |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up flavor specialists in North America and Europe have consolidated hardwood smoke condensate suppliers and precision-fermentation capacity, tightening supply discipline while enforcing three-tier pricing structures across premium natural, standard clean-label, and economy synthetic tiers. This ownership concentration amplifies pricing power over snack manufacturers and plant-based meat startups, who face 40-60% raw material premiums when upgrading from synthetic to natural bacon flavor systems.
Pricing Analysis
Capacity additions in Germany and the Netherlands are reshaping price floors for purified low-PAH smoke condensates, compressing margins for mid-tier compounders lacking fractionation infrastructure. Three-tier pricing structure across premium, standard, and economy levels stratifies by volatile carbonyl standardization and EFSA compliance certification, with premium tiers commanding substantial markups for verified natural documentation. Pricing pressure stems from dual-sourcing mandates among German snack manufacturers reacting to EFSA polycyclic aromatic hydrocarbon reassessments. Food processing giants exhibit lowest price sensitivity due to volume leverage, while independent catering operators face acute cost compression.
Supply Chain Analysis
Freight costs for liquid smoke condensates and yeast-extract concentrates from North American hardwood regions to European formulation facilities have intensified geographic sourcing optimization. Supply concentrates in the United States, Germany, and the Netherlands, with premium hickory and mesquite wood sourcing tethered to specific Appalachian and Ozark forest zones. Raw material dependencies include hardwood feedstocks, fermentation substrates, and Maillard-reaction precursors. Single-source vulnerability runs through concentrated North American smoke wood harvesting regions exposed to climate volatility. Distribution runs through direct technical partnerships with plant-based protein manufacturers, displacing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bacon flavors market functions as a stable compounder anchored by irreversible clean-label reformulation mandates across FDA and EFSA jurisdictions, ensuring sustained demand migration toward natural and biotechnology-derived systems.
For Market Incumbents: Anticipate accelerated supplier consolidation as EFSA polycyclic aromatic hydrocarbon thresholds harden, forcing mid-tier competitors into exit or acquisition. Deepen backward integration into captive hardwood sourcing and precision-fermentation capacity to defend margin position against biotech-enabled entrants. Prioritize embedded application scientist deployments within Netherlands and California plant-based protein clusters to lock in co-development relationships. For New Entrants and Emerging Players: Capture white-space in Asia-Pacific snack seasoning localization, where South Korean and Japanese manufacturers seek Western savory profiles with regional palate adaptation. Target foodservice QSR chains requiring proprietary limited-time offering formulations, as this segment rewards solution-based relationships over commodity scale. Pursue direct technical partnership go-to-market models rather than distributor-mediated sales. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier European smoke condensate houses facing EFSA compliance capex burdens but holding irreplaceable customer formulations. Long-term viability across the analysis window rests on biotechnology-derived molecule pipelines and verified low-PAH production assets. Monitor precision-fermentation partnership announcements between flavor houses and agricultural biotechnology clusters as inflection signal for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Partnership | Enables natural-label compliance with batch consistency unattainable through thermal processing alone. |
| Low-PAH Production Asset Expansion | Secures EFSA-compliant supply positioning for European sauce and seasoning applications. |
| Embedded Application Scientist Deployment | Locks in co-development relationships with plant-based protein manufacturers in innovation clusters. |
| Hardwood Sourcing Backward Integration | Reduces geographic vulnerability to climate and harvest volatility in concentrated forest regions. |
| Foodservice Custom Formulation Capability | Captures premium pricing through proprietary limited-time offering development for QSR chains. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with flavor house R&D directors, plant-based protein manufacturer procurement leads, snack seasoning formulators, and foodservice chain menu development executives. Secondary validation draws from FDA Food Safety Modernization Act guidance documents, EFSA scientific opinions on smoke condensate safety, USDA labeling regulations, and customs trade data on natural flavor ingredient flows. Bottom-up segment sizing and top-down market triangulation cross-validate volume and value estimates.
Rate-of-change decomposition separates volume growth from pricing migration across the analysis window, modeling flavor type, application, distribution channel, and end-user dimensions alongside regulatory compliance tier and substrate compatibility requirements. CAGRs derive from segment-level growth rate blending weighted by base-year contribution, with biotechnology adoption curves and clean-label reformulation timelines as key forecast inputs.
EFSA polycyclic aromatic hydrocarbon threshold revisions, FDA natural flavor documentation enforcement shifts, and hardwood supply climate disruptions are the dominant revision risks to modeled outcomes. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
United Arab Emirates Red Meat Market
Meat Products
Meat Mincers Market
Meat Products
Canned Beef Market
Meat Products
Bacon Slicers Market
Meat Products
Europe Meat Products Market
Meat Products
Europe Bacon Market
Meat Products
Grass-Fed Meat Market
Meat Products
North America Canned Meat Market
Meat Products
Pepperoni Foods Market
Meat Products
France Meat Products Market
Meat Products
Binders and Scaffolders for Meat and Meat Substitutes Market
Meat Products
Beef Liver Market
Meat Products
North America Poultry Meat Market
Meat Products
Beef Bone Broth Market
Meat Products
North America Edible Meat Market
Meat Products
Beef Jerky Market