
 Germany Poultry Meat Market | 2026-2036
Germany Poultry Meat Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Poultry Meat Market Insights
A capital-intensity divergence between automated processing lines and conventional slaughter facilities is reorganizing competitive tiers in the Germany poultry meat sector. PHW Group leverages vertical integration from hatchery to retail packaging across Lower Saxony. Rothkötter Group sustains geographic dominance through dense farm networks in the northwest. Plukon Food Group differentiates via specialized portioning technology for food service clients.
Germany poultry meat comprises muscle tissue from domesticated Gallus gallus, Meleagris gallopavo, and Anas platyrhynchos species, typically processed to achieve moisture retention between 70-75% and shelf lives of 7-14 days under refrigerated distribution. Chicken dominates volume throughput across German slaughterhouses, while turkey occupies premium positioning in cold-cut and ready-meal applications. Vacuum packaging captures margin pools in retail channels, whereas tray formats anchor supermarket fresh-meat counters. Online retail represents the fastest-growing distribution vector, though butchers retain loyalty in southern German states.
The German Federal Ministry of Food and Agriculture enforces Animal Welfare Livestock Farming Ordinance standards that dictate stocking densities and slaughter transport intervals. EU Green Deal farm-to-fork targets pressure nitrogen emission reductions from intensive poultry operations. KBA traceability requirements for refrigerated transport add compliance layers for cross-state distribution. Stakeholders must monitor how carbon-accounting rules reshape feed sourcing decisions and processor certification requirements.
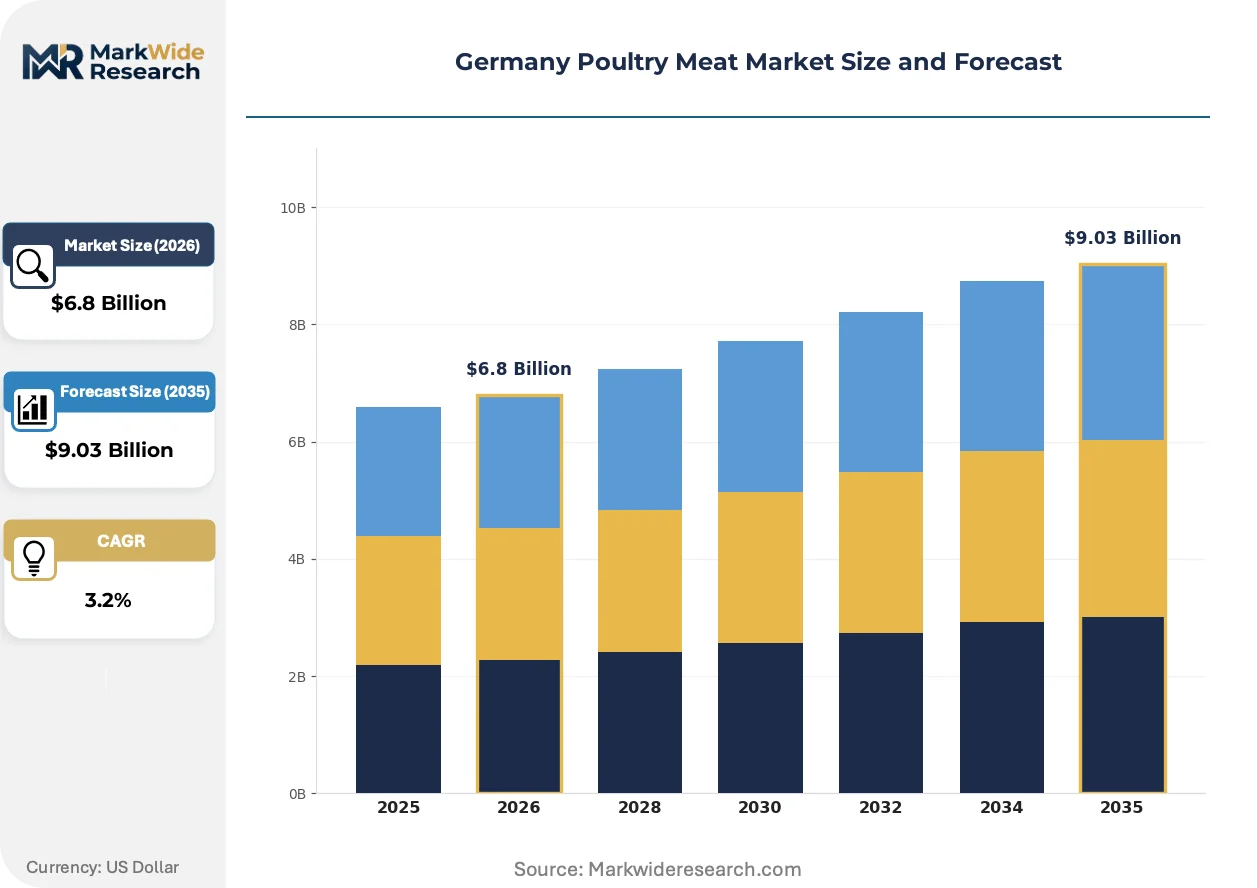
Market Dynamics
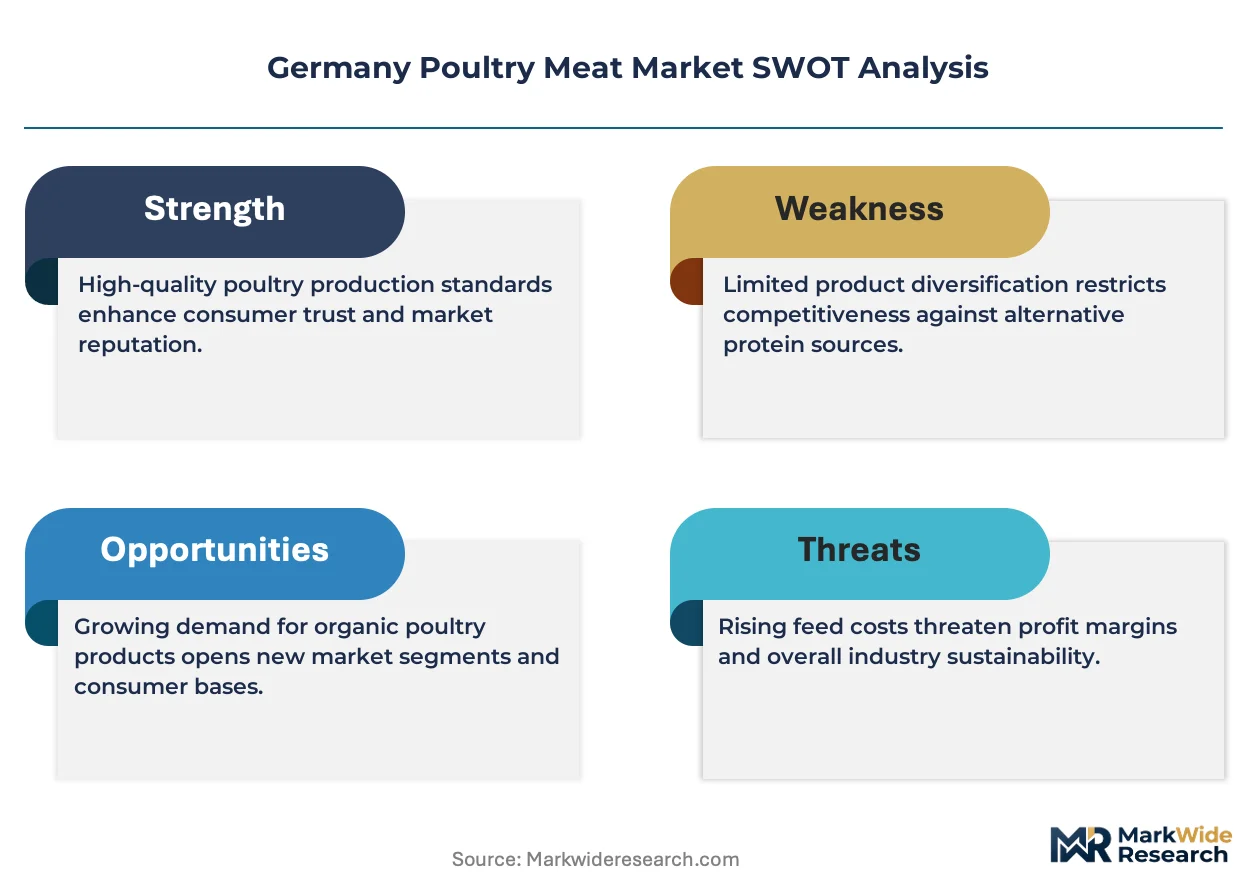
The Animal Welfare Livestock Farming Ordinance is compressing housing densities and forcing capital redeployment toward enriched cage systems across Lower Saxony and Bavaria production clusters.
Growth Catalysts
- Food service menu integration:Operators in Berlin and Hamburg metropolitan corridors are expanding poultry cut offerings. This pulls volume through specialized portioning channels.
- EU Green Deal farm-to-fork targets:Nitrogen emission reduction mandates are accelerating feed reformulation investments. Producers securing early certification capture retail shelf space advantages.
- Online retail channel expansion:Refrigerated last-mile networks in North Rhine-Westphalia are enabling direct-to-consumer fresh poultry delivery. This bypasses traditional supermarket counter intermediaries.
Market Restraints
- Feed input cost volatility:Soybean and grain price swings compress processor margins. German producers lack backward integration into feed milling.
- Slaughterhouse supply concentration:Processing capacity clusters in northwest Germany create geographic bottlenecks. Transport intervals face KBA traceability compliance layers.
- Regulatory friction from carbon accounting:Emerging feed sourcing certification requirements add administrative burden. Small-scale farms struggle with documentation overhead.
Strategic Opportunities
- Vacuum packaging premiumization:Extended shelf-life formats capture margin pools in southern German retail. This displaces traditional tray packaging at fresh-meat counters.
- Turkey cold-cut application expansion:Premium positioning in ready-meal segments remains underdeveloped. Food manufacturers can extend portioning technology from chicken.
- CSRD-aligned sustainability reporting:Early adoption of EU corporate sustainability disclosure standards differentiates supplier relationships. Retail buyers prioritize traceable upstream partners.
Industry Challenges
- Veterinary specialist shortages:Animal health compliance roles face recruitment gaps across rural production zones. This delays flock health certification timelines.
- Automated processing capex intensity:Enriched system upgrades compete with line automation investments for capital allocation. Mid-scale operators face squeeze pressure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Poultry Meat Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.03 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chicken, Turkey, Duck, Goose Distribution Channel: Supermarkets, Online Retail, Grocery Stores, Butchers End User: Residential, Food Service, Processing Plants, Catering Packaging Type: Plastics, Vacuum Packs, Cans, Trays |
| Companies Covered | PHW Group, Rothkötter Group, Plukon Food Group, Sprehe Geflügel und Tiefkühlfeinkost, Heidemark GmbH, Lambert Dodard Chancereul (LDC) Group, Vion Group, Trinity Meat Company, Gut Bergmark Premium Geflügel, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Poultry Meat Market Trends and Innovations
Processing automation and animal welfare compliance are restructuring capital deployment patterns. Producers must balance equipment modernization against housing system upgrades.
Hyperspectral sorting systems for defect detection and quality grading are bifurcating competitive tiers. Large-scale slaughterhouses in Lower Saxony deploy these for real-time moisture and freshness assessment. Mid-tier facilities lacking this capability face margin compression on export-grade contracts.
The EU Green Deal farm-to-fork nitrogen reduction framework is tightening emission ceilings for intensive poultry operations. German producers must document feed conversion efficiency and manure management protocols. Operations in nitrate-vulnerable zones face accelerated compliance timelines compared to eastern federal states.
Food service procurement is consolidating toward single-source poultry suppliers with certified animal welfare credentials. Hotel and restaurant chains in Bavaria now mandate enriched housing documentation. This displaces fragmented multi-supplier purchasing that dominated pre-2020 contract structures.
Germany Poultry Meat Market Segmentation
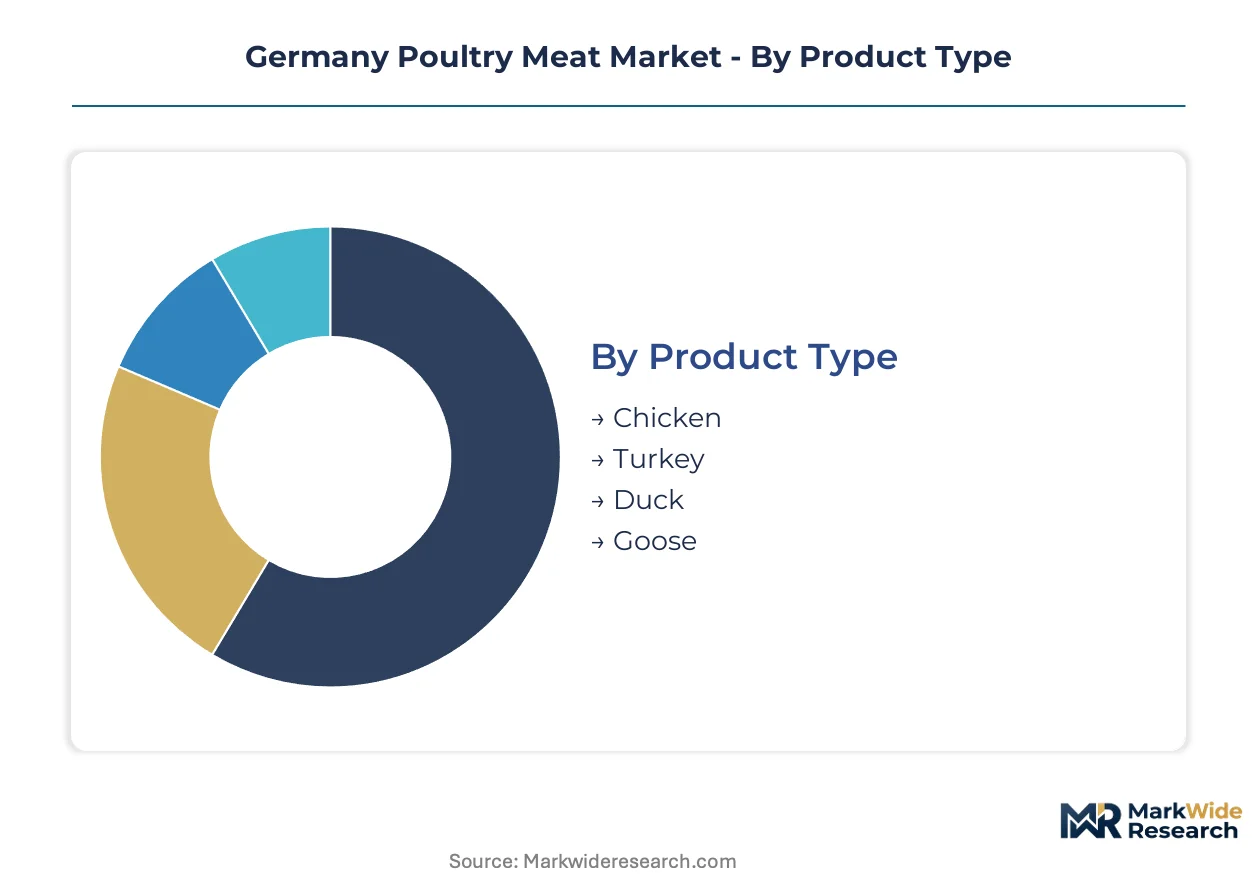
German poultry meat segmentation reflects divergent compliance burdens across product categories and channel formats. Animal Welfare Livestock Farming Ordinance standards apply unevenly, creating tiered cost structures that reshape competitive positioning.
Product Type:
KBA traceability requirements for slaughter transport intervals hit turkey and goose producers hardest due to longer supply chains and specialized processing needs.
- Chicken:Muscle tissue from Gallus gallus processed to 70-75% moisture retention dominates German slaughterhouse throughput. Berlin and Hamburg metropolitan corridors pull volume through fresh-chicken portioning channels serving food service operators. Lower Saxony production clusters face compressed housing densities under enriched system mandates.
- Turkey:Meleagris gallopavo occupies premium positioning in cold-cut and ready-meal applications with extended shelf-life requirements. Bavaria hotel chains now mandate enriched housing documentation for procurement contracts. Nitrate-vulnerable zone operations face accelerated EU Green Deal compliance timelines.
- Duck:Anas platyrhynchos serves specialized restaurant segments with shorter production cycles and distinct fat composition profiles. Northwestern farm networks concentrate breeding stock.
- Goose:Seasonal demand peaks align with traditional holiday consumption patterns in southern German states. Limited slaughter capacity creates geographic bottlenecks.
Chicken handles the majority of throughput; turkey is expanding most quickly on share as premium cold-cut applications displace conventional pork alternatives.
Distribution Channel:
Margin pools concentrate where refrigerated last-mile infrastructure meets traceability compliance layers.
- Supermarkets:Tray formats anchor fresh-meat counters across North Rhine-Westphalia retail networks. Vacuum packaging displaces traditional formats in southern German states where extended shelf-life commands price premiums.
- Online Retail:Direct-to-consumer delivery bypasses supermarket intermediaries through refrigerated logistics in metropolitan corridors. This channel is climbing the fastest as digital procurement patterns solidify among younger demographics.
- Grocery Stores:Neighborhood formats serve residential demand in rural production zones with limited cold-chain investment.
- Butchers:Southern German states retain loyalty through custom portioning and welfare-certified sourcing relationships.
Supermarkets maintain volume dominance; online retail is gaining share fastest through convenience positioning.
End User:
Procurement consolidation toward single-source suppliers with certified credentials is restructuring contract structures.
- Residential:Household consumption concentrates in fresh-chicken segments with 7-14 day shelf-life expectations. Berlin and Hamburg corridors show strongest online retail adoption.
- Food Service:Hotel and restaurant chains in Bavaria mandate enriched housing documentation, displacing fragmented multi-supplier purchasing. Menu integration of poultry cuts is accelerating across metropolitan operators.
- Processing Plants:Ready-meal manufacturers source standardized portions with moisture retention specifications for extended distribution.
- Catering:Institutional volume runs through centralized procurement with batch consistency requirements.
Food service captures margin premiums; residential demand shows steepest expansion trajectory through channel diversification.
Packaging Type:
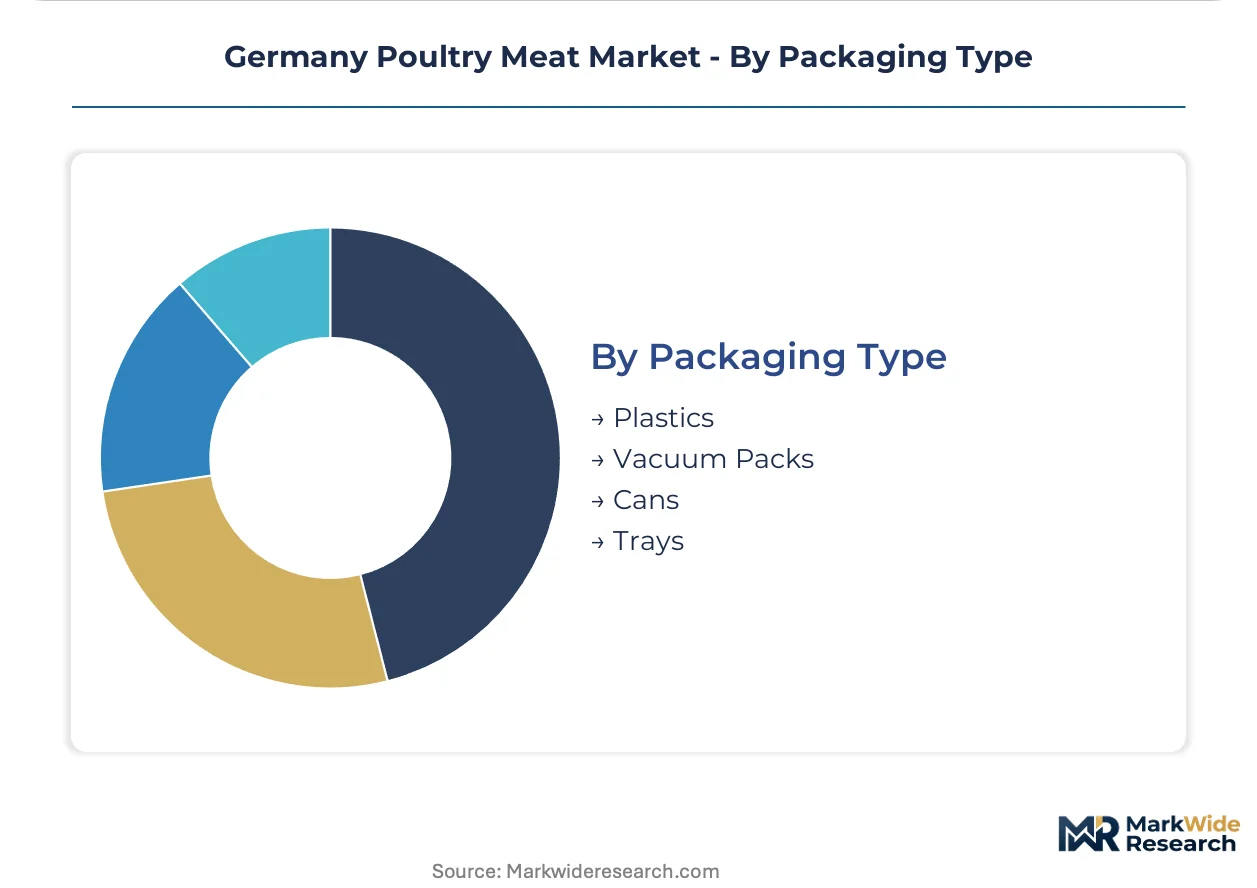
Carbon-accounting rules for feed sourcing are extending into packaging material certification requirements.
- Plastics:Conventional formats face pressure from EU Green Deal circular economy targets. Recyclability documentation is becoming a retail shelf-space determinant.
- Vacuum Packs:Extended shelf-life technology captures premium positioning in southern German retail networks. This format is expanding most quickly as freshness indicators replace visual inspection.
- Cans:Shelf-stable formats serve emergency procurement and institutional stockpiling with minimal cold-chain dependency.
- Trays:Traditional fresh-meat counter formats dominate supermarket volume but face displacement from vacuum alternatives.
Trays handle current volume leadership; vacuum packs are climbing fastest on margin capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Lower Saxony outstrips Bavaria by roughly 12-15% on fresh-chicken contracts, reflecting slaughterhouse density advantages versus metropolitan demand premiums. This asymmetry shapes capital deployment patterns across German production clusters.
Lower Saxony
Automated processing lines and hatchery-to-retail integration anchor volume leadership here. The Animal Welfare Livestock Farming Ordinance compresses housing densities in Emsland and Oldenburg districts. PHW Group operates dense farm networks across the northwest corridor, pulling supply through specialized portioning channels.
Bavaria
Hotel and restaurant chains in Munich and Nuremberg mandate enriched housing documentation for procurement contracts. KBA traceability requirements add compliance layers for cross-state distribution from northwest processing clusters. Food service menu integration accelerates across metropolitan operators, displacing fragmented multi-supplier purchasing.
North Rhine-Westphalia
Refrigerated last-mile networks in Düsseldorf and Cologne enable direct-to-consumer fresh poultry delivery. Online retail bypasses traditional supermarket counter intermediaries here faster than elsewhere. Rothkötter Group sustains geographic dominance through dense farm networks feeding retail and food service channels.
Baden-Württemberg
Vacuum packaging captures margin pools in Stuttgart and Karlsruhe retail networks where extended shelf-life commands premiums. EU Green Deal nitrogen emission mandates pressure feed reformulation investments. Butcher loyalty persists through custom portioning and welfare-certified sourcing relationships.
Berlin-Brandenburg
Metropolitan corridor demand concentrates in premium fresh-chicken segments with 7-14 day shelf-life expectations. Online retail adoption runs highest here among younger demographics. Plukon Food Group differentiates via specialized portioning technology for food service clients serving the capital region.
Germany Poultry Meat Market Competitive Landscape
Concentration sits with vertically integrated processors controlling hatchery-to-retail pipelines. Three to five large-scale operators dominate slaughterhouse throughput, while mid-tier facilities face margin compression on export-grade contracts. Strategic archetypes include: integrated processors with captive farm networks, specialized portioning technology providers, and regional slaughterhouse operators with dense geographic coverage. Dominant competitive moves encompass enriched system capital redeployment and automated processing line upgrades competing for limited investment budgets.
Within the integrated processor tier, PHW Group and Rothkötter Group exemplify divergent geographic strategies—one leveraging Lower Saxony density, the other sustaining northwest network dominance. Plukon Food Group occupies a position as the portioning technology specialist serving food service procurement consolidation. These three entities represent the competitive structure: scale-driven integration, regional network density, and technology-led differentiation.
| Leading Market Players |
|---|
| PHW Group |
| Rothkötter Group |
| Plukon Food Group |
| Sprehe Geflügel und Tiefkühlfeinkost |
| Heidemark GmbH |
| Lambert Dodard Chancereul (LDC) Group |
| Vion Group |
| Trinity Meat Company |
| Gut Bergmark Premium Geflügel |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between Lower Saxony processing clusters and Bavaria hotel chains lock in supply access while anchoring price visibility for enriched housing-compliant poultry volumes. These arrangements insulate contracted parties from feed input volatility while exposing non-contracted operators to spot-market compression.
Pricing Analysis
The customization-premium spread in German poultry meat separates standard tray-format chicken from vacuum-packed portions with Animal Welfare Livestock Farming Ordinance certification. Three-tier pricing structure across premium, standard, and economy levels reflects quality grade and certification level as primary differentiation drivers. Price erosion runs through economy tiers as feed cost volatility compresses processor margins without backward integration. Food service operators in metropolitan corridors show least price sensitivity due to menu premiumization, while residential segments through grocery stores exhibit highest elasticity.
Supply Chain Analysis
Strategic stockpile preferences dominate turkey and goose supply chains due to seasonal demand concentration, while chicken flows through just-in-time refrigerated networks. Geographic supply concentration centers on Lower Saxony, North Rhine-Westphalia, and Bavaria production clusters. Raw material dependencies include soybean meal, wheat, and corn feed inputs. Single-source vulnerability from northwest slaughterhouse concentration creates geographic bottlenecks under KBA traceability requirements. Distribution runs through supermarket retail networks, online direct-to-consumer channels, and specialized food service portioning pipelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through food service procurement consolidation toward single-source suppliers with certified animal welfare credentials, displacing fragmented multi-supplier structures that dominated pre-2020 contract frameworks.
For Market Incumbents: Consolidate processing capacity in Lower Saxony and Bavaria corridors to defend against margin compression from automated line investments at competitor facilities. Prioritize enriched system certification to secure hotel chain procurement contracts before veterinary specialist shortages delay flock health timelines. Channel control through captive farm networks remains the critical lever for volume retention. For New Entrants and Emerging Players: Anchor in online retail distribution through refrigerated last-mile partnerships in Berlin-Brandenburg and North Rhine-Westphalia metropolitan zones. Turkey cold-cut applications remain underdeveloped relative to chicken saturation, offering white-space entry through specialized portioning technology. A direct-to-consumer freshness positioning bypasses supermarket intermediary capture. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale operators with dense geographic farm networks and pending enriched system compliance investments across nitrate-vulnerable zones. Long-term viability hinges on early CSRD-aligned sustainability reporting adoption that differentiates supplier relationships for retail buyers. Watch for inflection when carbon-accounting rules extend into mandatory feed sourcing certification thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Enriched Housing System Upgrade | Animal Welfare Livestock Farming Ordinance compliance secures Bavaria hotel chain procurement contracts. |
| Automated Processing Line Deployment | Hyperspectral sorting systems enable real-time quality grading for export-grade contract capture. |
| Refrigerated Last-Mile Network Expansion | Direct-to-consumer delivery bypasses supermarket intermediaries in metropolitan corridors. |
| CSRD-Aligned Sustainability Reporting | Early adoption differentiates supplier relationships as retail buyers prioritize traceable upstream partners. |
| Feed Reformulation Investment | Nitrogen emission reduction under EU Green Deal farm-to-fork targets captures retail shelf space advantages. |
Research Methodology
The analysis maps chicken, turkey, duck, and goose sub-sectors, each validated through hatchery operators, slaughterhouse managers, food service procurement directors, and retail category buyers. Primary interviews with these stakeholders combined with secondary validation from Bundesamt für Wirtschaft und Ausfuhrkontrolle trade data, EU Green Deal regulatory filings, KBA transport compliance records, and Federal Ministry of Food and Agriculture enforcement reports. Bottom-up volume triangulation against top-down production capacity assessments ensures consistency.
Consistency checks validated outputs against external benchmarks including slaughterhouse throughput statistics and cold-chain infrastructure deployment disclosures. Segmentation dimensions modeled include product type, distribution channel, end user, and packaging format across the analysis window. CAGRs derived from trend extrapolation of historical volume trajectories adjusted for regulatory compliance cost impacts and channel shift dynamics. Feed input cost indices and nitrogen emission reduction timelines served as industry-specific forecast inputs.
Material uncertainties — regulatory enforcement intensity, veterinary specialist availability, and feed commodity price spikes — sit outside the modeled envelope. Forecasts reflect assumptions about Animal Welfare Livestock Farming Ordinance implementation pace and EU Green Deal nitrogen ceiling adherence. Revision becomes warranted when carbon-accounting rule adoption crosses mandatory certification thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
United States Animal Protein Market
Meat Products
Middle East Poultry Meat Market
Meat Products
Brazil Meat Products Market
Meat Products
Low-Fat Ham Market
Meat Products
Meat Packaging Market
Meat Products
Reduced Fat Meat Market
Meat Products
India Animal Protein Market
Meat Products
Organic Meat Market
Meat Products
Vegan Meatball Market
Meat Products
United States Bacon Market
Meat Products
Asia-Pacific Red Meat Market
Meat Products
Mechanically Separated Meat Market
Meat Products
Mexico Meat Products Market
Meat Products
Germany Meat Products Market
Meat Products
Meat Emulsions Market
Meat Products
Meat Flavors Market