
 Meat, Poultry and Seafood Market | 2026-2036
Meat, Poultry and Seafood Market Size, Share, and Industry Trends Forecast 2026-2036
Meat, Poultry and Seafood Market Intelligence
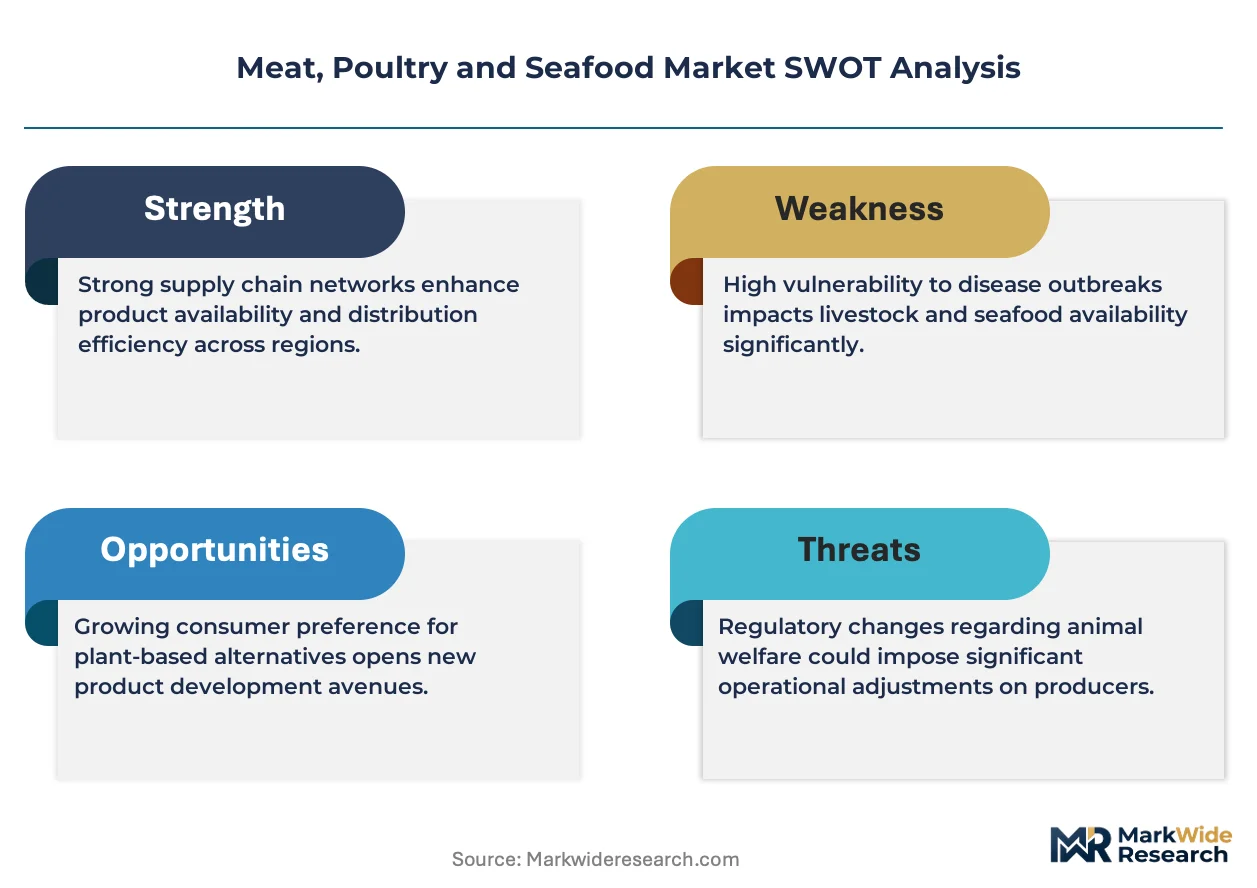
The premium protein tier is decoupling from commodity meat economics as grass-fed, antibiotic-free, and cell-cultured alternatives command fundamentally different pricing architectures. JBS S.A. leverages its vertically integrated beef and poultry platforms across Brazil, Australia, and North America to balance volume against margin volatility. Tyson Foods anchors its position through massive U.S. chicken processing scale and direct retail distribution partnerships. Cargill competes via global grain-to-protein supply chain control and specialized fat-trim specifications for food manufacturing clients.
Meat, poultry and seafood encompasses muscle tissue and edible offal from slaughtered livestock, aquaculture-raised fish, and wild-caught marine species, typically processed to achieve specific pH levels, moisture-to-protein ratios, and microbial safety thresholds for human consumption. Fresh and frozen processing methods dominate value retention as chilled supply chains shorten slaughter-to-retail windows, while dried and canned formats serve extended-shelf-life demand in institutional and emergency food channels. Beef and pork segments carry mature margin structures tied to feed-grain cost cycles, whereas fish and chicken categories attract faster growth through lower feed-conversion ratios and expanding aquaculture capacity.
USDA's FSIS enforces pathogen reduction and residue testing standards that shape domestic slaughterhouse operating protocols, while EFSA's scientific opinions on zoonotic risk and welfare standards influence European import requirements and retail procurement policies. Brazil's MAPA and China's SAMR impose divergent certification demands that fragment export compliance pathways for multinational processors. Stakeholders must monitor regulatory divergence on cultured-meat nomenclature and novel protein approval timelines as these frameworks will determine which production technologies achieve commercial scale first.
Market Dynamics
Antimicrobial residue testing mandates from USDA FSIS and EFSA are forcing slaughterhouse operators to reconfigure processing protocols and extend compliance documentation chains across export corridors.
Growth Catalysts
- Cell-cultured protein approval frameworks:Singapore's SFA and US FDA novel food pathways are creating regulatory precedents that accelerate capital deployment into bioreactor-based meat production. Early entrants gain first-mover certification advantages.
- Aquaculture feed conversion efficiency:Fish farming achieves protein output ratios superior to terrestrial livestock, attracting investment into recirculating aquaculture systems and offshore cage infrastructure. Input cost stability relative to grain-fed beef supports margin expansion.
- EFSA welfare standard harmonization:Unified European procurement criteria for cage-free eggs and slow-growth poultry are consolidating retailer demand around certified supply pools. Compliance becomes a volume-access gateway.
Market Restraints
- Soybean-meal price volatility:Brazilian drought cycles and US planting acreage shifts transmit directly into poultry and pork feed cost structures. Margin compression forces processor hedging complexity.
- Slaughter capacity concentration:Brazil's integrated beef-poultry corridor controls disproportionate global export volume. Disruption at Paranaguá or Santos port clusters cascades through international protein pricing.
- Cold-chain infrastructure gaps:Sub-Saharan African and South Asian markets lack consistent chilled distribution networks. Fresh product spoilage rates constrain premium positioning.
Strategic Opportunities
- Vietnam aquaculture modernization:Pangasius and shrimp farming zones seek disease-resistant genetics and automated feeding systems. Technology transfer partnerships unlock export-grade certification.
- EU Green Deal agricultural methane targets:Livestock sector emissions caps incentivize feed additive adoption and manure-to-biogas investments. Early compliance generates carbon credit revenue streams.
- Precision fermentation collagen scaffolding:Hybrid cell-cultured products combining animal cells with plant-derived structural proteins reduce bioreactor run costs. Foodservice manufacturers pilot texture-matched applications.
Industry Challenges
- Multi-jurisdiction residue tolerance reconciliation:Brazil's MAPA, China's SAMR, and Saudi Arabia's SFDA maintain divergent maximum residue limits for antibiotics and growth promoters. Exporters maintain parallel testing protocols.
- Cell-cultured nomenclature litigation risk:Conventional livestock lobbies challenge "meat" and "beef" labeling claims in US state courts and EU trademark proceedings. Regulatory uncertainty delays retail rollout timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meat, Poultry and Seafood Market |
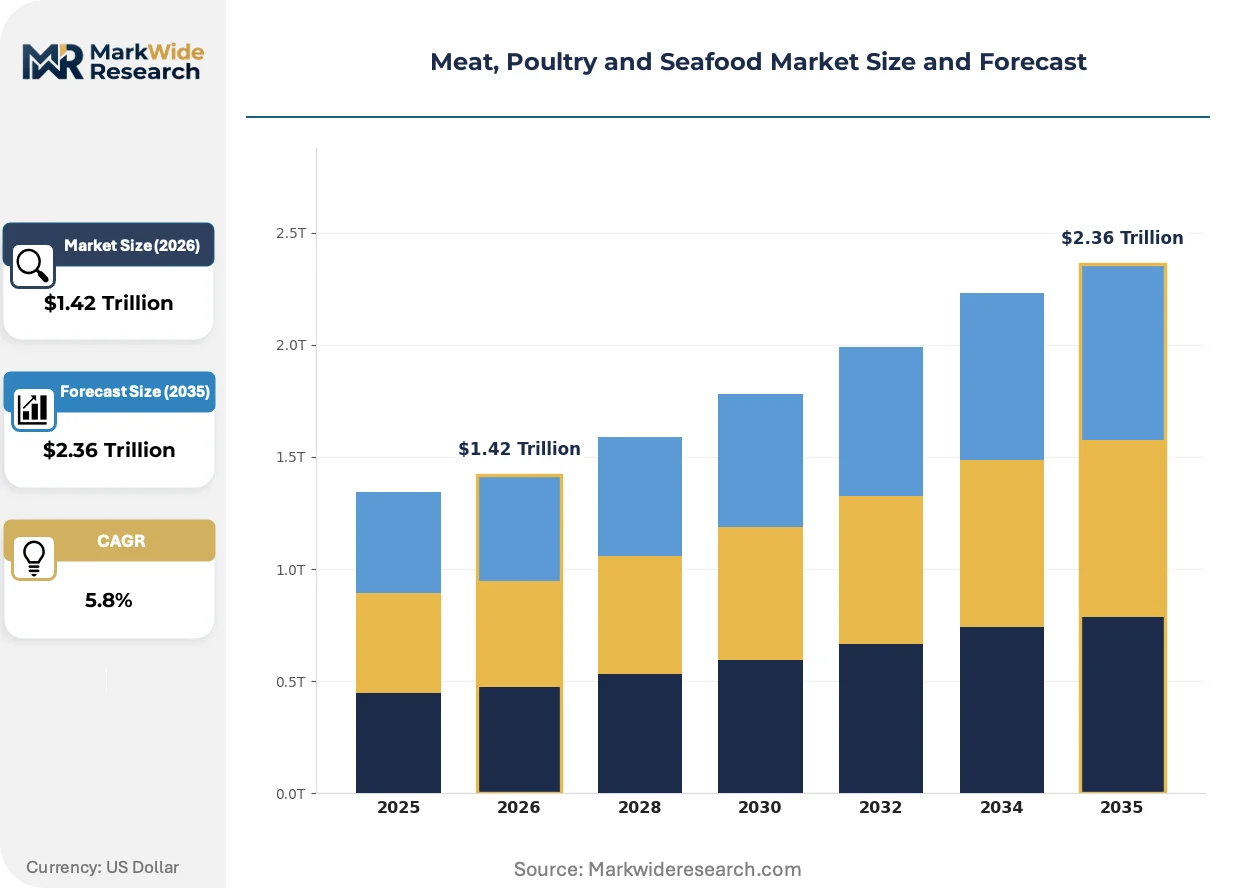
| Market Size in 2026 | $1.42 Trillion |
| Market Size in 2035 | $2.36 Trillion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beef, Chicken, Pork, Fish Processing Method: Fresh, Frozen, Canned, Dried Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Foodservice End User: Households, Restaurants, Caterers, Food Manufacturers |
| Companies Covered | JBS S.A., Tyson Foods, Cargill, WH Group Limited, Marfrig Global Foods, Conagra Brands, Hormel Foods, NH Foods, Danish Crown, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meat, Poultry and Seafood Market Strategic Shifts & Innovations
Processing automation and alternative protein production technologies are fragmenting the traditional commodity-meat value chain into specialized tiered supply systems with divergent capital and expertise requirements.
Bioreactor-based cell cultivation is modularizing protein production geography by enabling distributed manufacturing closer to demand centers. Foodservice manufacturers in Singapore, Israel, and California are piloting 10,000-liter perfusion systems for structured meat products. This technology is compressing the historical dependence on concentrated slaughter capacity and long-haul refrigerated distribution.
EFSA's updated scientific opinions on zoonotic disease transmission through intensive livestock operations are tightening European import inspection frequencies for third-country poultry. Slaughterhouses in Thailand and Ukraine face elevated documentary requirements and physical sampling rates. Frozen breast meat shipments to EU retail chains now carry extended veterinary certification chains.
Direct-to-foodservice procurement contracts are displacing traditional spot-market purchasing for premium beef and seafood cuts. Large restaurant groups in Dubai, London, and Tokyo negotiate six-month volume commitments with specified aging protocols and traceability documentation. This concentration of buying power compresses spot-market liquidity for middle-tier processors.
Meat, Poultry and Seafood Market Segmentation
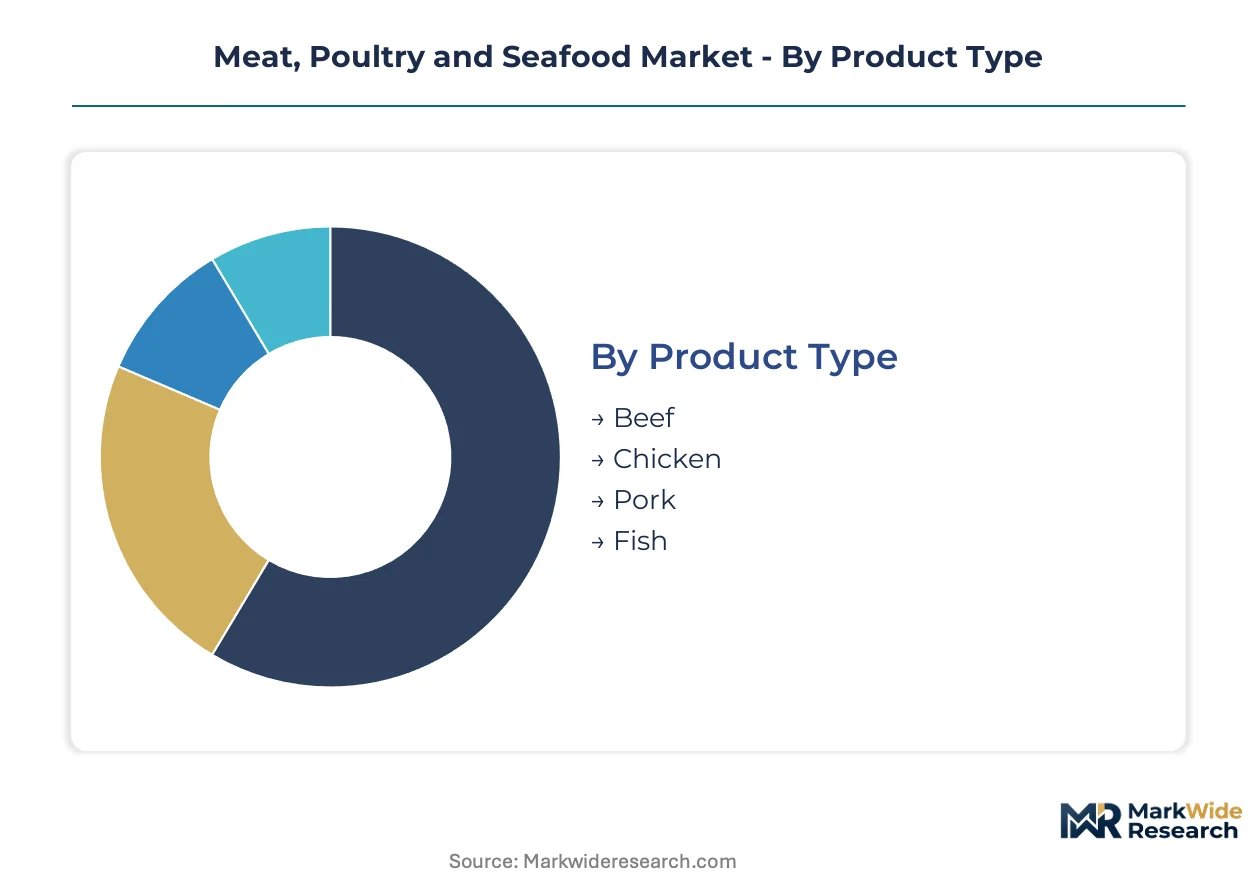
Protein procurement patterns fragment across temperature requirements, shelf-life demands, and traceability thresholds. Each segmentation axis reveals distinct margin structures and capital intensity profiles that shape processor specialization strategies.
Product Type:
Customization versus standardization spans breed genetics, aging protocols, and certification tiers across this category.
- Beef:Grain-fed and grass-finished variants diverge on marbling scores and omega-3 lipid profiles. Demand concentrates in Dubai and Tokyo steakhouse channels where specified aging periods command premium positioning against commodity feedlot supply.
- Chicken:Whole-bird, cut-up, and further-processed formats serve distinct operational economics. Brazil's integrated processors supply deboned breast meat to EU retail under EFSA welfare certification requirements.
- Pork:Bellies and loins dominate industrial slicing and curing applications across German and Italian manufacturing clusters.
- Fish:Whitefish and salmon categories separate on aquaculture sourcing versus wild-catch documentation for sushi-grade distribution.
Leading the category by volume: Chicken. Expanding most quickly: Fish.
Processing Method:
Cost tier separation runs from minimal-intervention fresh products through capital-intensive frozen and shelf-stable formats.
- Fresh:Chilled slaughter-to-retail windows under 72 hours preserve pH stability and myoglobin color retention. EU supermarket chains specify vacuum-skin packaging and temperature-logging compliance for case-ready beef and poultry.
- Frozen:Blast-freezing at minus 40 degrees Celsius arrests enzymatic degradation for ocean-crossing supply chains. Pangasius fillets from Vietnam reach European foodservice through this channel.
- Canned:Retort sterilization extends shelf life for emergency food stockpiles and military procurement.
- Dried:Moisture reduction below 15 percent enables ambient distribution in cold-chain-deficient markets.
Highest margin capture: Fresh. Steepest volume expansion: Frozen.
Distribution Channel:
Customer type stratification separates price-sensitive household procurement from specification-driven institutional buying.
- Supermarkets:Private-label penetration and case-ready packaging dominate volume throughput in US and Brazilian retail.
- Online Retail:Subscription-box models and flash-frozen direct delivery attract urban households seeking convenience.
- Specialty Stores:Halal, kosher, and organic certification gates filter supply for demographic-concentrated neighborhoods.
- Foodservice:Direct contracts with specified traceability documentation displace spot purchasing for hotel and restaurant groups.
Dominant volume pathway: Supermarkets. Gaining share fastest: Foodservice.
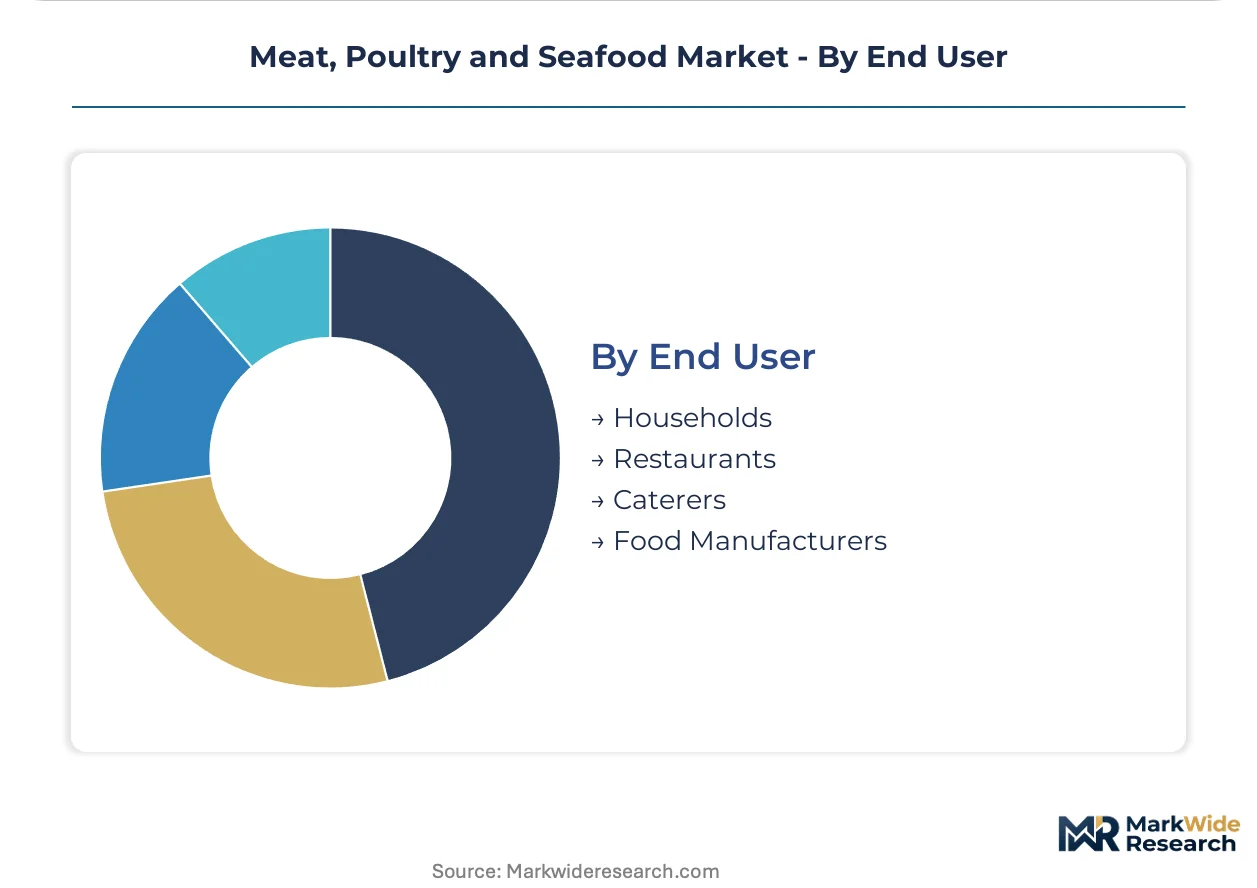
End User:
Application maturity separates established household consumption from emerging precision-manufacturing demand.
- Households:Retail pack sizes and preparation convenience drive purchasing decisions across income segments.
- Restaurants:Menu-engineering specifications for portion consistency and plate coverage shape procurement.
- Caterers:Bulk preparation requirements and holding-temperature resilience prioritize cost-stable supply.
- Food Manufacturers:Ingredient functionality—emulsion capacity, binding properties, and protein content—determines sourcing for processed meat and ready-meal applications.
Largest demand base: Households. Climbing fastest: Food Manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo anchors protein processing capacity through Brazil's integrated beef-poultry corridor, where JBS S.A. and Marfrig Global Foods operate slaughter-to-port infrastructure that commands global export flows.
United States
Foodservice operators in Chicago and Dallas are expanding premium protein menu variety. USDA FSIS enforces pathogen reduction standards that shape domestic slaughterhouse protocols. Tyson Foods anchors massive chicken processing scale across Arkansas and Georgia, balancing volume against margin volatility through direct retail distribution partnerships.
Brazil
Integrated processors in Mato Grosso and Paraná dominate global beef and poultry export volume. MAPA imposes certification demands that fragment compliance pathways for multinational exporters. The Paranaguá and Santos port clusters concentrate cold-chain logistics, where disruption cascades through international protein pricing.
China
Urban households in Shanghai and Beijing drive demand for imported chilled beef and aquaculture-raised seafood. SAMR maintains divergent maximum residue limits for antibiotics that exporters must reconcile with parallel testing protocols. Qingdao and Dalian processing zones attract investment in automated slaughter and precision-cut fabrication for food manufacturing clients.
Germany
Retail chains in Berlin and Munich specify EFSA welfare certification for cage-free eggs and slow-growth poultry. The EU Green Deal agricultural methane targets incentivize feed additive adoption across Lower Saxony livestock operations. Cologne and Frankfurt food manufacturing clusters source specialized fat-trim specifications for industrial slicing and curing applications.
Vietnam
Pangasius and shrimp farming zones in the Mekong Delta seek disease-resistant genetics and automated feeding systems. Technology transfer partnerships unlock export-grade certification for European foodservice channels. Ho Chi Minh City logistics hubs coordinate blast-frozen fillet shipments through ocean-crossing supply chains.
Meat, Poultry and Seafood Market Key Industry Players
Capital-heavy producers compete with asset-light designers across divergent processing tiers. Vertically integrated slaughter-to-retail operators control margin capture through captive supply chains, while specialized processors focus on certification-tier differentiation. Three archetypes dominate: scale-driven commodity processors, premium-certified specialists, and hybrid cell-cultured technology developers. M&A consolidation and bioreactor capacity expansion represent the dominant competitive moves reshaping positioning.
Within the scale-driven tier, JBS S.A. and Tyson Foods exemplify vertically integrated structures spanning multiple protein categories and continents. Cargill occupies a position anchored in global grain-to-protein supply chain control. These three represent the archetype of volume-access gateways, where compliance documentation chains and cold-chain infrastructure investments determine export corridor access.
| Leading Market Players |
|---|
| JBS S.A. |
| Tyson Foods |
| Cargill |
| WH Group Limited |
| Marfrig Global Foods |
| Conagra Brands |
| Hormel Foods |
| NH Foods |
| Danish Crown |
| Others |
Cost & Logistics Intelligence
EFSA welfare certification mandates for cage-free eggs and slow-growth poultry are forcing EU retail chains to consolidate procurement around certified supply pools, compressing spot-market liquidity and elevating contract premiums for compliant processors.
Pricing Analysis
Yield-per-feed-unit pricing anchors protein economics as grain-fed beef, poultry, and aquaculture operations compete on feed conversion efficiency. Three-tier pricing structure across premium, standard, and economy levels separates grass-finished and certified-welfare supply from commodity feedlot output. Cost compression in standard-tier chicken breast is intensifying because Brazilian drought cycles transmit into soybean-meal volatility. Foodservice operators show least price sensitivity for specified aging protocols and traceability documentation, while household retail segments prioritize pack-size value.
Supply Chain Analysis
Trim and offal recovery flows from slaughterhouse fabrication return protein value into pet food and rendering channels, completing circular material utilization. Brazil, Australia, and the United States anchor global beef and poultry export capacity. Production draws from feed-grain inputs, live animal inventories, and bioreactor cell lines. Single-source vulnerability concentrates at Paranaguá and Santos port clusters, where disruption cascades through international pricing. Distribution runs through vertically integrated processor-controlled cold chains and third-party logistics partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell-cultured protein bioreactors are displacing concentrated slaughter capacity as the dominant production technology, restructuring capital deployment and geographic manufacturing patterns across the industry.
For Market Incumbents: Deepen backward integration into feed-grain origination and genetics breeding programs to buffer margin volatility from input cost spikes. Lock in EFSA and USDA FSIS certification documentation chains ahead of tightening residue tolerance harmonization. Prioritize captive cold-chain infrastructure investments in Brazil's integrated corridor to defend volume-access gateways against port disruption risks. For New Entrants and Emerging Players: The mid-tier price-point gap between commodity feedlot supply and premium grass-finished certification offers white-space entry for hybrid cell-cultured products combining precision fermentation scaffolding with animal cell cultivation. Target Vietnam's aquaculture modernization zones for disease-resistant genetics partnerships. Pursue direct-to-foodservice procurement contracts with specified traceability as the primary go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors precision fermentation and bioreactor technology developers with novel food regulatory approvals from Singapore's SFA or US FDA. Long-term viability hinges on which production technologies achieve commercial scale first under divergent global nomenclature frameworks. Monitor litigation outcomes on cell-cultured "meat" labeling claims in US state courts and EU trademark proceedings as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Bioreactor Capacity Expansion | 10,000-liter perfusion systems in Singapore and California compress dependence on concentrated slaughter infrastructure. |
| EFSA Welfare Certification Investment | Cage-free and slow-growth compliance unlocks volume access to EU retail chain procurement pools. |
| Backward Integration into Feed Origination | Soybean-meal hedging through Brazilian grain origination buffers poultry and pork margin volatility. |
| Direct-to-Foodservice Contracting | Six-month volume commitments with Dubai and Tokyo restaurant groups displace spot-market purchasing. |
| Aquaculture Technology Transfer Partnership | Disease-resistant genetics and automated feeding systems unlock Vietnam's export-grade certification pathways. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with slaughterhouse operations directors, cold-chain logistics managers, retail category buyers, and foodservice procurement executives. USDA FSIS enforcement records, EFSA scientific opinions, Brazil MAPA certification databases, and China SAMR residue tolerance documentation provided regulatory boundary conditions. Bottom-up protein volume modeling triangulated against top-down consumer expenditure data across the analysis window.
Production volume streams reconciled with trade flow data and channel inventory estimates throughout the forecast period. Segmentation dimensions spanned protein category, processing temperature tier, distribution channel, and end-use application. CAGRs derived from elasticity-adjusted demand projections incorporating feed-grain cost cycle assumptions and regulatory approval timeline scenarios for novel protein technologies.
Inputs from customs authorities and trade associations were available through the study window; gaps in real-time slaughter capacity utilization and cold-chain spoilage rates introduce uncertainty bands around export volume forecasts. Practitioners should monitor EFSA welfare standard harmonization progress and Singapore SFA novel food pathway expansion for early signals of competitive positioning shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Meat Packaging Market
Meat Products
Beef Fat Market
Meat Products
Europe Bacon Market
Meat Products
North America Bacon Market
Meat Products
Pork Belly Meat Market
Meat Products
Europe Animal Protein Market
Meat Products
Low-Fat Ham Market
Meat Products
Asia-Pacific Edible Meat Market
Meat Products
Meat Mincers Market
Meat Products
Low-Fat Chorizo Market
Meat Products
Global Red Meat Market
Meat Products
Chicken Buckets Market
Meat Products
GCC Edible Meat Market
Meat Products
India Poultry Meat Market
Meat Products
Europe Processed Meat Market
Meat Products
Non-Veg Rte and Rtc Market