
 Yellow Oyster Mushroom Market | 2026-2036
Yellow Oyster Mushroom Market Size, Share, and Industry Trends Forecast 2026-2036
Yellow Oyster Mushroom Market Analytics
Sawdust-based substrate formulations are broadening cultivation economics for small and mid-scale producers of yellow oyster mushrooms. MycoFarm leverages proprietary spawn technology to sustain consistent fruiting cycles across variable climate zones. Hollandia Produce anchors premium retail supply through integrated greenhouse operations in the Netherlands. Fungi Perfecti differentiates via educational outreach and mycological R&D intensity that strengthens brand authority among home cultivators.
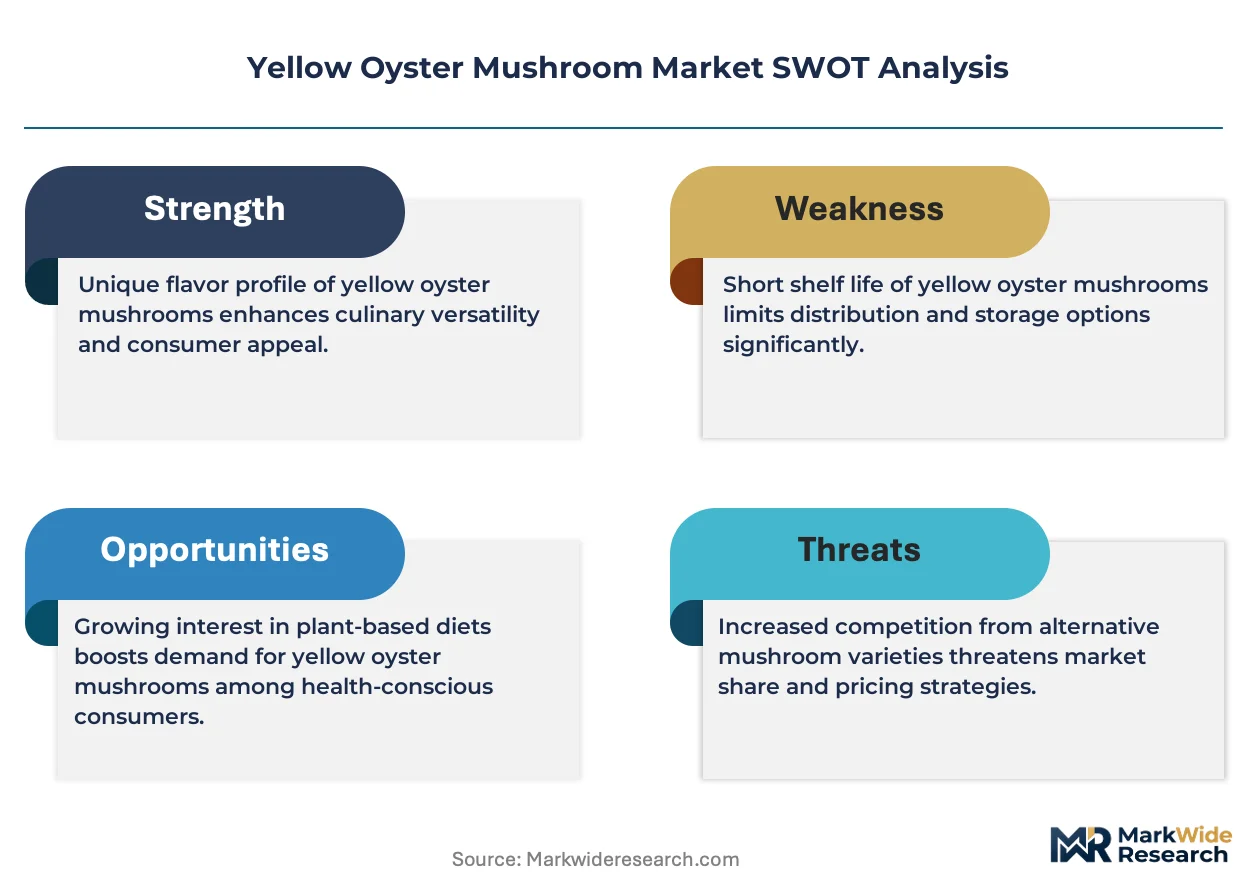
Yellow oyster mushrooms (Pleurotus citrinopileatus) are edible basidiomycetes characterized by bright yellow caps, lateral or absent stipes, and optimal fruiting temperatures between 18°C and 24°C; they serve commercial markets as a visually distinctive, protein-rich ingredient in gourmet and plant-forward cuisines. Fresh product type dominates value capture due to perishability premiums and chef preference for texture integrity, while dried formats occupy a stable niche in specialty retail and export channels where shelf stability commands price premiums. Distribution through farmers' markets and direct online platforms is expanding fastest as traceability and local provenance become decisive purchase criteria for food processors and home consumers.
The FDA and USDA oversee food safety and organic certification standards that govern interstate commerce and export eligibility for cultivated mushroom operations in the United States. EFSA and EU Organic Regulation shape pesticide residue limits and labeling requirements that determine market access for European producers and importers. Stakeholders must monitor evolving substrate sourcing regulations and mycotoxin testing protocols, as compliance costs will increasingly separate scaled certified operations from informal suppliers.
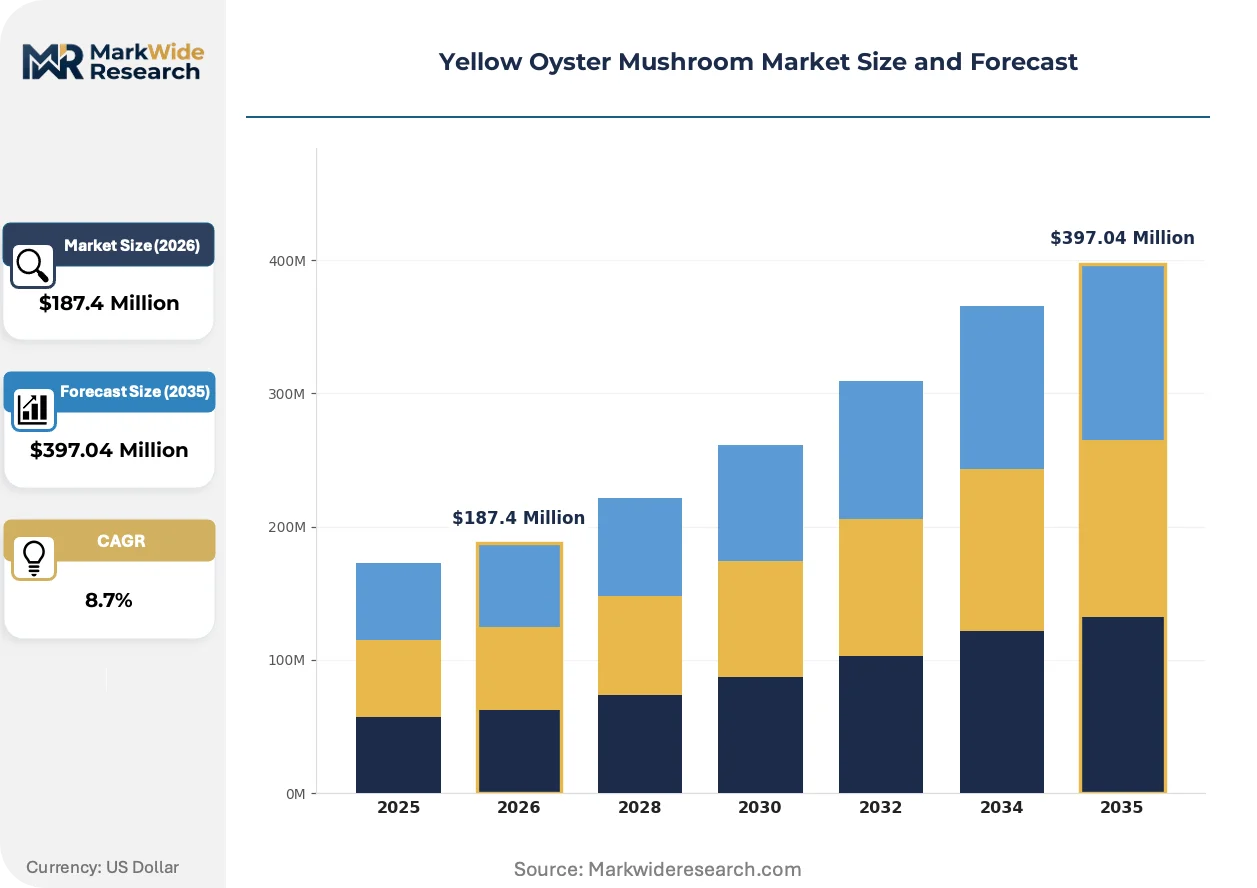
Market Dynamics
Controlled-environment agriculture certifications and substrate sterilization technologies are tightening quality thresholds, separating scaled certified operations from informal suppliers across major producing regions.
Growth Catalysts
- EU Organic Regulation:Stricter pesticide residue limits and labeling requirements create premium positioning for certified Dutch greenhouse clusters supplying European retail chains.
- Specialty restaurants:Chef demand for visually distinctive, protein-rich ingredients drives procurement of fresh yellow oyster mushrooms as premium umami components in plant-forward cuisines.
- Sawdust-based substrate formulations:Lower-cost cultivation inputs broaden economics for small and mid-scale producers entering year-round production cycles.
Market Restraints
- Perishability premiums:Fresh product fragility limits distribution radius and compresses margin capture for non-integrated suppliers lacking cold-chain infrastructure.
- Dutch supply concentration:Year-round output dependency on Netherlands greenhouse clusters creates geographic vulnerability to climate anomalies or energy price shocks.
- Spawn technology scarcity:Proprietary fruiting-cycle consistency remains concentrated among limited technology holders, constraining new entrant scale-up velocity.
Strategic Opportunities
- Farmers' markets and direct online platforms:Traceability and local provenance preferences open fastest-expanding distribution channels for food processors and home consumers.
- Dried format export channels:Shelf-stable niche positioning commands price premiums in specialty retail where fresh distribution proves uneconomical.
- Mycological R&D intensity:Educational outreach investments strengthen brand authority and spawn loyalty among home cultivator segments.
Industry Challenges
- Substrate sourcing compliance:Evolving regulations on mycotoxin testing protocols extend certification timelines and raise operational overhead for scaled facilities.
- Climate zone variability:Maintaining optimal fruiting temperatures between 18°C and 24°C across variable environments demands capital-intensive environmental controls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yellow Oyster Mushroom Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh, Dried, Canned, Frozen Distribution Channel: Online, Supermarkets, Farmers' Markets, Wholesale End User: Restaurants, Retailers, Food Processors, Home Consumers Packaging Type: Boxes, Bags, Trays, Jars |
| Companies Covered | Oke USA, Hollandia Produce, MycoFarm, Shrooms Inc., Fungi Perfecti, Mushroom Mountain, FreshCap Mushrooms, North Spore, The Mushroom Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yellow Oyster Mushroom Market Evolving Landscape
Spawn technology standardization and direct-to-consumer channel maturation are compressing traditional wholesale intermediation while elevating quality transparency requirements.
Automated climate control systems with sensor-network feedback loops are modularizing greenhouse operations. Mid-scale Dutch producers deploy these systems to maintain consistent fruiting cycles without proprietary spawn technology. The approach compresses capital requirements for quality parity with integrated incumbents.
EFSA mycotoxin testing protocols are tightening residue thresholds for interstate commerce eligibility. Cultivated mushroom operations face expanded laboratory verification burdens. European importers and domestic US facilities under FDA oversight are consolidating supplier relationships around pre-certified operations.
Home cultivators now prioritize substrate kit traceability over price minimization. Direct online platforms displace generalist retailers as the primary research-and-purchase channel. This behavioral pivot concentrates most visibly in North American and Western European urban markets where mycological education investments have built brand recognition.
Yellow Oyster Mushroom Market Segmentation
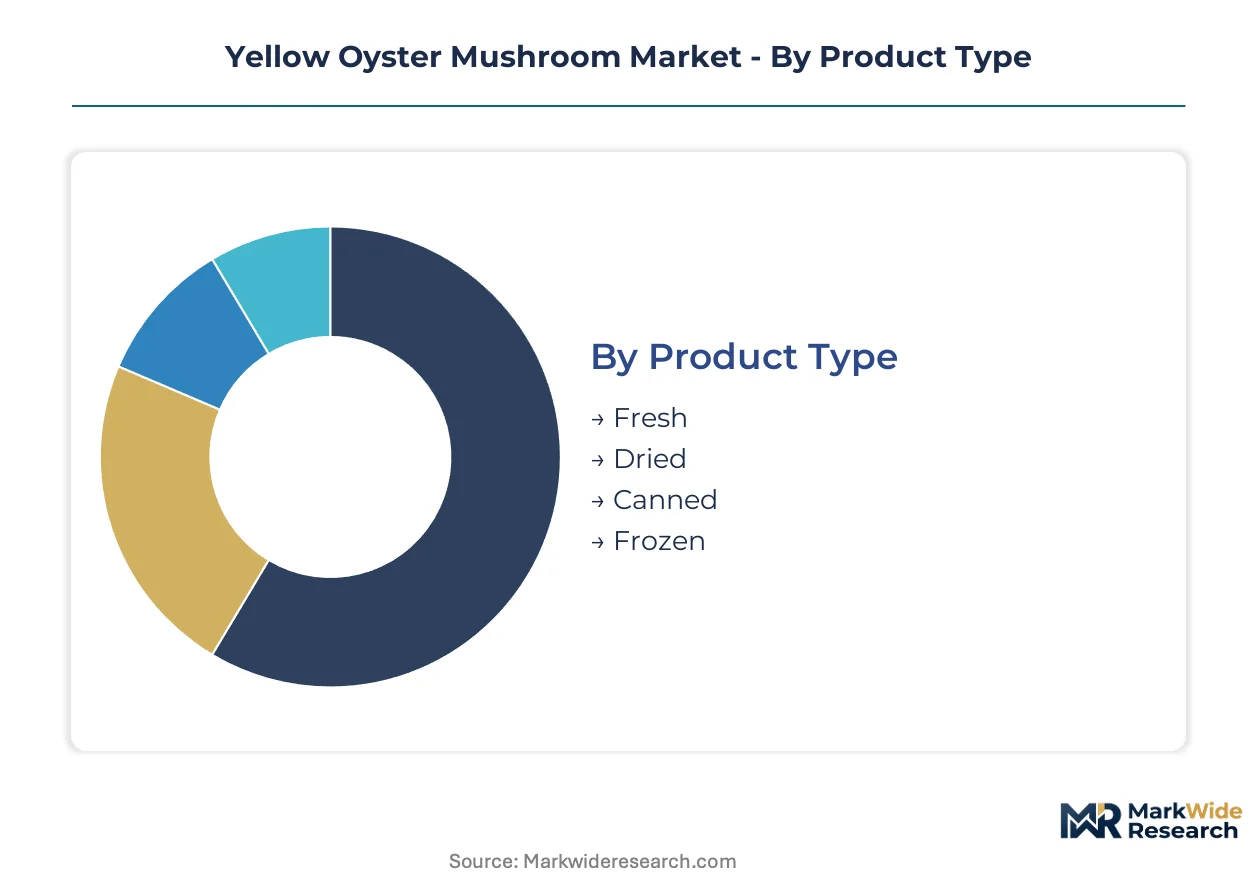
Segmentation in the yellow oyster mushroom market reveals how perishability pressures, traceability demands, and channel economics split procurement behavior across distinct operational tiers. Producers must match format and packaging investments to the temperature tolerance and shelf-life requirements of each downstream segment.
Product Type:
Standardization dominates at the commodity end through bulk dried and frozen formats, while fresh products command premium customization for chef-specific texture and visual specifications.
- Fresh:Unprocessed fruiting bodies with intact cap structure and lateral stipe attachment deliver the visual distinction and firm texture that specialty restaurants prioritize for raw and lightly cooked applications. Dutch greenhouse clusters supply year-round fresh output to European retail chains under controlled-environment agriculture certifications that verify substrate sterilization and pesticide compliance.
- Dried:Dehydrated caps and stems with moisture content below 10 percent enable shelf-stable distribution to export channels where cold-chain infrastructure proves uneconomical. Demand concentrates in North American and Western European specialty retail where home cultivators and food processors accept texture trade-offs for extended storage and concentrated umami extraction.
- Canned:Brine-packed or marinated formats for food service bulk procurement and institutional catering operations requiring extended holding periods without refrigeration dependency.
- Frozen:IQF and block-frozen products for industrial food processors integrating yellow oyster mushrooms into ready-meal and plant-based protein formulations.
Most installed capacity flows through Fresh. Expansion is steepest in Dried.
Distribution Channel:
Channel selection tracks customer scale and provenance verification intensity, with direct platforms capturing traceability-focused segments and wholesale retaining volume aggregation for processed formats.
- Online:Direct-to-consumer platforms and specialized mycology retailers displace generalist channels as primary research-and-purchase venues for home cultivators prioritizing substrate kit traceability over price minimization. Urban markets in the Netherlands and Germany show highest penetration where educational outreach investments have built brand recognition.
- Farmers' Markets:Local provenance verification and harvest-date transparency attract food processors and restaurant buyers seeking short-chain procurement with visible cultivation credentials.
- Supermarkets:Consolidated retail procurement for packaged fresh and dried formats with standardized quality grades and barcode traceability systems.
- Wholesale:Volume aggregation for canned and frozen products serving institutional food service and industrial processing operations with pallet-scale logistics.
Volume concentrates in Wholesale. Climbing the fastest are Online channels.
End User:
User segmentation separates premium ingredient positioning in food service from commodity input functions in processing, with home cultivation emerging as a distinct behavioral cluster.
- Restaurants:Chef-driven procurement of fresh yellow oyster mushrooms as visually distinctive, protein-rich components in plant-forward and gourmet cuisines. Specialty restaurants in the Netherlands and Belgium anchor demand for premium umami ingredients with specific cap diameter and color intensity specifications.
- Home Consumers:Hobbyist cultivators and culinary enthusiasts purchasing spawn kits, substrate blocks, and educational materials through direct online platforms. This segment shows strongest growth in North American urban markets where mycological R&D investments have built brand authority.
- Food Processors:Industrial buyers of dried, frozen, and canned formats for integration into plant-based meat alternatives, ready meals, and extraction applications.
- Retailers:Supermarket and specialty store buyers curating packaged fresh and dried assortments for consumer self-selection.
Procurement scale peaks with Food Processors. Gaining share fastest are Home Consumers.
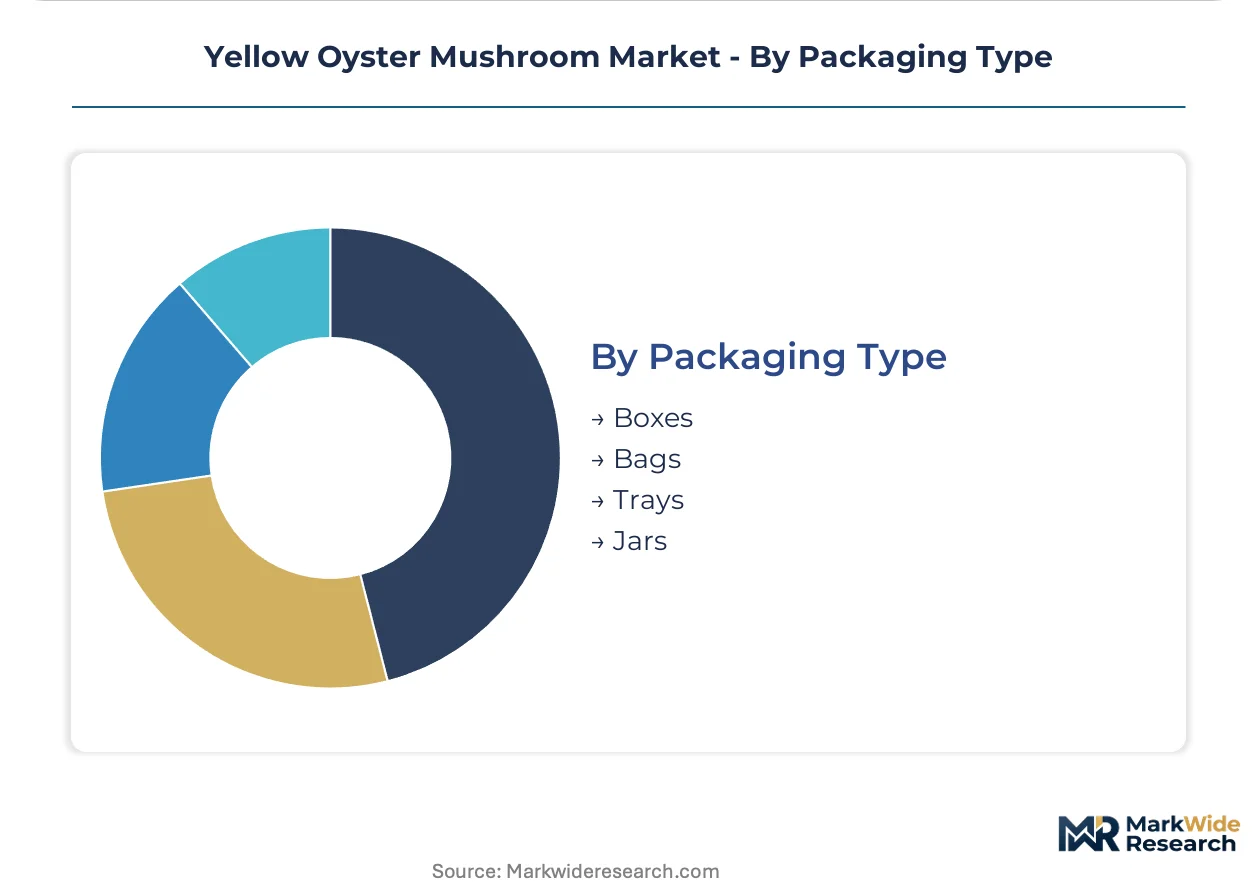
Packaging Type:
Packaging economics align with perishability windows and handling intensity, from breathable structures for fresh short-chain distribution to hermetic barriers for shelf-stable export.
- Trays:Modified-atmosphere and overwrapped structures for fresh retail presentation preserving cap integrity and moisture balance during refrigerated display. Dutch greenhouse operations favor tray formats for direct supply to European supermarket chains with automated checkout compatibility.
- Bags:Vacuum and gas-flushed barriers for dried product shelf stability and bulk food service distribution with reseal functionality.
- Boxes:Corrugated and solid fiber containers for wholesale aggregation of fresh, frozen, and canned products with stack strength for palletized logistics.
- Jars:Glass and rigid plastic containers for marinated, brined, and value-added preserved formats in specialty retail.
Shipment volume flows predominantly through Boxes. Steepest expansion trajectory belongs to Trays.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dutch greenhouse clusters in Westland and Noord-Brabant supply year-round yellow oyster mushroom output to European retail chains under controlled-environment agriculture certifications. Specialty restaurants in Amsterdam and Rotterdam drive premium fresh procurement with specific cap diameter and color intensity specifications. EFSA pesticide residue limits and EU Organic Regulation labeling requirements determine market access for producers and importers across the continent.
Netherlands
Integrated greenhouse operations in Westland supply year-round fresh output to Albert Heijn and Jumbo retail chains. EU Organic Regulation certification creates premium positioning for Dutch clusters exporting to Germany and Belgium. Noord-Brabant cultivation facilities deploy automated climate control systems to maintain 18°C-24°C fruiting temperatures across variable seasons.
United States
Home cultivator demand concentrates in Pacific Northwest urban markets where mycological education investments built brand recognition. FDA food safety standards and USDA organic certification govern interstate commerce eligibility for spawn kit distributors. Pennsylvania-based substrate suppliers serve mid-Atlantic restaurant clusters seeking local provenance verification.
Germany
Specialty retail chains in Berlin and Munich prioritize substrate kit traceability over price minimization for home cultivation segments. EFSA mycotoxin testing protocols tighten residue thresholds for imported dried formats. Bavarian direct-to-consumer platforms displace generalist retailers as primary research-and-purchase channels.
Belgium
Chef-driven procurement in Brussels and Antwerp anchors demand for premium umami ingredients with visual distinction requirements. EU Green Deal agricultural sustainability metrics influence substrate sourcing compliance timelines. Flanders greenhouse operations leverage Dutch supply chain infrastructure for cold-chain distribution to French retail.
China
Sawdust-based substrate formulations broaden cultivation economics for small-scale producers in Fujian and Zhejiang provinces. National food safety standards under SAMR oversight govern pesticide residue limits for export eligibility. Yangtze River Delta processing clusters supply dried formats to North American specialty retail channels.
Yellow Oyster Mushroom Market Competitive Landscape
Global majors compete with regional champions across spawn technology and controlled-environment agriculture certifications. The vendor base separates into integrated greenhouse operators, spawn technology specialists, and direct-to-consumer education platforms. Three archetypes dominate: proprietary spawn holders sustaining consistent fruiting cycles, vertically integrated greenhouse clusters with year-round output capacity, and mycological R&D firms building brand authority among home cultivators. Competitive moves concentrate on automated climate control licensing and substrate sterilization certification consolidation.
Within the integrated greenhouse tier, Hollandia Produce anchors premium retail supply through Dutch operations exemplifying controlled-environment scale. Spawn technology specialists include MycoFarm occupying a position among proprietary fruiting-cycle consistency holders. Mycological R&D intensity differentiates Fungi Perfecti, which sits within the education-platform archetype strengthening brand recognition among North American home cultivators.
| Leading Market Players |
|---|
| Oke USA |
| Hollandia Produce |
| MycoFarm |
| Shrooms Inc. |
| Fungi Perfecti |
| Mushroom Mountain |
| FreshCap Mushrooms |
| North Spore |
| The Mushroom Company |
| Others |
Value Network & Pricing Analysis
Sawdust pellet indices in Fujian province cascade through substrate formulation costs into three-tier pricing structure across premium, standard, and economy levels for yellow oyster mushroom output. Dutch greenhouse clusters leverage year-round production to command premium positioning while small-scale Chinese producers compete on volume economics.
Pricing Analysis
Input-cost pass-through from spawn technology licensing and substrate sterilization equipment compresses margins for non-integrated producers. Three-tier pricing structure across premium, standard, and economy levels separates EU Organic certified Dutch output from conventional greenhouse production and informal smallholder supply. Pricing pressure stems from energy cost volatility in Netherlands greenhouse operations. Food processors show highest price sensitivity due to commodity input substitution options, while specialty restaurants absorb premiums for visual distinction specifications.
Supply Chain Analysis
Refrigerated freight cost premiums for fresh distribution constrain radius economics for non-integrated suppliers. Production concentrates in the Netherlands, China, and the United States, with Dutch clusters anchoring premium supply and Chinese Fujian province feeding dried export channels. Raw material dependencies center on sawdust substrates, proprietary spawn cultures, and sterilization energy inputs. Single-source vulnerability from Netherlands energy grid exposure threatens year-round output continuity. Distribution runs through direct online platforms and wholesale aggregation for processed formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Organic Regulation certification milestones create durable demand segmentation between premium and commodity tiers.
For Market Incumbents: Lock in spawn technology licensing agreements to defend against emerging automated climate control modularization. Secure backward integration into substrate supply chains in Zhejiang province to neutralize raw material cost volatility. Prioritize EFSA pre-certification consolidation to filter informal competitors from retail procurement lists. For New Entrants and Emerging Players: Direct-to-consumer online platforms offer the lowest barrier entry path for home cultivator segments in North American urban markets. Target substrate kit traceability positioning where brand authority gaps persist against established education platforms. Pursue white-label supply agreements with mid-Atlantic restaurant clusters seeking local provenance verification. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated greenhouse operators possessing both spawn technology and controlled-environment agriculture certifications. Long-term viability hinges on regulatory compliance scalability rather than volume expansion alone. Watch EFSA mycotoxin testing protocol tightening as the inflection signal for supplier consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Climate Control Licensing | Modular greenhouse systems enable Dutch mid-scale producers to match integrated incumbent quality parity. |
| EU Organic Certification Investment | EFSA compliance creates premium positioning for Netherlands clusters exporting to German retail chains. |
| Direct-to-Consumer Platform Launch | Online channels displace generalist retailers where home cultivators prioritize substrate kit traceability. |
| Substrate Sourcing Backward Integration | Sawdust supply control in Fujian province insulates Chinese producers from pellet price volatility. |
| Mycological Education Partnership | Brand authority investments strengthen spawn loyalty among Pacific Northwest hobbyist cultivators. |
Research Methodology
Direct dialogue with greenhouse operations managers, spawn technology specialists, restaurant procurement chefs, and substrate suppliers grounded qualitative findings in operational reality. Secondary validation drew from EFSA pesticide residue databases, FDA food safety inspection records, Dutch customs export statistics, and EU Organic Regulation certification registries. Bottom-up cultivation capacity estimates triangulated against top-down retail channel volume aggregation.
Bottom-up modeling tracked individual producer capacity across Netherlands, China, and United States greenhouse operations, while top-down analysis calibrated against European retail chain procurement disclosures and North American direct-to-consumer platform transaction data. Segmentation dimensions spanned product format, distribution channel, end-user archetype, and packaging type across the projection horizon. CAGR derivation incorporated spawn technology adoption curves, energy cost scenario modeling, and regulatory compliance timeline assumptions.
Energy price shocks, EFSA mycotoxin threshold revisions, and climate anomaly disruptions are the dominant revision risks for forecast trajectories. Forecasts reflect documented assumptions about substrate sterilization technology diffusion and certification cost curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Argentina Fruits & Vegetables Market
Fruits and Vegetables
Raisins Market
Fruits and Vegetables
Fresh Figs Market
Fruits and Vegetables
Goji Berries Market
Fruits and Vegetables
Date Fruit Market
Fruits and Vegetables
Fruit and Vegetable Pulp Market
Fruits and Vegetables
Global Morel Mushroom Market
Fruits and Vegetables
Peach Extract Market
Fruits and Vegetables
Spring Market
Fruits and Vegetables
Organic Bananas Market
Fruits and Vegetables
Dried Fruits Market
Fruits and Vegetables
Asia-Pacific Shiitake Mushroom Market
Fruits and Vegetables
Bahrain Fruits and Vegetables Market
Fruits and Vegetables
Europe Dried Mushroom Market
Fruits and Vegetables
Infused Dried Fruits Market
Fruits and Vegetables
Cranberries Market