
 Asia-Pacific Edible Meat Market | 2026-2036
Asia-Pacific Edible Meat Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Edible Meat Market Outlook
The gap between premium chilled cuts and frozen commodity volumes is rebalancing across Asia-Pacific trading floors. WH Group Limited leverages its integrated pork operations across China to sustain cost advantages in wholesale channels. Nichirei Corporation anchors its position through deep cold chain infrastructure in Japan. Charoen Pokphand Group dominates Southeast Asian feed-to-farm networks that supply regional processors.
Asia-Pacific edible meat encompasses muscle tissue and organ meats from livestock and aquaculture, processed to moisture contents typically below 75 percent for fresh retail or preserved through thermal treatment and controlled-atmosphere packaging for extended shelf stability. Its commercial purpose centers on delivering standardized protein units to retail, food service, and further-processing industries with verifiable safety credentials. Poultry leads volume throughput due to shorter production cycles and lower feed conversion ratios, while beef commands concentrated margin pools in premium chilled and vacuum-packed formats. The food service customer segment is expanding fastest as hotel and restaurant chains professionalize procurement, though household retail still occupies the largest absolute consumption base across the region.
Japan's Ministry of Agriculture, Forestry and Fisheries enforces JAS grading and import health certificates that filter supplier eligibility, while China's SAMR monitors domestic slaughter hygiene and labeling compliance through updated GB standards. Australia's Department of Agriculture biosecurity framework restricts live animal and fresh meat pathways, redirecting trade flows toward processed and frozen categories. Stakeholders must monitor how ASEAN harmonization talks reshape cross-border inspection protocols and determine whether to build in-house compliance teams or outsource certification management.
Market Dynamics
Cold chain infrastructure modernization across Southeast Asia is redrawing procurement geography, enabling food service operators to source chilled cuts from processing clusters previously reachable only through frozen logistics. This shift compresses margin pools for commodity traders while rewarding integrated operators with captive cold storage networks.
Growth Catalysts
- ASEAN harmonization talks:Proposed cross-border inspection protocol alignment is reducing clearance friction for Vietnamese processors exporting to Indonesian food service channels. The streamlined certification pathway accelerates inventory turns.
- Urban corridor demand concentration:Vietnam's Ho Chi Minh City-Hanoi corridor and Indonesia's Greater Jakarta cluster are absorbing premium chilled beef volumes as hotel chains professionalize protein procurement specifications.
- Controlled-atmosphere packaging:Extended shelf stability technology is enabling Australian exporters to bypass traditional frozen-only pathways into Japanese retail, capturing margin premiums previously reserved for domestic chilled supply.
Market Restraints
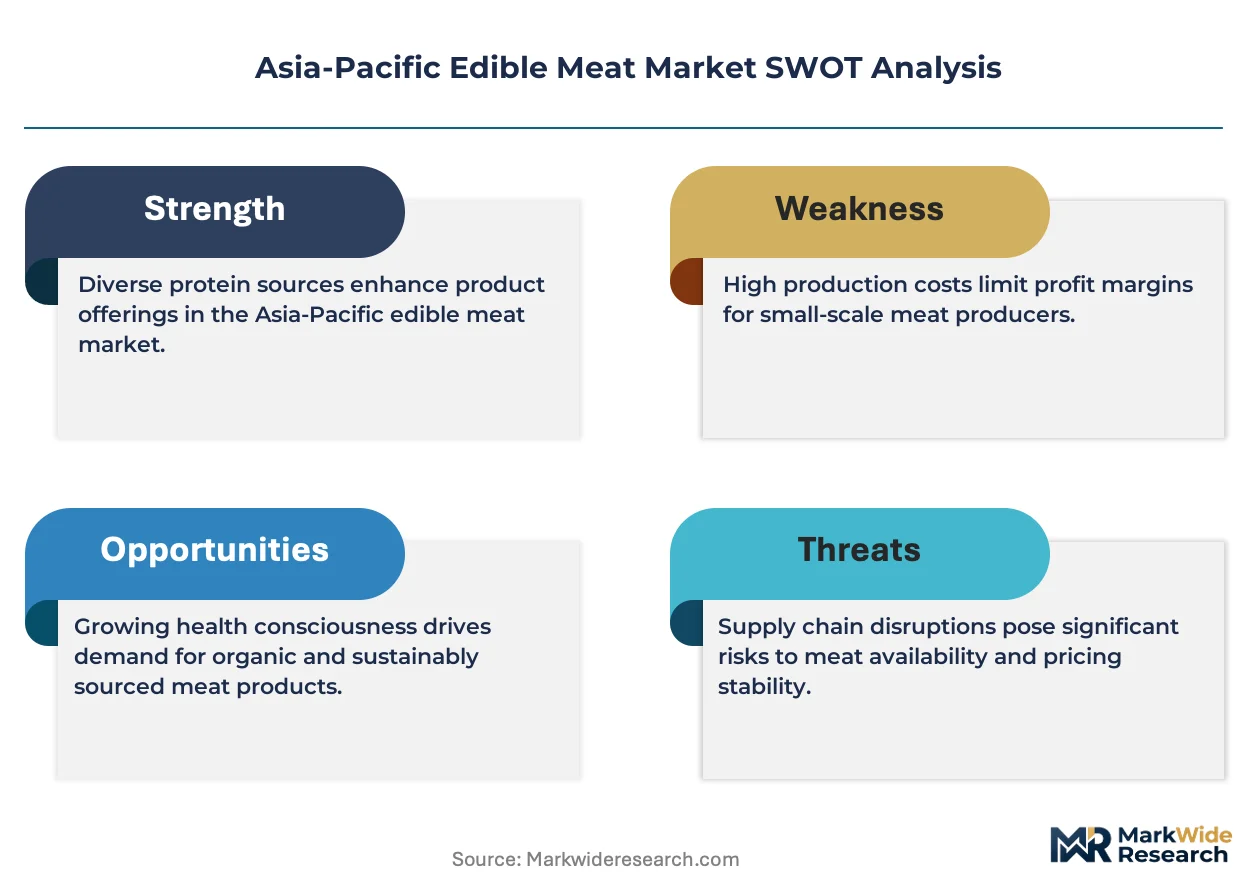
- Feed input cost volatility:Soybean meal and corn price swings compress margin predictability for Southeast Asian poultry integrators operating on fixed-price food service contracts.
- Biosecurity protocol stringency:Australia's Department of Agriculture restrictions on live animal and fresh meat pathways force trade flow redirection toward processed categories with lower unit economics.
- Cold chain infrastructure gaps:Last-mile refrigeration deficits in Indonesian archipelago distribution limit chilled product penetration outside Java-based processing clusters.
Strategic Opportunities
- Philippine archipelago penetration:Underdeveloped cold chain networks in Visayas and Mindanao create first-mover advantage for integrated operators building captive distribution.
- Japan JAS organic certification:Tightening import criteria for organic-labeled product creates premium positioning opportunity for Australian and New Zealand suppliers with verified pasture-based systems.
- Direct-to-hotel procurement platforms:Digital tendering systems are disintermediating traditional wholesale layers, enabling processors to capture margin previously allocated to trading intermediaries.
Industry Challenges
- Veterinary certification bottlenecks:Australia's export health certificate processing timelines create inventory planning complexity for processors serving Japanese import windows.
- Halal slaughter compliance integration:Dual-standard facilities serving both domestic and Middle Eastern export markets face capex intensity for segregated processing lines and auditor qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Edible Meat Market |
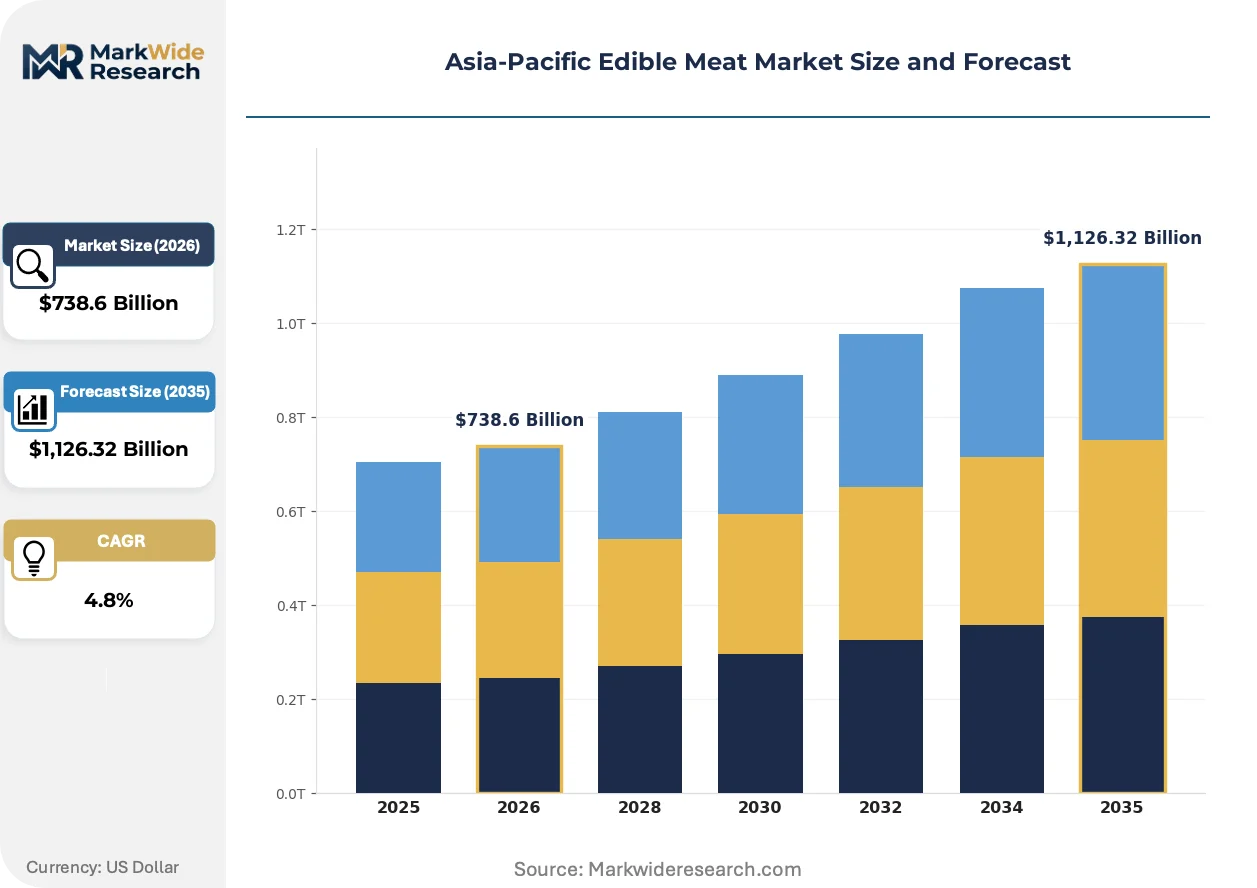
| Market Size in 2026 | $738.6 Billion |
| Market Size in 2035 | $1,126.32 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pork, Beef, Poultry, Seafood Distribution Channel: Retail, Wholesale, Online, Meat Shops Packaging Type: Tray, Vacuum Pack, Canned, Chilled Customer Type: Household, Food Service, Retailers, Processors |
| Companies Covered | BRF S.A., WH Group Limited, COFCO Corporation, Nichirei Corporation, NH Foods Ltd, JBS S.A., Tyson Foods Inc., Danish Crown AmbA, Charoen Pokphand Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Edible Meat Market Strategic Shifts
Protein sourcing patterns across Asia-Pacific food service are professionalizing as procurement teams adopt specification-driven tendering, displacing relationship-based purchasing. Technology deployment now centers on traceability verification and automated sorting systems that compress labor dependency in high-throughput processing environments.
Hyperspectral imaging systems are automating fat-content grading and foreign-object detection in Australian and Japanese beef processing facilities. Mid-scale operators in Vietnam and Thailand are retrofitting existing lines with modular units, reducing manual inspection headcount while accelerating line speeds. The technology is automating quality consistency previously achievable only through experienced manual graders, compressing skill premium differentials between facilities.
China's SAMR updated GB standards for slaughter hygiene and labeling compliance are tightening domestic processor accountability. The framework mandates enhanced traceability documentation and third-party audit frequency, elevating compliance costs for smaller operators. Beef and pork segments serving premium retail channels are absorbing certification investments fastest, while commodity-oriented processors face margin compression or exit pressure.
Hotel and restaurant chains across Southeast Asia are consolidating supplier relationships around integrated processors with captive cold chain assets. The procurement model displaces fragmented spot-market purchasing with annual volume commitments tied to specification compliance. Indonesia's international hotel operators and Singapore's contract catering sector are driving this consolidation most visibly, prioritizing supply security over price minimization in their sourcing calculus.
Asia-Pacific Edible Meat Market Segmentation
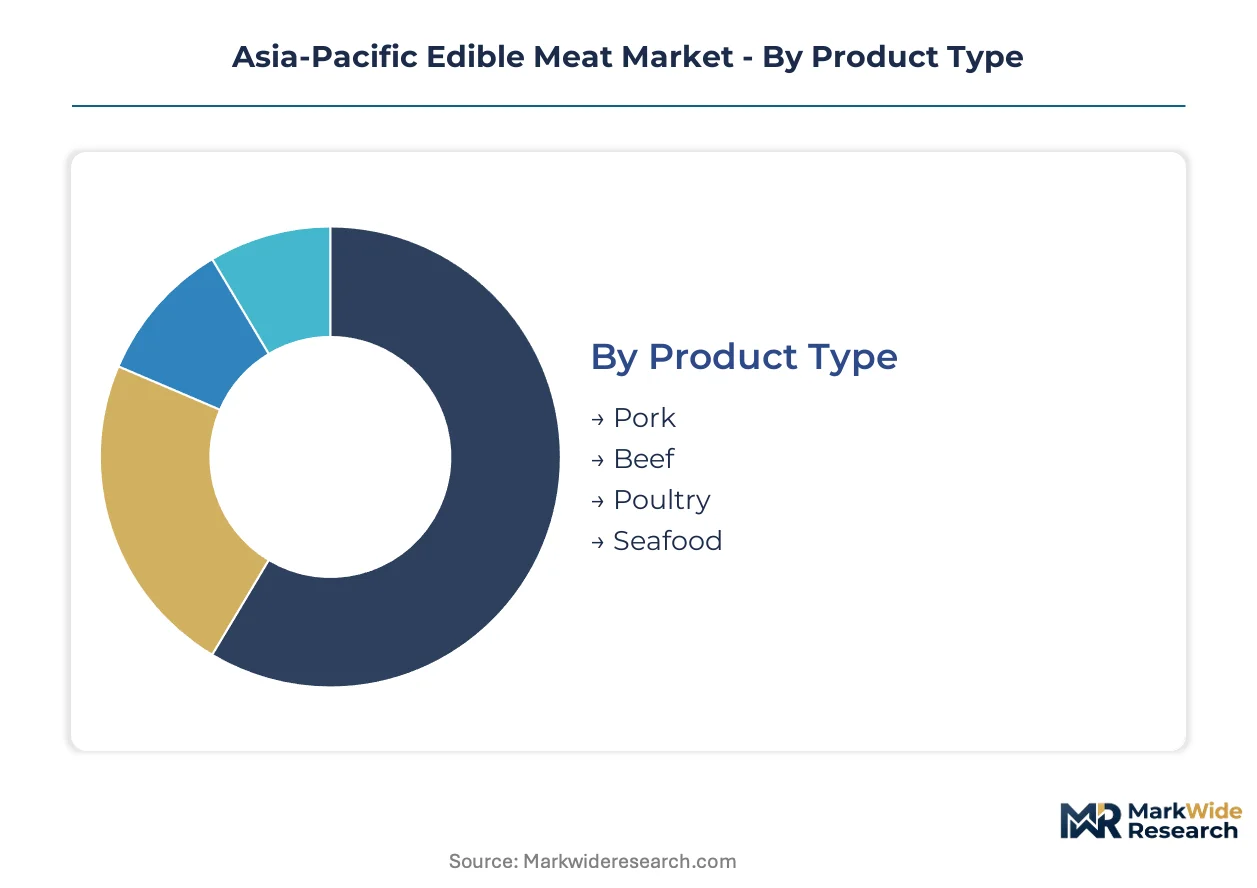
Protein sourcing patterns across Asia-Pacific diverge sharply between high-volume commodity flows and specification-driven premium channels. Segmentation discipline separates traders optimizing for throughput from integrators capturing margin through certification and captive cold chain assets.
Product Type:
Pork commands absolute volume across East Asian wholesale floors while beef concentrates margin in chilled premium formats. Poultry's feed conversion efficiency sustains cost leadership in Southeast Asian food service procurement.
- Pork:Muscle tissue from swine dominates Chinese wholesale throughput with moisture content typically below 75 percent for fresh retail distribution. WH Group's integrated operations across Henan and Sichuan provinces anchor cost advantages in domestic food service channels facing procurement professionalization.
- Poultry:Shorter production cycles and superior feed conversion ratios position broiler meat as the default protein for Southeast Asian hotel chains expanding room service and banquet operations. Indonesia's Java-based processing clusters absorb the fastest volume expansion as cold chain logistics modernize.
- Beef:Vacuum-packed chilled cuts from Australian pasture systems command premium positioning in Japanese retail channels governed by JAS grading protocols.
- Seafood:Aquaculture-derived muscle tissue supplies protein units with distinct fatty acid profiles for health-positioned retail formats across South Korean and Japanese markets.
Today's leader: Poultry. Tomorrow's challenger: Beef.
Distribution Channel:
Channel selection determines margin capture versus volume throughput for processors navigating procurement consolidation.
- Retail:Supermarket chains across Vietnam's urban corridor and Indonesia's Greater Jakarta cluster specify chilled presentation with controlled-atmosphere packaging extending shelf stability. Nichirei's deep cold chain infrastructure enables Japanese retail penetration that Australian exporters previously accessed only through frozen pathways.
- Wholesale:Trading intermediaries in Bangkok and Singapore spot markets aggregate commodity volumes for further-processing industries and traditional wet market vendors. Margin compression accelerates as direct-to-hotel digital tendering platforms disintermediate traditional layers.
- Online:E-commerce platforms serving Seoul and Shanghai metropolitan areas require frozen or modified-atmosphere specifications compatible with last-mile delivery windows.
- Meat Shops:Traditional butcher counters across Philippine and Indonesian secondary cities maintain relationship-based purchasing with limited specification compliance documentation.
Retail captures margin premiums. Wholesale retains volume dominance.
Packaging Type:
Packaging technology selection governs shelf stability extension and logistics cost structure across archipelago distribution challenges.
- Vacuum Pack:Oxygen-exclusion systems enable Australian beef exporters to bypass traditional frozen-only pathways into Japanese retail, capturing margin premiums previously reserved for domestic chilled supply. Extended shelf stability compresses inventory risk for processors serving import health certificate windows.
- Chilled:Temperature-controlled distribution at 0-4°C preserves organoleptic properties for hotel and restaurant chains professionalizing protein procurement specifications across Ho Chi Minh City-Hanoi corridor expansion.
- Tray:Modified-atmosphere overwrap dominates Southeast Asian supermarket fresh meat counters with shorter planned turnover cycles.
- Canned:Thermal treatment preservation supplies emergency stockpiling and military procurement channels across archipelago nations with refrigeration infrastructure gaps.
Vacuum pack gains share in premium channels. Tray formats defend mass-market position.
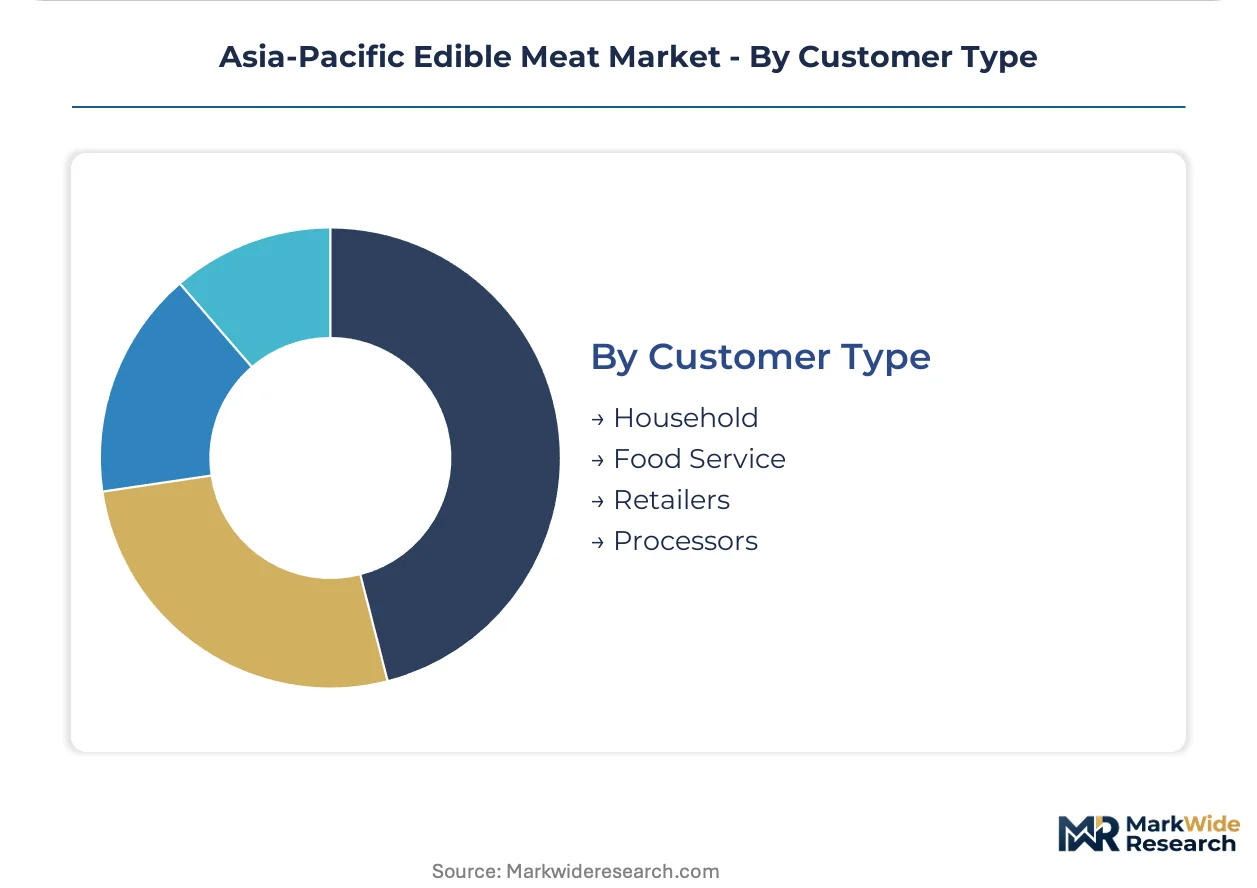
Customer Type:
End-user sophistication separates specification-driven tendering from price-sensitive spot purchasing.
- Food Service:Hotel and restaurant chains across Singapore's contract catering sector and Indonesia's international hotel operators consolidate supplier relationships around integrated processors with captive cold chain assets. Annual volume commitments displace fragmented spot-market purchasing with specification compliance requirements.
- Household:Retail purchasing across East Asian metropolitan markets still occupies the largest absolute consumption base despite slower growth trajectory relative to food service professionalization.
- Processors:Further-processing industries in Thailand and Vietnam source standardized protein units for sausage, cured meat, and ready-meal manufacturing with verifiable safety credentials.
- Retailers:Supermarket procurement teams adopt specification-driven tendering with traceability documentation requirements filtering supplier eligibility.
Food service expands most quickly. Household retains volume base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Processing expertise concentrates in Vietnam's Red River Delta and Indonesia's Central Java, where skilled labor pools support scaled slaughter operations. These workforce clusters anchor regional protein supply as cold chain investments expand reach.
China
Henan and Sichuan provinces drive pork processing throughput for domestic food service channels. SAMR's updated GB standards for slaughter hygiene tighten compliance documentation requirements. WH Group's integrated operations across these provinces sustain cost advantages in wholesale distribution.
Japan
Hotel chains in Tokyo and Osaka professionalize beef procurement specifications for premium chilled formats. METI and MAFF enforce JAS grading protocols and import health certificates that filter supplier eligibility. Nichirei's deep cold chain infrastructure enables domestic retail penetration with extended shelf stability technology.
Australia
Pasture-based beef systems supply vacuum-packed chilled cuts to Japanese retail channels. The Department of Agriculture's biosecurity framework restricts live animal and fresh meat pathways, redirecting trade toward processed categories. Queensland and New South Wales processing clusters capture margin premiums through controlled-atmosphere packaging exports.
Vietnam
The Ho Chi Minh City-Hanoi corridor absorbs expanding poultry volumes as hotel chains consolidate supplier relationships. ASEAN harmonization talks streamline cross-border inspection protocols for processors exporting to Indonesian food service channels. Red River Delta slaughter facilities modernize with automated sorting systems to meet specification-driven tendering requirements.
Indonesia
Java-based processing clusters face last-mile refrigeration deficits limiting chilled product penetration to outer islands. The national halal certification authority mandates segregated processing lines for dual-standard facilities serving Middle Eastern export markets. Greater Jakarta's international hotel operators drive procurement consolidation around integrated processors with captive cold chain assets.
Asia-Pacific Edible Meat Market Competitive Environment
Capital-heavy producers compete with asset-light traders across Asia-Pacific protein flows. The market structures around three tiers: integrated operators with captive feed-to-farm networks, regional cold chain specialists, and commodity traders optimizing for throughput. Strategic moves center on backward integration into feed production and geographic expansion through processing cluster acquisitions.
Within the integrated operator tier, WH Group Limited and Charoen Pokphand Group exemplify asset-heavy positioning through captive supply networks spanning multiple countries. Nichirei Corporation occupies a distinct archetype as a cold chain infrastructure anchor enabling premium channel access. These three represent the dominant strategic configurations: upstream control over feed inputs, regional feed-to-farm integration, and distribution infrastructure ownership.
| Leading Market Players |
|---|
| BRF S.A. |
| WH Group Limited |
| COFCO Corporation |
| Nichirei Corporation |
| NH Foods Ltd |
| JBS S.A. |
| Tyson Foods Inc. |
| Danish Crown AmbA |
| Charoen Pokphand Group |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap processors across Vietnam's Red River Delta and Indonesia's Central Java clusters exercise pricing discipline through captive slaughter capacity, resisting margin erosion from commodity traders while Australia's pasture-based integrators leverage biosecurity-restricted supply routes to sustain premium positioning in Japanese retail channels.
Pricing Analysis
The bundled cold-chain-plus-certification service split separates Australian exporters commanding vacuum-packed chilled premiums from spot-market traders moving frozen commodity volumes through Bangkok and Singapore trading floors. Three-tier pricing structure across JAS-certified organic, standard chilled, and frozen economy levels stratifies buyer segments, with hotel chains in Ho Chi Minh City and Jakarta absorbing specification-driven premiums while wet market vendors in Philippine secondary cities remain acutely price-sensitive. Pricing pressure stems from feed input cost volatility compressing margin predictability for Southeast Asian poultry integrators locked into fixed-price food service contracts.
Supply Chain Analysis
Australia's domestic-content mandates for biosecurity-compliant processing reshape sourcing patterns, redirecting trade flows toward Queensland and New South Wales facilities equipped for controlled-atmosphere packaging exports. Geographic supply concentrates in Australian pasture systems, Indonesian Java-based clusters, and Vietnamese Red River Delta operations, with raw material dependencies tethered to soybean meal, corn, and veterinary health certificate processing timelines. Single-source vulnerability runs through Australia's Department of Agriculture export health certificate bottlenecks. Distribution feeds from integrated processors with captive cold storage networks directly into hotel procurement platforms, disintermediating traditional wholesale layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific edible meat market offers margin expansion through controlled-atmosphere packaging technology capturing premium-tier shifts in Japanese retail and professionalized food service procurement across Southeast Asian urban corridors.
For Market Incumbents: Deploy captive cold chain infrastructure as the defensive lever against digital tendering platforms disintermediating wholesale traders. WH Group and Charoen Pokphand Group should consolidate feed-to-farm networks across Henan and Central Java to absorb volume commitments from hotel chains professionalizing specifications. Biosecurity protocol stringency from Australia's Department of Agriculture threatens margin pools in fresh meat categories; redirect capacity toward vacuum-packed chilled formats qualifying for JAS organic certification premiums. For New Entrants and Emerging Players: Hyperspectral imaging automation for fat-content grading offers entry wedge into mid-scale Vietnamese and Thai processing facilities retrofitting existing lines. Philippine Visayas and Mindanao archipelago penetration presents the most penetrable white-space target, with underdeveloped last-mile refrigeration creating first-mover advantage for integrated operators building captive distribution. Go-to-market positioning should emphasize direct-to-hotel procurement platforms bypassing traditional wholesale markups. For Investors and Strategic Acquirers: Valuations sit cheapest among commodity-oriented processors facing China's SAMR updated GB standards compliance cost pressure. Long-term viability over the analysis window favors operators with backward integration into feed production and certification management capabilities. Acquisition target archetype: mid-scale Southeast Asian processors with latent cold chain assets and unexploited halal slaughter compliance for Middle Eastern export markets. The signal to watch is ASEAN harmonization talk progress on cross-border inspection protocol alignment accelerating inventory turns for Vietnamese exporters.| Strategic Initiative | Industry Significance |
|---|---|
| Cold Chain Infrastructure Expansion | Captive refrigeration networks in Indonesian archipelago bypass Java-centric supply constraints for premium chilled penetration. |
| Backward Integration into Feed Production | Control over soybean meal and corn inputs insulates Southeast Asian poultry integrators from commodity price volatility. |
| Halal Certification Compliance Investment | Segregated processing lines unlock Middle Eastern export markets for dual-standard Indonesian facilities. |
| Direct-to-Hotel Digital Platform Launch | Disintermediation of Bangkok and Singapore trading floors captures margin previously allocated to wholesale intermediaries. |
| JAS Organic Certification Pathway | Pasture-based Australian suppliers qualify for tightening Japanese import criteria commanding retail premium positioning. |
Study Parameters
Multiple input streams — executive interviews with protein procurement directors at international hotel chains, regulatory affairs specialists at Australia's Department of Agriculture, and plant managers across Vietnamese Red River Delta facilities, combined with trade data from ASEAN customs databases, MAFF import health certificate disclosures, and SAMR GB standard filings — were reconciled through bottom-up volume modeling and top-down value triangulation.
Data-stream reconciliation across the projection horizon applied segmented modeling across protein type, distribution channel, packaging technology, and customer sophistication tier, with CAGRs derived from trend extrapolation anchored in cold chain investment trajectories and food service procurement professionalization patterns. Industry-specific forecast inputs incorporated feed conversion ratio improvements in Indonesian broiler operations and controlled-atmosphere packaging adoption rates in Australian beef exports.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ASEAN harmonization implementation timelines, Australia's biosecurity protocol adjustments, and feed input commodity price cycles. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Middle East Red Meat Market
Meat Products
Hams Market
Meat Products
Chicken Buckets Market
Meat Products
Europe Poultry Meat Market
Meat Products
Low Fat Sausage Market
Meat Products
Animal Protein Market
Meat Products
Organic Beef Meat Market
Meat Products
Nitrate-Free Bacon Market
Meat Products
Middle East Edible Meat Market
Meat Products
Organic Pork Market
Meat Products
Bahrain Poultry Meat Market
Meat Products
Meat Paste Market
Meat Products
North America Canned Meat Market
Meat Products
Pork Flavors Market
Meat Products
United States Bacon Market
Meat Products
Mechanically Separated Meat Market