
 Organic Pork Market | 2026-2036
Organic Pork Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Pork Market Analysis
Precision livestock monitoring is narrowing the productivity gap between conventional and organic pork operations. Organic Prairie leverages its vertically integrated farm-to-retail network to control breed stock and feed grain sourcing across the Upper Midwest. Strauss Brands anchors its position through dedicated organic processing facilities that handle both fresh and value-added product lines. Becker Lane Organic differentiates by specializing in heritage breed programs that command premium positioning in specialty retail channels.
Organic pork denotes meat from hogs raised under certified organic protocols requiring 100% organic feed, outdoor access, and prohibition of antibiotics or synthetic growth promoters, with carcass specifications typically requiring lean percentages above 54% for premium grading. The product serves commercial foodservice and retail channels where traceability and animal welfare credentials influence procurement decisions. Fresh organic pork occupies the dominant volume position across supermarket and specialty store channels, while processed segments including sausages and cured items capture disproportionate margin pools due to brand differentiation and extended shelf life. Online retailers represent the fastest-growing distribution channel as direct-to-consumer platforms reduce intermediaries and enable subscription models for recurring household purchases.
USDA Organic certification governs feed standards and livestock handling practices in the United States, while the EU Green Deal and F-Gas Regulation shape methane reduction targets and cold chain requirements across European production zones. FDA oversight of veterinary drug residues intersects with organic protocol prohibitions, creating dual compliance obligations for processors serving both conventional and certified product lines. Stakeholders must monitor evolving feed cost structures and certification audit frequencies as determinants of sustainable margin architecture in organic pork supply chains.
Market Dynamics
The EU Green Deal's farm-to-fork sustainability targets are compressing feed sourcing timelines and forcing processors to reconfigure procurement networks around certified organic grain suppliers.
Growth Catalysts
- Antibiotic-free protein mandates:Restaurant operators across Germany, France, and Denmark are rewriting procurement specifications to exclude conventionally raised pork from premium menu tiers.
- EU Green Deal feed standards:The regulatory framework is accelerating investment in dedicated organic feed milling capacity and traceability infrastructure.
- Heritage breed premiums:Specialty retail channels in urban clusters are capturing margin expansion through differentiated breed provenance claims.
Market Restraints
- Organic feed cost volatility:Corn and soybean price swings in the Upper Midwest transmit directly to producer margins due to the 100% organic feed requirement.
- Processing concentration risk:Dedicated organic slaughter and fabrication capacity remains concentrated among three regional processor networks.
- Certification audit frequency:USDA Organic and EU organic protocols require annual on-site inspections that disrupt production scheduling.
Strategic Opportunities
- Direct-to-consumer subscription models:Online platforms are disintermediating traditional distributor relationships and capturing recurring household revenue streams.
- Cold chain digitization:Blockchain-enabled traceability systems are opening export pathways into Japanese and South Korean premium retail channels.
- Value-added processing capacity:Cured and fermented product lines offer margin insulation against fresh commodity price cycles.
Industry Challenges
- Veterinary skill scarcity:The prohibition on synthetic antibiotics demands specialized livestock health management expertise that conventional operations rarely possess.
- Dual-line compliance complexity:Processors handling both conventional and organic carcasses must maintain segregated equipment, staffing, and sanitation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Pork Market |
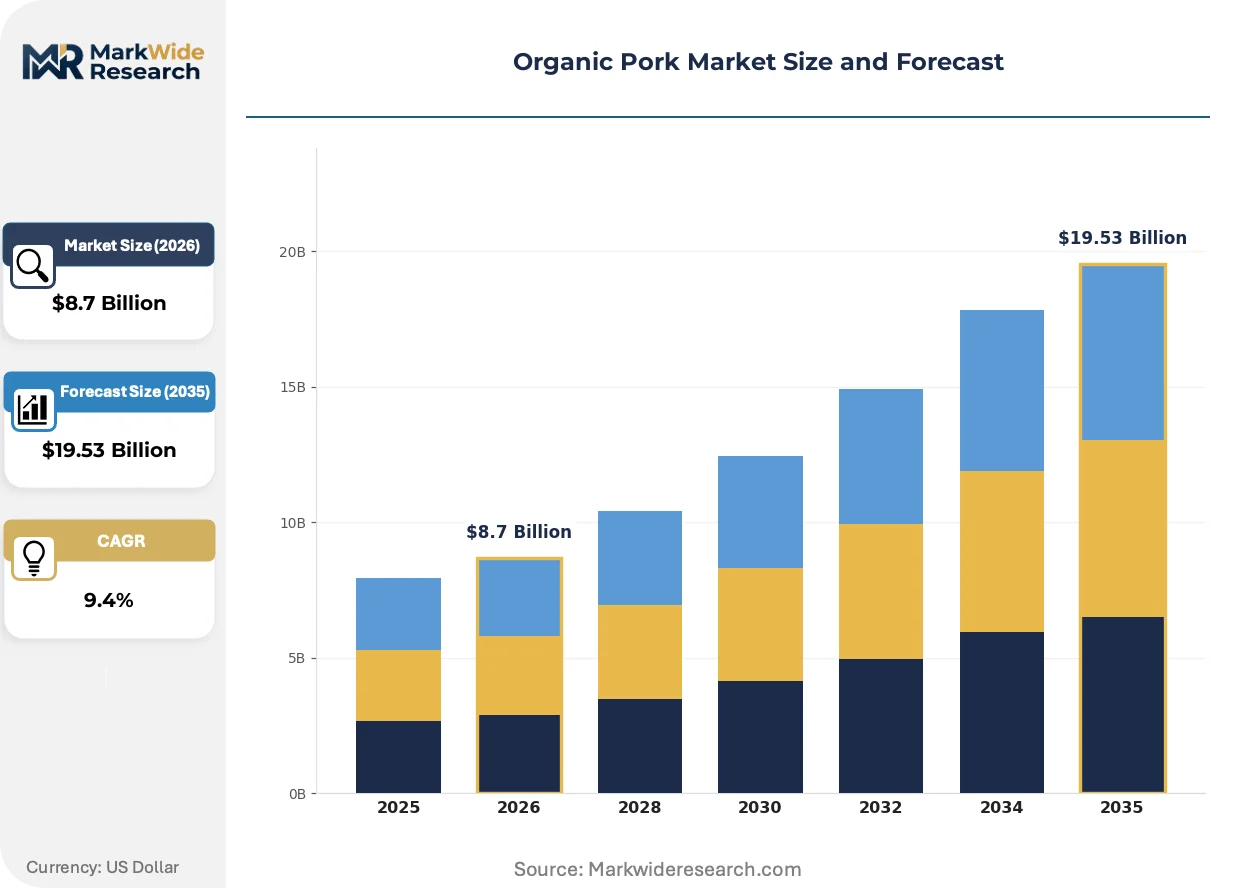
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh, Frozen, Processed, Cured Distribution Channel: Supermarkets, Online Retailers, Farmers' Markets, Specialty Stores Packaging Type: Vacuum Pack, Tray Pack, Loose, Canned End User: Restaurants, Households, Food Processing, Catering Services |
| Companies Covered | Organic Prairie, Becker Lane Organic, Good Earth Farms, Seven Sons Farms, Skagit River Ranch, Strauss Brands, Dalehead Foods, Longbush Free Range, Hoch Orchard & Gardens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Pork Market Emerging Trajectories
Precision agriculture technologies are penetrating livestock operations at accelerating rates, narrowing the productivity differential that has historically disadvantaged organic systems against conventional confinement models.
Sensor-based livestock monitoring systems are digitizing individual animal health tracking, feed conversion measurement, and environmental condition logging. Mid-scale organic operations in Iowa and Minnesota are deploying these platforms to compress mortality rates and improve finishing weights. The technology is digitizing record-keeping workflows that previously consumed substantial labor hours, enabling producers to scale head counts without proportional staff expansion.
REACH chemical restrictions and the EU F-Gas Regulation are tightening cold chain equipment specifications for organic pork storage and transport. Refrigeration system retrofits now dominate capital allocation discussions among European distributors. German retail chains are responding by consolidating organic volumes through dedicated distribution centers with upgraded ammonia-based cooling systems.
Buyer concentration in foodservice procurement is compressing supplier qualification timelines and demanding real-time traceability data. National restaurant groups in the United States are displacing traditional distributor relationships with direct contracting arrangements that specify breed, feed source, and processing facility. This pattern is most visible in the fast-casual segment, where chains use organic pork credentials to differentiate menu positioning against conventional competitors.
Organic Pork Market Segmentation
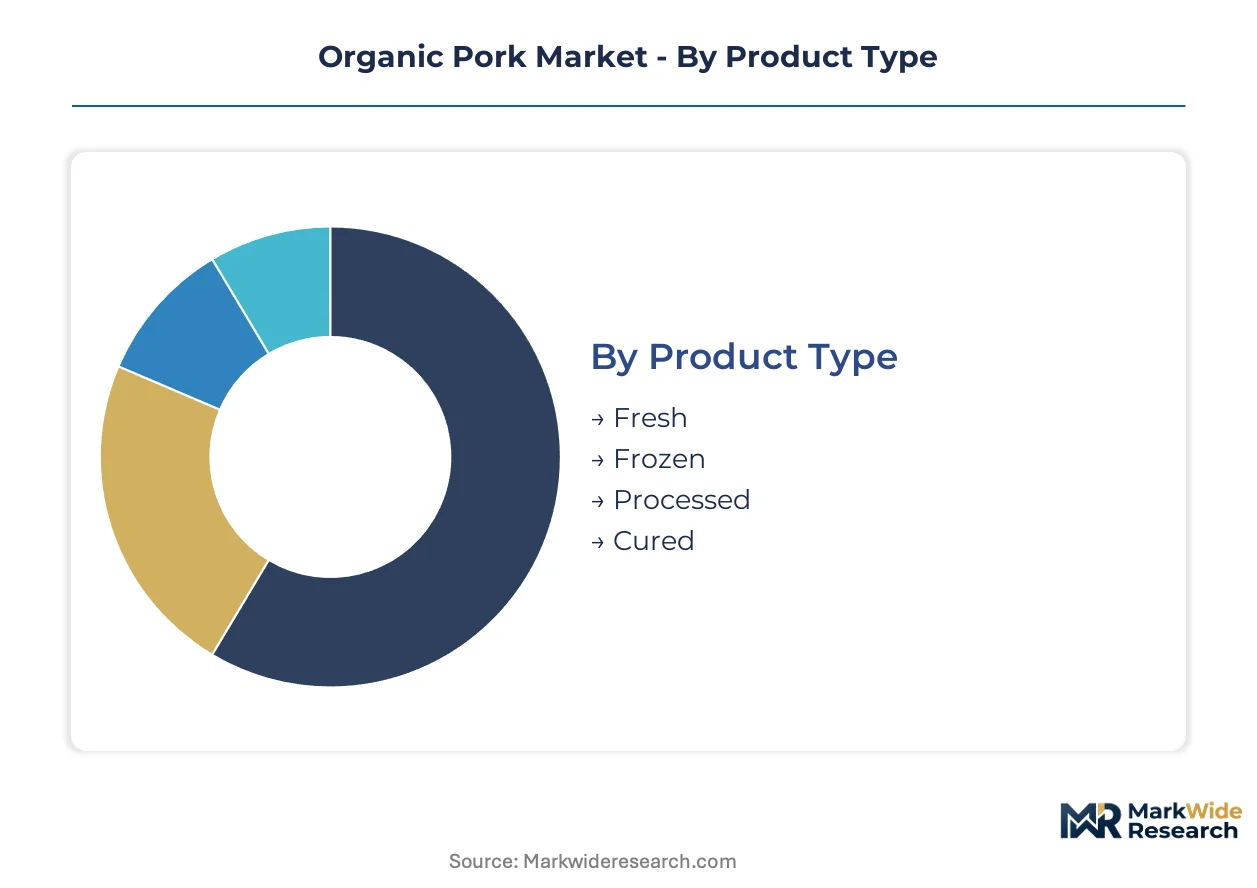
Segmentation in organic pork reveals how certification requirements and cold chain constraints reshape channel economics. Each dimension exposes distinct margin architectures and compliance burdens that determine supplier viability across retail and foodservice pathways.
Product Type:
Mature segments dominate volume flows while emerging formats capture premium positioning through extended shelf life and convenience attributes.
- Fresh:Chilled carcasses and primal cuts require continuous cold chain maintenance from slaughter through retail display. German supermarket chains have built dedicated organic meat sections around this segment, leveraging high turnover rates and traceability transparency to justify price premiums over conventional pork.
- Frozen:Blast-frozen primal and retail-cut formats enable inventory buffering against seasonal supply fluctuations and export logistics. Demand concentrates in foodservice procurement networks across Denmark and France, where operators value portion consistency and reduced waste against fresh delivery schedules.
- Processed:Ground pork and sausage formats absorb trim volumes and command formulation flexibility for spice and casing variations.
- Cured:Bacon, ham, and charcuterie products deliver extended shelf life and brand differentiation in specialty retail channels.
Fresh retains volume leadership; cured holds the steepest expansion curve.
Distribution Channel:
Cost tier stratification separates capital-intensive modern retail from low-overhead direct channels, with digital platforms disrupting traditional margin extraction.
- Supermarkets:Multi-outlet retail chains dominate procurement volumes through centralized distribution and dedicated organic meat sections. German retailers have invested in segregated processing infrastructure to prevent cross-contamination with conventional pork, satisfying EU organic protocol requirements for equipment separation.
- Online Retailers:Direct-to-consumer platforms eliminate distributor markups and enable subscription-based household replenishment models. Strauss Brands and Organic Prairie have built proprietary e-commerce capabilities to capture recurring revenue streams and customer data for demand forecasting.
- Farmers' Markets:Producer-direct sales capture maximum margin per unit but face scale constraints and seasonal availability limitations.
- Specialty Stores:Independent butchers and natural food retailers emphasize breed provenance and local sourcing credentials for urban consumer segments.
Supermarkets retain volume leadership; online retailers are climbing the fastest.
Packaging Type:
Application requirements drive format selection, with foodservice demanding portion control and retail prioritizing shelf appeal and extended display life.
- Vacuum Pack:Barrier film systems exclude oxygen to extend refrigerated shelf life and enable centralized processing for distant retail markets. Iowa and Minnesota organic processors have adopted vacuum packaging for export shipments to Japanese premium retail channels, where appearance consistency and leak-free performance determine qualification.
- Tray Pack:Modified atmosphere packaging with absorbent pads maintains color stability in retail display cases. French and Danish supermarket chains specify tray pack formats for fresh organic pork to match conventional meat department presentation standards and consumer handling expectations.
- Loose:Unpackaged whole carcasses and primal cuts serve foodservice fabrication and traditional butcher counter operations.
- Canned:Retort-processed shelf-stable formats target emergency preparedness and institutional procurement with minimal cold chain requirements.
Vacuum pack retains volume leadership; tray pack shows the steepest expansion trajectory.
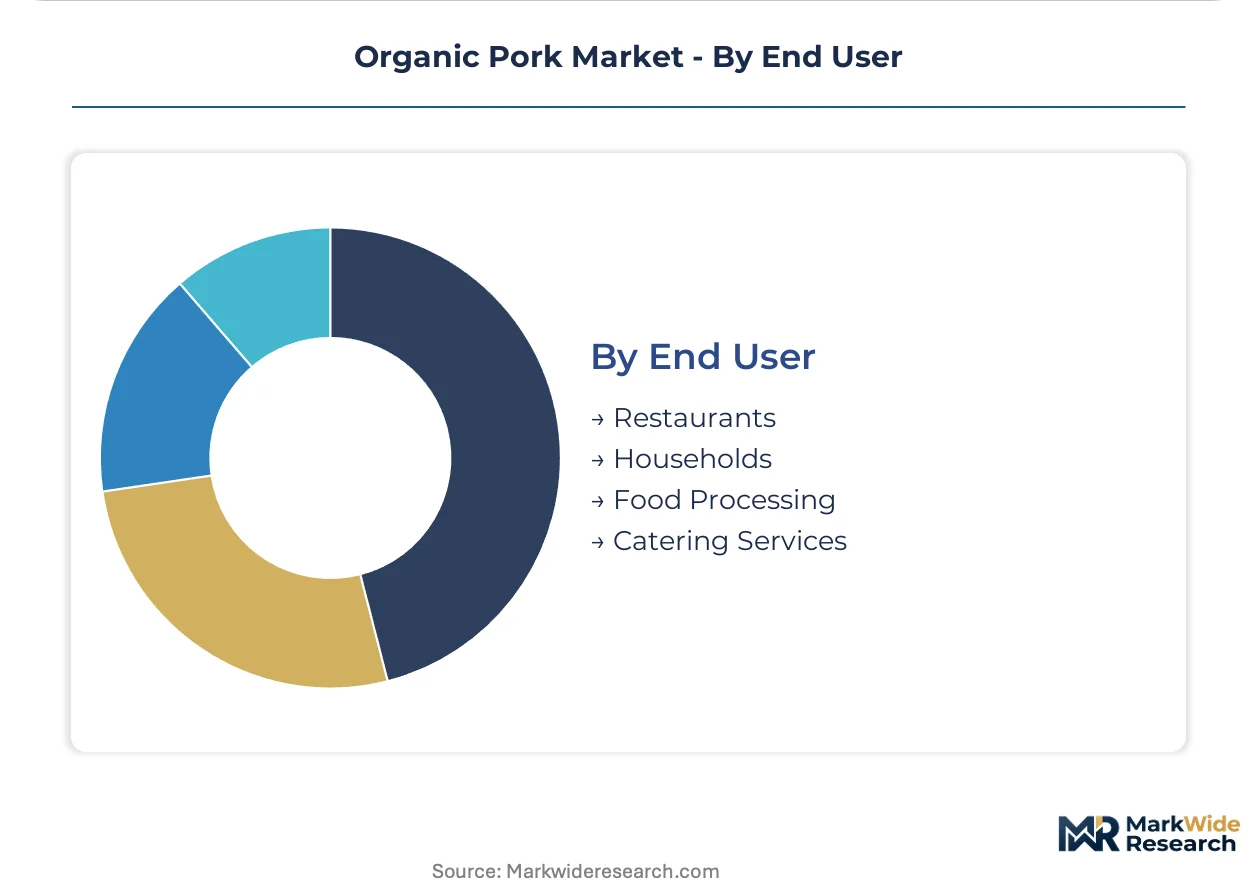
End User:
Customer type differentiation separates high-volume contract foodservice from fragmented household procurement, with traceability requirements intensifying across commercial segments.
- Restaurants:Fast-casual and fine-dining operators specify certified organic pork for menu differentiation and antibiotic-free protein claims. National restaurant groups in the United States have displaced traditional distributors with direct contracting arrangements that specify breed, feed source, and processing facility for supply security.
- Households:Individual consumers purchase through retail and online channels with subscription models gaining traction for recurring protein procurement. German households demonstrate the highest per-capita organic meat consumption in Europe, supported by dedicated retail sections and price transparency initiatives.
- Food Processing:Industrial buyers of organic pork ingredients for sausage, ready-meal, and ingredient manufacturing applications.
- Catering Services:Event and institutional foodservice operators with volume requirements and menu certification needs for corporate and public sector clients.
Restaurants retain volume leadership; households demonstrate the steepest demand expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German organic pork processors export chilled primal cuts to Japanese premium retail channels, establishing the dominant westbound trade corridor in certified antibiotic-free protein.
United States
Iowa and Minnesota hog finishers supply Strauss Brands and Organic Prairie with certified organic grain-fed animals for domestic foodservice contracts. USDA Organic protocols mandate 100% organic feed and outdoor access, creating compliance barriers for conventional converters. Chicago-area processing infrastructure anchors the Upper Midwest supply cluster, with dedicated organic slaughter lines preventing cross-contamination.
Germany
Retail chains Edeka and REWE have constructed segregated organic meat sections commanding premium shelf positioning across Bavaria and North Rhine-Westphalia. EU Green Deal farm-to-fork targets compress feed sourcing timelines, forcing processors to certify grain suppliers earlier in the production cycle. Berlin-Brandenburg distribution centers operate ammonia-based cooling systems meeting F-Gas Regulation specifications for cold chain integrity.
Denmark
Foodservice procurement networks source blast-frozen organic pork portions for portion-controlled menu applications in Copenhagen's fast-casual restaurant segment. Danish Veterinary and Food Administration residue testing intersects with EU organic protocol requirements, creating dual compliance checkpoints at slaughter facilities. Jutland Peninsula finishing operations concentrate heritage breed programs supplying specialty retail channels in urban clusters.
France
Supermarket chains Carrefour and Intermarché specify tray-pack fresh organic pork formats matching conventional meat department presentation standards. ANSM oversight of veterinary drug residues reinforces organic antibiotic prohibitions for export-bound production. Auvergne-Rhône-Alpes processing cooperatives have invested in modified atmosphere packaging lines serving domestic retail and Italian cross-border demand.
Japan
Premium retail channels in Tokyo and Osaka import vacuum-packed organic primal cuts from US and German suppliers, with appearance consistency determining vendor qualification. METI import standards for livestock products require documentation of feed source and processing facility registration. Kanto region cold storage operators have retrofitted ammonia refrigeration systems to meet domestic energy efficiency codes and organic handling protocols.
Organic Pork Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement networks where scale advantages concentrate in processing infrastructure. The vendor base separates into three strategic archetypes: vertically integrated farm-to-retail operators, dedicated organic processing specialists, and heritage breed program curators. Dominant competitive moves include backward integration into certified organic feed milling and geographic expansion through direct-to-consumer platform development.
Within the integrated operator tier, Organic Prairie and Strauss Brands exemplify channel-control strategies through captive supply networks and proprietary distribution infrastructure. Becker Lane Organic occupies a specialist position emphasizing breed differentiation for premium retail positioning. These three anchors represent distinct competitive vectors—scale integration, processing dedication, and genetic specialization—shaping procurement relationships with national restaurant groups and supermarket chains.
| Leading Market Players |
|---|
| Organic Prairie |
| Becker Lane Organic |
| Good Earth Farms |
| Seven Sons Farms |
| Skagit River Ranch |
| Strauss Brands |
| Dalehead Foods |
| Longbush Free Range |
| Hoch Orchard & Gardens |
| Others |
Supply Flow & Price Mechanics
Upper Midwest organic feed grain concentration in Iowa and Minnesota directly determines where margin pools accumulate across the organic pork value chain, with certified grain suppliers capturing disproportionate value relative to downstream processors.
Pricing Analysis
Certification-generation pricing gaps separate USDA Organic heritage breed premiums from conventional antibiotic-free tiers and emerging EU Green Deal compliant lines. Three-tier pricing structure across premium heritage, standard certified organic, and economy private-label levels dominates channel economics. Price differentiation hinges on breed provenance documentation and feed source traceability depth. Cost compression in standard certified tiers is intensifying because organic corn and soybean price volatility transmits directly to producer margins. Fast-casual restaurant groups demonstrate least price sensitivity due to menu positioning requirements, while institutional foodservice buyers exhibit highest elasticity.
Supply Chain Analysis
EU Green Deal feed certification restrictions and USDA Organic protocol requirements limit cross-border grain flows and shape procurement network architecture. Geographic supply concentration centers on the United States, Germany, and Denmark for finished organic pork, with feed grain sourcing anchored in the Upper Midwest and Black Sea regions. Raw material dependencies include certified organic corn, organic soybean meal, and heritage breed genetic stock. Single-source vulnerability runs through dedicated organic slaughter capacity concentrated among three regional processor networks. Distribution runs through segregated cold chain infrastructure preventing cross-contamination with conventional pork.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-enabled traceability platforms are reshaping organic pork into an interoperable data ecosystem where feed source verification and cold chain integrity credentials determine buyer access.
For Market Incumbents: Entrench control through captive certified organic feed milling capacity and proprietary direct-to-consumer subscription platforms. Strauss Brands and Organic Prairie have demonstrated that backward integration into breed stock programs insulates margin architecture against commodity price swings. The emergence of precision livestock monitoring startups threatens traditional record-keeping-based certification advantages. Priority investment in sensor-based health tracking and automated compliance documentation preserves audit efficiency against rising inspection frequency requirements. For New Entrants and Emerging Players: Establish a beachhead in direct-to-consumer subscription models for recurring household organic pork procurement. Online retail channels demonstrate lowest incumbent saturation and highest growth velocity across the analysis window. Target urban coastal markets in the United States and German metropolitan clusters where heritage breed premiums command maximum price realization. Go-to-market positioning should emphasize transparent feed source storytelling and breed provenance documentation rather than competing on commodity fresh pork pricing. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-scale organic processors lacking integrated feed sourcing or proprietary channel control. Long-term viability over a five-to-ten year horizon rests on certification moat durability and cold chain infrastructure ownership rather than volume scale alone. Acquisition targets should demonstrate either captive organic grain supply relationships or established direct contracting with national restaurant groups. Watch for EU Green Deal feed standard acceleration as the signal indicating margin compression for non-integrated processors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Organic Feed Milling | Captive grain supply insulates margin architecture against commodity price volatility in the Upper Midwest. |
| Direct-to-Consumer Subscription Platform Launch | Recurring revenue streams from German and US urban households reduce distributor dependency and improve demand forecasting. |
| Precision Livestock Monitoring Deployment | Sensor-based health tracking compresses mortality rates and digitizes USDA Organic audit documentation workflows. |
| Heritage Breed Program Expansion | Provenance differentiation commands premium positioning in specialty retail channels and fast-casual menu tiers. |
| Blockchain Cold Chain Traceability Implementation | Japanese METI import standards and EU F-Gas Regulation compliance open export pathways into premium retail channels. |
Methodological Framework
Cross-validation between processor procurement executives and certified organic feed suppliers anchors the qualitative findings in operational reality. Primary interviews with hog finishers, organic grain millers, supermarket category buyers, restaurant procurement directors, and cold chain logistics operators combined with secondary validation from USDA Organic certification databases, EU farm-to-fork policy filings, and customs trade records. Bottom-up volume modeling triangulates against top-down market sizing across product type, distribution channel, and regional regulatory clusters.
Calibration against historical price transmission patterns and certification audit frequency trends shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product format, packaging type, distribution channel, end-user category, and regional regulatory framework. CAGRs derive from elasticity-adjusted demand curves and supply-side capacity constraints. Industry-specific forecast inputs incorporate organic feed cost indices and restaurant procurement contract renewal cycles.
Macroeconomic conditions sit as an overlay; deviation in feed grain commodity prices or EU Green Deal implementation timelines would shift the trajectory. Forecasts reflect documented assumptions regarding certification protocol stability and cold chain infrastructure investment continuity. Material shifts in USDA Organic audit requirements or F-Gas Regulation enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
3D Printed Meat Market
Meat Products
Organic Beef Meat Market
Meat Products
Asia-Pacific Edible Meat Market
Meat Products
Reduced Fat Meat Market
Meat Products
Low-Fat Chorizo Market
Meat Products
Meat Mincers Market
Meat Products
Organic Halal Meat Market
Meat Products
Grass-Fed Meat Market
Meat Products
Rendered Poultry Products Market
Meat Products
Organic Meat Market
Meat Products
Canned Beef Market
Meat Products
Europe Processed Meat Market
Meat Products
Saudi Arabia Red Meat Market
Meat Products
Raw Chicken Feet Market
Meat Products
Global Duck Meats Market
Meat Products
Meat Paste Market