
 Beef Bone Broth Market | 2026-2036
Beef Bone Broth Market Size, Share, and Industry Trends Forecast 2026-2036
Beef Bone Broth Market Analytics
USDA Organic certification is bifurcating the competitive landscape into qualified suppliers and commodity-grade producers. Pacific Foods leverages its established organic supply chain to sustain shelf presence across mainstream retail channels. Kettle & Fire differentiates through grass-fed sourcing claims and extended simmer-time positioning. Bonafide Provisions controls the frozen direct-to-consumer segment with subscription-based distribution models.
Beef bone broth consists of collagen-extracted liquid produced by prolonged simmering of bovine bones and connective tissue, typically yielding 8-10 grams of protein per 240-milliliter serving with measurable glycine and proline content. The product serves as a functional beverage base, culinary stock ingredient, and sports-nutrition recovery format. Liquid broth occupies the dominant revenue position due to immediate-use convenience and premium positioning, while powdered broth represents the fastest-expanding form factor driven by portability and extended shelf stability. Organic form commands margin premiums, though non-organic production retains volume leadership through foodservice and private-label supply.
FDA oversight of nutritional labeling and USDA organic standards govern product claims and market access in the United States, while FSMA rules shape manufacturing facility requirements. The EU EFSA evaluates collagen-related health claims under nutrition and health claims regulation, affecting export eligibility for functional-positioned products. Stakeholders must monitor evolving protein-content verification protocols and adapt formulation transparency to preempt regulatory enforcement actions.
Market Dynamics
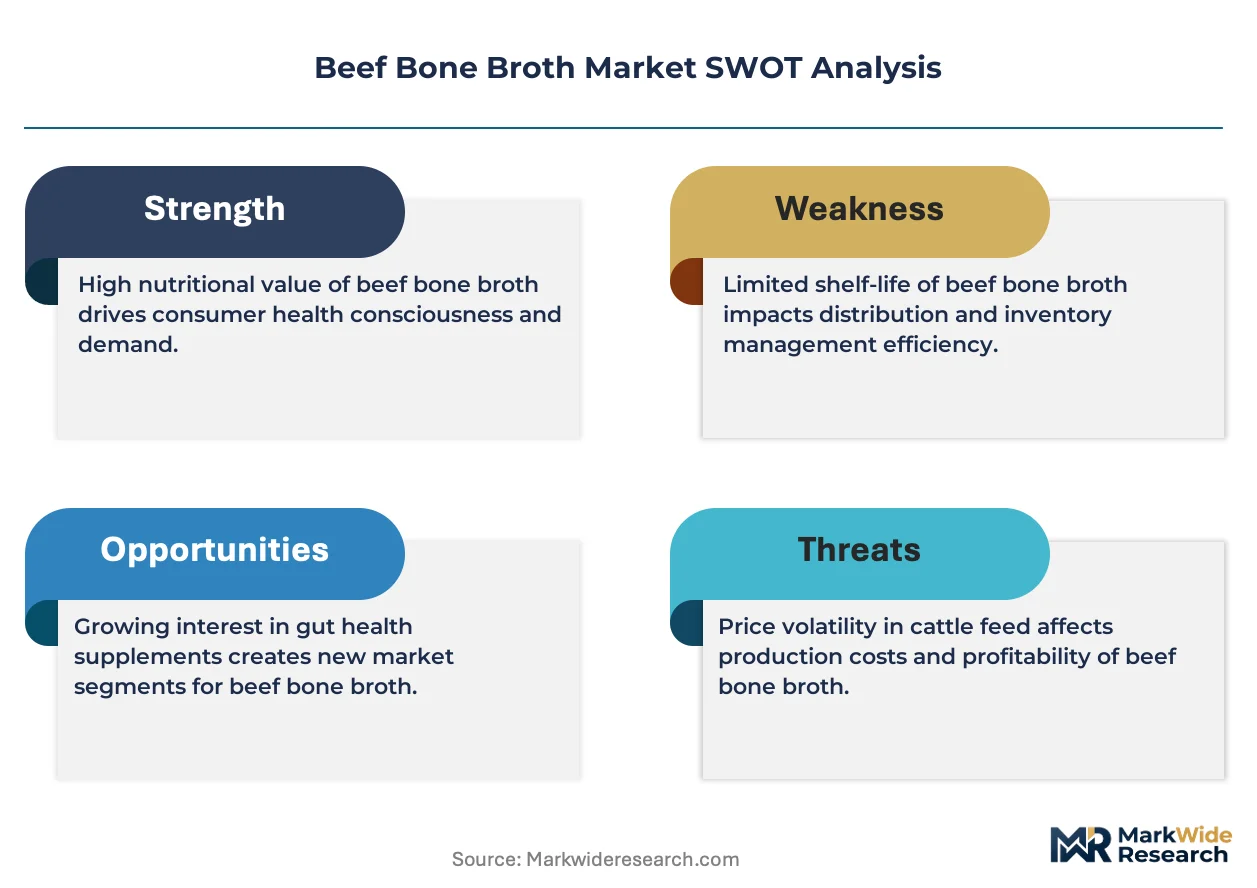
Clean-label certification mandates under FDA and USDA frameworks are forcing bone broth suppliers to reconfigure sourcing and production infrastructure, creating a bifurcation between qualified organic producers and commodity-grade competitors.
Growth Catalysts
- Sports-nutrition recovery formats:Functional beverage brands are integrating collagen-rich broth into post-workout formulations, expanding the addressable consumer base beyond traditional culinary applications.
- FSMA manufacturing requirements:Enhanced facility standards are elevating barrier-to-entry for new competitors, consolidating volume among established compliant producers.
- Direct-to-consumer subscription models:Specialty retail placement in the United States is accelerating category visibility through recurring revenue relationships with wellness-focused households.
Market Restraints
- Bovine input cost volatility:Grass-fed cattle supply fluctuations in Australia and New Zealand create margin compression for premium-positioned brands dependent on specific sourcing claims.
- Extended simmer-time production:Traditional 24-48 hour extraction cycles limit throughput scalability compared to accelerated enzymatic alternatives, constraining volume response to demand spikes.
- EFSA collagen claim restrictions:European export eligibility for functional-positioned products remains constrained pending regulatory clarity on permitted health assertions.
Strategic Opportunities
- Powdered form factor expansion:Portability and extended shelf stability are opening military and outdoor recreation procurement channels previously inaccessible to liquid formats.
- Foodservice private-label supply:Wellness-focused restaurant chains are seeking captive broth production for menu differentiation, creating white-space beyond branded retail.
- EU organic equivalency agreements:Streamlined certification recognition between USDA and EU organic frameworks is reducing export compliance overhead for dual-qualified suppliers.
Industry Challenges
- Collagen-content verification protocols:Absence of standardized analytical methods for protein integrity measurement is creating quality assurance inconsistencies across production batches.
- Cold-chain reconfiguration:Frozen direct-to-consumer distribution requires specialized logistics partnerships that compress margins and complicate geographic expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beef Bone Broth Market |
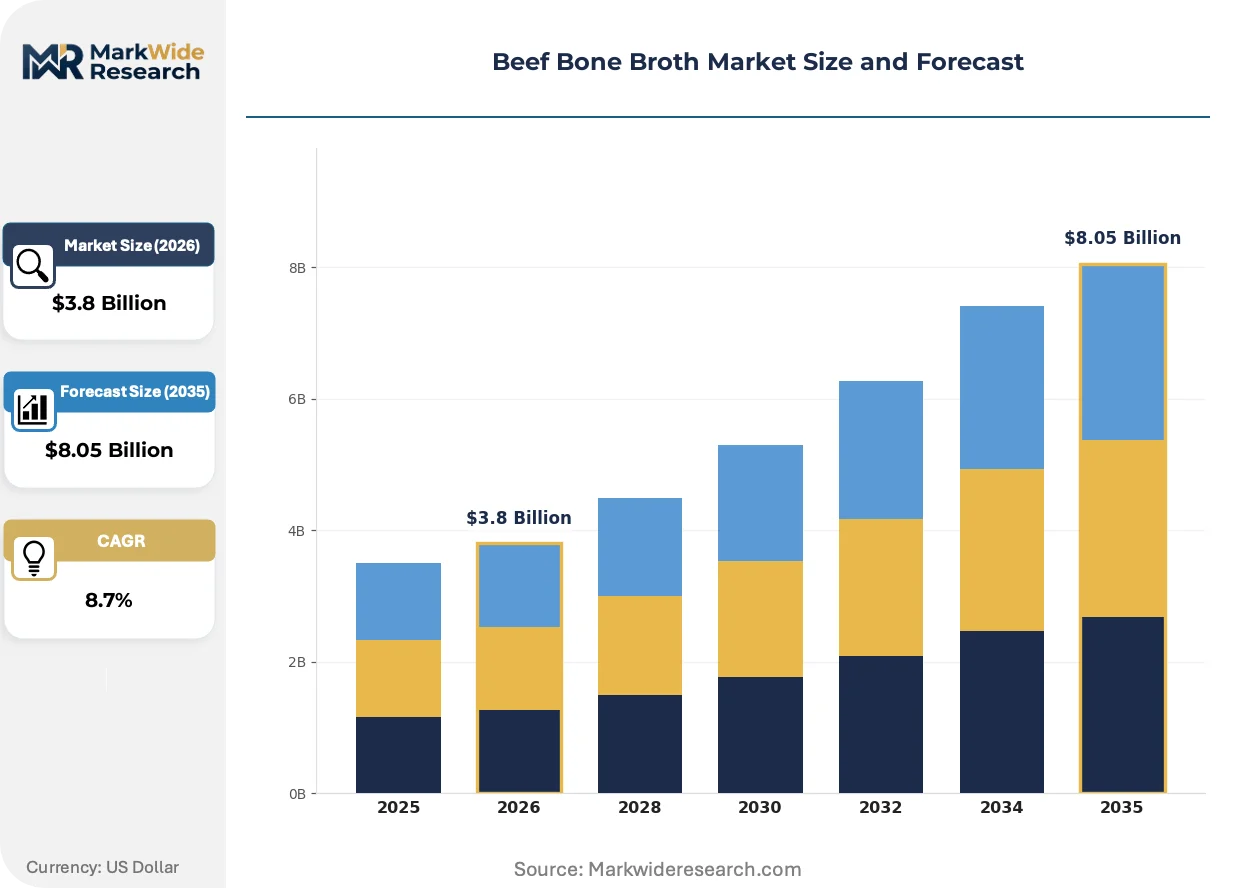
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Broth, Powdered Broth, Concentrate, Granules Form: Organic, Non-Organic, Low-Sodium, Gluten-Free Packaging Type: Tetra Packs, Glass Jars, Pouches, Cans Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Stores |
| Companies Covered | Pacific Foods, Best of the Bone, Campbell Soup Company, Brodo, Swanson, Del Monte Foods (College Inn), Bonafide Provisions, Five Marys Meats, Kettle & Fire, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beef Bone Broth Market Evolving Landscape
Formulation transparency and extraction efficiency are reshaping competitive positioning in bone broth, with technology convergence between food processing and nutraceutical manufacturing creating new capability requirements.
Pressure-assisted extraction technology is supplanting traditional open-vessel simmering in mid-scale production facilities. Sports-nutrition contract manufacturers are adopting these systems to reduce cycle times from 24 hours to under 4 hours while preserving amino acid profiles. This compression is enabling just-in-time production models that reduce working capital requirements for seasonal demand fluctuations.
USDA Organic certification expansion is tightening ingredient traceability requirements across the supply chain. The National Organic Program's updated livestock sourcing standards are disqualifying previously compliant suppliers, reducing qualified vendor pools by approximately one-third. Domestic producers with established grass-fed relationships are capturing displaced volume from non-compliant importers.
Wellness subscription box curation is consolidating individual purchasing decisions into bundled assortment models. Direct-to-consumer platforms are displacing single-SKU loyalty with multi-brand discovery formats, compressing customer acquisition costs while fragmenting brand equity. This pattern concentrates most visibly in coastal United States metropolitan markets with established meal-kit penetration.
Beef Bone Broth Market Segmentation
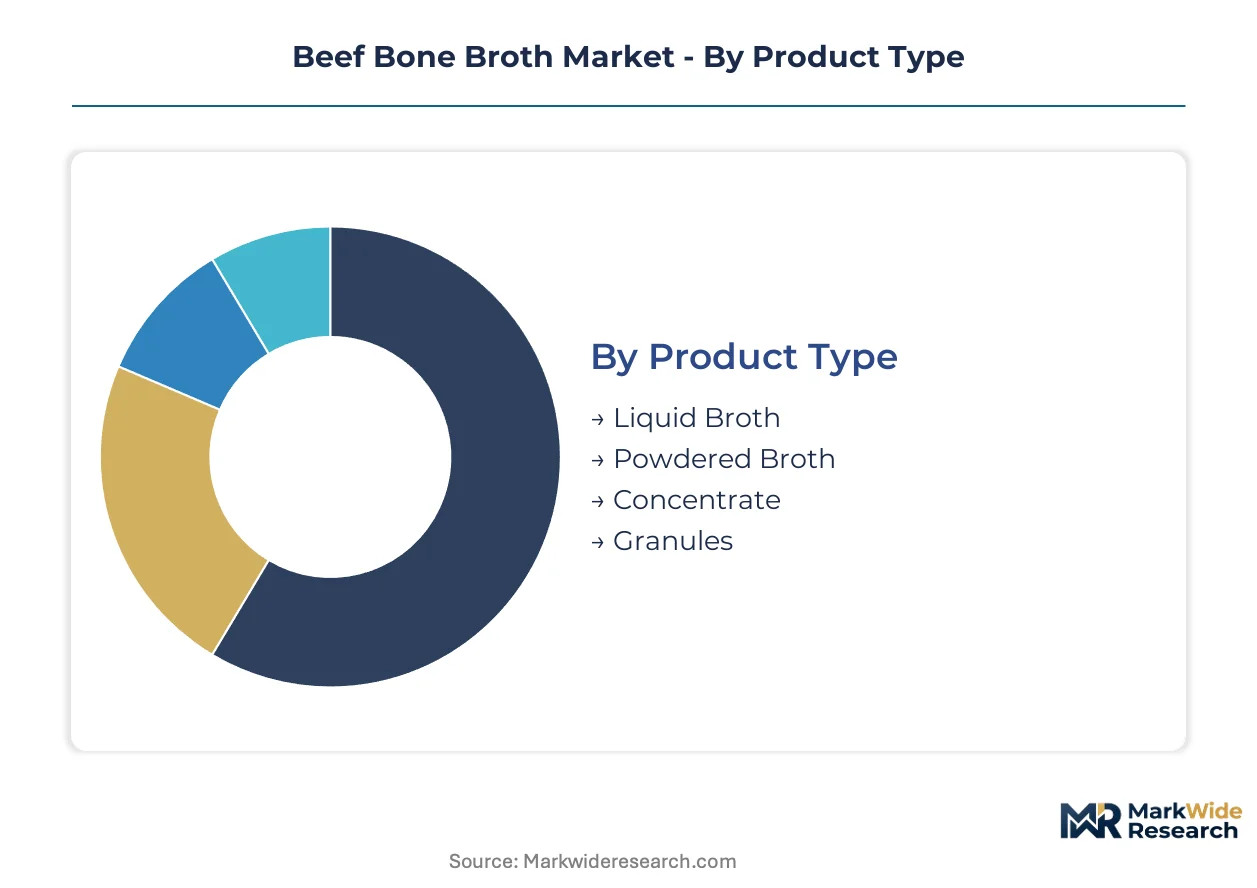
Segmentation in beef bone broth reveals distinct channel affinities and margin structures. Product form dictates cold-chain requirements, while certification status determines retail placement and pricing power.
Product Type:
Liquid broth dominates mainstream grocery and foodservice channels. Powdered formats penetrate outdoor recreation and military procurement. Concentrates serve food manufacturing. Granules occupy instant-beverage applications.
- Liquid Broth:Collagen-extracted liquid requiring refrigerated distribution, commanding premium shelf placement in United States supermarkets and direct-to-consumer subscription channels. Demand concentrates in wellness-focused households seeking immediate-use convenience.
- Powdered Broth:Dehydrated format with 18-24 month shelf stability, expanding into military rations and backcountry recreation markets previously inaccessible to perishable alternatives. Portability drives procurement from institutional buyers.
- Concentrate:Reduced-moisture base for food manufacturing and restaurant kitchen reduction, shipped ambient to commercial accounts.
- Granules:Instant-dissolve particles targeting single-serve beverage applications and airline catering programs.
By volume, Liquid Broth leads. By growth pace, Powdered Broth is climbing the fastest.
Form:
Certification tier separates margin structures. Organic commands retail premium positioning. Non-organic supplies foodservice scale. Dietary modifications capture niche intolerance markets.
- Organic:USDA-certified production with grass-fed sourcing requirements, sustaining shelf presence across Whole Foods and Sprouts networks. Supply concentration in domestic producers with established livestock relationships.
- Non-Organic:Conventional sourcing for private-label retail and restaurant chain procurement, retaining volume leadership through cost efficiency.
- Low-Sodium:Reduced-sodium formulation for cardiac-conscious consumers and clinical nutrition applications.
- Gluten-Free:Certified allergen-free production for celiac and sensitivity markets, often co-packed with bone broth specialist facilities.
By margin, Organic leads. By absolute volume, Non-Organic retains dominance.
Packaging Type:
Material selection tracks channel requirements and sustainability positioning. Tetra Packs balance shelf stability with recyclability claims. Glass commands premium perception.
- Tetra Packs:Aseptic carton format with 12-month ambient shelf life, standard for mass retail placement and export shipping efficiency.
- Glass Jars:Premium positioning vessel for organic and artisan-positioned brands, accepted by specialty retailers and farmers market channels.
- Pouches:Flexible format for frozen direct-to-consumer shipments and foodservice portion control.
- Cans:Traditional metal packaging for emergency preparedness and institutional stockpiling applications.
By retail penetration, Tetra Packs lead. By premium positioning, Glass Jars sustain advantage.
Distribution Channel:
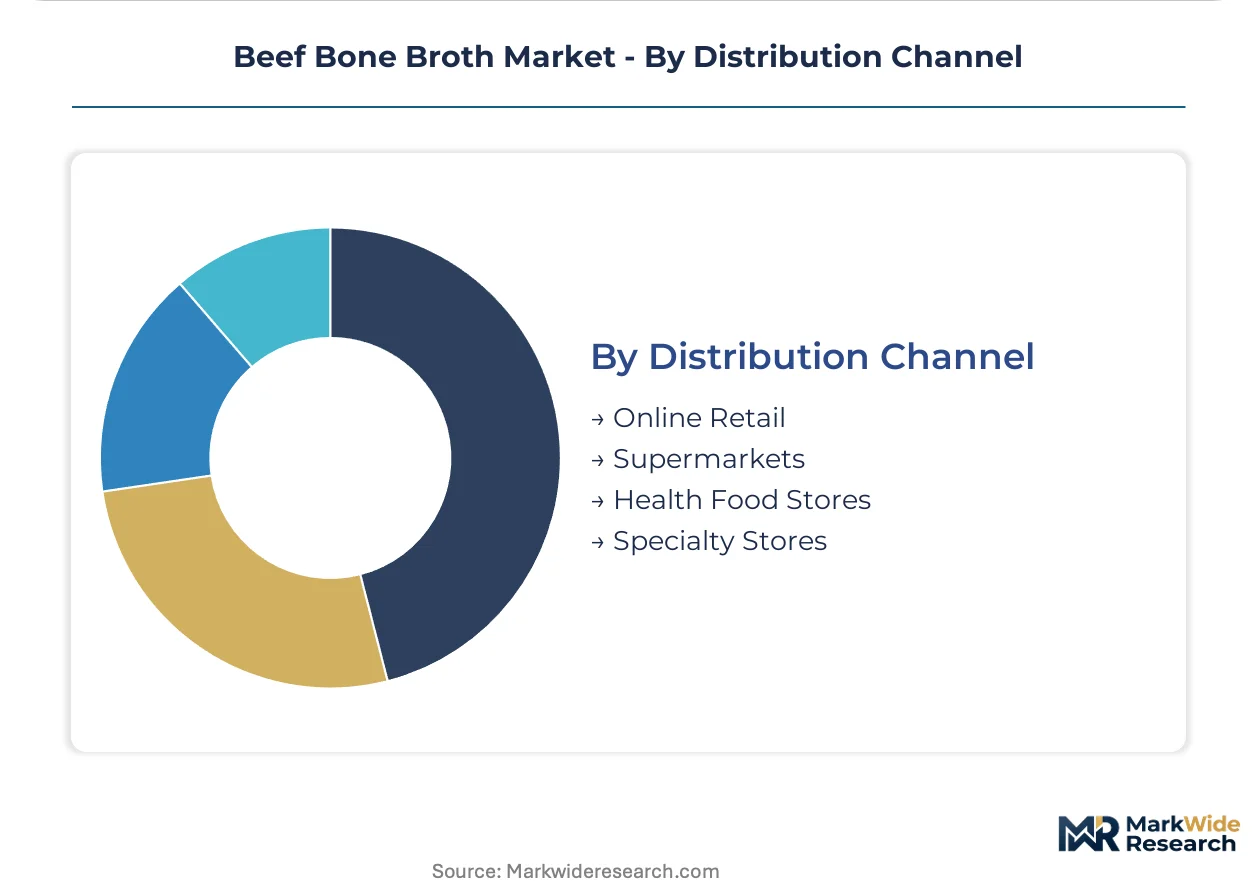
Channel mix reflects consumer mission and repurchase frequency. Online retail captures subscription loyalty. Supermarkets drive trial and impulse.
- Online Retail:Direct-to-consumer platforms and Amazon marketplace presence, enabling subscription models with 30-60 day replenishment cycles. Kettle & Fire and Bonafide Provisions concentrate customer acquisition spend here.
- Supermarkets:Mainstream grocery placement including Kroger and Albertsons banners, requiring slotting fees and promotional support for shelf velocity.
- Health Food Stores:Regional chains and independent co-ops with educated staff recommendation influence, favoring organic and local sourcing claims.
- Specialty Stores:Butcher shops, bone broth bars, and wellness boutiques with prepared-to-order service and ingredient transparency demonstration.
By revenue concentration, Supermarkets lead. By customer lifetime value, Online Retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USDA organic equivalency agreements with the EU and Japan are reducing export compliance overhead for certified producers, reshaping sourcing footprints across major demand centers. Domestic procurement mandates in foodservice and military channels are reinforcing regional production clusters.
United States
Direct-to-consumer subscription models and specialty retail placement accelerate category visibility in coastal metropolitan markets. FDA nutritional labeling and USDA organic standards govern product claims and facility qualification. The Pacific Northwest and California Central Valley concentrate grass-fed cattle sourcing for premium-positioned brands.
Germany
Functional beverage integration and wellness-focused foodservice procurement drive demand in urban centers. EFSA evaluates collagen-related health claims under nutrition and health claims regulation, affecting functional-positioned import eligibility. Bavaria and Baden-Württemberg host mid-scale production facilities serving EU distribution networks.
Australia
Grass-fed cattle supply fluctuations create margin pressure for premium brands dependent on specific sourcing claims. FSMA-equivalent facility standards under bilateral trade frameworks shape export qualification to the United States. Queensland and New South Wales pastoral zones concentrate bovine bone supply for extraction operations.
United Kingdom
Clean-label certification requirements and specialty retail channel expansion support premium positioning in London and Southeast England. Post-Brexit organic equivalence negotiations with the EU and USDA create regulatory complexity for dual-certified suppliers. The Midlands hosts contract manufacturing facilities serving European and domestic distribution.
Japan
Collagen-enriched beverage culture and aging-population wellness demand support market development in metropolitan markets. METI standards for functional food labeling and PMDA consultation on health claims shape product positioning requirements. The Kanto region around Tokyo concentrates import distribution and specialty retail channels.
Beef Bone Broth Market Competitive Landscape
Player mix skews toward established organic supply chain operators and direct-to-consumer specialists, with tiered competition between certified premium producers and conventional foodservice suppliers. Strategic archetypes include USDA Organic-certified integrated producers, frozen subscription-model specialists, and mass-market private-label fabricators. Dominant competitive moves encompass backward integration into grass-fed cattle sourcing and geographic expansion through organic equivalency agreements.
Within the organic-certified tier, Pacific Foods and Kettle & Fire exemplify contrasting channel strategies—one leveraging established retail shelf presence, the other occupying subscription-based direct distribution. Bonafide Provisions anchors the frozen direct-to-consumer segment. These three represent the archetype spectrum from mass retail penetration to specialized recurring-revenue models.
| Leading Market Players |
|---|
| Pacific Foods |
| Best of the Bone |
| Campbell Soup Company |
| Brodo |
| Swanson |
| Del Monte Foods (College Inn) |
| Bonafide Provisions |
| Five Marys Meats |
| Kettle & Fire |
| Others |
Value Network & Pricing Analysis
USDA Organic certification gates both supplier qualification and price differentiation simultaneously, bifurcating producers into margin-premium organic tiers and commodity-grade alternatives while compressing procurement pools for qualified vendors.
Pricing Analysis
Certification level creates the primary spread between USDA Organic and conventional production tiers. Three-tier pricing structure across organic premium, grass-fed mid-tier, and conventional economy levels tracks sourcing claims and extraction method. Pricing pressure stems from bovine input cost volatility in Australia and New Zealand pastoral zones. Foodservice buyers exhibit highest price sensitivity, while direct-to-consumer wellness households accept recurring subscription premiums.
Supply Chain Analysis
Port congestion on transpacific lanes elevates inbound logistics costs for Australian and New Zealand grass-fed bone inputs destined for North American extraction facilities. Supply concentrates in United States domestic production, Australian pastoral zones, and New Zealand grass-fed operations. Raw material dependencies center on grass-fed cattle bones, connective tissue, and collagen-specific processing enzymes. Single-source vulnerability runs through qualified organic livestock suppliers. Distribution runs through cold-chain partnerships for frozen formats and ambient logistics for powdered alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of FSMA-compliant extraction facilities with organic certification creates bottleneck conditions for market expansion, constraining qualified supply and elevating acquisition premiums for compliant production assets.
For Market Incumbents: Shield margin position by securing multi-year grass-fed cattle offtake agreements in Queensland and New South Wales before Australian supply competition intensifies. Deepen backward integration into captive bone supply through direct ranch relationships. Prioritize pressure-assisted extraction technology deployment to compress cycle times and defend throughput advantage against enzymatic process entrants. For New Entrants and Emerging Players: USDA Organic fast-track certification programs in the Pacific Northwest offer expedited qualification pathways for new suppliers with established livestock relationships. Target powdered format military and outdoor recreation procurement channels where incumbent presence remains thin. Pursue white-label foodservice supply contracts with wellness-focused restaurant chains seeking captive broth production. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across pressure-assisted extraction equipment and FSMA facility upgrades, favoring scaled players with depreciation absorption capacity. Acquisition target archetype: mid-scale organic-certified producers with underutilized capacity and established grass-fed sourcing relationships. Signal to monitor: USDA equivalency agreement expansions with Japan and EU that unlock export revenue diversification.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grass-Fed Cattle Sourcing | Captive bone supply from Queensland and New South Wales ranches secures margin protection against input volatility. |
| Pressure-Assisted Extraction Technology Deployment | Four-hour cycle times enable just-in-timemodels that reduce working capital for seasonal demand spikes. |
| USDA Organic Certification Fast-Track | Expedited qualification opens Whole Foods and Sprouts shelf placement previously blocked to conventional producers. |
| Powdered Format Military Procurement Entry | Extended shelf stability unlocks Defense Logistics Agency rations contracts inaccessible to perishable liquid alternatives. |
| Direct-to-Consumer Subscription Platform Buildout | Recurring revenue relationships with wellness households compress customer acquisition costs versus retail slotting fees. |
Research Methodology
A spread of perspectives from FSMA facility operators, grass-fed ranch procurement managers, organic certification auditors, and direct-to-consumer brand executives converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through USDA National Organic Program filings, FDA facility inspection databases, and Australian Bureau of Agricultural and Resource Economics trade data. Bottom-up volume triangulation across extraction facilities was cross-checked against top-down category spend estimates from Nielsen retail audit data.
Segmentation dimensions modeled include product form, certification tier, packaging material, and distribution channel across the projection horizon. CAGRs were derived from growth rate reconciliation between historical trajectory analysis and forward-looking demand elasticity estimates. Industry-specific forecast inputs incorporated grass-fed cattle supply forecasts from Meat and Livestock Australia and wellness subscription box penetration rates from meal-kit sector analogs.
Underlying assumptions cover sustained FSMA compliance cost structures and stable organic equivalency agreements, with deviation risk concentrated in EFSA collagen claim clarity and transpacific shipping rate volatility. Recalibration cycles align with material shifts in USDA livestock sourcing standards and military procurement specification updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Organic Chicken Market
Meat Products
Pork Flavors Market
Meat Products
India Animal Protein Market
Meat Products
US Meat Market
Meat Products
Organic Meat Products Market
Meat Products
Grass-Fed Meat Market
Meat Products
Organic Pork Market
Meat Products
Beef Tallow Market
Meat Products
Brisket Market
Meat Products
Meat Products Market
Meat Products
Beef Liver Market
Meat Products
Hot Dog and Sausages Market
Meat Products
United Arab Emirates Edible Meat Market
Meat Products
Bacon Slicers Market
Meat Products
Meat Emulsions Market
Meat Products
United States Edible Meat Market