
 United States Processed Pork Meat Market | 2026-2036
United States Processed Pork Meat Market Size, Share, and Industry Trends Forecast 2026-2036
United States Processed Pork Meat Market Analytics
Midwestern packing plant capacity is rebalancing as regional processors modernize aging facilities and expand cold-chain infrastructure. Smithfield Foods leverages vertical integration from farm to retail case, sustaining margin capture across fresh and value-added lines. Tyson Foods anchors its position through broad protein portfolio breadth, while Hormel Foods differentiates via branded specialty categories and direct-to-retail channel control.
Processed pork meat encompasses cured, smoked, fermented, or cooked pork products manufactured through thermal processing, brine injection, or dry-curing methods, with sodium content, water activity, and pH serving as critical safety and shelf-life parameters. The category serves retail grocery, foodservice preparation, and institutional feeding applications where consistency, portion control, and extended distribution windows carry commercial weight. Sausages and bacon occupy mature volume positions with established household penetration, while portion packs and vacuum-sealed formats capture expanding demand from smaller households and convenience-oriented retail channels. Foodservice and wholesale distribution channels concentrate margin pools through contract volume commitments and specialized product specifications.
USDA FSIS inspection protocols, HACCP compliance mandates, and FDA nutrition labeling requirements govern product safety, pathogen reduction, and consumer transparency across the category. These frameworks elevate capital requirements for new market entry and accelerate consolidation toward plants with validated process control systems. Stakeholders must monitor evolving sodium reduction guidance and alternative protein labeling disputes that could reshape competitive positioning in prepared meat cases.
Market Dynamics
USDA FSIS inspection mandates and sodium reduction guidance are compressing formulation flexibility while concentrating processing capacity among plants with validated HACCP systems and automated pathogen detection infrastructure.
Growth Catalysts
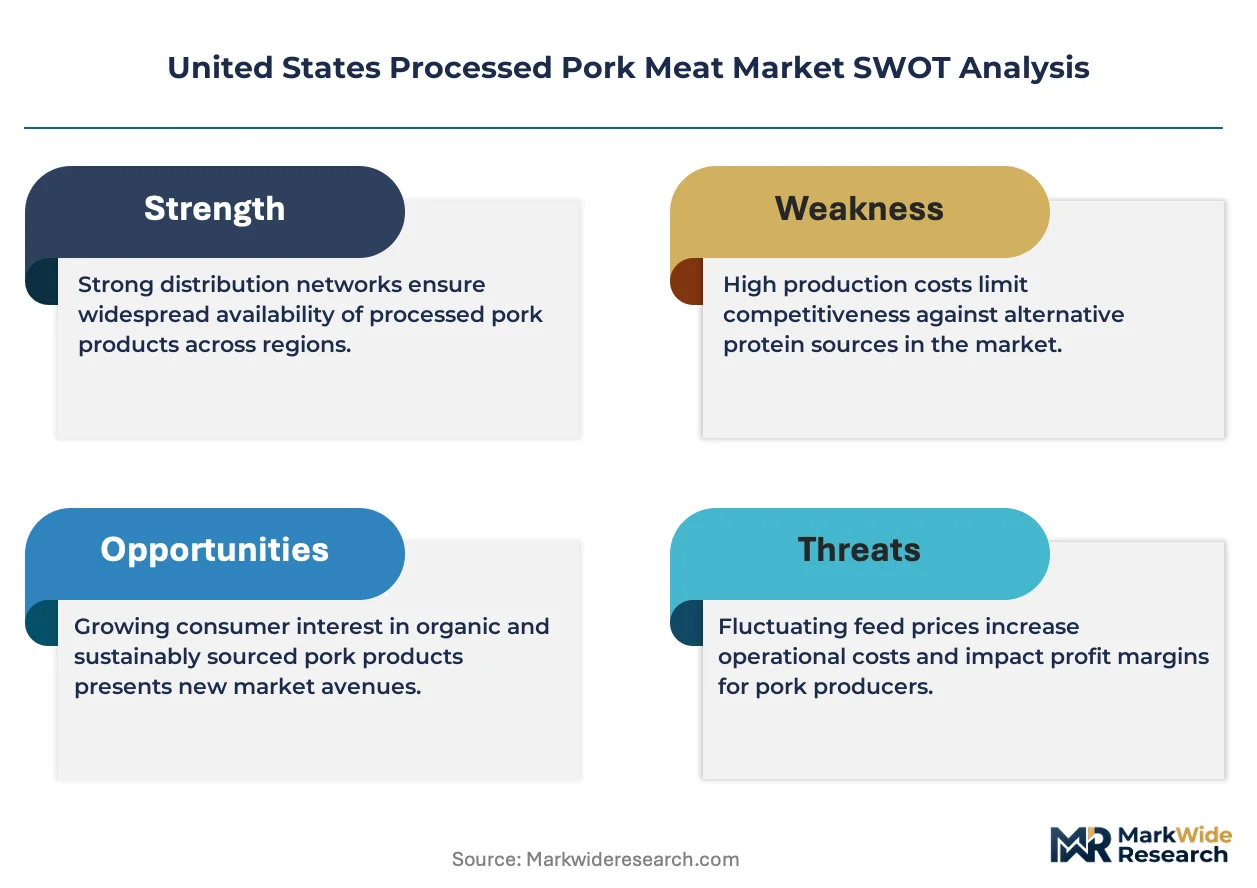
- Foodservice menu expansion:QSR chains and casual dining operators are widening bacon and cured ham applications across breakfast, sandwich, and bowl formats.
- FSMA traceability mandates:FDA record-keeping rules for high-risk foods are rewarding processors with integrated farm-to-plant data systems.
- Midwestern cold-chain investment:Iowa, Illinois, and Minnesota are adding blast-freezing and automated storage capacity to reduce distribution bottlenecks.
Market Restraints
- Feed cost volatility:Corn and soybean meal price swings compress packer margins and limit forward-contracting flexibility for independent producers.
- Plant concentration risk:Iowa and Minnesota house disproportionate slaughter capacity, creating regional disruption exposure from weather or disease events.
- Plant-based substitution:Pea and mycoprotein analogs are capturing shelf space in retail prepared meat cases and flexitarian household baskets.
Strategic Opportunities
- Smaller household formats:Vacuum-sealed portion packs and resealable bacon packs address two-person and single-person household growth.
- USDA BioPreferred procurement:Federal foodservice contracts with biobased purchasing preferences open institutional channels for domestically processed products.
- Clean-label fermentation:Natural curing cultures and celery powder alternatives are enabling nitrite-free positioning in premium retail tiers.
Industry Challenges
- FSIS label approval timelines:USDA review queues for new product claims and nutritional statements extend launch windows by four to eight months.
- Legacy equipment retrofit costs:Aging Midwestern plants face capital-intensive upgrades to meet updated Salmonella performance standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Processed Pork Meat Market |
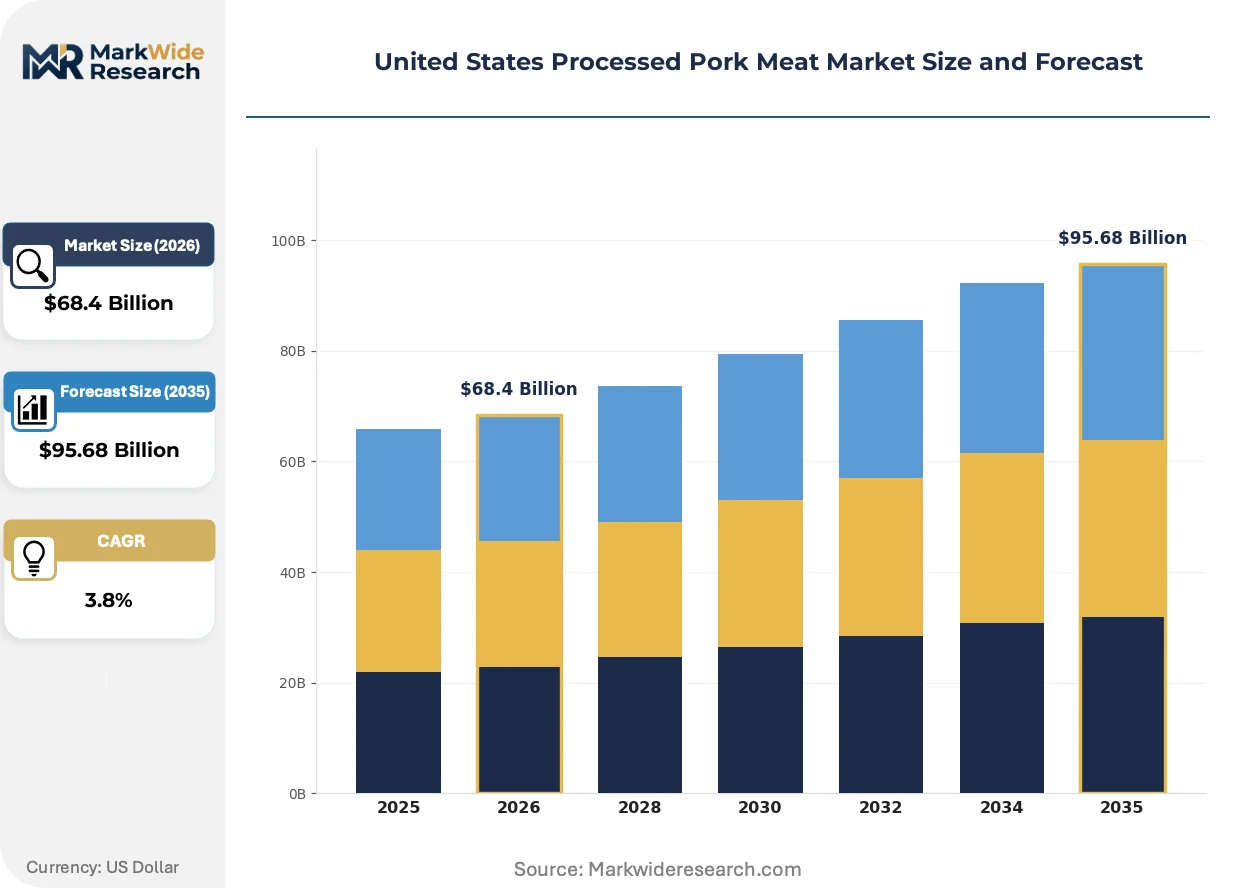
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $95.68 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sausages, Bacon, Ham, Hot Dogs Packaging Type: Vacuum Packs, Canned, Tray Packs, Portion Packs Distribution Channel: Retail, Foodservice, Online, Wholesale End User: Households, Restaurants, Cafes, Catering Services |
| Companies Covered | Smithfield Foods, Inc., Tyson Foods, Inc., Hormel Foods Corporation, JBS USA Holdings, Inc., Seaboard Foods LLC, Clemens Food Group, OSI Group, LLC, Conagra Brands, Inc., Cargill, Incorporated, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Processed Pork Meat Market Evolving Landscape
Automation, regulatory transparency mandates, and shifting household structures are compressing traditional processing models while opening specialty and convenience-positioned niches.
High-pressure processing is consolidating shelf-life extension capabilities among mid-scale processors seeking clean-label pathogen control without thermal degradation. Regional co-packers in Illinois and Minnesota are adopting HPP units to serve branded retail clients demanding sixty-plus-day refrigerated codes. This technology is consolidating competitive position for plants that can justify capital deployment against commodity margin pressure.
FDA updated sodium guidance and USDA FSIS front-of-pack labeling proposals are forcing reformulation investments across bacon, ham, and sausage lines. Processors are responding with potassium chloride blends, yeast extracts, and reduced-water-activity formulations that maintain sensory thresholds. Smoked and dry-cured subcategories face the steepest technical hurdles given salt's functional role in moisture management and texture development.
Smaller households are displacing bulk club formats with single-serve and twin-pack retail configurations. Grocery retailers are reallocating refrigerated case footage toward resealable bacon and individually wrapped sausage portions. This pattern concentrates in suburban and urban Midwestern markets where household size has compressed most sharply over the past decade.
United States Processed Pork Meat Market Segmentation
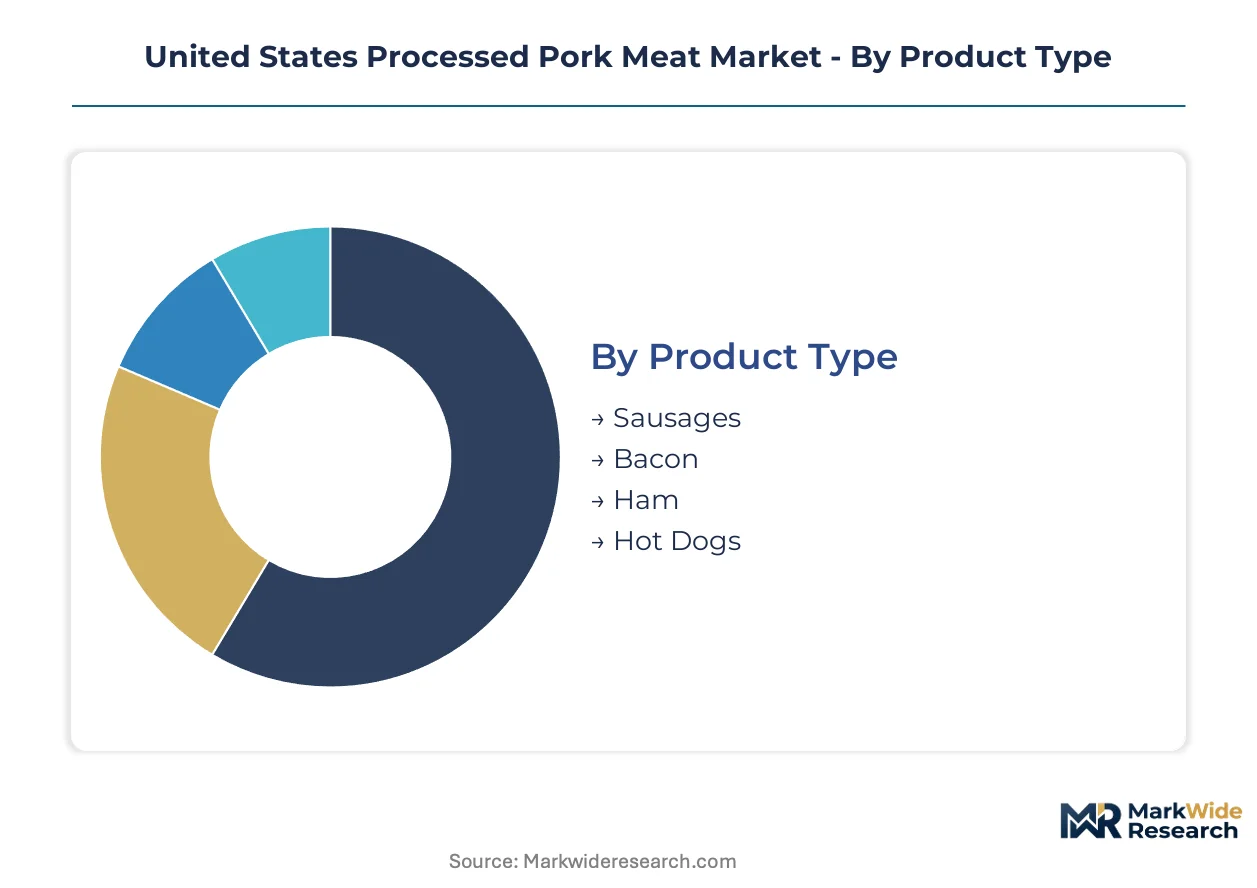
Segmentation reveals how USDA FSIS inspection tiers, packaging automation requirements, and channel margin structures concentrate investment across distinct product-positioning strategies. Each dimension carries divergent capital intensity and certification burdens that reshape processor portfolio priorities.
Product Type:
USDA FSIS mandates diverge sharply across these categories, with ready-to-eat products facing Listeria monocytogenes testing protocols that semi-dry fermented items escape.
- Sausages:Fresh, smoked, and dry-cured varieties span breakfast links to Italian specialty formats. Fresh breakfast links dominate Midwestern retail velocity, though antibiotic-free and natural-casing positioning is capturing shelf space in Minneapolis-Chicago corridor independents.
- Bacon:Dry-cured and pumped belly products vary by slice thickness, smoke source, and sodium content. Center-cut and lower-sodium formulations are expanding in suburban grocery sets as household size compresses and health-positioned retailers reallocate case footage.
- Ham:Bone-in, boneless, and reformed muscle products serve distinct holiday and everyday consumption occasions. Water-added and natural-juice regulatory distinctions govern labeling claims and price-tier placement.
- Hot Dogs:Skinless and natural-casing formats target divergent channel applications from ballpark concessions to premium grilling segments. Mechanically separated pork content thresholds determine institutional eligibility.
Bacon sits at the top of the volume ranking, with sausages climbing the fastest.
Packaging Type:
Capital requirements scale with barrier sophistication, with modified-atmosphere and high-barrier films demanding equipment investments that separate regional co-packers from integrated processors.
- Vacuum Packs:Multi-layer coextruded films with oxygen scavengers extend refrigerated shelf life to sixty-plus days. Illinois and Minnesota plants are adding capacity to serve branded retail clients demanding clean-label pathogen control without preservatives.
- Canned:Retort processing for shelf-stable hams and Vienna sausages serves institutional stockpiling and disaster-relief procurement. Federal USDA BioPreferred purchasing preferences favor domestically canned product for military and school feeding contracts.
- Tray Packs:Modified-atmosphere overwrap for fresh sausages and bacon optimizes retail case density. This format concentrates in club and mass retail channels where turnover velocity justifies shorter code dating.
- Portion Packs:Individually wrapped slices and twin-pack configurations address single-person and two-person household growth. Resealable zipper technologies are migrating from premium to standard tier across Iowa and Illinois retail markets.
Vacuum packs hold the dominant share position, with portion packs gaining share fastest.
Distribution Channel:
Channel selection dictates lot-size economics, with foodservice contract volumes enabling dedicated production runs that retail fragmentation cannot match.
- Retail:Grocery, mass merchant, and club formats demand case-ready presentation and promotional calendar coordination. Direct store delivery requirements favor processors with captive distribution assets in the Midwestern packing corridor.
- Foodservice:QSR chains, casual dining, and institutional operators specify exacting portion control and holding-stability parameters. Bacon bits, pre-cooked strips, and portion-cut ham dominate this channel's procurement specifications.
- Online:Direct-to-consumer and third-party platform sales require frozen or deep-chilled fulfillment infrastructure. Subscription bacon clubs and specialty cured product bundles are emerging in this channel.
- Wholesale:Broadline distributors and specialty meat purveyors aggregate fragmented buyer demand. This channel concentrates procurement power among Sysco, US Foods, and regional independents serving white-tablecloth and ethnic restaurant segments.
Retail commands the volume base, with online expanding most quickly.
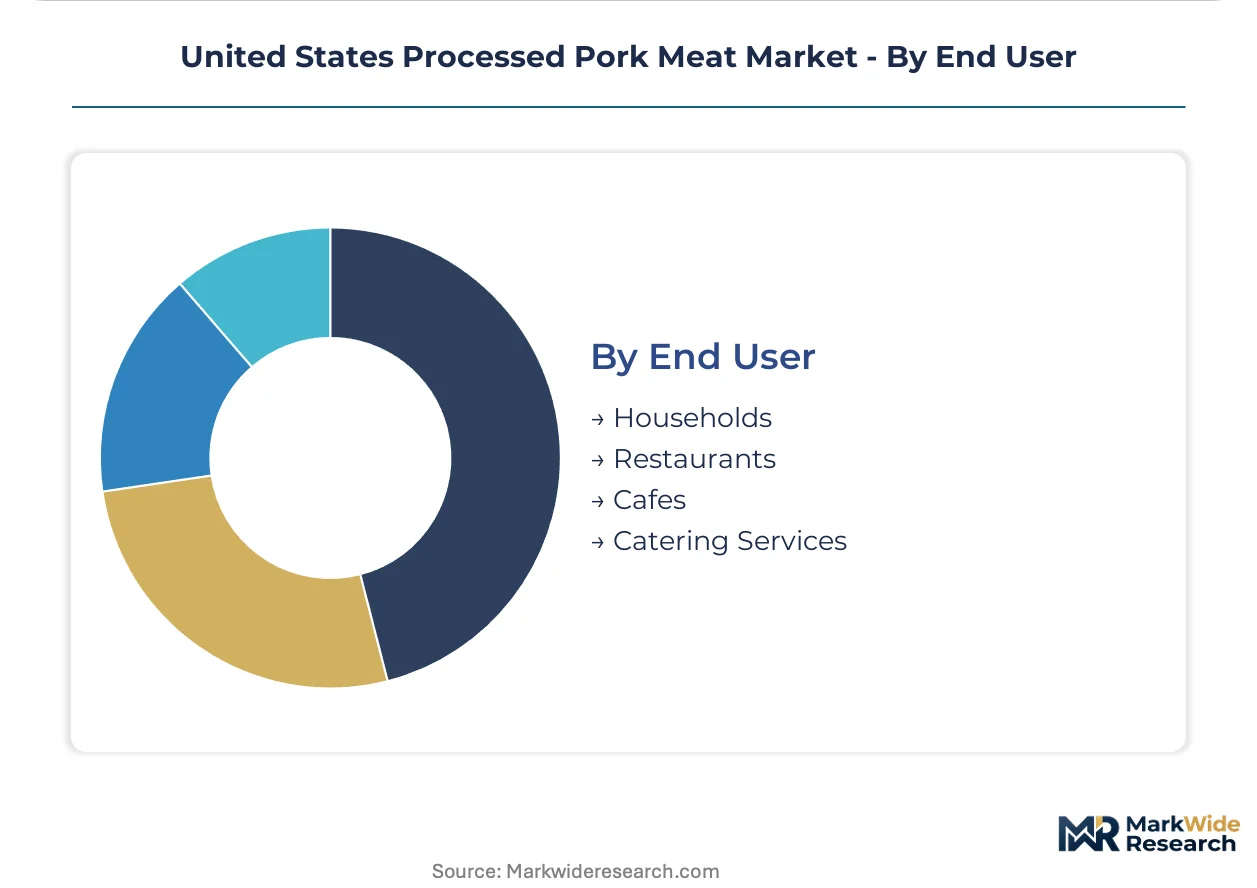
End User:
User type determines formulation complexity, with foodservice demanding holding stability and households prioritizing preparation convenience.
- Households:Weekly bacon purchases and seasonal ham acquisitions drive retail velocity. Smaller household formation is fragmenting package size demand toward sub-pound formats.
- Restaurants:Kitchen labor constraints favor pre-cooked bacon and portion-controlled sausage patties. Breakfast-all-day menu expansion is widening pork placement across dayparts.
- Cafes:Limited-service coffee and breakfast concepts specify grab-and-ready protein components. Breakfast sandwich assembly drives pre-cooked patty and slice demand.
- Catering Services:Event and institutional feeding requires bulk formats with extended holding tolerance. Spiral-sliced ham and heat-and-serve sausage dominate this procurement set.
Households anchor demand volume, with cafes showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping plant investment patterns as processors migrate toward states with lower compliance-cost burdens and streamlined USDA inspection protocols. Iowa, Illinois, and Minnesota maintain processing gravity, yet facility expansion is accelerating in jurisdictions offering tax incentives for cold-chain infrastructure.
Iowa
Slaughter capacity concentration drives feedlot procurement efficiency and live-hog logistics optimization. The Iowa Economic Development Authority offers tax credits for meat processing facility modernization under its Targeted Jobs Program. Sioux City and Council Bluffs anchor expanding blast-freezing capacity to serve branded retail clients demanding extended shelf-life codes.
Illinois
Chicago metropolitan demand pulls portion-pack and case-ready production toward collar-county processing parks. Illinois Department of Agriculture grants support HACCP system upgrades for mid-scale processors seeking FSMA compliance. The Peoria-Bloomington corridor is adding automated slicing and packaging lines to capture foodservice contract volumes.
Minnesota
Smaller household formation is accelerating demand for twin-pack bacon and resealable sausage formats across Minneapolis-St. Paul retail channels. Minnesota Department of Employment and Economic Development funds workforce training for high-pressure processing equipment operation. Austin and Worthington plants are retrofitting legacy lines to meet updated Salmonella performance standards.
North Carolina
Eastern seaboard distribution access is drawing cured ham and bacon production toward Wilmington and Smithfield processing complexes. North Carolina Biotechnology Center grants support clean-label fermentation research for nitrite-free product development. The Research Triangle Park corridor is incubating specialty cured-meat startups targeting direct-to-consumer channels.
Nebraska
Corn-belt feed sourcing proximity sustains cost-competitive hog finishing for integrated packers. Nebraska Department of Economic Development incentives attract cold-storage construction along Interstate 80 corridor nodes. Grand Island and Fremont facilities are expanding automated pathogen detection infrastructure to reduce FSIS hold-and-test delays.
United States Processed Pork Meat Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue clean-label fermentation and direct-to-consumer subscription models. The vendor base concentrates among integrated packers with captive hog supply, mid-scale regional processors with HPP capabilities, and specialty cured-meat artisans with USDA BioPreferred certification. Three archetypes dominate: vertically integrated commodity processors, technology-forward co-packers, and premium-positioned heritage brands. Capacity expansion and portfolio diversification toward portion-pack formats represent the dominant competitive moves.
Among integrated packers, Smithfield Foods, Inc., Tyson Foods, Inc., and Hormel Foods Corporation exemplify the scale-driven archetype with backward integration into hog production and forward control over retail case placement. These entities anchor the standard tier through broad protein portfolio breadth and direct store delivery infrastructure across the Midwestern packing corridor.
| Leading Market Players |
|---|
| Smithfield Foods, Inc. |
| Tyson Foods, Inc. |
| Hormel Foods Corporation |
| JBS USA Holdings, Inc. |
| Seaboard Foods LLC |
| Clemens Food Group |
| OSI Group, LLC |
| Conagra Brands, Inc. |
| Cargill, Incorporated |
| Others |
Value Network & Pricing Analysis
Corn and soybean meal feed costs cascade through live-hog procurement contracts into packer margin compression and retail price tier separation. USDA FSIS inspection mandates add fixed-cost layers that concentrate pricing power among integrated processors with validated HACCP systems and captive hog supply.
Pricing Analysis
Retailer markup layers separate branded premium tiers from private-label economy positioning across Midwestern grocery channels. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments. Cost compression in economy tiers intensifies because independent producers lack forward-contracting flexibility against feed price volatility. Foodservice contract buyers exhibit lowest price sensitivity due to menu cost pass-through mechanisms, while club-format retail shoppers demonstrate highest elasticity to unit-price changes.
Supply Chain Analysis
Live-hog supply rests on Iowa, Illinois, and Minnesota finishing operations tethered to corn-belt feed sourcing density. Key inputs span weaner pig procurement, specialized curing salt formulations, and high-barrier packaging films. Single-source vulnerability concentrates in regional slaughter capacity exposed to weather disruption and disease containment protocols. Distribution runs through captive cold-chain assets of integrated packers and broadline foodservice distributors aggregating fragmented buyer demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
USDA FSIS sodium reduction guidance and updated Salmonella performance standards compound regulatory compliance costs into competitive moats for scaled processors. These mandates accelerate demand for automated pathogen detection and reformulation-capable production assets.
For Market Incumbents: Deepen backward integration into hog finishing operations to secure feed-cost hedging and live-animal supply continuity against weather-driven procurement disruptions. Expand high-pressure processing capacity in Illinois and Minnesota to capture sixty-plus-day refrigerated code demand from branded retail clients. Prioritize HACCP system recertification ahead of FSIS inspection queue bottlenecks that extend product launch windows.
For New Entrants and Emerging Players: Direct-to-consumer subscription channels offer white-space entry around heritage-breed cured products and nitrite-free positioning for flexitarian households. Target the Research Triangle Park corridor for clean-label fermentation research partnerships enabling premium tier access. Pursue USDA BioPreferred certification to unlock federal foodservice procurement contracts with biobased purchasing preferences.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale regional processors lack capital for legacy equipment retrofits to meet updated Salmonella performance standards. Long-term viability favors technology-forward co-packers with HPP capabilities and specialty cured-meat artisans with direct-to-consumer channel control. Watch FSIS label approval timeline extensions as inflection indicator for launch-window competitive disadvantage.
| Strategic Initiative | Industry Significance |
|---|---|
| High-Pressure Processing Capacity Addition | Extends refrigerated shelf-life codes for clean-label retail positioning without thermal degradation. |
| Backward Integration into Hog Finishing | Captures margin pool upstream and secures supply continuity against feed price volatility. |
| USDA BioPreferred Certification Pursuit | Unlocks federal institutional procurement channels with mandated biobased purchasing preferences. |
| Direct-to-Consumer Subscription Launch | Bypasses retail slotting fees and builds recurring revenue from heritage-product enthusiasts. |
| Legacy Plant HACCP System Retrofit | Maintains FSIS inspection eligibility amid tightening Salmonella performance standards. |
Research Methodology
Coverage spans the Midwestern packing corridor, Eastern seaboard processing clusters, and Corn Belt feed sourcing regions, with primary inputs from each. The approach combines interviews with plant operations managers, USDA FSIS compliance officers, retail category buyers, and foodservice procurement directors with secondary validation against USDA production data, FDA guidance documents, SEC processor filings, and trade association statistics. Bottom-up volume modeling and top-down value triangulation cross-check segment outputs.
Rate-of-change decomposition separates volume growth drivers from price-mix effects across the projection horizon. Segmentation dimensions span product type, packaging format, distribution channel, and end-user application with regional regulatory cluster overlays. CAGRs derive from trend-line extrapolation adjusted for feed cost cycle phases and FSIS compliance cost step-changes. Industry-specific inputs include hog inventory cycles, cold-chain capacity utilization, and sodium reduction reformulation timelines.
The model assumes a particular technology adoption path for high-pressure processing equipment; alternative pathways for clean-label fermentation cultures would alter the outlook. Forecasts reflect assumptions around feed grain price stability and inspection protocol enforcement intensity. Disease containment events, plant-based substitution acceleration, and trade policy shifts on pork exports constitute revision triggers. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Asia-Pacific Processed Meat Market
Meat Products
Middle East Red Meat Market
Meat Products
Meat Products Market
Meat Products
Organic Meat Market
Meat Products
Middle-East and Africa Animal-Based Meat and Dairy Products Market
Meat Products
Pork Belly Meat Market
Meat Products
Asia-Pacific Edible Meat Market
Meat Products
Beef Fat Powder Market
Meat Products
Ham Slicers Market
Meat Products
North America Red Meat Market
Meat Products
United States Red Meat Market
Meat Products
Qatar Poultry Meat Market
Meat Products
Saudi Arabia Edible Meat Market
Meat Products
Meat Tenderizer Market
Meat Products
Grass-Fed Meat Market
Meat Products
Pepperoni Foods Market