
 Beacon Market | 2026-2036
Beacon Market Size, Share, and Industry Trends Forecast 2026-2036
Beacon Market Intelligence
Enterprise buyer concentration in warehousing firms and retail chains is consolidating around vendors with proven scale. Kontakt.io anchors its position through cloud-managed beacon infrastructure deployed across logistics campuses. Estimote, Inc. differentiates via programmable edge compute modules that reduce gateway dependency. Aruba Networks, Inc. leverages existing Wi-Fi access point density to deliver converged beacon-location services without dedicated hardware overlays.
A beacon is a compact, battery-powered radio transmitter that broadcasts identifier signals using Bluetooth Low Energy protocols at 2.4 GHz, typically with a range of one to seventy meters and power consumption measured in microamperes, enabling proximity-aware automation in physical environments. Bluetooth Low Energy dominates installed volume due to native support in iOS and Android operating systems, while Ultra-Wideband is gaining traction in asset tracking applications demanding sub-30-centimeter precision. Proximity marketing applications command mature margin pools in retail, though indoor navigation deployments in transportation hubs are expanding faster as operators retrofit legacy terminals.
The FCC in the United States governs unlicensed spectrum use for BLE transmissions under Part 15 rules, while GDPR and the EU AI Act constrain how European beacon networks process biometric-derived location data. Product certification complexity is rising as regulators in multiple geographies mandate cybersecurity labeling for connected sensor hardware. Stakeholders must monitor evolving spectrum allocation decisions and privacy enforcement patterns to anticipate where deployment permissions will tighten or relax.
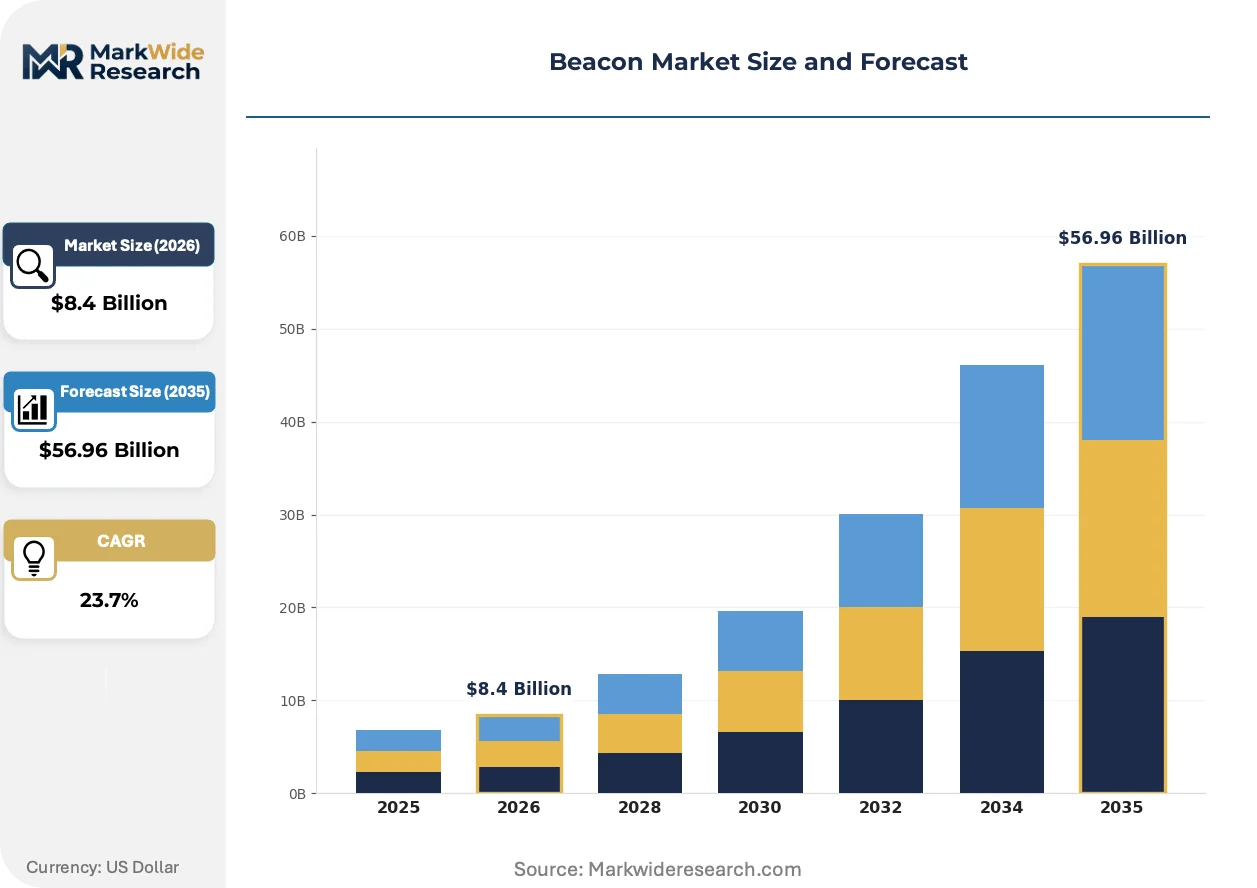
Market Dynamics
Enterprise consolidation around cloud-managed beacon infrastructure is compressing vendor margins while privileging operators with captive gateway density and firmware update automation capabilities.
Growth Catalysts
- GDPR Article 6 compliance frameworks:European retailers are retrofitting consent-layer beacon deployments to unlock proximity marketing budgets previously frozen under legal uncertainty.
- Bluetooth Low Energy 5.3 protocol extensions:Direction-finding and periodic advertising sync are enabling sub-meter positioning without Ultra-Wideband hardware overlays.
- Airport terminal modernization programs:Transportation authorities in the United States, Germany, and Singapore are mandating indoor navigation infrastructure as passenger experience criteria.
Market Restraints
- Lithium manganese dioxide cell volatility:Beacon battery supply concentrates in East Asian chemical processors, exposing OEMs to cobalt-free cathode material shortages.
- FCC Part 15 transmit power ceilings:Unlicensed spectrum restrictions cap range at seventy meters, forcing denser gateway deployment in large-format retail.
- Ultra-Wideband handset penetration thresholds:Apple and Samsung ecosystem fragmentation delays UWB beacon ROI for asset tracking vendors.
Strategic Opportunities
- India's Smart Cities Mission:Municipal transit authorities are tendering for beacon-enabled passenger information systems in Tier-1 urban corridors.
- EU AI Act biometric inference prohibitions:Proximity-only beacon networks gain competitive advantage over camera-based alternatives in European retail.
- Healthcare RTLS convergence:BLE beacon infrastructure is merging with nurse call and bed management platforms in United States hospital construction.
Industry Challenges
- Embedded RF engineering talent scarcity:Firmware optimization for microampere consumption requires specialized Bluetooth stack expertise concentrated in Nordic semiconductor ecosystems.
- PTCRB and GCF certification timelines:North American carrier requirements add four to six months to hardware launch schedules.
- Legacy Wi-Fi access point integration friction:Enterprises with Aruba or Cisco installed bases face firmware lock-in when overlaying third-party beacon management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beacon Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $56.96 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Bluetooth Low Energy, Ultra-Wideband, Infrared, Near Field Communication, Zigbee Application: Asset Tracking, Indoor Navigation, Proximity Marketing, Visitor Analytics, Workforce Management End User: Retail Chains, Transportation Operators, Event Organizers, Museums, Warehousing Firms Deployment: Fixed Installation, Wearable Devices, Mobile Integration, Vehicle-Mounted, Environmental Monitoring |
| Companies Covered | BlueCats, Blue Sense Networks, Estimote, Inc., Glimworm Beacon, Gelo, Inc., Kontakt.io, Accent Advanced Systems, SLU, Sensorberg GmbH, Aruba Networks, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beacon Market Strategic Shifts & Innovations
Beacon hardware is shedding dedicated gateway dependency through edge compute migration and access point convergence, while regulatory pressure on biometric surveillance accelerates privacy-preserving proximity alternatives.
Ultra-Wideband chipsets are converging with BLE SoC designs into single-package solutions. Automotive Tier-1 suppliers are adopting these fused modules for hands-free entry systems, compressing the addressable market for standalone beacon vendors in vehicle access control.
The EU AI Act's prohibition on real-time biometric identification in public spaces is redirecting smart city budgets toward beacon-based people-counting. French and German municipal operators are stripping camera networks from transit hubs and replacing density analytics with BLE triangulation arrays.
Retailers are unbundling beacon hardware from managed service contracts. United States big-box chains now procure tags through distribution while negotiating software subscriptions separately, compressing integrated vendor margins and privileging pure-play cloud platforms.
Beacon Market Segmentation
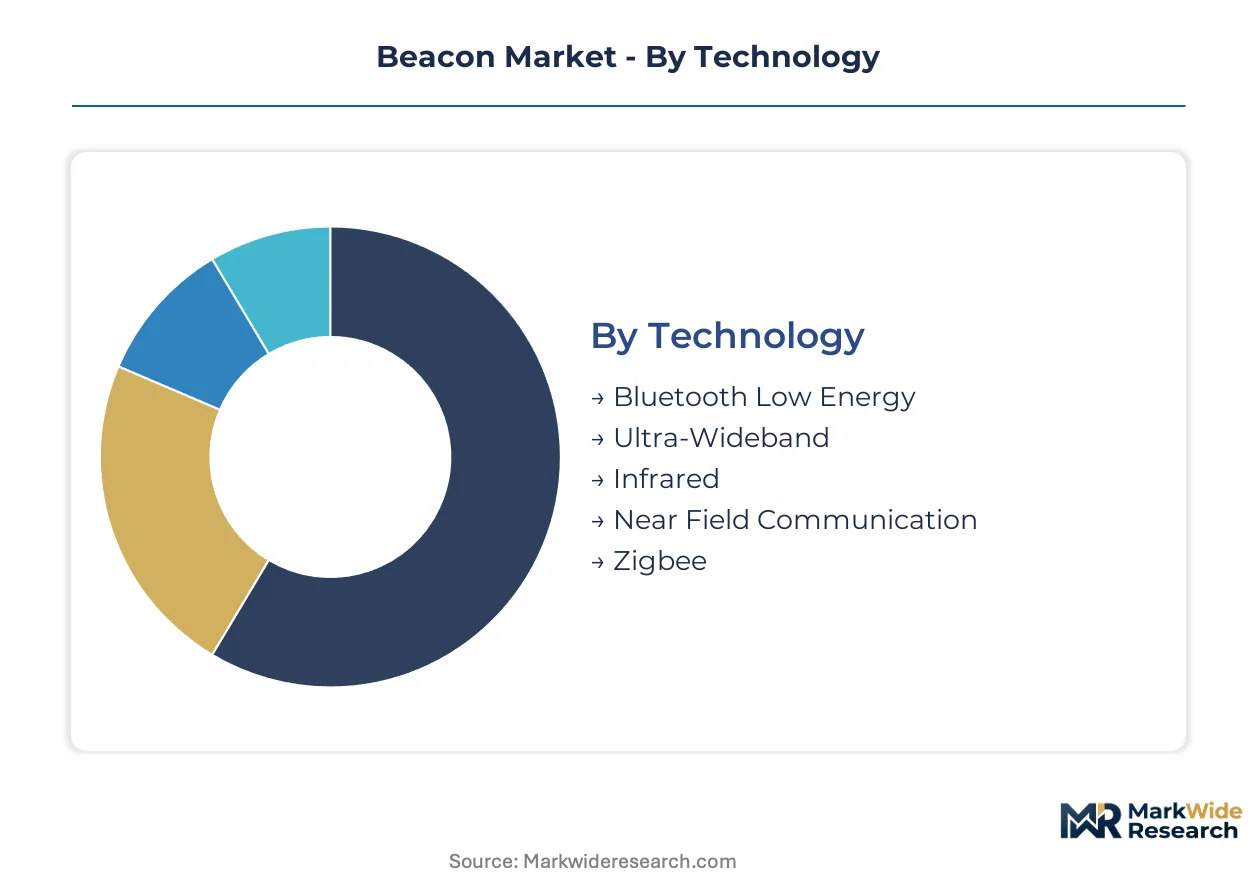
Beacon market segmentation reveals how technology choices cascade through deployment economics and end-user requirements. Supply concentration in radio frequency components and battery chemistry creates divergent margin structures across categories.
Technology:
Supply concentration in semiconductor fabrication and RF module assembly shapes competitive positioning across protocol standards.
- Bluetooth Low Energy:Native integration into iOS and Android operating systems eliminates handset compatibility barriers. Retail chains in the United States and Germany concentrate procurement here for proximity marketing at sub-dollar per-unit costs.
- Ultra-Wideband:Sub-30-centimeter precision enables high-value asset tracking in automotive assembly plants and pharmaceutical cold chains. Apple and Samsung ecosystem fragmentation constrains addressable market expansion despite superior accuracy.
- Infrared:Line-of-sight dependency limits use to controlled museum environments and gallery installations requiring precise zone delineation.
- Near Field Communication:Contact-range operation suits payment authentication and access control rather than continuous proximity sensing.
- Zigbee:Mesh networking capabilities attract smart building integrators in commercial real estate seeking interoperability with lighting and HVAC controllers.
Today's leader: Bluetooth Low Energy. Tomorrow's challenger: Ultra-Wideband.
Application:
Cost tier differentiation separates high-frequency operational deployments from episodic marketing use cases.
- Asset Tracking:Real-time location systems in United States hospital construction and German automotive logistics command premium hardware margins. FCC Part 15 and GDPR Article 6 compliance requirements add certification overhead that smaller vendors cannot absorb.
- Indoor Navigation:Airport authorities in Singapore, Germany, and the United States mandate beacon infrastructure as passenger experience criteria. Terminal retrofit programs in Frankfurt and Dallas-Fort Worth are accelerating deployment velocity.
- Proximity Marketing:Mature margin pools in retail concentrate around cloud-managed beacon platforms with automated firmware updates.
- Visitor Analytics:EU AI Act biometric prohibitions redirect smart city budgets from camera networks to BLE triangulation in French and German transit hubs.
- Workforce Management:Safety compliance in United States warehousing and construction sites drives demand for wearable panic-button beacons.
Asset Tracking commands the steepest expansion trajectory through healthcare and logistics convergence.
End User:
Customer type fragmentation creates divergent procurement patterns between centralized enterprise buyers and decentralized facility operators.
- Retail Chains:United States big-box operators unbundle hardware procurement from software subscriptions, compressing integrated vendor margins.
- Transportation Operators:Municipal transit authorities in India's Tier-1 cities and Singapore's Land Transport Authority tender for passenger information systems.
- Event Organizers:Temporary deployment models favor rental-based beacon services over capital purchases for trade shows and festivals.
- Museums:Cultural institutions in France and Italy prioritize infrared and BLE hybrid solutions for exhibit-specific content delivery.
- Warehousing Firms:Enterprise consolidation around cloud-managed infrastructure privileges vendors with captive gateway density.
Retail Chains anchor current volume. Transportation Operators are climbing the fastest.
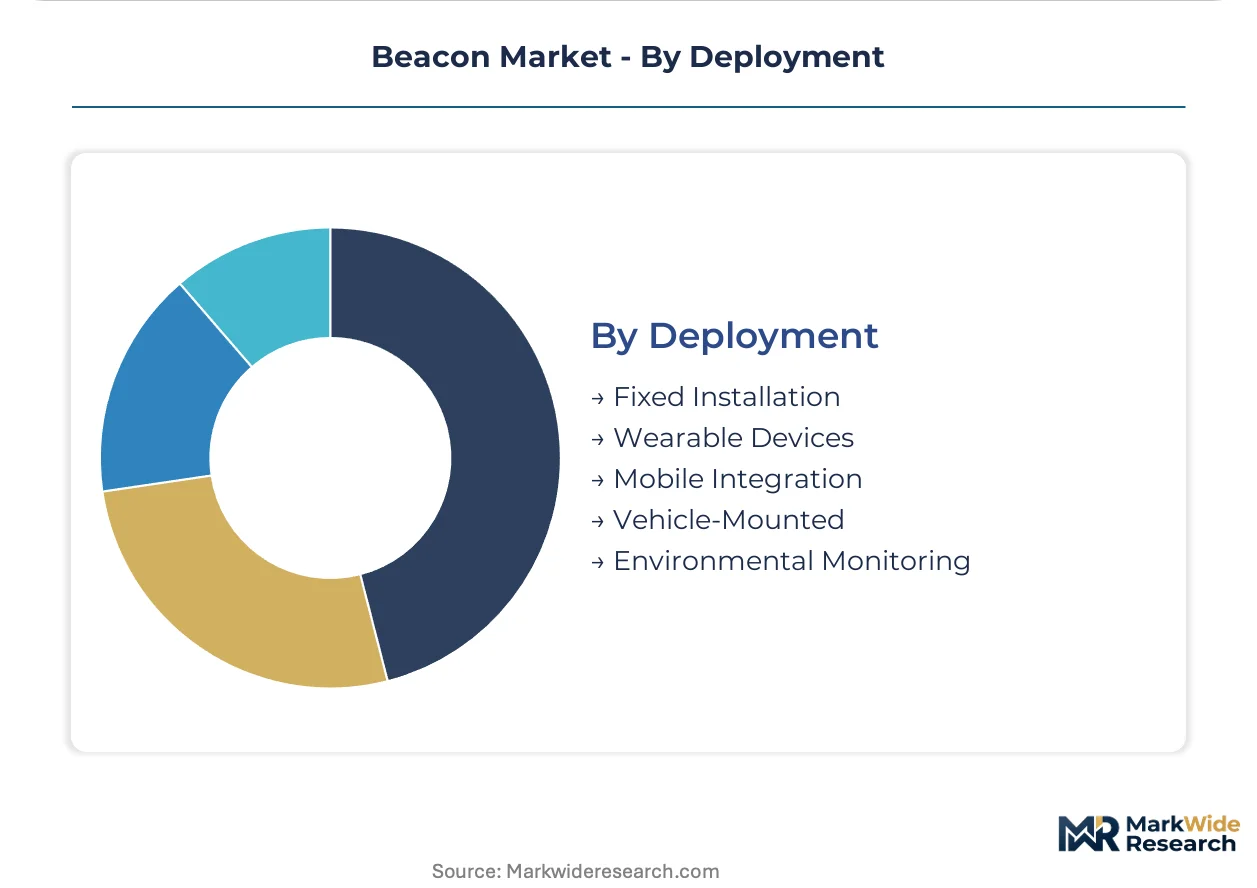
Deployment:
Volume concentration in fixed infrastructure contrasts with emerging mobility-integrated formats requiring specialized power management.
- Fixed Installation:Ceiling-mounted and wall-mounted units dominate logistics campuses and retail floors, leveraging existing electrical infrastructure.
- Wearable Devices:Healthcare worker badges and industrial safety monitors in United States hospitals require microampere-level power optimization.
- Mobile Integration:Smartphone-based beacon transmission enables peer-to-peer proximity tracing without dedicated hardware overlays.
- Vehicle-Mounted:Automotive Tier-1 suppliers adopt fused BLE-UWB modules for hands-free entry, compressing standalone beacon addressable markets.
- Environmental Monitoring:Temperature and humidity sensors in pharmaceutical supply chains combine beacon transmission with sensor fusion.
Fixed Installation maintains installed base dominance. Wearable Devices are gaining share fastest through healthcare RTLS convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's airport terminal modernization programs are outpacing retail beacon deployments in France, while India's municipal transit tenders concentrate demand in entirely different procurement patterns. National regulatory frameworks are diverging sharply between GDPR-constrained European markets and FCC-governed North American corridors.
United States
Major metropolitan retail corridors and airport hubs in Dallas-Fort Worth and Atlanta are driving fixed-installation beacon density for proximity marketing and passenger navigation. FCC Part 15 rules govern unlicensed BLE spectrum use with seventy-meter transmit power ceilings. Healthcare construction in Texas and Florida is merging beacon infrastructure with nurse call platforms.
Germany
Frankfurt Airport's terminal retrofit programs and automotive logistics campuses in Stuttgart command premium asset-tracking deployments. GDPR Article 6 compliance frameworks are unlocking previously frozen retail proximity budgets through consent-layer architectures. Bavarian municipal operators are stripping camera networks from transit hubs in favor of BLE triangulation arrays.
Singapore
The Land Transport Authority mandates beacon-enabled indoor navigation as passenger experience criteria across Changi Airport and MRT terminals. National procurement standards favor cloud-managed infrastructure with automated firmware update capabilities. Smart city budgets are redirecting from biometric surveillance to privacy-preserving proximity analytics.
India
Tier-1 urban corridors including Mumbai, Delhi, and Bengaluru are tendering beacon-enabled passenger information systems under the Smart Cities Mission. BIS certification requirements for connected sensor hardware are rising alongside municipal cybersecurity mandates. Warehousing firms in Haryana and Maharashtra are consolidating around vendors with captive gateway density.
France
EU AI Act biometric inference prohibitions are redirecting smart city budgets in Paris and Lyon toward beacon-based people-counting alternatives. ANSM and CNIL enforcement patterns are tightening constraints on camera-derived location data processing. Cultural institutions in Île-de-France are prioritizing infrared-BLE hybrid solutions for exhibit-specific content delivery.
Beacon Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across cloud-managed beacon infrastructure and programmable edge compute modules. Market structure shows consolidation around vendors with proven scale in logistics campuses and captive gateway density. Three archetypes dominate: network equipment incumbents leveraging Wi-Fi convergence, cloud-native beacon specialists, and semiconductor-integrated module suppliers. Competitive moves center on firmware update automation capabilities and strategic partnerships for healthcare RTLS convergence.
Within the cloud-native specialist tier, Kontakt.io and Estimote, Inc. exemplify divergent positioning around gateway dependency reduction. Aruba Networks, Inc. represents the network equipment incumbent archetype, occupying a position where existing access point density enables converged service delivery without dedicated hardware overlays. These three anchors illustrate how vendor selection criteria are compressing around firmware automation and installed base leverage rather than hardware differentiation alone.
| Leading Market Players |
|---|
| BlueCats |
| Blue Sense Networks |
| Estimote, Inc. |
| Glimworm Beacon |
| Gelo, Inc. |
| Kontakt.io |
| Accent Advanced Systems, SLU |
| Sensorberg GmbH |
| Aruba Networks, Inc. |
| Others |
Cost & Logistics Intelligence
BLE 5.3 direction-finding integration into single-package SoCs is compressing hardware bill-of-materials while concentrating procurement leverage among semiconductor fabricators in Taiwan and South Korea. This convergence simultaneously lowers per-unit production costs and amplifies dependency on advanced node foundries, reshaping how vendors negotiate volume commitments and pass-through pricing.
Pricing Analysis
Capacity additions in Taiwan and South Korea are reshaping price floors for BLE beacon modules, pressuring legacy vendors. Three-tier pricing structure across premium, standard, and economy levels separates firmware-automation bundled offerings from bare-metal hardware. Price differentiation hinges on PTCRB certification tier and gateway management sophistication. Margins are tightening due to retail chain unbundling of hardware from SaaS subscriptions. Warehousing firms exhibit highest price sensitivity; healthcare systems prioritize certification over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with East Asian lithium manganese dioxide cell processors, particularly Japanese and South Korean chemical suppliers. Semiconductor fabrication draws from Taiwan, South Korea, and mainland China for BLE SoC wafers. Raw material dependencies include cobalt-free cathode materials, FR4 substrate laminates, and 2.4 GHz ceramic antennas. Tariff exposure on Chinese-assembled modules threatens North American OEM cost structures. Distribution runs through electronics component distributors and direct enterprise procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds around regulatory milestones, with EU AI Act biometric prohibitions redirecting smart city budgets toward privacy-preserving proximity infrastructure. Compliance-driven retrofit cycles create durable demand visibility for vendors with pre-certified architectures.
For Market Incumbents: Cement firmware update automation as a defensive moat against cloud-native challengers. Deepen captive gateway density in United States hospital construction and German automotive logistics to lock out overlay competitors. Invest in GDPR Article 6 consent-layer architectures before European retail budgets fully unlock. Vertical integration into Nordic semiconductor ecosystems mitigates RF engineering talent scarcity.
For New Entrants and Emerging Players: Programmable edge compute modules offer a technology-first wedge against gateway-dependent incumbents. Target India's Tier-1 municipal transit tenders under Smart Cities Mission, where BIS certification barriers filter out established Western vendors. Pursue wearable device formats for healthcare RTLS convergence, bypassing fixed-installation incumbents. Lead with API-first beacon management platforms unbundled from hardware.
For Investors and Strategic Acquirers: Valuations sit cheapest among semiconductor-integrated module suppliers lacking cloud management layers. Five-to-ten year viability favors vendors with healthcare RTLS convergence capabilities and automated firmware pipelines. Acquisition target archetype: pure-play cloud platforms with hospital system referenceability. Watch FCC spectrum allocation decisions as inflection indicator for unlicensed transmit power ceilings.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Platform Integration | Converges beacon management with existing Wi-Fi infrastructure at Dallas-Fort Worth and Frankfurt airports. |
| Healthcare RTLS Partnership | Aligns BLE infrastructure with nurse call platforms in Texas and Florida hospital construction. |
| Regulatory Certification Investment | Accelerates PTCRB and GCF timelines to capture unbundled retail procurement in United States big-box chains. |
| Edge Compute Module Development | Reduces gateway dependency for automotive Tier-1 hands-free entry systems. |
| Smart City Geographic Expansion | Positions for India's BIS-certified municipal transit tenders in Mumbai and Delhi corridors. |
Research Approach
Multiple input streams — primary interviews with logistics technology officers, retail procurement directors, and healthcare biomedical engineers; secondary validation through FCC equipment authorization databases, ETSI harmonized standards filings, and customs trade records; plus bottom-up and top-down triangulation — were reconciled to construct market estimates. Stakeholder consultations included cloud platform CTOs, semiconductor RF module designers, and airport authority planning officers. Secondary sources encompassed Bluetooth SIG specification releases, GDPR enforcement pattern tracking, and smart city tender documentation from India's Ministry of Housing and Urban Affairs.
Data-stream reconciliation applied across the analysis window segmented volume and value by technology protocol, application use case, end-user vertical, and deployment format. CAGRs were derived from fitted growth curves against historical adoption velocity in comparable proximity technology markets. Industry-specific forecast inputs included BLE 5.3 handset penetration trajectories and UWB ecosystem fragmentation indices from Apple and Samsung device release patterns.
The model holds under stable regulatory enforcement and continued unlicensed spectrum availability; deviation in FCC Part 15 rulemaking or EU AI Act biometric interpretation would shift deployment permission landscapes. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Asia Pacific Container Monitoring Market
Sensors
Terrestrial Laser Scanning System Market
Sensors
Asset Tracking Market
Sensors
Handheld RFID Readers Market
Sensors
Real Time Location System Market
Sensors
Global RFID Market
Sensors
Global Real-Time Locating Systems (RTLS) Market
Sensors
Traffic Sensor Market
Sensors
Remote Sensing Technology Market
Sensors
Barcode Scanner Market
Sensors
Eye Tracking Solutions Market
Sensors
Digital Compass (E-Compass) Market
Sensors
Europe RFID Market
Sensors
Refrigeration Monitoring Market
Sensors
Drain Camera Market
Sensors
Handheld GPS Units Market