
 Asia Pacific Container Monitoring Market | 2026-2036
Asia Pacific Container Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Container Monitoring Market Insights
The Asia Pacific container monitoring landscape is restructuring around a sharp split between premium integrated platforms and commodity tracking hardware. ORBCOMM Inc. leverages satellite-cellular hybrid networks to sustain high-margin contracts with refrigerated cargo operators across trans-Pacific lanes. Emerson Electric Co. anchors its position through deep calibration expertise in temperature-sensitive pharmaceutical shipments. Globe Tracker ApS competes aggressively on Nordic-designed sensor durability for harsh maritime climates.
Container monitoring encompasses the remote surveillance of intermodal shipping containers through embedded telemetry, combining GPS positioning, environmental sensors, and wireless data transmission to deliver real-time visibility across multimodal supply chains. Systems typically integrate cellular, satellite, and low-power wide-area protocols to maintain connectivity through port dead zones and open ocean corridors. IoT Sensors and Temperature Monitoring command the strongest margin pools as pharmaceutical and food-grade shippers mandate continuous environmental logging with audit-grade data integrity. Cloud-Based deployment is displacing on-premises infrastructure among mid-sized logistics providers seeking elastic scalability without capital-intensive server commitments.
Japan's METI enforces stringent IoT security guidelines for critical infrastructure devices, while China's MIIT mandates GB-standard compliance for radio equipment deployed in port automation zones. Australia's TGA aligns cold chain validation protocols with pharmaceutical import requirements, tightening sensor calibration standards for temperature-critical cargo. Stakeholders must weigh sovereign data localization rules against cross-border fleet management architectures as regulatory fragmentation intensifies across the region.
Market Dynamics
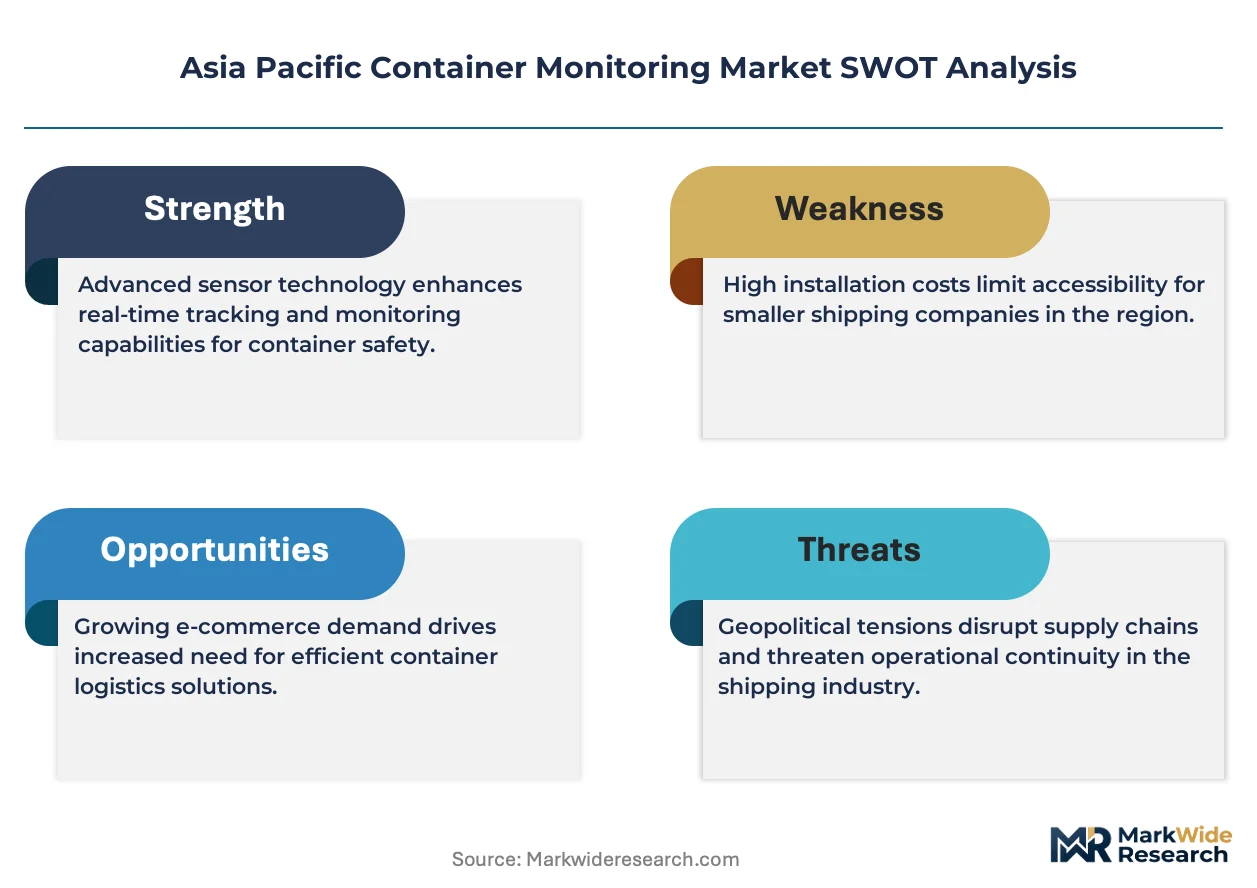
Asia Pacific container monitoring is bifurcating around sovereign data localization mandates that fragment cross-border fleet architectures, forcing operators to rebuild connectivity stacks for each national jurisdiction rather than deploying unified global platforms.
Growth Catalysts
- India's PLI scheme for electronics manufacturing:Domestic production incentives for IoT devices reduce import dependency and shorten procurement cycles for logistics operators deploying sensor networks across Indian ports.
- Pharmaceutical cold chain mandates:Temperature-critical biologics shipments from Singapore and South Korea require continuous environmental logging with audit-grade data integrity, expanding sensor attach rates per container.
- Smart terminal investments:Deepening automation at Shanghai and Shenzhen port clusters embeds monitoring infrastructure directly into berth and yard operations, creating captive demand for integrated telemetry systems.
Market Restraints
- Semiconductor input volatility:LoRa and NB-IoT chipset supply concentrates among Taiwanese and South Korean foundries, exposing hardware manufacturers to allocation disruptions during capacity crunches.
- Radio equipment compliance fragmentation:China's MIIT GB-standard certification, Japan's METI security guidelines, and Australia's ACMA radiocommunications licensing create multi-jurisdictional approval costs that scale with fleet geography.
- Satellite connectivity substitution:Low Earth orbit constellation providers are compressing pricing for maritime data backhaul, eroding the margin premium historically captured by cellular-satellite hybrid networks.
Strategic Opportunities
- Underpenetrated Indonesian archipelago logistics:Inter-island shipping lanes lack real-time visibility infrastructure, creating first-mover advantage for sensor providers establishing local data residency compliant with Indonesia's data protection framework.
- Convergence of blockchain and IoT telemetry:Immutable cargo documentation tied to sensor-verified condition data addresses documentary fraud in Southeast Asian agricultural and seafood exports.
- Vietnam's emerging pharma manufacturing:Contract manufacturing growth for temperature-sensitive generics and vaccines creates demand for calibrated cold chain validation systems aligned with EU GMP import standards.
Industry Challenges
- Embedded systems cybersecurity expertise scarcity:Hardening sensor firmware against port-side intrusion attempts requires specialized talent pools concentrated in Israel and Estonia, creating recruitment friction for Asia Pacific operators.
- Multi-protocol integration complexity:Legacy container fleets deployed with 2G GSM modules resist seamless upgrade to LTE-M or 5G RedCap without hardware replacement, stranding capital in depreciating asset bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Container Monitoring Market |
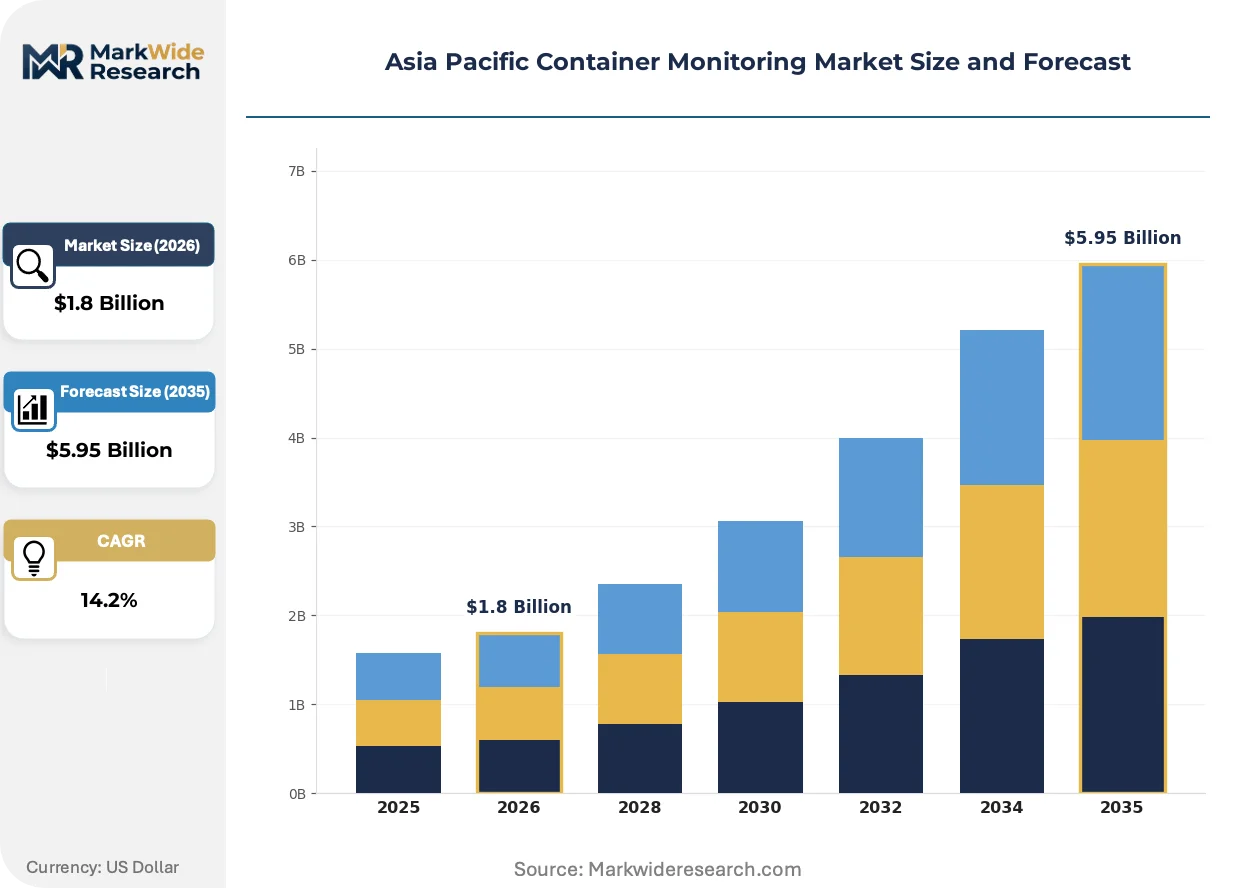
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: GPS Tracking, RFID Solutions, IoT Sensors, Temperature Monitoring End User: Shipping Companies, Logistics Providers, Retailers, Freight Forwarders Application: Supply Chain Management, Asset Tracking, Inventory Control, Cold Chain Logistics Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing |
| Companies Covered | ORBCOMM Inc., Geoforce Inc., Globe Tracker ApS, Phillips Connect Technologies, Emerson Electric Co., COSCO, CMA CGM Asia, APL Logistics, DP World, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Container Monitoring Market Trends and Innovations
Edge computing architectures are migrating analytics from cloud data centers to container-mounted gateways, reducing latency for automated reefer intervention and enabling operation during satellite coverage gaps in open ocean corridors.
Low-power wide-area protocols is overtaking traditional cellular for intra-yard container tracking. LoRaWAN and NB-IoT modules extend battery life beyond five years for stationary assets in dense port environments. Terminal operators in Busan and Kaohsiung are deploying these networks at scale, compressing total cost of ownership for yard management systems and displacing Wi-Fi and RFID infrastructure that required powered infrastructure at every read point.
Australia's TGA cold chain validation protocols are tightening sensor calibration standards for pharmaceutical imports, requiring traceable ISO 17025 laboratory certification for temperature probes. This regulatory tightening elevates technical barriers for commodity hardware vendors while deepening the competitive moat for calibration-specialist service providers. Logistics operators serving Australian biopharma lanes are consolidating vendor relationships around accredited metrology partners to avoid customs detention at Port Botany and Melbourne.
Shipper procurement patterns are compressing contract durations from multi-year enterprise agreements to annual or transactional arrangements. Mid-sized cold chain operators in Thailand and Malaysia now evaluate monitoring providers on per-container-per-voyage economics rather than fleet-wide platform subscriptions. This behavioral shift favors modular hardware vendors with minimal integration overhead and disadvantages integrated platform providers requiring lengthy deployment timelines and minimum volume commitments.
Asia Pacific Container Monitoring Market Segmentation
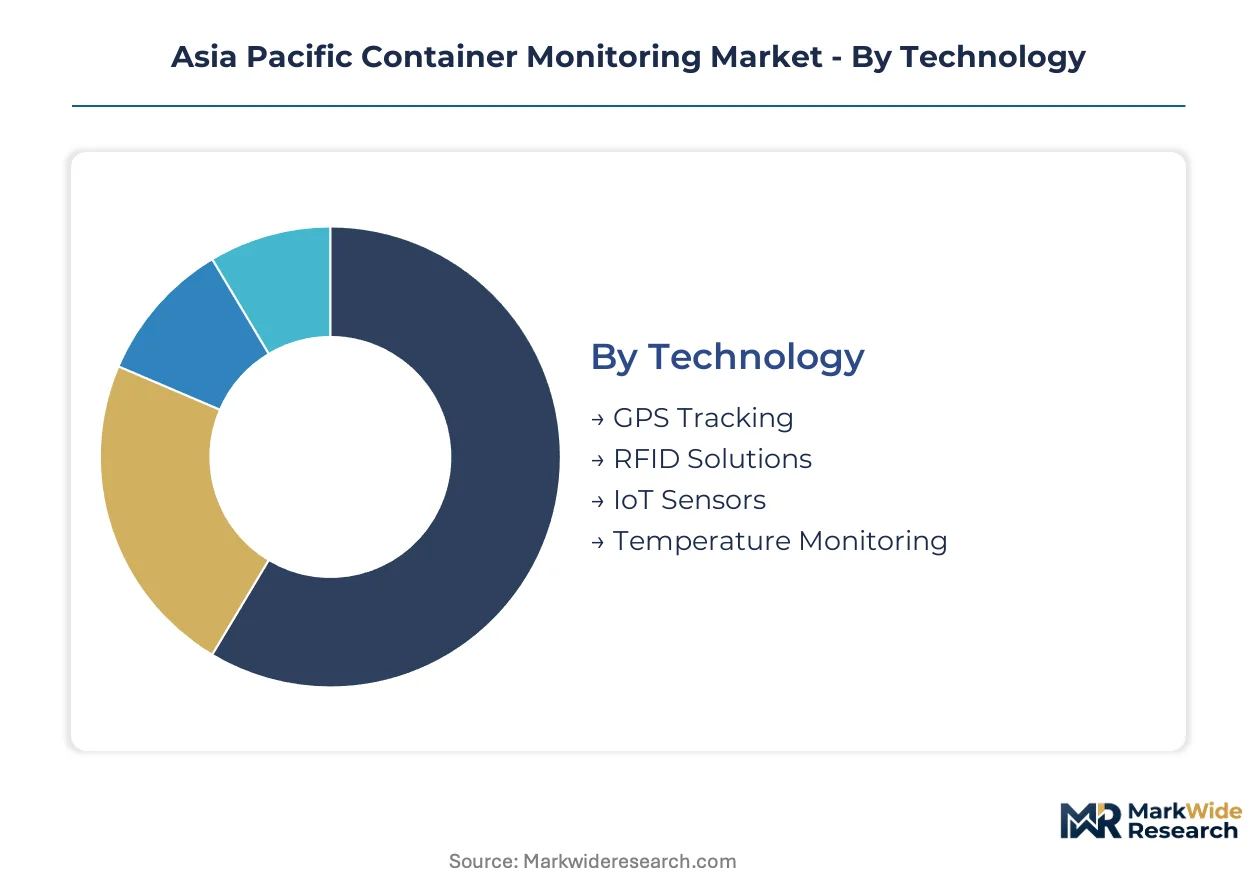
Container monitoring systems fragment across four distinct axes, each reflecting divergent buyer priorities around capital intensity, data sovereignty, and operational complexity. Technology choices determine connectivity economics, while deployment models increasingly separate multinational fleets from domestic operators.
Technology:
Customization intensity varies sharply across this category, with bespoke sensor fusion commanding premium pricing against standardized GPS commoditization.
- IoT Sensors:Multi-sensor arrays combine accelerometers, humidity detectors, and shock monitors into unified telemetry streams. Pharmaceutical shippers across Singapore and South Korea mandate these configurations for audit-grade condition documentation, driving attach rates in temperature-critical lanes.
- Temperature Monitoring:Calibrated probe systems with ISO 17025 traceability validate cold chain integrity for biologics and vaccines. Australia's TGA tightening of import standards is elevating technical barriers for uncertified hardware vendors while deepening vendor consolidation around accredited metrology partners.
- GPS Tracking:Position-only modules dominate commodity dry container deployments where environmental logging is unnecessary.
- RFID Solutions:Passive and active radio-frequency tags support yard management and gate automation at automated terminals.
Most installed capacity flows through GPS Tracking. Expansion is steepest in Temperature Monitoring.
End User:
Buyer sophistication stratifies this category, with asset-owning carriers demanding integrated platforms against freight intermediaries seeking transactional visibility.
- Shipping Companies:Ocean carriers with owned container fleets deploy unified telemetry architectures spanning reefers, dry boxes, and chassis. These operators prioritize satellite-cellular hybrid connectivity for trans-Pacific coverage and resist vendor fragmentation across trade lanes.
- Logistics Providers:Third-party operators managing multi-carrier container pools favor modular, carrier-agnostic monitoring that aggregates visibility without hardware lock-in. Mid-sized cold chain operators in Thailand and Malaysia now evaluate providers on per-container-per-voyage economics rather than fleet-wide subscriptions.
- Freight Forwarders:Non-asset intermediaries rely on carrier-provided data feeds or third-party sensor rentals for customer-facing visibility.
- Retailers:Large importers deploy monitoring for high-value seasonal inventory, prioritizing integration with warehouse management systems over maritime connectivity.
Shipping Companies anchor current installed base. Logistics Providers are gaining share fastest as outsourcing of fleet management accelerates.
Application:
Margin concentration aligns with regulatory intensity, with compliance-driven use cases sustaining price premiums against operational efficiency applications.
- Cold Chain Logistics:Continuous environmental logging for pharmaceuticals, fresh produce, and frozen seafood requires calibrated sensor networks with tamper-evident data integrity. India's vaccine distribution expansion and Vietnam's contract manufacturing growth for temperature-sensitive generics are expanding addressable demand.
- Supply Chain Management:End-to-end visibility platforms integrate container telemetry with customs documentation, port scheduling, and inland distribution. Smart terminal investments at Shanghai and Shenzhen are embedding monitoring infrastructure directly into berth and yard operations, creating captive demand for integrated systems.
- Asset Tracking:Location-centric monitoring supports equipment utilization optimization and theft recovery for container chassis and gensets.
- Inventory Control:In-transit visibility feeds replenishment planning for retail and manufacturing importers with just-in-time supply chains.
Cold Chain Logistics commands highest revenue per unit. Supply Chain Management is climbing the fastest as terminal automation deepens.
Deployment:
Capital availability and data governance requirements split this category between elastic cloud consumption and sovereign infrastructure commitments.
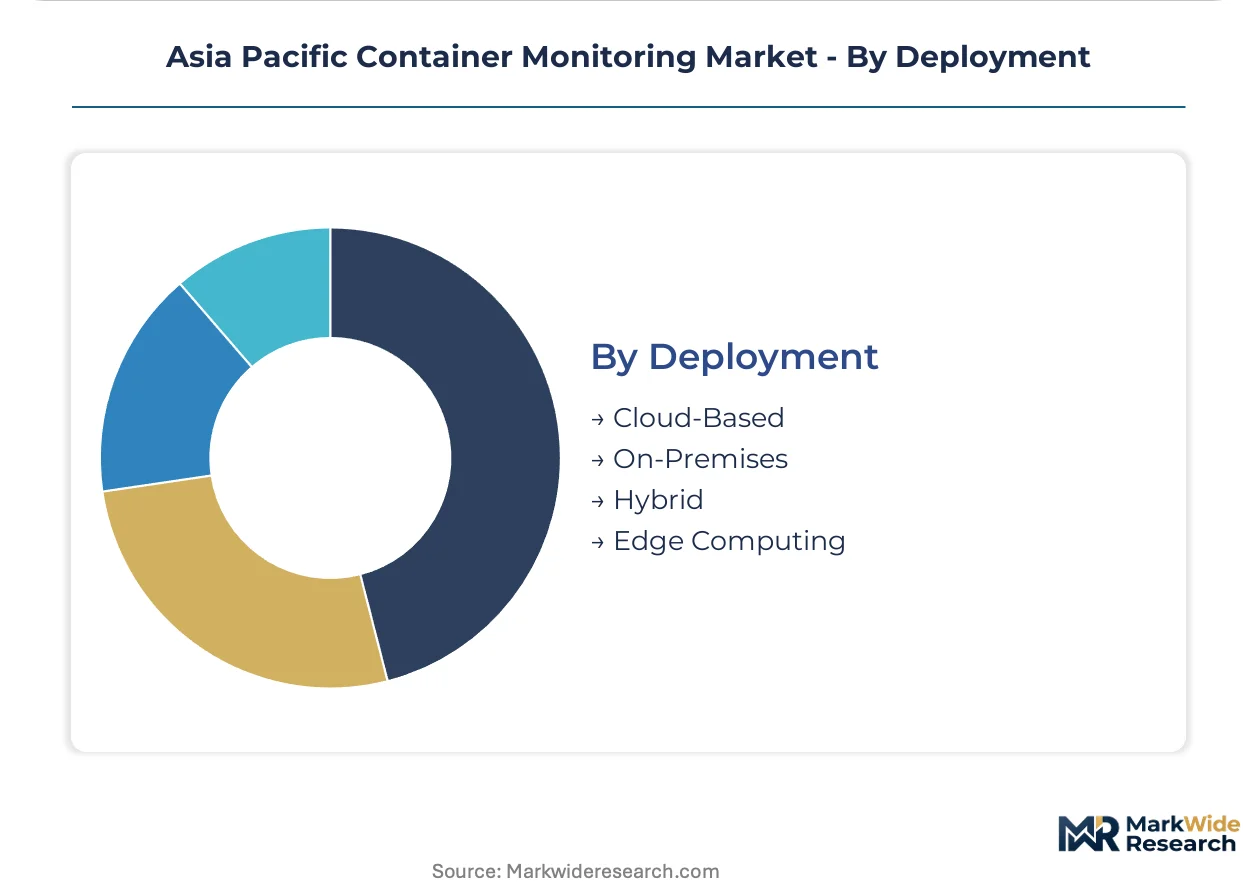
- Cloud-Based:Scalable subscription models eliminate server capital expenditure and enable rapid geographic expansion without local IT infrastructure. Mid-sized logistics providers across Southeast Asia are displacing on-premises installations as data residency requirements clarify.
- Edge Computing:Container-mounted gateways process analytics locally, reducing latency for automated reefer intervention and maintaining operation during satellite coverage gaps in open ocean corridors. Japanese and Australian operators with stringent latency requirements are deploying these architectures for autonomous container management.
- Hybrid:Split architectures retain sensitive data on local servers while leveraging cloud scalability for non-critical analytics and customer-facing dashboards.
- On-Premises:Dedicated infrastructure persists among state-owned port operators and defense-cargo handlers with strict data sovereignty mandates.
Cloud-Based deployments dominate new installations. Edge Computing is expanding most quickly as latency-sensitive automation spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Embedded systems engineers cluster around Shanghai, Singapore, and Bengaluru, anchoring hardware design and firmware development for port automation systems across the region.
China
Smart terminal investments at Shanghai and Shenzhen port clusters drive sensor deployment density for automated berth operations. MIIT mandates GB-standard compliance for radio equipment in port automation zones, fragmenting connectivity architectures. Yangtze River Delta logistics operators embed telemetry directly into yard management systems.
India
Domestic vaccine distribution networks and contract manufacturing expansion for temperature-sensitive generics accelerate cold chain sensor demand. PLI scheme incentives for electronics manufacturing reduce import dependency for IoT monitoring devices. Gujarat and Maharashtra port operators shorten procurement cycles through localized hardware sourcing.
Japan
Pharmaceutical cold chain exports to Southeast Asia require continuous environmental logging with audit-grade data integrity. METI enforces stringent IoT security guidelines for critical infrastructure devices deployed in port environments. Kanto region terminal operators prioritize latency-sensitive edge computing architectures for autonomous container management.
South Korea
Busan port automation and biologics manufacturing growth expand calibrated sensor networks for temperature-critical shipments. MFDS alignment with international pharmaceutical import standards tightens validation protocols. Busan-Ulsan logistics corridors deploy LoRaWAN infrastructure at scale for yard management systems.
Australia
TGA cold chain validation protocols for pharmaceutical imports require traceable ISO 17025 laboratory certification for temperature probes. Port Botany and Melbourne operators consolidate vendor relationships around accredited metrology partners to avoid customs detention. New South Wales biopharma lanes deepen technical barriers for uncertified hardware vendors.
Asia Pacific Container Monitoring Market Competitive Landscape
Top-tier vendors anchor integrated platform provision, while commodity hardware specialists compete on per-unit sensor economics. The market structures around three distinct tiers: satellite-cellular hybrid network operators, calibration-specialist service providers, and modular sensor fabricators. Strategic moves concentrate on M&A for technology stack completion and geographic expansion through local data residency partnerships.
Among satellite-cellular hybrid operators, ORBCOMM Inc. and Geoforce Inc. occupy positions emphasizing trans-Pacific connectivity coverage. Calibration-focused specialists include Emerson Electric Co., which exemplifies metrology-accredited service provision for temperature-critical pharmaceutical lanes. Globe Tracker ApS represents Nordic-designed sensor durability for harsh maritime climates, anchoring the hardware-specialist archetype.
| Leading Market Players |
|---|
| ORBCOMM Inc. |
| Geoforce Inc. |
| Globe Tracker ApS |
| Phillips Connect Technologies |
| Emerson Electric Co. |
| COSCO |
| CMA CGM Asia |
| APL Logistics |
| DP World |
| Others |
Pricing and Supply Chain Analysis
Captive production of LoRa and NB-IoT chipsets within Taiwanese and South Korean foundries anchors both hardware cost structures and vendor margin profiles across the Asia Pacific container monitoring landscape. This geographic concentration of semiconductor fabrication creates asymmetric pricing power for module suppliers while forcing sensor manufacturers to absorb allocation volatility through inventory buffers or contract renegotiation.
Pricing Analysis
Bundled platform subscriptions versus unbundled per-container transactional models now define the pricing architecture. Three-tier pricing structure across premium, standard, and economy levels separates ISO 17025-certified pharmaceutical monitoring from commodity GPS tracking for dry containers. Cost compression in the standard tier is intensifying because low Earth orbit satellite providers are eroding maritime data backhaul premiums. Mid-sized logistics providers in Thailand and Malaysia exhibit highest price sensitivity, demanding per-voyage economics over multi-year fleet commitments.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese foundries for LoRa chipsets and South Korean fabricators for NB-IoT modules. Hardware assembly draws from Shenzhen electronics clusters and Vietnamese contract manufacturers for sensor enclosure fabrication. Tariff exposure runs through US-China technology trade restrictions affecting radio equipment certification portability. Distribution runs through direct OEM relationships with terminal operators and carrier fleet managers, bypassing traditional industrial distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific container monitoring market functions as a geographic-arbitrage play where India's PLI scheme for electronics manufacturing offers 15-20% landed cost advantages against import-dependent Southeast Asian operators facing stricter data localization enforcement.
For Market Incumbents: Hedge satellite-cellular hybrid margin erosion by deepening calibration service accreditation for Australia's TGA pharmaceutical lanes. Establish captive chipset inventory positions with Taiwanese foundries to buffer allocation crunches. Prioritize ISO 17025 metrology partnerships over hardware volume expansion as regulatory barriers tighten. For New Entrants and Emerging Players: Terminal operator partnerships in underpenetrated Indonesian archipelago logistics offer lowest competitive density against established regional platforms. Vietnam's contract manufacturing growth for temperature-sensitive generics presents attach-rate expansion opportunity. Lead with modular, data-residency-compliant hardware avoiding lengthy enterprise platform deployment cycles. For Investors and Strategic Acquirers: Roll-up economics work for calibration-specialist service providers because Australia's TGA and Japan's METI are fragmenting vendor qualification standards across national jurisdictions. Five-to-ten year viability hinges on accumulated accreditation moats rather than sensor hardware scale. Watch for Indonesia's data protection framework finalization as signal for first-mover infrastructure deployment windows.| Strategic Initiative | Industry Significance |
|---|---|
| Local Data Residency Partnership | Indonesia's data protection framework mandates sovereign server infrastructure for fleet operators. |
| ISO 17025 Calibration Accreditation | Australia's TGA tightening elevates technical barriers for uncertified temperature probe vendors. |
| LoRaWAN Yard Network Deployment | Busan and Kaohsiung terminal operators displace Wi-Fi infrastructure with five-year battery life modules. |
| Edge Computing Gateway Integration | Japanese Kanto operators reduce reefer intervention latency through container-mounted analytics. |
| Blockchain-IoT Documentation Convergence | Southeast Asian agricultural exporters address documentary fraud through immutable sensor-verified records. |
Research Methodology
Direct dialogue with fleet operations managers at shipping companies, cold chain logistics directors, terminal automation engineers, and regulatory affairs specialists at IoT device manufacturers grounded qualitative findings. Secondary validation drew from MIIT GB-standard filings, Australia's TGA cold chain guidance documents, India's PLI scheme administrative records, and customs trade data for sensor module imports. Bottom-up unit economics for container attach rates were triangulated against top-down market sizing from port automation investment disclosures.
Installed base projections across technology segments, end-user categories, and deployment models were generated through the analysis window. The modeling framework incorporated connectivity protocol migration curves, regulatory compliance cost escalation, and semiconductor foundry capacity allocation patterns. CAGRs were derived from segmented growth rate differentials weighted by revenue concentration in cold chain logistics versus commodity tracking applications.
Revisions become necessary when sovereign data localization mandates expand beyond Indonesia to additional Southeast Asian markets, or when low Earth orbit constellation pricing compresses satellite backhaul premiums faster than modeled. Semiconductor foundry capacity crunches or trade restriction escalations affecting radio equipment certification portability would similarly alter trajectory assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
GNSS-Enabled Consumer Device Market
Sensors
Underground Service Locator Market
Sensors
Yield Monitoring Systems Market
Sensors
Global Positioning Systems Market
Sensors
Eye Tracking Market
Sensors
Global Position Tracking System Market
Sensors
Global Weather Monitoring Solutions and Services Market
Sensors
In-Counter Barcode Scanners Market
Sensors
APAC Wireless Sensors Market
Sensors
Smart Barcode Readers Market
Sensors
Handheld GPS Units Market
Sensors
Safety Motion Control System Market
Sensors
RFID Smart Cabinet Market
Sensors
Underground Utility Mapping Market
Sensors
Global Real-Time Locating Systems (RTLS) Market
Sensors
Smart Beacon Market