
 Europe Retail Analytics Market | 2026-2036
Europe Retail Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Retail Analytics Market Foresight
Data science talent scarcity across the continent is rotating retail analytics from descriptive dashboards toward automated decision systems that require fewer specialized operators. SAP SE leverages its deep ERP integration to anchor enterprise-grade deployments across German grocery networks. Microsoft Corporation competes through Azure-native analytics stacks that simplify cloud migration for mid-sized specialty retailers.
Europe retail analytics encompasses software, hardware, and services that process transactional, behavioral, and operational data to optimize pricing, assortment, and fulfillment decisions, typically integrating real-time inventory feeds with machine learning inference at sub-second latency. The primary commercial purpose is converting fragmented retail data into actionable merchandising and supply chain commands. Cloud-based deployment leads in new installations as retailers abandon aging on-premise data warehouses, while customer analytics captures disproportionate investment as loyalty program digitization intensifies across French and British department stores. Predictive analytics for demand forecasting represents the fastest-expanding solution area, though business intelligence retains the largest installed base.
The EU AI Act and GDPR jointly constrain how predictive models ingest personal data, compelling vendors to engineer explainable algorithms and localized processing architectures. EMA guidelines on algorithmic transparency in consumer-facing applications add compliance layers for health and beauty retailers deploying recommendation engines. Stakeholders must weigh the trade-off between model sophistication and auditability before scaling automated pricing or personalization systems.
Market Dynamics
The EU AI Act is forcing retailers to re-architect algorithm governance frameworks, converting compliance from a cost center into a competitive differentiator that separates explainable-AI adopters from laggards facing enforcement action.
Growth Catalysts
- GDPR-Compliant Personalization:French and British department stores are digitizing loyalty programs to merge online and in-store behavioral data streams, creating unified customer profiles that drive repeat purchase rates.
- Machine Learning Inference:German grocery networks deploy shelf-edge analytics with sub-second latency to reduce spoilage through dynamic markdown automation.
- Cloud Migration:Mid-sized specialty retailers across the continent abandon aging on-premise data warehouses for cloud-native architectures that simplify real-time inventory integration.
Market Restraints
- Algorithmic Transparency Mandates:EMA guidelines on explainable algorithms add compliance layers for health and beauty retailers deploying recommendation engines, extending deployment timelines.
- Data Science Talent Scarcity:The continent-wide shortage of specialized operators limits enterprise-scale predictive analytics deployment to organizations with captive AI capabilities.
- Localized Processing Requirements:GDPR data residency rules prevent cross-border model training, fragmenting analytics infrastructure across national boundaries.
Strategic Opportunities
- Spanish and Italian Retail Networks:These markets show underpenetration in omnichannel analytics, presenting first-mover advantages for vendors with proven ERP integration.
- Predictive Demand Forecasting:This solution area captures disproportionate investment as supply chain volatility drives merchant demand for automated replenishment commands.
- CSRD Reporting Alignment:The EU Corporate Sustainability Reporting Directive creates procurement pull for analytics platforms that trace product carbon footprints from source to shelf.
Industry Challenges
- Legacy System Integration:Decades-old POS and inventory management architectures in established European retail chains resist API-based connectivity, requiring expensive middleware development.
- Model Auditability Requirements:The EU AI Act's risk-classification framework demands documentation trails that many black-box machine learning systems cannot produce without re-engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Retail Analytics Market |
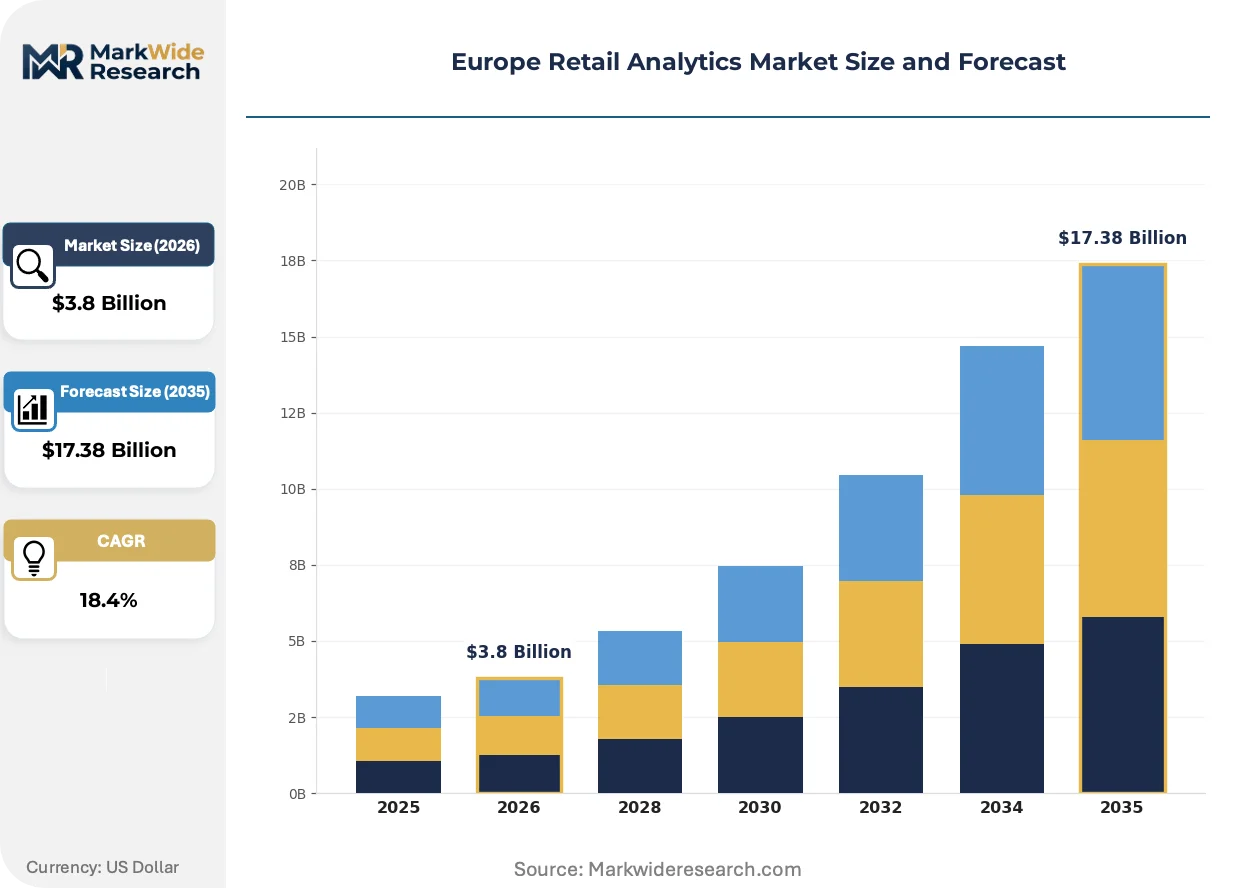
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.38 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Services, Cloud Solutions End User: Supermarkets, Department Stores, E-commerce, Specialty Retailers Deployment: On-premise, Cloud-based, Hybrid, Mobile Solution: Business Intelligence, Predictive Analytics, Customer Analytics, Inventory Management |
| Companies Covered | SAP SE, Oracle Corporation, IBM Corporation, SAS Institute Inc., Microsoft Corporation, Tableau Software LLC, Qlik Technologies Inc., Alteryx Inc., RetailNext Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Retail Analytics Market Shifts & Advancements
Edge computing architectures are displacing centralized cloud processing for latency-sensitive retail applications, while regulatory pressure on algorithmic decision-making accelerates investment in interpretable machine learning frameworks.
Computer vision systems with on-shelf product recognition are displacing manual inventory audits across European grocery chains. German and French retailers deploy shelf-edge cameras that feed real-time stock-level data into automated replenishment workflows. This sensor infrastructure is displacing periodic cycle counts with continuous digital twins of store-level inventory positions.
The EU AI Act's risk-based classification system imposes mandatory conformity assessments on high-risk predictive pricing algorithms. Retailers must now document training data provenance and model performance metrics before deploying automated markdown systems. Health and beauty segments face the steepest compliance burden as recommendation engines fall under heightened scrutiny.
Omnichannel merchants are unbundling analytics procurement from monolithic ERP contracts. British and French retailers now source best-of-breed customer analytics modules through API marketplaces rather than single-vendor suites. This procurement fragmentation favors specialized vendors with vertical expertise over horizontal platform providers.
Europe Retail Analytics Market Segmentation
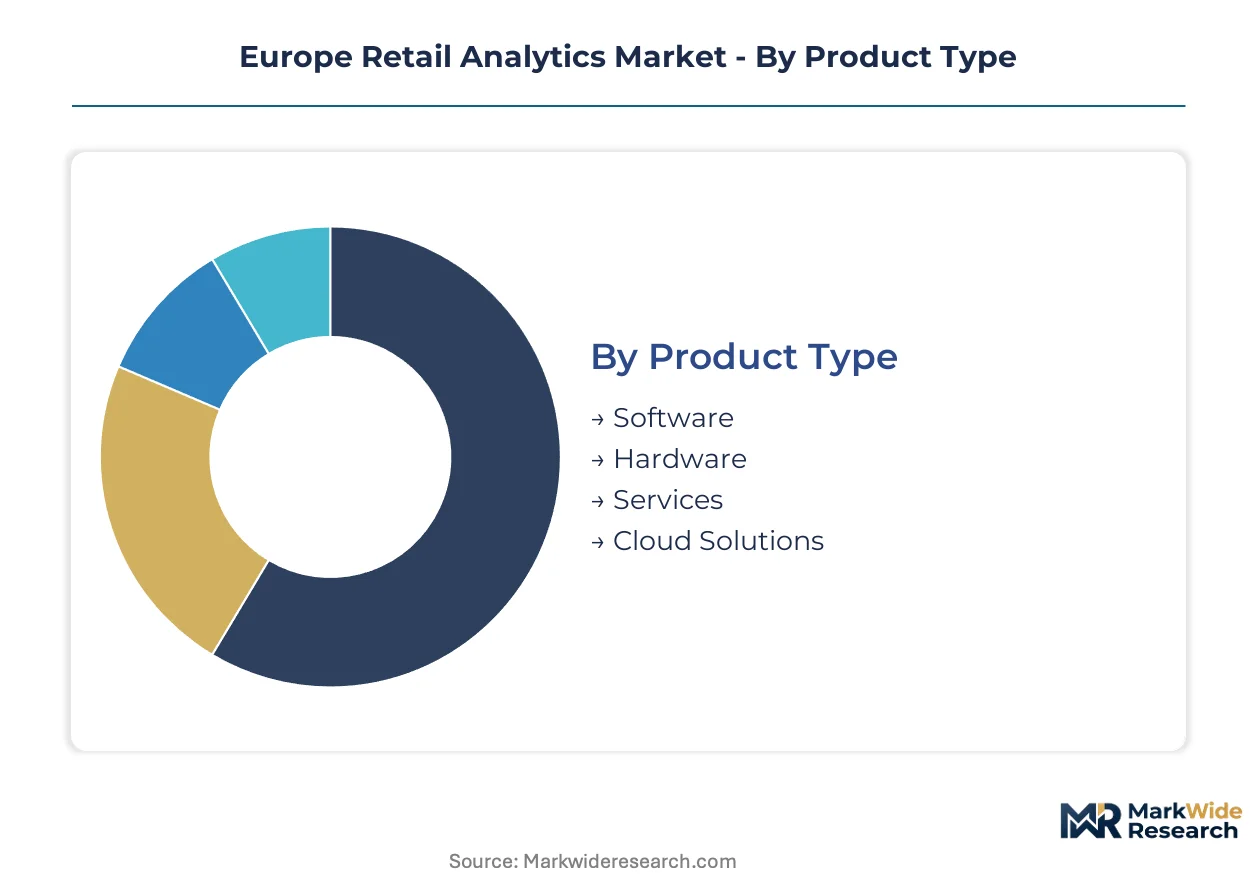
European retailers segment analytics procurement by operational maturity and data sovereignty requirements. German grocers prioritize shelf-edge hardware while British omnichannel operators concentrate investment in cloud-native customer intelligence.
Product Type:
Software solutions dominate domestic deployments across France and Germany where ERP integration determines vendor selection. Hardware demand concentrates in export-led networks serving cross-border retail operations.
- Software:Embedded analytics modules process transactional feeds at sub-second latency for dynamic pricing automation. German grocery chains anchor enterprise deployments through SAP-integrated stacks that govern markdown decisions.
- Hardware:Shelf-edge cameras and edge computing nodes capture real-time inventory positions without cloud round-trips. French retailers deploy these systems to minimize GDPR exposure from cross-border data flows.
- Services:Implementation and change management contracts support mid-tier retailers lacking captive data science capabilities.
- Cloud Solutions:Managed analytics platforms reduce infrastructure overhead for specialty retailers abandoning on-premise warehouses.
Software commands the established base. The steepest expansion runs through hardware as computer vision infrastructure proliferates.
End User:
Supermarket networks drive volume through standardized replenishment algorithms. Department stores and specialty retailers pursue margin through differentiated customer intelligence.
- Supermarkets:High-frequency transaction environments demand real-time inventory optimization with spoilage reduction as the primary ROI metric. German chains deploy shelf-edge analytics to automate markdown timing.
- Department Stores:Complex category portfolios require unified customer profiles merging online and in-store behavioral streams. British and French operators digitize loyalty programs to drive repeat purchase rates.
- E-commerce:Pure-play digital merchants prioritize predictive demand forecasting for fulfillment center positioning.
- Specialty Retailers:Niche assortment strategies favor best-of-breed analytics modules over monolithic ERP suites.
Supermarkets anchor current procurement volumes. Specialty retailers are gaining share fastest as API-based procurement fragments vendor relationships.
Deployment:
Cloud architectures dominate new installations while hybrid configurations address data residency constraints. On-premise retention persists where legacy POS systems resist API connectivity.
- On-premise:Aging data warehouses in established European chains require expensive middleware development for real-time integration.
- Cloud-based:Native architectures simplify inventory feed ingestion for mid-sized retailers without captive infrastructure teams. GDPR residency rules fragment deployments across national boundaries.
- Hybrid:Sensitive customer data processes locally while aggregate analytics train in centralized cloud environments.
- Mobile:Store manager dashboards and field merchandising tools extend decision authority to floor operations.
Cloud-based deployment captures the majority of new investment. Hybrid configurations climb the fastest as the EU AI Act intensifies localized processing requirements.
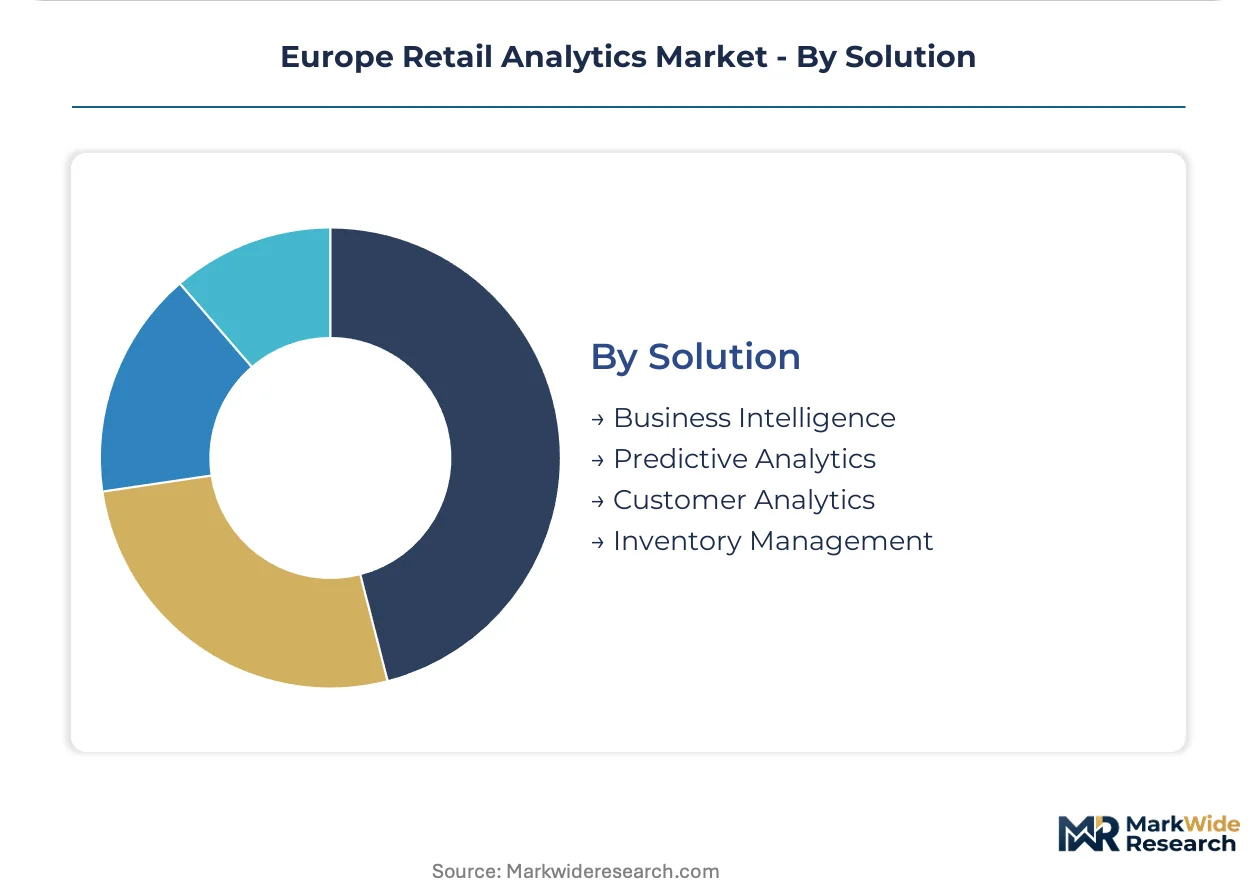
Solution:
Business intelligence retains the largest installed base through descriptive dashboards. Predictive and customer analytics concentrate investment growth as automation replaces specialized operators.
- Business Intelligence:Historical reporting and visualization tools support merchant decision-making through standardized KPI dashboards. These systems require minimal data science intervention.
- Predictive Analytics:Machine learning models generate automated replenishment commands and demand forecasts. Supply chain volatility drives merchant demand for algorithmic decision support.
- Customer Analytics:Unified profile engines merge behavioral streams across channels to personalize promotion targeting. French and British department stores concentrate investment here.
- Inventory Management:Real-time stock positioning and automated reorder point calculation reduce carrying costs.
Business intelligence holds the established base. Predictive analytics displays the steepest expansion trajectory as retailers automate merchant decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Retail analytics consumption patterns diverge sharply across Europe, with German grocers prioritizing shelf-edge automation while British merchants concentrate investment in unified customer intelligence platforms.
United Kingdom
Omnichannel retailers in London and the Southeast merge online and in-store behavioral data streams to power loyalty program digitization. The UK Information Commissioner's Office enforces GDPR-aligned consent frameworks for predictive personalization engines. Manchester-based grocery cooperatives deploy cloud-native customer analytics modules through API marketplaces rather than monolithic ERP suites.
Germany
German grocery networks anchor enterprise-grade deployments through SAP-integrated stacks that govern dynamic markdown decisions at sub-second latency. The EU AI Act's risk-classification framework forces retailers to document training data provenance before deploying automated pricing algorithms. Berlin-Brandenburg and Bavaria host dense clusters of mid-sized specialty retailers abandaging on-premise warehouses for Azure-native architectures.
France
Parisian department stores concentrate investment in unified customer profiles that drive repeat purchase rates through digitized loyalty programs. The CNIL mandates algorithmic transparency documentation for health and beauty recommendation engines. Lyon and Marseille retailers deploy shelf-edge cameras to minimize GDPR exposure from cross-border data flows while maintaining real-time inventory visibility.
Italy
Italian retail networks show underpenetration in omnichannel analytics, presenting first-mover advantages for vendors with proven ERP integration capabilities. EMA guidelines on explainable algorithms extend deployment timelines for automated replenishment systems in health and beauty segments. Lombardy-based fashion retailers source best-of-breed analytics modules rather than single-vendor suites to preserve assortment differentiation.
Spain
Spanish supermarket chains lag in predictive demand forecasting adoption despite supply chain volatility driving merchant demand elsewhere in Europe. GDPR data residency rules fragment analytics infrastructure across national boundaries, preventing cross-border model training. Barcelona and Madrid retailers increasingly procure cloud-based deployment solutions to reduce infrastructure overhead without captive data science teams.
Europe Retail Analytics Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier that fragments across vertical applications and deployment modalities. Enterprise software conglomerates anchor the upper tier through deep ERP integration, while cloud-native specialists capture mid-market share through simplified migration pathways. Three archetypes dominate: legacy platform extenders, hyperscale cloud providers, and vertical analytics specialists. Competitive intensity manifests through strategic partnerships with grocery networks and portfolio diversification into edge computing hardware.
Within the legacy platform extender tier, SAP SE and Oracle Corporation represent entrenched positions in German grocery networks where ERP integration determines vendor selection. Microsoft Corporation exemplifies the hyperscale cloud provider archetype, competing through Azure-native analytics stacks that reduce infrastructure overhead for mid-sized specialty retailers. These three companies occupy positions that reflect the market's bifurcation between enterprise-grade governance requirements and cloud-native agility demands.
| Leading Market Players |
|---|
| SAP SE |
| Oracle Corporation |
| IBM Corporation |
| SAS Institute Inc. |
| Microsoft Corporation |
| Tableau Software LLC |
| Qlik Technologies Inc. |
| Alteryx Inc. |
| RetailNext Inc. |
| Others |
Supply & Pricing Matrix
Sub-500-millisecond inference latency requirements for shelf-edge analytics tie software licensing premiums to edge hardware deployment density, concentrating pricing power with vendors controlling both sensor infrastructure and algorithm governance stacks. This interdependence forces mid-sized retailers into bundled procurement contracts that inflate total cost of ownership relative to standalone cloud solutions.
Pricing Analysis
Long-term SaaS subscriptions dominate enterprise deployments, with three-tier pricing structure across premium, standard, and economy levels differentiated by ERP integration depth and GDPR compliance automation. Premium tiers command 40-60% markups for pre-certified EU AI Act documentation trails. Cost compression in standard tiers intensifies because hyperscale cloud providers bundle analytics modules with infrastructure credits. Mid-sized specialty retailers exhibit highest price sensitivity, while German grocery networks prioritize integration reliability over unit economics.
Supply Chain Analysis
GDPR data residency rules create chokepoints that fragment cloud infrastructure across national boundaries, preventing centralized model training and forcing redundant edge node deployment in each member state. Hardware supply concentrates in Taiwan for GPU acceleration, Germany for industrial edge computing, and China for camera sensor components. Software licensing draws from US hyperscalers and European ERP conglomerates. Single-source vulnerability runs through NVIDIA's dominance in inference-optimized silicon. Distribution runs through systems integrators with vertical retail expertise rather than direct vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API-based procurement fragmentation is splintering vendor relationships and creating service-layer niches where specialized analytics modules outperform monolithic suites. This demand-side shift rewards agile entrants with vertical-specific algorithm governance expertise.
For Market Incumbents: Compound ERP integration advantages by embedding EU AI Act compliance automation directly into core platforms, neutralizing the threat from cloud-native specialists with faster certification pathways. Prioritize backward integration into edge hardware to capture shelf-edge analytics margins currently leaking to camera sensor vendors. Channel control through exclusive systems integrator networks remains the priority lever for defending German grocery deployments. For New Entrants and Emerging Players: Mid-tier retailer change management services represent the most penetrable white-space target, as SAP and Oracle under-serve implementation support for cloud migration. Spanish and Italian retail networks offer lowest competitive density for omnichannel analytics penetration. A best-of-breed positioning through API marketplace distribution bypasses incumbent procurement lock-in and accelerates time-to-revenue. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because EU AI Act compliance automation will consolidate around vendors with pre-certified algorithm governance stacks. Acquisition targets should profile as vertical analytics specialists with health and beauty sector expertise and existing EMA transparency documentation. The signal to watch is enforcement action velocity against black-box pricing algorithms, which will accelerate explainable-AI procurement pull.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Automation | Pre-certified documentation trails separate explainable-AI vendors from enforcement-exposed laggards. |
| Edge Hardware Integration | Captures shelf-edge analytics margins currently flowing to camera sensor and GPU suppliers. |
| API Marketplace Distribution | Bypasses monolithic ERP procurement and accelerates adoption among specialty retailers. |
| Vertical Analytics Specialization | Health and beauty expertise commands premium pricing under EMA algorithmic transparency guidelines. |
| Change Management Services | Mid-tier retailers lacking captive data science capabilities require implementation support beyond software licensing. |
Research Methodology
A spread of perspectives from retail CIOs, grocery chain operations directors, ERP implementation specialists, and cloud procurement officers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through SEC filings of listed software vendors, hyperscaler capex disclosures, and EU regulatory documentation including GDPR enforcement actions and EU AI Act implementation guidance. Bottom-up sizing of deployment volumes triangulated against top-down market value estimates from trade associations and national statistical offices.
Segmentation dimensions modeled include deployment architecture, solution type, end-user category, and national data sovereignty requirements across the projection horizon. CAGRs were derived from trend extrapolation of historical adoption curves adjusted for regulatory inflection points. Industry-specific forecast inputs incorporated grocery spoilage reduction ROI benchmarks and department store loyalty program digitization investment cycles.
Underlying assumptions cover sustained EU AI Act enforcement intensity and cloud migration continuity among mid-sized retailers, with deviation risk concentrated in GDPR data residency rule amendments and edge hardware supply disruptions. Practitioners should keep alternative scenarios live as algorithmic transparency mandate timelines and hyperscaler pricing strategies evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Italy Geospatial Analytics Market
Analytics
Global Wi-Fi Analytics Market
Analytics
North America Operational Intelligence Market
Analytics
AI Performance Marketing Market
Analytics
Imagery Analytics Market
Analytics
Global Mobile BI Market
Analytics
Regression Analysis Tool Market
Analytics
Augmented Analytics in BFSI Market
Analytics
Speech Analytics Market
Analytics
Personal Analytics Market
Analytics
Supply Chain Analytics Market
Analytics
Global Enterprise Data Visualization Platform Market
Analytics
Spain Geospatial Imagery Analytics Market
Analytics
Iraq ICT Market
Analytics
Content Analytics Market
Analytics
Contact Center Analytics Market