
 Global RFID Market | 2026-2036
Global RFID Market Size, Share, and Industry Trends Forecast 2026-2036
Global RFID Market Outlook
The EU Green Deal is broadening RFID demand across European retail and automotive supply chains as traceability becomes a compliance mandate. Avery Dennison leverages its materials science heritage to dominate inlay and label production for apparel tagging. Impinj anchors the UHF chip segment through sustained R&D intensity in RAIN RFID protocol development. Zebra Technologies controls the reader and printer hardware layer, competing on channel depth across North American distribution.
Radio-frequency identification encompasses wireless systems using electromagnetic fields to transfer data between tags and readers for automatic object identification and tracking. Passive RFID tags harvest energy from the reader's interrogation signal, operate without batteries, and function across frequencies from 125 kHz to 960 MHz depending on the application environment. UHF RFID leads in logistics and supply chain management due to longer read ranges and lower per-tag costs at volume scale. Active RFID represents the fastest-expanding technology category in cold chain and real-time location systems where battery-powered beacons transmit over extended distances. Vision-based RFID sits at the premium tier, integrating optical recognition with radio frequency for high-value asset verification in healthcare and aerospace.
FDA mandates for pharmaceutical track-and-trace, EPCglobal standards for retail interoperability, and REACH compliance for tag substrate materials collectively shape product design and market access requirements across the value chain. The EU AI Act's risk classification framework is beginning to intersect with RFID-enabled automated decision systems in personnel monitoring applications. Stakeholders must monitor how GS1 standards evolution and national data sovereignty laws will redefine cross-border tag data governance before committing to long-term infrastructure investments.
Market Dynamics
EU Green Deal circular economy mandates are forcing traceability infrastructure retrofits across automotive and retail supply chains, compressing deployment timelines and reshaping vendor selection criteria toward certified substrate compliance.
Growth Catalysts
- REACH substrate compliance:European manufacturers must source recyclable tag materials, accelerating demand for biodegradable inlays and paper-based antennas.
- Smart manufacturing in China:MIIT's industrial internet initiatives mandate machine-readable asset tracking in tier-one automotive plants.
- Pharmaceutical serialization:FDA track-and-trace requirements for drug distribution security are expanding RFID deployment at unit-dose packaging lines.
Market Restraints
- Silicon wafer supply concentration:UHF chip fabrication depends on concentrated East Asian foundry capacity, creating vulnerability to geopolitical disruption.
- Metals price volatility:Silver and copper antenna deposition costs fluctuate with commodity markets, squeezing inlay margins.
- Read-range physics limits:Passive UHF tags face interference from liquid and metal surfaces, restricting use in beverage and automotive component tracking.
Strategic Opportunities
- India logistics modernization:DGFT's electronic cargo tracking mandates for bonded warehousing create greenfield demand for UHF infrastructure.
- Sensor-integrated RFID convergence:Temperature-logging tags for cold chain are merging with blockchain verification for pharmaceutical provenance.
- Japan METI carbon accounting:Supply chain emissions disclosure rules are creating demand for item-level tracking to calculate Scope 3 footprints.
Industry Challenges
- RF engineering talent scarcity:Antenna design and impedance matching expertise concentrates in legacy telecom regions, limiting deployment scale-up.
- GS1 EPC certification timelines:Interoperability testing for retail reader networks extends procurement cycles by six to nine months.
- Legacy barcode integration:Hybrid environments require middleware investment to synchronize RFID event streams with existing ERP inventory modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global RFID Market |
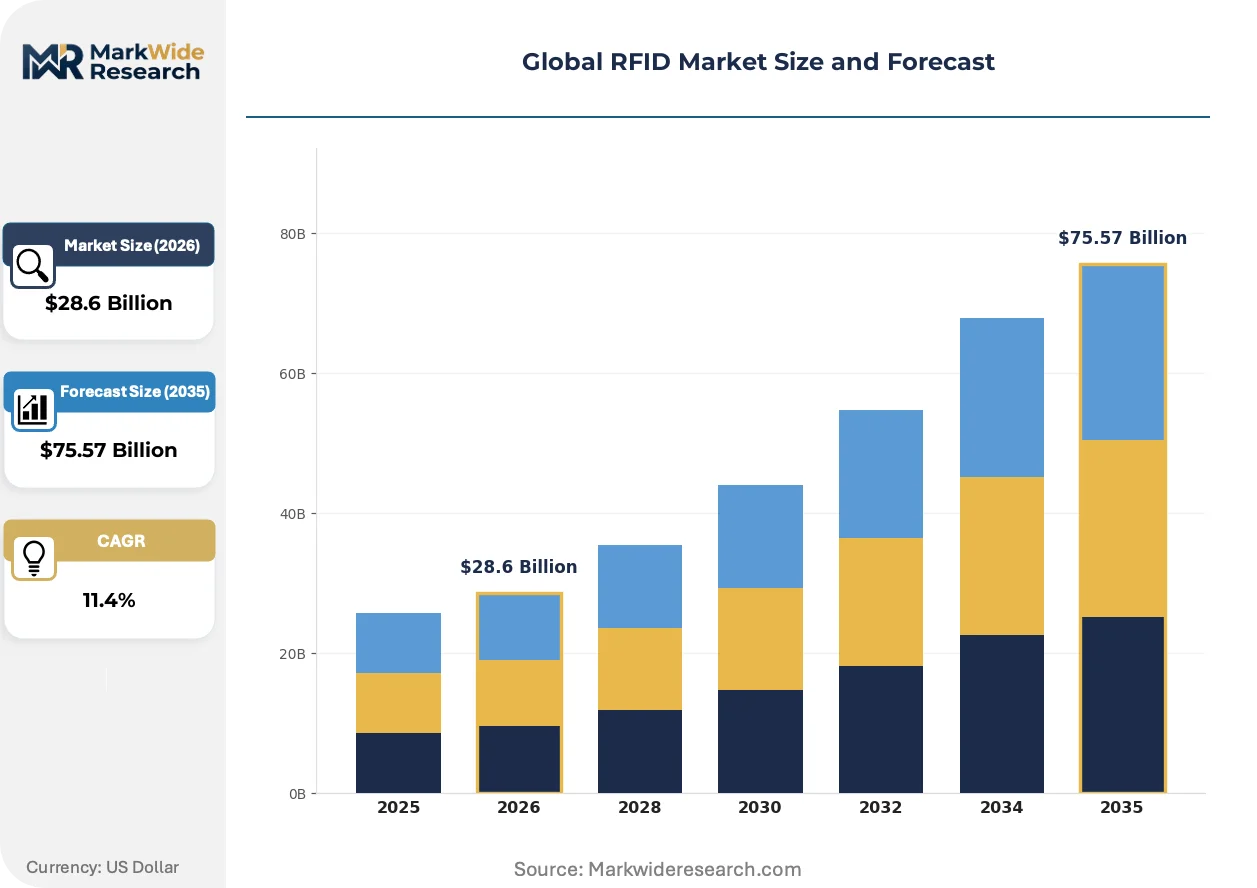
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active RFID, Passive RFID, Semi-passive RFID, Vision-based RFID Technology: LF RFID, HF RFID, UHF RFID, Microwave RFID Application: Inventory Management, Asset Tracking, Personnel Monitoring, Supply Chain Management End User: Retail, Healthcare, Logistics, Manufacturing |
| Companies Covered | Zebra Technologies, Honeywell International, Avery Dennison, Impinj, NXP Semiconductors, HID Global, Alien Technology, GAO RFID, Invengo Information Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global RFID Market Strategic Shifts
Chipless RFID encoding methods are compressing tag production costs while vision-RFID fusion systems are creating premium verification tiers for high-value asset classes.
RAIN RFID protocol implementations are overtaking proprietary UHF standards in enterprise deployments. Retailers in Germany and the United States are adopting EPC Gen2V2 readers for item-level apparel tracking. This protocol unification is overtaking fragmented vendor lock-in strategies and enabling multi-source procurement for infrastructure components.
The EU AI Act's risk classification framework is intersecting with RFID-enabled automated decision systems in personnel access control and warehouse worker monitoring. Industrial facility operators in France and the Netherlands must now conduct conformity assessments for biometric-inferred location tracking. Healthcare logistics providers are responding by segregating RFID data flows to ensure human-in-the-loop oversight for high-risk algorithmic outputs.
Pharmaceutical distributors are consolidating tag procurement through direct manufacturer contracts rather than distributor intermediaries. Large hospital networks in the United States and hospital pharmacy chains in Switzerland are negotiating volume commitments for serialized unit-dose packaging. This channel compression is most visible in oncology and biologics distribution where temperature excursion liability demands direct vendor accountability.
Global RFID Market Segmentation
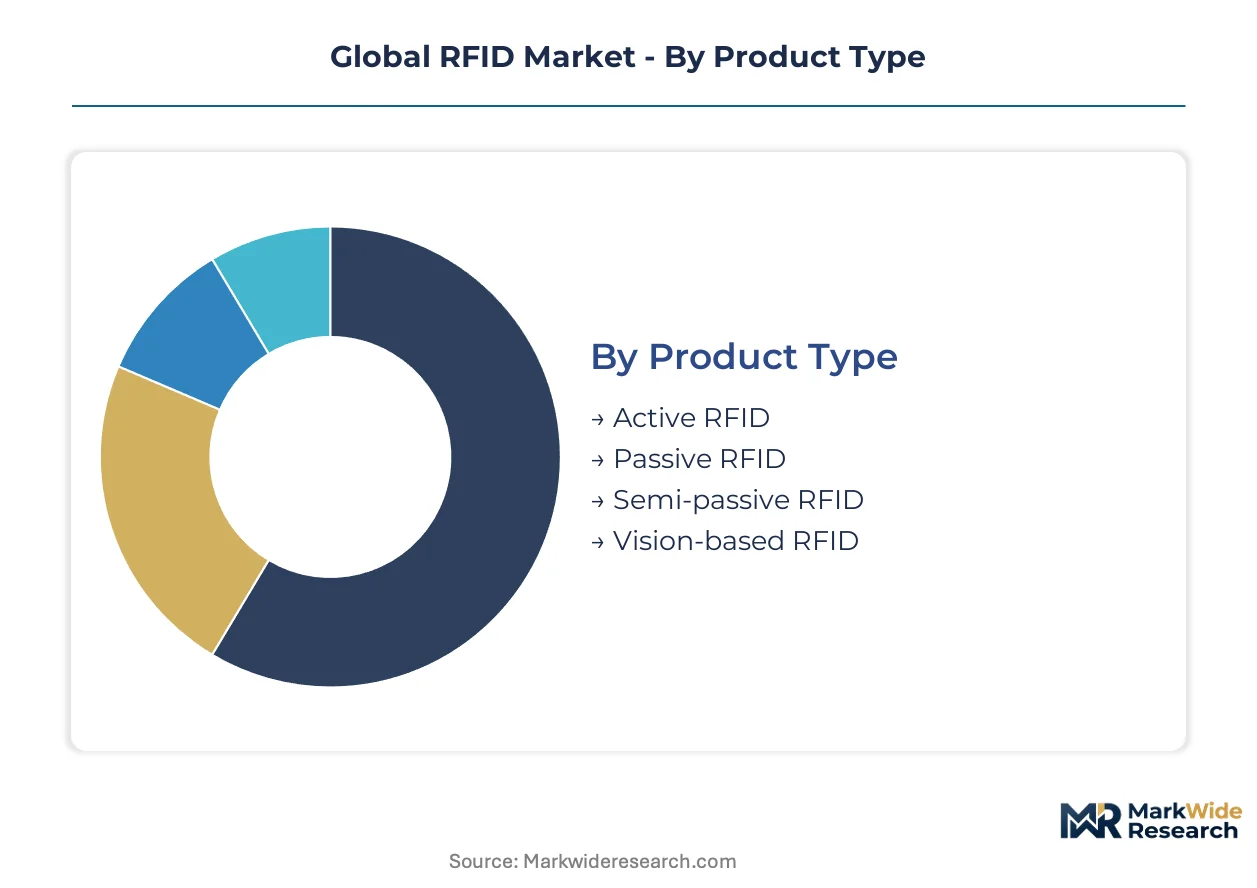
RFID deployment patterns diverge sharply across product architectures, frequency bands, and operational use cases. Certification requirements from ETSI, FCC, and national telecom authorities fragment procurement specifications by geography. Understanding these segment boundaries enables infrastructure buyers to match hardware selection against regulatory constraints and read-range physics.
Product Type:
REACH substrate compliance and FCC Part 15 emissions certifications impose divergent testing burdens across powered versus unpowered tag architectures.
- Passive RFID:Harvests interrogation energy from reader electromagnetic fields without onboard batteries. Retail apparel tagging in Germany and the United States concentrates volume demand, driven by EPC Gen2V2 standardization enabling multi-source reader procurement.
- Active RFID:Battery-powered beacons transmit over extended distances for real-time location systems. Cold chain monitoring in pharmaceutical distribution networks anchors demand, with temperature-logging sensor integration climbing fastest.
- Semi-passive RFID:Combines battery-assisted response with passive backscatter architecture for intermediate read ranges. Automotive component tracking in tier-one supplier plants creates niche demand.
- Vision-based RFID:Fuses optical recognition with radio frequency transmission for high-value asset verification. Aerospace MRO facilities and hospital surgical instrument sterilization chains anchor this premium tier.
Passive RFID sits at the top of the volume ranking, with active RFID climbing the fastest.
Technology:
Frequency allocation by national regulators determines antenna design and interference tolerance across deployment environments.
- UHF RFID:Operates at 860-960 MHz with longest read ranges and lowest per-tag costs at volume. Logistics modernization programs in India and bonded warehouse mandates from DGFT concentrate infrastructure demand.
- HF RFID:Functions at 13.56 MHz with robust near-field performance against liquid and metal surfaces. NFC payment integration and pharmaceutical unit-dose serialization in FDA-regulated packaging lines anchor deployment.
- LF RFID:Transmits at 125-134 kHz with minimal environmental interference. Animal identification and automotive immobilizer systems sustain this mature segment.
- Microwave RFID:Leverages 2.45 GHz and 5.8 GHz bands for specialized high-data-rate applications. Electronic toll collection on Japanese expressways and select ETC deployments concentrate demand.
UHF RFID commands the largest installed base, with HF RFID gaining share fastest through NFC convergence.
Application:
ROI measurement frameworks differ sharply between asset-centric versus flow-centric deployment models.
- Inventory Management:Enables real-time stock visibility and automated replenishment triggers. Apparel retailers in France and the Netherlands deploy item-level tagging to compress cycle-count labor.
- Asset Tracking:Locates high-value equipment across distributed facility footprints. Hospital networks in Switzerland and manufacturing plants under China's MIIT industrial internet mandates concentrate demand.
- Supply Chain Management:Tracks goods from origin through final delivery. EU Green Deal circular economy traceability requirements and Japan METI carbon accounting rules accelerate deployment.
- Personnel Monitoring:Manages access control and worker location in hazardous environments. EU AI Act conformity assessments for biometric-inferred tracking reshape vendor selection in French industrial facilities.
Inventory management leads by deployment count, with supply chain management expanding most quickly on regulatory tailwinds.
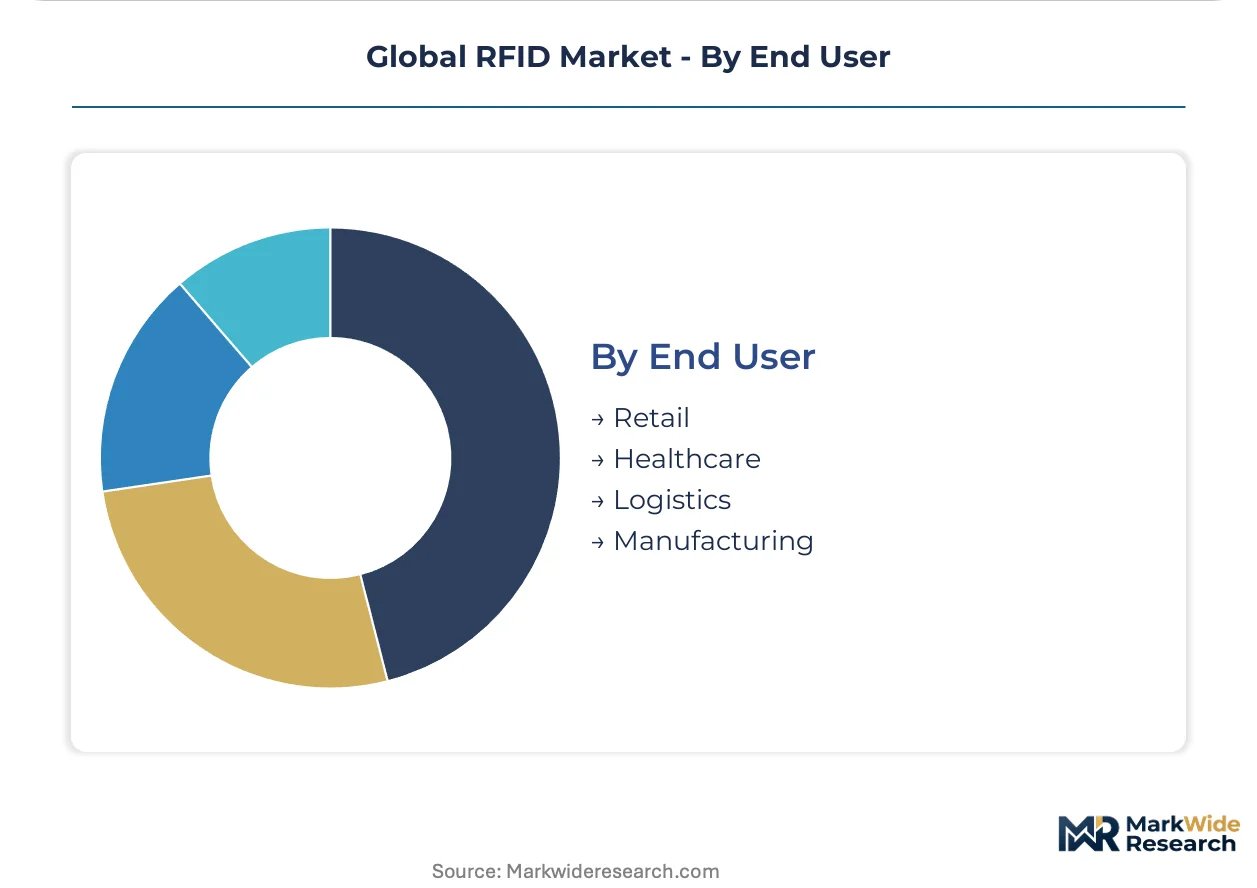
End User:
Customer procurement sophistication spans from centralized enterprise IT to fragmented operational technology buyers.
- Retail:Deploys item-level tagging for loss prevention and omnichannel fulfillment accuracy. German fashion chains and North American department stores anchor reader infrastructure demand.
- Healthcare:Tracks pharmaceuticals, medical devices, and patient specimens through sterile supply chains. FDA track-and-trace mandates and Swiss hospital network serialization contracts concentrate tag volume.
- Logistics:Modernizes warehouse automation and cross-dock visibility. India's DGFT electronic cargo tracking mandates for bonded warehousing create greenfield UHF infrastructure demand.
- Manufacturing:Tags work-in-process inventory and finished goods for smart factory integration. Automotive plants in China under MIIT machine-readable asset mandates and German industrial clusters lead deployment.
Retail holds the largest installed base, with healthcare expanding most quickly on pharmaceutical serialization requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
RFID engineering talent clusters in legacy telecom regions of Germany, Japan, and the United States anchor antenna design capabilities. Foundry capacity for UHF chips concentrates in East Asia. Regulatory divergence on frequency allocation and data sovereignty is fragmenting procurement specifications across national borders.
United States
Retail apparel chains and hospital networks drive reader infrastructure demand. FDA track-and-trace mandates for pharmaceutical distribution compress deployment timelines. The Greater Boston corridor concentrates RAIN RFID protocol development alongside Silicon Valley fabless chip design.
Germany
Automotive tier-one suppliers and fashion retailers anchor UHF tag volume demand. EU Green Deal circular economy traceability requirements force supply chain retrofits. The Stuttgart industrial cluster leads semi-passive RFID deployment for component tracking.
China
MIIT industrial internet initiatives mandate machine-readable asset tracking in automotive plants. Smart manufacturing programs concentrate demand through state-backed logistics modernization. The Yangtze River Delta dominates inlay production for export markets.
India
DGFT electronic cargo tracking mandates for bonded warehousing create greenfield UHF infrastructure demand. Logistics modernization programs accelerate reader deployment at ports and distribution centers. The Mumbai-Pune corridor anchors pharmaceutical serialization contract negotiations.
Japan
METI carbon accounting rules create demand for item-level tracking to calculate Scope 3 emissions. Automotive and electronics manufacturers deploy sensor-integrated tags for supply chain verification. The Chubu region around Nagoya concentrates aerospace MRO facilities adopting vision-based RFID.
Global RFID Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the RFID value chain. The market structures around three tiers: integrated materials-to-systems conglomerates, specialized chip and inlay fabricators, and regional hardware assemblers. Strategic moves concentrate on backward integration into antenna substrate production and forward integration into cloud-based asset management platforms.
Within the integrated materials tier, Avery Dennison exemplifies substrate-to-label vertical control. Impinj and NXP Semiconductors occupy positions at the fabless chip design end, anchoring RAIN RFID protocol implementation. Zebra Technologies sits within the hardware systems archetype, representing reader and printer infrastructure scale.
| Leading Market Players |
|---|
| Zebra Technologies |
| Honeywell International |
| Avery Dennison |
| Impinj |
| NXP Semiconductors |
| HID Global |
| Alien Technology |
| GAO RFID |
| Invengo Information Technology |
| Others |
Value Chain & Pricing Dynamics
Silver and copper antenna deposition costs cascade through inlay production tiers, compressing margins for volume apparel taggers while REACH-certified biodegradable substrates command premium positioning in European automotive supply chains. Raw material volatility in East Asian foundry markets feeds directly into UHF chip pricing differentials between certified and uncertified vendor tiers.
Pricing Analysis
Bundled hardware-software service packages dominate enterprise reader deployments, while unbundled per-tag transactional pricing prevails in high-volume apparel retail. Three-tier pricing structure across premium, standard, and economy levels separates vision-RFID fusion systems for aerospace from standard UHF inlays for logistics and economy-grade HF tags for access control. Cost compression in passive UHF tags is intensifying because silicon wafer supply concentration in East Asia squeezes fabless designers. Price sensitivity concentrates among logistics operators in India's bonded warehousing sector, while pharmaceutical serialization contracts in Switzerland and the United States show lowest sensitivity due to liability-driven vendor accountability requirements.
Supply Chain Analysis
RF engineering talent scarcity in Germany, Japan, and the United States limits antenna design scale-up even as Yangtze River Delta inlay production expands for export markets. UHF chip fabrication draws from concentrated East Asian foundry capacity, while silver and copper antenna deposition feeds from commodity metals markets subject to price volatility. Single-source vulnerability in silicon wafer supply creates exposure to geopolitical disruption. Distribution runs through direct manufacturer contracts consolidating in pharmaceutical and hospital network procurement, bypassing traditional distributor intermediaries in oncology and biologics segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Green Deal circular economy mandates force traceability infrastructure retrofits across automotive and retail supply chains, compressing deployment timelines and reshaping vendor selection criteria toward certified substrate compliance.
For Market Incumbents: Extend backward integration into antenna substrate production to capture REACH-compliant biodegradable materials margin, while consolidating cloud-based asset management platform capabilities to offset hardware commoditization pressure from Zebra Technologies and Honeywell International channel depth. Threat substitution from chipless RFID encoding methods demands sustained R&D intensity in RAIN RFID protocol development to maintain protocol unification advantages.
For New Entrants and Emerging Players: Begin with India's DGFT electronic cargo tracking mandates for bonded warehousing, where greenfield UHF infrastructure demand outpaces established vendor presence and project-based procurement favors agile system integrators. Target sensor-integrated RFID convergence for pharmaceutical cold chain as the most penetrable white-space, leveraging temperature-logging tag development partnerships with blockchain verification providers to bypass incumbent hardware lock-in.
For Investors and Strategic Acquirers: Roll-up economics work for specialized antenna design boutiques because RF engineering talent scarcity in legacy telecom regions creates captive acquisition value for impedance matching expertise. Five-to-ten year viability hinges on GS1 EPC certification capability as gatekeeper to retail infrastructure procurement. Watch for EU AI Act conformity assessment requirements in French and Dutch industrial facilities as inflection signal for biometric-inferred location tracking compliance services.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Antenna Substrate Production | REACH-certified biodegradable inlay materials capture margin in EU automotive supply chains. |
| RAIN RFID Protocol Standardization Investment | EPC Gen2V2 reader certification enables multi-source procurement for German apparel retailers. |
| Sensor-Integrated Tag Development Partnership | Temperature-logging convergence with blockchain verification addresses pharmaceutical liability exposure. |
| Cloud-Based Asset Management Platform Launch | Software recurring revenue offsets hardware margin compression from reader commoditization. |
| RF Engineering Talent Acquisition Cluster | Antenna design capability scarcity in Germany and Japan creates defensive moat against chipless RFID displacement. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with RFID hardware procurement managers, supply chain directors at pharmaceutical distributors, automotive tier-one supplier logistics leads, and hospital network biomedical engineers with secondary validation from FCC Part 15 filings, ETSI emissions certifications, FDA track-and-trace guidance documents, and MIIT industrial internet mandate disclosures. Bottom-up tag volume estimates triangulate against top-down infrastructure spending projections.
Granularity-level modeling disaggregates volume and value across the projection horizon by product architecture (passive, active, semi-passive, vision-based), frequency band (UHF, HF, LF, microwave), application use case, and end-user procurement sophistication, with CAGRs derived from segment-level growth rate reconciliation against macroeconomic indicators. Industry-specific forecast inputs include GS1 EPC certification pipeline data and DGFT bonded warehouse mandate implementation timelines.
Several conditions sit outside the modeled scope, including unforeseen geopolitical disruption to East Asian foundry capacity, abrupt metals price spikes beyond historical volatility bands, and GS1 standards evolution altering interoperability testing protocols. Forecasts reflect documented assumptions about regulatory enforcement continuity and technology substitution rates. Material deviation in EU AI Act implementation timelines or REACH substrate compliance enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
IO-Link Technology Market
Sensors
Global Load Monitoring System (LMS) Market
Sensors
Heat Stress Meter Market
Sensors
Connected Smart Thermostats Market
Sensors
Asset Tracking Market
Sensors
Global Position Tracking System Market
Sensors
Smart Pest Monitoring Management System Market
Sensors
Bluetooth Beacons Market
Sensors
Beacon Technology Market
Sensors
Body Area Network Market
Sensors
Global Energy Harvesting System for Wireless Sensor Network Market
Sensors
India Asset Tracking Market
Sensors
Vibration Monitoring Market
Sensors
Safety Motion Control System Market
Sensors
Ultrasonic Technologies Market
Sensors
Smart Beacon Market