
 Global Android Kiosk Software Market | 2026-2036
Global Android Kiosk Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Android Kiosk Software Market Foresight
Subscription-based device management is expanding as the dominant commercial model for Android kiosk software, shifting vendor economics from perpetual licenses toward recurring revenue streams. 42Gears Mobility Systems leverages deep OEM partnerships to sustain hardware-agnostic deployment across Samsung and Zebra device fleets. Hexnode MDM anchors its position through cross-platform MDM consolidation, allowing IT administrators to manage Android kiosks alongside iOS and Windows endpoints from a single console. KioWare competes on browser lockdown specialization, offering granular peripheral control that appeals to payment kiosk operators requiring PCI-DSS alignment.
Android kiosk software comprises system-level lockdown utilities, remote management agents, and application whitelisting frameworks that restrict commercial tablets and purpose-built terminals to a single app or curated set of functions, typically enforcing kiosk mode through Android Enterprise APIs, custom launchers, and policy controllers. The software serves industries requiring unattended or semi-attended customer-facing terminals where operational continuity and data security override user flexibility. Cloud-based deployment leads in new installations because fleet operators prioritize over-the-air configuration pushes and real-time telemetry ingestion without maintaining private server infrastructure. Self-service kiosks represent the fastest-growing solution offering as quick service restaurants and grocery chains accelerate checkout automation to reduce labor dependency. Digital signage lags in growth velocity but commands durable margin pools from advertising networks seeking content scheduling with interactivity overlays.
FDA guidelines on data integrity for healthcare patient registration terminals shape product requirements for audit trails and tamper-evident logging in medical clinic deployments. The EU AI Act and GDPR impose algorithmic transparency and data minimization obligations on European kiosk operators, particularly for facial recognition and behavioral analytics integrations. India's BIS certification mandates and RBI payment security directives govern banking transaction kiosk deployments across public and private sector banks. Stakeholders must monitor regulatory divergence between jurisdictions to avoid fragmented compliance architectures that inflate deployment costs and delay market entry.
Market Dynamics
Subscription-based device management is compressing vendor economics toward recurring revenue streams, while the EU AI Act and GDPR compliance requirements are forcing European deployers toward certified lockdown platforms that fragment procurement architectures.
Growth Catalysts
- Retail POS modernization:Merchants are replacing legacy checkout infrastructure with Android-based self-service terminals to reduce labor dependency and accelerate transaction throughput.
- GDPR algorithmic transparency mandates:European kiosk operators must adopt certified platforms with tamper-evident logging and data minimization frameworks for facial recognition integrations.
- India's BIS certification push:Banking transaction kiosk deployments across public and private sector banks are standardizing on lockdown-compliant Android hardware under RBI payment security directives.
Market Restraints
- Input cost volatility:Purpose-built terminal manufacturers face pressure from semiconductor component shortages and display panel price swings.
- Supply concentration risk:Samsung and Zebra dominate enterprise-grade Android hardware fleets, creating single-source vulnerability for large-scale rollouts.
- Technical fragmentation:Android Enterprise API versioning across OEM custom skins complicates cross-device policy deployment.
Strategic Opportunities
- Underpenetrated German healthcare:Patient registration terminals remain under-automated, creating openings for FDA-aligned audit trail solutions.
- Quick service restaurant automation:Grocery chains and fast-casual dining operators are accelerating checkout automation to compress labor costs.
- Cloud-native telemetry convergence:Fleet operators are prioritizing over-the-air configuration pushes and real-time analytics ingestion without private server infrastructure.
Industry Challenges
- Certification timeline compression:PCI-DSS alignment for payment kiosk operators requires granular peripheral control validation that extends deployment cycles.
- Legacy system integration friction:Retail merchants face middleware complexity when connecting modern Android terminals to existing ERP and inventory management stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Android Kiosk Software Market |
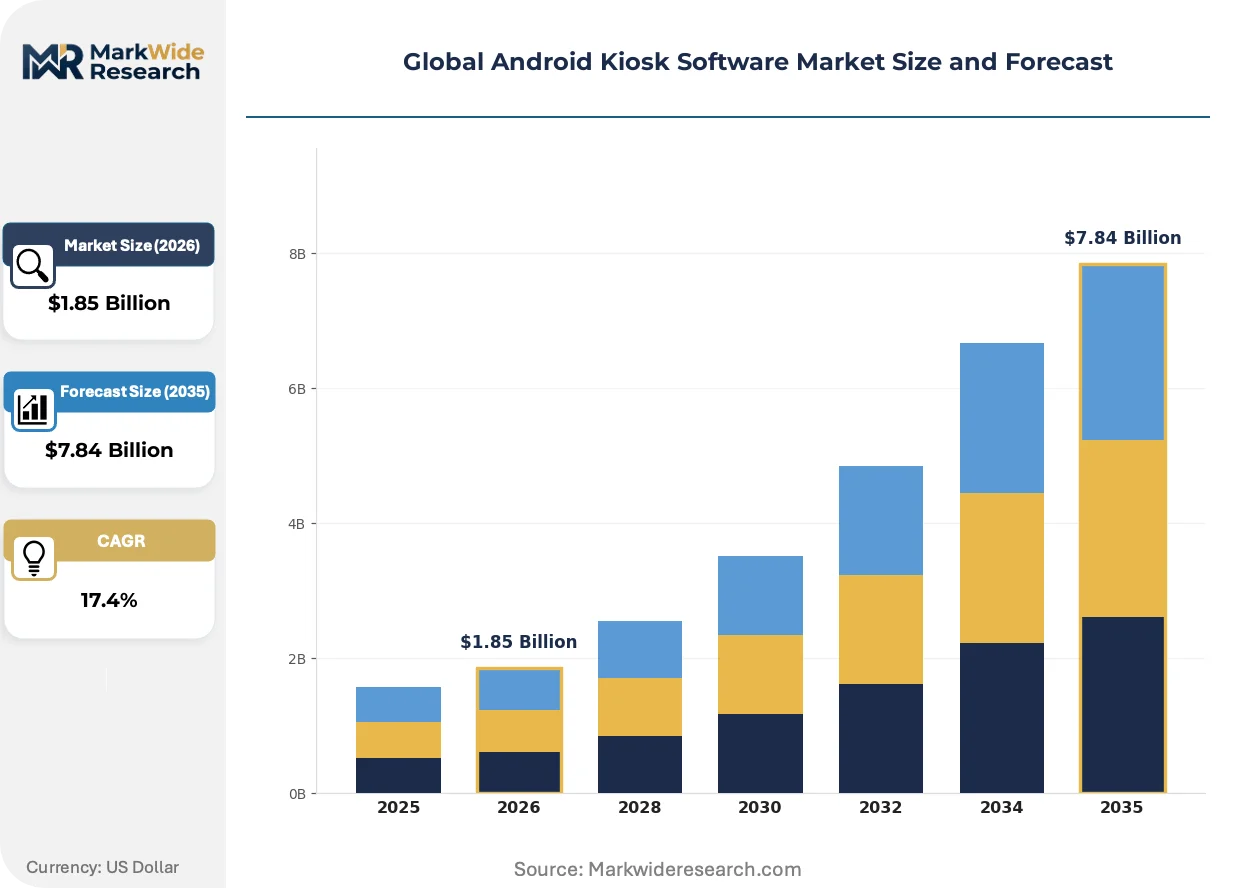
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-based, On-Premises, Hybrid, Edge Computing Solution Offering: Self-Service Kiosks, Digital Signage, Payment Kiosks, Wayfinding Systems, Ticketing Systems Use Case: Retail Checkout, Hospitality Check-in, Transportation Ticketing, Healthcare Patient Registration, Banking Transactions Industry Vertical: Quick Service Restaurants, Public Transportation, Financial Services, Medical Clinics, Entertainment Venues |
| Companies Covered | 42Gears Mobility Systems, KioWare, SureLock Kiosk Lockdown, Hexnode MDM, Moki Mobility, Inteset Secure Lockdown, ManageEngine Mobile Device Manager Plus, Samsung Knox Manage, Provisio SiteCaster, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Android Kiosk Software Market Shifts & Advancements
Android kiosk software architecture is pivoting toward cloud-native telemetry and cross-platform consolidation, while regulatory pressure is hardening compliance requirements across healthcare and financial verticals.
Zero-touch enrollment via Android Enterprise is rewriting fleet deployment economics. System integrators are adopting bulk provisioning workflows that eliminate manual staging. This compression of deployment labor is enabling faster scaling for quick service restaurant operators managing thousands of endpoints.
The EU AI Act's risk classification framework is reshaping biometric integration strategies. Kiosk operators deploying facial recognition must implement algorithmic transparency documentation and human oversight protocols. European retail and banking segments are responding by segregating high-risk analytics to edge processing with local data residency.
IT administrators are consolidating endpoint management across Android, iOS, and Windows through unified MDM consoles. Single-pane-of-glass administration is displacing siloed kiosk-specific tools in mid-market enterprises. This consolidation pattern is most visible in United States healthcare systems standardizing device governance across patient registration and clinical workflow tablets.
Global Android Kiosk Software Market Segmentation
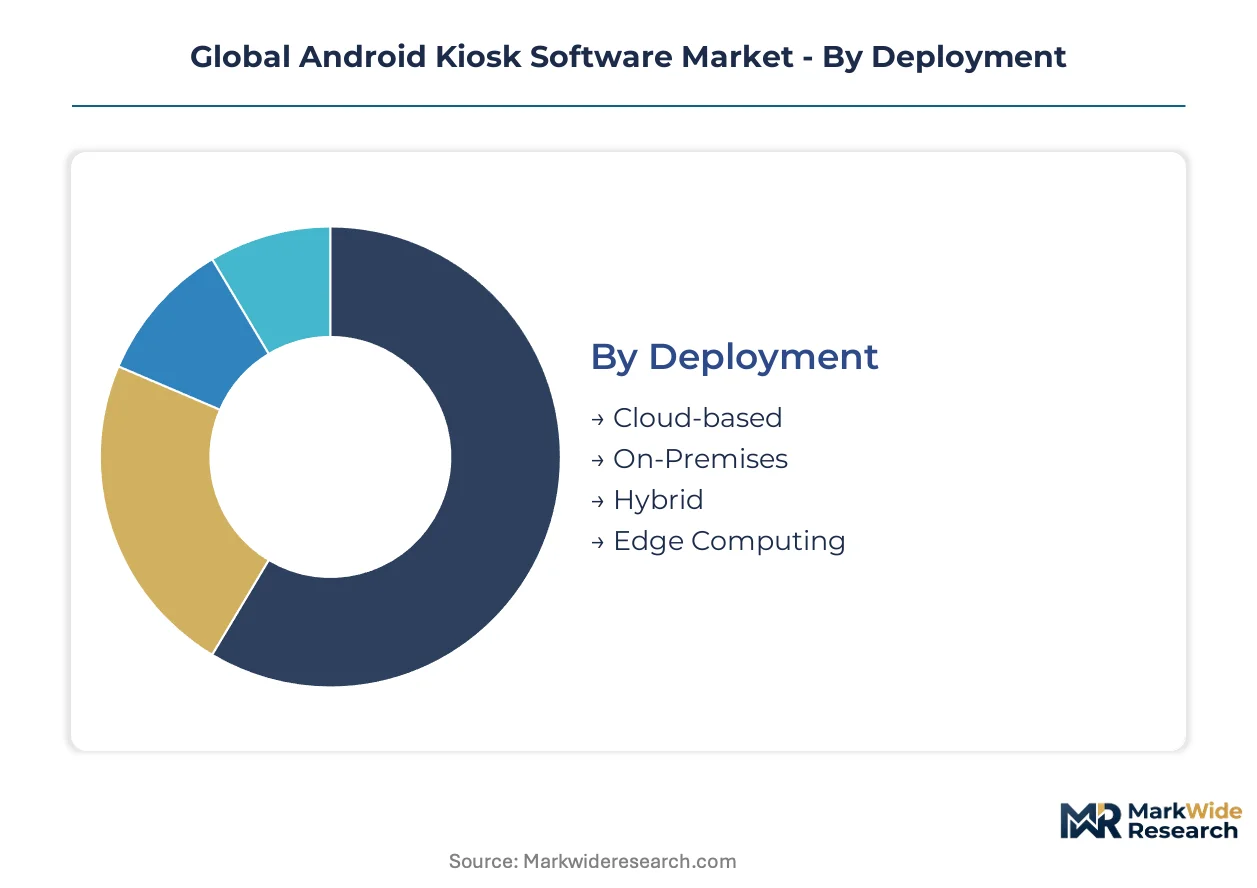
Segmentation in Android kiosk software reveals how deployment architecture, solution configuration, and industry application determine procurement priorities. Fleet operators select configurations based on connectivity constraints, regulatory exposure, and endpoint scale rather than feature breadth alone.
Deployment:
Cloud infrastructure concentration among hyperscalers has compressed on-premises deployment economics toward niche compliance scenarios.
- Cloud-based:Centralized policy orchestration and over-the-air configuration pushes dominate new installations. United States quick service restaurant chains prioritize real-time telemetry ingestion without maintaining private server infrastructure.
- On-Premises:Air-gapped environments in European banking and German healthcare enforce local data residency through dedicated policy controllers. GDPR audit trail requirements and EU AI Act algorithmic transparency mandates sustain demand despite higher total cost of ownership.
- Hybrid:Split architectures separate sensitive biometric processing at the edge from analytics aggregation in cloud tenants. Indian banking transaction kiosks under RBI directives deploy hybrid models to balance BIS certification compliance with centralized fleet visibility.
- Edge Computing:Local inference execution for facial recognition and behavioral analytics reduces latency in transportation ticketing and entertainment venue access control. Processing gravity shifts toward endpoints as EU risk classification frameworks push high-risk analytics away from centralized infrastructure.
Today's leader: Cloud-based. Tomorrow's challenger: Edge Computing.
Solution Offering:
Solution margins concentrate where peripheral integration complexity and certification requirements create defensive moats.
- Self-Service Kiosks:Checkout automation terminals integrate payment hardware, barcode scanners, and receipt printers through Android Enterprise APIs. Grocery chains and fast-casual dining operators in the United States accelerate deployment to compress labor costs.
- Payment Kiosks:PCI-DSS alignment demands granular peripheral control and tamper-evident logging frameworks. Certification timeline compression extends deployment cycles for operators integrating legacy ERP stacks.
- Digital Signage:Content scheduling with interactivity overlays commands durable margin pools from advertising networks. Lower hardware integration complexity limits pricing power compared to payment-adjacent solutions.
- Wayfinding Systems:Indoor positioning and interactive directory deployments concentrate in German healthcare campuses and Indian public transportation hubs. Integration with existing facility management systems determines vendor selection.
- Ticketing Systems:Transportation and entertainment verticals demand high-availability uptime with offline transaction buffering. Indian Railways and metropolitan transit authorities standardize on lockdown-compliant Android hardware under BIS certification mandates.
Payment Kiosks extract the steepest premiums. Self-Service Kiosks are climbing the fastest.
Use Case:
Use case selection tracks labor cost pressure and transaction throughput requirements across customer-facing touchpoints.
- Retail Checkout:Self-service terminal deployment accelerates as merchants replace legacy POS infrastructure. United States grocery chains and big-box retailers drive volume through standardized Android hardware fleets.
- Banking Transactions:RBI payment security directives and BIS certification requirements govern kiosk deployments across Indian public and private sector banks. Biometric authentication integration demands algorithmic transparency documentation under emerging regulatory frameworks.
- Hospitality Check-in:Hotel operators deploy automated front-desk terminals to reduce staffing ratios during peak arrival windows. Integration with property management systems and key encoding hardware determines solution architecture.
- Healthcare Patient Registration:FDA guidelines on data integrity shape audit trail and tamper-evident logging requirements in United States medical clinic deployments. German healthcare facilities remain under-automated, creating expansion opportunities for compliant vendors.
- Transportation Ticketing:Fare collection terminals require offline transaction capability and rapid card-present authentication. Indian metropolitan transit authorities and European rail operators prioritize certification alignment over feature differentiation.
Retail Checkout commands current deployment volume. Healthcare Patient Registration offers the widest expansion runway.
Industry Vertical:
Vertical specialization determines whether vendors compete on certification depth, integration breadth, or hardware optimization.
- Quick Service Restaurants:Order automation and checkout acceleration dominate procurement criteria. United States chains standardize on Android-based terminals with kitchen display system integration and loyalty program connectivity.
- Financial Services:PCI-DSS compliance and biometric authentication frameworks create certification barriers. Indian banks under RBI directives and European institutions navigating GDPR and EU AI Act requirements sustain premium pricing for compliant platforms.
- Medical Clinics:Patient registration terminals require FDA-aligned audit trails and HIPAA-compliant data handling. German healthcare underpenetration creates regional expansion opportunities for vendors with existing United States clinical credentials.
- Public Transportation:Fare collection systems demand ruggedized hardware and offline transaction resilience. Indian metropolitan authorities and European rail operators drive standardization through BIS and CE marking requirements respectively.
- Entertainment Venues:Access control and concession automation prioritize throughput and user experience over deep systems integration. Seasonal demand volatility favors subscription-based deployment models with elastic endpoint scaling.
Financial Services sustains the deepest margins. Quick Service Restaurants deliver the steepest volume expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's healthcare automation lags behind United States clinical deployments, creating divergent expansion timelines for kiosk software vendors navigating FDA-aligned versus CE-marking compliance pathways.
United States
Quick service restaurant chains and grocery retailers drive fleet standardization on Android-based self-service terminals. FDA guidelines on data integrity for healthcare patient registration terminals mandate audit trails and tamper-evident logging frameworks. Hospital networks in Texas and Florida accelerate deployment of automated check-in kiosks to reduce front-desk staffing ratios during peak arrival windows.
Germany
Patient registration terminals remain under-automated across medical clinic networks, creating whitespace for compliant vendors. EU AI Act risk classification frameworks and GDPR algorithmic transparency obligations push operators toward certified lockdown platforms with local data residency. Healthcare campuses in Bavaria and North Rhine-Westphalia pilot automated wayfinding systems integrated with existing facility management infrastructure.
India
Banking transaction kiosk deployments expand across public and private sector banks under RBI payment security directives. BIS certification mandates govern hardware standardization for transaction terminals handling card-present authentication. Metropolitan transit authorities in Mumbai and Delhi deploy lockdown-compliant Android hardware for fare collection systems requiring offline transaction buffering.
United Kingdom
Retail merchants accelerate POS modernization to replace legacy checkout infrastructure with self-service terminals. GDPR compliance requirements and emerging biometric regulation shape procurement criteria for facial recognition integrations. London-based quick service restaurant operators standardize on cloud-native device management for elastic endpoint scaling across seasonal demand cycles.
Global Android Kiosk Software Market Competitive Landscape
Top-tier vendors anchor the subscription-based device management tier, while hardware-agnostic specialists and cross-platform consolidators compete on integration breadth. The vendor base organizes around three strategic archetypes: OEM-captive platforms leveraging deep hardware partnerships, independent MDM providers pursuing multi-OS consolidation, and browser lockdown specialists targeting payment-adjacent compliance verticals. Dominant competitive moves include zero-touch enrollment capability expansion and edge computing architecture development for biometric processing localization.
Within the hardware-agnostic deployment tier, 42Gears Mobility Systems and KioWare represent contrasting specialization vectors. 42Gears occupies a position exemplifying OEM partnership depth across Samsung and Zebra device fleets, while KioWare anchors the browser lockdown archetype with PCI-DSS alignment capabilities. Hexnode MDM sits within the cross-platform consolidation segment, enabling unified endpoint governance that displaces siloed kiosk-specific tools in mid-market healthcare and retail deployments.
| Leading Market Players |
|---|
| 42Gears Mobility Systems |
| KioWare |
| SureLock Kiosk Lockdown |
| Hexnode MDM |
| Moki Mobility |
| Inteset Secure Lockdown |
| ManageEngine Mobile Device Manager Plus |
| Samsung Knox Manage |
| Provisio SiteCaster |
| Others |
Supply & Pricing Matrix
Captive hardware-software integration across Samsung and Zebra device fleets anchors vendor pricing power while compressing margins for pure-play software providers lacking OEM partnership depth. This integration pattern concentrates procurement leverage among fleet operators standardizing on enterprise-grade Android terminals, forcing independent vendors toward subscription-tiered models to sustain recurring revenue against bundled competition.
Pricing Analysis
Capacity additions in India's BIS-certified terminal manufacturing are reshaping price floors for compliant banking transaction kiosks under RBI directives. Pricing stratifies across premium certification tiers for PCI-DSS-aligned payment platforms, standard SaaS tiers for cross-platform MDM consolidation, and economy tiers for basic browser lockdown utilities. Cost compression in the economy tier intensifies because hardware-agnostic deployment tools face commoditization from Android Enterprise native capabilities. Quick service restaurant chains in the United States exhibit the highest price sensitivity, prioritizing elastic endpoint scaling over peripheral integration depth, while European banking operators under GDPR and EU AI Act mandates accept premium pricing for certified lockdown platforms with local data residency.
Supply Chain Analysis
India's domestic-content mandates for public sector banking kiosks are reshaping sourcing patterns for lockdown-compliant Android hardware. Component manufacturing concentrates in China for display panels and semiconductor assemblies, South Korea for memory modules and processor fabrication, and Taiwan for system-on-chip design. Purpose-built terminal production draws from these inputs while facing single-source vulnerability from Samsung and Zebra dominance in enterprise-grade Android fleets. Distribution runs through systems integrators serving quick service restaurant chains and direct OEM channels for large-scale banking deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where vendors with existing FDA-aligned audit trail capabilities in the United States can extract premium pricing in underpenetrated German healthcare while navigating CE-marking compliance pathways.
For Market Incumbents: To counter cloud-native telemetry convergence by cross-platform MDM providers, deepen OEM partnership exclusivity with Samsung and Zebra through co-developed zero-touch enrollment workflows. Prioritize certification investment in EU AI Act algorithmic transparency frameworks to defend margin position against hardware-agnostic competitors lacking European regulatory depth. For New Entrants and Emerging Players: Systems integrators specializing in quick service restaurant automation represent the most accessible channel partner type for market entry. Target German healthcare patient registration terminals as the least penetrated geography with existing United States clinical workflow expertise. Pursue a compliance-first go-to-market angle bundling FDA-aligned audit trails with CE-marking navigation services. For Investors and Strategic Acquirers: Roll-up economics work for browser lockdown specialists because PCI-DSS alignment capabilities create defensive moats that platform consolidators cannot easily replicate. Five-to-ten year viability favors vendors with vertical-specific certification depth over horizontal MDM generalists. Watch EU AI Act enforcement timelines as the inflection indicator for premium pricing power in European deployments.| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Touch Enrollment Expansion | Samsung Knox Manage and 42Gears compress deployment labor for quick service restaurant fleets. |
| Edge Computing Architecture Development | Biometric processing localization addresses EU AI Act risk classification for facial recognition integrations. |
| Cross-Platform MDM Consolidation | Hexnode displaces siloed kiosk tools in United States healthcare systems standardizing device governance. |
| PCI-DSS Alignment Specialization | KioWare maintains peripheral control granularity that payment kiosk operators require for certification. |
| Healthcare Compliance Pathway Navigation | FDA audit trail expertise transfers to German clinical expansion under CE-marking requirements. |
Research Methodology
Direct dialogue with fleet operations directors at quick service restaurant chains, IT procurement officers in Indian banking, healthcare technology managers in German clinics, Android Enterprise integration specialists, and regulatory compliance consultants grounded qualitative insights. Secondary validation drew from RBI payment security circulars, FDA data integrity guidance documents, EU AI Act implementing texts, Android Enterprise deployment whitepapers, and hyperscaler IoT platform disclosures. Bottom-up terminal deployment tallies triangulated against top-down software revenue estimates.
Bottom-up modeling tracked cloud-based versus on-premises deployment splits, self-service kiosk versus payment kiosk solution margins, and quick service restaurant versus financial services vertical penetration rates across the projection horizon. Top-down analysis calibrated total addressable market boundaries against Android Enterprise API adoption curves and OEM partnership ecosystem expansion. CAGRs derived from segment-level growth rate blending weighted by deployment architecture concentration and regulatory compliance timeline compression.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU AI Act enforcement rigor, RBI directive expansion scope, and semiconductor supply normalization trajectories. Assumptions reflect current regulatory frameworks without anticipating unannounced amendments. A small set of triggers—BIS certification timeline shifts, FDA audit trail requirement updates, and Samsung-Zebra hardware sourcing disruptions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Software-Defined Machine Market
Software & Services
Intelligent Enterprise Data Capture Software Market
Software & Services
Italy HR Payroll Software Market
Software & Services
Terminal Emulator Software Market
Software & Services
Global Coworking Space Management Software Market
Software & Services
Combat Management Systems Software Market
Software & Services
Time Series Databases Software Market
Software & Services
Contract Abstraction Software Market
Software & Services
Ad Creation Software Market
Software & Services
Advanced Mobile UX Design Services Market
Software & Services
Interior Design Software Market
Software & Services
Virtual Studio Software Market
Software & Services
Preventive Maintenance Software Market
Software & Services
Global Software Resellers Market
Software & Services
Construction Estimating Software Market
Software & Services
E-Invoicing Software Market